
 Wood Truss Market | 2026-2036
Wood Truss Market Size, Share, and Industry Trends Forecast 2026-2036
Wood Truss Market Analytics
Mass timber is broadening the addressable market for engineered structural components as architects substitute concrete and steel with wood-based systems in mid-rise construction. UFP Industries leverages vertical integration from lumber procurement to component fabrication, sustaining cost advantages across volatile fiber markets. Builders FirstSource dominates distribution through national contractor relationships, while Littfin Truss specializes in complex custom geometry for commercial roof systems.
A wood truss is a triangulated framework of dimensional lumber or engineered wood members connected by metal plate connectors, designed to carry roof or floor loads across spans typically ranging from twenty to sixty feet. The primary industrial purpose is to replace traditional stick-framed rafters and joists with factory-built components that reduce field labor and material waste. Fink Truss configurations occupy the largest volume share in residential pitched roofs due to their economical web pattern and manufacturing simplicity, while prefabricated installation types are capturing share from custom-built alternatives as builders prioritize schedule compression and labor cost containment.
US building codes enforced by the International Code Council mandate structural grading and connector plate standards that shape product qualification and market access for domestic manufacturers. EPA regulations on formaldehyde emissions from composite wood products influence material sourcing decisions for laminated veneer lumber and oriented strand board chords used in high-performance truss designs. Stakeholders must monitor evolving mass timber height allowances and fire-resistance rating requirements as jurisdictions recalibrate permitted construction types.
Market Dynamics
Mass timber building codes adopted by the International Code Council are compressing design-to-erection timelines and displacing conventional steel framing in mid-rise commercial construction across North America.
Growth Catalysts
- Mass Timber Code Expansion:The International Code Council's Type IV-A, B, and C construction classifications now permit wood structures up to 18 stories, opening mid-rise commercial and mixed-use verticals previously reserved for concrete and steel.
- Southeastern US Housing Cluster:Concentrated housing starts in Georgia, Florida, and the Carolinas are pulling prefabricated truss capacity toward regional fabrication hubs, reducing freight costs and delivery windows for residential builders.
- Labor Cost Compression:Stick-framed roof systems require 40-60% more field labor hours than componentized truss installation, driving procurement preference toward factory-built alternatives as construction wages escalate.
Market Restraints
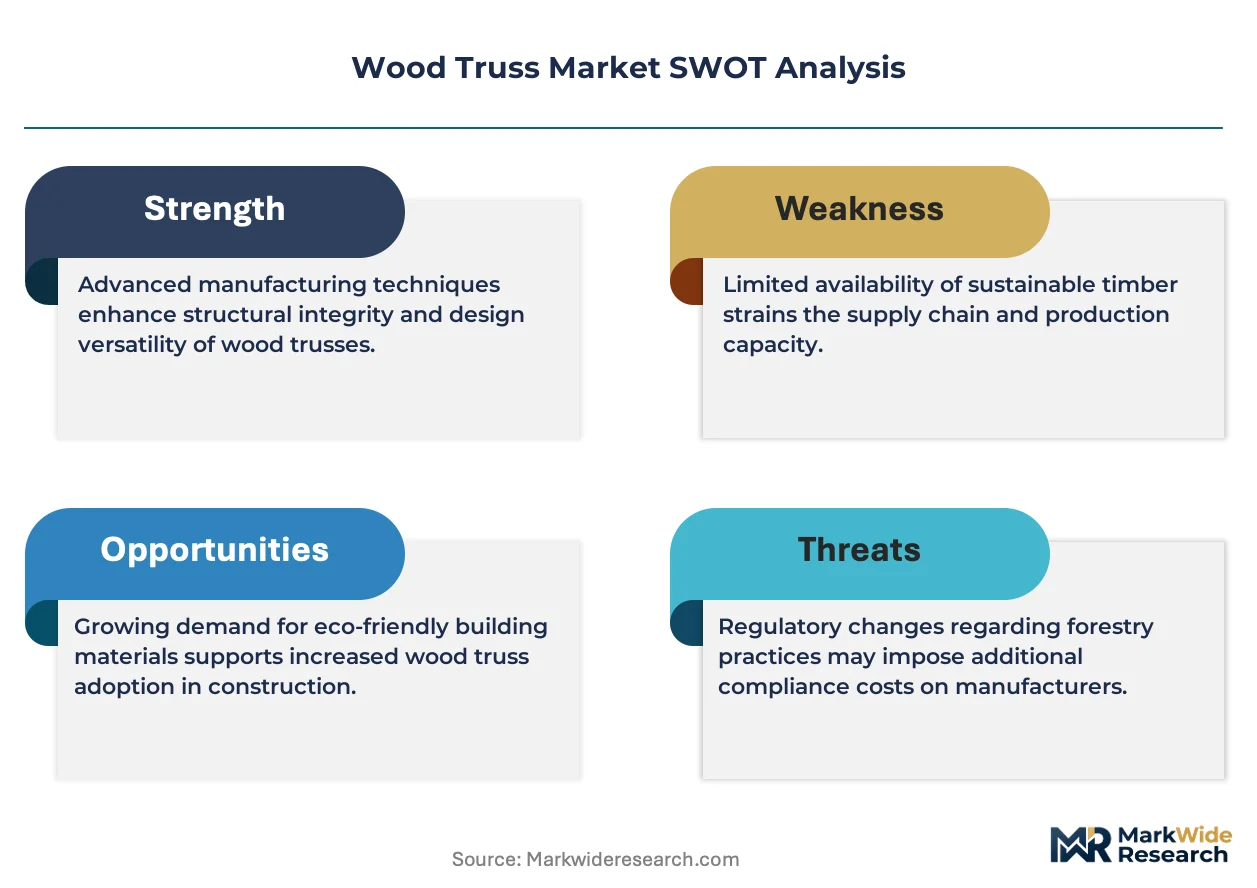
- Lumber Price Volatility:Dimensional lumber and oriented strand board chord inputs fluctuate with North American milling capacity constraints and tariff exposure on Canadian softwood imports, compressing fabricator margins during spike cycles.
- Plate Connector Supply Concentration:Galvanized steel truss plates depend on a concentrated base of specialty roll-forming suppliers, creating single-source vulnerability during raw steel allocation periods.
- Fire-Resistance Certification Gaps:Mass timber assemblies require project-specific fire testing and engineering judgments that extend approval timelines beyond conventional material substitutions, slowing adoption in risk-averse jurisdictions.
Strategic Opportunities
- Mid-Rise Commercial Vertical:Five-to-twelve-story office and residential buildings in Portland, Minneapolis, and Toronto represent underpenetrated demand for engineered wood floor and roof systems as architects seek embodied carbon reductions.
- Design-Assist Contracting Models:Early-stage collaboration between truss fabricators and design-build contractors is compressing RFQ-to-fabrication cycles and capturing value previously retained by structural engineering intermediaries.
- Carbon Accounting Integration:Environmental product declarations and whole-building life-cycle assessments are converging with green building certification requirements, positioning wood truss systems for specification preference in publicly procured projects.
Industry Challenges
- Truss Designer Talent Scarcity:Specialized structural design skills for complex commercial geometry remain concentrated among aging practitioners, constraining fabricator capacity to bid custom architectural roof systems.
- ERP Integration Friction:Legacy fabrication scheduling software lacks API compatibility with builder procurement platforms, forcing manual order entry and delaying real-time inventory visibility for national distributor networks.
- Quality Control Standardization:In-plant third-party inspections and plate-embedment verification protocols vary by state, complicating multi-jurisdictional production for regional fabricators seeking scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood Truss Market |
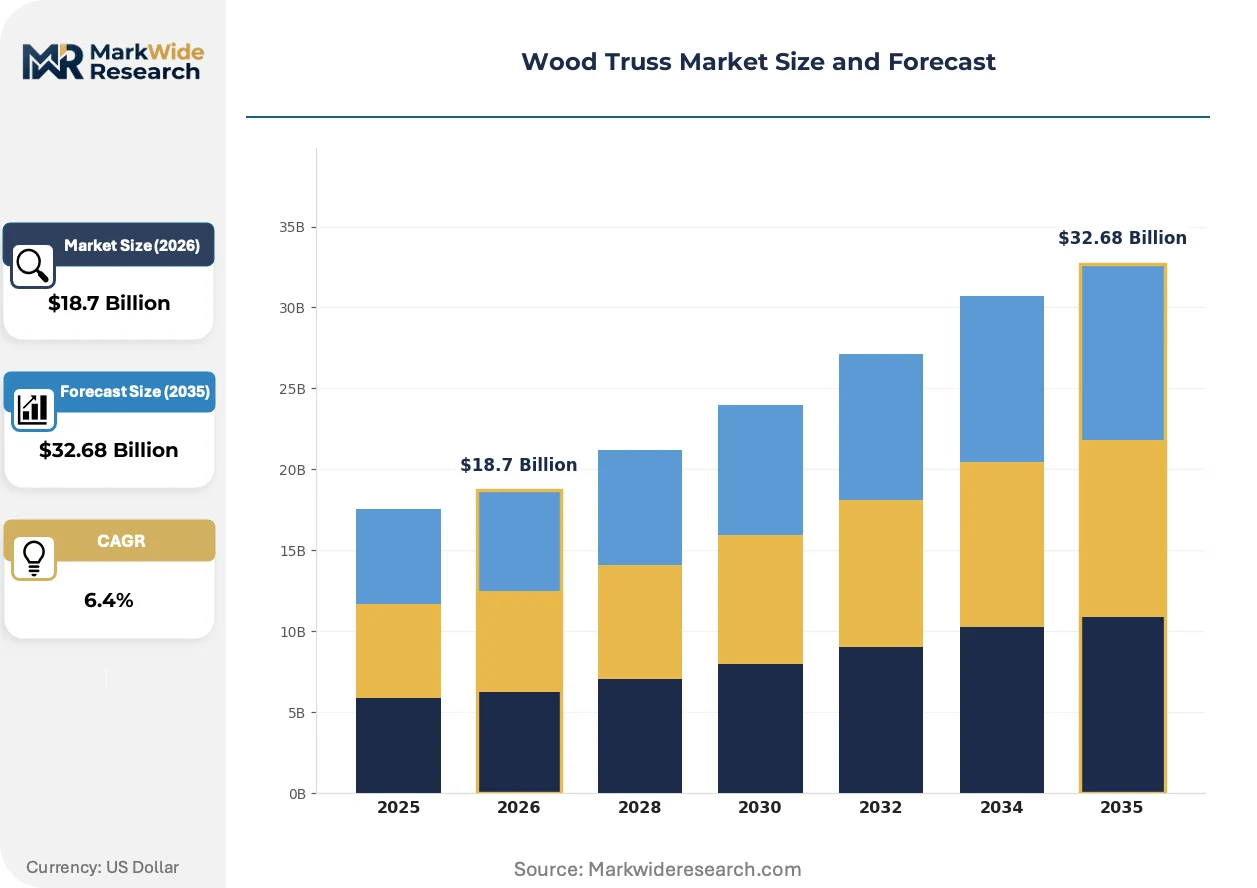
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fink Truss, Gambrel Truss, Howe Truss, Mono Truss Application: Residential Buildings, Commercial Buildings, Industrial Structures, Agricultural Facilities Installation Type: Prefabricated, Custom-Built, On-Site Assembly, Modular End User: Contractors, Architects, Builders, Developers |
| Companies Covered | Foxworth-Galbraith Lumber, Ridgway Roof Truss, UFP Industries, Ramona Lumber, Littfin Truss, Builders FirstSource, Parr Lumber, Carter Lumber, The Truss Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood Truss Market Evolving Landscape
Digital fabrication workflows and automated plate-pressing equipment are compressing production cycle times while enabling geometric complexity previously uneconomical at volume.
Building information modeling is converging with CNC-enabled fabrication equipment to enable direct-to-machine cutting files that eliminate manual layout errors and reduce dimensional lumber waste below 5% in optimized facilities. Multi-family developers in the Pacific Northwest are specifying these digitally integrated truss packages for podium-style construction. The structural consequence is compressing pre-construction engineering from weeks to days while enabling mass customization at production-scale economics.
EPA formaldehyde emission standards under the Toxic Substances Control Act Title VI are tightening certification requirements for laminated veneer lumber and oriented strand board chords used in high-performance truss designs. Fabricators must maintain chain-of-custody documentation from panel supplier through final assembly. The residential segment bears the primary compliance burden, with builders in California and the Northeast demanding CARB Phase 2 or EPA TSCA Title VI labels as baseline specification requirements.
Componentized procurement is displacing site-built alternatives as national homebuilders consolidate supplier relationships around turnkey structural package providers. Regional distributors are responding by adding in-house truss design capabilities and direct mill relationships. This pattern concentrates most visibly in the southeastern United States, where production builders execute repetitive floor plans across multi-community portfolios and prioritize schedule certainty over per-component price optimization.
Wood Truss Market Segmentation
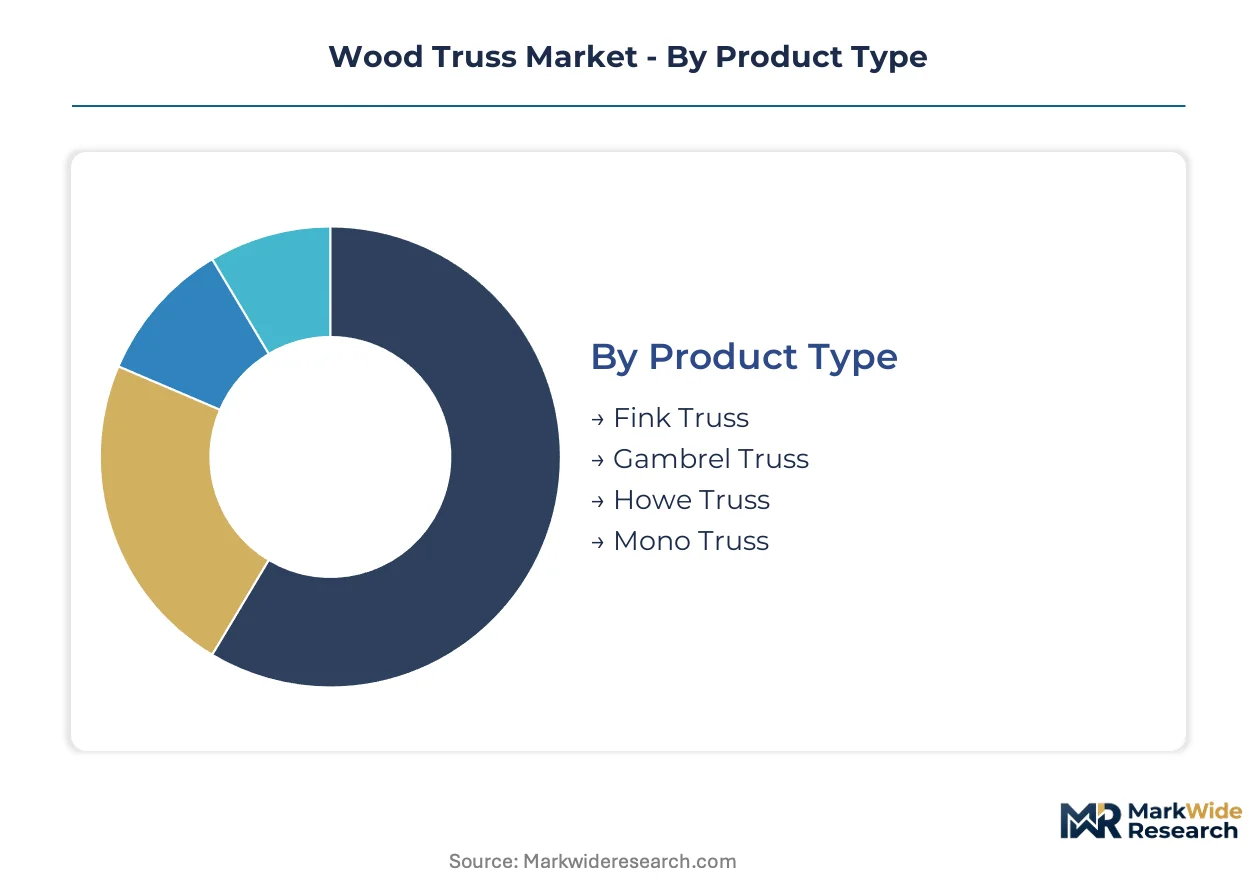
Wood truss procurement patterns diverge sharply between standardized residential production and complex commercial geometry. Fabricators configure equipment, labor, and design workflows around specific segment profiles rather than serving uniform demand.
Product Type:
Customization intensity varies from mass-produced web patterns to architecturally complex profiles requiring specialized engineering labor.
- Fink Truss:Triangular web configuration with internal W-pattern bracing dominates residential pitched roof applications. Georgia and Florida production builders specify Fink configurations for repetitive subdivision layouts where engineering standardization minimizes per-project design costs.
- Gambrel Truss:Double-slope profile creates expanded attic volume for storage or living space. Agricultural facilities in the Carolinas and dairy operations across Wisconsin specify Gambrel systems for functional headroom requirements.
- Howe Truss:Diagonal compression members with vertical tension rods suit longer commercial spans.
- Mono Truss:Single-slope design serves lean-to additions and modern residential aesthetics.
Most installed capacity flows through Fink Truss configurations. Expansion is steepest in Gambrel Truss as agricultural building retrofits accelerate.
Application:
Structural loading requirements and code complexity separate high-volume residential from engineering-intensive commercial verticals.
- Residential Buildings:Single-family and multi-family housing consumes standardized truss packages with repetitive span tables. National homebuilders in Texas, Arizona, and North Carolina consolidate procurement around regional fabricators offering 48-hour turnaround on standard designs.
- Commercial Buildings:Office, retail, and hospitality structures demand project-specific engineering for longer spans and heavier mechanical loads. Minneapolis and Portland architects specify engineered wood roof systems for five-to-twelve-story mass timber buildings.
- Industrial Structures:Manufacturing and warehouse facilities require heavy-duty floor trusses for concentrated equipment loads.
- Agricultural Facilities:Barns, equipment storage, and livestock buildings prioritize cost per square foot over architectural refinement.
Residential Buildings absorb the majority of production volume. Commercial Buildings are climbing the fastest as mass timber code adoption accelerates mid-rise specification.
Installation Type:
Field labor substitution versus design flexibility defines the procurement calculus across builder types.
- Prefabricated:Factory-built components with pre-pressed connector plates arrive crane-ready for rapid field installation. Production builders across the southeastern United States specify prefabricated packages to compress framing schedules and reduce skilled carpenter dependence.
- Custom-Built:Site-fabricated trusses assembled from loose lumber and plates suit remote locations or non-standard geometries.
- On-Site Assembly:Pre-cut chord and web members assembled at the construction location.
- Modular:Complete structural modules integrating trusses with wall and floor systems.
Prefabricated systems command the dominant share of installed volume. Modular approaches are gaining share fastest as off-site construction methods mature.
End User:
Technical sophistication and procurement scale separate price-sensitive volume buyers from specification-driven design professionals.
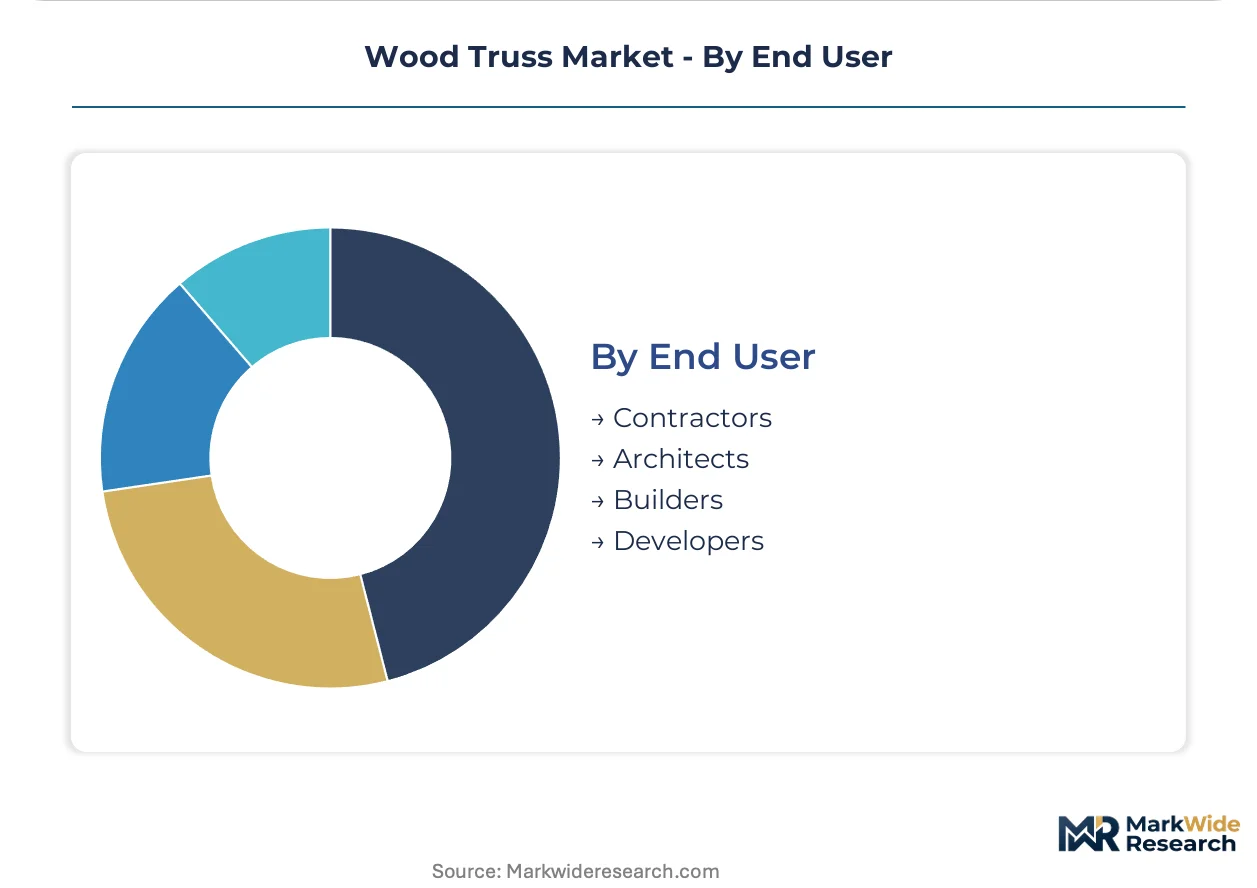
- Contractors:Framing and general contracting firms prioritize schedule certainty and lump-sum pricing for competitive bidding. Texas and Florida roofing contractors maintain standing orders with regional fabricators for standard residential configurations.
- Builders:Production and custom home builders consolidate supplier relationships around turnkey structural packages.
- Architects:Design professionals specify engineered wood systems for aesthetic and sustainability objectives.
- Developers:Multi-project portfolio owners negotiate master service agreements for cost predictability.
Contractors channel the largest volume of truss procurement. Architects are expanding their specification influence fastest as mass timber and carbon accounting reshape material selection criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The southeastern United States anchors wood truss fabrication capacity, with Georgia and the Carolinas hosting dense clusters of component manufacturing facilities serving regional housing markets.
United States
Residential construction in Texas, Florida, and North Carolina drives prefabricated truss procurement as national homebuilders compress framing schedules. The International Code Council's Type IV-A, B, and C mass timber classifications now permit eighteen-story wood structures, opening mid-rise commercial verticals. Minneapolis and Portland architects specify engineered wood roof systems for five-to-twelve-story buildings seeking embodied carbon reductions.
Canada
British Columbia mass timber projects absorb specialized truss capacity as Vancouver developers pursue tall wood building certifications. Canadian softwood lumber tariffs create input cost volatility for cross-border fabricators. Quebec's engineered wood research clusters advance CNC fabrication protocols for complex commercial geometry.
Germany
Bavarian timber engineering firms supply hybrid steel-wood systems for Central European commercial construction. The country's national building regulator enforces rigorous fire-resistance testing for mass timber assemblies exceeding seven stories. Stuttgart and Munich architectural practices specify carbon-accounted structural packages for publicly procured projects.
Japan
Tokyo's post-and-beam construction traditions adapt prefabricated truss methods for seismic-resistant mid-rise housing. METI promotes wooden building initiatives through procurement preferences for municipal structures. Osaka-based fabricators integrate automated plate-pressing equipment with traditional joinery techniques.
Australia
New South Wales and Victoria multi-family developers specify prefabricated floor trusses for podium-style construction above retail bases. The country's national construction code regulator revises timber height allowances following international mass timber precedents. Melbourne engineering consultancies pioneer design-assist contracting models with regional fabricators.
Wood Truss Market Competitive Landscape
Global majors compete with regional champions across distribution reach and fabrication specialization. The vendor base separates into turnkey structural package providers, component specialists, and vertically integrated lumber-processor-fabricators. Three archetypes dominate: national distributors with contractor relationships, regional custom geometry specialists, and backward-integrated fiber-to-component operators. Competitive moves concentrate on design-assist service expansion and automated fabrication technology deployment.
Among North American fabricators, UFP Industries, Builders FirstSource, and Littfin Truss occupy distinct positioning vectors. UFP Industries exemplifies backward integration from lumber procurement through component fabrication. Builders FirstSource anchors the national distribution tier through contractor relationship density. Littfin Truss represents the custom geometry specialization archetype for commercial roof systems.
| Leading Market Players |
|---|
| Foxworth-Galbraith Lumber |
| Ridgway Roof Truss |
| UFP Industries |
| Ramona Lumber |
| Littfin Truss |
| Builders FirstSource |
| Parr Lumber |
| Carter Lumber |
| The Truss Company |
| Others |
Value Network & Pricing Analysis
Family-owned regional fabricators across the southeastern United States anchor pricing discipline through multi-generational mill relationships and conservative leverage profiles, insulating component costs from volatile spot lumber swings while constraining margin expansion during fiber price troughs.
Pricing Analysis
Dimensional lumber and oriented strand board chord inputs transmit directly to truss package quotations, with fabricators adjusting weekly spot pricing to Canadian softwood tariff exposure and regional milling capacity constraints. Price differentiation hinges on grade certification and volume scale, with CARB Phase 2-compliant laminated veneer lumber commanding premiums in California and Northeast markets while standard-grade configurations serve price-sensitive production builders in Texas and Florida. Cost compression in standard residential packages is intensifying because national homebuilders consolidate procurement around turnkey structural providers. Production builders exhibit highest price sensitivity, prioritizing per-square-foot cost predictability over component-grade optimization, while mass timber architects demonstrate lowest sensitivity, accepting premium engineering for embodied carbon accounting.
Supply Chain Analysis
Reverse-logistics flows for steel connector plates remain underdeveloped, with spent galvanizing scrap and defective plate batches lacking systematic reclamation pathways to specialty roll-forming suppliers concentrated in Ohio and Indiana. Primary material sourcing draws from Canadian softwood lumber, southeastern US dimensional milling, and laminated veneer lumber producers in Louisiana and Arkansas. Supply chain risk centers on single-source vulnerability for galvanized truss plates during raw steel allocation periods. Distribution runs through national contractor relationships anchored by regional fabrication hubs serving 200-mile delivery radii.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The International Code Council's Type IV-A, B, and C mass timber classifications function as a regulatory compounder, expanding permitted wood construction to eighteen stories and structurally enlarging addressable demand for engineered floor and roof systems.
For Market Incumbents: Anchor southeastern US capacity positions through direct mill relationships and automated plate-pressing equipment deployment to defend against emerging design-assist specialists capturing commercial specification influence. Deepen backward integration into laminated veneer lumber procurement to offset Canadian softwood tariff volatility and secure CARB Phase 2 certification continuity.
For New Entrants and Emerging Players: Regional design-build contractors represent the most accessible channel partner type for market entry, particularly in Minneapolis and Portland where mass timber code adoption outpaces local fabrication capacity. Target five-to-twelve-story commercial verticals with turnkey structural packages bundling truss engineering with CNC-enabled dimensional cutting. Pursue carbon-accounted procurement channels through environmental product declaration alignment and whole-building life-cycle assessment integration.
For Investors and Strategic Acquirers: Private-equity-backed building products platforms are the most active acquirer in this space, rolling up regional fabricators to achieve national contractor coverage. The five-to-ten-year viability window favors targets with established design-assist capabilities and automated fabrication technology deployment. Monitor mass timber fire-resistance certification velocity as the critical inflection indicator for commercial segment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Design-Assist Service Expansion | Captures engineering value previously retained by structural intermediaries in commercial projects. |
| Automated Plate-Pressing Deployment | Compresses production cycle times while enabling geometric complexity for custom roof systems. |
| Backward Integration into LVL Procurement | Secures CARB Phase 2-compliant chord supply for California and Northeast specification requirements. |
| CNC Fabrication Technology Investment | Eliminates manual layout errors and reduces dimensional lumber waste below 5% in optimized facilities. |
| Carbon Accounting Integration | Positions wood truss systems for publicly procured projects through environmental product declaration alignment. |
Research Methodology
Multiple input streams — structured interviews with truss fabricator executives, regional contractor procurement leads, and mass timber project architects — were reconciled against secondary validation from International Code Council proceedings, EPA TSCA Title VI certification databases, and southeastern US housing start permits. Primary fieldwork engaged component manufacturing plant managers, design-build contractor operations directors, and laminated veneer lumber supplier technical sales teams. Secondary sources encompassed building permit filings, customs trade data on Canadian softwood imports, and SEC disclosures from publicly traded building products distributors. Bottom-up volume modeling triangulated against top-down construction spending allocations.
Data-stream reconciliation anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, application vertical, installation method, and end-user procurement archetype. CAGRs derived from historical volume trajectories and forward construction pipeline assessments. Industry-specific forecast inputs incorporated mass timber code adoption timelines and regional housing start clustering patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lumber price volatility cycles and fire-resistance certification velocity for mass timber assemblies. Practitioners should monitor International Code Council height allowance revisions and galvanized steel plate supply allocation announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Europe Building Materials Market
Building & Construction Materials
Corrugated Polycarbonate Panels Market
Building & Construction Materials
Stone Veneer Market
Building & Construction Materials
Basalt Fiber Reinforced Polymer BFRP Market
Building & Construction Materials
Traffic Road Marking Coatings Market
Building & Construction Materials
Global Drywall Textures Market
Building & Construction Materials
Architectural Acoustic Panels Market
Building & Construction Materials
Lightweight Composite External Access Panels and Doors Market
Building & Construction Materials
Spray Foam Insulation Market
Building & Construction Materials
Vinyl Windows Market
Building & Construction Materials
Asia-Pacific Ceramic Sanitary Ware Market
Building & Construction Materials
Roofing Underlay Market
Building & Construction Materials
USA and Canada Pre-Painted Steel Roofing and Cladding Market
Building & Construction Materials
Global Roofing Market
Building & Construction Materials
Fire Hydrant System Market
Building & Construction Materials
GCC Exterior Sheathing Market