
 Building and Construction Plastics Market | 2026-2036
Building and Construction Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Building and Construction Plastics Market Analysis
Direct-to-contractor distribution is fragmenting as digital procurement platforms and regional bulk distributors erode traditional wholesale hierarchies. BASF leverages its integrated polyamide and polyurethane complexes to secure specification lock-in with major European infrastructure consortia. Dow competes through geographic dominance in North American polyethylene supply, anchoring its position with on-spec resin continuity for extruded building products. SABIC differentiates via high-heat polycarbonate formulations that serve Middle Eastern facade projects where solar gain thresholds are stringent.
Building and construction plastics encompass thermoplastic and thermoset polymer formulations engineered for structural, insulating, cladding, and utility applications in residential, commercial, and civil engineering projects, typically specified by flame-retardancy ratings, tensile modulus, and thermal conductivity coefficients below 0.04 W/m·K. These materials substitute for concrete, timber, and metal in weight-critical or corrosion-exposed assemblies where installation speed and thermal bridging reduction determine lifecycle cost. Polyvinyl chloride occupies the largest volume position across window frame and piping applications where cost-per-meter and weldability sustain its mature margin pool. Polycarbonate represents the fastest-growing chemistry segment in roofing and daylighting systems where impact resistance and UV stability command specification premiums.
EPA regulations on volatile organic compound emissions from building products are reshaping adhesive and sealant formulations, while REACH restrictions on phthalate plasticizers are forcing PVC compounders toward bio-based or non-orthophthalate alternatives. China's MEE enforcement of dual carbon goals is tightening polymer production emissions thresholds, redirecting capital toward lower-carbon feedstock routes. Stakeholders must monitor how evolving EPD requirements and embodied carbon accounting standards will re-rank material choices in public procurement frameworks.
Market Dynamics
China's GB standards for building energy efficiency are compressing specification timelines for thermal performance upgrades across residential and commercial construction, forcing polymer suppliers to accelerate formulation cycles for lower-conductivity systems.
Growth Catalysts
- Dual carbon enforcement:China's MEE mandates on embodied carbon are redirecting public procurement toward certified low-carbon polymer systems in facade and insulation applications.
- Urban corridor density:Southeast Asian commercial construction clusters in Vietnam, Indonesia, and the Philippines are outpacing conventional material supply chains, creating specification windows for engineered plastics.
- Thermal bridging mandates:Jurisdictions across Germany, France, and California are tightening U-value requirements for building envelopes, accelerating substitution of metal and concrete with polymer-based thermal breaks.
Market Restraints
- Feedstock volatility:Naphtha and natural gas liquid price swings compress margin predictability for polyethylene and polypropylene compounders serving extruded building products.
- Phthalate substitution friction:REACH restrictions on orthophthalate plasticizers force PVC processors toward bio-based alternatives with shorter formulation track records and higher certification costs.
- Recycling infrastructure gaps:Post-consumer PVC and polycarbonate collection systems remain underdeveloped across Central and Eastern Europe, limiting closed-loop feedstock availability for sustainable product lines.
Strategic Opportunities
- Retrofit acceleration:Germany's building energy efficiency renovation mandates under the EU Green Deal are creating sustained demand for window frame and insulation upgrades using high-performance polymer systems.
- Facade-integrated photovoltaics:Convergence of polycarbonate daylighting panels with thin-film solar laminates is opening specification channels for building-integrated energy generation in Middle Eastern commercial towers.
- Digital procurement platforms:Direct-to-contractor marketplaces are eroding traditional wholesale hierarchies, enabling compounders to capture margin previously allocated to distributor tiers in North American residential construction.
Industry Challenges
- EPD documentation complexity:Third-party verified environmental product declarations require 12-18 month validation cycles, delaying specification entry for reformulated low-carbon compounds in public tenders.
- Flame-retardant formulation expertise:Scarcity of polymer chemists with halogen-free fire-safety certification experience constrains R&D throughput for Class A-rated cladding applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Building and Construction Plastics Market |
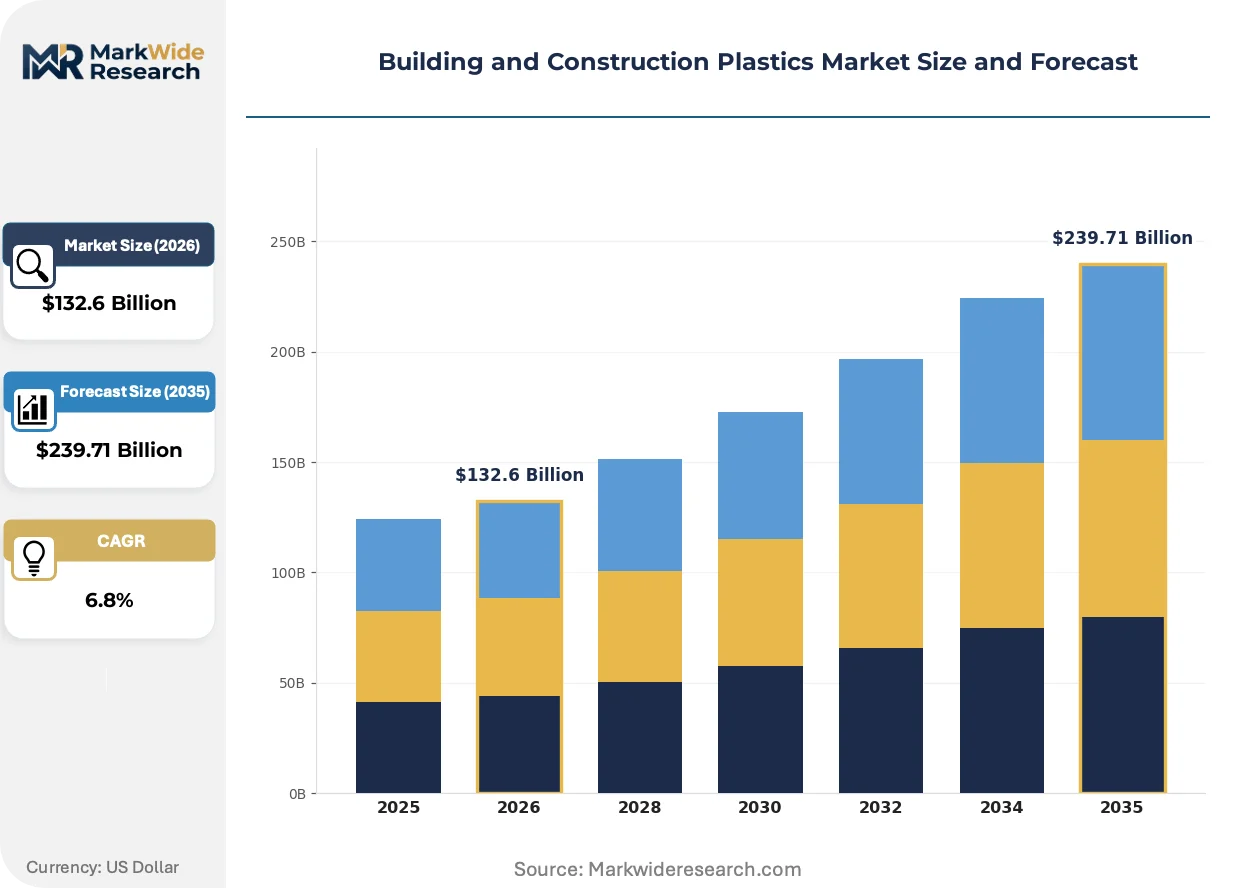
| Market Size in 2026 | $132.6 Billion |
| Market Size in 2035 | $239.71 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polyvinyl Chloride, Polycarbonate, Polystyrene Application: Insulation, Roofing, Flooring, Window Frames End User: Contractors, Architects, Builders, Developers Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | BASF, SABIC, Dow, LyondellBasell Industries Holdings B.V., Borealis GmbH, Formosa Plastics Corporation, INEOS, Solvay, Asahi Kasei Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Building and Construction Plastics Market Emerging Trajectories
Formulation science is converging with digital manufacturing controls to compress development cycles for performance-graded polymer systems, while regulatory pressure on embodied carbon is re-ranking material selection criteria across procurement frameworks.
Polyamide-insulated window profiles are hybridizing glass fiber reinforcement with aerogel fillers to achieve thermal conductivity coefficients below 0.02 W/m·K. European window manufacturers are specifying these systems for passive house certification projects. The technology is hybridizing cost structures across the premium fenestration segment, compressing the performance gap between polymer and triple-glazed timber frames.
EPA regulations on volatile organic compound emissions from adhesive and sealant formulations are forcing reformulation of construction-grade polyurethane and silicone systems. Manufacturers serving the US residential market are accelerating water-based and low-VOC curing chemistry deployment. Flooring and roofing membrane applications face the steepest compliance timelines, with California's CARB standards extending requirements beyond federal baselines.
Contractor buying collectives are consolidating procurement volumes for extruded building products across multi-state residential developers in the southern United States. Traditional two-step distribution through regional building material wholesalers is losing share to direct mill relationships and private-label sourcing arrangements. This concentration is most visible in Texas and Florida metro corridors where production homebuilders specify polymer siding and trim at scale.
Building and Construction Plastics Market Segmentation
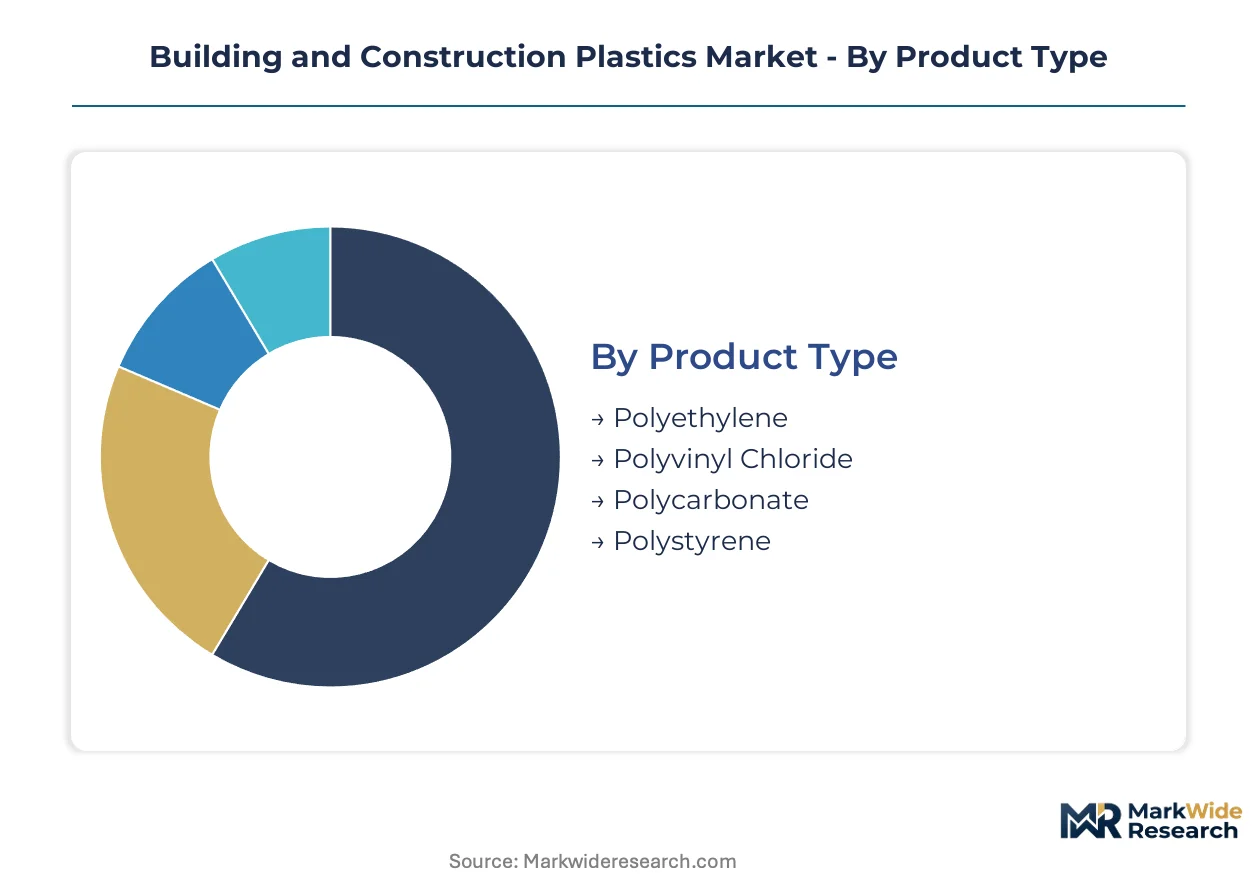
Segmentation in building and construction plastics reveals how specification authority, procurement patterns, and installation requirements vary across material chemistries and project phases. Understanding these divides helps suppliers align formulation investments with the decision-makers who actually control volume.
Product Type:
After-sales service intensity varies sharply across polymer families, with high-performance grades demanding technical field support while commodity resins rely on distributor troubleshooting networks.
- Polyvinyl Chloride:Chlorinated polymer with inherent flame resistance and weldability, formulated with calcium-zinc or organotin stabilizers for outdoor durability. Window frame and piping specifications in Germany and California absorb the largest volumes as thermal bridging codes tighten. REACH phthalate restrictions are forcing compounders toward bio-based plasticizer alternatives with shorter performance track records.
- Polycarbonate:Amorphous thermoplastic with exceptional impact strength and optical clarity, UV-stabilized through co-extruded cap layers. Roofing and daylighting systems in Middle Eastern commercial towers specify these panels where solar gain thresholds exceed 50°C surface temperatures. The material commands specification premiums against acrylic and glass alternatives.
- Polyethylene:Semi-crystalline polyolefin with moisture resistance and flexural fatigue performance, processed through rotomolding or extrusion for geomembranes and vapor barriers.
- Polystyrene:Rigid thermoplastic available in expanded or extruded forms, valued for thermal insulation in below-grade and cavity wall applications where compressive strength requirements are moderate.
Polyvinyl chloride holds the largest share; momentum sits with polycarbonate.
Application:
Cost tier stratification separates specification-grade systems from contractor-grade alternatives, with premium positions commanding 40-60% price multiples over economy formulations.
- Insulation:Rigid foam boards and spray-applied systems engineered for thermal conductivity below 0.04 W/m·K, specified by R-value per inch and compressive strength. Passive house projects in Austria and Belgium are driving demand for vacuum-insulated panels and aerogel-enhanced polymeric systems. China's GB standards are compressing upgrade timelines for existing building stock.
- Window Frames:Extruded profiles in PVC, pultruded fiberglass, or polyamide hybrid constructions, specified by U-value and air infiltration rates. German renovation mandates under the EU Green Deal are sustaining multi-year demand cycles for high-performance fenestration upgrades.
- Roofing:Single-ply membranes, polycarbonate panels, and spray polyurethane foam systems designed for waterproofing and thermal performance across commercial and residential structures.
- Flooring:Resilient surfaces including luxury vinyl tile and sheet goods, specified for wear layer thickness and slip resistance in high-traffic commercial environments.
Insulation dominates volume; window frames are climbing the fastest.
End User:
Customer type determines whether procurement flows through specification influence or direct volume contracting, with architects controlling premium segment access and builders driving commodity scale.
- Contractors:Installation firms executing trade-specific work, purchasing through wholesale distributors or direct mill relationships based on project scale and bonding requirements.
- Developers:Project sponsors controlling capital allocation across multi-building portfolios, consolidating procurement volumes for polymer siding, trim, and insulation across Texas and Florida metro corridors.
- Architects:Design professionals specifying material performance criteria, increasingly requiring EPD documentation and embodied carbon disclosures for public sector tenders.
- Builders:Production homebuilders and custom residential contractors selecting standard-grade formulations based on installed cost and warranty terms.
Developers command the largest aggregate spend; architects are gaining specification influence fastest.
Distribution Channel:
Supply concentration in regional bulk distributors is fragmenting traditional two-step hierarchies as digital platforms capture mid-market project volumes.
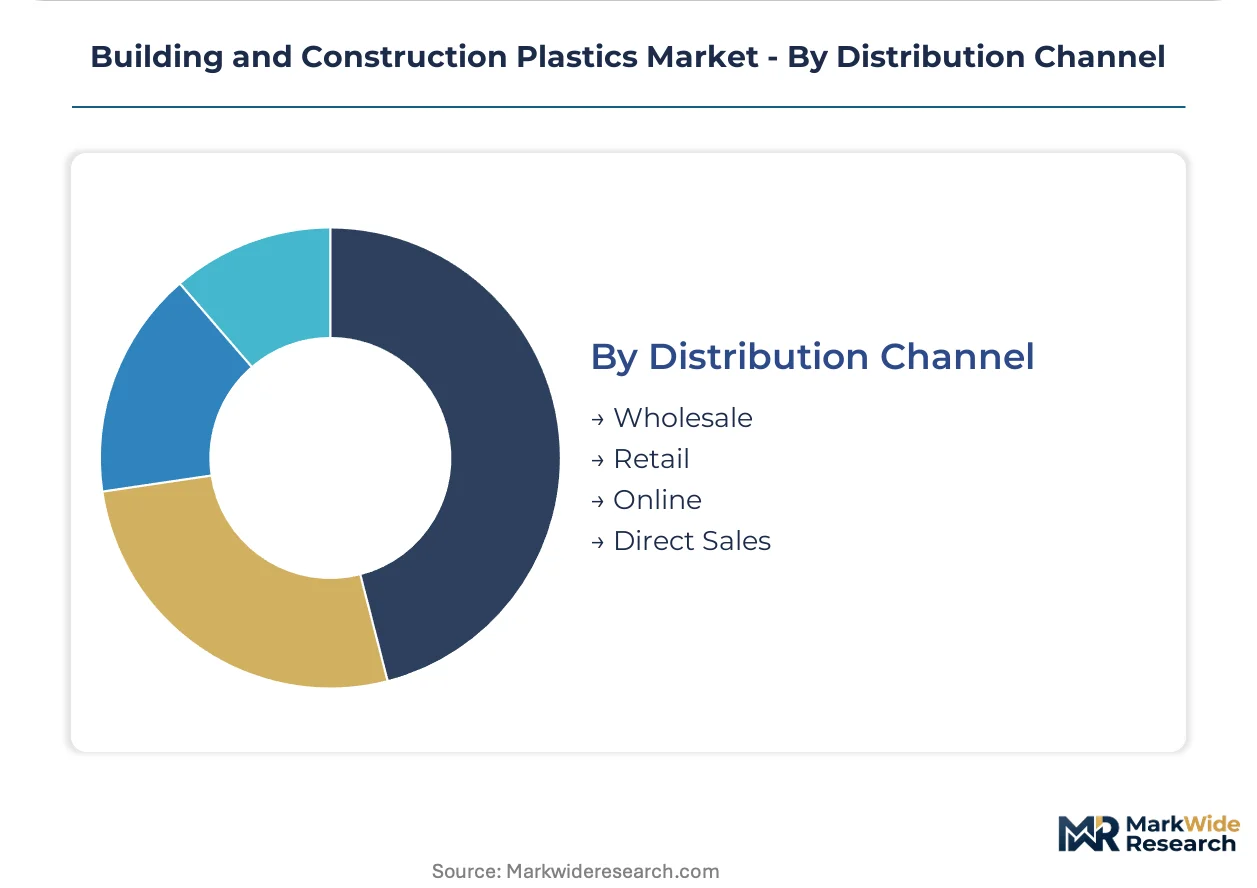
- Wholesale:Regional building material distributors maintaining inventory positions and credit facilities for contractor accounts, losing share to direct procurement in high-volume segments.
- Direct Sales:Manufacturer-to-contractor relationships bypassing distributor margins, concentrated among multi-state residential developers with standardized specifications.
- Online:Digital procurement platforms aggregating contractor demand for extruded products and specialty formulations, eroding traditional wholesale hierarchies in North American residential construction.
- Retail:Big-box and specialty store channels serving repair and renovation volumes, with limited penetration in commercial-grade polymer systems.
Wholesale retains the largest share; online channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese compounders command pricing leverage in polycarbonate facade systems, while Gulf producers struggle to match specification depth despite feedstock advantages. This asymmetry reshapes procurement flows across Middle Eastern commercial towers and Southeast Asian infrastructure corridors.
China
GB standards for building energy efficiency compress retrofit timelines for residential envelopes. MEE enforcement of dual carbon goals tightens polymer production emissions thresholds. Yangtze River Delta manufacturers accelerate low-conductivity polyamide formulations for passive house certification projects.
Germany
EU Green Deal renovation mandates sustain multi-year demand cycles for window frame and insulation upgrades. REACH restrictions on phthalate plasticizers force PVC compounders toward bio-based alternatives. Bavarian fenestration clusters specify aerogel-enhanced profiles for thermal conductivity below 0.02 W/m·K.
United States
EPA regulations on VOC emissions reshape adhesive and sealant formulations for residential construction. Texas and Florida metro corridors concentrate contractor buying collectives for extruded polymer siding. California's CARB standards extend requirements beyond federal baselines for flooring and roofing membranes.
Saudi Arabia
High-heat polycarbonate formulations serve commercial facade projects where solar gain thresholds exceed 50°C surface temperatures. SFDA and municipal building codes tighten fire-safety ratings for cladding applications. Riyadh and Jeddah tower developments specify UV-stabilized daylighting panels against acrylic alternatives.
Vietnam
Rapid urbanization in Ho Chi Minh City and Hanoi corridors outpaces conventional material supply chains. Commercial construction clusters create specification windows for engineered insulation and piping systems. Provincial infrastructure programs absorb polyethylene geomembranes for water management projects.
Building and Construction Plastics Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in formulation and resin supply. The vendor base separates into three distinct layers: integrated petrochemical giants controlling polymer feedstock, regional compounders serving specification-grade applications, and distributed extruders capturing commodity construction volumes. Two strategic moves dominate competitive positioning: backward integration into captive resin production to defend margin predictability, and technology licensing partnerships to accelerate halogen-free flame-retardant certification cycles.
Among European-integrated chemical conglomerates, BASF and Borealis occupy positions anchored in polyamide and polyolefin complexes respectively. Dow represents North American polyethylene supply dominance with geographic concentration in extruded building products. SABIC sits within the high-performance thermoplastics tier serving Middle Eastern and Asian facade specifications.
| Leading Market Players |
|---|
| BASF |
| SABIC |
| Dow |
| LyondellBasell Industries Holdings B.V. |
| Borealis GmbH |
| Formosa Plastics Corporation |
| INEOS |
| Solvay |
| Asahi Kasei Corporation |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta freight corridors carry polymer resin shipments from Shanghai port to inland compounding facilities, with container cost swings compressing margin predictability for extruded building product manufacturers while simultaneously amplifying price differentiation between bulk-contract buyers and spot-market purchasers across Southeast Asian construction corridors.
Pricing Analysis
Configured-to-order polycarbonate facade systems command 35-50% premiums over standard-grade extruded profiles, with pricing stratifying across premium, standard, and economy tiers based on thermal conductivity certification and flame-retardancy ratings. BASF and SABIC capture value through specification-grade polyamide and high-heat polycarbonate formulations, while commodity PVC compounders face cost compression from naphtha feedstock volatility and REACH-mandated phthalate substitution. Large-scale residential developers in Texas and Florida exercise lowest price sensitivity through consolidated procurement volumes, whereas independent contractors in fragmented European renovation markets demonstrate highest sensitivity to per-meter resin costs.
Supply Chain Analysis
Contract manufacturing for extruded building products concentrates among specialized compounders in Germany, China, and the United States, with regional processors in Vietnam and Indonesia capturing emerging specification volumes. The supply chain draws from naphtha-derived polyethylene, chlorine-based PVC feedstock, and bisphenol-A polycarbonate precursors, with single-source vulnerability concentrated in Middle Eastern solar-grade polycarbonate additives. Tariff exposure runs through US-China resin trade flows. Distribution runs through direct mill relationships with multi-state developers and digital procurement platforms eroding traditional wholesale hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: tightening thermal performance mandates and EPD documentation requirements create switching costs that lock in specification relationships with certified compounders.
For Market Incumbents: Pre-empt emerging bio-based plasticizer suppliers by accelerating captive production of calcium-zinc and organotin stabilizer systems for PVC window frame applications. Secure backward integration into low-carbon feedstock routes before China's MEE tightens polymer production emissions thresholds further. Defend specification lock-in with European infrastructure consortia through expanded technical field support for passive house certification projects.
For New Entrants and Emerging Players: Build out halogen-free flame-retardant formulation capabilities to serve Class A-rated cladding specifications in Saudi Arabian and UAE commercial tower developments, where SFDA and municipal fire-safety codes are tightening fastest. Target Vietnam's Ho Chi Minh City corridor for polyethylene geomembrane supply to provincial water management programs, penetrating through direct contractor relationships bypassing established wholesale networks.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking to divest non-core construction polymer assets with stranded formulation expertise in high-performance thermal breaks. Long-term viability hinges on positioning within low-carbon certification pipelines serving EU Green Deal renovation mandates. Monitor MEE enforcement actions on dual carbon goals as the signal for accelerated consolidation among Chinese compounders lacking emissions-compliant feedstock routes.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Carbon Feedstock | Captive bio-based naphtha routes defend margin predictability against MEE emissions enforcement. |
| Halogen-Free Flame-Retardant Certification | Class A-rated formulation expertise unlocks specification channels in SFDA-regulated Middle Eastern towers. |
| Direct-to-Contractor Digital Platform | Mill relationships with Texas and Florida developers capture distributor margins in residential construction. |
| Aerogel-Enhanced Polyamide R&D Partnership | Thermal conductivity below 0.02 W/m·K secures passive house certification with Bavarian fenestration clusters. |
| EPD Documentation Acceleration Program | Third-party verification compression from 18-month cycles enables faster public tender entry in Germany. |
Methodological Framework
A spread of perspectives from polymer plant managers, procurement leads at European window manufacturers, distribution channel partners in Southeast Asia, and technical R&D directors at integrated chemical conglomerates converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with downstream specification influencers and upstream resin supply specialists. Secondary validation drew from customs and trade data tracking polyethylene and polycarbonate flows, ACC and Cefic industry reports, SEC 10-K filings from listed chemical producers, and GB standard documentation from China's Standardization Administration. Bottom-up volume modeling triangulated against top-down value estimates across product chemistry and application segments.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning polymer chemistry families, thermal performance grades, end-use applications, and regional procurement clusters. CAGRs derived from regression analysis of historical volume trajectories adjusted for regulatory enforcement timelines and retrofit mandate acceleration. Industry-specific forecast inputs incorporated MEE dual carbon policy implementation schedules and EU Green Deal renovation obligation phase-ins.
Practitioners should monitor feedstock price volatility, phthalate substitution compliance costs, and EPD validation cycle compression for early signals requiring forecast revision. Quarterly review of MEE enforcement intensity, REACH restriction expansion proposals, and contractor buying collective formation rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Global Fiber Cement Siding Market
Building Materials
Granite Market
Building Materials
Europe Fiber Cement Market
Building Materials
Cross Laminated Timber (CLT) Market
Building Materials
Latin America Facade Market
Building Materials
Poland Architectural Coatings Market
Building Materials
Global Builders Joinery and Carpentry of Wood Market
Building Materials
GCC Concealed Cistern Market
Building Materials
Gravity Retaining Wall Market
Building Materials
Canada Architectural Coatings Market
Building Materials
Fly Ash Bricks Market
Building Materials
Asia-Pacific Building and Construction Sheets Market
Building Materials
India Concrete Admixtures Market
Building Materials
Asia-Pacific Cement Market
Building Materials
Asia-Pacific White Cement Market
Building Materials
Spain Cement Market