
 Spain Cement Market | 2026-2036
Spain Cement Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Cement Market Insights
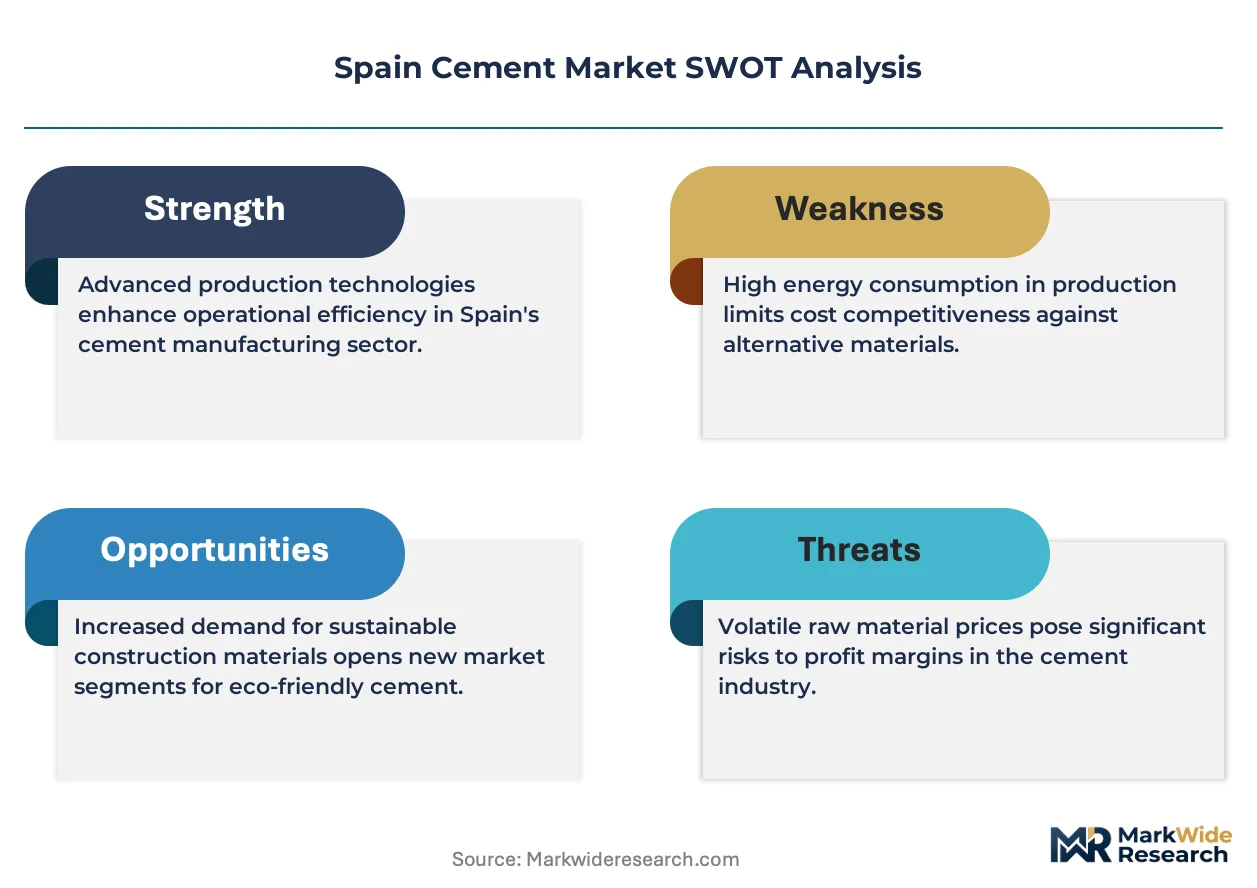
UNE-EN 197-1 cement conformity certification is reorganizing competitive access across Spain's domestic market, raising compliance costs for smaller producers. Heidelberg Materials sustains integrated quarry-to-distribution operations across the Cantabrian coast. CEMEX leverages its Mediterranean logistics network to serve coastal infrastructure projects. Cementos Portland Valderrivas anchors supply relationships with Madrid's metropolitan construction consortiums.
Cement is a hydraulic binder produced by calcining limestone and clay minerals at approximately 1450 degrees Celsius, then grinding the resulting clinker with gypsum to control setting time; its primary function is to bind aggregates into concrete for load-bearing structures. Portland cement occupies the dominant volume position in Spain's commercial and infrastructure applications, though margin pools are shifting toward blended formulations as carbon accounting tightens. White cement specializes in architectural and decorative finishes where aesthetic performance commands premium positioning. Colored cement competes in niche restoration and urban design segments across historic city centers.
Spain's Ministry for Ecological Transition enforces EU ETS compliance for cement kiln emissions, while the Technical Building Code (CTE) mandates specific cement performance classes for seismic zones. The country's national integrated energy and climate plan requires industrial decarbonization pathways that reshape fuel choices and clinker substitution rates. Stakeholders must monitor how EU Carbon Border Adjustment Mechanism implementation affects import competition from North African producers and whether domestic green hydrogen pilot projects at major kiln sites achieve scalable cost structures.
Market Dynamics
Spain's cement sector is compressing around EU ETS carbon pricing mechanics that punish clinker-intensive production while rewarding blended formulations. This structural pivot is redrawing competitive advantage toward producers with limestone clay reserves and alternative fuel infrastructure already in place.
Growth Catalysts
- EU ETS compliance arbitrage:Blended cement formulations with lower clinker factors generate surplus carbon allowances that trade at premium values across Spanish industrial clusters.
- Andalusia housing stock modernization:Municipal rehabilitation programs in Seville and Málaga are absorbing rising cement volumes for structural reinforcement and energy efficiency retrofits.
- Alternative fuel substitution:Refuse-derived fuel and biomass co-processing at major kiln sites is cutting fossil fuel exposure while meeting national integrated energy and climate plan targets.
Market Restraints
- Clinker input cost volatility:Petroleum coke and natural gas price swings at Spanish industrial hubs compress margin predictability for integrated producers.
- North African import concentration:Moroccan and Algerian cement flows through Mediterranean ports threaten pricing power in coastal demand centers.
- EU Carbon Border Adjustment Mechanism friction:Upcoming import carbon accounting rules create compliance complexity for cross-border sourcing relationships.
Strategic Opportunities
- Catalonia infrastructure pipeline:Barcelona metropolitan transit expansion and port modernization tenders favor low-carbon cement specifications.
- Green hydrogen pilot scaling:Valencia and Bilbao kiln sites testing H2 fuel substitution could unlock first-mover positioning in zero-clinker production.
- Digital procurement platforms:Construction consortiums in Madrid are consolidating purchase volumes through centralized e-tendering systems that reward certified low-carbon suppliers.
Industry Challenges
- UNE-EN 197-1 certification timelines:Smaller producers face 12-18 month conformity assessment delays that freeze tender eligibility.
- Alternative materials integration:Fly ash and slag supply consistency from Spanish steel and power sectors remains unpredictable for blend formulation planning.
- Kiln engineer scarcity:Specialized pyroprocess expertise is concentrating at major groups, constraining operational upgrades at mid-scale facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Cement Market |
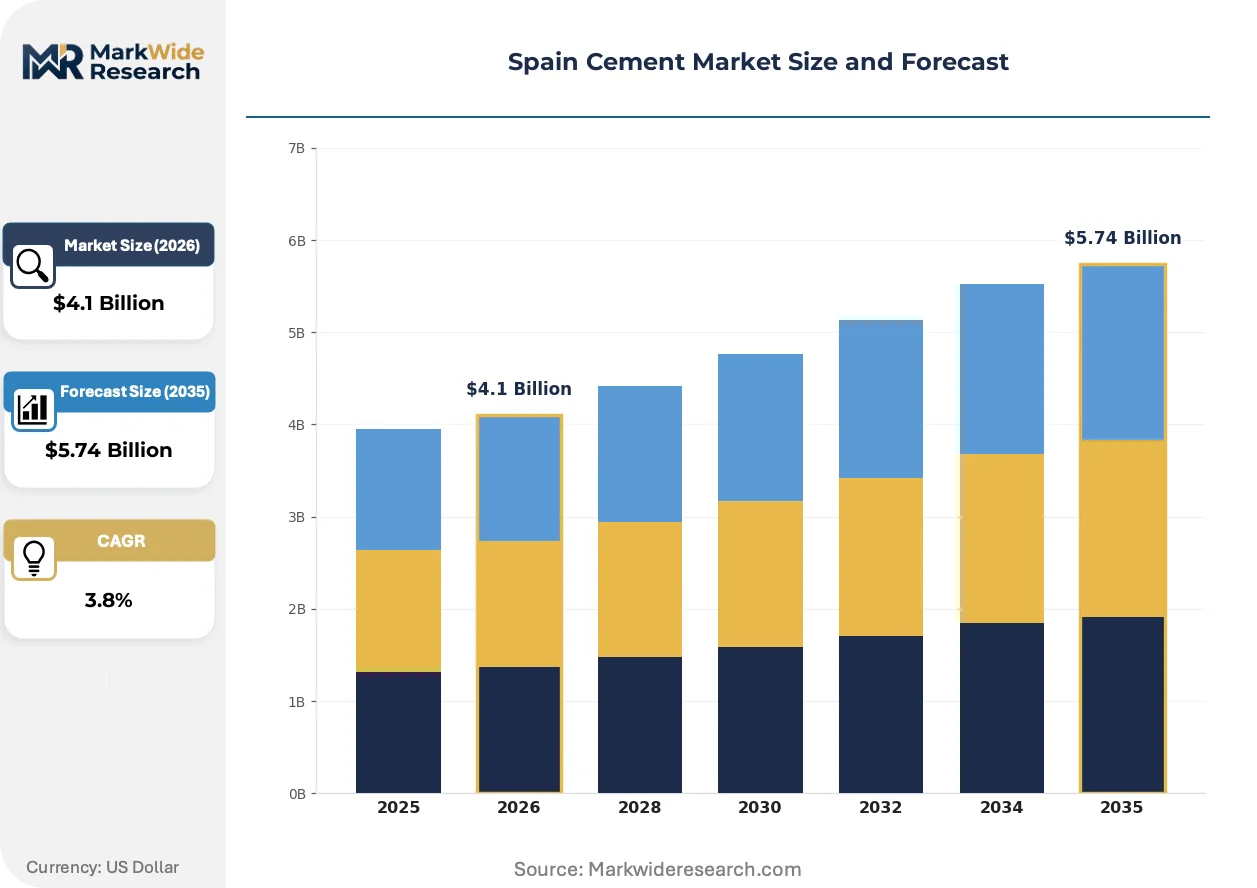
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $5.74 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portland, Blended, White, Colored Application: Residential, Commercial, Infrastructure, Industrial Distribution Channel: Direct Sales, Distributors, Retailers, Online End User: Contractors, Builders, Government, DIY Consumers |
| Companies Covered | Cementos Portland Valderrivas, CEMEX, Heidelberg Materials, Holcim, Cementos Molins, Votorantim, SA Tudela Veguín, Cementos Balboa, CRH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Cement Market Trends and Innovations
Carbon accounting granularity is penetrating every layer of Spain's cement value chain, from quarry blasting protocols to concrete pour documentation. This measurement imperative is accelerating process innovation and procurement specification rewriting across the Mediterranean construction corridor.
Calcined clay activation technology is miniaturizing the carbon footprint of ordinary Portland cement without sacrificing early strength performance. Infrastructure contractors along the Mediterranean corridor are specifying LC3 formulations at accelerating rates for bridge and tunnel projects. The technology is miniaturizing the market share of traditional clinker-heavy products in public tenders where environmental scoring dominates award criteria.
Spain's Ministry for Ecological Transition is enforcing EU ETS compliance timelines that tighten through 2030 with declining free allocation benchmarks. Industrial emitters must secure verified emissions reductions or purchase allowances at auction prices that have doubled since 2021. Cement producers with pre-2000 kiln assets face disproportionate retrofit capital demands compared to newer Mediterranean facilities.
Builder procurement patterns are consolidating around environmental product declarations that document cradle-to-gate carbon intensity. Madrid metropolitan construction consortiums now require EPD-substantiated cement for all public building contracts above threshold values. This documentation mandate favors producers with integrated quarry-to-distribution traceability systems already operational across Castile and León supply zones.
Spain Cement Market Segmentation
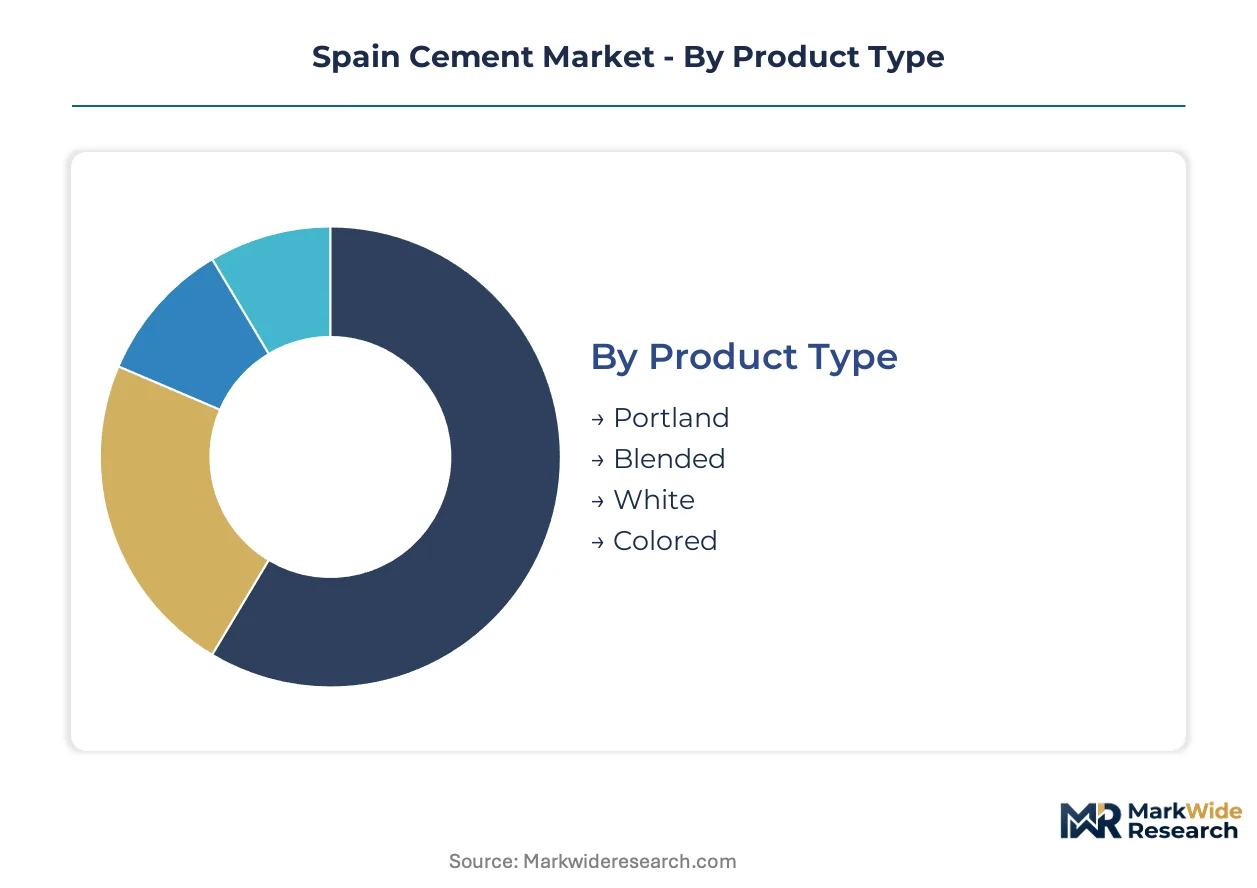
Segmentation in Spain's cement market reveals how carbon pricing and procurement specifications are fragmenting demand across technical grades and supply channels. Each dimension carries distinct margin implications as builders and infrastructure agencies rewrite material specifications.
Product Type:
Substitution pressure from calcined clay and supplementary cementitious materials is reshaping the competitive hierarchy across product categories, with clinker-intensive formulations facing the steepest displacement risk.
- Portland:Ordinary Portland cement contains 95% clinker and 5% gypsum, delivering standardized compressive strength for structural concrete. Seville and Málaga rehabilitation programs absorb substantial volumes for structural reinforcement, though EU ETS carbon costs are eroding margin pools versus blended alternatives.
- Blended:Formulations incorporating fly ash, slag, or limestone reduce clinker factors to 65-80%, cutting carbon intensity per ton. Barcelona metropolitan transit tenders now mandate low-carbon blends, with environmental scoring dominating award criteria for tunnel and bridge concrete.
- White:Low-iron clinker yields aesthetic surfaces for architectural finishes in historic city center restorations.
- Colored:Pigmented formulations serve niche urban design and monument conservation segments across Madrid's heritage districts.
Portland cement anchors the volume base while blended formulations gain share at the steepest rate.
Application:
Cost tier differentiation separates premium infrastructure specifications from commodity residential flows, with carbon certification requirements widening the price spread between tiers.
- Residential:Housing stock modernization across Andalusia and Catalonia drives structural reinforcement and energy efficiency retrofit demand. Municipal rehabilitation programs in Málaga specify standard-grade Portland for cost-sensitive multi-family renovations.
- Infrastructure:Public tenders along the Mediterranean corridor require EPD-substantiated low-carbon cement for projects above threshold contract values. Barcelona port modernization and Valencia transit expansion favor LC3 and blended formulations with verified cradle-to-gate carbon documentation.
- Commercial:Madrid metropolitan construction consortiums consolidate procurement through centralized e-tendering systems that reward certified suppliers with integrated traceability.
- Industrial:Manufacturing facility foundations and warehouse slabs absorb bulk volumes with less stringent environmental scoring than public infrastructure.
Residential construction commands the largest absolute tonnage while infrastructure applications expand most quickly on carbon-adjusted value metrics.
Distribution Channel:
Customer type concentration shapes channel economics, with project scale determining whether direct mill supply or intermediary logistics delivers cost efficiency.
- Direct Sales:Major construction consortiums in Madrid and Barcelona negotiate mill-direct contracts for volume certainty and carbon documentation traceability.
- Distributors:Regional wholesalers serve mid-scale contractors across Castile and León with blended inventory and technical support.
- Retailers:Builder merchants supply bagged cement to small contractors and renovation specialists in urban peripheries.
- Online:Digital procurement platforms are emerging for standardized grades, though bulk concrete remains physically delivered.
Direct sales capture the highest-margin tonnage while distributor networks maintain the broadest geographic coverage.
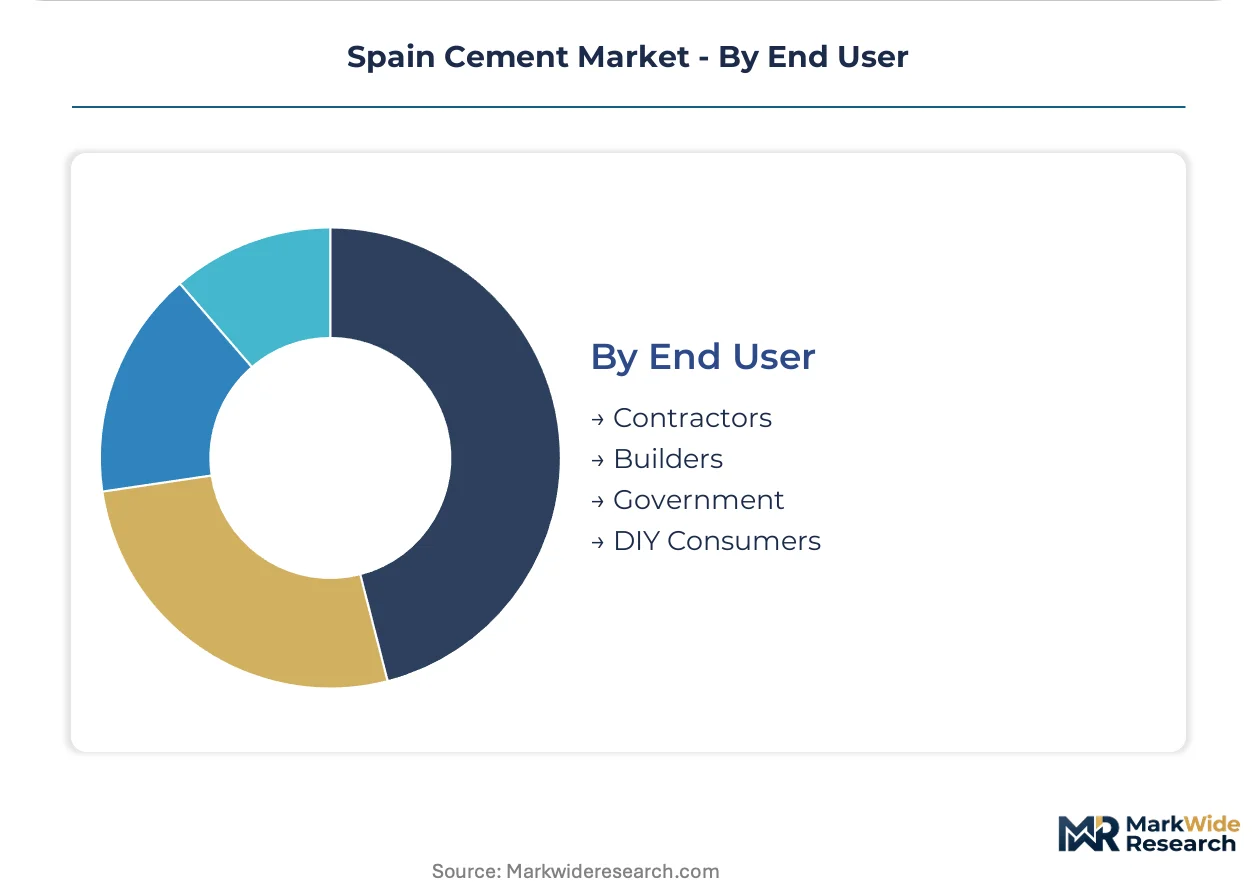
End User:
Maturity divergence separates established contractor relationships from emerging DIY demand, with procurement sophistication varying sharply across user types.
- Contractors:Specialized concrete and masonry firms dominate public infrastructure and commercial project execution, with environmental product declaration requirements now standard for tender eligibility.
- Builders:Residential developers across Andalusia prioritize cost predictability and delivery reliability for multi-unit housing construction.
- Government:Public agencies enforce low-carbon specifications through the Technical Building Code and EU ETS-aligned procurement rules.
- DIY Consumers:Home improvement retailers serve renovation and repair demand with bagged products, representing minimal volume but higher per-unit margins.
Contractor demand anchors the revenue base while government procurement is climbing the fastest on decarbonization-mandated volume growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large construction consortiums in Madrid and Barcelona dominate procurement volumes, while municipal rehabilitation programs across Andalusia and Catalonia absorb blended cement at rising rates. Government infrastructure tenders along the Mediterranean corridor now mandate environmental product declarations for contract eligibility.
Madrid
Metropolitan transit expansion and commercial high-rise construction drive bulk cement consumption. Spain's Technical Building Code enforces seismic performance classes for structural concrete. The Madrid-Castile corridor hosts integrated quarry-to-distribution operations serving central Iberian demand clusters.
Catalonia
Barcelona port modernization and coastal infrastructure tenders favor low-carbon cement specifications. EU ETS compliance timelines tighten through 2030 with declining free allocation benchmarks. The Barcelona metropolitan construction consortium consolidates procurement through centralized e-tendering systems rewarding certified suppliers.
Andalusia
Housing stock modernization in Seville and Málaga absorbs rising volumes for structural reinforcement and energy efficiency retrofits. Municipal rehabilitation programs specify standard-grade Portland for cost-sensitive multi-family renovations. The Guadalquivir industrial belt hosts alternative fuel co-processing facilities cutting fossil fuel exposure.
Valencia
Transit expansion and coastal defense projects generate infrastructure-grade demand with stringent environmental scoring. Spain's national integrated energy and climate plan requires industrial decarbonization pathways reshaping fuel choices. Green hydrogen pilot projects at major kiln sites test scalable zero-clinker production methods.
Basque Country
Bilbao metropolitan industrial foundations and port logistics infrastructure absorb bulk volumes with traceability requirements. The Ministry for Ecological Transition enforces verified emissions reductions or auction purchases for industrial emitters. The Cantabrian coast anchors integrated operations with limestone clay reserves and captive fuel infrastructure.
Spain Cement Market Competitive Landscape
Player mix skews toward integrated multinational groups with quarry-to-distribution control and mid-scale domestic specialists serving regional construction consortiums. Three archetypes dominate: carbon-advantaged blend producers with alternative fuel infrastructure, legacy kiln operators facing disproportionate retrofit capital demands, and coastal logistics players leveraging Mediterranean port access. Competitive moves concentrate on securing alternative material supply agreements and achieving UNE-EN 197-1 certification ahead of tender eligibility windows.
Among Spain-based integrated producers, Cementos Portland Valderrivas and Cementos Molins occupy positions anchoring supply relationships with metropolitan construction consortiums. Heidelberg Materials and CEMEX exemplify multinational archetypes with coastal logistics networks and quarry reserves already compliant with tightening carbon accounting rules. These four represent the competitive core around which mid-scale facilities must secure alternative fuel partnerships or face margin compression from rising EU ETS compliance costs.
| Leading Market Players |
|---|
| Cementos Portland Valderrivas |
| CEMEX |
| Heidelberg Materials |
| Holcim |
| Cementos Molins |
| Votorantim |
| SA Tudela Veguín |
| Cementos Balboa |
| CRH |
| Others |
Pricing and Supply Chain Analysis
UNE-EN 197-1 certification gates both supply qualification and price differentiation simultaneously, forcing producers to absorb conformity assessment costs while competing on carbon-adjusted value metrics across Spanish tender markets.
Pricing Analysis
Long-term offtake contracts with petroleum coke and natural gas indexation dominate procurement between integrated producers and Madrid metropolitan construction consortiums. Price differentiation rests on clinker factor certification grade and verified carbon intensity documentation, with low-carbon blends commanding premiums in Barcelona infrastructure tenders. Cost compression in standard-grade Portland intensifies as North African imports pressure coastal demand centers. Residential developers across Andalusia exhibit highest price sensitivity, while public infrastructure agencies prioritize environmental scoring over unit cost.
Supply Chain Analysis
Mediterranean port congestion at Valencia and Barcelona underwrites distribution economics for coastal logistics networks serving eastern Spanish demand clusters. Clinker production concentrates in Castile and León, Catalonia, and Andalusia, with limestone clay reserves anchoring integrated operations. Raw material dependencies span petroleum coke from Spanish industrial hubs, fly ash from domestic steel sectors, and imported gypsum. Single-source vulnerability to EU Carbon Border Adjustment Mechanism compliance complexity threatens cross-border sourcing relationships. Distribution runs through mill-direct contracts for major consortiums and regional wholesalers for mid-scale contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon accounting services and EPD verification layers expand faster than commodity cement tonnage, creating recurring-revenue opportunities for producers with integrated traceability systems.
For Market Incumbents: Secure alternative fuel supply agreements with waste management operators to lock in refuse-derived fuel and biomass feedstock ahead of national integrated energy and climate plan enforcement. Invest in calcined clay activation capacity to defend margin pools against clinker-intensive displacement. Vertical integration into quarry-to-distribution traceability systems strengthens positioning as Madrid e-tendering systems harden environmental documentation requirements. For New Entrants and Emerging Players: Lead with LC3 formulation specialization targeting Barcelona metropolitan transit and Valencia coastal defense tenders where environmental scoring dominates award criteria. Municipal rehabilitation programs in Málaga and Seville offer penetrable white-space for cost-competitive blended products. Partner with regional distributors in Castile and León to bypass 12-18 month UNE-EN 197-1 certification timelines freezing direct tender eligibility. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational groups divesting pre-2000 kiln assets facing disproportionate EU ETS retrofit capital demands. Long-term viability favors producers with captive limestone reserves and operational alternative fuel infrastructure. Monitor green hydrogen pilot scalability at Valencia and Bilbao sites as inflection indicator for zero-clinker production economics.| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Fuel Infrastructure Buildout | Refuse-derived fuel co-processing cuts fossil exposure while meeting Spain's climate plan targets. |
| Calcined Clay Activation Capacity | LC3 technology miniaturizes carbon footprint without sacrificing early strength performance specifications. |
| EPD Verification System Integration | Cradle-to-gate traceability unlocks Madrid public building contract eligibility above threshold values. |
| Green Hydrogen Pilot Scaling | Valencia and Bilbao kiln sites test H2 fuel substitution for first-mover zero-clinker positioning. |
| Regional Distributor Partnership | Channel control in Castile and León bypasses certification delays freezing smaller producer tender access. |
Research Methodology
The analysis maps clinker-intensive, blended, and novel formulation sub-sectors, each validated through plant managers, procurement leads at construction consortiums, distribution channel partners, and technical R&D directors across Spanish industrial clusters. Primary fieldwork combined with secondary validation from customs and trade data, Oficemen sector reports, EU ETS registry disclosures, and SEC filings of listed parent entities. Bottom-up capacity and consumption modeling triangulated against top-down macroeconomic indicators.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include product type, application, distribution channel, and end user, with regional production hub and carbon intensity tier as industry-specific overlays. CAGRs derived from trend extrapolation of historical consumption patterns adjusted for regulatory phase-in schedules and infrastructure pipeline visibility. Forecast inputs incorporated EU ETS allowance price trajectories and national housing stock rehabilitation program commitments.
Forecasts assume regulatory continuity in EU ETS compliance timelines and Spain's national integrated energy and climate plan; material policy shifts would require re-modeling of clinker substitution rates and free allocation benchmarks. Specific risks include EU Carbon Border Adjustment Mechanism implementation friction, alternative material supply disruption from Spanish steel sector volatility, and green hydrogen pilot cost structure scalability. Practitioners should keep alternative scenarios live as EU ETS auction price dynamics and North African import flow patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
India Aluminum Door and Window Market
Building Materials
United Kingdom White Cement Market
Building Materials
Asia-Pacific White Cement Market
Building Materials
Ductile Iron Pipe Market
Building Materials
Cribbing Blocks Market
Building Materials
Italy Facade Market
Building Materials
Stone Coated Steel Roofing Market
Building Materials
Global Pozzolan Market
Building Materials
Fiber Reinforced Polymer Composites (FRP) Market
Building Materials
Qatar Cement Market
Building Materials
Recycled Concrete Aggregates Market
Building Materials
Building and Construction Plastics Market
Building Materials
Polymer Concrete Market
Building Materials
North America Architectural Coatings Market
Building Materials
East Africa Cement Market
Building Materials
Roof Cover Boards Market