
 Corrugated Polycarbonate Panels Market | 2026-2036
Corrugated Polycarbonate Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Corrugated Polycarbonate Panels Market Insights
The gap between specification-grade corrugated polycarbonate and commodity resin panels is broadening as architects and commercial growers demand certified UV resistance, fire ratings, and load-bearing profiles. Covestro leverages its upstream bisphenol-A and polycarbonate resin operations to control raw material quality and batch consistency for premium architectural channels. Palram Industries differentiates through vertical integration from extrusion to distribution, sustaining cost discipline across greenhouse and skylight segments in North America and Europe.
Corrugated polycarbonate panels are extruded thermoplastic sheets featuring repeating sinusoidal or trapezoidal profiles, typically manufactured from aliphatic-aromatic polycarbonate copolymers with coextruded UV-protective layers measuring 30–50 micrometers. These panels transmit up to 90% of visible light while providing impact resistance sixteen times that of glass, serving primarily as glazing substitutes in agricultural, commercial, and industrial roofing applications. Multiwall panels dominate value capture in cold-climate greenhouse construction where thermal insulation coefficients determine operating economics, while corrugated sheets lead volume in cost-sensitive agricultural roofing across developing markets. The commercial end-user segment anchors margin pools through specification-driven procurement of fire-rated and hail-resistant profiles for transit canopies and retail atriums.
REACH restrictions on bisphenol-A migration and EU Construction Products Regulation (CPR) fire-classification requirements are elevating compliance costs for suppliers serving European commercial construction. The US EPA and OSHA jointly influence market access through VOC emission standards for installation adhesives and workplace exposure limits during on-site cutting and thermoforming. Stakeholders must monitor evolving polymer additive regulations in target markets and assess whether coextrusion investments or formulation partnerships offer more durable compliance pathways.
Market Dynamics
Specification-grade procurement is fragmenting the corrugated polycarbonate market into parallel supply tiers, as certified UV resistance and fire ratings separate premium architectural channels from commodity agricultural roofing.
Growth Catalysts
- EU Construction Products Regulation:Fire-classification mandates under CPR are forcing commercial builders toward certified panels, creating specification-driven demand in transit canopies and retail atriums.
- Greenhouse thermal economics:Multiwall panel adoption is accelerating in cold-climate horticulture where insulation coefficients directly determine heating cost recovery.
- Germany:Large-scale municipal canopy installations and commercial horticultural projects are concentrating procurement of load-bearing, hail-resistant profiles.
Market Restraints
- Bisphenol-A feedstock volatility:Polycarbonate resin prices track benzene and propylene markets, squeezing margin predictability for extruders without captive chemical operations.
- Substitution by ETFE membranes:Tensile architecture projects increasingly specify fluoropolymer films for large-span roofing, compressing addressable volume in stadium and airport segments.
- REACH additive restrictions:ECHA scrutiny of UV stabilizers and flame retardants is extending formulation approval timelines and raising compliance costs for European distributors.
Strategic Opportunities
- India agricultural modernization:Polyhouse subsidy schemes under the MIDH program are creating first-time demand for cost-optimized corrugated roofing among commercial vegetable growers.
- Coextrusion technology convergence:Integration of nanoceramic UV barriers with base polycarbonate is enabling 20-year warranty offerings that commodity extruders cannot match.
- Direct-to-farm distribution:Bypassing traditional building-material wholesalers through agritech platforms is reducing landed cost for greenhouse contractors in emerging horticulture clusters.
Industry Challenges
- Skilled thermoforming technician shortage:Complex radius bending and on-site fabrication of specification-grade panels requires trained crews that remain scarce outside major metropolitan construction markets.
- Multi-certification timeline compression:Simultaneous pursuit of UL fire ratings, Miami-Dade wind uplift approval, and specific project hail resistance is stretching engineering resources at mid-tier extruders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrugated Polycarbonate Panels Market |
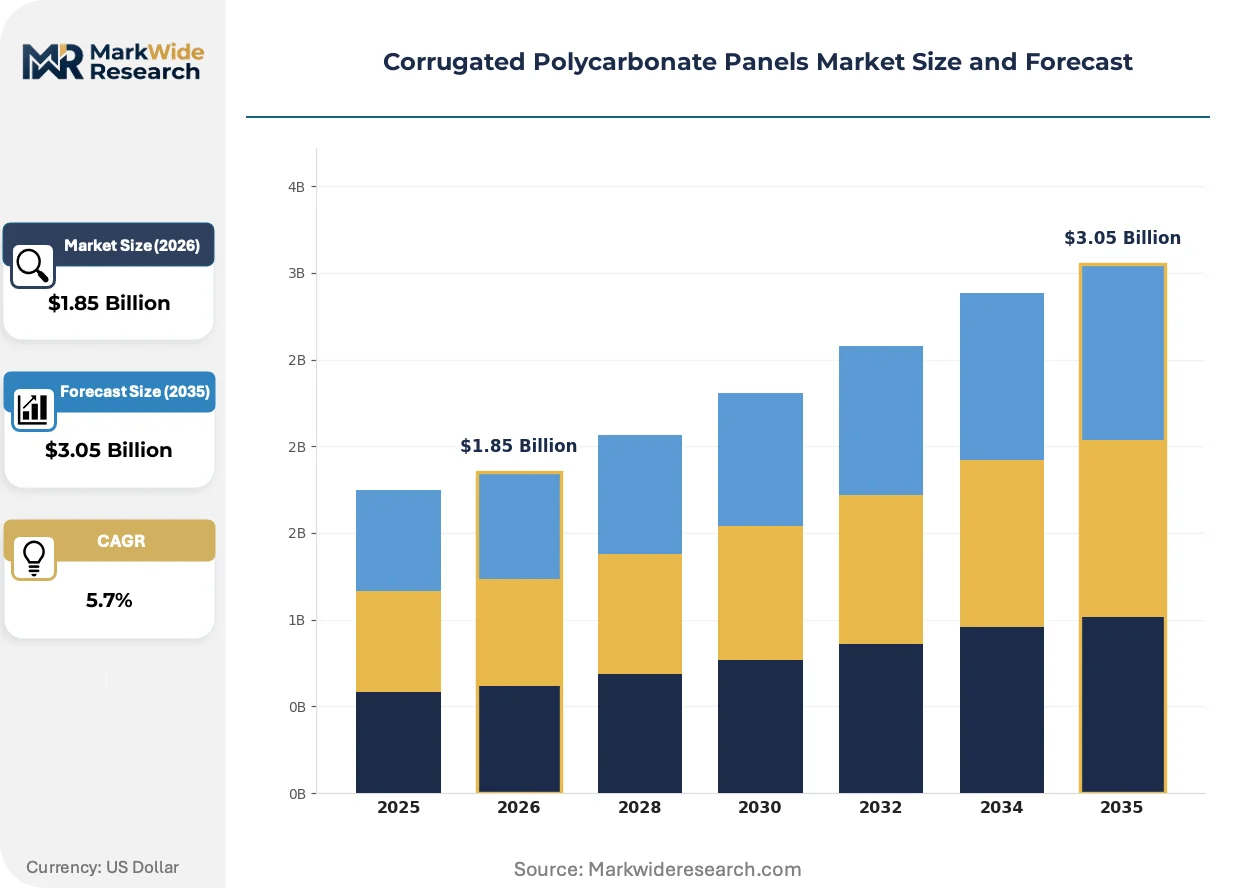
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.05 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Sheets, Multiwall Panels, Corrugated Sheets, Flat Panels Application: Greenhouses, Skylights, Canopies, Roofing End User: Commercial, Residential, Industrial, Agricultural Installation Type: New Construction, Renovation, DIY, Professional |
| Companies Covered | Sabic, Covestro, Palram Industries, UG-Plast, Plazit Polygal, Gallina, Verzatec Group, Brett Martin, Arla Plast AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrugated Polycarbonate Panels Market Trends and Innovations
Material science advances and procurement digitization are compressing product lifecycles while elevating performance benchmarks across agricultural and architectural segments.
Coextruded nanoceramic UV barriers are consolidating technical differentiation in the premium tier, replacing conventional organic absorbers that degrade under high-irradiance conditions. Specifiers in commercial greenhouse and skylight applications are mandating these advanced formulations for projects requiring 20-year service warranties. The technology is consolidating specification authority among extruders with in-house polymer compounding capabilities, marginalizing distributors reliant on commodity resin stocks.
REACH restrictions on halogenated flame retardants are forcing reformulation of roofing panels targeting commercial construction in the European Union. ECHA's 2023-2025 substance evaluation roadmap specifically targets phosphorus-based alternatives, creating uncertainty for suppliers mid-transition. German and Dutch distributors are responding by dual-sourcing from extruders with completed SVHC-compliant certifications and those still in transition, hedging against supply interruption.
Buyer concentration among national greenhouse construction consortia is compressing negotiation cycles and unbundling after-sales technical support from panel supply contracts. Large horticultural developers in the Netherlands and Spain now procure directly from extruders, bypassing regional building-material distributors that previously handled specification translation. This disintermediation is most visible in Almería and Westland, where integrated greenhouse developers specify corrugated polycarbonate as part of turnkey environmental control packages.
Corrugated Polycarbonate Panels Market Segmentation
Corrugated polycarbonate panels fragment across four distinct category axes, each mapping to divergent margin profiles and specification intensities. Product geometry and installation context determine whether procurement flows through agricultural distributors or architectural specification channels.
Product Type:
Thickness, wall configuration, and light transmission specifications separate commodity agricultural roofing from certified architectural glazing.
- Multiwall Panels:These extruded sheets incorporate internal rib structures creating insulating air chambers, delivering thermal resistance coefficients critical for cold-climate greenhouse economics. Dutch and Spanish horticultural developers specify these for integrated environmental control packages where heating cost recovery dominates operating margins.
- Corrugated Sheets:Sinusoidal or trapezoidal profiles manufactured through continuous extrusion dominate volume in cost-sensitive agricultural roofing across India and Southeast Asia. Polyhouse subsidy schemes under India's MIDH program are accelerating first-time adoption among commercial vegetable growers seeking alternatives to polyethylene film.
- Solid Sheets:Monolithic polycarbonate construction provides maximum impact resistance for security glazing and machine guarding applications.
- Flat Panels:Planar extrusions serve interior partition and signage applications where profiled geometry offers no functional advantage.
Volume sits with Corrugated Sheets; growth tilts toward Multiwall Panels.
Application:
Structural load requirements and weather exposure severity determine whether procurement prioritizes hail resistance, fire ratings, or thermal insulation.
- Greenhouses:Controlled-environment agriculture demands panels balancing PAR light transmission with thermal retention, driving specification of coextruded UV barriers and anti-drip coatings. German and Dutch commercial horticultural projects concentrate procurement of load-bearing profiles certified for snow and wind loads.
- Canopies:Transit shelters and retail atriums require fire-rated and hail-resistant profiles meeting EU Construction Products Regulation classifications. German municipal canopy installations anchor specification-grade demand for certified panels with documented impact resistance.
- Skylights:Daylighting applications prioritize visible light transmission and UV blocking for interior fade protection.
- Roofing:Industrial and agricultural roofing applications emphasize cost per square meter and rapid installation.
Procurement concentrates in Greenhouses; specification premiums expand fastest in Canopies.
End User:
Budget authority and technical staff availability determine whether buyers prioritize upfront material cost or lifecycle performance warranties.
- Agricultural:Commercial greenhouse operators and polyhouse contractors dominate volume, with Indian vegetable growers and Dutch horticultural developers representing opposite ends of the specification spectrum. Direct-to-farm distribution through agritech platforms is compressing landed costs for emerging horticulture clusters.
- Commercial:Retail developers and transit authorities anchor margin pools through mandated fire ratings, Miami-Dade wind uplift approvals, and project-specific hail resistance certifications. Multi-certification timelines strain engineering resources at mid-tier extruders serving this segment.
- Industrial:Warehouse and manufacturing facilities prioritize impact resistance and natural illumination for worker safety.
- Residential:Homeowners and small contractors drive DIY channel volume for patio covers and greenhouse kits.
Agricultural buyers move the most volume; Commercial end users capture the steepest expansion trajectory through specification premiums.
Installation Type:
Project scale and labor skill availability determine distribution channel selection and after-sales technical support requirements.
- Professional:Certified installation crews handle complex radius bending and on-site thermoforming for specification-grade commercial projects. Skilled technician scarcity outside major metropolitan construction markets constrains addressable volume for high-performance profiles.
- New Construction:Greenfield commercial and agricultural projects enable integrated panel specification within turnkey environmental control packages.
- Renovation:Retrofit applications require compatibility assessment with existing structural members and weatherproofing systems.
- DIY:Consumer-direct sales of pre-cut panel kits bypass traditional building-material wholesalers.
New Construction anchors volume; Professional installation captures specification premiums as warranty requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Almería and Westland anchor commercial horticultural procurement of corrugated polycarbonate panels, with integrated greenhouse developers specifying these materials within turnkey environmental control packages that span Dutch, Spanish, and German operations.
Germany
Large-scale municipal canopy installations and commercial horticultural projects concentrate procurement of load-bearing, hail-resistant profiles. EU Construction Products Regulation fire-classification mandates under CPR force commercial builders toward certified panels. Bavaria and North Rhine-Westphalia host specification-grade distributors serving transit shelter and retail atrium developers.
Netherlands
Westland's integrated greenhouse developers procure directly from extruders, bypassing regional building-material distributors that previously handled specification translation. National greenhouse construction consortia compress negotiation cycles and unbundle after-sales technical support from panel supply contracts. Dutch horticultural developers specify multiwall panels for cold-climate operations where thermal resistance coefficients determine heating cost recovery.
Spain
Almería's commercial greenhouse operators drive volume for cost-optimized corrugated roofing in vegetable production clusters. Polyhouse development in Murcia and Valencia accelerates first-time adoption among commercial growers seeking alternatives to polyethylene film. Spanish distributors hedge against REACH additive restriction uncertainty by dual-sourcing from extruders with completed SVHC-compliant certifications.
India
Polyhouse subsidy schemes under the MIDH program create first-time demand for cost-optimized corrugated roofing among commercial vegetable growers in Maharashtra and Gujarat. Direct-to-farm distribution through agritech platforms reduces landed cost for greenhouse contractors in emerging horticulture clusters. India's BIS standards influence material specifications for agricultural roofing across Karnataka and Telangana polyhouse developments.
United States
Commercial retail developers and transit authorities anchor margin pools through mandated fire ratings and Miami-Dade wind uplift approvals. EPA and OSHA jointly influence market access through VOC emission standards for installation adhesives and workplace exposure limits during on-site cutting. Skilled thermoforming technician scarcity outside major metropolitan construction markets constrains addressable volume for high-performance profiles.
Corrugated Polycarbonate Panels Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification intensity, with specification-grade extruders capturing architectural channels while resin converters serve cost-sensitive agricultural roofing. The vendor base organizes into three strategic archetypes: upstream resin producers with captive extrusion capacity, standalone sheet extruders with regional distribution networks, and integrated building-material suppliers with in-house compounding capabilities. Dominant competitive moves include backward integration into polymer additive formulation and geographic expansion through agritech platform partnerships.
Within the integrated materials tier, Covestro AG exemplifies upstream resin producers leveraging bisphenol-A and polycarbonate operations to control raw material quality. Palram Industries Ltd. occupies a position among vertically integrated extruders sustaining cost discipline across greenhouse and skylight segments. Sabic represents petrochemical-origin players with captive polymer supply chains serving specification-grade architectural channels.
| Leading Market Players |
|---|
| Sabic |
| Covestro |
| Palram Industries |
| UG-Plast |
| Plazit Polygal |
| Gallina |
| Verzatec Group |
| Brett Martin |
| Arla Plast AB |
| Others |
Pricing and Supply Chain Analysis
Bisphenol-A feedstock costs cascade through extrusion tiers, with resin price volatility transmitted downstream as tiered pricing spreads between specification-grade architectural channels and commodity agricultural roofing. Buyers in Germany and the Netherlands absorb premium markups for REACH-compliant UV stabilizers and CPR-certified fire ratings, while Indian polyhouse contractors negotiate landed costs through direct-to-farm agritech platforms.
Pricing Analysis
Value-based pricing anchors on thermal performance coefficients for cold-climate greenhouse operations, where heating cost recovery justifies premium multiwall panel procurement. Certification grade and volume scale drive differentiation, with UL fire-rated and Miami-Dade wind-uplift-approved profiles commanding architectural premiums. Cost compression in commodity corrugated sheets intensifies as Indian and Southeast Asian extruders compete for MIDH-subsidized polyhouse contracts. Agricultural buyers exhibit highest price sensitivity, while commercial transit canopy developers prioritize lifecycle warranty coverage over upfront panel cost.
Supply Chain Analysis
Direct-to-farm channels handle emerging horticulture demand in India and Spain, bypassing traditional building-material wholesalers that previously managed specification translation. Manufacturing concentrates in Germany, the Netherlands, and China, with extruders in Bavaria and Westland serving specification-grade European markets. Raw material flows draw from bisphenol-A producers, specialty UV stabilizer compounders, and nanoceramic additive suppliers. Single-source vulnerability sits with European distributors dependent on SVHC-compliant additive pipelines amid ECHA transition timelines. Distribution runs through agritech platforms, national greenhouse consortia, and regional architectural specification houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EU REACH additive restrictions and CPR fire-classification mandates erect barrier-to-entry moats for extruders with completed SVHC certifications and in-house polymer compounding capabilities.
For Market Incumbents: Cement specification authority by deepening captive supply of coextruded nanoceramic UV barriers that commodity extruders cannot replicate. Expand compounding capacity in North Rhine-Westphalia to serve German municipal canopy procurement concentrated in Bavaria. ETFE membrane substitution in stadium and airport tensile architecture threatens long-term volume in large-span roofing segments. For New Entrants and Emerging Players: Begin with cost-optimized corrugated sheet production for India's MIDH-subsidized polyhouse sector, where first-time commercial vegetable growers lack specification sophistication. Target Maharashtra and Gujarat greenhouse clusters through agritech platform partnerships that compress distributor margins. Agritech direct-to-farm distribution offers the most penetrable go-to-market angle for bypassing entrenched wholesale channels. For Investors and Strategic Acquirers: ECHA's 2023-2025 substance evaluation roadmap targeting phosphorus-based flame retardants is the leading indicator that formulation-compliant extruders will capture stranded volume from distributors caught mid-transition. Five-to-ten-year viability favors integrated players with backward control over polymer additive supply chains. Acquisition targets include mid-tier extruders with completed SVHC certifications and established relationships with Dutch and Spanish national greenhouse consortia.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into UV Stabilizer Formulation | ECHA REACH compliance timelines favor extruders with in-house additive compounding capabilities. |
| Agritech Platform Partnership | Direct-to-farm channels in India and Spain compress landed costs for polyhouse contractors. |
| Coextrusion Technology Upgrade | Nanoceramic UV barriers enable 20-year warranties that commodity extruders cannot match. |
| Multi-Certification Engineering Investment | Simultaneous UL, Miami-Dade, and hail-resistance approvals unlock commercial canopy specification. |
| Greenhouse Consortium Direct Supply Contract | Bypassing regional distributors captures margin pools in Dutch Westland and Spanish Almería clusters. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with extrusion plant managers, procurement leads at Dutch greenhouse developers, distribution channel partners, and technical R&D directors at polymer additive suppliers. ECHA SVHC candidate list updates, EU Construction Products Regulation certification databases, and Indian MIDH subsidy disbursement records provided validation layers. Bottom-up panel shipment analysis triangulated against top-down construction spending forecasts across agricultural and commercial end-use segments.
Granularity-level modeling tracked product type, application, end-user budget authority, and installation skill requirements across the projection horizon. Multiwall and corrugated sheet volumes were separately projected against cold-climate greenhouse economics and cost-sensitive agricultural roofing demand. CAGRs derived from regression analysis of historical resin price elasticity and specification-grade procurement trends. Forecast inputs incorporated bisphenol-A feedstock volatility patterns and REACH additive restriction implementation timelines.
Underlying measurement precision varies by segment; specification-grade architectural channels carry tighter precision than commodity agricultural roofing due to documented certification audit trails. Forecasts reflect assumptions regarding ECHA regulatory implementation pace and Indian subsidy program continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
GCC Exterior Sheathing Market
Building & Construction Materials
Prefabricated Building System Market
Building & Construction Materials
Global Raised Access Floor Systems Market
Building & Construction Materials
Residential Non-metal Electrical Conduit Market
Building & Construction Materials
Mechanically Fastened Cross-Laminated Timber Market
Building & Construction Materials
Steel Casing Pipes Market
Building & Construction Materials
Clean Room Panels Market
Building & Construction Materials
Residential Elevator Market
Building & Construction Materials
Cement Roofing Sheets Market
Building & Construction Materials
China UPVC Doors and Windows Market
Building & Construction Materials
Engineered Wood Market
Building & Construction Materials
APAC Commercial Glazing System Market
Building & Construction Materials
Europe Particle Board Market
Building & Construction Materials
United Kingdom Prefab Wood Buildings Market
Building & Construction Materials
Epoxy Grout Market
Building & Construction Materials
Glazed Tiles Market