
 Asia-Pacific Cement Market | 2026-2036
Asia-Pacific Cement Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Cement Market Insights
Infrastructure construction is rebalancing the Asia-Pacific cement demand mix as residential activity moderates in saturated Chinese provinces. Anhui Conch Cement Company Limited anchors production scale across central and eastern China through extensive limestone quarry control. SCG leverages its Thai manufacturing base to dominate clinker exports throughout mainland Southeast Asia. UltraTech Cement Ltd. sustains cost leadership in India through captive power generation and integrated logistics networks.
Asia-Pacific cement comprises hydraulic binders manufactured from calcareous and argillaceous materials fired at 1,450°C in rotary kilns, primarily producing calcium silicate compounds that harden through hydration with water. Portland cement occupies the dominant volume position due to universal structural compatibility, while blended cement registers the fastest structural expansion as fly ash and slag incorporation reduces clinker factors and carbon intensity. The technology dimension shows dry-process kilns leading installed capacity, though alternate-fuel systems attract disproportionate capital allocation as coal substitution targets tighten.
China's MIIT enforces GB standards mandating clinker-to-cement ratios below specific thresholds, while India's BIS certifies Portland Pozzolana grades that govern public procurement eligibility. Indonesia's Ministry of Industry promotes domestic clinker capacity under local content regulations that restrict import dependency. Stakeholders must monitor regulatory divergence between carbon-border preparation in developed Asia-Pacific economies and capacity-building imperatives in frontier markets.
Market Dynamics
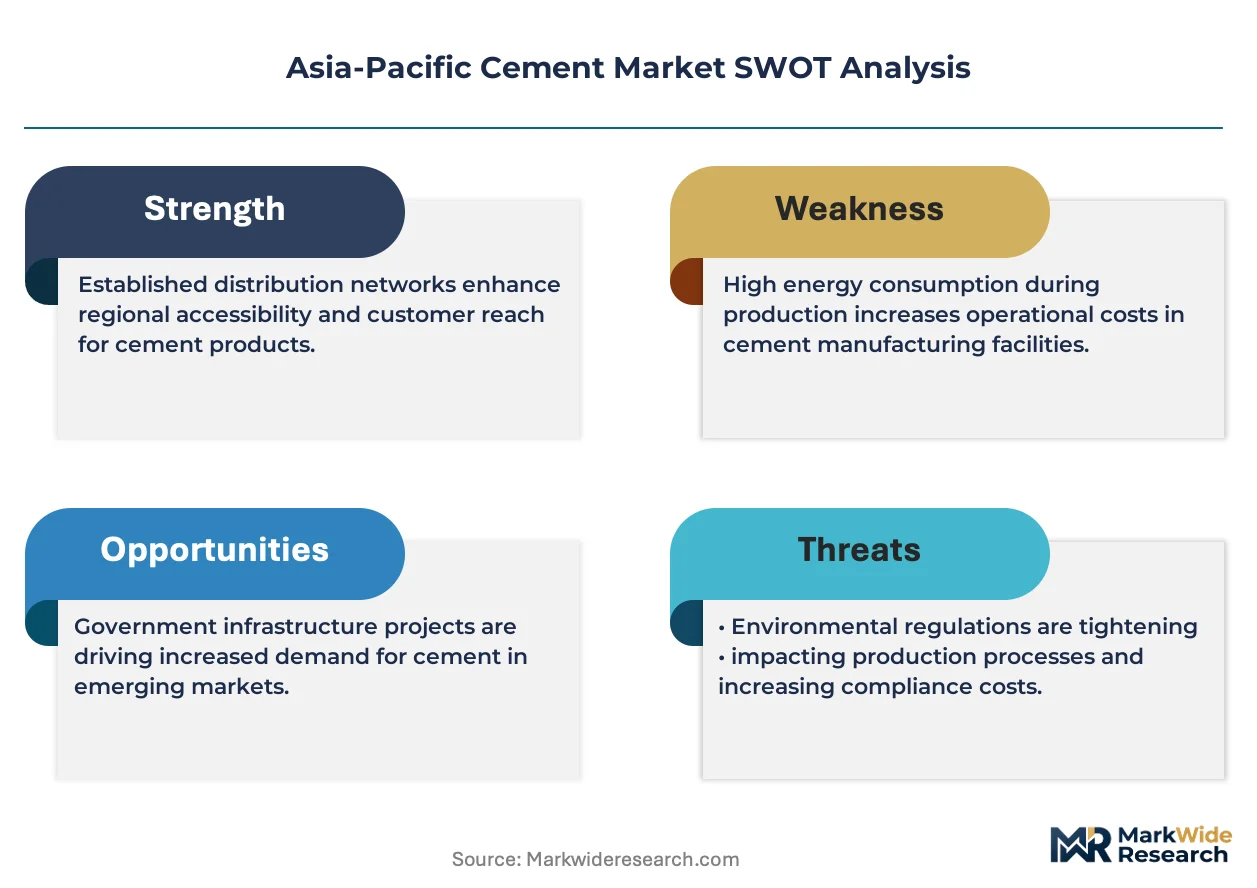
Kiln technology upgrades across China and India are compressing the competitive set as smaller operators face stranded-asset risk from MIIT clinker-factor mandates and BIS energy-efficiency thresholds. The technology transition favors integrated producers with captive limestone reserves and capital access.
Growth Catalysts
- MIIT GB Standards:China's clinker-to-cement ratio ceilings are accelerating dry-process kiln retrofits. Compliance investments concentrate capacity among state-backed producers with balance-sheet depth.
- Southeast Asian Megaprojects:Indonesia's Nusantara capital relocation and Vietnam's North-South expressway corridor are absorbing record cement volumes. Infrastructure procurement favors domestic clinker over imports.
- Blended Cement Formulation:Fly ash and blast-furnace slag incorporation is lowering carbon intensity per ton. Industrial byproduct sourcing agreements are securing feedstock for pozzolanic blends.
Market Restraints
- Coal Price Volatility:Thermal coal remains the dominant kiln fuel across the region. Price spikes in Australian and Indonesian export markets directly compress operating margins.
- Limestone Reserve Concentration:Vietnam and the Philippines hold disproportionate high-grade calcareous deposits. Import-dependent markets face raw-material security constraints.
- Carbon Border Adjustment Mechanisms:Preparatory frameworks in developed Asia-Pacific economies threaten export competitiveness for clinker-intensive producers. Compliance cost differentials are emerging.
Strategic Opportunities
- Philippines Infrastructure Gap:The country's archipelagic geography creates distributed demand nodes. Island-specific grinding plants can bypass Luzon-centric supply chains.
- Alternate Fuel Systems:Municipal solid waste and biomass co-processing technologies are maturing. Early adopters in Thailand and Malaysia are securing waste-stream contracts.
- India's BIS Certification Expansion:Portland Pozzolana and Portland Slag grades are gaining public-procurement preference. Blended product portfolios align with government carbon-intensity targets.
Industry Challenges
- Kiln Engineer Scarcity:Dry-process and alternate-fuel system expertise concentrates among retiring specialists. Training pipelines have not kept pace with technology turnover.
- Legacy Wet-Process Stranded Assets:Older kilns in frontier markets face prohibitive retrofit economics. Asset write-downs are compressing regional profitability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Cement Market |
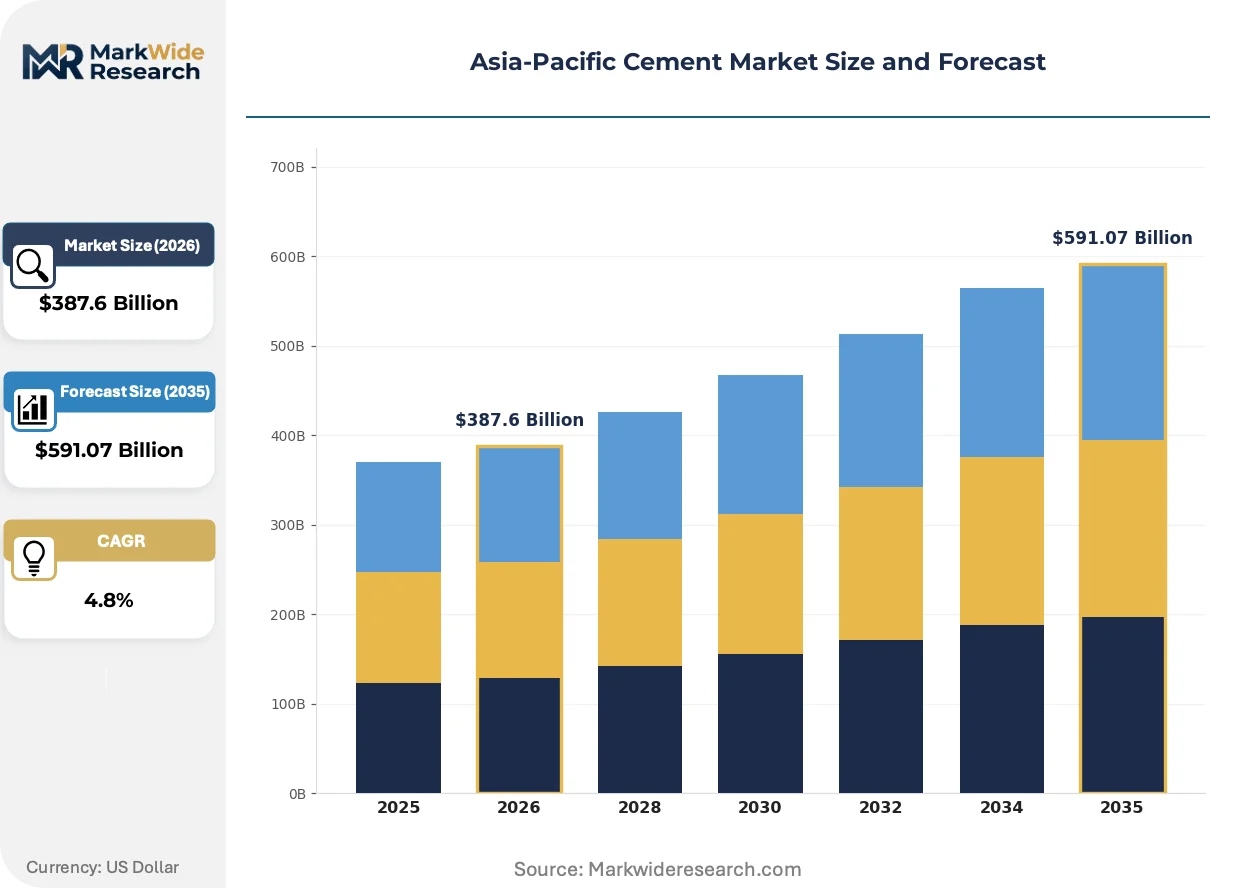
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $591.07 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portland Cement, Blended Cement, White Cement, Oil Well Cement End Use: Residential Construction, Commercial Construction, Infrastructure, Industrial Construction Distribution Channel: Direct Sales, Wholesale Distributors, Online Retail, Export Technology: Dry Process, Wet Process, Semi-Dry Process, Alternate Fuel |
| Companies Covered | SCG, BBMG Corporation, Anhui Conch Cement Company Limited, Taiheiyo Cement, China Resources Cement Holdings, China National Building Material Group Corporation, Taiwan Cement Ltd., Semen Indonesia, UltraTech Cement Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Cement Market Trends and Innovations
Carbon-intensity measurement is becoming a procurement gate across public infrastructure tenders. Producers are restructuring product portfolios and kiln fuel mixes to meet emerging verification requirements.
Calcined clay activation is rewriting low-carbon binder economics. The technology replaces up to half of clinker content with thermally processed kaolinitic materials. European cement majors are licensing processes to Asian joint ventures. The structural consequence is a compression of the premium attached to traditional Portland grades.
China's MIIT enforcement of GB 175-2007 amendments is tightening clinker-factor ceilings. Non-compliant facilities face production quota restrictions. The mandate is accelerating kiln shutdowns in Shandong and Henan provinces while consolidating output among national champions.
Public-sector buyers are unbundling cement supply from construction contracts. Direct procurement by infrastructure authorities is displacing contractor-mediated purchasing. The Philippines' Department of Public Works and the Indonesia Infrastructure Authority are piloting centralized sourcing platforms. The shift concentrates volume leverage with state purchasers and compresses distributor margins.
Asia-Pacific Cement Market Segmentation
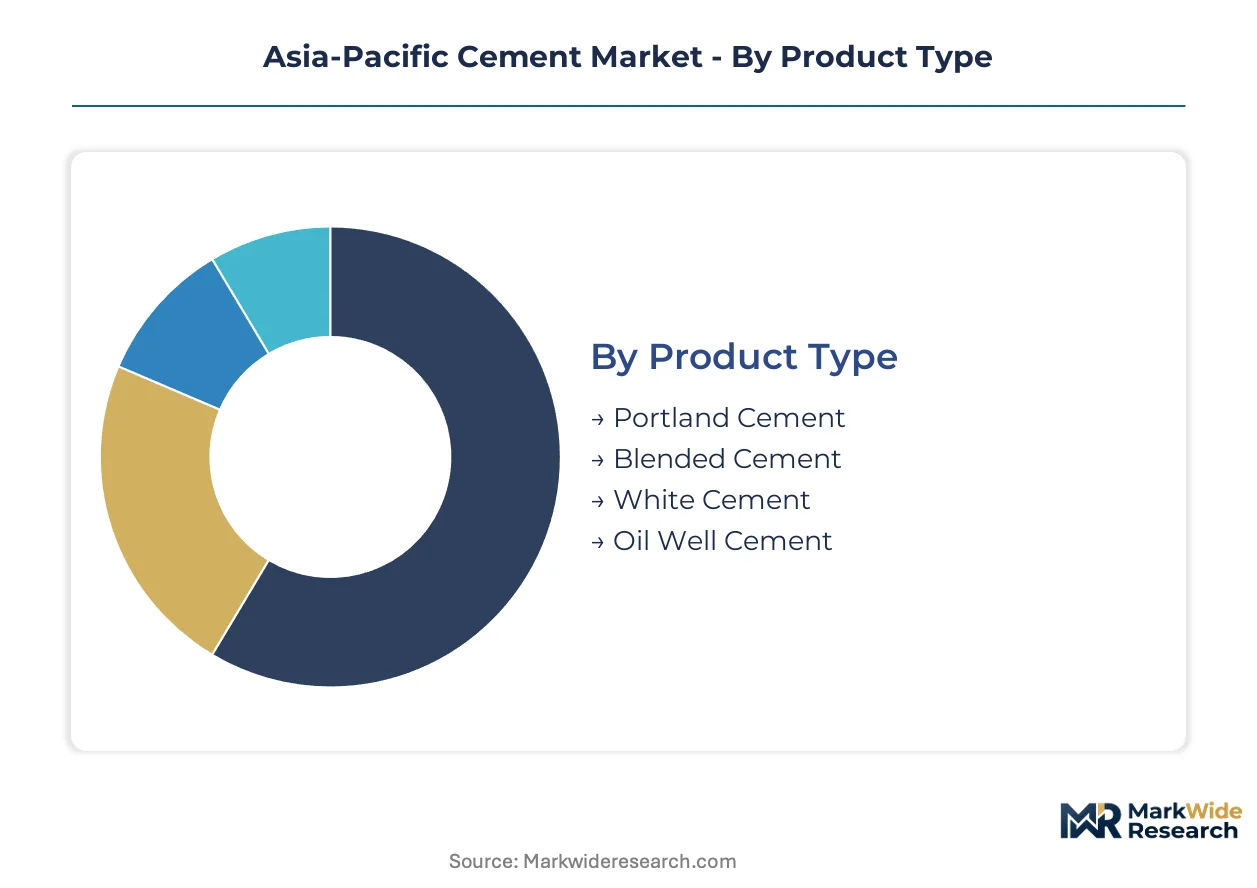
Segmentation reveals how kiln technology and clinker sourcing arrangements concentrate margin capture among integrated producers. Product formulation and distribution channel choices determine carbon-intensity positioning under tightening procurement standards.
Product Type:
Supply concentration in limestone-rich provinces shapes competitive dynamics across binder categories.
- Portland Cement:Calcium silicate-based hydraulic binder produced by firing calcareous and argillaceous materials at 1,450°C. Demand concentrates in China's central provinces and India's western states where infrastructure procurement specifies GB 175 and BIS IS 269 grades for structural concrete.
- Blended Cement:Incorporates fly ash, blast-furnace slag, or pozzolana to reduce clinker factors below 0.65. Vietnam and Indonesia are absorbing volumes fastest as public tenders mandate carbon-intensity thresholds.
- White Cement:Low-iron clinker formulation for architectural finishes. Premium pricing reflects kaolin feedstock scarcity and specialized kiln control requirements.
- Oil Well Cement:API-specified sulfate-resistant grades for geothermal and hydrocarbon well casing. Procurement ties to Indonesia's upstream projects and Philippine geothermal expansion.
Portland cement absorbs the bulk of installed capacity; blended cement is expanding most quickly.
End Use:
Application mix determines clinker factor requirements and logistics radius economics.
- Infrastructure:Bridges, dams, and transport corridors specify high early-strength grades. Indonesia's Nusantara relocation and Vietnam's North-South expressway are concentrating demand in Java and northern provinces.
- Residential Construction:Multi-story housing dominates in Philippine urban clusters and Indian tier-2 cities. Volume scale favors bulk delivery through ready-mix concrete channels.
- Commercial Construction:Office and retail specifications emphasize finish quality and rapid strength gain. Premium-grade procurement concentrates in Bangkok, Singapore, and Sydney CBD projects.
- Industrial Construction:Manufacturing facilities and power plants require sulfate-resistant and low-alkali formulations. Chemical resistance specifications tighten near coastal zones.
Infrastructure commands the largest volume share; residential construction shows the steepest expansion trajectory in frontier markets.
Distribution Channel:
Channel structure reflects limestone reserve geography and clinker grinding plant placement.
- Direct Sales:Long-term supply agreements with infrastructure authorities and ready-mix operators. Philippine DPWH and Indonesia Infrastructure Authority centralized platforms are consolidating this channel.
- Wholesale Distributors:Regional stockists serve fragmented contractor bases in archipelagic markets. Inventory carrying costs favor producers with coastal grinding capacity.
- Online Retail:Bagged cement platforms emerging for small-batch residential orders. Logistics complexity limits penetration outside major metropolitan zones.
- Export:Clinker and bulk cement shipments from Thailand and Vietnam to Bangladesh and African markets. Trade flows respond to Indian Ocean freight differentials.
Direct sales channelize the majority of tonnage; online retail is gaining share fastest in urban bagged segments.
Technology:
Process selection determines fuel flexibility and carbon-intensity compliance positioning.
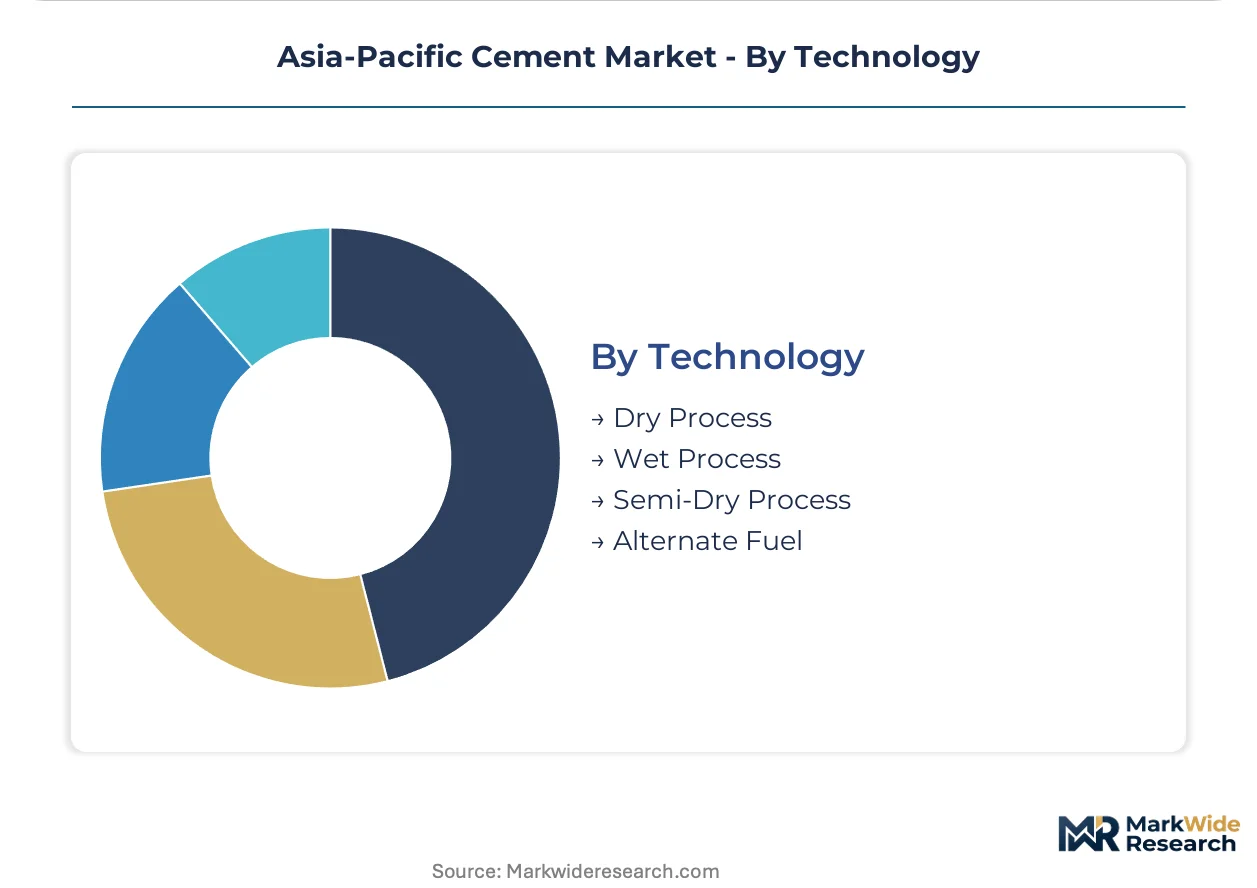
- Dry Process:Preheater-precalciner kilns dominate new capacity additions. China's MIIT mandates favor this technology for clinker-factor compliance.
- Wet Process:Slurry-fed kilns persist in older Indian and Philippine assets. Retrofit economics are marginal given energy penalties.
- Semi-Dry Process:Lepol grate preheaters occupy intermediate positions in Vietnam and Indonesia. Conversion to full dry-process attracts capital allocation.
- Alternate Fuel:Municipal solid waste and biomass co-processing systems. Thailand and Malaysia operators are securing long-term waste-stream contracts.
Dry process holds the dominant installed base; alternate fuel systems are climbing the fastest amid coal substitution targets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's Nusantara special economic zone is concentrating cement demand through state-backed infrastructure relocation. Vietnam's northern industrial corridors absorb volumes from expressway megaprojects. China's MIIT enforcement compresses output among compliant producers in limestone-rich provinces.
China
Shandong and Henan provinces host the bulk of compliant dry-process capacity under MIIT production quotas. The GB 175-2007 amendment enforcement is shuttering non-compliant kilns while consolidating output among state-backed national champions. Anhui province anchors limestone reserve control through integrated quarry-to-plant operations.
India
Gujarat and Maharashtra clusters drive blended cement absorption through BIS-certified Portland Pozzolana procurement mandates. The western states concentrate captive power generation and coastal clinker import capacity. UltraTech Cement Ltd. exemplifies cost leadership through integrated logistics networks spanning these industrial corridors.
Indonesia
Java's northern coast concentrates grinding plant placement to serve Nusantara capital relocation demand. The Ministry of Industry's local content regulations restrict clinker import dependency for public infrastructure tenders. Kalimantan limestone deposits are attracting kiln investment to bypass Java-centric supply chains.
Vietnam
The North-South expressway corridor is absorbing record cement volumes through state procurement of domestic clinker. Northern provinces hold disproportionate high-grade limestone reserves that shape export competitiveness. Thai Nguyen and Ha Nam industrial zones concentrate dry-process capacity with coastal bulk export terminals.
Philippines
Archipelagic geography creates distributed demand nodes across Visayas and Mindanao island clusters. The Department of Public Works centralized sourcing platform is displacing contractor-mediated procurement. Cebu and Davao grinding plants bypass Luzon-centric supply chains through coastal clinker imports.
Asia-Pacific Cement Market Competitive Landscape
Top-tier vendors anchor national-scale limestone reserve control, while mid-tier operators compete on regional logistics radius. The competitive set compresses around MIIT clinker-factor mandates and BIS energy-efficiency thresholds that strand sub-scale assets. Strategic archetypes include integrated quarry-to-plant operators, coastal export specialists, and blended-cement formulators with industrial byproduct sourcing agreements. Dominant competitive moves center on captive limestone acquisition and alternate-fuel system licensing.
Among China-based integrated producers, Anhui Conch Cement Company Limited and BBMG Corporation occupy positions defined by extensive limestone quarry control and state-backed balance-sheet depth. SCG anchors the Thai manufacturing base that dominates clinker exports throughout mainland Southeast Asia. Taiwan Cement Ltd. and Taiheiyo Cement exemplify coastal export specialists with established Indian Ocean freight networks.
| Leading Market Players |
|---|
| SCG |
| BBMG Corporation |
| Anhui Conch Cement Company Limited |
| Taiheiyo Cement |
| China Resources Cement Holdings |
| China National Building Material Group Corporation |
| Taiwan Cement Ltd. |
| Semen Indonesia |
| UltraTech Cement Ltd. |
| Others |
Pricing and Supply Chain Analysis
Indonesian thermal coal price benchmarks cascade through kiln fuel costs into cement pricing tiers, compressing margins for import-dependent operators while rewarding integrated producers with captive limestone reserves and coastal grinding capacity.
Pricing Analysis
Short lead-time premiums for infrastructure megaprojects command pricing advantages over spot inventory discounts in fragmented contractor markets. Three-tier pricing structure across premium, standard, and economy levels segments by clinker factor and BIS certification grade. Price differentiation hinges on GB 175 compliance status and MIIT production quota access. Cost compression in economy tiers is intensifying because coal substitution investments strain sub-scale balance sheets. Public infrastructure authorities exhibit lowest price sensitivity; bagged retail distributors face highest margin pressure.
Supply Chain Analysis
Kiln engineer scarcity in Vietnam and Thailand constrains dry-process retrofit timelines and alternate-fuel system deployment. Supply concentrates in China, Vietnam, and Indonesia through limestone reserve geography and coastal clinker export terminal placement. Raw material dependencies center on high-grade calcareous deposits, Australian thermal coal, and industrial fly ash sourcing. Single-source vulnerability in Indonesian limestone imports to Philippine grinding plants threatens archipelagic supply continuity. Distribution runs through direct sales agreements with state infrastructure authorities and coastal bulk terminals serving ready-mix concrete networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Limestone reserve depletion rates in high-grade Vietnamese provinces prop pricing power by constraining greenfield kiln capacity additions. Supply-constrained dynamics favor integrated producers with captive quarry control.
For Market Incumbents: Anticipate MIIT clinker-factor enforcement accelerating stranded-asset risk among wet-process operators. Secure captive limestone reserves in Kalimantan and northern Vietnam before regulatory barriers harden. Prioritize alternate-fuel system licensing to offset coal price volatility threatening margin stability. Channel control through DPWH and Indonesia Infrastructure Authority direct sales agreements locks out distributor competitors. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Philippine island markets offers white-space entry through coastal grinding plant placement. Target Visayas and Mindanao distributed demand nodes bypassing Luzon-centric supply chains. Pursue municipal solid waste co-processing partnerships in Thailand and Malaysia securing long-term waste-stream feedstock contracts. Position blended cement formulations for BIS Portland Pozzolana certification eligibility in Indian public procurement. For Investors and Strategic Acquirers: Distressed-cycle entries favor semi-dry process operators in Vietnam with convertible Lepol grate assets and coastal terminal access. Long-term viability over the next decade hinges on carbon-intensity positioning under emerging border adjustment frameworks. Monitor calcined clay licensing agreements as inflection indicator for clinker substitution economics compressing traditional Portland premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Limestone Reserves | Kalimantan quarry acquisitions secure feedstock for Nusantara infrastructure demand under local content regulations. |
| Alternate Fuel System Licensing | Thai and Malaysian waste-stream contracts reduce coal dependency amid thermal price volatility. |
| Blended Cement Certification Investment | BIS Portland Pozzolana and Portland Slag grades unlock Indian public procurement eligibility. |
| Coastal Grinding Plant Expansion | Philippine island-specific capacity bypasses Luzon supply chain chokepoints for archipelagic distribution. |
| Direct Sales Platform Development | Centralized DPWH and Indonesia Infrastructure Authority procurement displaces contractor-mediated purchasing. |
Research Methodology
Multi-period observation of kiln technology retrofit rates, clinker export volumes, and MIIT compliance enforcement anchored the trend analysis, supplemented by interviews with plant operations directors, procurement leads at infrastructure authorities, limestone quarry geologists, and ready-mix concrete distributors. Secondary validation drew from MIIT production quota disclosures, BIS certification registries, Indonesian Ministry of Industry local content reports, and Vietnam customs clinker trade data. Bottom-up capacity modeling and top-down demand aggregation triangulated volume estimates across the analysis window.
Input-output matrices mapped limestone reserve grades to kiln fuel mixes across product type, end-use application, distribution channel, and technology segments. CAGRs were derived from regression analysis of historical consumption patterns and infrastructure project pipelines. Forecast inputs incorporated Nusantara relocation timelines, North-South expressway construction phases, and GB 175-2007 amendment enforcement trajectories without year-specific milestones.
Inputs from state planning commissions and industry associations were available through the study window; gaps in proprietary limestone reserve quality data introduce uncertainty bands around clinker substitution elasticity assumptions. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and infrastructure commitment durability. Material deviation in coal price trajectories, carbon border implementation schedules, or kiln technology licensing costs warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Dry Mix Mortar Market
Building Materials
Cross Laminated Timber (CLT) Market
Building Materials
Concrete Market
Building Materials
Engineered Wood Product Market
Building Materials
Asia-Pacific Kinetic Tiles Market
Building Materials
Asia-Pacific Aluminum Door and Window Market
Building Materials
Exterior Doors Market
Building Materials
Bolt (Fastener) Market
Building Materials
Southeast Asia Concrete Admixtures Market
Building Materials
Global Lightweight Aggregate Concrete Market
Building Materials
Global Corrugated Steel Sheets Market
Building Materials
Asia-Pacific White Cement Market
Building Materials
Stone Coated Steel Roofing Market
Building Materials
North America Building and Construction Sheets Market
Building Materials
Iron and Steel Slag Market
Building Materials
China Cement Market