
 Europe Fiber Cement Market | 2026-2036
Europe Fiber Cement Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Fiber Cement Market Insights
Wood and traditional masonry in European exterior envelopes is shifting toward fiber cement composites as builders pursue lighter structural loads and improved thermal bridging performance. Etex Group leverages captive cellulose sourcing and integrated pulp-to-board manufacturing to sustain margin control across its Benelux and French operations. James Hardie Europe GmbH anchors its position through specialized facade systems engineered for Nordic moisture cycling, while Saint-Gobain competes via distribution depth and specification relationships with major continental architects.
Europe fiber cement denotes a composite building material comprising Portland cement, silica, and cellulose fibers pressed into dense sheets or molded profiles, typically rated for fire resistance up to Class A2-s1,d0 under EN 13501-1 and engineered for dimensional stability across freeze-thaw climates. Its primary commercial purpose spans exterior cladding, roofing, and wet-area substrates where moisture durability and non-combustibility prove essential. Siding and wall cladding applications dominate volume as renovation rates accelerate across aging European housing stock, while facade-grade panels command premium positioning due to through-color technology and custom surface finishing. Roofing tiles retain mature demand patterns in Mediterranean markets where traditional terracotta aesthetics persist, though boards are gaining share in modular and prefabricated construction systems.
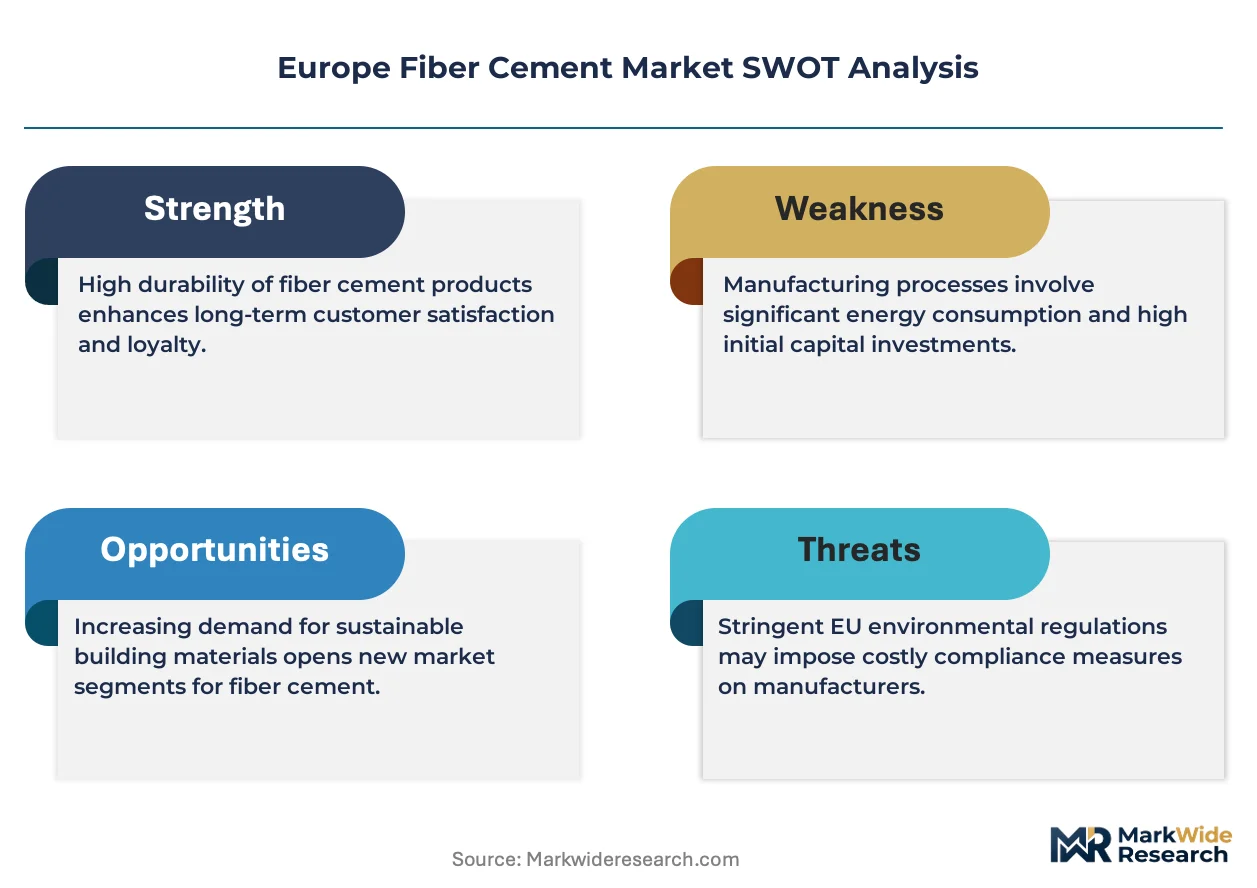
REACH compliance and the EU Green Deal's embodied carbon thresholds are reshaping raw material qualification and driving reformulation toward lower-clinker cement blends across European manufacturing. ECHA scrutiny of crystalline silica content in fiber cement production is tightening workplace exposure standards and prompting capital investment in automated cutting and dust suppression systems. CE marking under the Construction Products Regulation remains mandatory for market access, with national building codes in Germany, France, and Italy layering additional performance tests for wind load and seismic anchoring. Stakeholders must monitor evolving Ecodesign requirements and national renovation wave funding allocations to align product portfolios with subsidized retrofit pipelines.
Market Dynamics
The EU Green Deal's embodied carbon thresholds are forcing wholesale reformulation of cementitious binders, compressing clinker ratios while manufacturers race to qualify alternative pozzolanic additives for CE marking compliance.
Growth Catalysts
- Renovation Wave funding:National allocations under the EU Green Deal are channeling public capital into facade retrofit pipelines, directly stimulating specification of fiber cement cladding for thermal envelope upgrades.
- REACH-driven silica scrutiny:ECHA's tightening workplace exposure standards are accelerating capital deployment into automated cutting lines and dust suppression infrastructure, favoring scaled producers with compliance headroom.
- Prefabrication adoption:Modular construction systems in Nordic markets are integrating fiber cement boards as standardized wet-area substrates, compressing on-site installation cycles.
Market Restraints
- Portland cement cost volatility:Energy-intensive clinker production exposes margins to natural gas price swings, particularly acute for German and Polish manufacturing clusters.
- Cellulose fiber supply concentration:Nordic pulp integration limits qualified fiber sources, constraining capacity expansion for non-integrated competitors.
- Masonry substitution ceiling:Traditional brick and render retain cultural preference in Mediterranean residential markets, capping fiber cement penetration in heritage-sensitive districts.
Strategic Opportunities
- Benelux renovation acceleration:Belgium and Netherlands housing stock age profiles align with stringent fire code cycles, creating concentrated demand for A2-s1,d0 rated facade panels.
- Through-color technology convergence:Mineral pigment integration with fiber cement matrices enables custom architectural finishes, opening specification relationships with continental design practices.
- Digital specification platforms:BIM-embedded product libraries are compressing architect discovery cycles, rewarding early-mover manufacturers with parametric object placement.
Industry Challenges
- Freeze-thaw certification timelines:EN 13501-1 testing protocols for Nordic climate ratings extend product validation cycles, delaying regional launch windows.
- Silica exposure compliance:ECHA-mandated workplace monitoring requires continuous capital reinvestment in extraction and cutting automation, pressuring mid-scale facility economics.
- Anchor system integration:Seismic and wind-load anchoring standards vary across German, French, and Italian national codes, fragmenting installation training and inventory requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Fiber Cement Market |
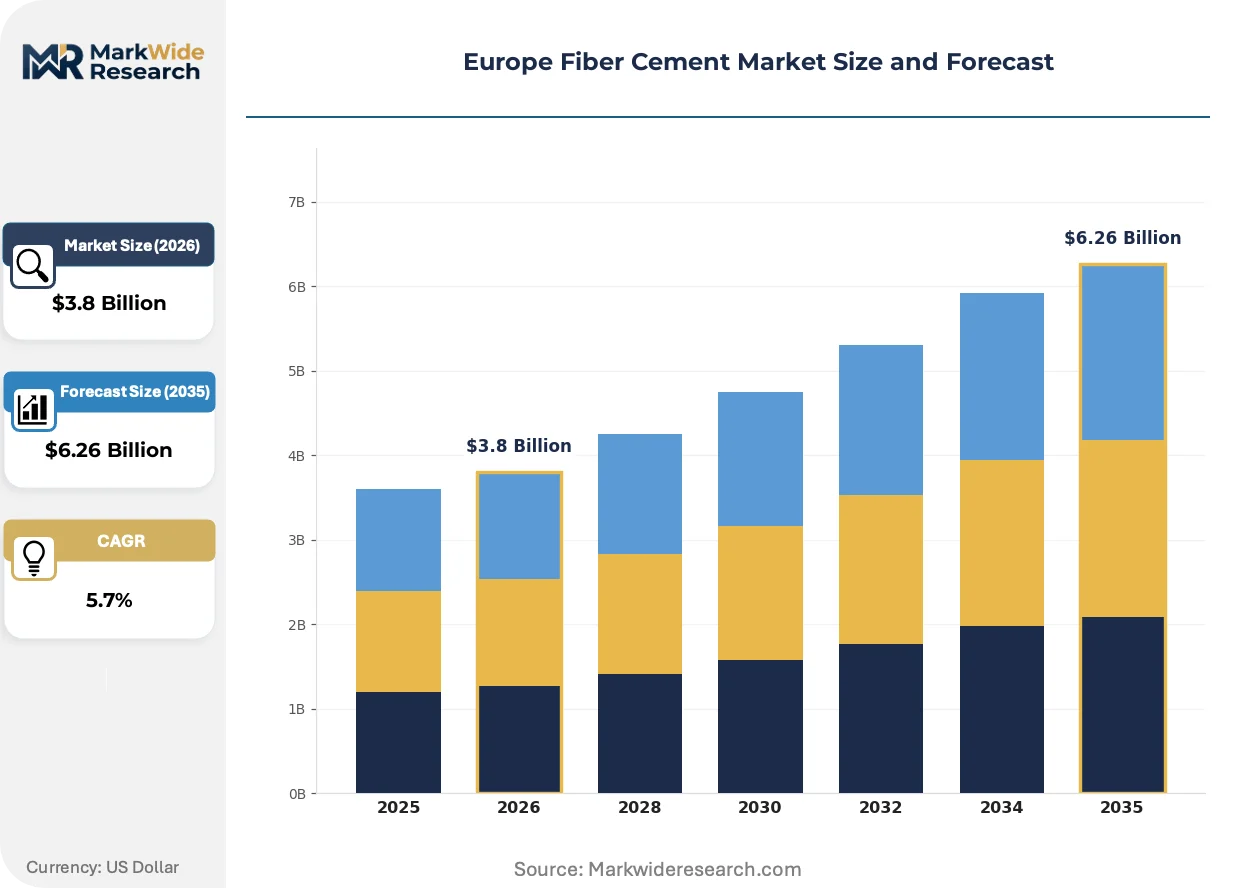
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: boards, panels, tiles, siding End User: residential, commercial, industrial, infrastructural Application: roofing, flooring, wall cladding, facades Distribution Channel: direct sales, wholesale, online, retailers |
| Companies Covered | Swisspearl Group AG, GIP GmbH, James Hardie Europe GmbH, Briarwood Products Ltd, Mastertec GmbH, Etex Group, Marley Eternit, Amulite Group, Saint-Gobain, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Fiber Cement Market Trends and Innovations
Formulation chemistry and digital specification channels are converging to reshape competitive positioning, with low-carbon binders and embedded product data emerging as primary differentiation vectors.
Calcined clay and ground limestone are decentralizing traditional Portland cement dominance in European fiber cement production. Manufacturers in France and Germany are adopting LC3 blends to meet EU Green Deal carbon intensity benchmarks. This binder diversification is compressing clinker supply dependencies while opening qualification pathways for regional pozzolan sources.
REACH enforcement is tightening crystalline silica thresholds across manufacturing operations. ECHA's 2023-2025 implementation timeline is forcing automated cutting investments and real-time dust monitoring deployment. German facilities face the steepest compliance curves due to prior reliance on manual finishing processes.
Architect specification behavior is pivoting toward digital product selection workflows. BIM object libraries and embodied carbon calculators are displacing traditional sample-based discovery in Benelux and Nordic markets. French design practices lead this transition, integrating EPD data directly into early-stage envelope modeling.
Europe Fiber Cement Market Segmentation
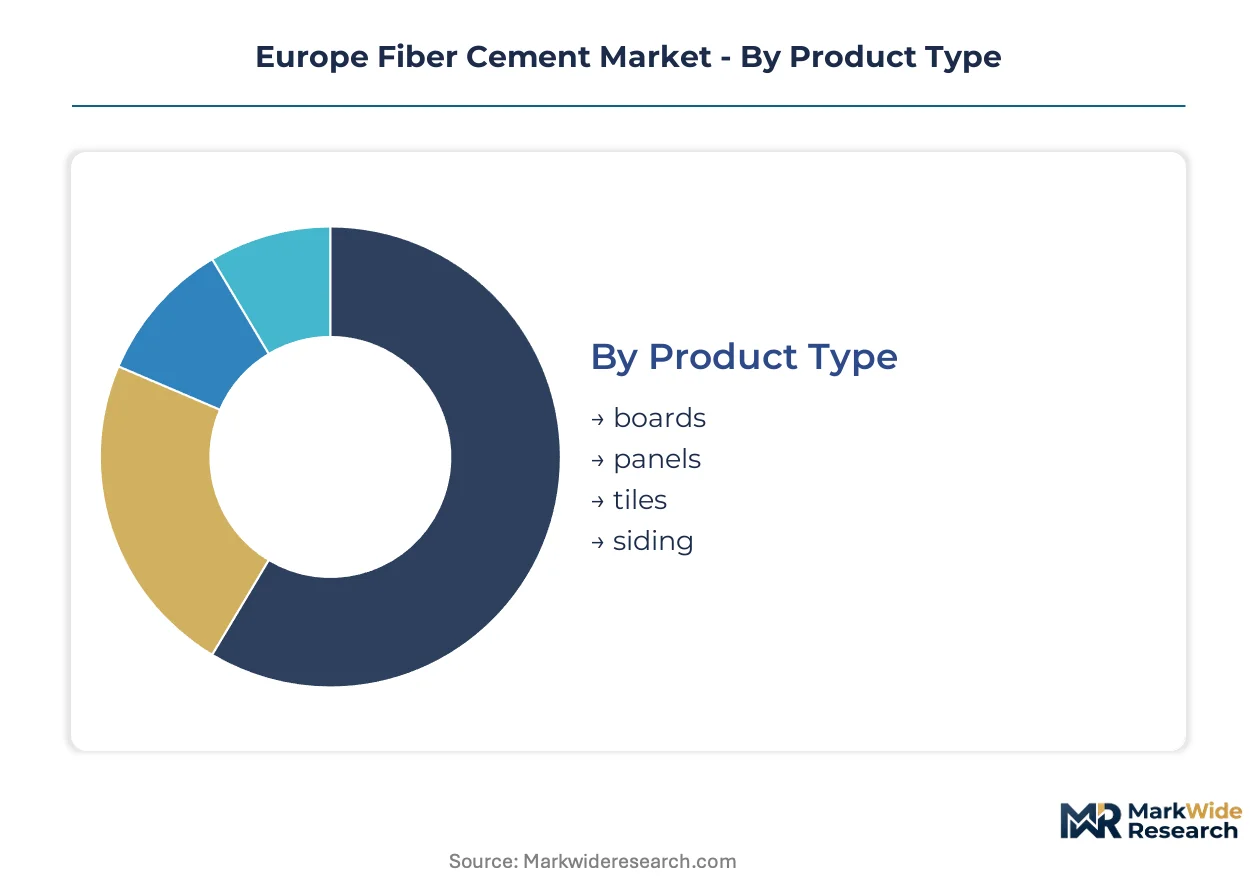
Segmentation in the Europe fiber cement market reveals how material specifications, end-use requirements, and channel economics fragment demand across distinct commercial pockets. Understanding these divisions exposes where formulation investments, specification relationships, and logistics infrastructure concentrate competitive advantage.
Product Type:
Customization intensity spans from commodity boards to architect-specified facade systems, with surface finish complexity and dimensional precision determining margin stratification.
- Boards:Standard-format sheets serve as the volume foundation, pressed from Portland cement-silica-cellulose matrices for wet-area substrates and modular construction backing. German and Polish prefabrication facilities drive uptake as standardized substrates compress on-site installation cycles. Leading the category by volume: boards. Growing fastest: panels.
- Panels:Through-color facade-grade sheets command specification premiums via mineral pigment integration and custom surface finishing, with A2-s1,d0 fire ratings mandatory for Benelux high-rise envelopes. French and Dutch design practices specify these for renovation wave retrofits requiring thermal bridge reduction.
- Tiles:Profiled roofing elements retain mature demand in Mediterranean markets where terracotta aesthetics persist, though modular systems erode share.
- Siding:Horizontal lap and shingle-style cladding dominates Nordic residential replacement cycles, engineered for freeze-thaw dimensional stability.
Volume leadership rests with boards. Panels climb fastest on renovation wave specification.
End User:
Project scale and procurement sophistication fragment demand from fragmented residential contractors to centralized industrial developers.
- Residential:Single-family and multi-family builders across Germany substitute fiber cement cladding for traditional masonry, prioritizing lighter structural loads and envelope thermal performance. Renovation wave subsidies accelerate facade retrofit specifications in France and Belgium.
- Commercial:Office and retail developers specify A2-rated facade panels for fire code compliance, with specification relationships concentrating among continental architect practices.
- Industrial:Warehouse and logistics facility constructors favor boards for rapid envelope closure, though price sensitivity limits premium panel penetration.
- Infrastructural:Tunnel linings, station cladding, and utility structures demand specialized formulations with enhanced impact resistance, qualifying through extended CE marking protocols.
Residential commands absolute volume. Commercial delivers margin expansion through specification premiums.
Application:
Exposure severity and aesthetic requirements stratify demand from concealed structural substrates to visible architectural surfaces.
- Roofing:Tiles and sheets compete with terracotta and metal systems, with fiber cement gaining share in modular Nordic construction where weight reduction matters.
- Flooring:Wet-area substrates in bathrooms and kitchens exploit moisture durability, though ceramic tile substitution limits volume.
- Wall Cladding:Exterior envelope surfacing dominates residential renovation across aging German and Benelux housing stock, with thermal upgrade funding channeling specification.
- Facades:Architect-visible curtain wall and rainscreen systems command the steepest premiums, requiring through-color technology and custom finishes for continental design practice relationships.
Wall cladding generates the largest addressable base. Facades capture the steepest value-per-square-meter trajectory.
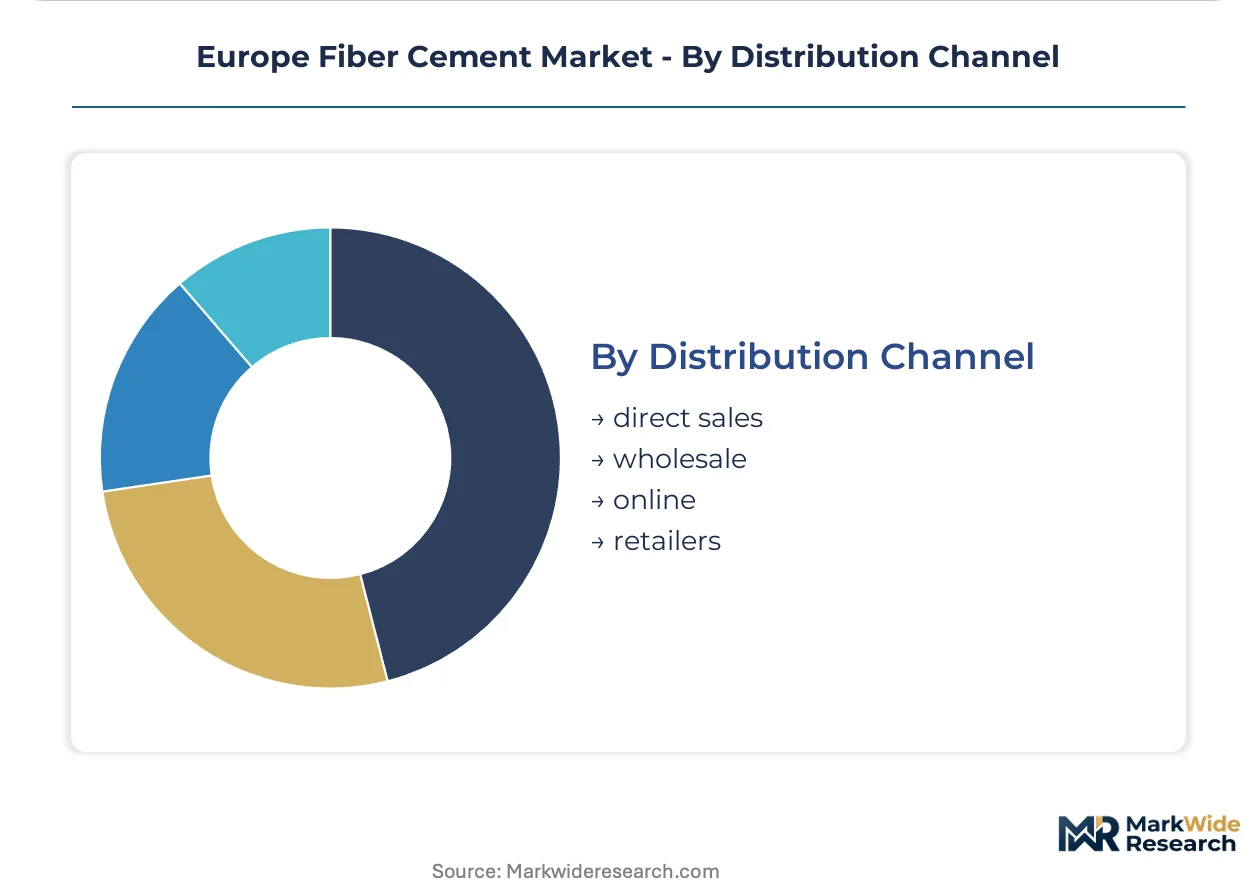
Distribution Channel:
Channel selection tracks project scale, specification complexity, and urgency requirements across the procurement spectrum.
- Direct Sales:Large commercial and industrial projects route through manufacturer specification teams, embedding BIM objects and EPD data for architect-driven selection.
- Wholesale:Regional distributors inventory standard boards and siding for residential contractors, with German and French merchant networks maintaining deepest penetration.
- Online:Digital procurement platforms gain traction among small residential contractors for standardized siding and accessory replenishment.
- Retailers:Big-box and specialized building material outlets serve DIY renovation segments, though fiber cement's installation complexity limits this channel relative to simpler alternatives.
Wholesale moves the highest absolute volume. Direct sales capture specification-driven premium flows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Renovation wave funding concentrates demand across German and Benelux housing stock, while Nordic prefabrication and Mediterranean aesthetic preferences fragment regional specification patterns.
Germany
Residential builders substitute fiber cement cladding for traditional masonry to reduce structural loads and improve thermal envelope performance. The national building code layers additional wind-load and seismic anchoring tests atop CE marking requirements. Manufacturing clusters in North Rhine-Westphalia and Bavaria supply prefabrication facilities with standardized board substrates.
France
Design practices specify through-color facade panels for renovation wave retrofits requiring thermal bridge reduction. The EU Green Deal's embodied carbon thresholds drive LC3 binder adoption in cementitious formulations. Industrial concentration in Île-de-France anchors specification relationships with continental architect practices.
Netherlands
Stringent fire safety codes for high-rise envelopes mandate A2-s1,d0 rated facade panels in residential renovation pipelines. National allocations under the EU Green Deal channel public capital into thermal upgrade projects. The Randstad corridor concentrates distribution infrastructure for merchant network penetration.
Belgium
Housing stock age profiles align with fire code renewal cycles, creating concentrated demand for architect-specified cladding systems. REACH enforcement tightens crystalline silica thresholds across manufacturing operations. The Etex Group maintains integrated pulp-to-board production in Flemish operations to sustain margin control.
Sweden
Modular construction systems integrate fiber cement boards as standardized wet-area substrates to compress on-site installation cycles. EN 13501-1 testing protocols for freeze-thaw climate ratings extend product validation timelines. James Hardie Europe GmbH engineers facade systems specifically for Nordic moisture cycling conditions.
Europe Fiber Cement Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers deploy automated cutting lines and dust suppression infrastructure to satisfy ECHA compliance timelines. The vendor base concentrates around integrated pulp-to-board operators and specialized facade system engineers. Three archetypes define competitive positioning: captive cellulose integrators, climate-specialized system designers, and distribution-depth conglomerates. M&A activity and portfolio diversification toward low-carbon binders represent the dominant competitive vectors reshaping market structure.
Among integrated European operators, Etex Group exemplifies the captive supply archetype through its Benelux and French manufacturing footprint. James Hardie Europe GmbH occupies the climate-specialized tier with Nordic-engineered facade systems. Saint-Gobain anchors the distribution-depth vector through specification relationships with continental architect practices. These three entities represent distinct strategic positions without overlapping operational emphasis.
| Leading Market Players |
|---|
| Swisspearl Group AG |
| GIP GmbH |
| James Hardie Europe GmbH |
| Briarwood Products Ltd |
| Mastertec GmbH |
| Etex Group |
| Marley Eternit |
| Amulite Group |
| Saint-Gobain |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between A2-s1,d0 facade panels and commodity-grade boards splits both pricing power and procurement geography across the Europe fiber cement market. Premium through-color panels command specification premiums via EN 13501-1 fire ratings and custom mineral finishes, while standard boards compete on clinker-input costs and logistics proximity to German and Polish prefabrication clusters.
Pricing Analysis
Volume leadership sits with commodity boards while margin capture concentrates in facade-grade panels. Three-tier pricing structure across premium, standard, and economy levels tracks EN 13501-1 certification tiers, with A2-rated products carrying substantial specification premiums over B-s1,d0 alternatives. Cost compression in standard boards is intensifying because Portland cement clinker exposure ties margins to natural gas price volatility. Industrial warehouse developers exhibit highest price sensitivity, while architect-specified commercial facades demonstrate lowest elasticity.
Supply Chain Analysis
Scrap board recovery and pulverized fiber cement recycling flow back into clinker kilns as alternative raw material inputs, though reverse logistics infrastructure remains underdeveloped outside Benelux manufacturing clusters. Production gravity centers on Belgium, Germany, and France, with Nordic pulp integration constraining qualified cellulose fiber sources. Formulation chemistry draws from Portland cement, crystalline silica, and specialty cellulose pulp. Single-source vulnerability runs through Nordic pulp suppliers for non-integrated competitors. Distribution runs through regional merchant networks for residential contractors and direct specification teams for commercial projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ECHA crystalline silica enforcement under REACH has erected a capital-intensive compliance barrier that favors scaled incumbents with automated cutting infrastructure and real-time dust monitoring systems.
For Market Incumbents: To counter margin erosion from Portland cement cost volatility, prioritize backward integration into regional pozzolan sourcing for LC3 binder formulations and deploy additional automated cutting capacity ahead of ECHA compliance deadlines. Captive cellulose pulp supply and integrated pulp-to-board manufacturing sustain cost position against non-integrated challengers. For New Entrants and Emerging Players: Launch via digital specification platforms embedding BIM objects and EPD data to bypass entrenched merchant network relationships. Mediterranean roofing tile replacement and Nordic modular wet-area substrates represent the most penetrable white-space segments, with lightweight board formats offering entry path against masonry substitution resistance. For Investors and Strategic Acquirers: Re-rating potential sits with integrated operators possessing captive pulp supply and CE marking breadth given EU Green Deal embodied carbon threshold tightening. Five-to-ten year viability favors manufacturers with demonstrated LC3 qualification pathways and automated compliance infrastructure. Monitor ECHA enforcement intensity and national renovation wave funding allocation velocity as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| LC3 Binder Reformulation | Reduces clinker dependence and qualifies products for EU Green Deal carbon intensity benchmarks. |
| Automated Cutting Line Deployment | Satisfies ECHA crystalline silica exposure limits while compressing labor cost structures. |
| Digital Specification Platform Launch | Embeds BIM objects and EPD data to capture architect-driven selection workflows in Benelux. |
| Nordic Climate Certification Investment | Extends EN 13501-1 validation for freeze-thaw ratings to access modular construction pipelines. |
| Captive Pulp Integration Expansion | Secures qualified cellulose fiber supply against Nordic source concentration constraints. |
Research Methodology
Trade association filings, customs import records, and national building code registries formed the secondary backbone, supplemented by primary interviews with plant operations directors, procurement leads at prefabrication facilities, specification architects at continental design practices, and distribution channel partners. Bottom-up volume triangulation across product-grade segments was cross-validated against top-down macroeconomic indicators and construction output indices.
Historical trendline analysis tracked clinker-input cost movements, renovation wave funding disbursement patterns, and prefabrication adoption curves across the analysis window. Segmentation dimensions modeled include product grade tier, end-use application, fire certification level, and regional manufacturing hub. CAGRs were derived from slope-adjusted extrapolation of volume trajectories, incorporating LC3 binder adoption curves and ECHA compliance investment cycles as industry-specific forecast inputs.
Portland cement price volatility, ECHA enforcement intensity variation, and national renovation funding allocation delays are the dominant revision risks to modeled outputs. Forecasts reflect underlying assumptions about regulatory trajectory continuity and clinker substitution technology maturation. Practitioners should monitor energy price indices, ECHA inspection announcement schedules, and EU Green Deal implementation guidance for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Ductile Iron Pipe Market
Building Materials
Construction Stone Market
Building Materials
Asia-Pacific Building and Construction Sheets Market
Building Materials
North America Concrete Admixtures Market
Building Materials
Europe Acrylic Resin Dispersion Based Primers in Construction Market
Building Materials
Self-Healing Construction Materials Market
Building Materials
India Cement Market
Building Materials
Cement Tiles Market
Building Materials
Indonesia Dry Mix Mortar Market
Building Materials
Sanded Grout Market
Building Materials
Refractory Cement Market
Building Materials
India Construction Ornamental Stone Market
Building Materials
Building Asphalt Market
Building Materials
Africa Green Cement Market
Building Materials
Granite Market
Building Materials
Precast Concrete Retaining Walls Market