
 Refurbished Construction Equipment Market | 2026-2036
Refurbished Construction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Refurbished Construction Equipment Market Analytics
Equipment-as-a-service subscription models is recalibrating how refurbished assets generate lifetime revenue. Caterpillar Inc. leverages its Cat Certified Rebuild program to anchor customer loyalty across multiple machine life cycles. Komatsu Ltd. competes through KOMTRAX telematics integration that extends residual value tracking into secondary markets.
Refurbished construction equipment encompasses previously operated machinery restored to verified performance standards through systematic component replacement, hydraulic system reconditioning, and powertrain overhaul to meet OEM or certified third-party specifications. These assets serve commercial buyers seeking production-grade capability at reduced capital outlay compared to new equipment. Excavators dominate transaction volumes due to universal application across residential and civil projects, while loaders capture expanding rental fleet demand. The dealer channel controls premium margin pools by bundling warranty coverage with certified rebuild documentation, whereas online platforms attract price-sensitive contractors purchasing good-condition units without service contracts.
Federal EPA regulations in the United States and EU Stage V standards enforced by national type-approval authorities mandate emissions compliance for rebuilt engines, creating certified rebuild demand that bypasses new-equipment premiums. Japan's METI energy-efficiency guidelines and JIS quality standards further shape refurbishment protocols for export-oriented machinery. Stakeholders must monitor how digital equipment records and blockchain-based provenance verification reshape buyer trust and pricing transparency in secondary markets.
Market Dynamics
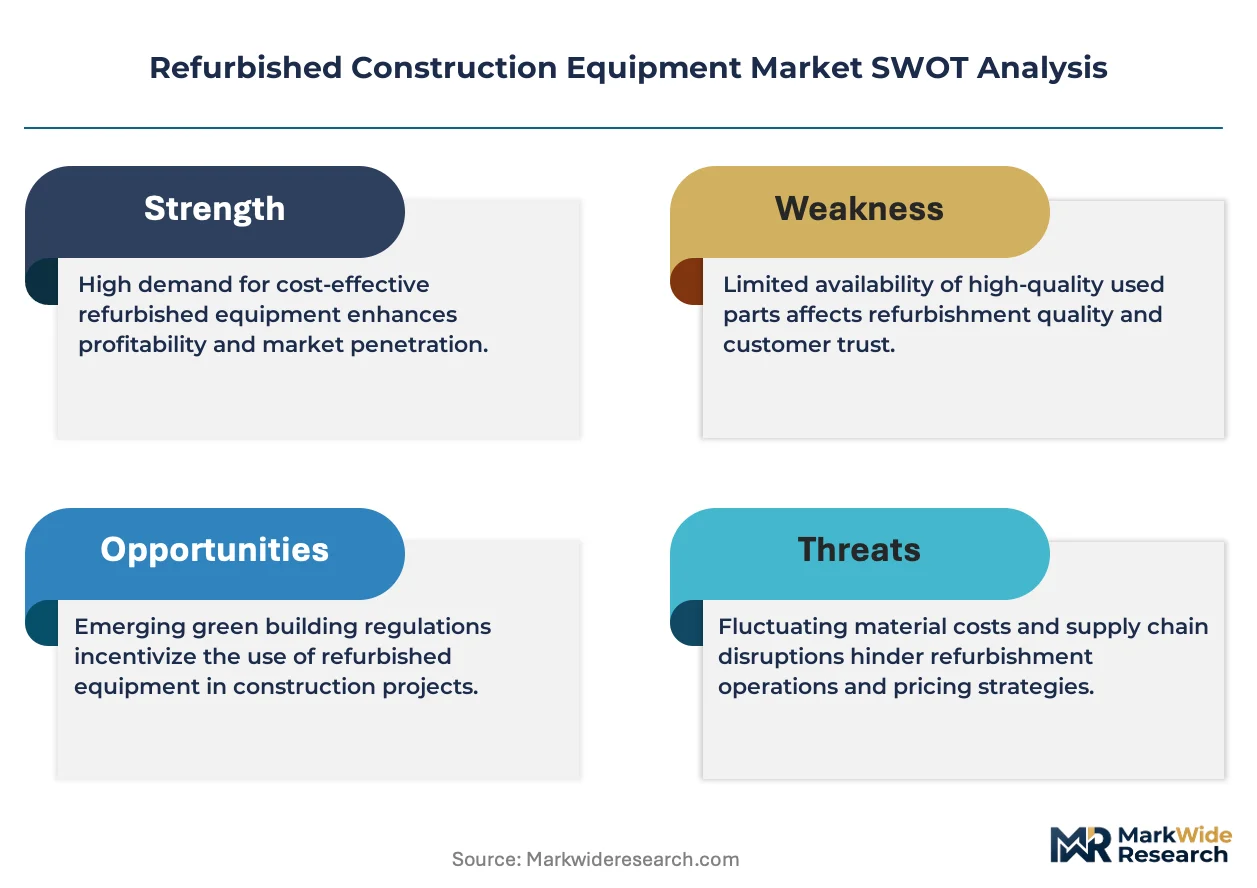
Equipment-as-a-service subscription models are recalibrating how refurbished assets generate lifetime revenue streams across multiple ownership cycles.
Growth Catalysts
- EPA Tier 4 Final mandates:United States emissions rules push fleet owners toward certified rebuild programs that restore compliance without new-equipment premiums.
- Telematics integration:OEM-embedded diagnostic systems enable predictive maintenance scheduling that extends machine service intervals and residual valuations.
- Rental fleet expansion:Equipment rental companies in Germany and Japan are scaling procurement of rebuilt units to manage capital deployment and depreciation schedules.
Market Restraints
- Steel and hydraulic component volatility:Input cost swings for high-pressure hoses and cylinder barrels compress rebuild margin predictability for independent refurbishers.
- Dealer network concentration:OEM-authorized service channels in the United States and Japan control access to proprietary technical documentation and genuine parts inventories.
- Battery-electric substitution threat:Zero-emission new equipment in urban construction zones risks displacing diesel rebuild demand in municipal fleet segments.
Strategic Opportunities
- Blockchain provenance verification:Distributed ledger systems for equipment history documentation are reducing information asymmetry in secondary market transactions.
- EU Stage V compliance services:Engine remanufacturing to meet European emissions standards creates certified rebuild demand that bypasses new-machine cost structures.
- India infrastructure build-out:National highway and metro rail projects are generating demand for cost-optimized earthmoving equipment with documented rebuild histories.
Industry Challenges
- Certified technician scarcity:Hydraulic system diagnostics and electronic control module programming require specialized training that outpaces vocational pipeline output.
- Warranty liability segmentation:Component-level coverage disputes between OEM rebuild programs and third-party refurbishers complicate buyer risk assessment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refurbished Construction Equipment Market |
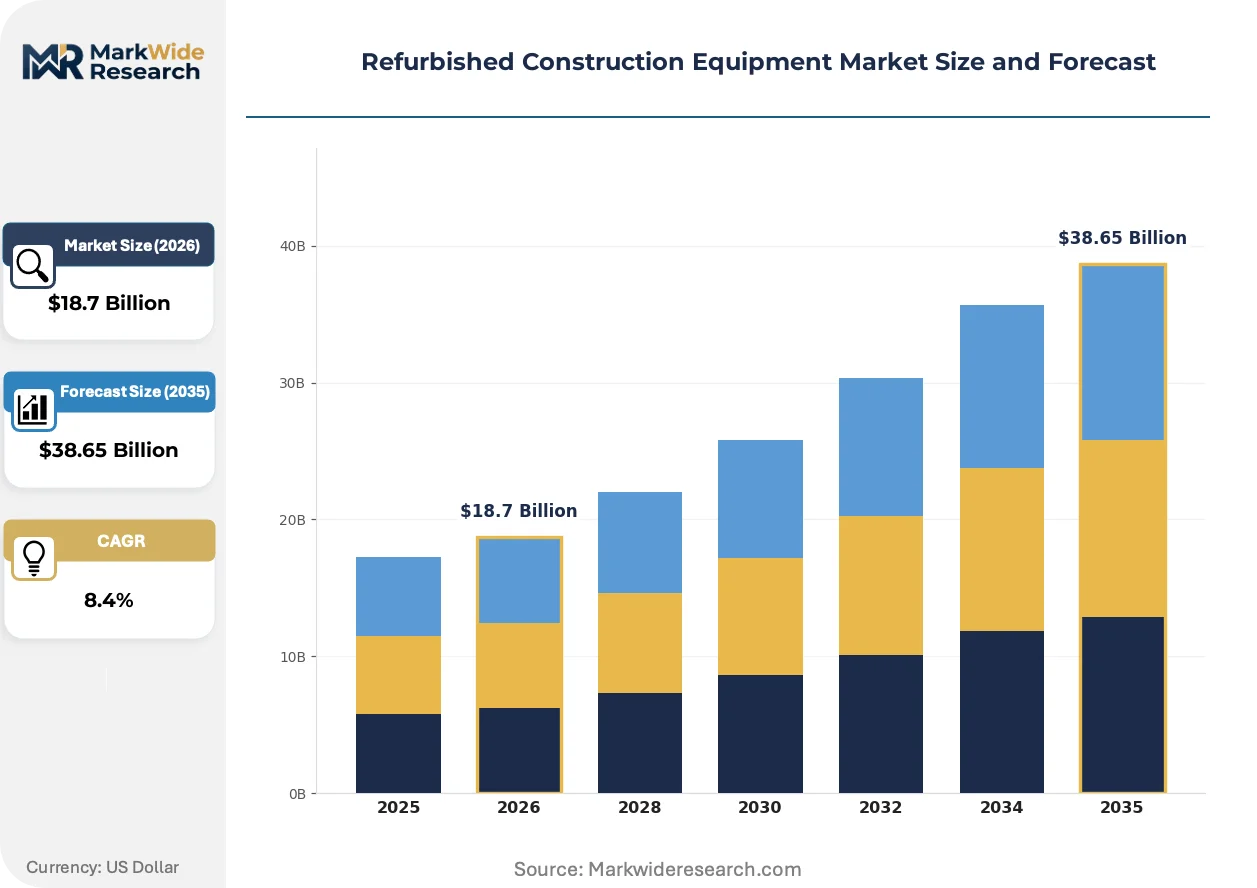
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Loaders, Cranes, Bulldozers End User: Contractors, Rental Companies, Government, Forestry Sales Channel: Direct Sales, Online Platforms, Auctions, Dealers Condition: Like New, Good, Fair, Needs Repair |
| Companies Covered | Volvo Construction Equipment, XCMG Group, Caterpillar Inc., Sany Heavy Industry Co. Ltd., Liebherr Group, Komatsu Ltd., Hitachi Construction Machinery Co., Ltd., Doosan Group, Deere & Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refurbished Construction Equipment Market Evolving Landscape
Digital equipment records and connected asset monitoring are compressing information gaps between rebuild quality tiers and reshaping how buyers evaluate secondary-market machinery.
Remanufactured powertrain assemblies with telematics-enabled health monitoring are overtaking traditional component replacement protocols in premium rebuild segments. Large civil contractors and mining operators are specifying these integrated systems for critical fleet units. The technology is compressing downtime risk premiums that previously favored new equipment acquisitions.
EU Stage V emissions enforcement by national type-approval authorities is mandating exhaust after-treatment retrofits for engines above 56kW in rebuilt machines. Industrial consequence includes mandatory diesel particulate filter and selective catalytic reduction installation that adds cost and complexity to refurbishment workflows. German and French construction fleets are responding by consolidating procurement through OEM-certified rebuild channels with documented compliance chains.
Subscription-based equipment access is fragmenting traditional ownership patterns among mid-sized contractors. Rental fleet operators and dealer finance arms are capturing demand that previously flowed to outright purchase of good-condition used units. This shift is most visible in United States residential construction verticals where project duration uncertainty favors operational expense treatment over capital deployment.
Refurbished Construction Equipment Market Segmentation
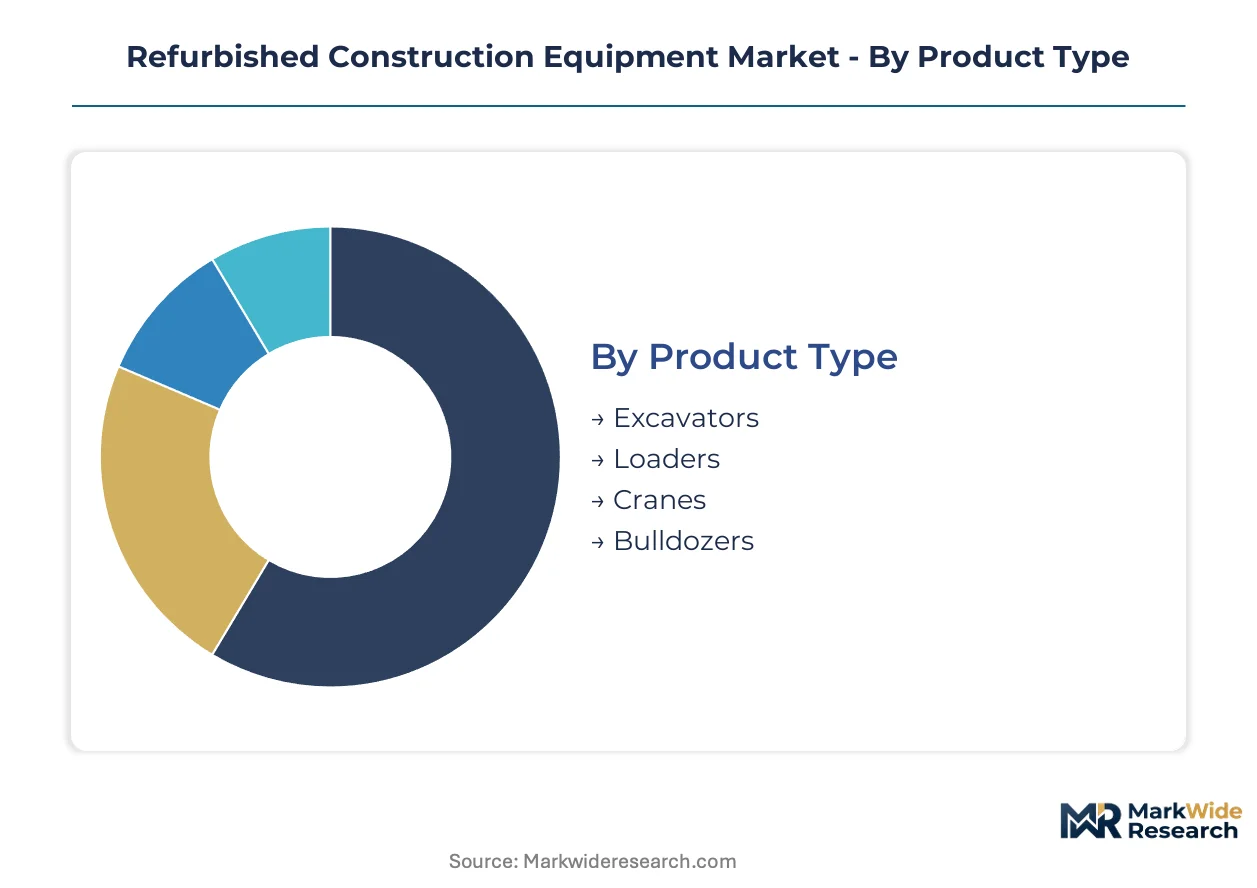
Segmentation reveals how capital deployment patterns and risk tolerance vary across buyer types in refurbished construction equipment. Equipment condition and procurement channel selection directly correlate with project duration certainty and fleet financing structures.
Product Type:
Capital intensity varies sharply across equipment categories, with larger machines demanding higher refurbishment investment but generating superior residual value retention.
- Excavators:Hydraulic systems and undercarriage components undergo systematic reconditioning to OEM torque and cycle-time specifications. Demand concentrates among United States residential contractors and German civil engineering firms seeking verified bucket breakout force without new-machine capital outlay. EPA Tier 4 Final engine retrofits add compliance cost but preserve resale liquidity in regulated markets.
- Loaders:Articulated frame rebuilds and transmission overhauls restore rated tipping load capacity. Rental fleet operators in Japan and Germany dominate procurement, driven by depreciation schedule management and telematics-enabled utilization tracking. Wheel loader transaction volumes exceed crawler variants due to urban mobility requirements.
- Cranes:Boom structural inspection and hoist mechanism recertification to ANSI/ISO standards.
- Bulldozers:Track system rebuilds and blade hydraulic cylinder reconditioning for grading precision.
Most installed capacity flows through excavators. Expansion is steepest in loaders.
End User:
Customer sophistication determines warranty uptake and certified rebuild preference versus as-is procurement.
- Rental Companies:Fleet standardization around OEM-certified rebuild programs enables uniform maintenance protocols and residual value forecasting. United States and German rental chains leverage volume procurement to secure extended component coverage and telematics integration. Capital deployment discipline favors documented rebuild histories over unverified used sources.
- Contractors:Project-specific equipment matching drives demand across condition tiers. Mid-sized United States residential builders balance upfront savings against downtime risk, with larger civil contractors specifying remanufactured powertrain units for critical path machinery. Financing access varies with rebuild documentation completeness.
- Government:Municipal procurement rules mandating emissions compliance and safety certification.
- Forestry:Specialized undercarriage and guarding modifications for steep-slope applications.
Rental companies command the largest transaction volumes. Contractors are gaining share fastest as subscription models fragment traditional ownership.
Sales Channel:
Channel selection determines information symmetry and pricing transparency available to buyers.
- Dealers:OEM-authorized networks bundle certified rebuild documentation with warranty coverage and genuine parts access. United States and Japanese dealer systems control premium margin pools through proprietary technical documentation and factory-trained technician certification. Financing integration captures buyers seeking operational expense treatment.
- Online Platforms:Digital marketplaces aggregate inventory across independent refurbishers and fleet disposition programs. Price-sensitive contractors in fragmented United States regional markets utilize these channels for good-condition units without service contract requirements. Photographic documentation and maintenance record uploads vary in completeness.
- Direct Sales:Fleet-to-fleet transactions between large operators with established equipment histories.
- Auctions:Accelerated disposition for distressed or incomplete rebuild candidates.
Dealers retain the highest value-add position. Online platforms are climbing the fastest as digital records improve trust mechanisms.
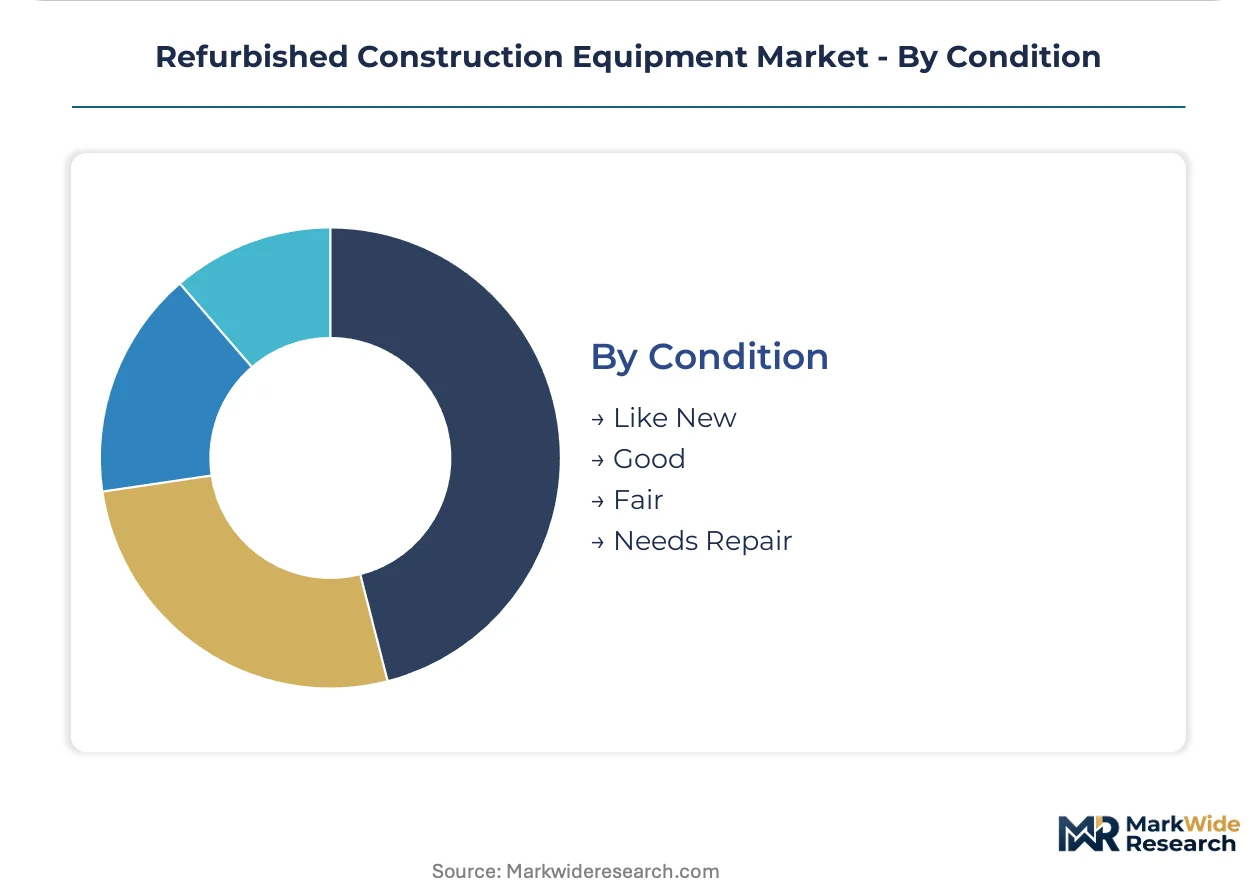
Condition:
Condition grading structures risk allocation between seller and buyer across price tiers.
- Like New:Comprehensive component replacement and cosmetic restoration to OEM cosmetic and performance standards. Premium pricing applies to units with complete service history documentation and remaining factory warranty transferability. United States and German buyers prioritize this tier for fleet standardization and residual value preservation.
- Good:Functional rebuild with verified operational metrics but visible wear indicators. Contractors with predictable project pipelines accept cosmetic imperfections in exchange for production-grade capability at reduced capital outlay. Financing availability depends on independent inspection certification.
- Fair:Operational units requiring near-term maintenance investment.
- Needs Repair:Incomplete refurbishment candidates for parts harvesting or rebuild-investment decisions.
Good condition units absorb the largest transaction volume. Like New inventory is expanding most quickly as OEM certified programs scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany generates higher certified rebuild volumes per capita than the United States, while Japan maintains stricter refurbishment protocols through METI-mandated energy-efficiency benchmarks.
United States
Rental fleet operators in Texas and Florida drive excavator and loader refurbishment demand through depreciation management strategies. EPA Tier 4 Final standards enforce diesel particulate filter and selective catalytic retrofits on rebuilt engines above 56kW. Houston's energy infrastructure cluster consumes remanufactured earthmoving equipment for pipeline and refinery maintenance cycles.
Germany
Civil engineering contractors in North Rhine-Westphalia prioritize OEM-certified rebuild programs with documented EU Stage V compliance chains. The country's national type-approval authority mandates exhaust after-treatment installation for non-road mobile machinery remanufacturing. Munich's construction equipment dealer networks bundle telematics integration with extended component warranties.
Japan
Metropolitan Tokyo rental companies standardize procurement around certified rebuild units with KOMTRAX-enabled utilization tracking. METI energy-efficiency guidelines and JIS quality standards shape refurbishment protocols for export-oriented hydraulic excavators. Osaka's industrial machinery cluster specializes in precision component reconditioning for secondary Asian markets.
India
National highway and metro rail projects in Maharashtra and Karnataka generate demand for cost-optimized earthmoving equipment with verified rebuild histories. The country's central infrastructure regulator emphasizes documented maintenance records for public works equipment procurement. Delhi-NCR contractor fleets increasingly specify remanufactured powertrain assemblies to manage project capital outlays.
China
Provincial infrastructure stimulus in Sichuan-Chongqing and the Yangtze River Delta sustains secondary market transaction volumes for hydraulic excavators. The Ministry of Ecology and Environment enforces emissions compliance timelines that accelerate certified rebuild adoption over new diesel purchases. Shanghai's equipment finance arms bundle refurbishment documentation with operational lease structures.
Refurbished Construction Equipment Market Competitive Landscape
Top-tier vendors anchor the premium certified-rebuild segment, while independent refurbishers compete on price-sensitive procurement channels. Market structure consolidates around OEM-authorized service networks controlling proprietary technical documentation and genuine parts access. Strategic archetypes include telematics-integrated rebuild specialists, emissions-compliance service providers, and rental fleet standardization partners. Dominant competitive moves encompass backward integration into remanufactured component production and strategic equipment-as-a-service subscription bundling.
Within the premium-tier vector, Caterpillar Inc. and Komatsu Ltd. occupy positions defined by certified rebuild program scale and connected asset monitoring integration. Sany Heavy Industry Co. Ltd. represents the Chinese archetype of volume-oriented refurbishment capacity serving infrastructure-intensive domestic markets. These three entities exemplify how geographic origin and corporate structure correlate with strategic emphasis on either warranty-backed certification or cost-optimized secondary market penetration.
| Leading Market Players |
|---|
| Volvo Construction Equipment |
| XCMG Group |
| Caterpillar Inc. |
| Sany Heavy Industry Co. Ltd. |
| Liebherr Group |
| Komatsu Ltd. |
| Hitachi Construction Machinery Co., Ltd. |
| Doosan Group |
| Deere & Company |
| Others |
Value Network & Pricing Analysis
Rental fleet operators in Germany and the United States anchor demand for certified rebuild programs, driving a contract-based pricing structure that bundles warranty coverage with predictable maintenance costs. This buyer concentration rewards OEM-authorized channels with premium margin capture while compressing price realization for independent refurbishers competing on transactional spot markets.
Pricing Analysis
Capacity additions in China's hydraulic component manufacturing base are reshaping price floors for cylinder barrels and high-pressure hoses used in refurbishment workflows. Three-tier pricing structure across premium, standard, and economy levels separates OEM-certified rebuilds with telematics integration from third-party refurbished units and as-is secondary market assets. Cost compression in the independent refurbisher tier is intensifying because steel input volatility erodes margin predictability. Small-to-mid contractors exhibit highest price sensitivity, while rental fleet operators prioritize total cost of ownership over upfront capital outlay.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for certified powertrain assemblies and remanufactured hydraulic systems. Component sourcing concentrates in China, Germany, and Japan for precision-engineered pumps, electronic control modules, and emissions after-treatment hardware. Rebuild operations draw from steel mills, specialized foundries, and genuine parts distribution networks controlled by dealer authorization systems. Single-source vulnerability in proprietary technical documentation access creates supply chain risk for independent refurbishers seeking OEM-grade certification. Distribution runs through authorized dealer networks, online marketplaces, and direct fleet disposition programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in refurbished construction equipment rests on certified rebuild program scaling and telematics-enabled service bundling that commands premium pricing over commodity secondary market transactions.
For Market Incumbents: Cement dealer network control by deepening captive supply of remanufactured powertrain assemblies and hydraulic components. Battery-electric substitution threats in municipal fleet segments demand accelerated investment in emissions compliance service capabilities to defend certified rebuild relevance against zero-emission new equipment. For New Entrants and Emerging Players: EU Stage V in Germany opens a window for specialized engine remanufacturing services targeting exhaust after-treatment retrofit demand. India's infrastructure build-out presents the most penetrable geography for cost-optimized earthmoving equipment with documented rebuild histories. A telematics-integrated fleet management offering provides differentiated go-to-market positioning against established OEM channels. For Investors and Strategic Acquirers: Equipment rental companies are the most active acquirer in this space, consolidating regional refurbishers to standardize fleet procurement and residual value forecasting. Long-term viability centers on subscription-based equipment access models that fragment traditional ownership patterns. Monitor battery-electric penetration rates in urban construction zones as the critical inflection signal for diesel rebuild demand displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Remanufactured Components | OEMs capture margin pools previously allocated to third-party hydraulic and powertrain suppliers. |
| Telematics-Enabled Subscription Bundling | Dealer finance arms convert capital expenditure buyers to operational expense treatment with utilization tracking. |
| EU Stage V Compliance Service Expansion | Engine remanufacturers in Germany secure mandated exhaust after-treatment retrofit contracts from civil contractors. |
| Blockchain Provenance Verification Deployment | Distributed ledger systems reduce information asymmetry for secondary market transactions across online platforms. |
| India Infrastructure Fleet Partnership | Certified rebuild providers align with national highway and metro rail project capital constraints. |
Research Methodology
Multiple input streams — maintenance director interviews, OEM aftermarket service head discussions, rental fleet procurement lead consultations, and dealer operations manager exchanges — were reconciled with trade data from customs records, equipment registration databases, and SEC filings from publicly listed machinery manufacturers. Secondary validation drew from EPA enforcement actions, EU type-approval authority documentation, and METI energy-efficiency guideline publications. Bottom-up transaction volume estimates and top-down market sizing approaches were cross-referenced to establish analytical coherence.
Historical rebuild volume patterns were cross-referenced against panel input from refurbishment facility operators and component suppliers across the projection horizon. Segmentation dimensions modeled include equipment category, condition tier, procurement channel, and end-user archetype. CAGRs were derived from trend extrapolation adjusted for regulatory compliance phase-in schedules and rental fleet expansion trajectories. Forecast inputs incorporated telematics adoption curves, emissions retrofit cost trajectories, and steel price volatility assumptions.
Revisions become necessary when battery-electric equipment penetration accelerates beyond modeled substitution rates, when steel and hydraulic component input costs diverge substantially from baseline assumptions, or when dealer network consolidation alters competitive access to proprietary technical documentation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Road Roller Market
Construction Equipment
Laser Cladding Systems Market
Construction Equipment
Pre-Owned Construction Equipment Market
Construction Equipment
Electrofusion Welding Machines Market
Construction Equipment
Plasma Cutting Equipment Market
Construction Equipment
Snow Clearing Vehicles Market
Construction Equipment
3-Wheel Sit-Down Counterbalance Forklift Market
Construction Equipment
Construction Equipment Rental Market
Construction Equipment
Pile Cage Welding Machine Market
Construction Equipment
Compaction Equipment Market
Construction Equipment
Rubber Track Pads for Construction Machinery Market
Construction Equipment
Rotary Trommel Market
Construction Equipment
Tray Dryers Market
Construction Equipment
Drone-Based Solutions in Construction Market
Construction Equipment
Drilling Machine Market
Construction Equipment
Ultrasonic Welding Machine Market