
 Philippines Roofing Market | 2026-2036
Philippines Roofing Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Roofing Market Analytics
Philippine Standard (DPWH) NSCP certification for wind and seismic load resistance is collapsing the supplier base to manufacturers with accredited testing facilities. Puyat Steel Corporation leverages its ISO-certified Batangas plant to dominate Luzon distribution. Colorsteel Systems Corporation sustains premium positioning through proprietary color-coating technology. Jacinto Color Steel Inc. anchors Visayas supply chains with regional fabrication capacity.
Philippines roofing encompasses engineered systems—metal sheets with zinc-aluminum coating, clay tiles fired at 1,000°C, and reinforced concrete panels—designed to shed tropical rainfall and resist typhoon wind loads exceeding 200 kph. Metal roofing leads volume due to lower installed cost and faster erection cycles for mass housing. Clay tiles command margin pools in heritage and high-end residential segments where aesthetic differentiation supports pricing power. Flat roof structures are gaining share in commercial and industrial applications as developers optimize floor-area ratios in dense urban zones.
The Department of Public Works and Highways enforces National Structural Code of the Philippines compliance, while the Bureau of Product Standards mandates BIS-equivalent material testing for imported substrates. DPWH infrastructure spending channels demand toward certified domestic suppliers, and local government building permit offices increasingly require proof of standard compliance before issuance. Stakeholders must monitor pending amendments to the National Building Code that could mandate higher thermal performance ratings for roofing assemblies in tropical climates.
Market Dynamics
DPWH enforcement of National Structural Code of the Philippines compliance is collapsing the supplier base toward accredited domestic manufacturers with certified testing facilities, reshaping procurement flows across Luzon industrial estates and Metro Manila residential corridors.
Growth Catalysts
- Industrial Estate Expansion:Calabarzon and Central Luzon industrial zones are driving bulk orders for metal roofing systems with rapid erection cycles.
- NSCP Certification Mandate:DPWH building code enforcement channels public infrastructure spending toward wind-resistant material suppliers with accredited laboratories.
- Mass Housing Programs:National Housing Authority initiatives in Metro Manila periphery provinces are accelerating demand for cost-competitive zinc-aluminum coated sheets.
Market Restraints
- Zinc-Aluminum Substrate Volatility:Global metal commodity swings compress margins for domestic coil coaters dependent on imported substrates.
- Batangas Supply Concentration:ISO-certified production capacity clusters in Southern Luzon, creating logistics bottlenecks for Visayas and Mindanao projects.
- Clay Tile Technical Ceiling:Firing temperatures above 1,000°C limit production scale-up and constrain supply response to heritage segment demand spikes.
Strategic Opportunities
- Visayas Fabrication Gap:Regional steel processing capacity in Cebu and Iloilo remains underdeveloped relative to construction permit growth.
- Flat Roof Commercial Pivot:Floor-area ratio optimization in dense urban zones is creating specification openings for membrane and reinforced panel systems.
- Thermal Performance Mandate:Pending National Building Code amendments on tropical climate roofing assemblies would favor insulated metal composite suppliers.
Industry Challenges
- NSCP Certification Timeline:DPWH accreditation processes for new material entrants extend 12-18 months, delaying market entry for imported substrate variants.
- Coating Application Skill Gap:Proprietary color-coating technology deployment requires specialized technician training unavailable in provincial labor pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Roofing Market |
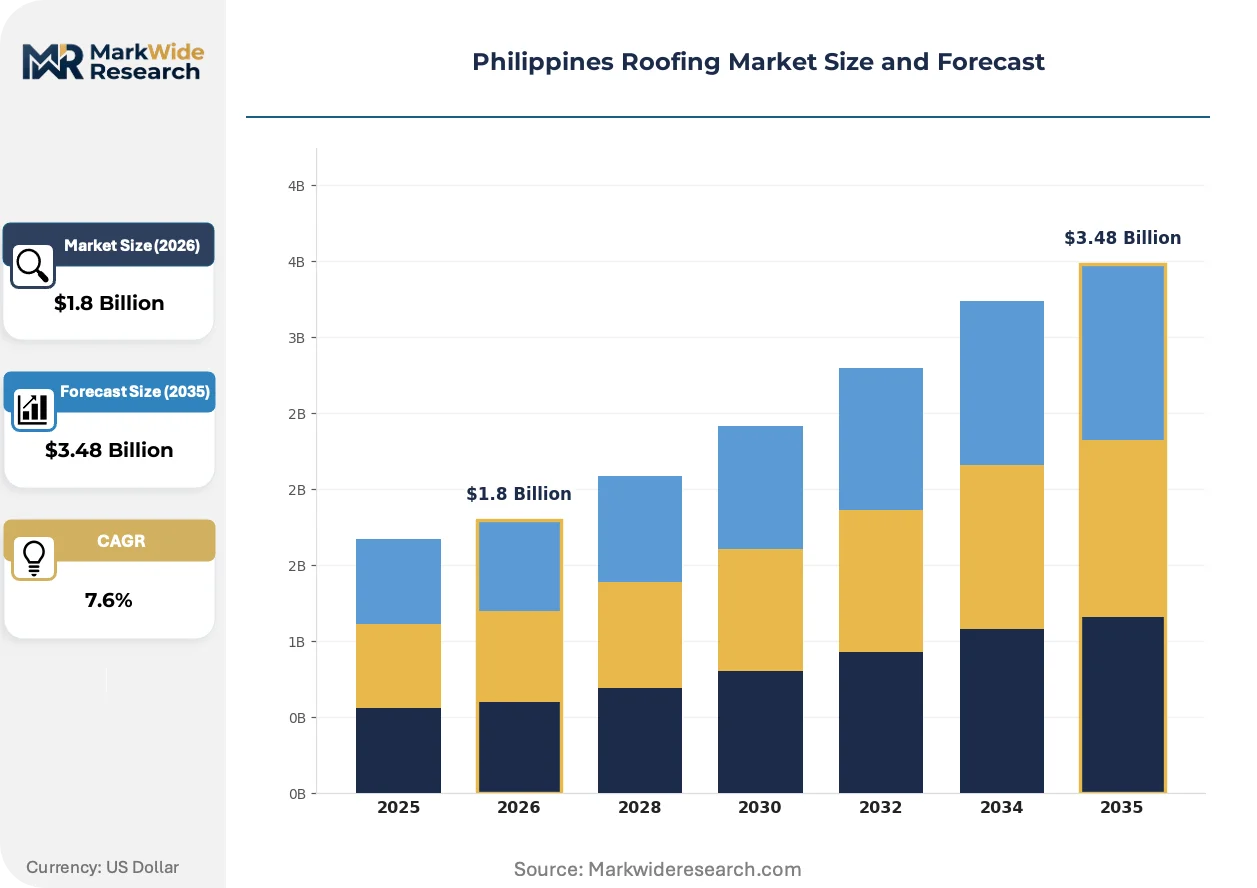
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Metal, Asphalt Shingles, Clay Tiles, Concrete Application: Residential, Commercial, Industrial, Agricultural Roof Structure: Flat, Pitched, Gabled, Curved Distribution Channel: Direct Sales, Retail, Wholesale, Online |
| Companies Covered | Philsteel Holdings Corporation, Puyat Steel Corporation, Colorsteel Systems Corporation, Sanlex Roofmaster Center Co. Inc., Metalink, Union Galvasteel Corporation, Jacinto Color Steel Inc., SCM Roofing Inc., DN Steel, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Roofing Market Evolving Landscape
Material science advances and regulatory pressure on thermal performance are compressing traditional specification hierarchies, while procurement centralization among large developers reconfigures channel economics across the archipelago.
Prefabricated insulated metal roof panels with integrated vapor barriers are miniaturizing on-site labor requirements for commercial and industrial builds. Large-scale warehouse developers in Calabarzon are specifying these systems for 40% faster envelope completion. The technology is miniaturizing traditional multi-trade roofing assemblies into single-source supplier relationships, compressing subcontractor tiers and shifting margin capture toward panel fabricators.
Pending DPWH amendments to thermal performance standards for tropical climate roofing assemblies are forcing specification upgrades across commercial permit applications. The industrial consequence is accelerated R&D spending on reflective coatings and insulated substrates by domestic coil coaters. Metro Manila commercial developers are responding by pre-qualifying suppliers with existing cool-roof certification rather than awaiting final rule publication.
Consolidated procurement by national residential developers is displacing fragmented distributor networks in volume segments. Direct mill relationships are replacing traditional hardware channel purchases for subdivision projects above 500 units. This concentration is most visible in Cavite and Laguna where horizontal housing estates dominate permit issuance and developers negotiate annual volume contracts with Batangas-based producers.
Philippines Roofing Market Segmentation
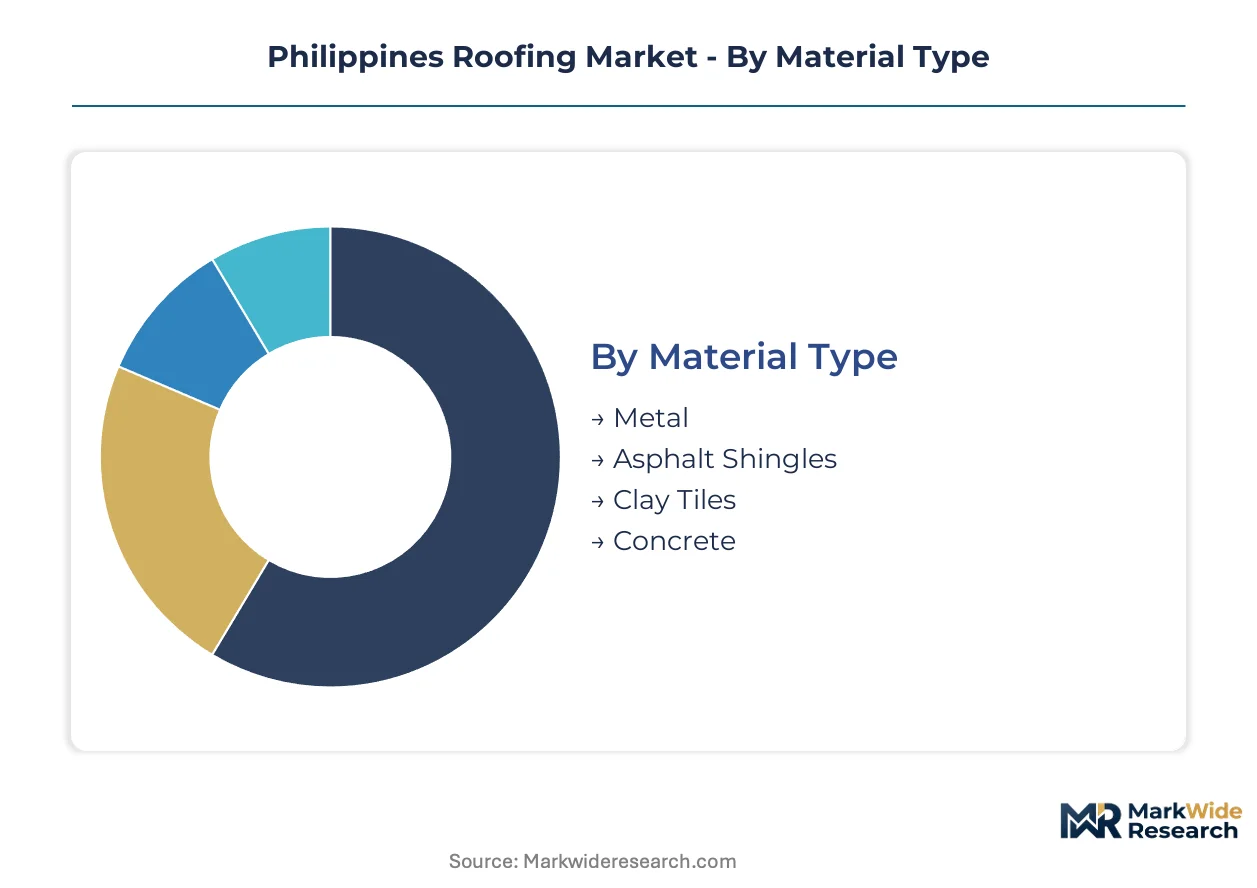
Material specification and roof geometry drive procurement channel selection in the Philippine archipelago. Typhoon wind loads and tropical rainfall intensity compress viable options for each application context.
Material Type:
Channel concentration varies sharply by substrate cost and installation complexity.
- Metal:Zinc-aluminum coated steel sheets with 200+ kph wind resistance dominate mass housing procurement through direct mill contracts. Calabarzon industrial estates and Metro Manila periphery subdivisions channel volume toward Batangas-based coil coaters with ISO-certified facilities.
- Clay Tiles:Fired at 1,000°C, these command heritage restoration and premium residential segments where aesthetic differentiation supports distributor markups. Supply bottlenecks constrain rapid scale-up despite margin pools in conservation zones.
- Asphalt Shingles:Limited tropical moisture resistance restricts specification to highland residential projects with moderated rainfall exposure.
- Concrete:Reinforced panels serve flat-roof commercial builds where floor-area ratio optimization drives specification in dense urban zones.
By volume, metal leads. By growth pace, concrete is climbing the fastest amid commercial flat-roof adoption.
Application:
End-use scale determines supplier relationship structure and certification requirements.
- Residential:Mass housing programs above 500 units consolidate procurement through annual volume contracts with domestic mills. National Housing Authority initiatives in Cavite and Laguna displace traditional hardware channels.
- Industrial:Warehouse and factory builds in Central Luzon industrial zones specify prefabricated insulated panels for 40% faster envelope completion. Rapid erection cycles compress subcontractor tiers toward single-source relationships.
- Commercial:Metro Manila office and retail permits increasingly pre-qualify cool-roof certified suppliers ahead of pending DPWH thermal performance amendments.
- Agricultural:Poultry and aquaculture structures in provincial zones rely on retail distributor networks with limited NSCP compliance documentation.
Industrial procurement concentrates fastest. Residential maintains absolute volume dominance.
Roof Structure:
Geometry selection interacts with local wind codes and urban density incentives.
- Pitched:Dominant across residential construction for rainfall shedding efficiency. DPWH National Structural Code of the Philippines mandates specific slope ratios for typhoon-prone zones.
- Flat:Expanding share in commercial and industrial applications as developers optimize floor-area ratios. Membrane and reinforced panel systems displace traditional multi-trade assemblies.
- Gabled:Standard specification for heritage restoration and high-end residential where clay tile aesthetics command premium positioning.
- Curved:Limited to signature commercial and institutional projects requiring specialized structural engineering and extended permit timelines.
Pitched structures retain volume leadership. Flat configurations gain share fastest in urban commercial permits.
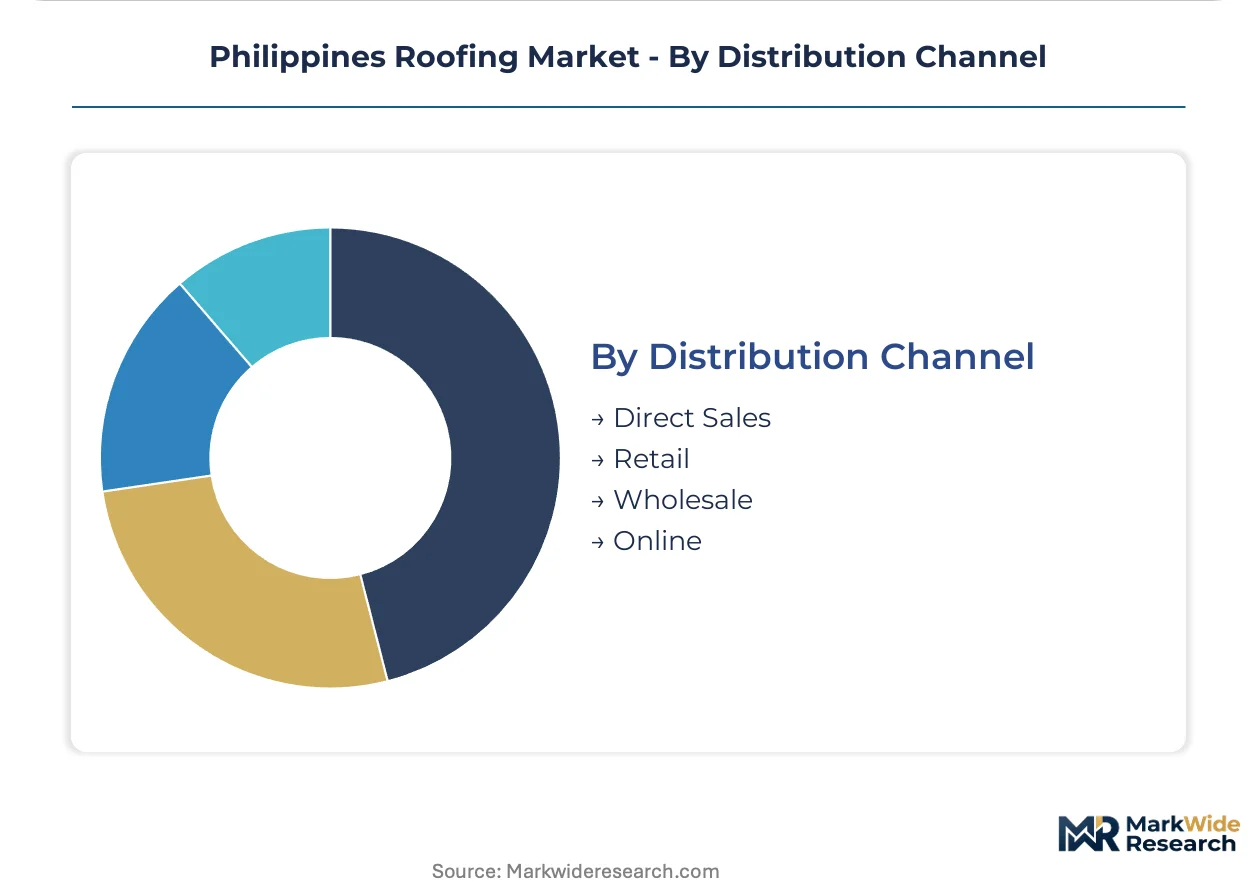
Distribution Channel:
Channel selection tracks project scale and certification complexity.
- Direct Sales:National residential developers and industrial estate operators negotiate mill-direct contracts bypassing distributor markups. Consolidated procurement above 500 units shifts margin capture toward Batangas-based producers.
- Wholesale:Regional contractors in Visayas and Mindanao rely on bulk distributors bridging Batangas supply concentration and archipelago logistics bottlenecks.
- Retail:Fragmented hardware channel serves small-scale residential repairs and agricultural builds with limited NSCP documentation requirements.
- Online:Emerging for standardized metal sheet specifications where buyers self-serve technical documentation and bypass provincial inventory limitations.
Direct sales expand most quickly. Wholesale retains intermediary dominance for inter-island logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-scale residential developers and industrial estate operators concentrate procurement power across three sub-regions that generate the bulk of certified roofing demand. National Housing Authority programs and DPWH infrastructure spending channel volume toward suppliers with accredited testing facilities in these corridors.
Metro Manila and Periphery Provinces
Cavite and Laguna horizontal housing estates dominate permit issuance, with developers negotiating annual volume contracts for zinc-aluminum coated sheets. The National Housing Authority's mass housing initiatives in Bulacan and Rizal accelerate demand for cost-competitive metal roofing with rapid erection cycles. Caloocan and Quezon City commercial permits increasingly pre-qualify cool-roof certified suppliers ahead of pending DPWH thermal performance amendments.
Calabarzon Industrial Corridor
Batangas-based ISO-certified coil coaters anchor Luzon supply chains, serving warehouse and factory builds across Laguna and Cavite industrial zones. DPWH enforcement of National Structural Code of the Philippines compliance channels public infrastructure spending toward wind-resistant material suppliers with accredited laboratories. Santa Rosa and Biñan manufacturing estates specify prefabricated insulated panels for faster envelope completion.
Central Luzon Growth Belt
Pampanga and Tarlac industrial estates drive bulk orders for metal roofing systems as Clark Freeport Zone expansion accelerates. The Department of Public Works and Highways updated building code enforcement pushes contractors toward certified materials for typhoon resistance. Subic Bay and Angeles City logistics hubs concentrate distribution capacity for northward supply to Ilocos and Cagayan Valley.
Visayas Supply Network
Cebu and Iloilo construction permit growth outpaces regional steel processing capacity, creating fabrication gaps bridged by Batangas-based distributors. Jacinto Color Steel Inc. anchors Visayas supply chains with regional fabrication capacity. Mandaue and Lapu-Lapu industrial zones rely on inter-island logistics for NSCP-certified materials.
Mindanao Emerging Demand
Davao del Norte and South Cotabato agricultural processing facilities generate demand for cost-optimized metal roofing through retail distributor networks. Cagayan de Oro commercial permits show early specification shifts toward flat-roof membrane systems. Mindanao projects face logistics bottlenecks from Batangas supply concentration.
Philippines Roofing Market Competitive Landscape
Player mix skews toward integrated domestic coil coaters with ISO-certified facilities and regional fabricators bridging archipelago logistics gaps. Three strategic archetypes dominate: Batangas-based integrated producers with captive coating capacity, Visayas-anchored regional fabricators with distribution reach, and hardware-channel distributors serving fragmented provincial demand. Competitive moves center on direct mill relationships with national developers and capacity expansion into underserved inter-island corridors.
Among domestic integrated producers, Puyat Steel Corporation and Colorsteel Systems Corporation exemplify the certified-facility archetype that DPWH compliance requirements favor. Jacinto Color Steel Inc. occupies a position within the regional-fabricator tier, anchoring Visayas supply chains against Luzon production concentration. These three companies represent the supplier-base collapse toward accredited domestic manufacturers that NSCP certification mandates have triggered.
| Leading Market Players |
|---|
| Philsteel Holdings Corporation |
| Puyat Steel Corporation |
| Colorsteel Systems Corporation |
| Sanlex Roofmaster Center Co. Inc. |
| Metalink |
| Union Galvasteel Corporation |
| Jacinto Color Steel Inc. |
| SCM Roofing Inc. |
| DN Steel |
| Others |
Value Network & Pricing Analysis
Annual volume contracts with Batangas-based coil coaters lock in zinc-aluminum substrate access and strip out spot-market volatility for national developers. DPWH certification requirements tether price visibility to ISO-accredited facility access, compressing procurement options toward integrated domestic producers.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange zinc and aluminum prices dominate procurement for volume buyers. Price differentiation rests on NSCP certification grade and volume scale, with mass housing developers commanding 15-20% discounts over retail hardware channels. Pricing pressure stems from global metal commodity swings eroding coil coater margins. Agricultural and provincial repair segments exhibit highest price sensitivity, while Metro Manila commercial developers prioritize thermal performance certification over unit cost.
Supply Chain Analysis
Port congestion at Manila North Harbor and container availability on China-Philippines trade lanes inflate inbound substrate costs for domestic coil coaters. Supply concentrates in China, South Korea, and Japan for zinc-aluminum coated steel substrates. Raw material dependencies span galvanized steel coils, color-coating chemicals, and aluminum-zinc alloy ingots. Single-source vulnerability concentrates in Batangas ISO-certified production, where typhoon disruption would cascade across Luzon industrial estates. Distribution runs through direct mill relationships for volume buyers and wholesale distributors bridging inter-island logistics gaps.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation across Visayas and Mindanao creates service-layer niches as centralized procurement displaces traditional hardware channels in Luzon. DPWH thermal performance amendments will bifurcate supplier tiers, rewarding pre-qualified certificated players.
For Market Incumbents: Shield certified-facility positioning by accelerating Visayas fabrication capacity before Jacinto Color Steel Inc. consolidates regional share. Prioritize backward integration into color-coating chemical supply to offset commodity volatility. Defend against direct-mill relationship erosion by embedding technical service teams with national developers. For New Entrants and Emerging Players: Post-installation technical service and warranty claim management represent under-served layers where incumbents lack provincial coverage. Target Mindanao agricultural processing facilities through retail distributor partnerships with NSCP documentation support. Enter via membrane and flat-roof panel specialization ahead of commercial pivot demand. For Investors and Strategic Acquirers: Capital is best deployed toward regional fabricators with inter-island logistics reach and pending DPWH certification pipeline. Five-to-ten year viability hinges on thermal performance mandate compliance rather than commodity cost position. Watch for DPWH accreditation timeline acceleration as inflection signal for consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Visayas Fabrication Capacity Expansion | Bridges supply gap as Cebu construction permits outpace regional steel processing. |
| Cool-Roof Certification Pre-Qualification | Positions suppliers ahead of pending DPWH thermal performance amendments. |
| Direct Mill Relationship Development | Captures margin from consolidated procurement by 500+ unit residential developers. |
| Prefabricated Insulated Panel Scale-Up | Addresses Calabarzon warehouse demand for 40% faster envelope completion. |
| Inter-Island Logistics Partnership | Resolves Batangas supply concentration bottlenecks for Mindanao project access. |
Research Methodology
A spread of perspectives from coil coater plant managers, National Housing Authority procurement officers, DPWH building code enforcement officials, and provincial hardware distributors converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through DPWH certification registries, Bureau of Product Standards import records, and industrial estate permit databases. Bottom-up volume triangulation across material type and application segments was cross-checked against top-down construction spending flows.
Segmentation dimensions modeled include material substrate, roof geometry, end-use application, and distribution channel structure across the analysis window. CAGRs were derived from trend extrapolation of certified supplier capacity expansion and permit issuance velocity. Forecast inputs incorporated NSCP certification timeline assumptions and thermal performance mandate implementation probability.
Forecasts assume regulatory continuity in DPWH building code enforcement and Bureau of Product Standards import testing regimes; material policy shifts would require re-modeling. Zinc-aluminum commodity price volatility and typhoon disruption frequency represent specific risk factors that could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
Metal Structural Insulation Panels Market
Structural Engineering
North America Anchors and Grouts Market
Structural Engineering
Cold-Formed Steel Market
Structural Engineering
North America Facade Market
Structural Engineering
UK Facade Market
Structural Engineering
Philippines Structural Insulated Panels Market
Structural Engineering
FRP Bridge Market
Structural Engineering
Steel Structure Anchor Bolt Market
Structural Engineering
Structural Lightweight Concrete Market
Structural Engineering
High Damping Rubber Bearing (HDRB) Market
Structural Engineering
Europe Facade Market
Structural Engineering
Structural Steel Market
Structural Engineering
Europe Structural Health Monitoring Market
Structural Engineering
Concrete Slabs Market
Structural Engineering
Prestressed High Strength Concrete Pipe Pile Market
Structural Engineering
Offshore Structural Analysis Software Market