
 India Concrete Admixtures Market | 2026-2036
India Concrete Admixtures Market Size, Share, and Industry Trends Forecast 2026-2036
India Concrete Admixtures Market Foresight
Product bundling of plasticizers with waterproofing systems is pivoting contractor procurement behavior toward single-source suppliers. Sika AG leverages its integrated construction chemicals portfolio to anchor premium positioning in metro rail projects across western India. BASF SE competes through specialized superplasticizer lines designed for high-strength concrete in coastal infrastructure. Pidilite Industries Ltd. dominates the mid-market through extensive distributor networks reaching tier-two contractors in Gujarat and Rajasthan.
Concrete admixtures are chemical formulations added during batching to modify fresh or hardened concrete properties, typically dosed at 0.5% to 5% by weight of cement content, enabling slump retention, accelerated set, or enhanced durability in aggressive environments. Superplasticizers command the deepest margin pools due to performance premiums on infrastructure-grade concrete, while liquid admixtures lead volume given ease of on-site dosing and compatibility with automated batching plants. Infrastructure projects represent the fastest-growing application channel as NHAI and state highway authorities specify extended workability windows for continuous paving operations.
BIS standards for construction chemicals, CEA building energy codes, and state-level RERA compliance frameworks collectively elevate product certification requirements, filtering out unorganized suppliers from institutional tenders. The central PLI scheme for specialty chemicals is channeling capital toward domestic manufacturing of polycarboxylate ether superplasticizers previously imported from European sources. Stakeholders must monitor BIS revision cycles and state public works department specification updates to anticipate formulation registration demands ahead of contract bidding windows.
Market Dynamics
Polycarboxylate ether superplasticizer localization under India's PLI scheme for specialty chemicals is compressing import dependence while BIS certification cycles filter supplier participation in institutional tenders.
Growth Catalysts
- NHAI Continuous Paving Specifications:National highway authority mandates for extended workability windows drive specification of high-range water reducers in bridge and elevated corridor projects across western India.
- Smart City Mission Concentration:Metro rail and urban infrastructure bundling in Maharashtra, Gujarat, and Tamil Nadu creates dense demand clusters for performance-grade admixture formulations.
- BIS IS 9103:2023 Revision:Updated construction chemical standards mandate third-party testing for air-entraining and retarding admixtures, accelerating formalization of supply relationships.
Market Restraints
- Ethylene Oxide Price Volatility:Polycarboxylate ether raw material exposure to naphtha-linked petrochemical cycles compresses margin predictability for domestic blenders.
- Western India Production Concentration:Gujarat and Maharashtra host over two-thirds of formulated admixture capacity, creating regional supply vulnerability during monsoon logistics disruptions.
- Liquid Admixture Shelf Constraints:Temperature-sensitive polymer stability limits inventory holding periods, forcing just-in-time production scheduling that amplifies working capital intensity.
Strategic Opportunities
- North-Eastern State Infrastructure Gap:Assam and Meghalaya highway expansion under the Special Accelerated Road Development Programme offers first-mover positioning before BIS enforcement tightens.
- CEA Building Energy Code Integration:Thermal mass optimization requirements in commercial construction create specification pull for retarding admixtures that enable extended pour windows in high-rise cores.
- Distributor Digital Integration:Tier-two contractor procurement through integrated construction chemical platforms is consolidating fragmented rural demand into trackable annual contracts.
Industry Challenges
- Formulation Chemist Scarcity:Polymer synthesis expertise for polycarboxylate ether molecular weight tuning concentrates in Ahmedabad and Mumbai, constraining R&D expansion for mid-market players.
- BIS Registration Timeline Compression:Six-to-nine month certification cycles for new admixture variants misalign with twelve-week public works department tender windows, forcing speculative pre-registration investment.
- Automated Batching Plant Compatibility:Legacy dry-mix facilities in Rajasthan and Madhya Pradesh require dosing system retrofits to handle liquid superplasticizer precision, delaying specification upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Concrete Admixtures Market |
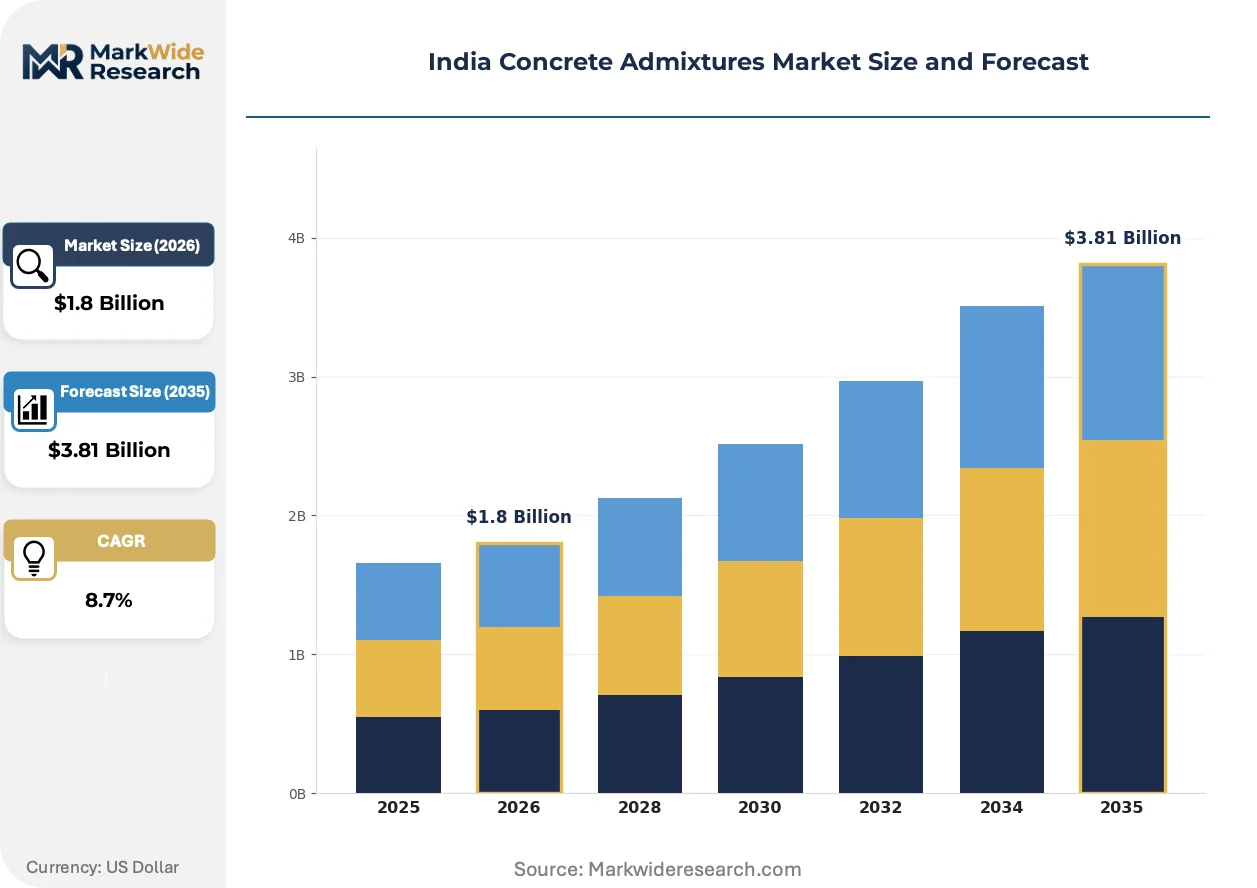
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasticizers, Superplasticizers, Retarding Admixtures, Accelerating Admixtures Application: Residential Construction, Commercial Construction, Industrial Construction, Infrastructure Projects Technology: Liquid Admixtures, Powder Admixtures, Mineral Admixtures, Synthetic Admixtures End User: Contractors, Builders, Construction Firms, Engineering Consultants |
| Companies Covered | MAPEI S.p.A., ACC Limited, Sika AG, Pidilite Industries Ltd., CICO Group, Fosroc, Inc., BASF SE, GCP Applied Technologies Inc., Saint-Gobain, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Concrete Admixtures Market Shifts & Advancements
Digital batching integration and bio-based polymer research are restructuring formulation value capture, while regulatory tightening on construction chemical quality is elevating certified supplier premiums.
Automated dosing systems with real-time slump monitoring are automating quality control in National Highway Authority of India continuous paving projects. Western India contractors deploying these integrated batching units report reduced on-site testing labor and tighter viscosity control across extended pour windows. The technology is automating specification compliance documentation, compressing the role of manual slump cone testing in institutional project acceptance protocols.
Bureau of Indian Standards IS 9103:2023 implementation mandates third-party laboratory certification for all construction chemical categories prior to tender eligibility. State public works departments in Maharashtra and Tamil Nadu have incorporated these certification requirements into technical bid evaluation criteria, filtering unorganized suppliers from metro rail and smart city contracts. Mid-market blenders are responding by consolidating formulation registration portfolios rather than pursuing marginal product line extensions.
Contractor procurement consolidation around single-source construction chemical suppliers is displacing fragmented multi-vendor purchasing in western India highway projects. Integrated waterproofing-admixture bundling from established distributors now dominates tier-one contractor annual agreements, compressing spot-market transactions for commodity plasticizers. This concentration is most visible in Gujarat, where state highway authority framework contracts specify bundled performance warranties across concrete durability systems.
India Concrete Admixtures Market Segmentation
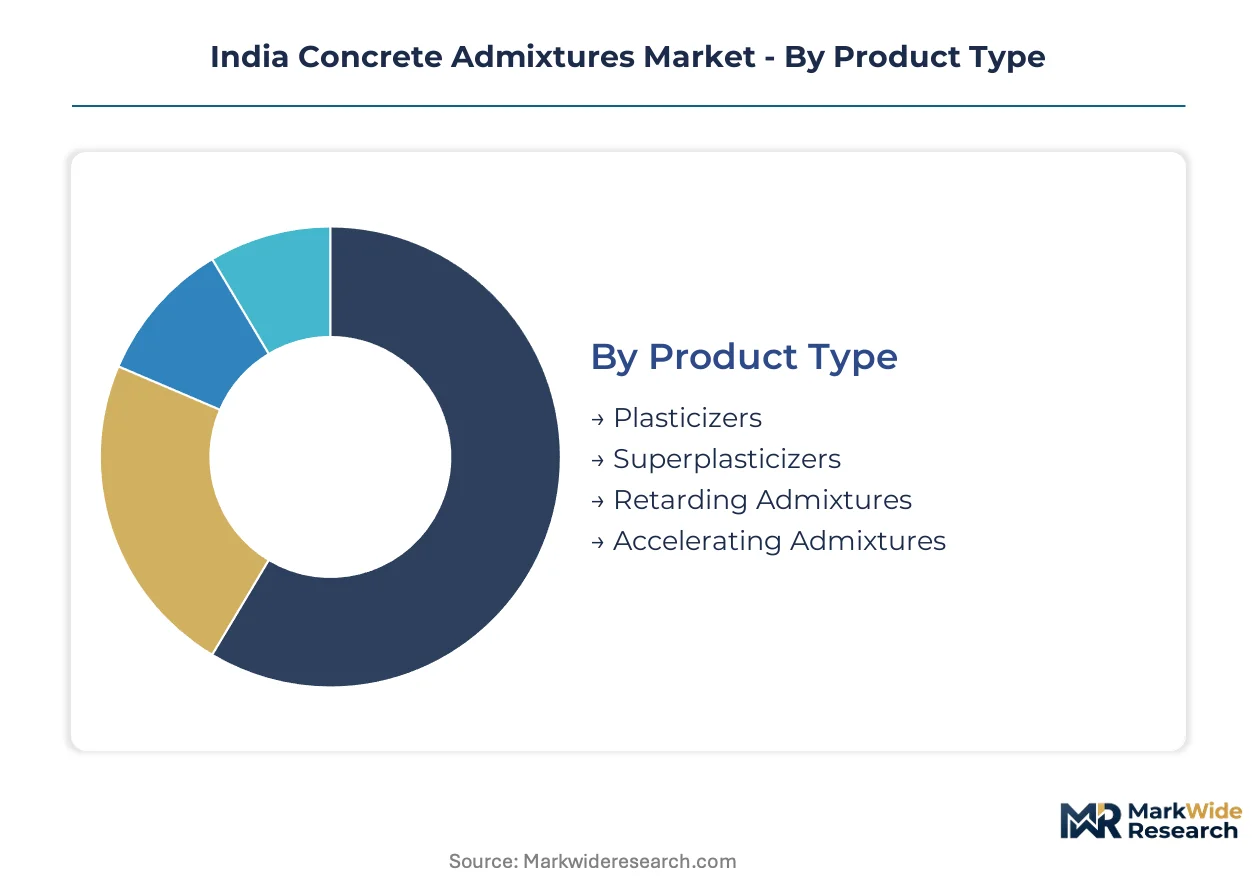
Segmentation in the India concrete admixtures market reveals how specification requirements diverge across project scales and regional infrastructure maturity. Understanding these divisions enables suppliers to align formulation portfolios with procurement patterns in western India's institutional corridor versus emerging demand pockets in the north-east.
Product Type:
Performance specifications for fresh and hardened concrete properties define the technology selection hierarchy across India's institutional construction pipeline.
- Superplasticizers:Polycarboxylate ether formulations enable high-range water reduction for extended workability windows in National Highway Authority continuous paving specifications. Maharashtra and Gujarat contractors specify these for elevated corridor projects demanding slump retention beyond 120 minutes.
- Plasticizers:Lignosulfonate and naphthalene-based mid-range water reducers serve standard-grade concrete in residential and commercial mid-rise construction. Demand concentrates in tier-two cities across Rajasthan and Madhya Pradesh where cost sensitivity dominates procurement decisions.
- Retarding Admixtures:Hydroxycarboxylic acid and sugar-based formulations delay initial set for large-volume pours in high-rise core construction.
- Accelerating Admixtures:Calcium chloride and non-chloride formulations compress curing cycles for precast yard operations in Tamil Nadu.
Superplasticizers lead on scale; retarding admixtures lead on momentum.
Application:
Project scale and institutional funding access determine specification stringency and admixture performance tier procurement.
- Infrastructure Projects:Bridge, highway, and metro rail construction under NHAI and state public works departments mandate certified high-performance formulations. Western India accounts for the densest contract concentration, with smart city bundling in Maharashtra and Gujarat driving specification upgrades.
- Commercial Construction:High-rise cores and mixed-use developments in Mumbai, Ahmedabad, and Chennai specify retarding and superplasticizer combinations for thermal mass optimization under CEA building energy codes.
- Residential Construction:Individual housing and small-scale apartment projects in tier-two and tier-three cities utilize standard plasticizers through distributor networks.
- Industrial Construction:Manufacturing facility floors and warehouse slabs in Gujarat's industrial corridors demand durability-focused formulations for heavy-load exposure.
Infrastructure projects command premium specification density; commercial construction shows steepest expansion trajectory.
Technology:
Physical form and polymer chemistry determine dosing precision, storage logistics, and compatibility with batching plant automation levels.
- Liquid Admixtures:Aqueous polymer solutions enable precise automated dosing in continuous paving operations and integrate seamlessly with modern ready-mix plant infrastructure. Temperature-sensitive shelf stability constrains inventory holding, forcing just-in-time production scheduling across western India supply nodes.
- Synthetic Admixtures:Engineered polymer systems including polycarboxylate ethers deliver performance premiums for infrastructure-grade specifications. Domestic manufacturing under the PLI scheme for specialty chemicals is compressing import dependence for these molecularly tuned formulations.
- Powder Admixtures:Dry-blended formulations serve legacy batching facilities in Rajasthan and Madhya Pradesh lacking liquid dosing retrofit capacity.
- Mineral Admixtures:Fly ash, silica fume, and slag-based extenders modify cementitious content for mass concrete applications in dam and foundation construction.
Liquid admixtures dominate volume throughput; synthetic formulations capture margin expansion.
End User:
Procurement sophistication and specification authority vary sharply between institutional framework contractors and fragmented tier-two builders.
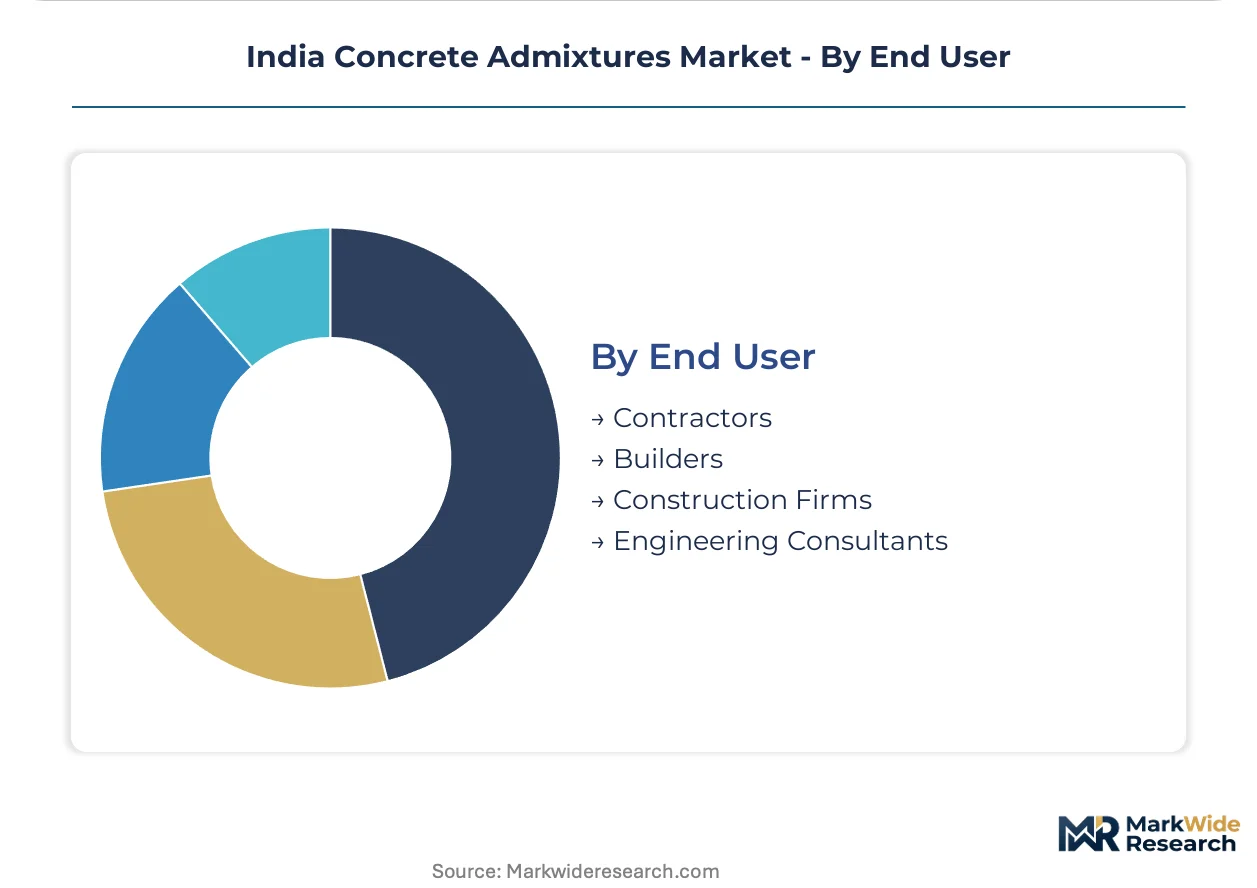
- Contractors:Tier-one highway and metro rail contractors in Maharashtra and Gujarat execute annual framework agreements with integrated construction chemical suppliers. Bundled waterproofing-admixture procurement is displacing fragmented multi-vendor purchasing in these relationships.
- Builders:Residential and commercial project developers in tier-two cities access admixtures through extensive distributor networks reaching Rajasthan and Madhya Pradesh procurement officers.
- Construction Firms:Mid-scale commercial and industrial specialists balance cost and performance across standard plasticizer and entry superplasticizer tiers.
- Engineering Consultants:Structural designers and quality assurance advisors influence specification writing for institutional tenders, driving BIS certification requirements into project documentation.
Contractors concentrate procurement volume; engineering consultants concentrate specification influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western India incubated the country's concrete admixtures industry during the 1990s construction boom, with Gujarat and Maharashtra developing integrated supply chains that now feed institutional infrastructure projects nationwide.
Maharashtra
Mumbai Metro and Nagpur Metro rail corridors drive specification-grade superplasticizer demand. State public works departments mandate BIS IS 9103:2023 certification for all bridge and elevated corridor tenders. The Mumbai-Pune industrial belt concentrates ready-mix plant capacity, with automated batching facilities enabling liquid admixture precision dosing.
Gujarat
State highway authority framework contracts bundle waterproofing and admixture procurement under single-source agreements. The PLI scheme for specialty chemicals channels domestic polycarboxylate ether manufacturing into Dahej and Vadodara chemical zones. Ahmedabad anchors formulation R&D, with polymer synthesis expertise clustering around Gujarat University research corridors.
Tamil Nadu
Chennai Metro expansion and smart city mission projects create dense demand for retarding admixtures in high-rise core construction. State urban development corporations specify extended workability windows for continuous pour operations. The Sriperumbudur-Oragadam industrial corridor hosts precast yard operations demanding accelerated curing formulations.
Delhi-NCR
NHAI continuous paving specifications for Delhi-Mumbai and Delhi-Kolkata expressways drive high-range water reducer procurement. Central Public Works Department tenders enforce BIS certification as technical bid eligibility criteria. Gurugram and Noida construction chemical distributors serve tier-one contractors executing annual framework agreements.
Rajasthan
Jaipur and Jodhpur highway expansion under state road development programs generates mid-range plasticizer demand. Legacy dry-mix batching facilities in tier-two cities require retrofit investment before liquid superplasticizer specification upgrades. Extensive distributor networks reach cost-sensitive contractors in Udaipur and Kota procurement markets.
India Concrete Admixtures Market Competitive Landscape
The competitive structure tilts toward integrated construction chemical conglomerates with diversified formulation portfolios. Tier-one institutional contractors consolidate procurement around single-source suppliers capable of bundling waterproofing, admixture, and repair system warranties. Three archetypes dominate: multinational specialty chemical majors with localized manufacturing, domestic diversified construction chemical houses with deep distribution networks, and regional blenders serving cost-sensitive tier-two markets. Capacity expansion and BIS certification pre-registration constitute the dominant competitive moves, with suppliers racing to lock formulation approvals ahead of twelve-week public works department tender windows.
Among multinational specialists, Sika AG exemplifies premium-tier positioning through integrated portfolio breadth, while BASF SE anchors performance-grade superplasticizer supply for coastal infrastructure specifications. Pidilite Industries Ltd. occupies the mid-market archetype, leveraging extensive distributor penetration across western and northern India to consolidate fragmented contractor demand. These three represent distinct strategic postures: technology-led specification influence, performance-driven institutional capture, and distribution-led volume aggregation.
| Leading Market Players |
|---|
| MAPEI S.p.A. |
| ACC Limited |
| Sika AG |
| Pidilite Industries Ltd. |
| CICO Group |
| Fosroc, Inc. |
| BASF SE |
| GCP Applied Technologies Inc. |
| Saint-Gobain |
| Others |
Supply & Pricing Matrix
Ethylene oxide price volatility cascades through polycarboxylate ether synthesis costs, compressing margin pools for domestic blenders while amplifying pricing power for integrated suppliers with captive naphtha-linked petrochemical feedstocks. BIS certification tiers stratify procurement across institutional highway contractors, commercial developers, and cost-sensitive tier-two builders.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates BIS-certified superplasticizer formulations from mid-range plasticizers and unorganized commodity blends. Price differentiation hinges on certification grade under IS 9103:2023 and volume scale in annual framework agreements. Pricing pressure stems from ethylene oxide feedstock exposure to petrochemical cycles, with margins tightening most acutely for non-integrated blenders. Tier-two contractors in Rajasthan and Madhya Pradesh exhibit highest price sensitivity, while NHAI-specified highway projects absorb premium tiers.
Supply Chain Analysis
Single-source vulnerability sits with Gujarat and Maharashtra, which host over two-thirds of formulated admixture capacity and concentrate polymer synthesis expertise around Ahmedabad and Mumbai. Raw material dependencies draw from naphtha-derived ethylene oxide, imported polycarboxylate ether intermediates, and lignosulfonate byproducts from pulp processing. Supply chain risk centers on monsoon logistics disruptions across western India transport corridors. Distribution runs through integrated construction chemical platforms consolidating fragmented tier-two contractor demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India concrete admixtures market functions as a stable compounder, with NHAI continuous paving specifications and smart city mission investments providing durable demand visibility across infrastructure cycles.
For Market Incumbents: Deploy BIS certification pre-registration as a competitive moat. Lock formulation approvals six-to-nine months ahead of twelve-week public works department tender windows to exclude unorganized competitors. Anchor premium positioning through integrated waterproofing-admixture bundling in Gujarat and Maharashtra framework contracts, defending against multinational specialty chemical majors expanding localized manufacturing under the PLI scheme. For New Entrants and Emerging Players: Automated dosing system compatibility offers a technology-first wedge for penetrating Rajasthan and Madhya Pradesh legacy dry-mix facilities requiring retrofit investment. Target north-eastern states—Assam and Meghalaya highway expansion under the Special Accelerated Road Development Programme—before BIS enforcement tightens. Pursue distributor digital integration to consolidate fragmented rural demand into trackable annual contracts. For Investors and Strategic Acquirers: Asymmetric upside sits with domestic mid-market blenders possessing established distributor networks and pending BIS certification portfolios. Five-to-ten year viability hinges on PLI scheme participation compressing import dependence for polycarboxylate ether manufacturing. Monitor state public works department specification updates as the inflection signal for formulation registration demand surges.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Captive feedstock supply insulates margin pools from naphtha-linked petrochemical volatility. |
| BIS Certification Pre-Registration | Six-to-nine month approval cycles lock out unorganized suppliers from institutional tender eligibility. |
| Distributor Digital Platform Integration | Trackable annual contracts consolidate fragmented tier-two contractor procurement in Rajasthan and Madhya Pradesh. |
| Automated Batching Plant Retrofit Partnerships | Liquid admixture precision dosing compatibility opens specification upgrades in legacy dry-mix facilities. |
| North-Eastern State Market Development | First-mover positioning in Assam and Meghalaya before BIS enforcement tightens tender requirements. |
Research Methodology
Bottom-up infrastructure project modeling reconciled against top-down specialty chemicals manufacturing tracking forms the analytical core of this study. Primary interviews with ready-mix plant managers, state public works department procurement officers, construction chemical distributors, and polymer synthesis R&D directors combined with secondary validation from BIS certification registries, customs import data for polycarboxylate ether intermediates, NHAI project sanctioning records, and state highway authority tender documents. Triangulation across these sources anchors volume and value estimates.
Input-output matrices segment the market across product type, application, technology, and end user dimensions throughout the forecast period. CAGRs derive from project pipeline analysis across NHAI expressways, state highway expansions, metro rail corridors, and smart city missions. Forecast inputs incorporate BIS revision cycle timelines, PLI scheme capacity addition schedules, and batching plant automation penetration curves.
The model holds under stable infrastructure investment continuity and petrochemical feedstock availability; deviation in central fiscal consolidation or ethylene oxide supply disruptions would shift trajectory. Forecasts reflect documented assumptions regarding certification enforcement timing and contractor procurement consolidation rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
North America Cement Market
Building Materials
Building and Construction Plastics Market
Building Materials
Asia-Pacific Building and Construction Sheets Market
Building Materials
Block Paving Market
Building Materials
Building Asphalt Market
Building Materials
Global Drywall and Building Plaster Market
Building Materials
Europe Cement Market
Building Materials
Fire Resistant Mortar Market
Building Materials
GRC Cladding Market
Building Materials
East Africa White Cement Market
Building Materials
Construction Materials Market
Building Materials
Global FRP Rebar Market
Building Materials
Global Pozzolan Market
Building Materials
Long Steel Market
Building Materials
East Africa Cement Market
Building Materials
Light Gauge Steel Framing Market