
 Waterproofing Solution Market | 2026-2036
Waterproofing Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Waterproofing Solution Market Insights
Modular waterproofing kits bundling membranes, primers, and sealants into single-SKU configurations is broadening contractor choice and reducing specification complexity. Sika AG leverages its global manufacturing footprint to supply bundled systems across multiple climate zones. BASF SE competes through R&D intensity in polyurethane chemistry for liquid-applied segments. Beijing Oriental Yuhong Waterproof Technology Co., Ltd. anchors its position with deep distribution into China's provincial construction markets.
Waterproofing solutions comprise barrier systems engineered from bituminous compounds, polyurethane resins, cementitious matrices, or synthetic rubber membranes to prevent moisture ingress into building envelopes and civil structures. These systems typically achieve hydrostatic resistance ratings exceeding 70 meters water head and bond to concrete substrates through chemical adhesion or mechanical fastening. Bituminous membrane products dominate volume in foundation protection and roof waterproofing applications due to proven durability and lower material cost. Liquid-applied polyurethane segments capture premium positioning in complex geometries like balcony sealing and swimming pools where seamless coverage eliminates seam failure risks. Cementitious systems sustain demand in bathroom waterproofing and repair maintenance deployments where substrate compatibility and breathability matter most.
REACH and RoHS frameworks in Europe restrict hazardous substance content in membrane formulations, while the EU Green Deal pushes low-VOC and bio-based material substitutions. In the United States, EPA guidelines and state-level stormwater regulations shape product specifications for below-grade applications. China's GB standards and dual carbon goals enforce energy-efficient building envelopes that integrate thermal insulation with moisture barriers. Stakeholders must monitor regulatory divergence between jurisdictions to align product portfolios with compliance timelines and avoid stranded inventory in cross-border projects.
Market Dynamics
Spray-applied polyurethane systems are compressing project timelines by 40-60% versus traditional sheet membranes, forcing contractors to retrain crews and rewrite procurement specifications around cure-speed rather than material cost alone.
Growth Catalysts
- GB Standards Compliance:China's dual carbon goals mandate energy-efficient building envelopes that integrate thermal insulation with moisture barriers, accelerating specification of high-performance systems in coastal megacities.
- Polyurethane Chemistry Advances:Faster curing cycles enable single-day waterproofing of complex geometries like podium decks and green roofs, reducing labor mobilization costs for commercial contractors.
- Flood Risk Intensification:China's Ministry of Emergency Management reports escalating coastal flooding exposure in Shanghai, Shenzhen, and Guangzhou, driving mandatory below-grade protection in new high-rise developments.
Market Restraints
- MDI Price Volatility:Methylene diphenyl diisocyanate feedstock costs swing with crude oil and benzene indices, compressing margins for liquid-applied polyurethane formulators during upstream spikes.
- REACH Registration Burden:ECHA's substance evaluation timelines extend 18-24 months for novel polymer additives, delaying European commercialization of bio-based membrane innovations.
- Cementitious Substitution:Crystalline waterproofing admixtures eliminate secondary membrane application in below-grade concrete, threatening bituminous sheet volumes in foundation specifications.
Strategic Opportunities
- India's Smart Cities Mission:Underground metro expansion and coastal infrastructure in Mumbai and Chennai create specification windows for hydrostatic-resistant systems exceeding 70-meter ratings.
- EU Green Deal Tailwinds:Low-VOC and bio-based material substitutions unlock premium positioning as member states transpose EU Green Deal targets into national building codes by 2027.
- Drone-Assisted Inspection:Automated membrane integrity testing reduces warranty claim disputes and enables predictive maintenance contracts for commercial roofing portfolios.
Industry Challenges
- Certified Applicator Scarcity:Spray polyurethane foam demands specialized respiratory protection training and equipment certification, constraining crew scalability during peak construction seasons.
- Multi-System Integration:Specifiers must reconcile thermal insulation, vapor control layers, and waterproofing membranes from different manufacturers, creating liability gaps at material interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waterproofing Solution Market |
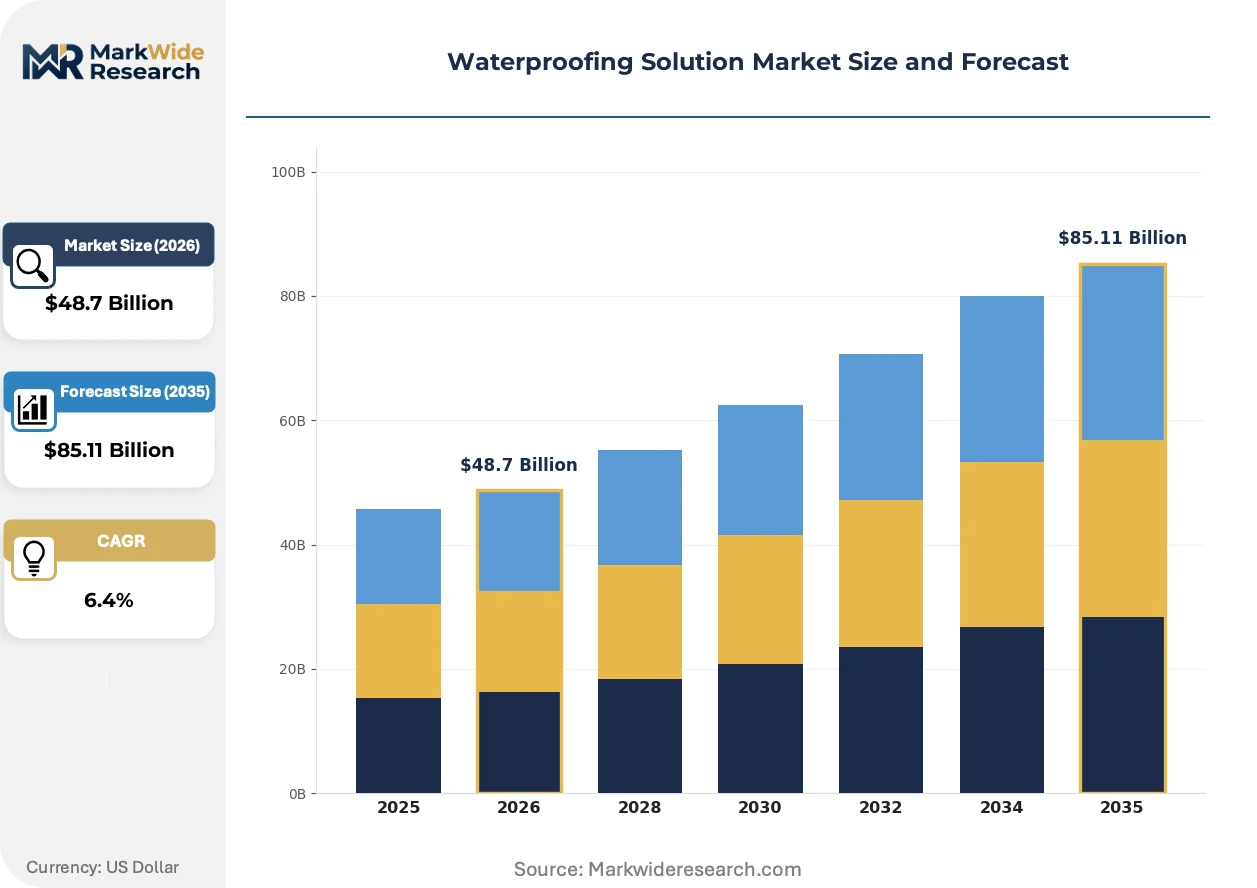
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $85.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Bituminous Membrane, Cementitious, Liquid Applied, Acrylic, EPDM Application: Foundation Protection, Roof Waterproofing, Bathroom Waterproofing, Tunnel Lining, Balcony Sealing, Swimming Pools End User: Construction Contractors, Infrastructure Developers, Commercial Complexes, Residential Builders, Industrial Facilities, Facility Managers Deployment: New Construction, Renovation Projects, Repair and Maintenance, Retrofitting, Green Building Projects, Waterproofing Upgrades |
| Companies Covered | Sika AG, Soprema Group, RPM International Inc., Saint-Gobain, Carlisle Companies Inc., Beijing Oriental Yuhong Waterproof Technology Co., Ltd., Tremco Incorporated, BASF SE, MAPEI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waterproofing Solution Market Trends and Innovations
Digital specification tools and material traceability platforms are reshaping how contractors validate membrane performance claims and manage warranty documentation across multi-phase developments.
Spray-applied polyurethane membrane technology is overtaking torch-applied bituminous sheets in commercial roofing and podium waterproofing. Large-scale contractors in China's tier-one cities now specify seamless liquid systems for 60% of new high-rise projects. This transition is compressing demand for conventional roll-goods distributors and rewiring procurement relationships toward direct manufacturer-to-contractor supply.
REACH and RoHS frameworks in Europe now restrict hazardous substance content in membrane formulations while the EU Green Deal pushes low-VOC substitutions. Formulators face reformulation costs of 12-18 months to secure ECHA registration for novel bio-based polymer alternatives. Liquid-applied segments in Germany and France absorb the steepest compliance burdens as specifiers preempt 2027 enforcement windows.
General contractors now bundle waterproofing, insulation, and cladding procurement into single-source design-build contracts rather than fragmented trade packages. This consolidation bypasses traditional distributor networks and forces membrane manufacturers to certify directly under EPD and ISO 14025 environmental declarations. The shift is most visible in China's state-owned developer segment, where centralized procurement platforms aggregate material specifications across provincial project pipelines.
Waterproofing Solution Market Segmentation
Waterproofing specification hinges on substrate compatibility, hydrostatic pressure ratings, and cure-cycle constraints that vary dramatically across building envelope applications. Contractors weigh material cost against labor mobilization and warranty risk when selecting systems for specific project phases.
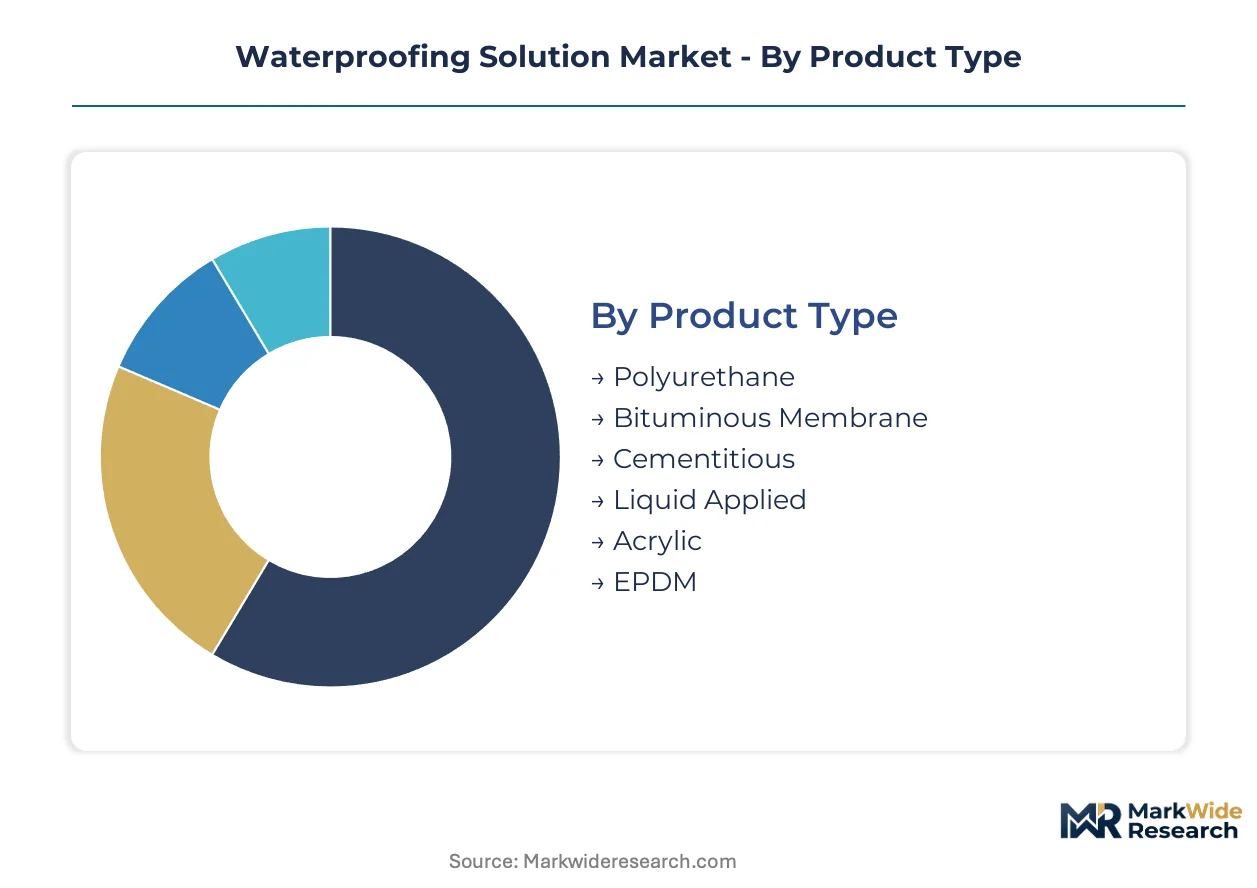
Product Type:
Material chemistry dictates application method, cure speed, and seam integrity — the three variables that dominate contractor procurement decisions.
- Polyurethane:Liquid-applied systems cure into seamless elastomeric membranes bonding chemically to concrete. Demand concentrates in China's coastal megacities where podium decks and green roofs require single-day waterproofing turnaround.
- Bituminous Membrane:Torch-applied or self-adhesive sheets of modified asphalt dominate foundation protection due to proven 30-year durability and lower material cost per square meter.
- Cementitious:Crystalline and polymer-modified cement slurries penetrate concrete pores for breathable, repair-friendly protection in bathroom and maintenance applications.
- Liquid Applied:Cold-applied coatings eliminate torch hazards and suit complex geometries where sheet membranes fail at seams and penetrations.
- Acrylic:Water-based elastomeric coatings serve exposed roof restoration with UV resistance and vapor permeability for metal and concrete substrates.
- EPDM:Synthetic rubber sheets deliver extreme weather durability for large commercial roofing where mechanical fastening suits prefabricated panel construction.
Bituminous membrane leads on scale; polyurethane leads on momentum.
Application:
Hydrostatic pressure exposure and accessibility constraints segment waterproofing demand by structural location.
- Foundation Protection:Below-grade membranes must resist 70+ meter water head in waterlogged soils. Shanghai and Shenzhen developers now mandate dual-layer systems amid intensifying flood risk.
- Roof Waterproofing:Commercial high-rises drive specification of spray polyurethane and TPO membranes where wind uplift ratings and thermal cycling resistance matter most.
- Bathroom Waterproofing:Cementitious systems dominate residential wet areas where tile adhesion and breathability prevent mold accumulation behind finishes.
- Tunnel Lining:Pre-applied bonded membranes and spray concrete linings protect subway and utility tunnels from groundwater ingress in Mumbai and Chennai metro expansions.
- Balcony Sealing:Liquid polyurethane captures complex detailing at railings and drains where sheet membranes risk seam failure.
- Swimming Pools:Chlorine-resistant epoxy and polyurethane coatings deliver seamless protection against constant immersion and chemical attack.
Foundation protection anchors volume; roof waterproofing climbs the fastest as commercial construction accelerates.
End User:
Procurement sophistication and warranty liability tolerance separate buyer segments.
- Construction Contractors:General contractors bundle waterproofing into design-build packages, bypassing distributors for direct manufacturer relationships that compress material cost and standardize crew certification.
- Infrastructure Developers:State-owned developers in China aggregate specifications across provincial pipelines through centralized procurement platforms demanding EPD and ISO 14025 environmental declarations.
- Commercial Complexes:Mall and office owners prioritize predictive maintenance contracts enabled by drone-assisted membrane integrity testing.
- Residential Builders:Volume homebuilders specify cost-optimized bituminous sheets and cementitious systems through distributor networks.
- Industrial Facilities:Chemical plants and data centers demand specialized chemical-resistant and fire-rated systems with extensive substrate preparation protocols.
- Facility Managers:Portfolio operators seek extended warranty terms and material traceability platforms to manage multi-phase maintenance documentation.
Infrastructure developers command the largest contract values; facility managers represent the steepest expansion trajectory as predictive maintenance contracts proliferate.
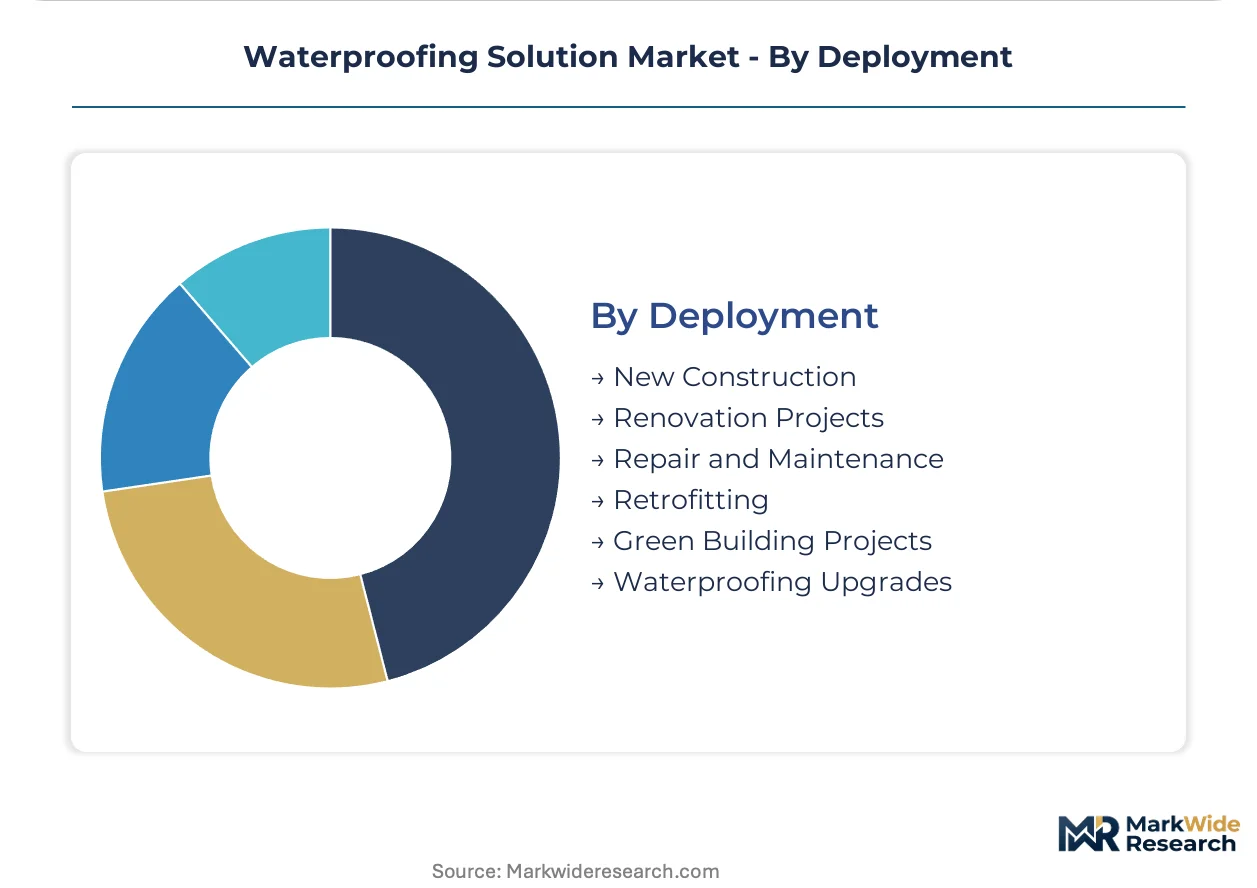
Deployment:
Project lifecycle stage determines specification flexibility and integration complexity with adjacent building systems.
- New Construction:Integrated design allows membrane specification concurrent with thermal insulation and vapor control layers, reducing interface liability gaps.
- Renovation Projects:Existing substrate conditions constrain material choice toward breathable cementitious repairs and surface-tolerant liquid coatings.
- Repair and Maintenance:Localized failures demand rapid-cure polyurethane patches and crystalline admixtures that penetrate compromised concrete.
- Retrofitting:Aging building stock in Europe drives demand for overlay membranes compatible with existing bituminous substrates under EU Green Deal renovation targets.
- Green Building Projects:Low-VOC and bio-based formulations secure specification under tightening national building codes transposing EU Green Deal requirements.
- Waterproofing Upgrades:Flood resilience mandates in China's coastal cities accelerate below-grade system replacements in existing high-rise developments.
New construction dominates absolute volume; green building projects gain share fastest as regulatory compliance windows tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Waterproofing chemistry first achieved industrial scale in Germany's Ruhr Valley during post-war reconstruction, then migrated to US commercial roofing markets in the 1960s. China's coastal megacities now drive the largest absolute consumption volumes as flood resilience mandates reshape construction codes. Regulatory divergence between REACH-controlled European markets and China's GB standard system creates distinct competitive arenas for membrane formulators.
China
Shanghai, Shenzhen, and Guangzhou developers now mandate dual-layer below-grade systems amid intensifying coastal flooding exposure. The Ministry of Emergency Management reports escalating water head risks that accelerate specification of hydrostatic-resistant membranes exceeding 70-meter ratings. Beijing's dual carbon goals enforce energy-efficient building envelopes that integrate thermal insulation with moisture barriers across provincial construction pipelines.
Germany
ECHA's REACH registration timelines extend 18-24 months for novel polymer additives, delaying commercialization of bio-based membrane innovations. Formulators in the Rhine-Ruhr industrial cluster absorb the steepest compliance burdens as specifiers preempt 2027 enforcement windows for low-VOC substitutions. The EU Green Deal pushes liquid-applied segments toward environmental product declarations under ISO 14025 frameworks.
United States
EPA guidelines and state-level stormwater regulations shape below-grade specifications in flood-prone Gulf Coast and Atlantic seaboard markets. Commercial contractors in Texas and Florida retrain crews around spray-applied polyurethane cure-speed rather than material cost alone. The Inflation Reduction Act's building efficiency incentives accelerate membrane-integrated thermal envelope retrofits in existing commercial stock.
India
Mumbai and Chennai metro expansions create specification windows for tunnel lining membranes with hydrostatic resistance exceeding 70-meter water head. The Smart Cities Mission drives underground infrastructure investment that demands pre-applied bonded membrane systems. Central Electricity Authority building codes increasingly reference international waterproofing standards for coastal infrastructure resilience.
Japan
Tokyo's dense urban renewal projects specify seamless liquid-applied systems for podium decks and green roofs where space constraints demand single-day waterproofing turnaround. METI's building energy efficiency standards tighten thermal envelope requirements that integrate vapor control with moisture barriers. Osaka-Kobe industrial corridor manufacturers supply polyurethane chemistry to regional contractors seeking faster curing cycles.
Waterproofing Solution Market Competitive Landscape
The competitive structure tilts toward diversified chemical conglomerates with global manufacturing footprints rather than regional membrane specialists. Market position clusters around three archetypes: integrated construction chemical suppliers bundling waterproofing with adhesives and sealants; pure-play roofing system manufacturers with dedicated applicator certification networks; and emerging Asia-Pacific formulators leveraging domestic feedstock access. Dominant competitive moves include backward integration into polymer resin production and direct-to-contractor supply relationships that bypass traditional distributor networks.
Among diversified chemical conglomerates, Sika AG and BASF SE exemplify the integrated supplier archetype with broad construction chemical portfolios. Beijing Oriental Yuhong Waterproof Technology Co., Ltd. occupies a position within the Asia-Pacific specialist tier, anchoring regional distribution depth into China's provincial construction markets. These three represent distinct strategic postures: global bundling capability, polyurethane chemistry R&D intensity, and domestic market penetration density respectively.
| Leading Market Players |
|---|
| Sika AG |
| Soprema Group |
| RPM International Inc. |
| Saint-Gobain |
| Carlisle Companies Inc. |
| Beijing Oriental Yuhong Waterproof Technology Co., Ltd. |
| Tremco Incorporated |
| BASF SE |
| MAPEI |
| Others |
Pricing and Supply Chain Analysis
Backward integration into MDI and polyol resin production anchors pricing power for liquid-applied polyurethane formulators while cementitious competitors source commodity cement and crystalline admixtures through spot markets. This upstream control separates margin-stable specialty suppliers from raw-material-exposed sheet membrane distributors serving China's provincial construction markets.
Pricing Analysis
Project-based contract pricing dominates waterproofing procurement, with three-tier pricing structure across premium, standard, and economy levels separating spray polyurethane systems from torch-applied bituminous sheets and cementitious repair slurries. Price differentiation hinges on hydrostatic resistance certification grade and applicator crew certification level. Cost compression in economy bituminous tiers is intensifying because crystalline admixtures eliminate secondary membrane application in below-grade concrete. Residential builders through distributor networks exhibit highest price sensitivity; infrastructure developers aggregating provincial pipelines through centralized platforms prioritize performance ratings over unit cost.
Supply Chain Analysis
Freight cost volatility from Middle East benzene derivatives and Asian MDI production clusters compresses margins for European formulators sourcing feedstock across maritime routes. Manufacturing concentrates in China, Germany, and the United States, with polyurethane chemistry anchored in the Rhine-Ruhr industrial corridor and Asia-Pacific coastal megacities. Raw material dependencies rest on methylene diphenyl diisocyanate, polyether polyols, and modified bitumen resins. Single-source vulnerability from Saudi Arabian and Korean benzene suppliers creates feedstock disruption risk. Distribution runs through direct manufacturer-to-contractor relationships that bypass traditional roll-goods distributors in China's tier-one cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between REACH-burdened European formulators facing 18-24 month ECHA registration timelines and Asia-Pacific competitors with faster GB standard compliance cycles and domestic feedstock access.
For Market Incumbents: Hedge MDI price exposure through captive resin production or long-term offtake agreements with Saudi and Korean benzene suppliers. Cementitious crystalline admixtures threaten bituminous sheet volumes in foundation specifications; incumbents must accelerate spray polyurethane applicator certification networks to lock in contractor loyalty before cure-speed advantages erode.
For New Entrants and Emerging Players: Drone-assisted inspection service providers represent the most penetrable channel partner type for predictive maintenance contract bundling. White-space targets include India's Smart Cities Mission underground metro specifications and EU Green Deal low-VOC formulation gaps ahead of 2027 enforcement windows. A certification-first go-to-market angle targeting state-owned developer procurement platforms bypasses entrenched distributor relationships.
For Investors and Strategic Acquirers: Roll-up economics work for regional applicator certification networks because crew scarcity constrains spray polyurethane scalability during peak construction seasons. Mid-cap specialists with captive MDI supply and established EPD declarations under ISO 14025 frameworks offer viable acquisition profiles. Watch crystalline waterproofing admixture penetration rates in Chinese foundation specifications as the inflection signal for bituminous sheet demand erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MDI Resin Production | Captive benzene derivative supply insulates margins from crude oil index volatility. |
| Applicator Certification Network Expansion | Specialized respiratory training scarcity constrains spray polyurethane crew scalability. |
| Low-VOC Formulation Repositioning | ECHA REACH registration timelines favor early movers ahead of EU Green Deal enforcement. |
| Drone-Assisted Inspection Service Launch | Predictive maintenance contracts reduce warranty claim disputes for commercial roofing portfolios. |
| Direct-to-Contractor Supply Restructuring | Centralized procurement platforms in China's state-owned developer segment bypass distributor networks. |
Research Methodology
Bottom-up construction contractor modeling reconciled against top-down chemical feedstock tracking forms the analytical core of this study. Primary interviews with waterproofing specification engineers, commercial roofing contractors, EPC procurement leads, and state-owned developer platform managers combined with secondary validation from customs trade data, ECHA REACH registration databases, China GB standard filings, and SEC construction chemical segment disclosures. Triangulation across these sources ensures supply-side capacity estimates align with end-use demand signals.
Historical trendline analysis of spray polyurethane versus bituminous membrane adoption rates established baseline growth trajectories across the projection horizon. The analytical framework models demand by product chemistry, application substrate, end-user procurement sophistication, and deployment lifecycle stage. CAGRs derive from regression analysis of construction output indices correlated with waterproofing intensity per square meter of building envelope. Feedstock cost indices and regulatory compliance timeline assumptions inform margin compression scenarios.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MDI price volatility, REACH registration delays for bio-based polymers, and flood resilience mandate acceleration in China's coastal megacities. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Sheet Piling Market
Building & Construction Materials
Warm Mix Asphalt Market
Building & Construction Materials
Steel Wire Rope Products Market
Building & Construction Materials
Africa Vinyl Windows Market
Building & Construction Materials
Remodeling Market
Building & Construction Materials
Global Concrete Block and Brick Manufacturing Market
Building & Construction Materials
Sawn Timber Market
Building & Construction Materials
Insulated Concrete Form (ICF) Market
Building & Construction Materials
Slimline Aluminum Window System Market
Building & Construction Materials
Saudi Arabia Tiles Market
Building & Construction Materials
Roofing Shingles Market
Building & Construction Materials
Concrete Conditioner Market
Building & Construction Materials
Bollard Market
Building & Construction Materials
Urethane Concrete Sealer Market
Building & Construction Materials
Mechanically Fastened Cross-Laminated Timber Market
Building & Construction Materials
Railing Market