
 Fly Ash Bricks Market | 2026-2036
Fly Ash Bricks Market Size, Share, and Industry Trends Forecast 2026-2036
Fly Ash Bricks Market Analysis
Aftermarket technical consulting for masonry specification is tilting toward producers with captive fly ash sourcing. Heidelberg Materials leverages integrated power plant partnerships across multiple continents to secure feedstock consistency. UltraTech Cement anchors South Asian demand through dense distribution networks reaching tier-2 and tier-3 construction markets. Charah Solutions specializes in beneficiated ash processing that commands specification-grade premiums from infrastructure contractors.
Fly ash bricks are compressed masonry units manufactured from pulverized fuel ash blended with lime, gypsum, and sand, typically achieving compressive strengths between 75 and 150 kg/cm² through steam-curing or ambient curing processes; they serve as load-bearing and non-load-bearing walling alternatives to fired clay bricks in structural applications. Solid bricks dominate residential construction volumes where familiarity among masons sustains specification inertia, while hollow bricks capture commercial and industrial projects seeking thermal insulation compliance and reduced structural dead loads. Infrastructure development applications represent the fastest-expanding segment as government procurement mandates increasingly embed embodied carbon thresholds favoring recycled industrial byproducts.
The US EPA regulates coal ash disposal under Subtitle D of the Resource Conservation and Recovery Act, while India's BIS enforces IS 12894 and IS 13757 standards for brick dimensional tolerance and compressive performance; China's GB standards and MEE circular economy directives similarly constrain ash landfill diversion toward construction material valorization. These regulatory architectures create dual pressure on power generators to monetize ash streams and on builders to document sustainable material sourcing. Stakeholders must monitor evolving carbon accounting protocols that could recategorize fly ash bricks from waste-derived products to primary building materials with altered certification obligations.
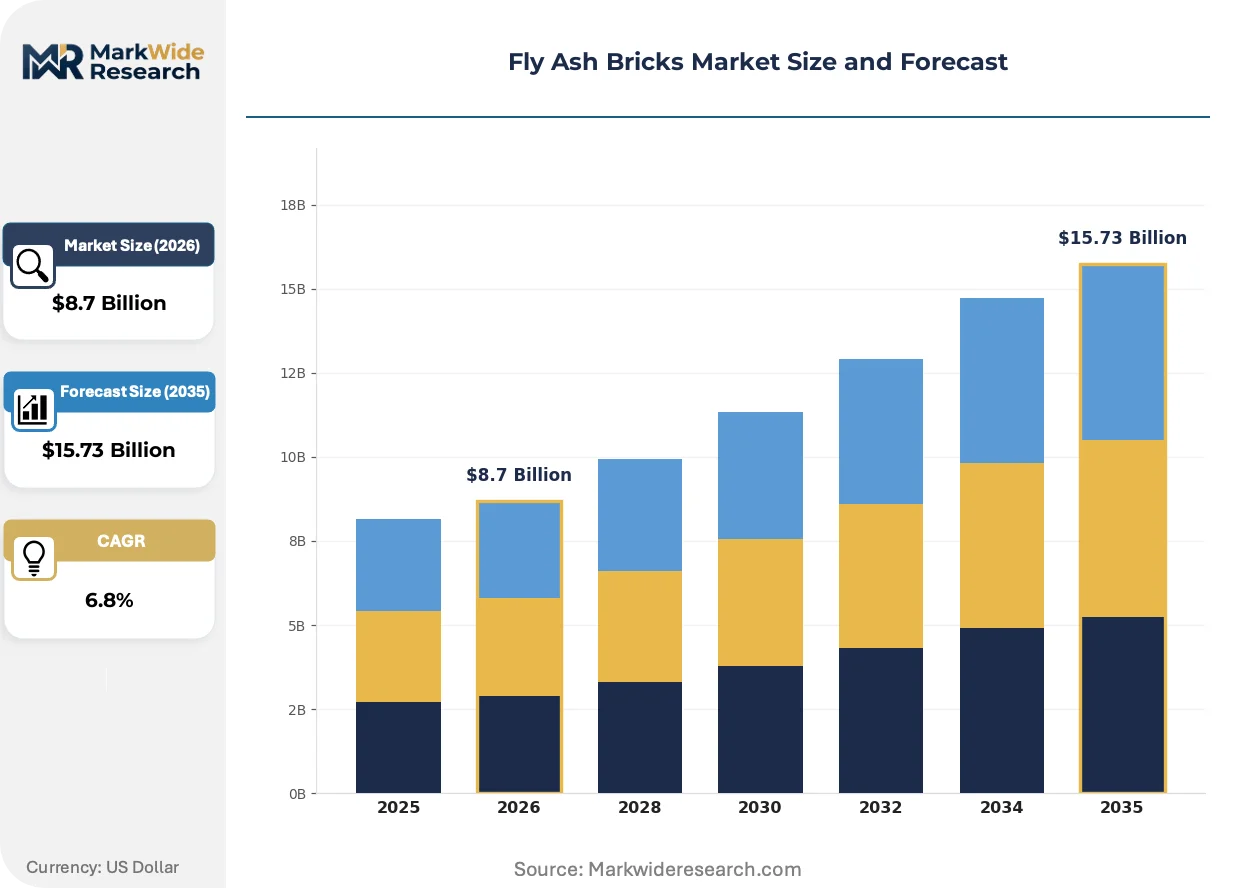
Market Dynamics
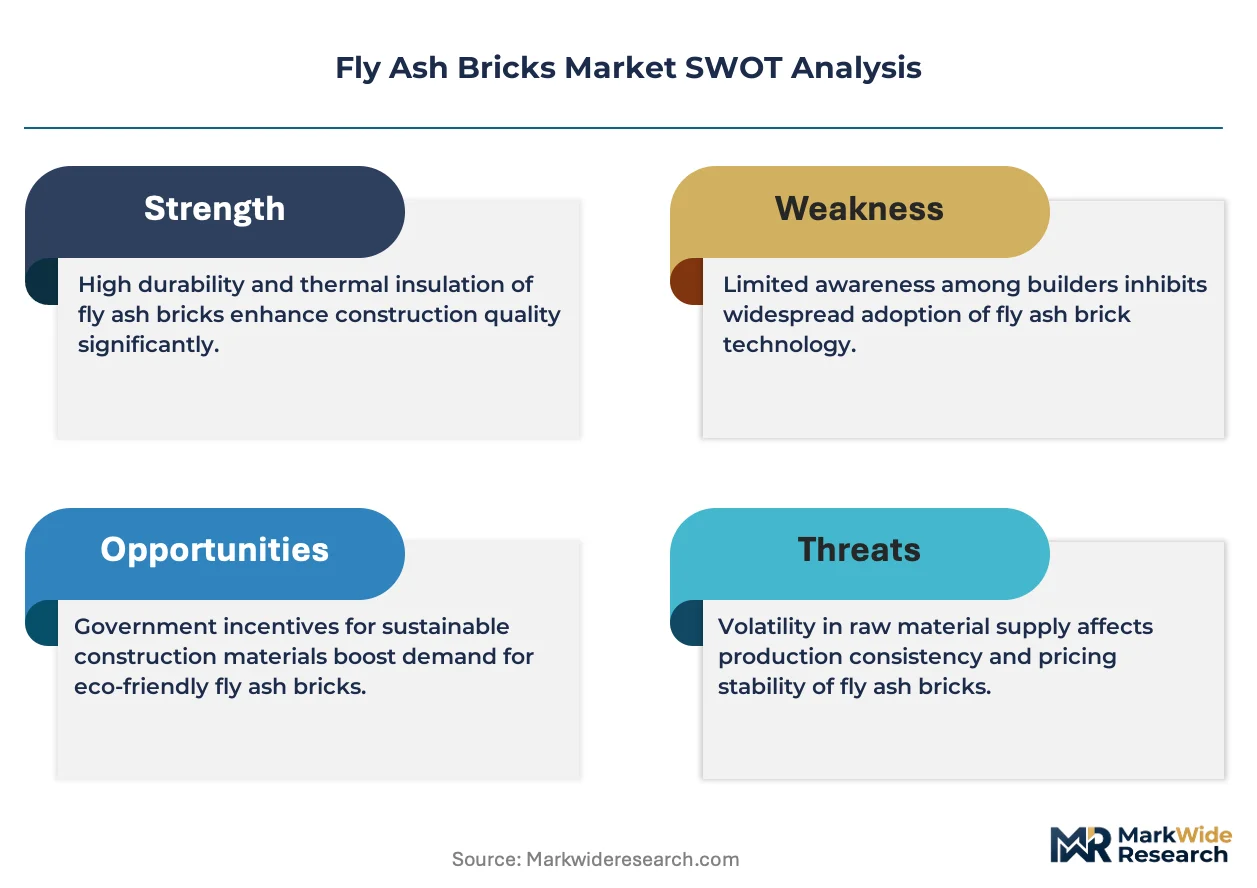
Coal plant retirement timelines are compressing fly ash availability windows, forcing brick manufacturers to lock in long-term sourcing contracts before feedstock scarcity reshapes production economics.
Growth Catalysts
- Infrastructure procurement mandates:India's Ministry of Road Transport and Highways mandates fly ash utilization in highway embankments and pavement construction, creating guaranteed offtake for specification-grade brick producers.
- IS 12894 certification expansion:India's BIS enforcement of dimensional tolerance and compressive strength standards is formalizing informal brick kilns into compliant manufacturing operations.
- Steam-curing process refinement:Automated curing chambers reduce ambient curing cycles from 28 days to 24 hours, enabling inventory turnover velocity that clay brick producers cannot match.
Market Restraints
- Coal ash supply concentration:India's northern and western states control over 70% of domestic thermal power generation, leaving eastern and southern manufacturers dependent on rail-borne ash with freight cost volatility.
- Fired clay brick substitution inertia:Rural masons in Uttar Pradesh and Bihar retain specification preference for traditional clay units due to established compressive strength familiarity and repair compatibility.
- Moisture absorption rate limitations:Unsealed fly ash bricks exhibit 10-15% water absorption versus 8-12% for fired clay, restricting specification in coastal Maharashtra and Kerala where monsoon exposure is severe.
Strategic Opportunities
- Tier-3 construction market penetration:India's tier-3 cities in Madhya Pradesh and Chhattisgarh lack organized brick distribution, creating first-mover advantage for producers establishing direct-to-contractor logistics.
- Hollow brick thermal compliance:Commercial real estate developers in Bangalore and Hyderabad are specifying hollow fly ash units to meet Energy Conservation Building Code insulation requirements.
- Beneficiated ash processing premiums:Charah Solutions-style ash beneficiation technology enables carbon removal and particle size grading, commanding specification-grade premiums from infrastructure contractors.
Industry Challenges
- Mason skill retraining requirements:Traditional clay brick laying techniques require modification for fly ash unit mortar consistency and curing sensitivity, creating workforce transition friction in Rajasthan and Gujarat construction markets.
- IS 12894 testing facility scarcity:BIS-authorized laboratories concentrate in Delhi, Mumbai, and Chennai, forcing regional producers to ship samples across state lines with 3-4 week certification delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fly Ash Bricks Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Bricks, Hollow Bricks, Perforated Bricks, Composite Bricks Application: Residential Construction, Commercial Construction, Industrial Projects, Infrastructure Development Distribution Channel: Direct Sales, Online Retail, Wholesalers, Specialty Stores End User: Contractors, Builders, Architects, Homeowners |
| Companies Covered | Heidelberg Materials, Boral, UltraTech Cement, Laxmi Enterprises, Charah Solutions, ACC, Cemex, Milestone Bricks, Holcim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fly Ash Bricks Market Emerging Trajectories
Fly ash brick production is pivoting from waste valorization to engineered material science, with curing automation and ash beneficiation compressing quality variance that once limited specification to non-structural applications.
High-pressure steam-curing technology is hybridizing traditional ambient curing with thermally accelerated strength development. Commercial contractors in Pune and Ahmedabad are specifying steam-cured units for mid-rise residential frames where 28-day ambient curing delays project schedules. This hybridization is compressing the competitive gap between fly ash and autoclaved aerated concrete in load-bearing wall applications.
India's BIS is tightening IS 13757 dimensional tolerance enforcement for hollow fly ash bricks, disqualifying kiln-molded producers who cannot achieve ±3mm length consistency. The industrial consequence is accelerated capital expenditure on hydraulic presses among mid-scale manufacturers. Commercial developers in the National Capital Region are responding by embedding BIS certification requirements directly into tender documents, bypassing contractor discretion.
Specification-grade procurement is consolidating around engineers and architects rather than contractor purchasing officers. Infrastructure project consultants in Mumbai and Delhi are inserting embodied carbon clauses into material schedules, displacing traditional lowest-cost bidding. This pattern is most visible in Maharashtra's metro rail and affordable housing verticals where sustainability documentation is mandatory for government reimbursement.
Fly Ash Bricks Market Segmentation
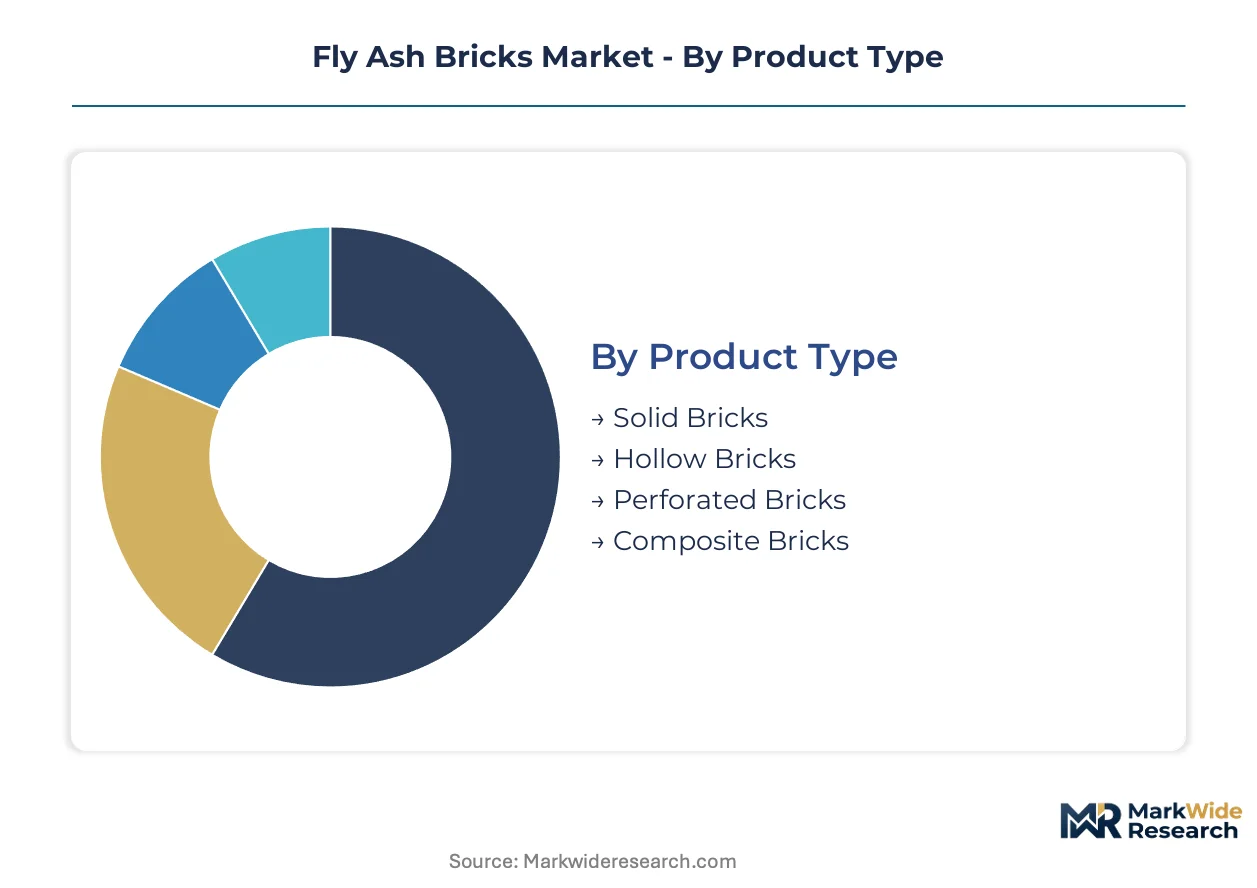
Segmentation in fly ash brick markets reveals how curing cycles, compressive strength requirements, and procurement authority distribution create divergent margin structures across product categories. Manufacturers align production configurations to match inventory velocity against specification complexity in each segment.
Product Type:
Steam-curing cycles compress lead times most dramatically for solid bricks, while hollow and perforated variants demand extended quality assurance timelines due to dimensional tolerance sensitivity.
- Solid Bricks:Dense masonry units manufactured without internal voids, achieving compressive strengths of 75-150 kg/cm² through ambient or accelerated curing. Residential contractors in Uttar Pradesh and Bihar specify solid bricks for load-bearing walls where mason familiarity sustains volume despite higher thermal mass. Inventory turnover reaches 24-48 hours with steam-curing automation.
- Hollow Bricks:Units with engineered voids reducing structural dead load by 25-30% while improving thermal insulation performance. Commercial developers in Bangalore and Hyderabad are embedding hollow fly ash specifications into Energy Conservation Building Code compliance strategies for mid-rise construction. Ambient curing cycles extend to 21-28 days due to wall thickness variance sensitivity.
- Perforated Bricks:Patterned void configurations enabling mortar keying and acoustic dampening in institutional facades.
- Composite Bricks:Hybrid formulations incorporating rice husk ash or slag for enhanced sulfate resistance in coastal Maharashtra applications.
Solid bricks anchor the volume base while hollow bricks gain share at the steepest rate.
Application:
Project scale and procurement documentation intensity separate segments by margin tier, with infrastructure mandates commanding specification-grade premiums against residential commodity pricing.
- Residential Construction:Single-family and multi-family housing projects where contractor purchasing officers prioritize unit cost over embodied carbon documentation. Mason specification inertia in northern Indian states sustains solid brick dominance despite hollow brick thermal advantages. Payment cycles and inventory requirements favor producers with distributed kiln networks.
- Infrastructure Development:Highway embankments, metro rail, and government affordable housing where India's Ministry of Road Transport and Highways mandates fly ash utilization. Engineers and architects control material schedules, inserting BIS certification and carbon accounting clauses that disqualify informal kiln producers. This segment commands the widest premium-to-commodity price spreads.
- Commercial Construction:Office and retail developments in National Capital Region and Mumbai where developer sustainability targets drive specification.
- Industrial Projects:Factory construction and warehousing in Gujarat and Tamil Nadu seeking rapid enclosure with reduced structural loads.
Residential construction absorbs the highest absolute volumes while infrastructure development expands most quickly.
Distribution Channel:
Channel selection correlates with customer technical sophistication, with direct sales capturing complex specification work and wholesalers moving commodity residential volumes.
- Direct Sales:Producer-to-contractor relationships for infrastructure and commercial projects requiring IS 12894 certification documentation and batch testing. Heidelberg Materials and UltraTech Cement leverage field engineering teams to secure multi-year supply agreements with metro rail and highway authorities. Channel margins compress freight costs through dedicated logistics contracts.
- Wholesalers:Regional distributors aggregating small-contractor demand across tier-2 and tier-3 construction markets in Madhya Pradesh and Chhattisgarh. Inventory pooling reduces working capital requirements for mid-scale manufacturers lacking captive distribution. Price discovery remains opaque with quality variance across supplier bases.
- Online Retail:Emerging platform-based procurement for renovation and small-scale residential projects in urban clusters.
- Specialty Stores:Urban outlets serving architect-specified restoration and premium facade applications.
Direct sales dominate value capture while wholesalers handle the greatest transaction volumes.
End User:
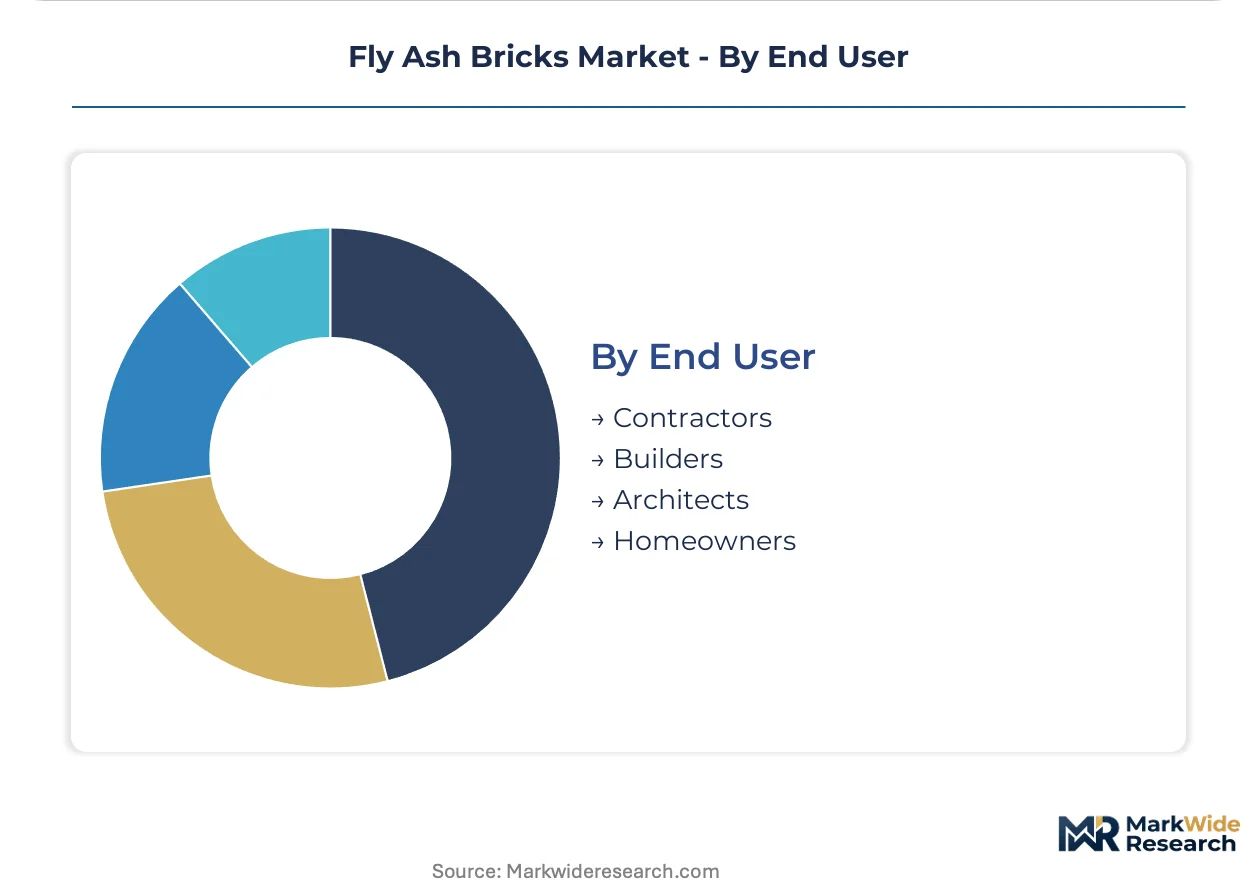
Technical authority concentration determines specification control, with architects and engineers displacing contractor purchasing officers in complex projects.
- Contractors:Execution-focused buyers prioritizing delivery reliability and mason acceptance over material innovation. Established relationships with local kiln operators create switching costs for fly ash alternatives in Rajasthan and Gujarat markets. Payment terms and credit availability heavily influence supplier selection.
- Architects:Design professionals embedding BIS certification and embodied carbon thresholds into tender documents for Maharashtra metro rail and affordable housing verticals. Specification authority consolidates around sustainability documentation requirements for government reimbursement eligibility. This user category drives premium pricing for beneficiated ash products.
- Builders:Developer-integrators balancing cost control with schedule certainty across multi-project portfolios.
- Homeowners:Fragmented retail demand for renovation and self-build construction with limited technical specification input.
Contractors retain volume leadership while architects reshape specification trajectories fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive residential contractors in rural India resist fly ash premiums, while infrastructure engineers in Germany and the UAE accept specification-grade costs for carbon-compliant documentation.
India
India's northern and western states host 70% of thermal power generation, ensuring captive fly ash feedstock for brick manufacturers. BIS mandates IS 12894 certification for highway embankment projects, formalizing informal kiln operations. Delhi-NCR contractors embed BIS requirements directly into metro rail tender documents, bypassing contractor discretion.
United States
US infrastructure contractors seek beneficiated ash products for LEED-compliant federal projects. EPA Subtitle D regulations under RCRA pressure coal plant operators toward construction material valorization. Charah Solutions processes specification-grade ash in the Ohio River Valley, supplying Midwestern highway authorities.
Germany
German commercial developers specify hollow fly ash units for EnEV thermal insulation compliance in mid-rise construction. EU Green Deal embodied carbon thresholds recategorize waste-derived bricks toward primary material status. Heidelberg Materials leverages integrated power plant partnerships across the Rhine-Ruhr industrial corridor.
China
China's GB standards and MEE circular economy directives mandate ash landfill diversion toward construction applications. Dual carbon goals accelerate steam-curing automation in the Yangtze River Delta. Shanghai infrastructure contractors document sustainable sourcing for state-owned enterprise procurement.
United Arab Emirates
UAE megaproject developers specify fly ash bricks for embodied carbon reduction in NEOM and Dubai South developments. MOHAP-adjacent building codes increasingly reference industrial byproduct utilization. Abu Dhabi contractors import beneficiated ash products to meet specification-grade premiums for government reimbursement eligibility.
Fly Ash Bricks Market Vendor Landscape
Capability concentration sits with beneficiated ash specialists; scale advantage sits with integrated cement conglomerates. The vendor base organizes around three strategic archetypes: captive feedstock operators, distributed kiln networks, and ash processing specialists. Consolidation pressure intensifies as coal plant retirements compress raw material availability windows. Dominant competitive moves include long-term power plant sourcing contracts and automated curing chamber deployment.
Among integrated materials conglomerates, Heidelberg Materials and UltraTech Cement exemplify captive feedstock strategies through power plant partnerships spanning multiple continents. Charah Solutions occupies the beneficiation specialist tier, commanding specification-grade premiums through carbon removal and particle size grading technology. These three anchors represent divergent paths to margin defense—vertical control over ash streams versus processing value-add—amid tightening feedstock economics.
| Leading Market Players |
|---|
| Heidelberg Materials |
| Boral |
| UltraTech Cement |
| Laxmi Enterprises |
| Charah Solutions |
| ACC |
| Cemex |
| Milestone Bricks |
| Holcim |
| Others |
Supply Flow & Price Mechanics
Coal plant retirement timelines compressing feedstock availability windows determine both pricing tier spreads and supply chain shape, forcing manufacturers to lock in long-term sourcing contracts before scarcity premiums reshape production economics across northern and western Indian states.
Pricing Analysis
After-sales technical consulting and IS 12894 certification documentation drive lifetime value beyond unit transactions. Three-tier pricing structure across premium, standard, and economy levels separates beneficiated ash products from commodity kiln output and informal producer volumes. Cost compression in economy tiers intensifies because rail-borne ash dependency in eastern and southern India injects freight volatility into landed costs. Residential contractors in Uttar Pradesh and Bihar exhibit highest price sensitivity, while infrastructure engineers in Maharashtra and Delhi-NCR accept specification-grade premiums for carbon-compliant documentation.
Supply Chain Analysis
Tariff exposure between Indian states with divergent freight cost structures dominates supply chain risk assessment for eastern and southern manufacturers dependent on rail-borne feedstock. Production gravity centers on India, China, and Germany, with beneficiated ash processing capabilities concentrating in the US Midwest and Rhine-Ruhr corridor. Raw material dependencies rest on pulverized fuel ash from thermal power generation, lime and gypsum binders, and sand aggregates. Distribution runs through direct sales channels for infrastructure projects requiring certification documentation, while wholesalers aggregate fragmented residential demand across tier-2 and tier-3 construction markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical consulting and certification documentation services attach faster than brick unit sales, as infrastructure contractors seek specification-grade support for BIS compliance and embodied carbon accounting.
For Market Incumbents: Insulate feedstock security through captive power plant partnerships before coal plant retirements compress availability windows. Backward integration into beneficiated ash processing technology defends margin position against Charah Solutions-style specialists commanding specification-grade premiums. Automated curing chamber deployment in Madhya Pradesh and Chhattisgarh locks in tier-3 market penetration ahead of organized distribution establishment. For New Entrants and Emerging Players: Tier-3 cities in Chhattisgarh and Madhya Pradesh present the most penetrable white-space opportunity, lacking organized brick distribution and IS 12894-certified producers. Hollow brick thermal compliance targeting Bangalore and Hyderabad commercial developers offers specification-grade entry with Energy Conservation Building Code alignment. Direct-to-contractor logistics partnerships bypass incumbent wholesaler networks entrenched in commodity residential segments. For Investors and Strategic Acquirers: The market sits at a feedstock consolidation phase that favors beneficiated ash processing specialists with technology differentiation over undifferentiated kiln operators. Long-term viability over the next decade hinges on securing captive ash streams ahead of power plant retirement waves. The signal to watch is BIS laboratory authorization expansion beyond Delhi, Mumbai, and Chennai, indicating regulatory capacity for formalization acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Power Plant Partnership | Heidelberg Materials-style integration secures feedstock consistency ahead of scarcity premiums. |
| Automated Steam-Curing Deployment | 24-hour curing cycles compress inventory turnover velocity that ambient curing cannot match. |
| IS 12894 Certification Investment | BIS compliance unlocks infrastructure procurement mandates from India's Ministry of Road Transport. |
| Beneficiated Ash Processing Technology | Carbon removal and particle grading command specification-grade premiums from metro rail contractors. |
| Tier-3 Distribution Network Buildout | Direct-to-contractor logistics in Madhya Pradesh captures first-mover advantage in unorganized markets. |
Methodological Framework
Cross-validation between regulatory filing analysis and plant-level production data anchors the qualitative findings in this study. Primary interviews with brick manufacturing plant managers, infrastructure procurement engineers at India's Ministry of Road Transport and Highways, BIS certification laboratory directors, thermal power plant ash handling officers, and commercial real estate developers in Bangalore and Hyderabad combined with secondary validation from BIS standards documentation, EPA Subtitle D regulatory filings, customs and trade flow data, and cement conglomerate SEC disclosures. Bottom-up production capacity modeling and top-down infrastructure spend allocation triangulate volume estimates.
Calibration against historical IS 12894 certification expansion rates and coal plant retirement announcements validates projection assumptions across the analysis window. Segmentation dimensions modeled include product type (solid, hollow, perforated, composite), application (residential, infrastructure, commercial, industrial), distribution channel (direct sales, wholesalers, online retail, specialty stores), and end user (contractors, architects, builders, homeowners). CAGRs derive from regression against thermal power generation forecasts and infrastructure procurement mandate intensity. Steam-curing automation penetration rates and beneficiated ash processing capacity expansion serve as industry-specific forecast inputs.
Practitioners should monitor coal plant retirement acceleration, BIS laboratory authorization geographic expansion, and embodied carbon accounting protocol evolution for early signals of forecast revision triggers. Forecasts reflect assumptions about regulatory enforcement continuity and feedstock availability trajectories. Macroeconomic infrastructure spend contraction, regulatory certification requirement relaxation, or breakthrough alternative material substitution would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Africa Aluminum Door and Window Market
Building Materials
LAMEA Engineered Stone Market
Building Materials
North America Engineered Stone Market
Building Materials
Spain Cement Market
Building Materials
Long Steel Market
Building Materials
Building Asphalt Market
Building Materials
Global FRP Rebar Market
Building Materials
Cement Market
Building Materials
Portland Cement Market
Building Materials
United Kingdom Architectural Coatings Market
Building Materials
US Commercial Paving Slabs Market
Building Materials
Sanded Grout Market
Building Materials
Pozzolana Cement Market
Building Materials
Mass Timber Construction Market
Building Materials
Solar Control Window Film Market
Building Materials
Spain Architectural Coatings Market