
 Building Acoustic Insulation Market | 2026-2036
Building Acoustic Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Building Acoustic Insulation Market Intelligence
The shift towards long-term project financing for large-scale commercial and public infrastructure developments is tilting the market toward manufacturers with extensive project management support. Saint-Gobain leverages its vast distribution network to service these complex, multi-stage projects effectively. ROCKWOOL International differentiates through its specialization in non-combustible stone wool solutions, specified for high-performance buildings like hospitals and data centers. Johns Manville competes on its broad portfolio spanning both fiberglass and foam products for varied architectural requirements.
Building acoustic insulation refers to materials engineered to reduce the transmission of airborne and impact sound between building spaces. These products, often specified by their Sound Transmission Class (STC) or Noise Reduction Coefficient (NRC) ratings, function by absorbing, blocking, or dampening acoustic energy. Mineral wool and fiberglass products dominate the market due to their inherent fire resistance and thermal co-benefits. Within applications, the commercial sector represents the largest segment, while the residential retrofitting of home offices represents the fastest-growing niche.
Regulatory frameworks such as the EU's Construction Products Regulation (CPR), which requires CE marking based on performance declarations, set critical market access standards. In the United States, local building codes often reference ASTM International standards for minimum STC ratings in multi-family housing and commercial buildings. Key stakeholders must continually evaluate the trade-off between higher-cost, multi-functional materials that meet stringent fire and acoustic codes versus lower-cost alternatives for less regulated applications.
Market Dynamics
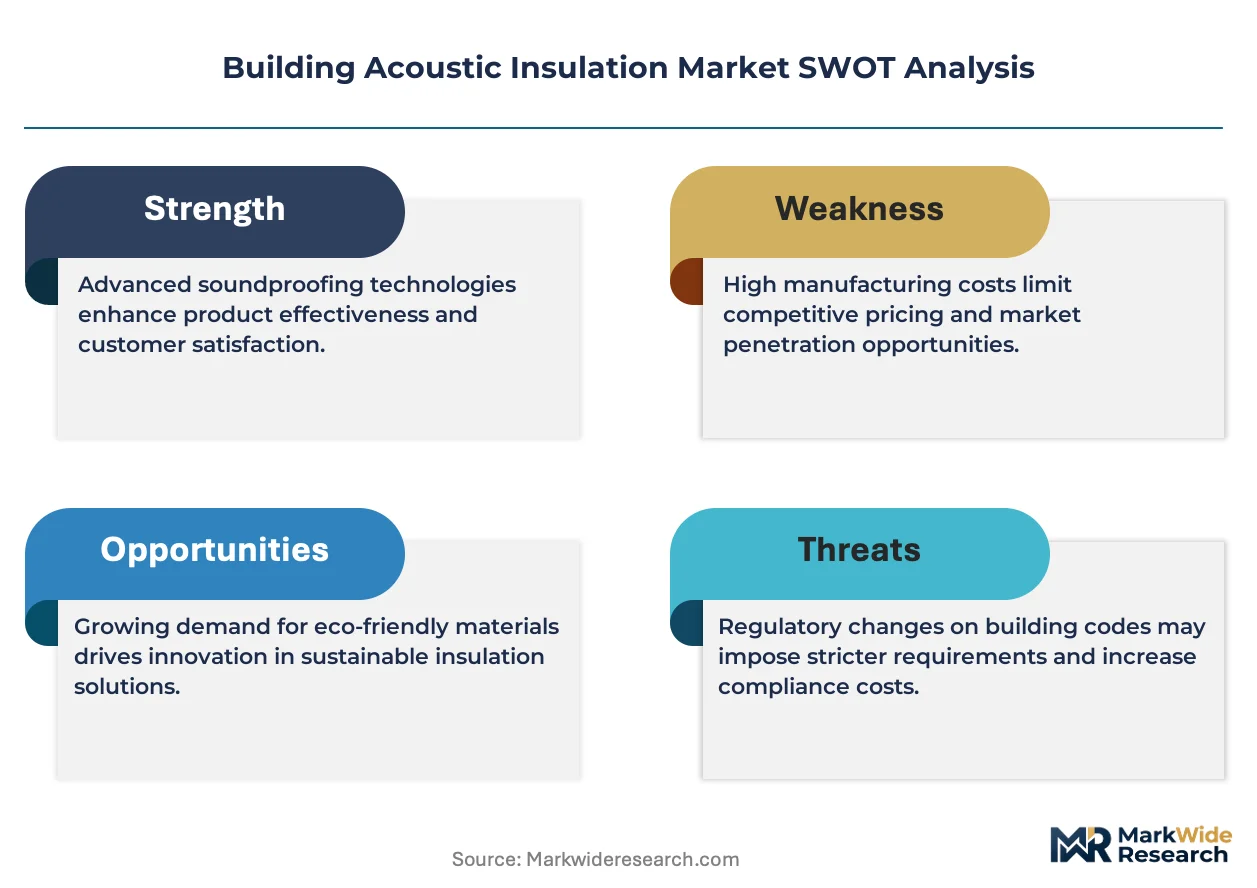
The building acoustic insulation market is fundamentally shaped by the escalating stringency of building codes and noise ordinances. Mandates within the EU Green Deal and municipal regulations in the United States are compelling architects and builders to specify materials with higher acoustic performance ratings, particularly in dense urban environments.
Growth Catalysts
- Regulatory Mandates:The EU's Construction Products Regulation (CPR) requires CE marking based on declared performance, forcing manufacturers to validate acoustic properties and driving adoption of certified materials over non-compliant alternatives.
- Commercial Sector Requirements:Demand from the healthcare and hospitality sectors for superior sound dampening to ensure patient recovery and guest satisfaction acts as a significant catalyst for high-performance mineral wool and fiberglass products.
- Urban Redevelopment:Concentrated urban redevelopment in Germany and China, especially in mixed-use zones, necessitates advanced acoustic separation between commercial and residential spaces within the same structure.
Market Restraints
- High Material Costs:The premium price of multi-functional insulation materials that offer combined acoustic, thermal, and fire-resistant properties can deter adoption in cost-sensitive residential projects or regions with less stringent building codes.
- Substitution from Building Techniques:Builders may opt for structural design alternatives, such as staggered-stud walls or resilient channels with standard insulation, as a lower-cost substitute for specialized high-STC acoustic panels, limiting market penetration.
- Technical Performance Gaps:Conventional insulation materials are often less effective at blocking low-frequency noise from sources like HVAC equipment or home theaters, creating performance gaps that require more complex and expensive engineered solutions.
Strategic Opportunities
- Residential Retrofitting Niche:The conversion of residential spaces into home offices creates a distinct opportunity for retrofitting solutions designed to isolate work areas from household noise, a previously underserved application.
- Lightweight Material Innovation:Development of next-generation materials, such as thin acoustic felts or composites, offers a pathway to provide high noise reduction without sacrificing valuable floor space, appealing to high-density housing projects.
- Emerging Market Construction Booms:Rapid urbanization and the introduction of modern building standards in Southeast Asian countries present untapped geographic markets for acoustic insulation products as new commercial and multi-family housing projects are commissioned.
Industry Challenges
- Complex Certification Pathways:Navigating the varied and time-consuming testing and certification processes, including ASTM standards in the United States and EN standards for CE marking in Europe, creates significant operational hurdles for manufacturers.
- Installation Skill Deficiencies:The effectiveness of acoustic insulation is highly dependent on correct installation; a shortage of trained installers can lead to performance failures, reputational risk, and costly remediation work for contractors.
- Logistical Demands of Large Projects:Servicing large-scale commercial developments requires sophisticated supply chain coordination to manage just-in-time delivery for multi-stage construction schedules, challenging smaller suppliers with limited distribution capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Building Acoustic Insulation Market |
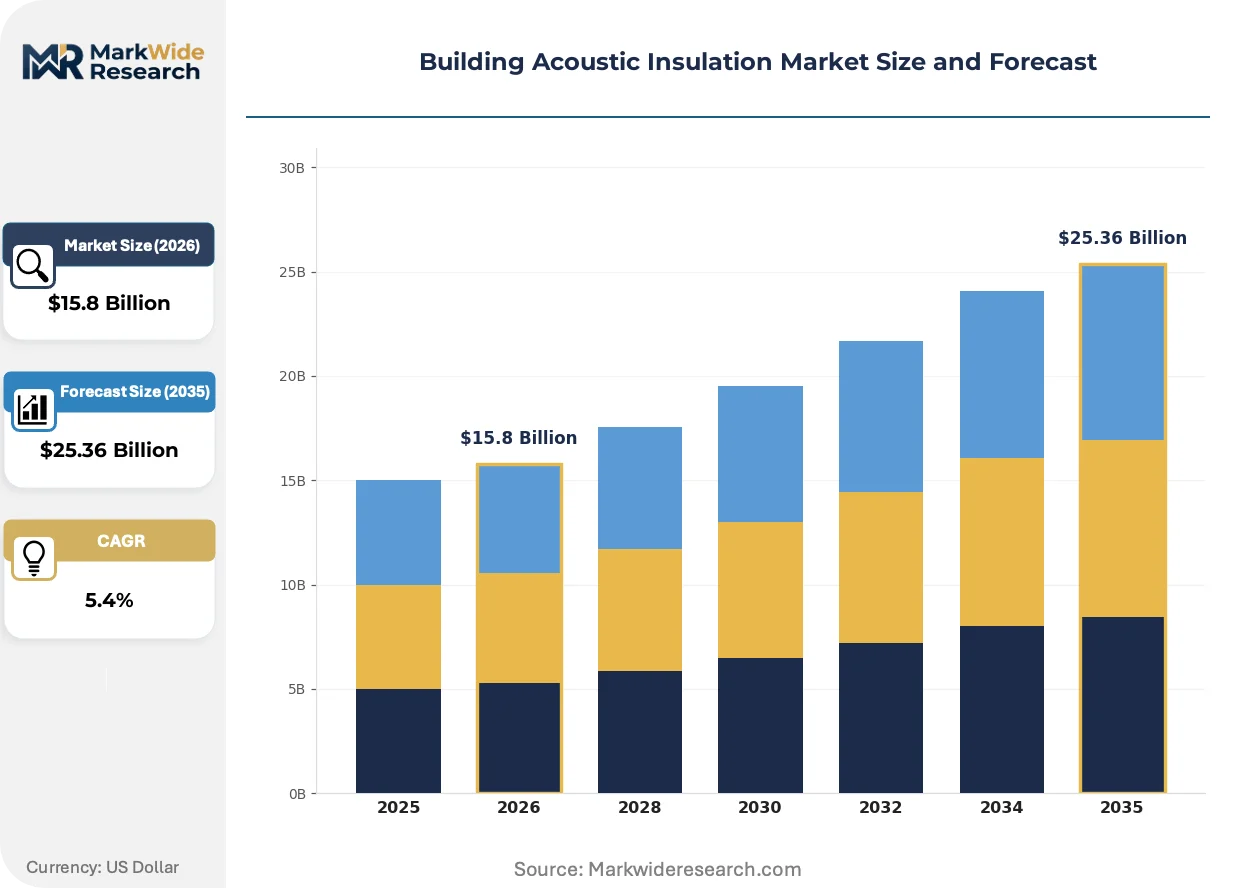
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $25.36 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam, Mineral Wool, Fiberglass, Mass Loaded Vinyl Application: Residential, Commercial, Industrial, Entertainment Installation Method: Wall Assembly, Ceiling Unit, Floor Layer, Window Treatment End User: Contractors, Builders, Architects, Designers |
| Companies Covered | Knauf Insulation, Kingspan Group, Saint-Gobain, Johns Manville, BASF SE, Owens Corning, Armacell International, Soprema, ROCKWOOL International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Building Acoustic Insulation Market Strategic Shifts & Innovations
The convergence of acoustic performance with other building requirements, such as fire safety and thermal efficiency, is defining product innovation. This integration is a direct response to holistic building performance standards and regulations that assess structures on multiple criteria simultaneously, moving the market beyond single-function materials.
Composite insulation panels that integrate different material layers are gaining traction. These products often combine a sound-absorptive core like mineral wool with a high-density sound-blocking layer such as mass-loaded vinyl. Architects specifying for performance-critical buildings like recording studios and hospitals are driving initial adoption. This technology is hybridizing material functions, enabling a single panel to deliver certified performance across acoustic, fire, and thermal categories, simplifying both specification and installation.
Regulatory frameworks are increasingly tying acoustic upgrades to broader environmental goals. The European Union's Green Deal, through its Renovation Wave strategy, provides a powerful incentive for deep energy retrofits of existing buildings. This policy creates a prime opportunity to incorporate acoustic insulation upgrades alongside thermal improvements. The residential and public building sectors in member states like France and Germany are most affected, spurring demand for products with verified thermal and acoustic co-benefits.
A notable behavioral shift is occurring in how projects are specified, moving from a component-cost focus to an occupant-centric, wellness-driven model. This trend is displacing the traditional procurement process, with building certifications like LEED and WELL becoming decisive factors in material selection. The emphasis on documented contributions to occupant health and comfort is most prominent in the Class A office and luxury multi-family residential segments across North America and Western Europe.
Building Acoustic Insulation Market Segmentation
Understanding the diverse segments within the building acoustic insulation market clarifies demand patterns and material preferences. This granular view helps stakeholders align product development with specific end-user requirements. Each category reveals unique drivers shaping material selection and project execution across the construction industry.
Product Type:
Material composition dictates the performance characteristics and suitability of acoustic insulation products across various building types.
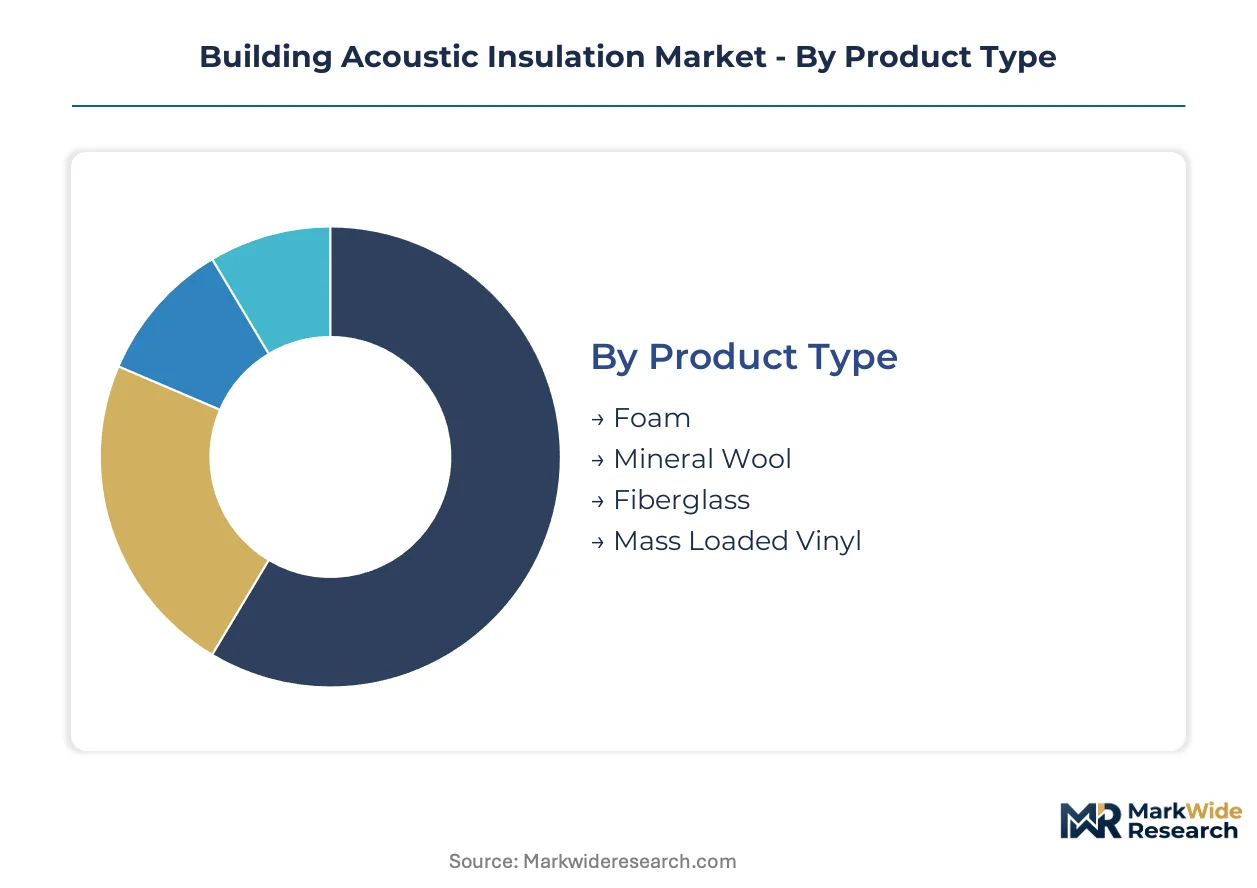
- Mineral Wool:Comprising rock or slag fibers, this material offers excellent sound absorption and fire resistance properties. Demand concentrates in commercial construction, particularly for healthcare and hospitality projects requiring superior sound dampening and non-combustible solutions.
- Fiberglass:Manufactured from fine glass fibers, this insulation provides effective thermal and acoustic benefits. It finds significant demand in multi-family housing and office buildings in urban redevelopment zones, driven by stricter municipal noise ordinances.
- Foam:Polymer-based materials like polyurethane or melamine provide lightweight sound absorption for specific applications such as recording studios.
- Mass Loaded Vinyl:This heavy, flexible barrier material effectively blocks airborne sound transmission in walls and ceilings.
Mineral Wool commands the established base. The steepest expansion runs through Fiberglass.
Application:
The end-use environment significantly influences the required acoustic performance and material specification for insulation.
- Commercial:This segment includes offices, healthcare facilities, and hotels, demanding high STC ratings for occupant comfort and privacy. Stricter building codes in Europe and the US drive demand for multi-functional materials in this sector.
- Residential:Encompassing single-family homes and multi-family units, this application increasingly seeks solutions for home office soundproofing and general noise reduction. Urban redevelopment in Germany and China boosts demand for advanced residential acoustic separation.
- Industrial:Acoustic insulation in this sector mitigates noise from machinery and processes to protect worker health and comply with OSHA regulations.
- Entertainment:This segment, including theaters and recording studios, requires specialized high-performance products for critical sound control.
Commercial applications hold the largest share. Residential retrofitting represents the fastest-growing niche.
Installation Method:
Structural integration dictates the form factor and placement of acoustic insulation within building envelopes.
- Wall Assembly:Insulation integrated into stud walls or partition systems primarily addresses airborne sound transmission between rooms. This method is critical for multi-family housing and commercial office spaces to meet STC requirements.
- Floor Layer:Materials installed beneath flooring or within floor joists reduce impact noise, essential for multi-story buildings and hospitality venues. Demand is high in urban residential projects where impact sound is a major concern.
- Ceiling Unit:Suspended panels or integrated tiles absorb reverberation and block sound transmission from above, common in open-plan offices.
- Window Treatment:Specialized glazing or secondary window inserts reduce external noise ingress, particularly in urban areas with high traffic.
Wall Assembly applications form the foundational market. Floor Layer installations are expanding most quickly.
End User:
Decision-making influence determines the specification and procurement channels for acoustic insulation products.
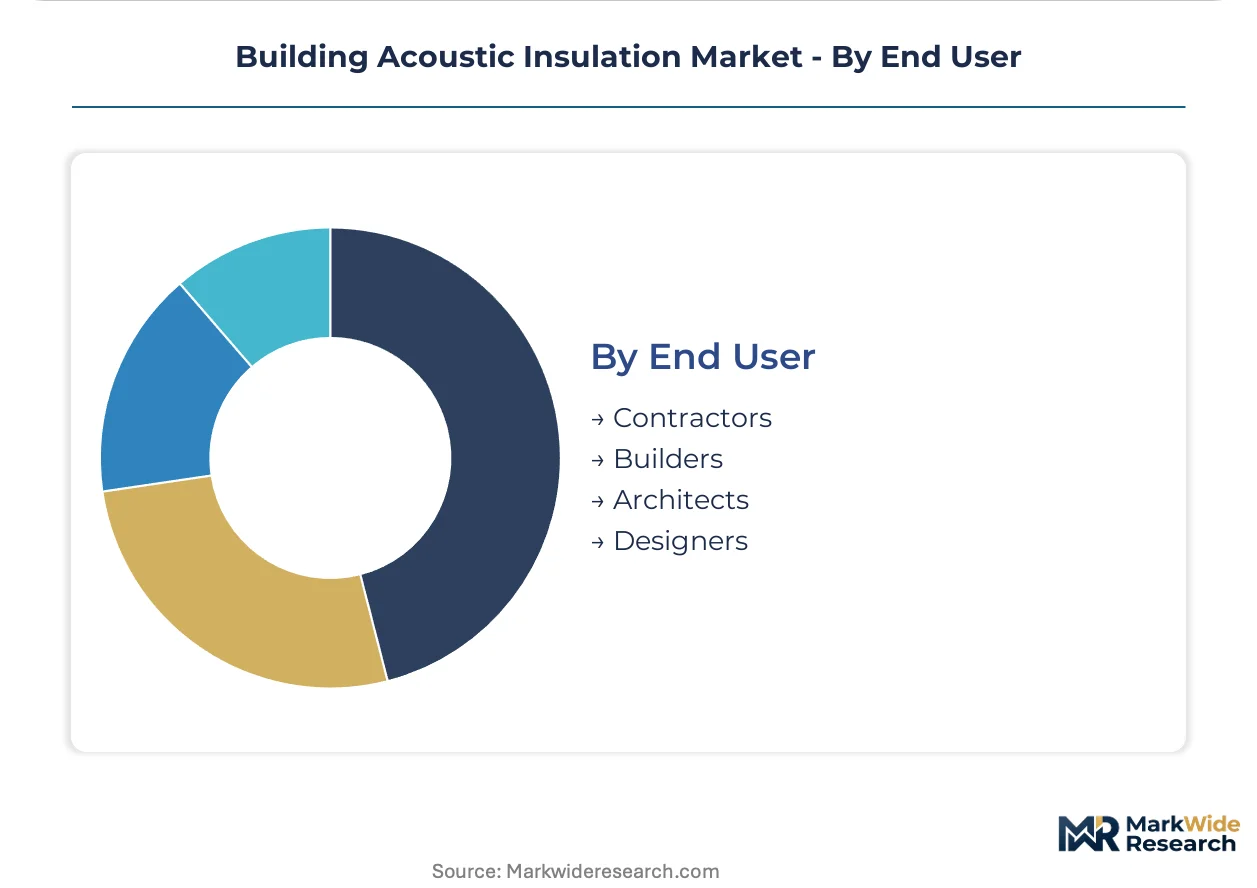
- Contractors:These professionals execute the installation, often selecting specific products based on cost, availability, and ease of application. Their role is critical in ensuring correct installation to achieve declared acoustic performance, particularly for large commercial projects.
- Architects:Responsible for initial design and material specification, architects select products based on performance ratings, aesthetic integration, and compliance with building codes. Their influence is paramount in high-performance buildings like hospitals and data centers.
- Builders:These entities oversee the entire construction process, making purchasing decisions for materials based on project budgets and timelines.
- Designers:Interior designers focus on aesthetic and functional integration, often influencing the choice of visible acoustic panels in commercial and residential spaces.
Contractors represent the largest purchasing group. Architects drive product innovation through specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global building acoustic insulation market exhibits a dynamic regional balance, with key manufacturing hubs often serving both domestic demand and international export markets. Countries with mature construction sectors balance local production with specialized imports for high-performance applications. Emerging economies are rapidly expanding domestic production to meet accelerated infrastructure development.
United States
Demand for acoustic insulation stems from multi-family housing and commercial office developments across the United States. Local building codes often reference ASTM International standards for minimum STC ratings in commercial and residential structures. Urban redevelopment zones in cities like New York and Los Angeles drive requirements for advanced soundproofing solutions. New construction projects increasingly emphasize occupant comfort and privacy.
Germany
Urban redevelopment projects and stringent environmental regulations underpin demand in Germany's acoustic insulation market. The EU Green Deal and its Renovation Wave strategy incentivize acoustic upgrades alongside thermal improvements in existing buildings. Mixed-use construction in Berlin and Munich requires advanced acoustic separation between commercial and residential spaces. Manufacturers focus on multi-functional materials that meet both acoustic and energy efficiency standards.
China
Rapid urbanization and the expansion of modern building standards fuel China's acoustic insulation market. National GB standards increasingly mandate higher acoustic performance in residential and commercial buildings. Concentrated urban redevelopment in the Yangtze River Delta necessitates advanced acoustic separation within mixed-use structures. Infrastructure projects across major cities integrate sound dampening solutions for public spaces and transportation hubs.
India
Infrastructure development and a growing urban population are driving India's acoustic insulation market. The country's national building codes are progressively incorporating acoustic performance requirements for new constructions. Major metropolitan areas like Mumbai and Delhi see demand from commercial and high-rise residential projects. Local manufacturers are expanding capacity to meet this rising demand for sound control products.
United Arab Emirates
Commercial and hospitality sector expansion drives demand for high-performance acoustic solutions in the United Arab Emirates. Strict building codes for luxury developments mandate superior sound dampening to ensure guest comfort and privacy. Iconic construction projects in Dubai and Abu Dhabi specify advanced insulation for critical acoustic performance. The region's focus on premium real estate sustains demand for specialized products.
Building Acoustic Insulation Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing raw materials and basic insulation forms. The market exhibits a tiered structure, with large multinational corporations offering comprehensive solutions alongside specialized regional manufacturers. Strategic archetypes include diversified building material conglomerates, pure-play acoustic insulation specialists, and innovative material science firms. Companies are increasingly pursuing portfolio diversification to meet integrated building performance standards.
Among the established players, Saint-Gobain exemplifies the diversified building materials giant, leveraging its vast distribution network to service complex, multi-stage commercial and public infrastructure projects. This approach allows them to cater to extensive project management support requirements. ROCKWOOL International anchors the pure-play specialist segment, focusing on non-combustible stone wool solutions specifically specified for high-performance buildings like hospitals and data centers due to their inherent fire resistance. Johns Manville occupies a position as a broad portfolio provider, offering both fiberglass and foam products to address varied architectural requirements across different construction types and performance needs.
| Leading Market Players |
|---|
| Knauf Insulation |
| Kingspan Group |
| Saint-Gobain |
| Johns Manville |
| BASF SE |
| Owens Corning |
| Armacell International |
| Soprema |
| ROCKWOOL International |
| Others |
Cost & Logistics Intelligence
Mineral wool and fiberglass raw material production in China and Europe significantly influences downstream pricing power for finished acoustic insulation products. This concentration impacts profit margins across the value chain, particularly for specialized solutions.
Pricing Analysis
Commercial project developers anchor project-based pricing for building acoustic insulation. Pricing stratifies across premium, standard, and economy tiers based on certified performance ratings like STC and NRC, alongside integrated fire resistance. Pricing softness runs through cost-sensitive residential applications due to competition from alternative building techniques. High-performance commercial and healthcare projects exhibit lower price sensitivity, prioritizing multi-functional material benefits and long-term project support.
Supply Chain Analysis
Major manufacturers like Saint-Gobain and ROCKWOOL International hold significant production capacity for building acoustic insulation, primarily concentrated across Europe and China. Production relies on key raw materials such as rock, slag, and glass fibers. Commodity price volatility for these inputs represents a structural risk for manufacturers. Distribution runs through established networks of building material suppliers and direct channels to large commercial contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The building acoustic insulation market is experiencing a cyclical recovery, driven by renewed investment in commercial construction and urban redevelopment projects. This rebound offers strategic opportunities across the value chain for focused expansion.
For Market Incumbents: Harden existing market positions by integrating advanced project management support for large-scale commercial developments. Invest in R&D for next-generation lightweight materials and composite panels to counter substitution from alternative building techniques. Streamline certification processes to reduce operational hurdles, leveraging established relationships with regulatory bodies. This protects market share against emerging material innovations and project cost pressures.
For New Entrants and Emerging Players: Establish a beachhead in the underserved residential retrofitting niche for home offices. Target emerging Southeast Asian markets experiencing construction booms and evolving building standards. Focus on lightweight material innovation, such as thin acoustic felts, that offer high noise reduction without sacrificing space. Partner with local contractors and interior designers to offer integrated, easy-to-install solutions for these specific applications.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized material science firms driving lightweight and multi-functional product innovation. The market exhibits strong long-term viability over the next 5-10 years, propelled by global urbanization and increasingly stringent acoustic regulations. Acquire companies with strong R&D capabilities in composite insulation panels or those offering robust project management support. The signal to watch is the pace of regulatory harmonization across global building standards.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Composite Panel R&D | Enables single-product solutions meeting acoustic, thermal, and fire standards for performance-critical buildings. |
| Expand Distribution in Emerging Markets | Captures demand from rapid urbanization and new construction projects in Southeast Asian countries. |
| Develop Residential Retrofit Kits | Addresses the fast-growing home office segment and provides accessible soundproofing solutions for consumers. |
| Standardize Installation Training Programs | Mitigates performance failures and reputational risks caused by skill deficiencies among contractors. |
| Pursue CE Marking for New Products | Ensures market access and regulatory compliance within the European Union's Construction Products Regulation. |
Research Approach
Initial hypotheses were tested against primary input from architects, contractors, building material manufacturers, and regulatory affairs specialists, and refined through iterative feedback. This involved combining qualitative insights from direct interviews with quantitative validation from secondary sources. Secondary data included EU Construction Products Regulation documents, ASTM International standards, and national building codes. A robust bottom-up and top-down triangulation approach ensured data consistency and accuracy.
Demand-supply balance models were constructed to project market evolution across the analysis window, integrating historical performance and future growth drivers. Segmentation dimensions modeled included product type, application, installation method, end user, and regional construction activity. Compound annual growth rates were derived from a synthesis of historical trends and projected impacts of regulatory changes. Key forecast inputs included urbanization rates and new commercial building permit issuances.
Stress conditions across raw material price fluctuations and shifts in building code enforcement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding economic stability and continued regulatory stringency. Quarterly review of commercial construction starts and key regulatory updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Branched Reinforced Fittings Market
Building & Construction Materials
North America Plywood Market
Building & Construction Materials
SBS Waterproofing Membrane Market
Building & Construction Materials
Germany Foam Insulation Market
Building & Construction Materials
Sanitary Ware Market
Building & Construction Materials
North America Non-Residential Polished Concrete Market
Building & Construction Materials
Global Intelligent Sanitary Ware Market
Building & Construction Materials
Saudi Arabia Tiles Market
Building & Construction Materials
Traffic Road Marking Coatings Market
Building & Construction Materials
North America Balustrade Market
Building & Construction Materials
US Plywood Market
Building & Construction Materials
Aerated Autoclaved Concrete (AAC) Market
Building & Construction Materials
Storefront Glass Market
Building & Construction Materials
Exterior Sheathing Market
Building & Construction Materials
Concrete Resurfacer Market
Building & Construction Materials
US Ceiling Tiles Market