
 Sanitary Ware Market | 2026-2036
Sanitary Ware Market Size, Share, and Industry Trends Forecast 2026-2036
Sanitary Ware Market Intelligence
Multi-source ceramic supply is hardening as manufacturers hedge against raw material volatility. Geberit AG leverages in-house vitreous china production to secure batch consistency across European plants. RAK Ceramics PJSC anchors its cost position through captive feldspar sourcing from UAE quarries. TOTO Ltd. differentiates via glaze-chemistry R&D, sustaining premium positioning in Japanese institutional channels.
Sanitary ware encompasses vitreous china, porcelain, and engineered ceramic fixtures designed for hygiene, water conveyance, and waste disposal in built environments. These products typically undergo high-temperature kiln firing at 1,200–1,400°C to achieve non-porous, stain-resistant surfaces suitable for repeated sanitization cycles. Ceramic material commands the largest share of value owing to durability perceptions and established distribution, while plastic segments gain traction in modular commercial installations where weight reduction matters. Wall-mounted installation types attract margin focus as concealed-cistern systems bundle higher-value hardware and drive aftermarket service revenue.
EPA WaterSense certification, EU Ecodesign requirements, and India's BIS IS 2556 standards collectively constrain flush-volume tolerances and mandate leak-testing protocols. Compliance with these frameworks shapes R&D allocation toward low-flow rim geometries and sensor-actuated mechanisms. Stakeholders must monitor evolving municipal rebate programs and building codes that accelerate replacement cycles in aging housing stock.
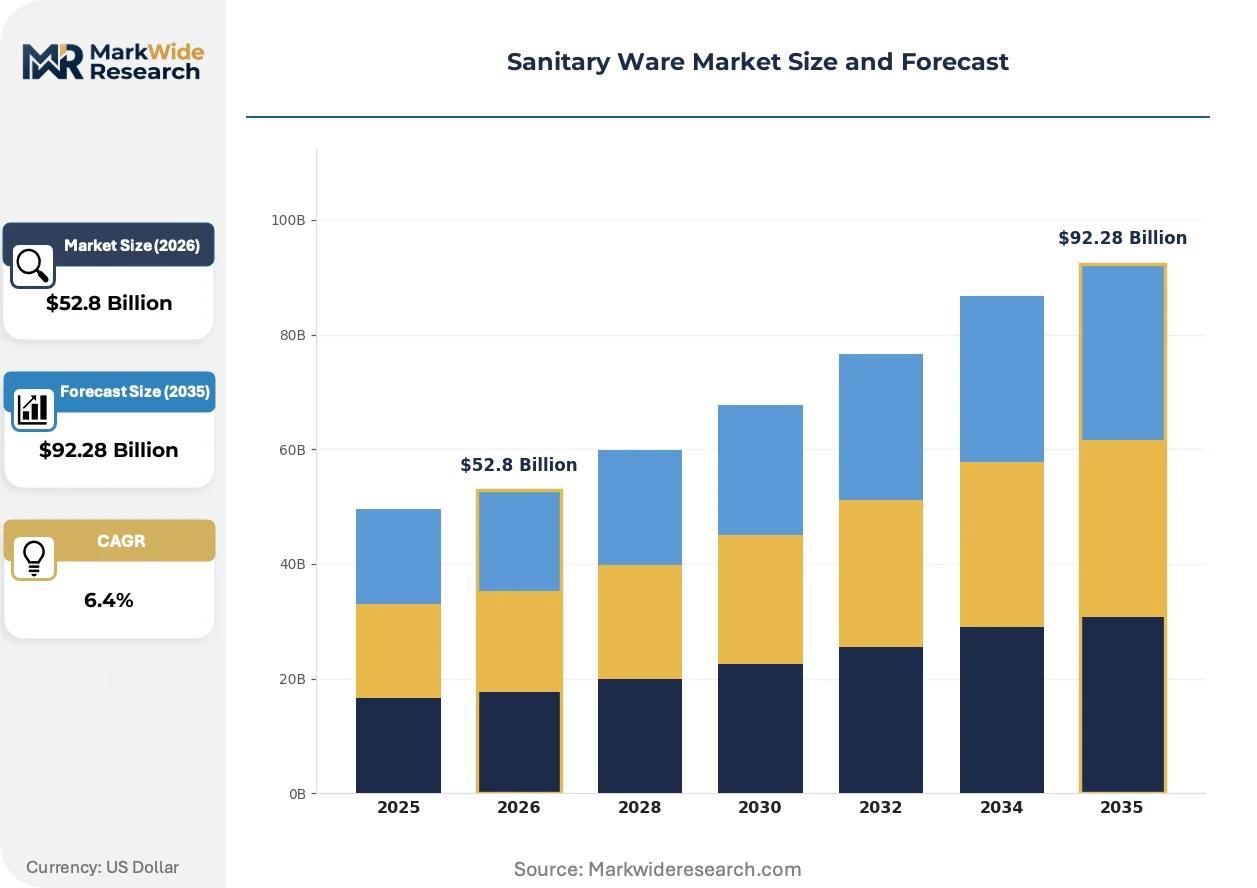
Market Dynamics
Water-efficiency mandates from EPA WaterSense and EU Ecodesign are compressing flush-volume tolerances and forcing R&D reallocation toward low-flow rim geometries, while raw material volatility in ceramic supply chains intensifies margin pressure across tier-1 manufacturers.
Growth Catalysts
- EPA WaterSense certification:Municipal rebate programs in the United States accelerate replacement cycles in aging housing stock, pulling forward demand for certified low-flow fixtures.
- Residential construction corridors:Urban housing development in India concentrates volume demand for vitreous china installations in high-rise residential towers.
- Sensor-actuated mechanisms:Touchless flush technology is penetrating institutional channels in Japan, driven by hygiene protocols in healthcare and hospitality end-uses.
Market Restraints
- Feldspar supply concentration:Captive quarry ownership in the UAE creates dependency risk for manufacturers without backward integration into raw material sourcing.
- Kiln energy intensity:Natural gas price volatility directly impacts firing costs for vitreous china production at 1,200–1,400°C operating temperatures.
- BIS IS 2556 compliance friction:India's mandatory leak-testing protocols extend product development timelines and raise certification costs for new market entrants.
Strategic Opportunities
- Modular commercial installations:Plastic sanitary ware segments gain traction where weight reduction matters, opening specification opportunities in prefabricated construction.
- Aftermarket service bundling:Concealed-cistern wall-mounted systems create recurring revenue streams through hardware maintenance and spare part replacement.
- EU Ecodesign expansion:Tightening flush-volume standards across European member states will mandate product line refreshes, favoring early movers with compliant low-flow portfolios.
Industry Challenges
- Glaze-chemistry R&D talent scarcity:Specialized ceramic engineers capable of developing stain-resistant, non-porous surface formulations command premium compensation and limited availability.
- Batch consistency at scale:Maintaining vitreous china uniformity across multi-plant European networks requires capital-intensive kiln control systems and real-time quality monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sanitary Ware Market |
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $92.28 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toilets, Wash Basins, Bathtubs, Showers Material: Ceramic, Plastic, Stainless Steel, Glass End User: Residential, Commercial, Institutional, Industrial Installation Type: Wall-Mounted, Floor-Mounted, Integrated, Freestanding |
| Companies Covered | Geberit AG, LIXIL Corporation, Roca Sanitario S.A., RAK Ceramics PJSC, Duravit AG, Kohler Co., Villeroy & Boch AG, Jaquar Group, TOTO Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sanitary Ware Market Strategic Shifts & Innovations
Digital manufacturing controls and material science advances are reshaping how sanitary ware producers balance water-efficiency mandates with surface durability requirements, compressing traditional trade-offs between performance and compliance.
Advanced glaze-chemistry formulations incorporating nano-scale surface treatments are absorbing premium positioning in Japanese institutional channels. Healthcare facilities and luxury hospitality operators specify these surfaces for enhanced stain resistance and accelerated sanitization cycles. The technology is absorbing margin compression from raw material volatility by justifying 40-60% price premiums over standard vitreous china.
EU Ecodesign requirements are tightening flush-volume tolerances across member states, forcing manufacturers to reengineer rim geometries and valve mechanisms. Production lines serving European distribution must now certify dual-flush systems below 4.5/3.0 liter thresholds. German and Italian sanitary ware specialists are responding fastest, leveraging existing low-flow R&D pipelines developed under earlier national standards.
Specification decisions in India's urban housing corridors increasingly hinge on BIS certification status rather than brand recognition alone. Bulk procurement by real estate developers favors pre-qualified suppliers with documented IS 2556 compliance, compressing vendor shortlists to certified manufacturers. This pattern concentrates volume with established players possessing in-house testing laboratories and regulatory affairs capabilities.
Sanitary Ware Market Segmentation

Segmentation in sanitary ware reveals how material specifications, installation constraints, and end-use hygiene protocols fragment procurement patterns. Manufacturers configure production lines around these divides, as ceramic firing economies differ fundamentally from plastic injection molding or stainless steel fabrication.
Product Type:
Standalone fixtures dominate residential specifications, while embedded systems integrate into prefabricated commercial modules. Integration depth varies by plumbing complexity and maintenance access requirements.
- Toilets:Vitreous china bowls with concealed-cistern mechanisms anchor water-efficiency compliance efforts under EPA WaterSense and EU Ecodesign. Demand concentrates in India's urban housing corridors where high-rise residential towers specify rim geometries optimized for low-flow performance.
- Wash Basins:Countertop and undermount configurations serve distinct installation workflows, with ceramic surfaces preferred for durability perceptions in hospitality end-uses. Sensor-actuated faucets are bundling with basins in Japanese healthcare facilities, driven by hygiene protocols that mandate touchless operation.
- Bathtubs:Acrylic and cast-iron variants serve premium residential segments where weight constraints matter less than thermal retention.
- Showers:Modular enclosure systems gain traction in commercial prefabrication where accelerated construction timelines compress installation windows.
Toilets lead volumes today; showers are gaining share fastest in commercial modular applications.
Material:
Cost tier stratification separates premium ceramic from economy plastic alternatives, with mid-market stainless steel occupying niche commercial segments.
- Ceramic:Vitreous china and porcelain formulations undergo kiln firing at 1,200–1,400°C to achieve non-porous, stain-resistant surfaces suitable for repeated sanitization cycles. India's BIS IS 2556 standards constrain batch consistency requirements, favoring manufacturers with in-house testing laboratories.
- Plastic:ABS and acrylic compounds reduce fixture weight by 60-70% versus ceramic, enabling specification in modular commercial installations where structural load limits matter.
- Stainless Steel:Brushed and polished finishes serve industrial and high-traffic institutional environments where impact resistance outweighs thermal comfort considerations.
- Glass:Tempered vessel sinks occupy premium residential and boutique hospitality segments where aesthetic differentiation commands price tolerance.
Ceramic commands the broadest specification base; plastic is climbing the fastest in commercial modular construction.
End User:
Application intensity varies by sanitization frequency and regulatory scrutiny, with institutional users facing the strictest hygiene protocols.
- Residential:Single-family and multi-family housing drives volume through replacement cycles and new construction, with India's urban corridors concentrating bulk procurement by real estate developers.
- Commercial:Hotels, restaurants, and retail spaces balance durability requirements with aesthetic refresh cycles, specifying mid-tier ceramic and solid-surface materials.
- Institutional:Healthcare facilities and educational buildings mandate sensor-actuated mechanisms and enhanced glaze-chemistry formulations under Japanese hygiene protocols.
- Industrial:Manufacturing and warehouse environments prioritize stainless steel and heavy-duty ceramic for chemical resistance and impact tolerance.
Residential anchors volume today; institutional is expanding most quickly on sensor-technology adoption.
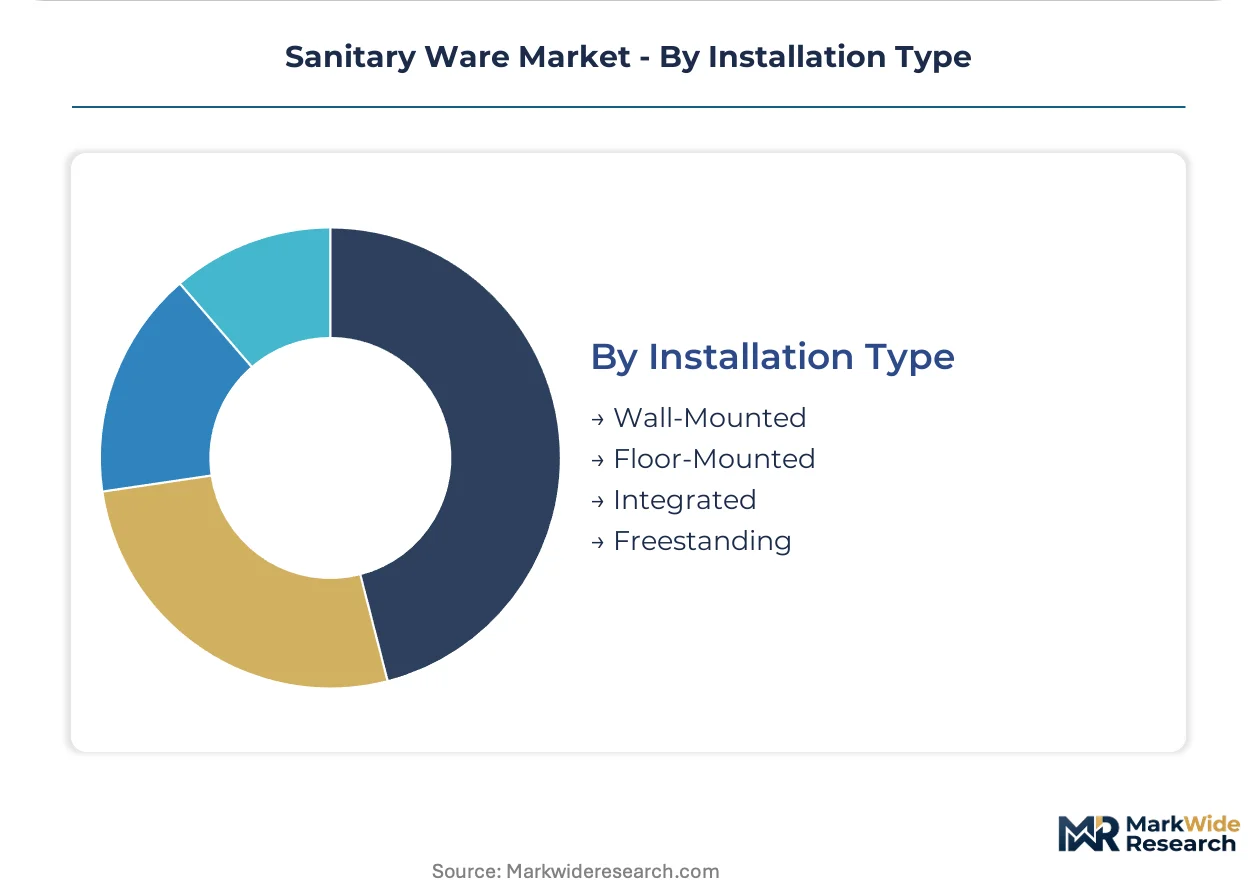
Installation Type:
Mounting configuration determines aftermarket service revenue potential and initial construction labor requirements.
- Wall-Mounted:Concealed-cistern systems bundle higher-value hardware and create recurring revenue through maintenance and spare part replacement, favored in European markets with established service infrastructure.
- Floor-Mounted:Traditional pedestal and close-coupled designs dominate replacement markets and budget residential construction where existing plumbing rough-ins constrain retrofit options.
- Integrated:Pre-fabricated bathroom pods combine multiple fixtures in factory-controlled conditions, compressing on-site construction timelines for hospitality and healthcare projects.
- Freestanding:Sculptural bathtubs and vessel sinks occupy premium residential segments where spatial statement matters more than space efficiency.
Floor-mounted leads volumes today; wall-mounted is gaining share fastest on concealed-cistern bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's urban housing corridors concentrate the fastest volume expansion, while regulatory tightening across the United States, Germany, and Japan pulls forward replacement demand for water-efficient fixtures.
United States
Municipal rebate programs in California and Texas accelerate fixture replacement in aging housing stock. EPA WaterSense certification requirements constrain flush-volume tolerances below 1.28 gallons per flush. Dallas-Fort Worth and Phoenix metropolitan clusters drive bulk procurement for low-flow retrofit installations.
Germany
EU Ecodesign requirements mandate dual-flush systems below 4.5/3.0 liter thresholds, forcing rim geometry reengineering. The country's national building efficiency regulator enforces tightening standards through the national implementation of EU directives. The Ruhr industrial corridor hosts specialized ceramic engineering facilities serving pan-European distribution.
India
High-rise residential towers in Mumbai and Bangalore specify vitreous china installations at scale. BIS IS 2556 standards enforce mandatory leak-testing protocols that compress vendor shortlists to certified manufacturers. The Delhi-Mumbai Industrial Corridor concentrates real estate developer procurement power.
Japan
Healthcare facilities and luxury hospitality operators in Tokyo and Osaka specify sensor-actuated mechanisms under strict hygiene protocols. METI guidelines shape institutional procurement standards for touchless operation. The Kanto region anchors glaze-chemistry R&D clusters serving premium institutional channels.
United Arab Emirates
Captive feldspar quarry ownership in Ras Al Khaimah creates raw material cost advantages for regional manufacturers. MOHAP building codes align with international water-efficiency benchmarks for hospitality and healthcare construction. Dubai's prefabricated bathroom pod factories serve Gulf Cooperation Council export markets.
Sanitary Ware Market Key Industry Players
Global majors compete with regional champions across material sourcing, certification compliance, and service infrastructure dimensions. The vendor base separates into three tiers: integrated ceramic producers with captive raw material access, specialized hardware innovators bundling concealed-cistern systems, and regional fabricators serving price-sensitive replacement markets. Dominant competitive moves include backward integration into feldspar and clay sourcing, plus strategic partnerships with real estate developers for bulk pre-qualification.
Among Swiss and German integrated producers, Geberit AG exemplifies the captive-manufacturing archetype through in-house vitreous china production. Japanese specialists TOTO Ltd. occupy positions emphasizing surface-technology differentiation. UAE-based RAK Ceramics PJSC anchors the regional-champion tier through upstream control over quarry assets.
| Leading Market Players |
|---|
| Geberit AG |
| LIXIL Corporation |
| Roca Sanitario S.A. |
| RAK Ceramics PJSC |
| Duravit AG |
| Kohler Co. |
| Villeroy & Boch AG |
| Jaquar Group |
| TOTO Ltd. |
| Others |
Cost & Logistics Intelligence
Digital manufacturing controls and real-time kiln monitoring systems are compressing batch consistency costs while simultaneously concentrating production among capital-intensive operators capable of deploying sensor networks across multi-plant European networks. This technological transition rewards manufacturers with backward integration into captive feldspar sourcing while squeezing margin recovery from tier-2 competitors dependent on spot ceramic raw material markets.
Pricing Analysis
Input-cost pass-through from natural gas firing expenses and feldspar procurement volatility is intensifying margin pressure across vitreous china production tiers. Three-tier pricing structure across premium, standard, and economy levels separates nano-glaze formulations commanding hospital procurement premiums from commodity close-coupled toilets serving Indian replacement markets. Price differentiation hinges on WaterSense certification status and concealed-cistern bundling with aftermarket service contracts. Cost compression in standard ceramic tiers is intensifying because spot feldspar markets expose non-integrated manufacturers to UAE quarry pricing power. Real estate developers in India's urban corridors exhibit highest price sensitivity, while Japanese healthcare procurement committees prioritize stain-resistance performance over unit economics.
Supply Chain Analysis
Feldspar supply rests on UAE quarry ownership concentration and Indian domestic clay deposits, with European kaolin deposits serving specialty glaze-chemistry formulations. Vitreous china production draws from captive feldspar, high-purity clay, and nano-scale surface treatment chemicals as critical inputs. Single-source vulnerability concentrates in UAE Ras Al Khaimah quarry assets controlled by regional champions, exposing non-integrated manufacturers to supply rationing during demand surges. Distribution runs through building material wholesalers in developed markets and direct real estate developer relationships in India's high-rise residential corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories favor manufacturers commanding captive raw material access and premium institutional channel positioning, with water-efficiency mandates accelerating replacement demand pull-through in aging housing stock across multiple geographies.
For Market Incumbents: Hedge against feldspar cost volatility through quarry acquisition or long-term offtake agreements with UAE operators. Deepen sensor-actuated mechanism R&D to defend premium positioning as Japanese healthcare hygiene protocols diffuse into Southeast Asian hospitality markets. Concealed-cistern service infrastructure represents the priority defensive moat against modular plastic competitors. For New Entrants and Emerging Players: Capture specification share in India's BIS IS 2556 pre-qualification pipeline by investing in in-house leak-testing laboratories before bulk procurement decisions crystallize. Prefabricated bathroom pod manufacturing for Gulf Cooperation Council hospitality construction offers the most penetrable white-space target. Go-to-market execution should anchor on real estate developer direct relationships rather than wholesale channel buildout. For Investors and Strategic Acquirers: Valuations sit cheapest among regional ceramic fabricators lacking backward integration but possessing certified production lines and established developer relationships. Long-term viability over the next decade hinges on water-efficiency mandate compliance depth and service revenue attachment rates. Watch EPA WaterSense rebate program expansion into additional US metropolitan clusters as the inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Feldspar Quarry Acquisition | RAK Ceramics' UAE asset control demonstrates margin insulation against raw material spot volatility. |
| Concealed-Cistern Service Infrastructure Buildout | Geberit's European maintenance networks convert hardware sales into recurring aftermarket revenue streams. |
| BIS IS 2556 Certification Investment | In-house testing laboratories compress vendor shortlists for India's Delhi-Mumbai Industrial Corridor procurement. |
| Nano-Glaze R&D Partnership | TOTO's Kanto region surface chemistry clusters justify 40-60% premiums in Japanese healthcare specifications. |
| Prefabricated Bathroom Pod Manufacturing | Dubai's factory-controlled production serves GCC hospitality timelines with accelerated installation windows. |
Research Approach
Coverage spans the United States, Germany, India, Japan, and the United Arab Emirates, with primary inputs from each market informing cross-regional pattern identification. Plant managers at vitreous china facilities, procurement leads at real estate development firms, regulatory affairs specialists navigating BIS and EPA frameworks, and aftermarket service heads at concealed-cistern distributors provided structured interview inputs. Secondary validation drew from EPA WaterSense certification databases, EU Ecodesign directive implementation records, Indian BIS IS 2556 testing protocols, and customs trade data on feldspar and ceramic raw material flows. Bottom-up volume estimates triangulated against top-down construction spending projections across residential and commercial end-uses.
Rate-of-change decomposition across the analysis window separated replacement cycle dynamics from new construction absorption patterns. Segmentation modeling incorporated material grade tier, installation type complexity, end-use hygiene protocol intensity, and regional regulatory cluster stringency. CAGRs were derived from fitted trend analysis of historical volume trajectories adjusted for mandate-driven replacement acceleration. Forecast inputs included municipal rebate program expansion timelines, high-rise residential tower pipeline data from Indian metropolitan clusters, and sensor-actuated mechanism penetration curves in Japanese institutional channels.
Natural gas price volatility, feldspar quarry supply disruptions, and BIS certification timeline extensions are the dominant revision risks to volume and value projections. Forecasts reflect assumptions about regulatory mandate enforcement consistency and real estate developer procurement concentration patterns. A small set of named triggers—EPA rebate program geographic expansion, EU Ecodesign threshold tightening, and MOHAP code alignment with international benchmarks—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Glue-Laminated Timber Market
Building & Construction Materials
Global Floor and Wall Glazed Tiles Market
Building & Construction Materials
Global Builder Hardware Market
Building & Construction Materials
Engineered Wood Market
Building & Construction Materials
North America Laminated Veneer Lumber Market
Building & Construction Materials
Roofing Tiles Market
Building & Construction Materials
Fiberglass Doors Market
Building & Construction Materials
Noise Insulation Jackets Market
Building & Construction Materials
Australia Steel Rebar Market
Building & Construction Materials
Electrically Dimmable Exterior Window Systems for Premium Cabins Market
Building & Construction Materials
Warm Mix Asphalt Market
Building & Construction Materials
Garage Doors Market
Building & Construction Materials
Europe Gypsum Board Market
Building & Construction Materials
Opening Trim Weatherstrips Market
Building & Construction Materials
Window Film Market
Building & Construction Materials
Plastic Fencing Market