
 North America Balustrade Market | 2026-2036
North America Balustrade Market Size, Share, and Industry Trends Forecast 2026-2036
North America Balustrade Market Outlook
Maintenance-service contracts for glass and stainless-steel systems is consolidating around premium installers. Feeney Inc. leverages its cable-rail expertise to dominate coastal residential retrofits. Q-railing anchors specification-grade projects through architectural channel partnerships. C.R. Laurence Co., Inc. controls distribution density across Western U.S. glazing contractors.
A balustrade is a row of balusters topped by a rail, engineered to resist minimum concentrated loads per IBC Section 1607.8 while providing fall protection on elevated walking surfaces. Glass balustrades, specified with laminated tempered panels in 12mm to 21.5mm thicknesses, command margin pools in luxury residential and hospitality verticals. Modular aluminum systems compete on speed of installation against custom ironwork in commercial atrium applications.
IBC guardrail provisions, OSHA fall-protection standards, and ADA accessibility criteria collectively determine balustrade spacing, height, and graspability requirements across U.S. and Canadian jurisdictions. Provincial building codes in Ontario and British Columbia enforce additional seismic-load considerations that filter product eligibility. Stakeholders must monitor code-cycle harmonization between NFPA and CSA standards as cross-border project specifications tighten.
Market Dynamics
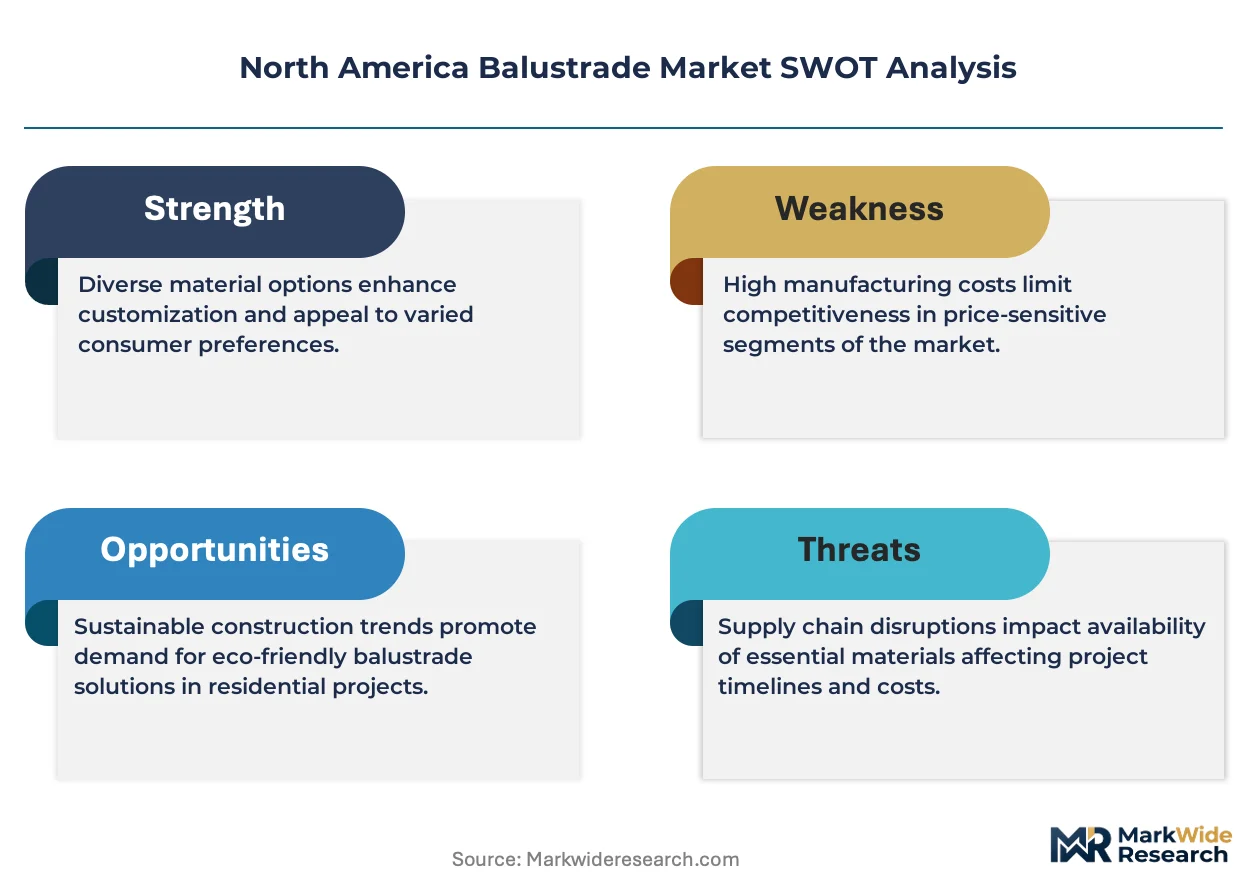
Updated International Building Code provisions on guardrail height and load resistance are forcing manufacturers to redesign product portfolios and recertify entire system families ahead of the 2024-2027 code cycle adoption window across U.S. jurisdictions.
Growth Catalysts
- IBC Section 1607.8 Load Standards:Stricter concentrated load requirements for glass balustrades are filtering out non-compliant imports and elevating specification-grade domestic manufacturers in high-rise residential towers.
- California Metropolitan Construction Corridors:Luxury multifamily developments in Los Angeles and San Francisco are specifying 21.5mm laminated tempered glass systems for unobstructed views, creating pull-through demand for premium hardware.
- Aluminum Extrusion Speed:Modular aluminum balustrade systems are compressing installation timelines from weeks to days, winning share from custom ironwork in commercial atrium and hospitality applications.
Market Restraints
- Seismic-Load Provincial Codes:Ontario and British Columbia building codes enforce additional lateral load testing that excludes many U.S.-certified glass systems from Canadian projects without expensive re-engineering.
- Specialized Installation Labor:Glass balustrade installation requires certified glaziers with structural silicone and point-fixing expertise, creating bottlenecks in markets where trade certification programs lag demand.
- Steel and Aluminum Input Volatility:6063-T6 aluminum extrusion and 316 stainless steel cable pricing fluctuations compress margin pools for mid-tier fabricators locked into fixed-price commercial contracts.
Strategic Opportunities
- Texas Sun Belt Expansion:Austin and Dallas-Fort Worth luxury residential construction is outpacing local balustrade supply capacity, creating entry points for California and Florida-based installers with established glass-system expertise.
- NFPA-CSA Harmonization:Anticipated alignment between U.S. and Canadian fire-safety and structural standards would eliminate dual-certification costs and unlock cross-border specification for integrated building envelope systems.
- Maintenance-Service Contracting:Glass and stainless-steel system owners face 15-25 year replacement cycles for gaskets, seals, and tensioning hardware, creating recurring revenue streams for installers who bundle initial installation with scheduled inspection programs.
Industry Challenges
- Glazier Apprenticeship Pipeline:North American construction trades face acute shortages of technicians trained in structural glass fixing, laminated panel handling, and cable-rail tensioning calibration.
- ADA Graspability Compliance:Handrail diameter and clearance specifications under ADA Standards for Accessible Design vary by jurisdiction, forcing manufacturers to maintain multiple rail profile inventories for national distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Balustrade Market |
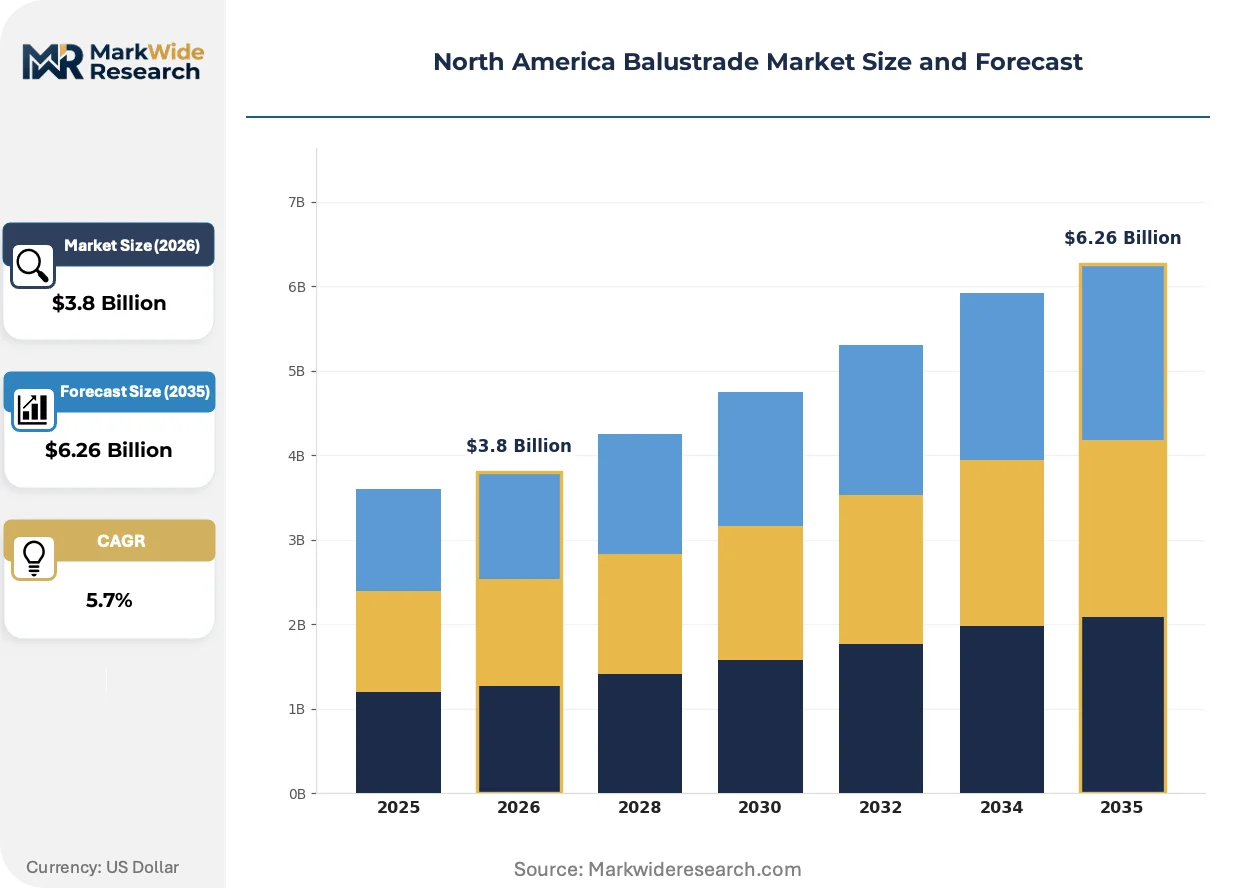
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Wood, Aluminum, Glass, Iron Product Design: Traditional, Modern, Custom, Modular End User: Residential, Commercial, Industrial, Institutional Installation Method: Pre-Fabricated, Custom Built, DIY, Professional |
| Companies Covered | Q-railing, Balcony Systems, Abbey Glass, Atlantis Rail, Feeney Inc., VIVA Railings, Tractel Ltd., Stairways, Inc., C.R. Laurence Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Balustrade Market Strategic Shifts
Digital measurement and fabrication workflows are compressing the traditional design-to-installation timeline for custom balustrade systems, while regulatory pressure on embodied carbon is reshaping material specification priorities across commercial and residential verticals.
Robotic glass-cutting and CNC aluminum machining is automating the production of complex balustrade geometries that previously required manual templating and field fitting. High-end residential developers in Miami and Vancouver are specifying curved glass panels with minimal visible hardware, demanding tolerances of ±1mm that automated fabrication achieves consistently. This capability is automating the displacement of traditional wrought-iron custom shops that cannot match speed or precision at comparable cost points.
OSHA's updated Walking-Working Surfaces standards are extending fall-protection requirements to previously exempt low-slope roof edges and mezzanine perimeters in industrial facilities. Warehouse and distribution center operators in Illinois and Ohio are retrofitting existing structures with modular aluminum guardrail systems to achieve compliance without structural modifications. The commercial retrofit segment is responding with quick-install base-plate-mounted systems that avoid core drilling and preserve roof warranties.
Architects are unbundling balustrade specification from general contractor procurement, engaging directly with specialized glazing subcontractors for design-assist contracts on complex projects. This disintermediation is visible most acutely in Manhattan and Chicago trophy office towers, where envelope consultants now specify point-supported glass systems before GC selection, locking in preferred installers early in the design phase and compressing competitive bidding windows for commodity alternatives.
North America Balustrade Market Segmentation
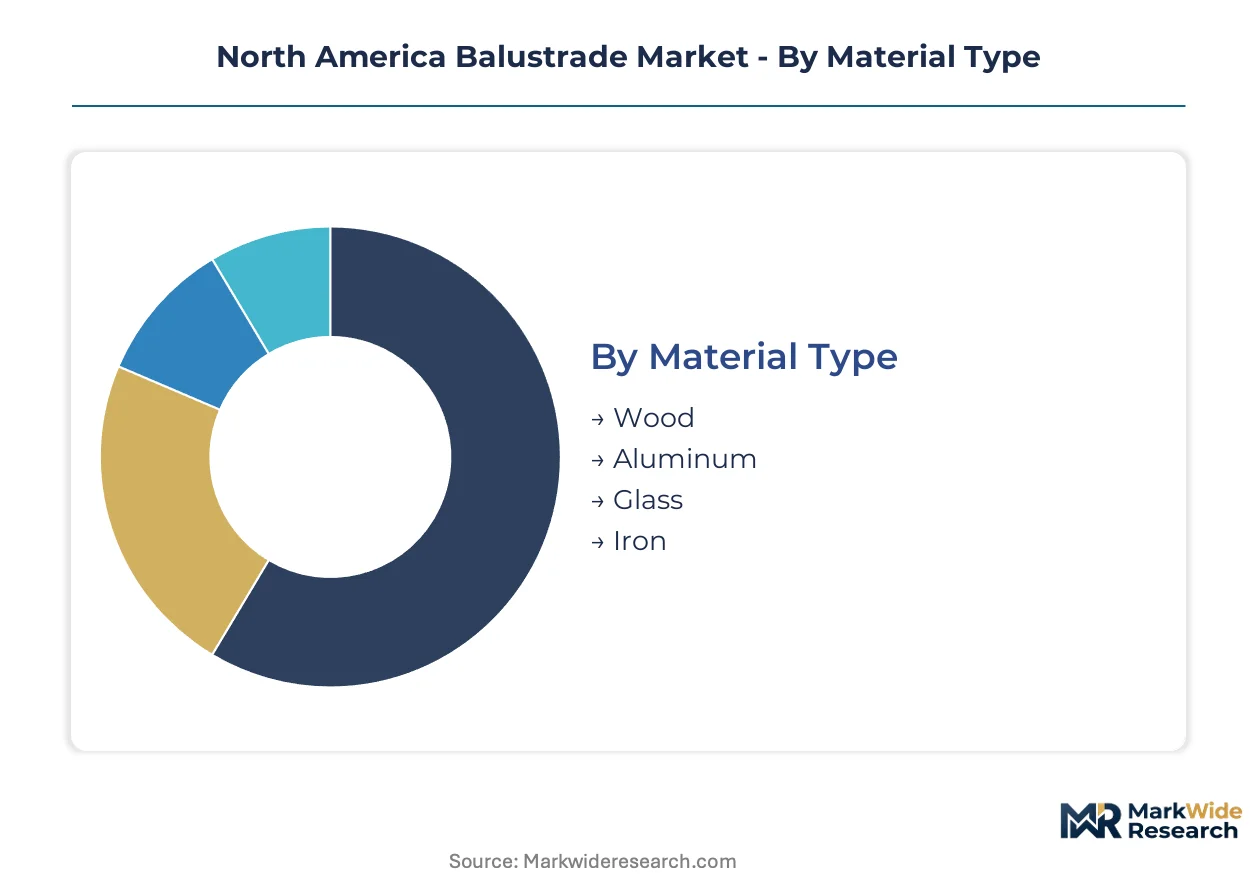
Balustrade procurement in North America splits sharply between systems specified as architectural envelope components versus those treated as finish carpentry. Material and design choices cascade through installation complexity, code compliance burden, and lifecycle maintenance obligations.
Material Type:
Glass and aluminum systems integrate as structural building envelope elements requiring engineering certification, while wood and iron function as decorative additions with simpler standalone installation paths.
- Wood:Cedar and redwood species dominate exterior residential applications in Pacific Northwest and Northeast markets. Pressure-treated pine competes on cost for interior stairs and decks across suburban Texas and Florida developments.
- Aluminum:6063-T6 extrusions with powder-coated finishes serve commercial atriums and coastal condominiums where corrosion resistance outweighs first-cost premiums. Modular railing systems from this material compress field installation to single-day completion.
- Glass:Laminated tempered panels in 12mm to 21.5mm thicknesses command specification priority in California luxury multifamily towers and Miami waterfront residences. IBC Section 1607.8 load certification requirements filter supply to domestic fabricators with in-house structural engineering.
- Iron:Wrought and cast iron retains share in historic district renovations and custom residential estates where ornamental forging justifies extended lead times. Ontario heritage preservation codes mandate this material for designated building restorations.
Volume placements concentrate in aluminum; the faster expansion belongs to glass.
Product Design:
Design segmentation tracks the divergence between architect-driven specification for trophy projects and production-builder procurement for volume housing.
- Traditional:Turned balusters, newel posts, and handrail profiles referencing 19th-century patterns persist in New England colonial revivals and Charleston historic districts. Municipal landmark commissions in Boston and Savannah enforce design guidelines that preserve this category.
- Modern:Clean lines, minimal visible hardware, and open sightlines define specification for Manhattan luxury condominiums and Vancouver high-rise residential. Cable rail systems and frameless glass channels dominate this aesthetic category.
- Custom:One-off forged ironwork and curved glass geometries serve estate-scale residential and boutique hospitality in Aspen, Napa Valley, and Hamptons markets. Digital templating and CNC fabrication are compressing historical cost premiums.
- Modular:Pre-engineered aluminum and steel component systems target commercial retrofit compliance with OSHA fall-protection standards. Warehouse operators in Illinois and Ohio specify quick-install base-plate-mounted configurations.
Modern design captures the steepest share gains in new construction; modular solutions dominate retrofit volume.
End User:
End-user segmentation reveals divergent procurement authority structures, with commercial and institutional buyers centralizing specification through architectural consultants while residential remains fragmented.
- Residential:Single-family custom builders and luxury multifamily developers drive demand for glass and cable systems with minimal sightline obstruction. California Title 24 energy code compliance adds specification complexity for exterior applications.
- Commercial:Office tower developers and hospitality operators in Chicago and Toronto specify point-supported glass systems through design-assist contracts with envelope consultants. Early installer lock-in compresses competitive bidding windows.
- Industrial:Distribution center and manufacturing facility operators retrofit existing structures with aluminum guardrail systems to meet OSHA Walking-Working Surfaces standards. Roof-edge fall protection represents the fastest-expanding subsegment.
- Institutional:University and healthcare campus construction in Texas and North Carolina specifies tamper-resistant stainless steel systems with enhanced durability for high-traffic public environments.
Commercial projects generate the highest specification-grade revenue per linear foot; industrial retrofits are climbing fastest in unit volume.
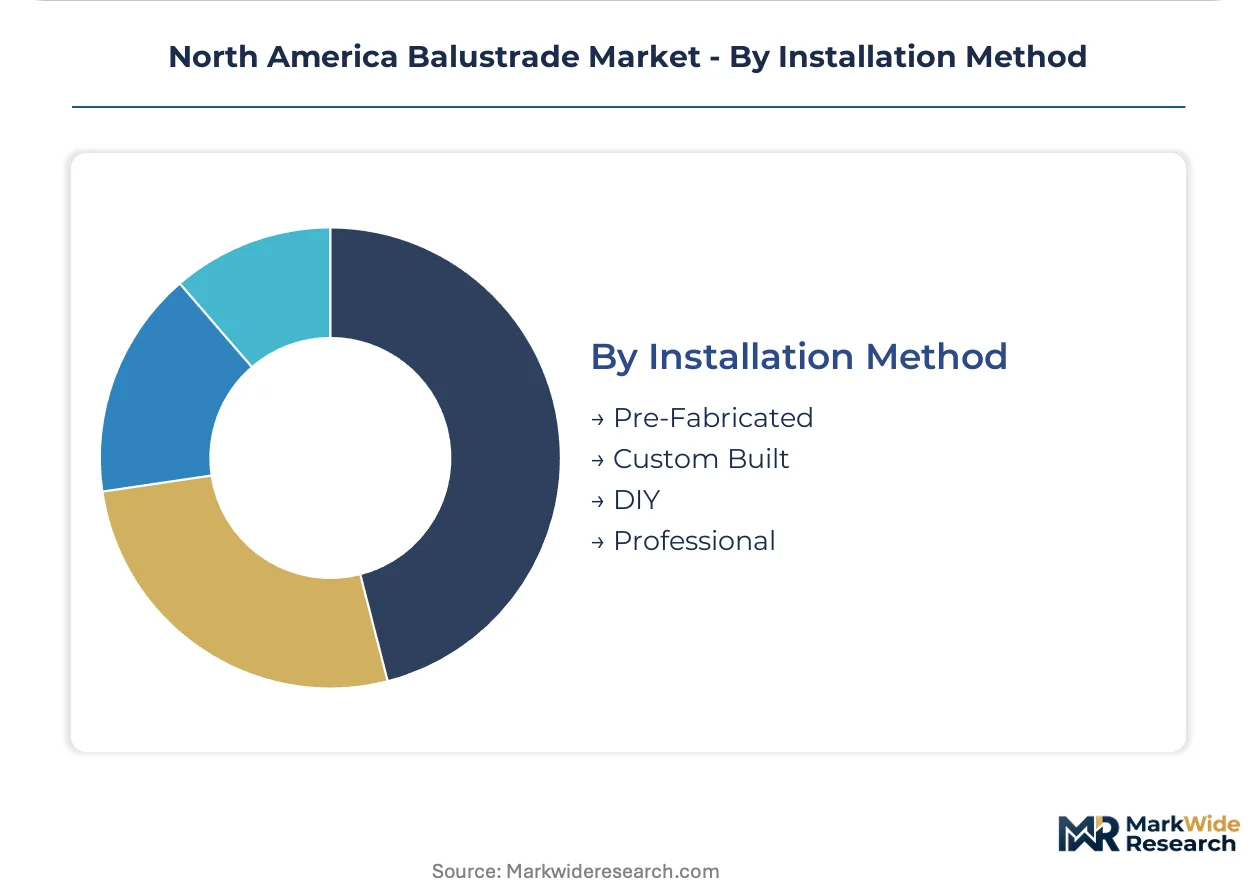
Installation Method:
Installation segmentation separates certified tradeswork requiring structural engineering oversight from consumer-accessible assembly.
- Pre-Fabricated:Factory-assembled panel systems arrive with integrated hardware and engineering documentation, reducing field labor hours for commercial contractors. This method dominates aluminum and glass specifications in high-rise construction.
- Custom Built:Site-measured and field-fabricated systems serve irregular geometries and historic restorations where standard modules fail. Skilled ironworkers and glaziers command wage premiums that inflate total installed cost.
- DIY:Pressure-treated wood and basic aluminum rail kits available through home center retail serve deck and porch projects in suburban markets. Code compliance responsibility shifts to homeowner permits and inspections.
- Professional:Certified glazing contractors and specialized railing installers handle structural glass and cable tensioning systems. Trade certification requirements in California and British Columbia constrain labor supply.
Professional installation commands the premium tier; pre-fabricated systems are gaining share fastest through speed-to-completion advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in the United States while Canadian demand relies heavily on cross-border supply chains. Mexico's construction sector imports premium systems from both neighbors. Regional code harmonization remains incomplete despite integrated building product trade flows.
United States
California's luxury multifamily towers and Florida's waterfront estates drive specification-grade glass demand. OSHA's Walking-Working Surfaces standards mandate retrofits across Illinois and Ohio warehouse districts. Dallas-Fort Worth and Austin construction corridors outpace local installer capacity.
Canada
Ontario and British Columbia enforce seismic-load testing that excludes many U.S.-certified glass systems. Health Canada building code harmonization efforts with NFPA standards remain stalled. Toronto's high-rise residential pipeline pulls premium aluminum systems through cross-border distribution channels.
Mexico
Monterrey and Mexico City commercial construction imports modular aluminum systems from Texas fabricators. Local building codes lack equivalent IBC load certification requirements. Baja California residential developments source glass balustrades through San Diego-based installers.
North America Balustrade Market Competitive Environment
Capital-heavy producers compete with asset-light designers across specification-grade and commodity tiers. The market structures around three archetypes: integrated glass fabricators with captive engineering capabilities, specialized cable-rail installers with coastal maintenance contracts, and aluminum extruders serving commercial retrofit volume. Consolidation pressures mount as code compliance costs rise and certified glazier shortages constrain installation capacity. Strategic moves center on design-assist contracting relationships with envelope consultants and backward integration into aluminum extrusion.
Among cable-rail specialists, Feeney Inc. exemplifies the premium coastal retrofit archetype through maintenance-contract bundling. Q-railing occupies a position within specification-grade architectural channels. C.R. Laurence Co., Inc. anchors distribution density across Western U.S. glazing contractor networks.
| Leading Market Players |
|---|
| Q-railing |
| Balcony Systems |
| Abbey Glass |
| Atlantis Rail |
| Feeney Inc. |
| VIVA Railings |
| Tractel Ltd. |
| Stairways, Inc. |
| C.R. Laurence Co., Inc. |
| Others |
Value Chain & Pricing Dynamics
IBC Section 1607.8 recertification mandates for glass balustrade systems are forcing manufacturers to absorb engineering validation costs or pass them downstream, compressing margin pools for mid-tier fabricators lacking captive structural testing facilities.
Pricing Analysis
Cost-down pressure on specification-grade glass systems accelerates as California and Florida developers consolidate procurement through design-assist contracts with envelope consultants. Three-tier pricing structure across premium, standard, and economy levels separates laminated tempered systems with in-house IBC certification from import-reliant competitors and commodity aluminum rail kits. Price differentiation traces to certification grade and after-sales service bundling. Commercial atrium projects show least price sensitivity; suburban residential retrofits through home center channels exhibit highest.
Supply Chain Analysis
6063-T6 aluminum extrusion supply rests on domestic U.S. producers and Mexican maquiladora operations near the Texas border, with 316 stainless steel cable and laminated glass interlayers drawing from South Korean and German specialty manufacturers. Raw material dependencies span aluminum billet, PVB interlayer film, and tensioning hardware. Tariff exposure on Chinese-sourced tempered glass panels creates supply chain risk. Distribution runs through regional glazing contractor networks and architectural specification channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OSHA's Walking-Working Surfaces standards erect a cost-of-compliance barrier that rewards incumbents with certified installation capacity and engineering documentation infrastructure.
For Market Incumbents: Cement design-assist relationships with Manhattan and Chicago envelope consultants before general contractor selection locks specification authority. Acquire certified glazing subcontractors in Texas Sun Belt corridors where Austin and Dallas-Fort Worth demand outpaces local installer supply. Channel control over specification-grade distribution networks defends against aluminum extruders pursuing backward integration into installation services.
For New Entrants and Emerging Players: NFPA-CSA harmonization efforts in Canada open a window for U.S.-certified fabricators to cross-sell into Toronto's high-rise residential pipeline without dual-certification cost burdens. Target industrial retrofit segments in Illinois and Ohio warehouse districts where OSHA compliance deadlines compress bidding windows and favor speed-to-installation over brand recognition. Bundle maintenance-service contracts with initial installation to capture recurring revenue streams.
For Investors and Strategic Acquirers: Re-rating potential sits with regional glazing contractors possessing captive engineering capabilities given IBC recertification cost escalation filtering out undercapitalized competitors. Long-term viability favors asset-light designers with maintenance-contract books over commodity aluminum extruders facing input volatility. Watch glazier apprenticeship program expansion in California and British Columbia as inflection indicator for installation capacity constraints easing.
| Strategic Initiative | Industry Significance |
|---|---|
| Design-Assist Contracting | Early installer lock-in with envelope consultants compresses competitive bidding windows for commodity alternatives. |
| Maintenance-Service Bundling | Recurring revenue from 15-25 year gasket and hardware replacement cycles stabilizes cash flow volatility. |
| Backward Integration into Extrusion | In-house 6063-T6 production insulates margin pools from aluminum pricing volatility on fixed-price contracts. |
| Cross-Border Certification Investment | Dual IBC and CSA seismic-load testing unlocks Toronto and Vancouver specification-grade project access. |
| Glazier Apprenticeship Pipeline Development | Certified technician supply expansion alleviates installation bottlenecks constraining revenue recognition timing. |
Study Parameters
Document review covered IBC code cycle documentation, OSHA regulatory filings, and provincial building code harmonization records, complemented by interviews with glazing contractors, architectural envelope consultants, and aluminum extrusion procurement leads. Secondary validation drew from customs trade data, SEC 10-K disclosures of building product manufacturers, and construction permit databases. Bottom-up project pipeline analysis triangulated against top-down material consumption estimates.
Segmented outputs across material type, product design, end user, and installation method dimensions fed into analytical framework projecting adoption trajectories across the analysis window. CAGRs derived from regression against construction spending indices, code adoption timelines, and regional permit velocity. Industry-specific inputs included glazier wage data and laminated glass import volumes.
The model assumes a particular technology adoption path; alternative pathways for robotic glass-cutting automation displacing field-fabricated custom work would alter the outlook. Forecasts reflect documented assumptions on code cycle adoption rates and trade certification program expansion. A small set of triggers—seismic-code harmonization progress, aluminum tariff policy shifts, and glazier union apprenticeship scaling—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
I-Joist Market
Building & Construction Materials
Building and Construction Plastic Fasteners Market
Building & Construction Materials
Tile Grout Market
Building & Construction Materials
China Marble Market
Building & Construction Materials
Ceiling Tiles Market
Building & Construction Materials
Asia-Pacific Oriented Strand Board Market
Building & Construction Materials
Insulating Glass Window Market
Building & Construction Materials
Italy Oriented Strand Board Market
Building & Construction Materials
Urethane Concrete Sealer Market
Building & Construction Materials
Europe Green Buildings Market
Building & Construction Materials
Russia Ceramic Tiles Market
Building & Construction Materials
Italy Prefab Wood Buildings Market
Building & Construction Materials
Europe AAC Blocks and Panels Market
Building & Construction Materials
Europe Timber Construction Connectors Market
Building & Construction Materials
Door Canopy Market
Building & Construction Materials
Point Supported Glass Curtain Wall Market