
 Acoustic Insulation Market | 2026-2036
Acoustic Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Acoustic Insulation Market Analysis
Market Context
China is narrowing its gap with Western producers through expanded basalt fiber capacity in Shandong and Hebei provinces. Saint-Gobain leverages integrated glass wool manufacturing across four continents to sustain cost discipline in commercial projects. ROCKWOOL International A/S anchors its position through captive stone wool production and closed-loop recycling systems. Knauf Insulation competes aggressively on lightweight gypsum-foam composites for residential wall assemblies.
Technical Definition and Segment Structure
Acoustic insulation encompasses engineered materials engineered to attenuate sound transmission through absorption, damping, or mass-barrier mechanisms, typically quantified by Noise Reduction Coefficient or Sound Transmission Class ratings. Mineral wool dominates industrial and commercial specifications due to fire resistance ratings reaching 1,200°C, while foam systems penetrate residential retrofits where weight and cavity depth constrain alternatives. Automotive application represents the fastest-expanding segment as electric vehicle platforms eliminate engine masking noise and expose road and wind intrusion. Mass loaded vinyl occupies a premium niche in recording studios and cinema construction where broadband frequency control commands specification priority.
Regulatory Environment
EPA guidelines on formaldehyde emissions from fiberglass binders and OSHA permissible exposure limits for respirable crystalline silica constrain mineral wool processing and jobsite handling protocols across the United States. REACH restrictions on flame retardant chemistries and the EU Green Deal building renovation targets collectively redirect European specification toward bio-based and recycled-content alternatives. Stakeholders must monitor evolving code harmonization between ASHRAE, ISO, and national building institutes to anticipate which test methodologies will govern cross-border product approvals.
Market Dynamics
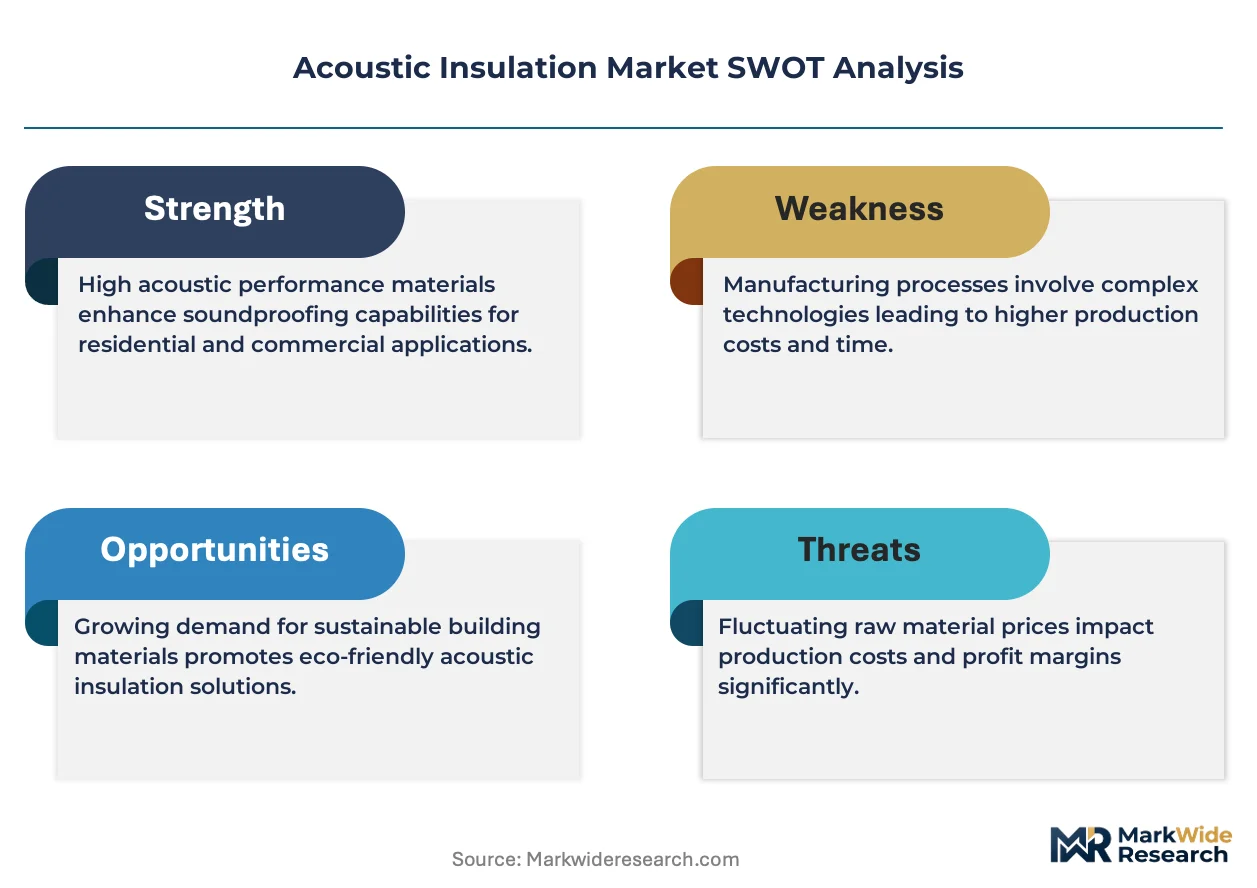
Building energy code harmonization across Germany, France, and the United Kingdom is compressing specification timelines and forcing material upgrades toward higher-density mineral wool and engineered foam systems in multi-family residential construction.
Growth Catalysts
- EU Green Deal renovation targets:Mandatory building retrofit quotas across European member states are accelerating specification of bio-based acoustic materials in existing residential stock.
- Electric vehicle platform proliferation:Automotive OEMs are specifying multi-layer damping composites to address road and wind noise intrusion as engine masking disappears.
- Urban infill density:High-rise corridors in New York, Chicago, and Los Angeles are generating overlapping retrofit and new construction demand for airborne and impact sound control.
Market Restraints
- Respirable crystalline silica exposure limits:OSHA permissible exposure constraints are raising mineral wool processing costs and jobsite handling complexity across United States commercial projects.
- Basalt fiber supply concentration:Expanded capacity in Shandong and Hebei provinces is creating geographic dependency risk for stone wool raw material sourcing.
- Mass loaded vinyl substitution ceiling:Premium pricing and installation labor intensity constrain penetration beyond recording studios and cinema construction niches.
Strategic Opportunities
- REACH flame retardant restrictions:Redirected European specification toward recycled-content and bio-based alternatives creates white space for non-halogenated binder technologies.
- Lightweight gypsum-foam composites:Residential wall assembly applications remain underpenetrated relative to mineral wool in North American single-family construction.
- ASHRAE-ISO code harmonization:Converging test methodologies for Sound Transmission Class ratings will streamline cross-border product approval processes for multinational suppliers.
Industry Challenges
- Certification timeline compression:Tightening building code cycles in France and the United Kingdom are outstripping laboratory testing capacity for Noise Reduction Coefficient validation.
- Closed-loop recycling integration:Captive stone wool recovery systems require significant capital deployment and operational reconfiguration for established mineral wool producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acoustic Insulation Market |
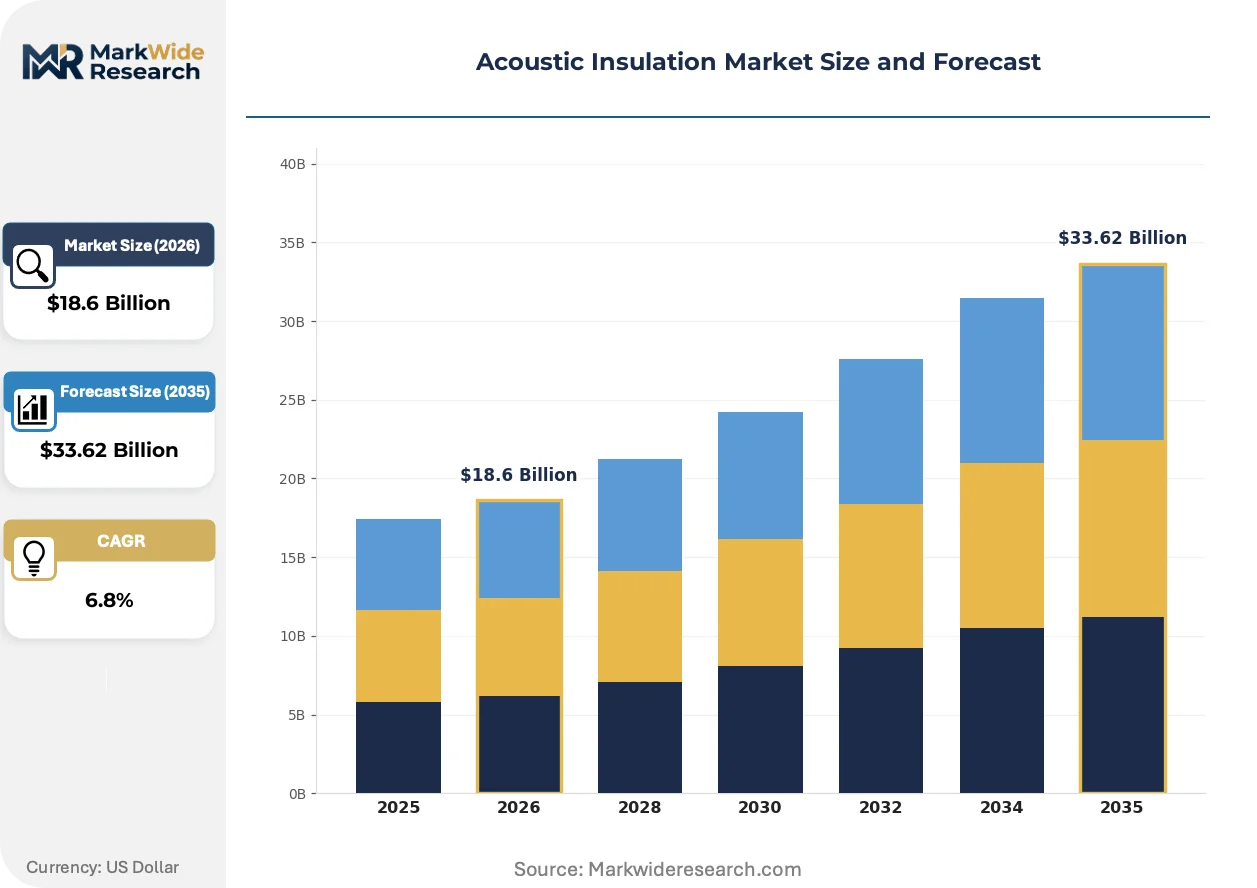
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $33.62 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam, Fiberglass, Mineral Wool, Mass Loaded Vinyl Application: Residential, Commercial, Industrial, Automotive End User: Contractors, Architects, Homeowners, Builders Installation Method: Wall, Ceiling, Flooring, Acoustic Panels |
| Companies Covered | Saint-Gobain, ROCKWOOL International A/S, Knauf Insulation, Owens Corning, BASF SE, Kingspan Group, Johns Manville, Armacell International, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acoustic Insulation Market Emerging Trajectories
Computational acoustic modeling and advanced manufacturing are converging to compress product development cycles and enable application-specific material tuning previously constrained by standardized production runs.
Digital twin simulation software is virtualizing the traditional physical prototyping phase for acoustic barrier design. Automotive Tier-1 suppliers are adopting cloud-based predictive modeling to optimize multi-layer composite stacking sequences before physical validation. This capability is virtualizing the iterative testing bottleneck that previously extended electric vehicle NVH development programs by months.
REACH restrictions on halogenated flame retardants are redirecting European specification toward phosphorus-based and mineral hydrate binder systems. Industrial consequence includes reformulation costs and supply chain requalification for mineral wool manufacturers serving commercial building markets. Germany and France are experiencing the most acute specification disruption as national building codes tighten ahead of EU-wide harmonization deadlines.
Specification authority is migrating from general contractors to specialized acoustic consultants as project complexity increases. Large-scale mixed-use developments in New York and Los Angeles are engaging independent acoustic engineers during schematic design rather than delegated design phases. This behavioral shift compresses material selection windows and elevates performance-certified products over commodity alternatives in high-stakes urban infill projects.
Acoustic Insulation Market Segmentation
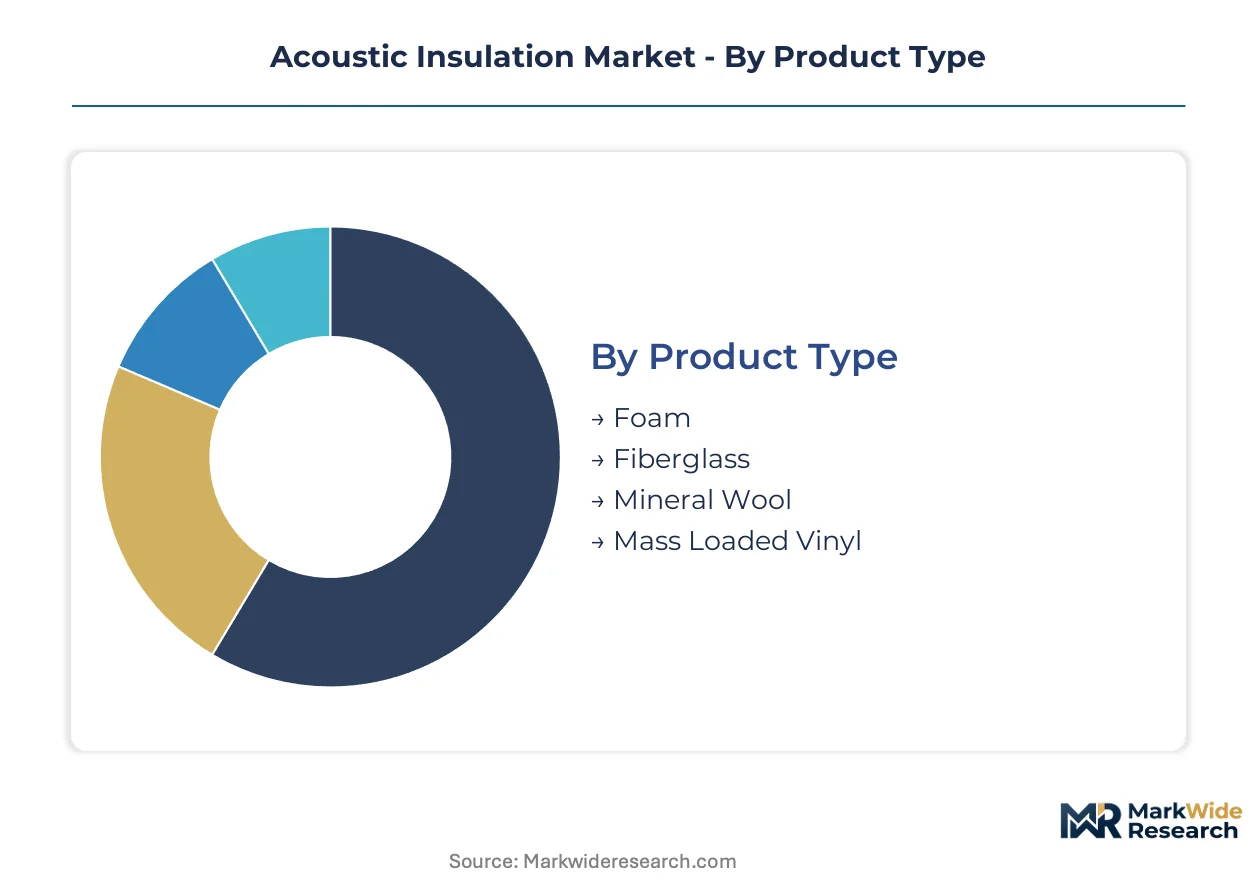
Segmentation in acoustic insulation reveals how material specifications diverge across fire safety requirements, weight constraints, and installation complexity. Contractors, architects, and builders each drive distinct procurement patterns based on project phase authority and performance certification priorities.
Product Type:
After-sales service intensity varies sharply across product categories, with mineral wool demanding specialized handling protocols and foam systems requiring applicator training networks.
- Mineral Wool:Engineered from spun basalt or slag fibers with density gradients optimized for broadband absorption. Demand concentrates in German and French multi-family residential towers where building energy codes mandate 1,200°C fire resistance ratings alongside airborne sound control.
- Foam:Lightweight polyurethane or melamine formulations suited to cavity-constrained retrofits. Specification is accelerating in Los Angeles and Chicago high-rise corridors where weight limits and installation speed override fire rating priorities in residential wall assemblies.
- Fiberglass:Glass fiber binders subject to EPA formaldehyde emission guidelines, dominant in cost-sensitive commercial projects across the United States.
- Mass Loaded Vinyl:Dense polymer-barrier composites for broadband frequency damping, confined to premium recording studios and cinema construction niches due to labor-intensive installation.
Mineral wool holds the largest share; momentum sits with foam.
Application:
Cost tier stratification separates specification authority, with industrial and automotive applications commanding premium multi-layer composites while residential segments compete on installed cost per square meter.
- Automotive:Multi-layer damping composites specified by OEMs to address road and wind noise intrusion as electric vehicle platforms eliminate engine masking. German and Japanese automotive suppliers are expanding NVH engineering capacity fastest.
- Residential:Airborne and impact sound control for multi-family construction, concentrated in New York urban infill zones where retrofit obligations overlap new construction timelines.
- Commercial:Open-plan office and hospitality specifications prioritizing speech privacy, governed by ASHRAE and ISO test methodology harmonization efforts.
- Industrial:Heavy machinery enclosures and process noise containment, concentrated in manufacturing belts of the United States and Germany.
Residential commands volume leadership; automotive is climbing the fastest.
End User:
Customer type determines procurement timing, with architects influencing schematic design specifications while contractors control value-engineering substitutions during construction documentation.
- Architects:Performance-certified product specification during schematic design phases, increasingly prevalent in large-scale mixed-use developments across New York and Los Angeles where independent acoustic consultants command authority.
- Contractors:Material selection compressed by tightening building code cycles in France and the United Kingdom, forcing rapid substitution decisions between mineral wool and engineered foam systems.
- Builders:Volume procurement for single-family residential tracts, concentrated in North American markets where lightweight gypsum-foam composites compete against mineral wool on labor cost.
- Homeowners:Retrofit demand triggered by tenant complaints in existing multi-family stock, concentrated in urban infill corridors with overlapping code compliance deadlines.
Contractors hold the largest share; momentum sits with architects.
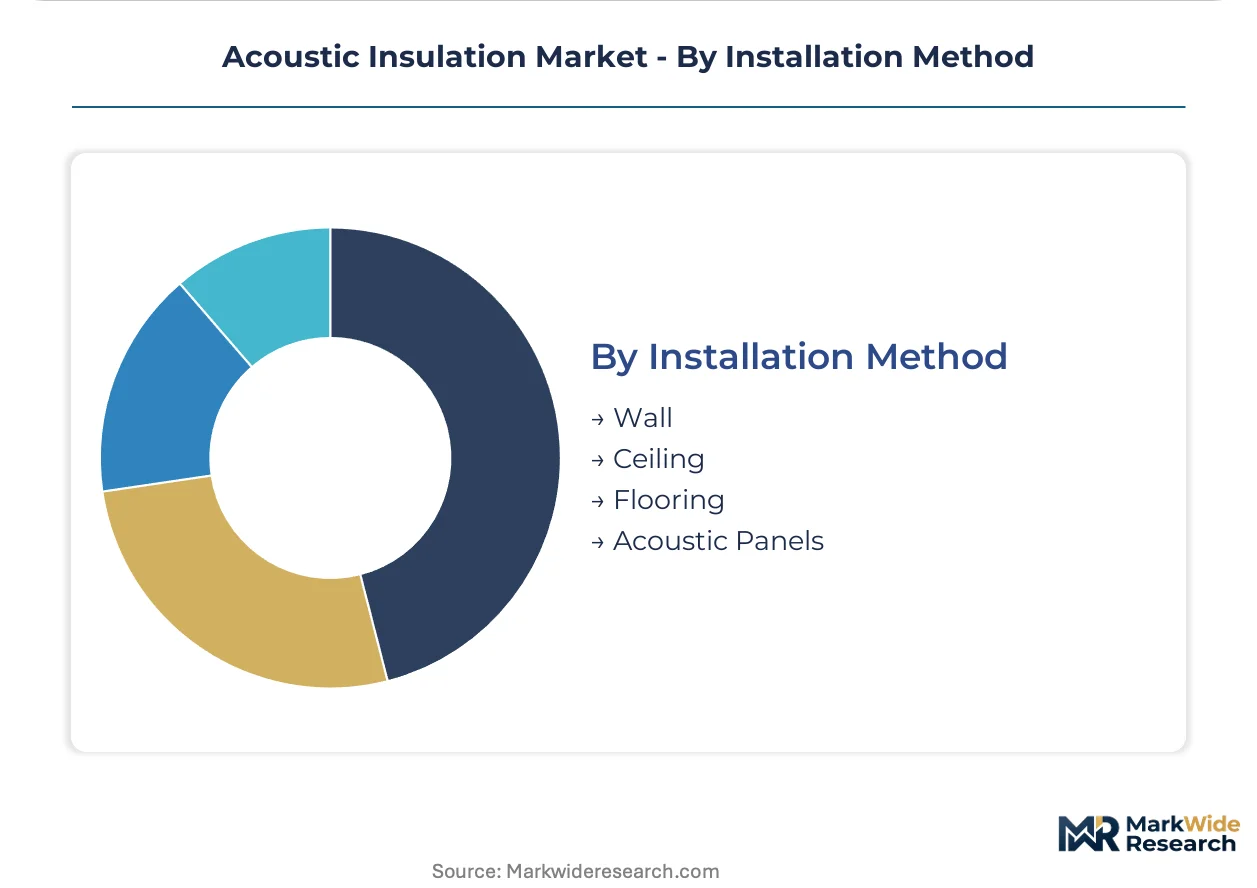
Installation Method:
Volume concentration tracks building typology, with wall and ceiling systems dominating multi-family residential while flooring specifications accelerate under impact sound regulations.
- Wall:Cavity-fill and surface-mounted systems for airborne transmission control, dominant in European residential retrofit programs under EU Green Deal renovation targets.
- Flooring:Impact sound insulation mandated by German, French, and United Kingdom building codes for multi-family construction, driving specification of high-density mineral wool underlayments.
- Ceiling:Suspended acoustic tile and direct-applied systems for commercial open-plan environments, concentrated in United States office construction.
- Acoustic Panels:Modular absorption systems for retrofit flexibility, gaining specification in cinema and recording studio construction where broadband frequency control commands priority.
Wall installations hold the largest share; flooring is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Basalt fiber production clusters in Shandong and Hebei provinces are reshaping raw material sourcing patterns for stone wool manufacturers worldwide. Western European producers maintain specification authority through captive recycling systems and fire-rated product portfolios. Demand generation concentrates in urban corridors where building code tightening overlaps with high-density residential construction timelines.
United States
Retrofit obligations in New York, Chicago, and Los Angeles high-rise corridors are overlapping with new construction demand for airborne and impact sound control. OSHA permissible exposure limits for respirable crystalline silica are constraining mineral wool processing costs and jobsite handling protocols. Specification authority is migrating toward specialized acoustic consultants in large-scale mixed-use developments.
Germany
Multi-family residential towers in Berlin, Munich, and Hamburg are mandating stricter airborne and impact sound control under tightening building energy codes. REACH restrictions on halogenated flame retardants are redirecting specification toward phosphorus-based and mineral hydrate binder systems. Basalt fiber capacity expansion in domestic processing facilities is reducing import dependency for stone wool raw materials.
China
Expanded basalt fiber capacity in Shandong and Hebei provinces is narrowing the supply gap with Western mineral wool producers. National dual carbon goals are accelerating closed-loop recycling system adoption among domestic stone wool manufacturers. Yangtze River Delta construction clusters are specifying higher-density mineral wool for commercial high-rise projects.
France
Building renovation targets under the EU Green Deal are accelerating bio-based acoustic material specification in existing Paris and Lyon residential stock. National building codes are tightening ahead of EU-wide harmonization deadlines, compressing certification timelines for Noise Reduction Coefficient validation. Independent acoustic engineers are commanding specification authority earlier in schematic design phases.
United Kingdom
London urban infill zones are generating overlapping retrofit and new construction demand for multi-family residential sound control. Tightening building code cycles are outstripping laboratory testing capacity for product validation. Specification is shifting toward engineered foam systems where weight limits and installation speed override fire rating priorities in high-rise wall assemblies.
Acoustic Insulation Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying raw fiber and binder chemistries. The vendor base stratifies across three tiers: multinational building material conglomerates with captive mineral wool capacity, regional foam system fabricators serving retrofit channels, and specialized mass loaded vinyl producers for premium studio applications. Dominant competitive moves include backward integration into basalt fiber sourcing and technology licensing for phosphorus-based flame retardant binders.
Within the multinational tier, Saint-Gobain and ROCKWOOL International A/S exemplify divergent strategic archetypes. The French conglomerate leverages integrated glass wool manufacturing across four continents to sustain cost discipline in commercial projects. The Danish stone wool specialist anchors its position through captive production and closed-loop recycling systems. Knauf Insulation represents the lightweight composite vector, competing on gypsum-foam systems for residential wall assemblies where labor cost drives specification.
| Leading Market Players |
|---|
| Saint-Gobain |
| ROCKWOOL International A/S |
| Knauf Insulation |
| Owens Corning |
| BASF SE |
| Kingspan Group |
| Johns Manville |
| Armacell International |
| 3M |
| Others |
Supply Flow & Price Mechanics
Shandong-to-Rotterdam basalt fiber freight corridors are transmitting cost volatility from Chinese production clusters into European mineral wool pricing, amplifying the spread between fire-rated premium grades and standard-density alternatives as contractors arbitrage specification authority across code jurisdictions.
Pricing Analysis
REACH flame retardant restrictions dictate the pricing tier structure across European acoustic insulation markets, separating phosphorus-based binder systems at premium levels from legacy halogenated formulations facing phase-out discounts. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with UL fire-rated mineral wool commanding substantial premiums over uncertified foam alternatives. Cost compression in standard-density fiberglass is intensifying because EPA formaldehyde emission compliance adds processing overhead. Residential retrofit contractors exhibit highest price sensitivity, while automotive OEMs prioritize NVH performance over unit cost.
Supply Chain Analysis
Extended payment terms from stone wool manufacturers to Shandong and Hebei basalt fiber processors are stabilizing raw material flows against commodity price swings. Supply concentration rests on China for basalt fiber, Denmark and Germany for captive recycling systems, and the United States for formaldehyde-compliant fiberglass binders. Critical dependencies include spun basalt feedstock, phosphorus-based flame retardant chemistries, and multi-layer damping composites for automotive applications. Single-source vulnerability in Chinese basalt fiber creates geographic concentration risk. Distribution runs through building material distributors for residential channels and direct OEM supply agreements for automotive Tier-1 integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among specialized acoustic consultants in large-scale mixed-use developments, fragmenting procurement authority away from general contractors and elevating performance-certified products over commodity alternatives.
For Market Incumbents: Pre-empt specification authority migration by embedding closed-loop recycling capabilities and captive basalt fiber sourcing before REACH-driven reformulation costs escalate. Threat substitution from bio-based foam alternatives demands rapid phosphorus-based binder certification investment. Backward integration into Shandong basalt fiber capacity anchors raw material cost discipline. For New Entrants and Emerging Players: North American single-family residential wall assemblies remain underpenetrated by lightweight gypsum-foam composites relative to mineral wool dominance. White space concentrates in Los Angeles and Chicago high-rise retrofits where weight-constrained foam systems outcompete fire-rated stone wool on installation speed. Target independent acoustic consultant specification channels during schematic design phases. For Investors and Strategic Acquirers: Regional foam system fabricators with applicator training networks represent the most defensible acquisition archetype against multinational mineral wool consolidation. Long-term viability hinges on EU Green Deal renovation target execution and electric vehicle platform proliferation sustaining automotive NVH demand. Monitor ASHRAE-ISO Sound Transmission Class harmonization progress as cross-border product approval inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Basalt Fiber | Captive Shandong and Hebei sourcing reduces exposure to Chinese export pricing volatility. |
| Phosphorus-Based Binder Certification | REACH-compliant reformulation unlocks premium positioning in German and French residential towers. |
| Closed-Loop Recycling System Deployment | Stone wool recovery infrastructure satisfies EU Green Deal circularity mandates for renovation projects. |
| Automotive NVH Engineering Partnership | Electric vehicle platform integration secures multi-layer composite offtake from German and Japanese OEMs. |
| Acoustic Consultant Channel Development | Schematic design engagement in New York and Los Angeles mixed-use projects captures specification authority. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with acoustic consultants, commercial contractors, mineral wool plant managers, automotive Tier-1 procurement leads, and building code officials across Germany, France, the United Kingdom, and the United States. Secondary validation drew from EPA formaldehyde emission filings, ECHA REACH substance registrations, EU Green Deal renovation target disclosures, OSHA silica exposure enforcement data, and national building institute code harmonization documents. Bottom-up segment sizing triangulated against top-down construction spend and automotive production forecasts.
Calibration against historical mineral wool and foam system price trajectories anchored volume and value outputs across the analysis window. Segmentation dimensions modeled include material type, fire resistance rating tier, installation method, end-use application, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections incorporating electric vehicle platform penetration rates and EU renovation mandate compliance timelines. Industry-specific inputs included Noise Reduction Coefficient certification lag times and basalt fiber capacity expansion schedules.
Practitioners should monitor REACH flame retardant restriction implementation pace and ASHRAE-ISO test methodology convergence for early signals of specification disruption. Forecasts reflect assumptions regarding building code tightening continuity, basalt fiber supply expansion, and electric vehicle NVH engineering prioritization. Macroeconomic construction cycle downturn, regulatory delay, or alternative damping technology breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Stone Veneer Market
Building & Construction Materials
Skirting Board Market
Building & Construction Materials
Europe Building Materials Market
Building & Construction Materials
Building Insulation Materials Market
Building & Construction Materials
Quarry Tiles Market
Building & Construction Materials
Global Floor and Wall Glazed Tiles Market
Building & Construction Materials
Europe Green Buildings Market
Building & Construction Materials
Residential Energy Efficient Windows Market
Building & Construction Materials
Ceiling Tiles Market
Building & Construction Materials
Hydraulic Binder Market
Building & Construction Materials
Tile Grout Market
Building & Construction Materials
Fire Hydrant System Market
Building & Construction Materials
External Wall Insulation Board Market
Building & Construction Materials
Sheet Piling Market
Building & Construction Materials
Sanitary Ware Market
Building & Construction Materials
Decks Market