
 Branched Reinforced Fittings Market | 2026-2036
Branched Reinforced Fittings Market Size, Share, and Industry Trends Forecast 2026-2036
Branched Reinforced Fittings Market Analytics
Utility procurement for water distribution infrastructure is consolidating around fewer integrated contractors with multi-decade maintenance agreements. Victaulic competes through its grooved mechanical joining systems that reduce field welding requirements. Mueller Water Products anchors North American municipal supply through ductile iron and brass fitting portfolios. Bonney Forge Corporation specializes in forged high-pressure branch connections for oil and gas processing facilities.
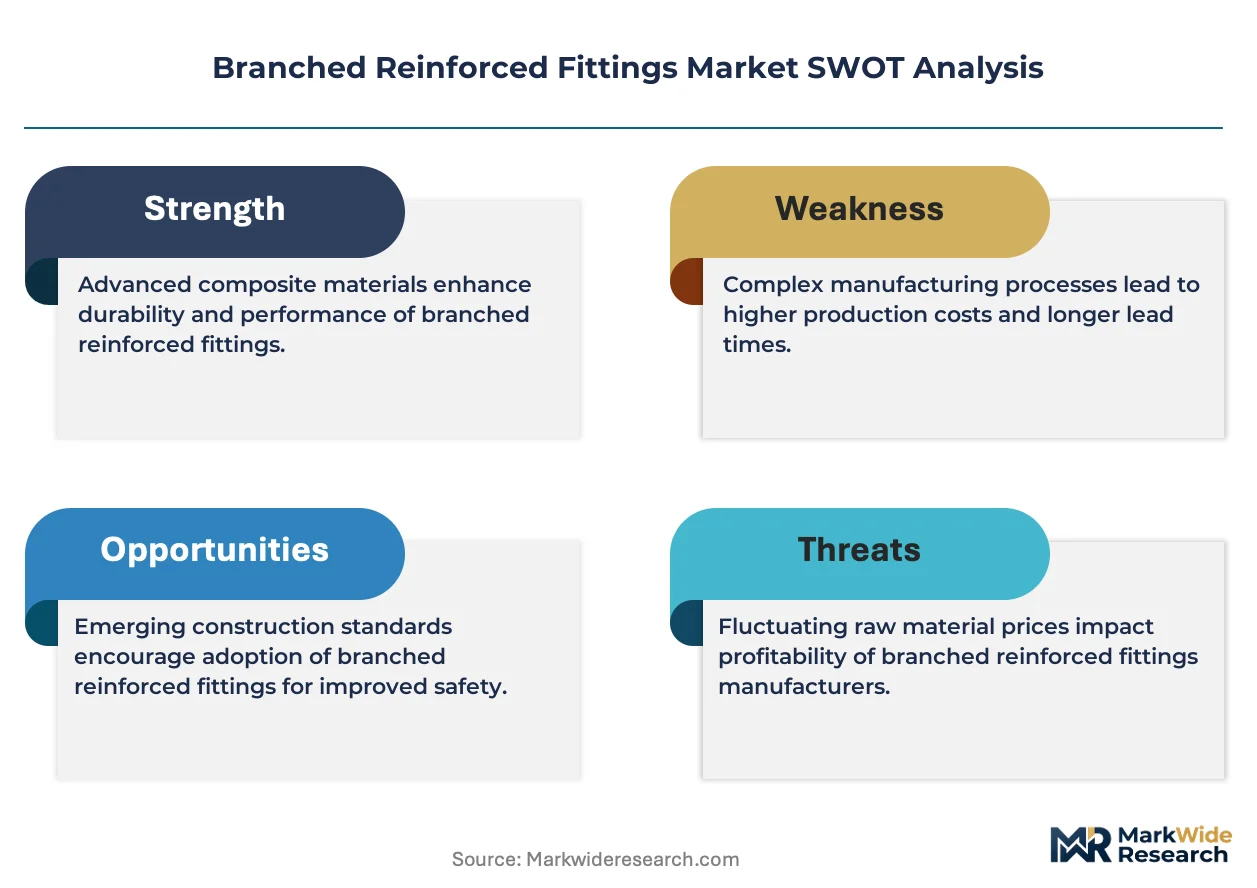
Branched reinforced fittings are pressure-rated piping components that distribute or redirect fluid flow through multiple outlet configurations, typically manufactured through hot forging, investment casting, or injection molding of fiber-reinforced polymers to achieve burst pressures exceeding standard schedule ratings. These components serve critical functions in maintaining structural integrity at junction points where pipelines experience multidirectional stress concentrations. Metal tees dominate heavy industrial applications where thermal cycling and mechanical loading exceed polymer capabilities. Composite crosses represent the fastest-expanding material-format pairing, particularly in marine environments where saltwater corrosion degrades conventional steel alternatives. Plastic elbows maintain mature, cost-driven demand in residential construction and light commercial HVAC systems.
The EPA enforces maximum contaminant levels and lead-free alloy standards under the Safe Drinking Water Act, compelling municipal buyers to specify certified low-lead brass and epoxy-lined ductile iron products. ASTM International and AWWA publish dimensional and performance standards that gate market access for non-compliant imports. ISO 9001 quality management certification has become a baseline procurement filter for tier-one engineering contractors. Stakeholders must monitor evolving PFAS detection protocols and state-level material disclosure mandates that could disqualify certain polymer formulations from potable water applications.
Market Dynamics
Utility infrastructure operators are consolidating procurement around multi-decade service agreements that bundle fitting supply with predictive maintenance, compressing vendor counts and privileging integrated contractors with grooved mechanical joining capabilities over traditional welding-dependent suppliers.
Growth Catalysts
- EPA Lead and Copper Rule Revisions:Accelerated replacement cycles across aging US municipal distribution networks are expanding specification volumes for certified low-lead brass and epoxy-lined ductile iron branch configurations.
- Texas Gulf Coast Petrochemical Corridor Expansion:Refinery capacity additions are driving procurement of high-pressure rated tee and cross assemblies with burst pressure ratings exceeding standard schedule classifications.
- Composite Material Advancement:Fiber-reinforced polymer crosses are displacing conventional steel in marine environments where saltwater corrosion degrades unprotected metal alternatives.
Market Restraints
- Copper and Nickel Price Volatility:Brass alloy feedstock cost swings compress margin predictability for low-lead fitting manufacturers serving municipal water segments.
- ISO 9001 Certification Concentration:Tier-one engineering contractors filter procurement through quality management baselines that exclude non-certified foundries and forge shops.
- Thermal Cycling Limitations:Polymer branch configurations face application ceilings in heavy industrial process lines where mechanical loading and temperature extremes exceed composite capabilities.
Strategic Opportunities
- PFAS Detection Protocol Evolution:State-level material disclosure mandates are creating first-mover advantage for fitting suppliers with fluoropolymer-free polymer formulations certified for potable water contact.
- Marine Infrastructure Renewal:Saltwater-resistant composite crosses are penetrating port authority and offshore platform specifications previously captive to cathodically protected steel.
- Integrated Digital-Mechanical Systems:Grooved joining technologies are converging with sensor-embedded fittings to enable real-time pressure monitoring in smart water networks.
Industry Challenges
- ASME Section IX Welder Certification Scarcity:Field welding requirements for high-pressure forged connections face qualified technician shortages that extend project timelines.
- Multi-Standard Compliance Complexity:Simultaneous ASTM International, AWWA, and ISO dimensional specifications create testing redundancy for export-oriented manufacturers.
- Legacy Ductile Iron Inventory Integration:New epoxy-lined branch configurations must interface with century-old unlined cast iron mains without galvanic degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Branched Reinforced Fittings Market |
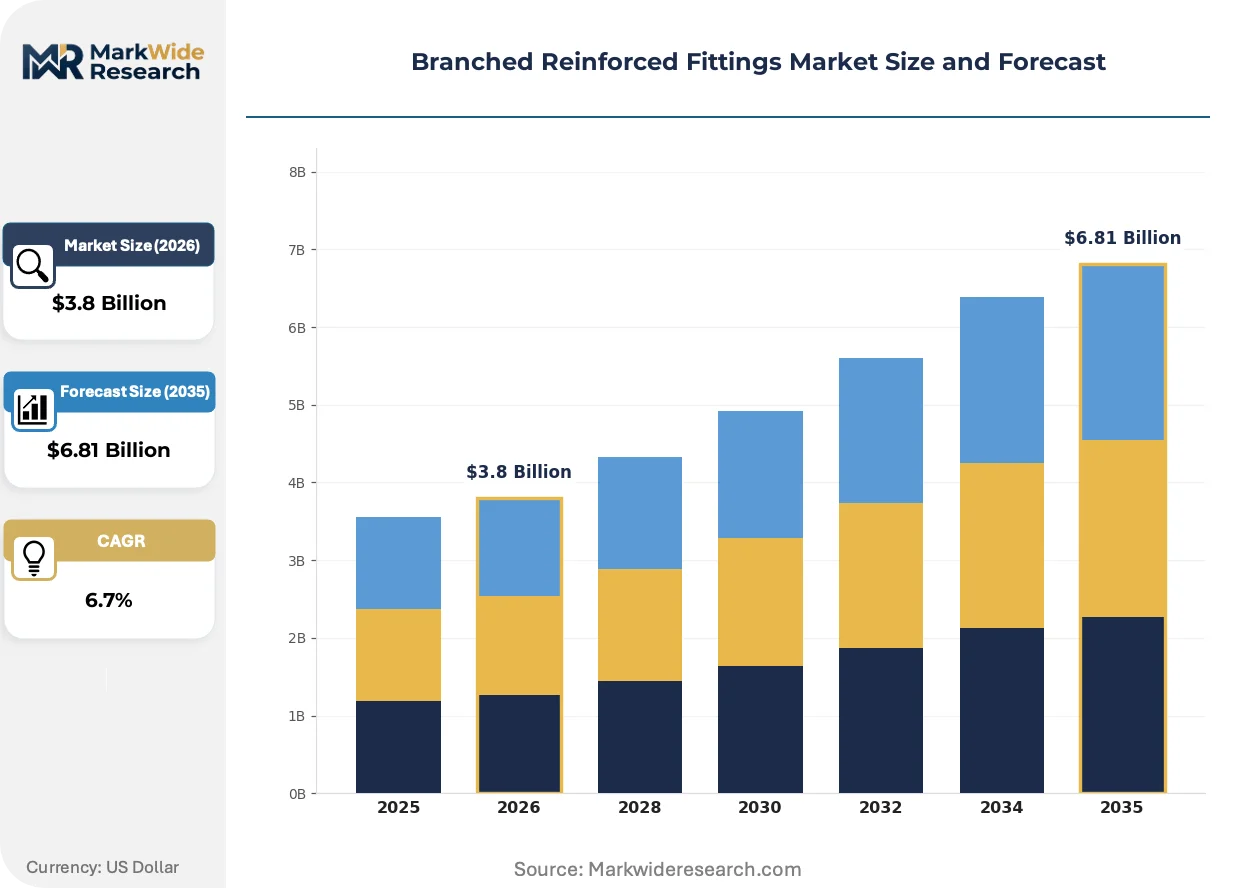
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Elbows, Tees, Crosses, Caps Material: Plastic, Metal, Composite, Rubber Industry Vertical: Construction, Automotive, Aerospace, Marine Installation Type: Above Ground, Underground, Modular, Field |
| Companies Covered | Bonney Forge Corporation, Delcorte Fittings, Victaulic, ASC Engineered Solutions, Mueller Water Products, Parker Hannifin, Swagelok, Saint-Gobain, GF Piping Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Branched Reinforced Fittings Market Evolving Landscape
Material science breakthroughs and regulatory chemistry mandates are redefining acceptable performance thresholds for pressure-rated junction components across water, petrochemical, and marine applications.
Sensor-embedded fiber-reinforced polymer tees are integrating IoT pressure monitoring capabilities directly into branch fitting bodies, eliminating external sensor mounting points. Municipal water authorities in coastal US states are piloting these units for leak detection. The technology is integrating predictive maintenance protocols into asset management systems previously reliant on manual inspection cycles.
REACH restrictions on lead content in drinking water contact materials are tightening alloy composition ceilings for brass fitting imports into European Union member states. Foundries serving this market are reformulating copper-zinc mixtures to comply with evolving ECHA substance thresholds. German municipal utilities are accelerating specification shifts toward silicon-bronze alternatives ahead of anticipated 2026 enforcement milestones.
Integrated procurement platforms are consolidating specification authority within fewer engineering-procurement-construction firms that bundle fitting supply with installation and decades-long maintenance. Traditional distributor networks serving independent contractors are losing specification influence. This concentration is most visible across North American municipal water infrastructure projects where design-build contracts now dominate large-diameter distribution network renewals.
Branched Reinforced Fittings Market Segmentation
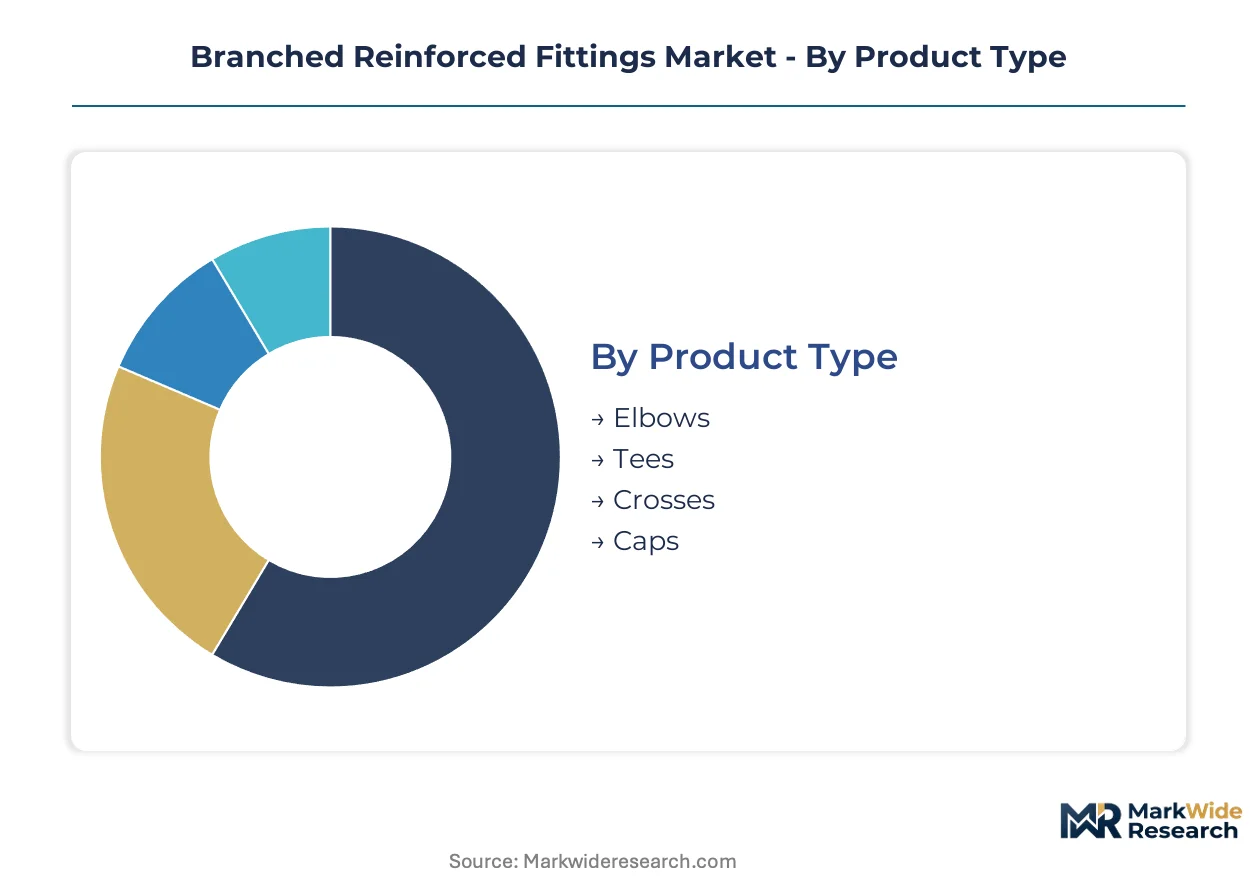
Branched reinforced fittings serve divergent performance requirements across pressure ratings, corrosion exposure, and installation constraints. Segmentation reveals how material science and configuration geometry determine addressable application scope.
Product Type:
Volume concentrates in directional change components while premium applications favor multi-port configurations.
- Elbows:Manufactured through injection molding of fiber-reinforced polymers or hot forging of ductile iron to achieve 90-degree and 45-degree directional changes. Residential construction and light commercial HVAC systems in Texas and Florida specify these for cost-sensitive drainage and ventilation networks where pressure cycling remains moderate.
- Tees:Three-way branch configurations forged from brass alloys or cast in epoxy-lined ductile iron dominate municipal water infrastructure. EPA Lead and Copper Rule revisions are accelerating procurement of certified low-lead brass tees across aging distribution networks in Chicago, Detroit, and Cleveland.
- Crosses:Four-way junction components serve complex distribution manifolds in petrochemical processing.
- Caps:Terminal closure fittings complete pipeline terminations in above-ground industrial installations.
Today's leader: Tees. Tomorrow's challenger: Crosses.
Material:
Cost tiers separate commodity polymers from engineered alloys and advanced composites.
- Metal:Brass, ductile iron, and forged steel deliver burst pressure ratings exceeding standard schedule classifications for high-pressure process lines. Texas Gulf Coast refinery expansions specify these for thermal cycling resistance above 200°C.
- Composite:Fiber-reinforced polymer formulations achieve saltwater corrosion immunity without cathodic protection. Port authorities in California, Washington, and Louisiana are specifying these for marine infrastructure renewal.
- Plastic:PVC and CPVC compounds serve residential plumbing and drainage where pressure and temperature demands remain constrained.
- Rubber:Elastomeric branch configurations provide vibration damping in automotive and select industrial applications.
Metal commands current specification authority. Composite formulations are climbing the fastest.
Industry Vertical:
Application maturity varies sharply between established infrastructure sectors and emerging mobility platforms.
- Construction:Municipal water distribution and commercial building systems generate specification volume for ductile iron and brass configurations. Multi-decade maintenance agreements are consolidating procurement around integrated contractors with grooved mechanical joining capabilities.
- Marine:Saltwater exposure drives fiber-reinforced polymer adoption for offshore platforms and port infrastructure. Composite crosses displace cathodically protected steel in corrosive coastal environments.
- Automotive:Fluid routing systems in electric and internal combustion powertrains specify lightweight polymer and aluminum branch configurations.
- Aerospace:Titanium and high-performance composite tees serve fuel and hydraulic systems with extreme weight and reliability requirements.
Construction anchors present demand. Marine applications are gaining share fastest.
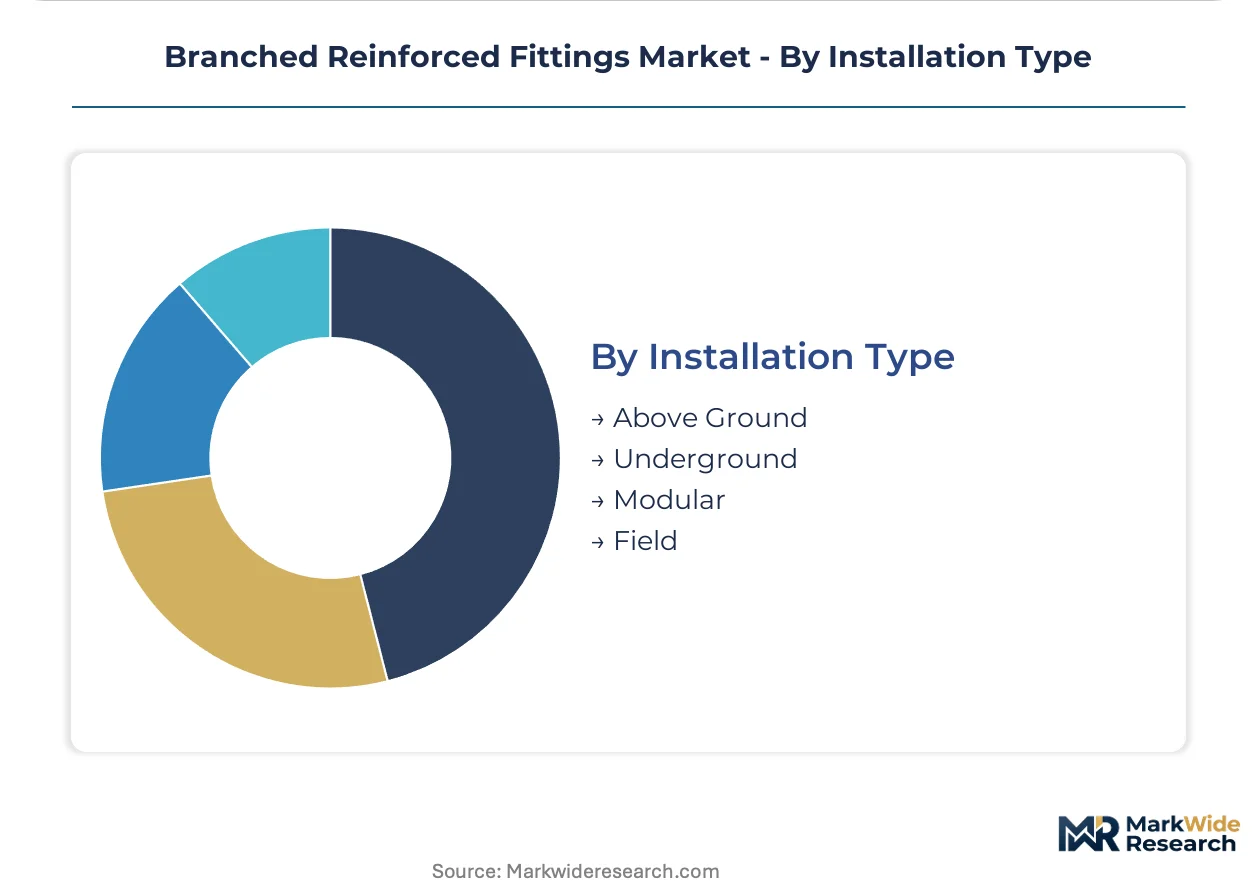
Installation Type:
Customer type separates field-adaptable systems from pre-engineered modular assemblies.
- Underground:Buried municipal water mains require corrosion-resistant materials and leak-tight joint integrity across century-long service horizons. Epoxy-lined ductile iron dominates this specification.
- Above Ground:Industrial process lines and building mechanical systems prioritize inspection accessibility and thermal expansion accommodation.
- Modular:Pre-assembled skidded systems reduce field labor for petrochemical and power generation projects.
- Field:Site-fabricated configurations address custom geometries in retrofit and repair scenarios.
Underground installations lead specification volume. Modular systems present the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled welders and certified pipefitters concentrate in industrial corridors where petrochemical expansion and water infrastructure renewal intersect. Their geographic clustering shapes procurement patterns for high-pressure forged components and corrosion-resistant branch configurations.
United States
The Texas Gulf Coast petrochemical corridor drives demand for ASME-rated tee and cross assemblies as refinery capacity expands. EPA Lead and Copper Rule revisions accelerate municipal replacement cycles in Chicago, Detroit, and Cleveland. Houston-area fabricators supply high-pressure forged connections to downstream processing facilities.
Germany
German municipal utilities are shifting specifications toward silicon-bronze alternatives ahead of anticipated ECHA enforcement milestones. REACH restrictions on lead content in drinking water contact materials tighten alloy composition ceilings for brass imports. Foundries in the Ruhr industrial region are reformulating copper-zinc mixtures to comply with evolving substance thresholds.
China
Chinese infrastructure investment prioritizes ductile iron branch configurations for municipal water distribution networks in the Yangtze River Delta. GB standards and MIIT regulations govern pressure ratings and material certifications for domestic procurement. Shanghai and Jiangsu province manufacturers serve both domestic utility programs and export markets.
India
Indian urban water infrastructure expansion concentrates demand in Maharashtra and Gujarat where BIS certification gates market access for imported fittings. The Jal Jeevan Mission drives rural distribution network deployment requiring cost-optimized polymer and metal branch configurations. Mumbai and Ahmedabad industrial clusters supply forged components to petrochemical facilities.
United Arab Emirates
UAE port authorities and offshore platform operators specify fiber-reinforced polymer crosses for saltwater corrosion immunity without cathodic protection. MOHAP and local emirate regulations govern potable water contact materials in desalination distribution systems. Dubai and Abu Dhabi marine infrastructure projects displace steel with composite alternatives.
Branched Reinforced Fittings Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct pressure-rating and material tiers. The vendor base stratifies between integrated mechanical joining system providers, forged high-pressure connection specialists, and municipal water infrastructure incumbents. Three archetypes dominate: grooved mechanical joining innovators, forged alloy fabricators serving petrochemical demand, and ductile iron foundries anchored in utility procurement. Competitive moves center on multi-decade service agreement bundling and sensor-embedded fitting integration for smart infrastructure.
Among North American suppliers, Victaulic exemplifies the grooved mechanical joining archetype through reduced field welding positioning. Mueller Water Products anchors the municipal infrastructure tier with established ductile iron and brass portfolios. Bonney Forge Corporation occupies the high-pressure forged segment serving oil and gas processing specifications. These three represent divergent strategic postures within a market consolidating around integrated contractors with predictive maintenance capabilities.
| Leading Market Players |
|---|
| Bonney Forge Corporation |
| Delcorte Fittings |
| Victaulic |
| ASC Engineered Solutions |
| Mueller Water Products |
| Parker Hannifin |
| Swagelok |
| Saint-Gobain |
| GF Piping Systems |
| Others |
Value Network & Pricing Analysis
ASME Section IX certified welders and pipefitters concentrate along the Texas Gulf Coast and Houston industrial corridor, where labor-cost differentials between union-certified fabrication shops and non-union contractors drive pricing-tier spreads across high-pressure forged branch configurations.
Pricing Analysis
Bundled multi-decade service agreements that combine fitting supply with predictive maintenance command premium pricing over unbundled transactional procurement. Three-tier pricing structure across premium, standard, and economy levels separates grooved mechanical joining systems from forged high-pressure assemblies from commodity polymer elbows. Pricing pressure stems from copper and nickel feedstock volatility compressing margin predictability for low-lead brass manufacturers. Municipal water authorities exhibit highest price sensitivity due to fixed-rate utility tariffs, while petrochemical operators prioritize burst-pressure certification over unit cost.
Supply Chain Analysis
Regional distribution centers in Houston, Chicago, and Ontario serve as hub-and-spoke nodes for North American utility procurement, with inventory positioning tied to EPA compliance certification timelines. Primary manufacturing concentrates in China, India, and the United States for ductile iron castings, brass forgings, and composite formulations respectively. Raw material dependencies draw from copper-zinc alloy feedstocks, epoxy resin compounds, and fiber-reinforced polymer matrices. Single-source vulnerability runs through specialized foundry capacity for ASME-rated high-pressure components. Distribution runs through integrated engineering-procurement-construction firms consolidating specification authority away from traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through sensor-embedded fitting integration that commands premium pricing in smart water network deployments, offsetting commodity pressure in standard polymer segments.
For Market Incumbents: Hedge against qualified welder scarcity by expanding grooved mechanical joining system penetration that eliminates field welding requirements. Consolidate around multi-decade maintenance agreements with municipal utilities to lock out price-competitive imports lacking ISO 9001 certification. Prioritize backward integration into fiber-reinforced polymer compounding to capture composite margin expansion in marine applications.
For New Entrants and Emerging Players: The price-point gap between premium grooved mechanical systems and economy polymer drainage fittings presents white-space opportunity for mid-tier sensor-embedded configurations. Target port authority marine infrastructure specifications in California and Louisiana where composite crosses displace cathodically protected steel. Pursue direct specification relationships with design-build contractors consolidating procurement authority away from traditional distribution channels.
For Investors and Strategic Acquirers: Integrated engineering-procurement-construction firms are the most active acquirer in this space, seeking captive fitting supply to bundle with installation and maintenance services. Five-to-ten year viability favors targets with fluoropolymer-free polymer formulations positioned ahead of evolving PFAS disclosure mandates. Monitor state-level material certification protocol evolution as the inflection signal for premium-tier specification shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Embedded Fitting Development | IoT pressure monitoring integration enables predictive maintenance contracts with municipal water authorities. |
| Fluoropolymer-Free Polymer Certification | PFAS-compliant formulations secure potable water specification ahead of state disclosure mandates. |
| Grooved Mechanical Joining Expansion | Reduced field welding requirements address ASME Section IX certified welder scarcity in petrochemical corridors. |
| Silicon-Bronze Alloy Transition | REACH-compliant alternatives capture German municipal utility procurement ahead of ECHA enforcement milestones. |
| Composite Marine Infrastructure Positioning | Saltwater-resistant crosses displace steel in UAE port authority and offshore platform specifications. |
Research Methodology
Direct dialogue with municipal utility procurement directors, petrochemical maintenance engineers, foundry operations managers, and grooved mechanical joining system distributors grounded qualitative assessment, cross-referenced with EPA enforcement databases, ASTM International certification registries, AWWA technical standards, and customs trade flow records. Bottom-up demand modeling triangulated against top-down macroeconomic indicators validated volume and value estimates.
Segmentation outputs across product type, material composition, industry vertical, and installation configuration informed the analytical framework over the projection horizon. CAGRs derived from historical replacement cycle analysis, regulatory compliance timeline acceleration, and infrastructure investment program commitments. Modeled inputs incorporated refinery capacity expansion schedules, municipal lead service line replacement mandates, and marine infrastructure renewal appropriations.
Caveats apply where copper and nickel commodity volatility, PFAS detection protocol evolution, or ASME welder certification scarcity could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Europe Construction Repair and Rehabilitation Chemicals Market
Building & Construction Materials
India Manufacturing Market
Building & Construction Materials
Rubber Expansion Joints Market
Building & Construction Materials
Barn Door Hardware Market
Building & Construction Materials
Plastic Decking Market
Building & Construction Materials
Polished Concrete Market
Building & Construction Materials
Welded Wire Mesh Market
Building & Construction Materials
Global Anchors and Grouts Market
Building & Construction Materials
Plastic Door and Window Market
Building & Construction Materials
Acoustic Doors Market
Building & Construction Materials
Calcium Sulphate Board Raised Access Floor Market
Building & Construction Materials
Global Iron and Steel Casting Market
Building & Construction Materials
Building Insulation Materials Market
Building & Construction Materials
Brick Market
Building & Construction Materials
Liquid Applied Roofing Market
Building & Construction Materials
Waterstop Market