
 Exterior Sheathing Market | 2026-2036
Exterior Sheathing Market Size, Share, and Industry Trends Forecast 2026-2036
Exterior Sheathing Market Intelligence
Performance-grade sheathing is bifurcating the Exterior Sheathing Market into specification-sensitive and commodity tiers. Georgia-Pacific leverages its integrated pulp-to-panel supply chain to sustain cost discipline across OSB and plywood lines. LP Building Solutions differentiates through engineered wood products optimized for structural resilience in high-humidity climates. James Hardie Industries anchors the fiber-cement segment with formulations that compete directly with traditional wood-based systems on fire-rating and termite resistance.
Exterior sheathing comprises rigid panel materials applied to structural framing to provide lateral bracing, weather resistance, and substrate for cladding systems; OSB dominates by volume due to engineered strand orientation achieving consistent mechanical properties at lower cost than plywood. Fiber cement leads in commercial and multi-story residential applications where non-combustible ratings and dimensional stability under thermal cycling command specification priority. Gypsum-based exterior sheathing occupies a specialized niche in fire-rated assemblies where moisture-managed formulations extend performance thresholds. Residential construction remains the largest end-user channel, though renovation projects represent the fastest-growing demand pool as energy retrofit programs accelerate envelope replacement cycles.
US builders navigate ICC-ES evaluation reports and APA Product Certification standards for structural panel acceptance, while EPA formaldehyde emission regulations under TSCA Title VI constrain resin chemistry choices in manufactured wood products. The EU Construction Products Regulation and harmonized EN 13986 standards govern market access for imported sheathing in European member states. Stakeholders must monitor evolving embodied-carbon disclosure requirements and biogenic carbon accounting methodologies that will reshape material selection criteria and supplier qualification protocols.
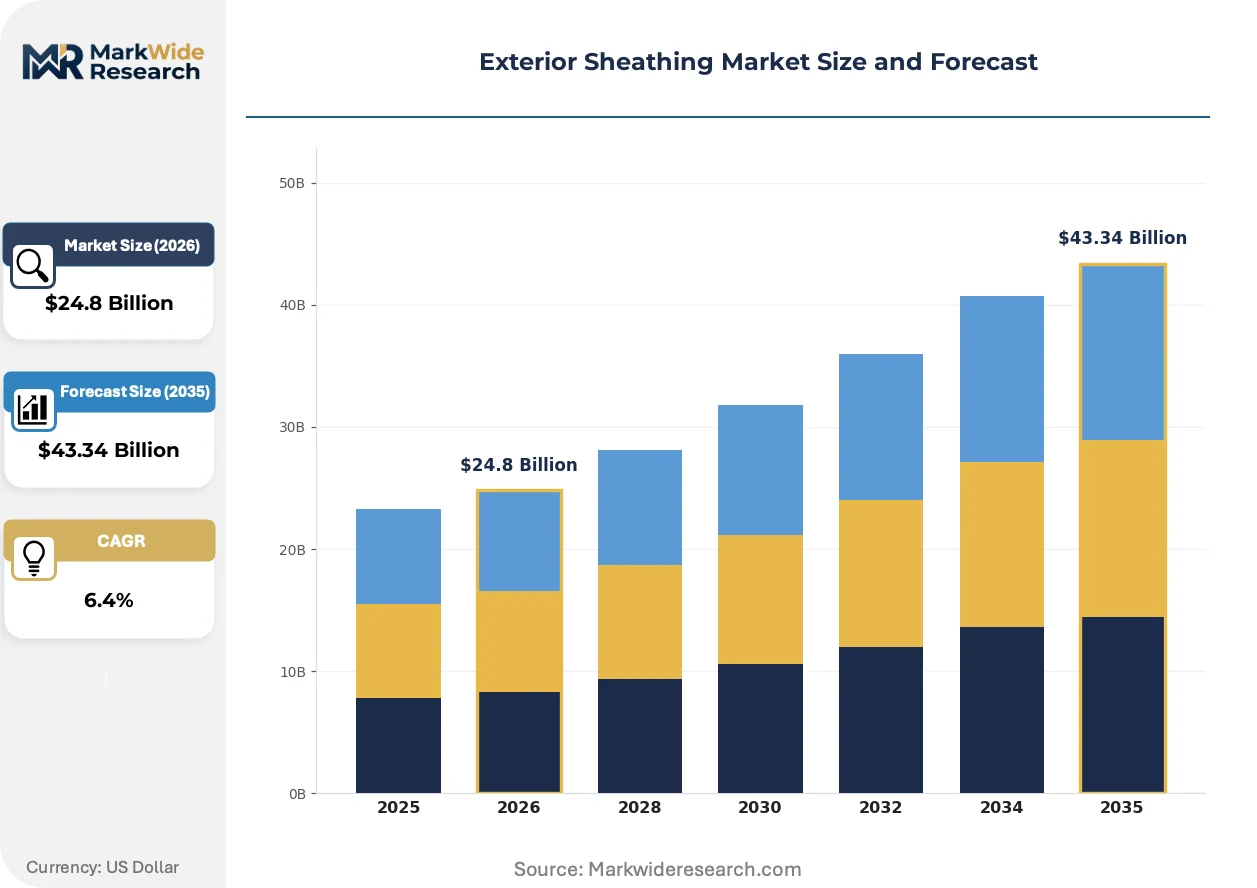
Market Dynamics
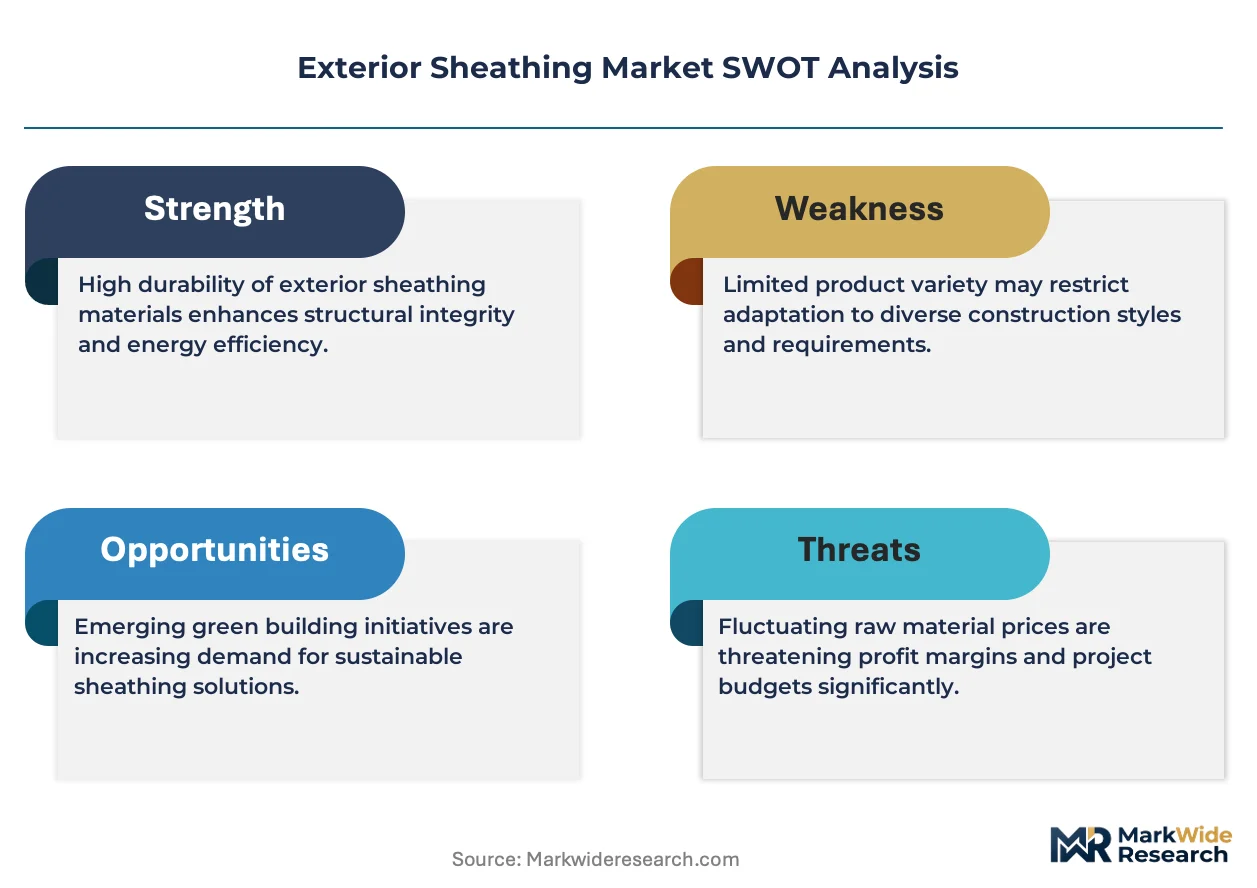
Building envelope performance standards under the International Energy Conservation Code are compressing specification tolerance for structural panels, forcing material selection trade-offs between cost, moisture resistance, and fire ratings that reshape competitive positioning across OSB, plywood, and fiber-cement categories.
Growth Catalysts
- Hurricane-resistant specifications:Elevated wind-load requirements in the southeastern United States drive specification upgrades across multi-family and single-family housing starts, concentrating demand for enhanced OSB panel performance.
- Energy retrofit acceleration:Federal and state-level weatherization programs compress envelope replacement cycles, expanding renovation project volumes as the fastest-growing demand channel for exterior sheathing replacement.
- Moisture-resistant resin chemistry:Advancements in phenol-formaldehyde and isocyanate binder systems extend OSB durability thresholds in high-humidity climates, opening specification access previously reserved for plywood.
Market Restraints
- Softwood supply concentration:Timber input costs fluctuate with British Columbia harvest restrictions and Pacific Northwest lumber capacity constraints, compressing margin stability for North American OSB manufacturers.
- EPA TSCA Title VI compliance burden:Formaldehyde emission caps constrain resin formulation flexibility, raising production complexity for engineered wood products versus naturally low-emitting fiber-cement alternatives.
- Dimensional stability limitations:OSB edge swell under prolonged moisture exposure limits warranty coverage in coastal flood zones, restricting specification in FEMA-designated special flood hazard areas.
Strategic Opportunities
- Mass timber commercial construction:Cross-laminated timber and nail-laminated timber projects in the Pacific Northwest and Northeast create specification pull for structural panels with enhanced fire-rating compatibility.
- Biogenic carbon accounting methodologies:Emerging embodied-carbon disclosure frameworks position wood-based sheathing favorably against mineral-based alternatives in LEED v5 and similar green building certifications.
- Pre-fabricated panelization:Off-site construction channels in the Sun Belt reward sheathing suppliers capable of precision-cut, moisture-managed panel delivery direct to modular assembly facilities.
Industry Challenges
- APA Product Certification timelines:Third-party structural panel verification cycles extend 12-18 months for novel engineered wood formulations, delaying market entry for innovation-focused suppliers.
- Tradeskill gaps in moisture-managed installation:Flashing integration and drainage plane sequencing require specialized training that lags behind code advancement in high-performance envelope assemblies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Exterior Sheathing Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plywood, OSB, Gypsum Board, Fiber Cement Material: Wood, Steel, Cement, Plastic End User: Residential Construction, Commercial Buildings, Industrial Facilities, Renovation Projects Installation Type: Direct Installation, Backed Installation, Prefabricated Systems, Retrofit Solutions |
| Companies Covered | Georgia-Pacific, LP Building Solutions, CertainTeed, James Hardie Industries, Huber Engineered Woods, USG Corporation, DuPont de Nemours, Etex Group, Boise Cascade Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Exterior Sheathing Market Strategic Shifts & Innovations
Material science advancement and procurement model evolution are compressing traditional category boundaries between wood-based, mineral-based, and hybrid sheathing systems. Specification criteria increasingly weight lifecycle carbon, thermal bridging performance, and assembly integration speed alongside first-cost metrics.
High-performance moisture-resistant OSB is bifurcating the residential sheathing market between specification-sensitive coastal zones and commodity interior applications. Custom homebuilders and multi-family developers in hurricane-prone counties specify enhanced edge-seal and resin formulations that command price premiums over standard-grade panels. This technology is compressing plywood's historical dominance in high-humidity structural applications while creating tiered supply contracts based on performance certification rather than volume scale.
EPA formaldehyde emission regulations under TSCA Title VI are constraining resin chemistry choices across manufactured wood products. The industrial consequence is accelerated R&D investment in no-added-formaldehyde binder systems and pre-emptive compliance certification to maintain specification eligibility in federally funded housing projects. Engineered wood producers serving the affordable housing segment face the most acute reformulation pressure, with some shifting capacity toward fiber-cement distribution partnerships to hedge regulatory risk.
Builder procurement patterns are consolidating around direct mill relationships that bypass traditional two-step distribution. Large production homebuilders in Texas and Florida negotiate annual volume commitments with OSB manufacturers for plant-direct delivery to subdivision sites, compressing inventory carrying costs and enabling just-in-time panel sequencing. This channel shift is most visible in the single-family detached segment, where national builders leverage scale to secure specification-grade product at commodity-tier pricing through captive logistics arrangements.
Exterior Sheathing Market Segmentation
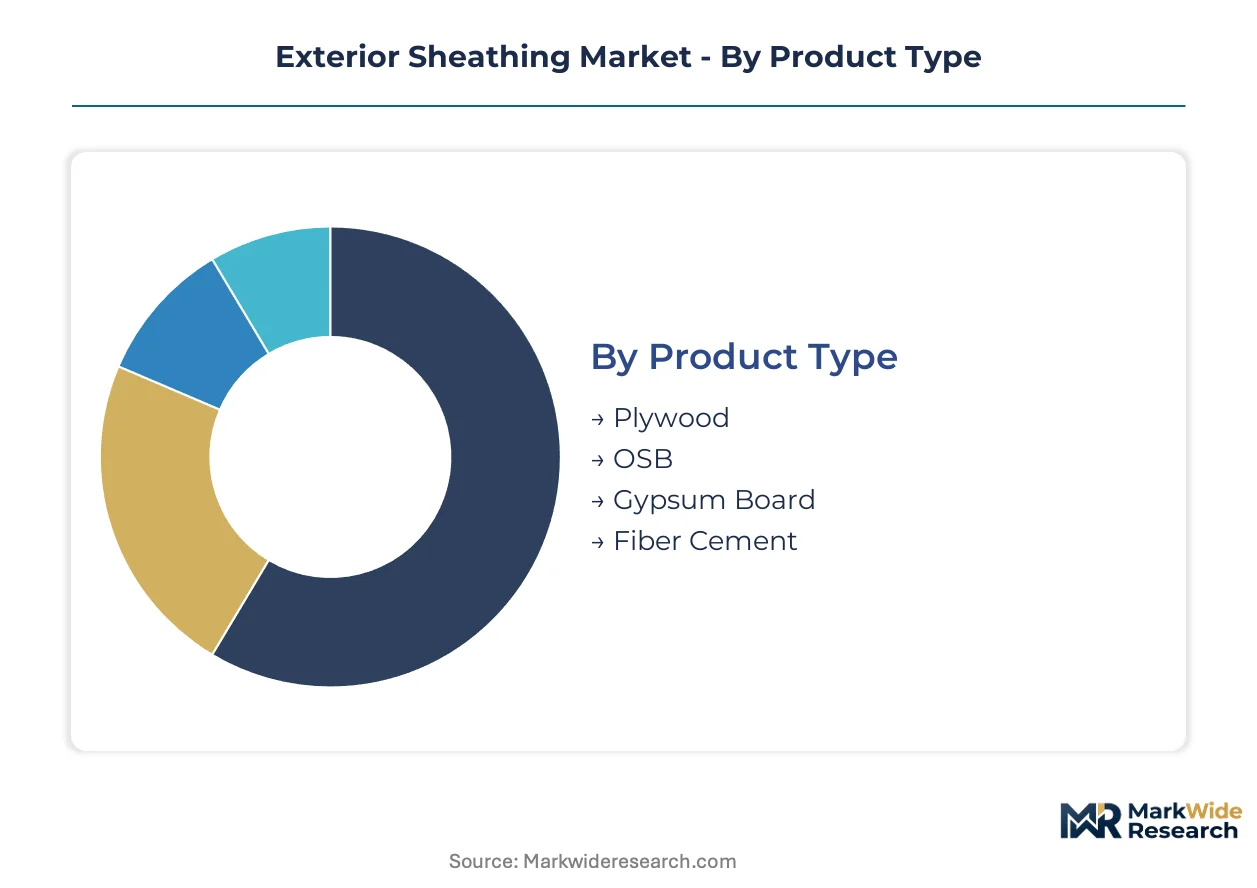
Segmentation in exterior sheathing reveals how material properties, installation methods, and end-use requirements channel demand toward distinct supply configurations. Specification-grade products flow through mill-direct relationships with national builders, while commodity tiers move via traditional distribution networks serving regional contractors.
Product Type:
Channel mix varies sharply by panel technology: OSB and plywood dominate bulk residential procurement through direct manufacturer agreements, while fiber cement and gypsum board concentrate in specification-driven commercial segments served by specialized distributors.
- OSB:Engineered strand orientation delivers consistent mechanical properties at lower fiber input than plywood. Demand concentrates in southeastern United States single-family production housing, where hurricane-resistant edge-seal specifications command mill-direct procurement channels.
- Plywood:Cross-laminated veneer construction provides superior dimensional stability and fastener-holding strength. Multi-family developers in coastal flood zones specify plywood for FEMA-compliant assemblies despite cost premiums over OSB alternatives.
- Gypsum Board:Calcium sulfate core with glass-fiber facing serves fire-rated exterior assemblies in Type I and Type II construction.
- Fiber Cement:Portland cement-cellulose composite offers non-combustible ratings and termite immunity for multi-story residential and commercial cladding substrates.
By volume, OSB leads. By growth pace, fiber cement is ahead.
Material:
Cost tier stratification separates wood-based systems from mineral and synthetic alternatives, with embodied-carbon accounting increasingly influencing material selection in publicly funded projects.
- Wood:Softwood-derived OSB and plywood carry biogenic carbon advantages under emerging LEED v5 methodologies. Residential builders in Pacific Northwest mass timber projects specify structural wood panels for fire-rating compatibility with CLT and NLT systems.
- Cement:Portland-based fiber cement dominates commercial and multi-story residential where non-combustible ratings are mandatory. Specification priority in urban infill projects rewards dimensional stability under thermal cycling.
- Steel:Cold-formed steel sheathing serves specialized industrial and institutional applications requiring electromagnetic shielding or extreme impact resistance.
- Plastic:Polymer-based panels occupy niche retrofit applications where moisture immunity and lightweight handling accelerate installation speed.
Wood commands the volume base. Cement captures the premium tier expansion.
End User:
Customer type determines procurement rhythm: production homebuilders negotiate annual volume commitments, while renovation contractors purchase intermittently through distribution.
- Residential Construction:Single-family and multi-family housing starts drive bulk panel consumption. National builders in Texas and Florida secure specification-grade OSB through captive logistics arrangements bypassing traditional two-step distribution.
- Renovation Projects:Energy retrofit programs compress envelope replacement cycles. Federal and state weatherization initiatives in the southeastern United States create demand spikes for moisture-managed panel replacement in existing housing stock.
- Commercial Buildings:Office, retail, and institutional projects specify fire-rated and impact-resistant assemblies. Design-build contractors prioritize fiber cement and gypsum-based systems for code compliance in Type I construction.
- Industrial Facilities:Manufacturing and warehouse applications require specialized load-bearing and chemical-resistant sheathing configurations.
Residential construction anchors volume. Renovation projects are climbing the fastest.
Installation Type:
Application method shapes supplier capability requirements: field-applied panels demand inventory availability, while prefabricated systems reward precision manufacturing and logistics coordination.
- Prefabricated Systems:Off-site panelization in Sun Belt modular facilities requires moisture-managed, precision-cut sheathing delivered direct to assembly plants. Suppliers with CNC cutting and just-in-time sequencing capabilities capture this expanding channel.
- Direct Installation:Conventional field application of structural panels to framing dominates single-family detached construction. Local lumberyards and pro dealers serve this segment with stock-and-serve inventory models.
- Backed Installation:Rainscreen and drainage plane assemblies with integrated weather-resistant barriers demand specialized flashing integration training that lags behind code advancement.
- Retrofit Solutions:Exterior insulation and finish system overlays on existing structures require thin-profile, moisture-tolerant sheathing adaptations.
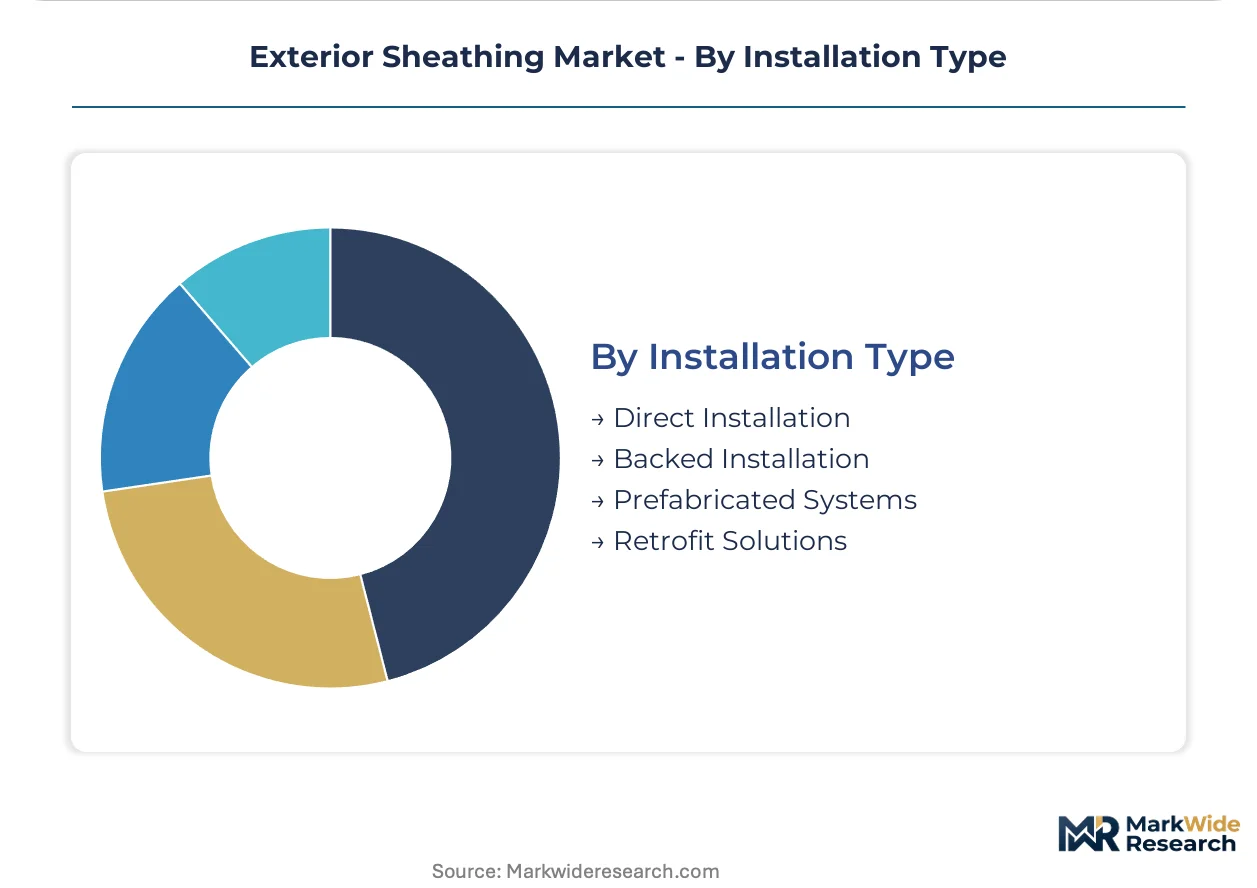
Direct installation holds volume dominance. Prefabricated systems show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSB mill capacity clusters in the southeastern United States and Pacific Northwest, with fiber-cement production concentrating in Australia and European coastal markets. Regional code variations and climate exposure patterns create distinct specification tiers across national markets.
United States
Hurricane-resistant edge-seal specifications in Florida and Gulf Coast counties drive demand for enhanced OSB panels. The International Energy Conservation Code adoption across jurisdictions tightens building envelope performance thresholds. Atlanta and Charlotte serve as distribution hubs for mill-direct procurement channels serving national production homebuilders.
Canada
British Columbia harvest restrictions compress softwood input availability for OSB manufacturers in western provinces. Health Canada and PMRA regulate formaldehyde emission standards for engineered wood products entering residential construction. Prairie province mills in Alberta and Manitoba supply moisture-resistant panels for cross-border shipment to US northern tier states.
Germany
The EU Construction Products Regulation and harmonized EN 13986 standards govern structural panel market access. Mass timber commercial projects in Bavaria and Baden-Württemberg create specification pull for fire-rated wood-based sheathing compatible with CLT systems. Munich-based distributors coordinate pan-European logistics for premium-tier fiber-cement imports.
China
GB standards under MIIT oversight establish structural panel performance benchmarks for domestic and export markets. Dual carbon goals accelerate embodied-carbon disclosure requirements in publicly funded construction projects. Yangtze River Delta manufacturing clusters produce engineered wood products for Southeast Asian export markets.
Australia
Bushfire attack level ratings in New South Wales and Victoria mandate non-combustible sheathing for construction in designated flame zones. The Building Code of Australia updates cycle compression drives specification turnover in residential envelope assemblies. James Hardie Industries anchors fiber-cement production capacity in Western Sydney for Asia-Pacific regional distribution.
Exterior Sheathing Market Key Industry Players
Concentration sits with integrated forest products conglomerates and specialized engineered wood manufacturers. The market structure tiers between volume-scale OSB producers, premium fiber-cement specialists, and regional plywood fabricators. Three archetypes dominate: pulp-to-panel integrated operators, resin-chemistry innovators, and mineral-composite formulators. Capacity expansion and captive supply chain control represent the two dominant competitive moves across the competitive set.
Within the integrated forest products tier, Georgia-Pacific and Boise Cascade Company exemplify backward integration into timber supply and resin production. LP Building Solutions occupies a position as an engineered wood specialist with product formulations optimized for structural resilience. These three entities anchor the competitive landscape through distinct supply chain configurations rather than overlapping market footprints.
| Leading Market Players |
|---|
| Georgia-Pacific |
| LP Building Solutions |
| CertainTeed |
| James Hardie Industries |
| Huber Engineered Woods |
| USG Corporation |
| DuPont de Nemours |
| Etex Group |
| Boise Cascade Company |
| Others |
Cost & Logistics Intelligence
Phenol-formaldehyde resin substitution for traditional urea binders in moisture-resistant OSB simultaneously shifts production geography toward southeastern United States mill clusters and compresses pricing spreads between specification-grade and commodity panels. This chemistry migration concentrates backward integration investments among producers seeking EPA TSCA Title VI compliance while eroding historical plywood premiums in high-humidity structural applications.
Pricing Analysis
EPA TSCA Title VI dictates the pricing tier structure across manufactured wood sheathing by mandating formaldehyde emission caps that stratify products into certified-compliant and legacy formulations. Three-tier pricing structure across premium, standard, and economy levels separates FEMA-compliant edge-seal panels from standard-grade OSB and untreated commodity alternatives. Cost compression in the economy tier is intensifying because resin reformulation expenses concentrate disproportionately in smaller producers lacking captive chemical operations. National production homebuilders exhibit lowest price sensitivity due to mill-direct volume commitments, while regional renovation contractors face acute margin pressure from distribution markups.
Supply Chain Analysis
Container availability constraints on trans-Pacific lanes from Chinese gypsum board manufacturers elevate landed costs for mineral-based alternatives competing in North American fire-rated assemblies. Raw material sourcing draws from British Columbia softwood harvests, Louisiana pine plantations, and Appalachian hardwood residuals for veneer operations. Single-source vulnerability concentrates in phenol supply chains tethered to Gulf Coast petrochemical complexes. Distribution runs through mill-direct channels for national builders and two-step lumberyard networks serving regional contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Building envelope specification platforms are converging around integrated moisture-management and fire-rating interoperability standards that reward suppliers with cross-certified product ecosystems. This platform economics inflection favors manufacturers capable of delivering panel-to-flashing system compatibility rather than discrete commodity supply.
For Market Incumbents: Compound specification lock-in through APA Product Certification pre-emptive investment for next-generation no-added-formaldehyde formulations. Deepen captive resin production capacity in Louisiana and Mississippi to defend margin position against fiber-cement substitution in coastal flood zones. Channel control through direct mill relationships with top-ten national builders remains the priority defensive lever.
For New Entrants and Emerging Players: ICC-ES evaluation report fast-track positions regional plywood fabricators to capture specification access in FEMA-designated special flood hazard areas where OSB warranty limitations create penetrable white space. Target multi-family developers in southeastern United States coastal counties seeking plywood alternatives with enhanced edge-seal performance. Go-to-market execution should emphasize just-in-time sequencing capabilities for prefabricated panelization channels in Texas and Florida Sun Belt markets.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors engineered wood specialists with differentiated resin chemistry and mass timber fire-rating compatibility. Long-term viability over the coming decade hinges on biogenic carbon accounting methodology alignment positioning wood-based systems favorably against mineral alternatives. Acquisition target archetype: mid-scale OSB producers with underutilized southeastern mill capacity and pending APA certification pipelines. The signal to watch is LEED v5 embodied-carbon disclosure adoption velocity in federally funded housing projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Resin Chemistry Reformulation | No-added-formaldehyde binder R&D secures EPA TSCA Title VI compliance eligibility for affordable housing specifications. |
| Mill-Direct Channel Expansion | Captive logistics arrangements with national builders compress inventory carrying costs and enable just-in-time panel sequencing. |
| Mass Timber Certification Investment | Fire-rated panel compatibility with CLT and NLT systems captures specification pull in Pacific Northwest commercial construction. |
| Prefabricated Panelization Partnership | Precision-cut moisture-managed delivery to Sun Belt modular facilities rewards CNC cutting and sequencing capabilities. |
| Biogenic Carbon Accounting Alignment | LEED v5 methodology positioning differentiates wood-based sheathing against fiber-cement in publicly funded projects. |
Research Approach
A spread of perspectives from OSB plant managers, national builder procurement directors, APA certification engineers, distribution channel partners, and residential envelope consultants converged on the working assumptions underlying volume and value estimates. Primary fieldwork combined structured interviews with secondary validation against APA Product Certification databases, EPA TSCA Title VI compliance filings, International Energy Conservation Code adoption tracking, and SEC 10-K disclosures from integrated forest products conglomerates. Bottom-up capacity utilization modeling and top-down construction spend allocation triangulated across the analysis window.
Segmentation dimensions modeled include product type stratification across OSB, plywood, fiber cement, and gypsum-based systems; material tier differentiation by wood, cement, and synthetic alternatives; end-user channel separation between residential construction, renovation projects, and commercial buildings; and installation type distinction across prefabricated systems, direct field application, and retrofit solutions. CAGRs were derived from housing start elasticity modeling and envelope replacement cycle compression under federal weatherization programs. Industry-specific forecast inputs incorporated British Columbia harvest restriction scenarios and hurricane-resistant specification adoption curves in southeastern United States counties.
Decision-makers should treat outputs as directional under assumptions of continued IECC envelope performance tightening and stable softwood input availability; material deviation in timber supply or regulatory acceleration would warrant model refresh. Practitioners should keep alternative scenarios live as biogenic carbon accounting methodologies and mass timber commercial construction penetration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Asia-Pacific Particle Board Market
Building & Construction Materials
Sound Barriers Market
Building & Construction Materials
Metal Grating Market
Building & Construction Materials
Global Raised Access Floor Systems Market
Building & Construction Materials
Laminated Veneer Lumber (LVL) Market
Building & Construction Materials
India Stainless Steel Plumbing Pipes and Fittings Market
Building & Construction Materials
Concrete Protective Liners Market
Building & Construction Materials
Risers Market
Building & Construction Materials
Acoustic Plasterboard Market
Building & Construction Materials
North America Balustrade Market
Building & Construction Materials
Waterproofing Solution Market
Building & Construction Materials
South America Industrial Flooring Market
Building & Construction Materials
US Steel Merchant and Rebar Market
Building & Construction Materials
Oriented Strand Board (OSB) Market
Building & Construction Materials
Tower Bolt Market
Building & Construction Materials
Architectural Membrane Market