
 SBS Waterproofing Membrane Market | 2026-2036
SBS Waterproofing Membrane Market Size, Share, and Industry Trends Forecast 2026-2036
SBS Waterproofing Membrane Market Insights
Commercial roofing is repositioning toward higher-performance assemblies as building owners prioritize lifecycle durability over first cost. Soprema Group leverages its bitumen compounding expertise to dominate European specification channels. Carlisle Companies Inc. sustains manufacturing scale across multiple North American plants, ensuring contractor availability during peak construction seasons. MBTechnology specializes in modified bitumen formulations for extreme climate zones, differentiating through cold-flex performance ratings.
Styrene-butadiene-styrene waterproofing membrane consists of asphalt or bitumen modified with SBS thermoplastic elastomer, typically reinforced with polyester or fiberglass carrier sheets, and manufactured via calendering or extrusion processes to achieve elongation properties exceeding standard APP-modified materials. Its primary purpose is to create flexible, crack-bridging barriers that protect structural substrates from water ingress across temperature cycling conditions. Bitumen-based products occupy the mature volume tier where contractor familiarity and cost predictability anchor specification, while polymeric segments capture premium positioning in chemically aggressive environments. Self-adhered installation methods are gaining specification share among contractors seeking to reduce open-flame permitting complexity and labor coordination costs.
EPA stormwater regulations and the EU Green Deal building renovation requirements are tightening performance thresholds for below-grade and roofing applications, directly shaping membrane thickness and permeability specifications that manufacturers must certify. Germany's KBA and France's ANSM do not regulate this category, but REACH compliance for chemical constituents in polymer modifiers constrains formulation options for European producers. Stakeholders must monitor how evolving carbon disclosure rules under CSRD reshape material sourcing decisions and supplier qualification criteria across major specification markets.
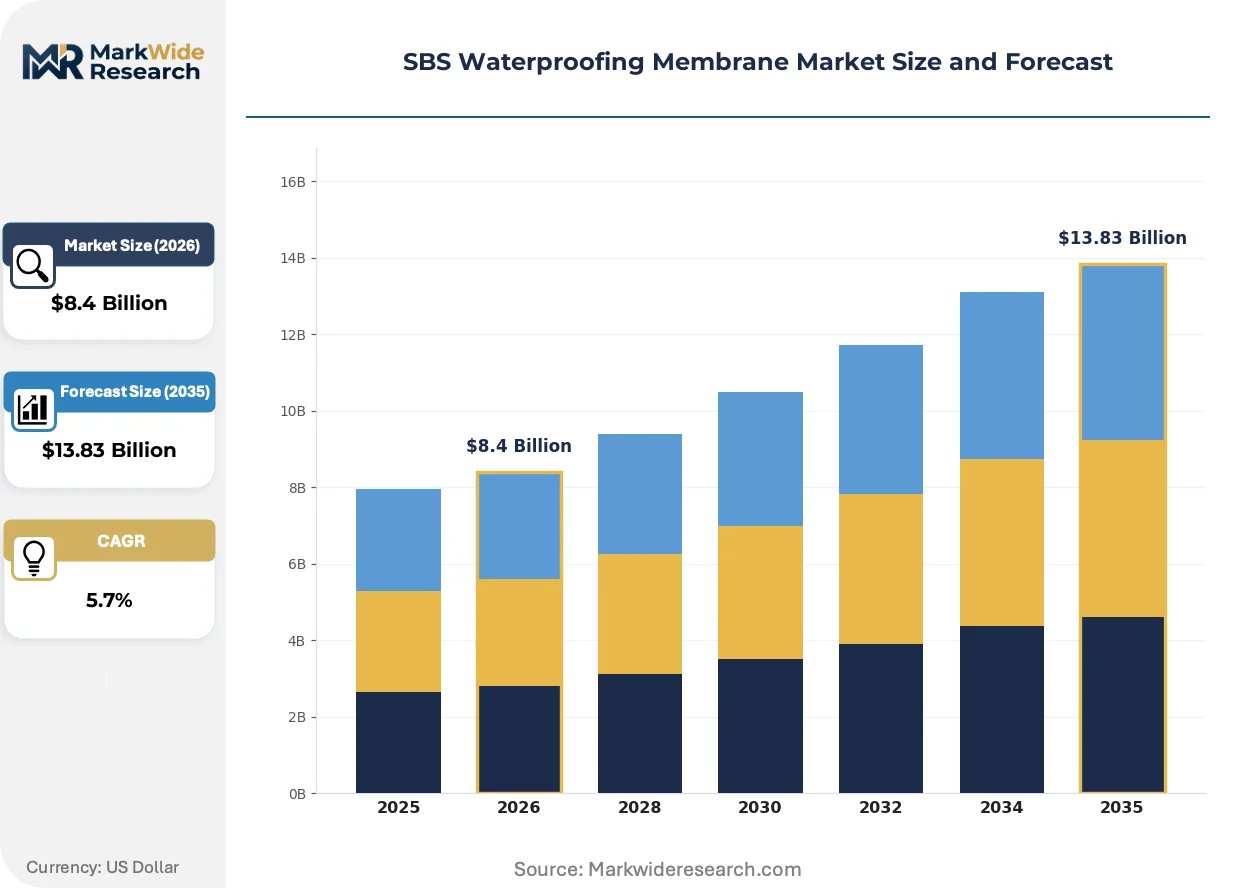
Market Dynamics
China's MIIT building envelope standards and the EU Green Deal renovation mandates are compressing specification timelines for high-performance membranes, forcing manufacturers to certify cold-flex ratings and permeability thresholds before contractors finalize roofing assemblies.
Growth Catalysts
- EU Green Deal building renovation wave:Germany's retrofit sector faces tightened carbon performance requirements for existing building stock, accelerating membrane replacement cycles in commercial roofing.
- Self-adhered installation technology:Commercial roofing contractors in North America are expanding specification of flame-free systems to reduce permitting complexity and labor coordination costs on restricted-access sites.
- Polymer modifier advances:SBS thermoplastic elastomer formulations now achieve elongation properties exceeding standard APP-modified materials, enabling crack-bridging in extreme temperature cycling zones.
Market Restraints
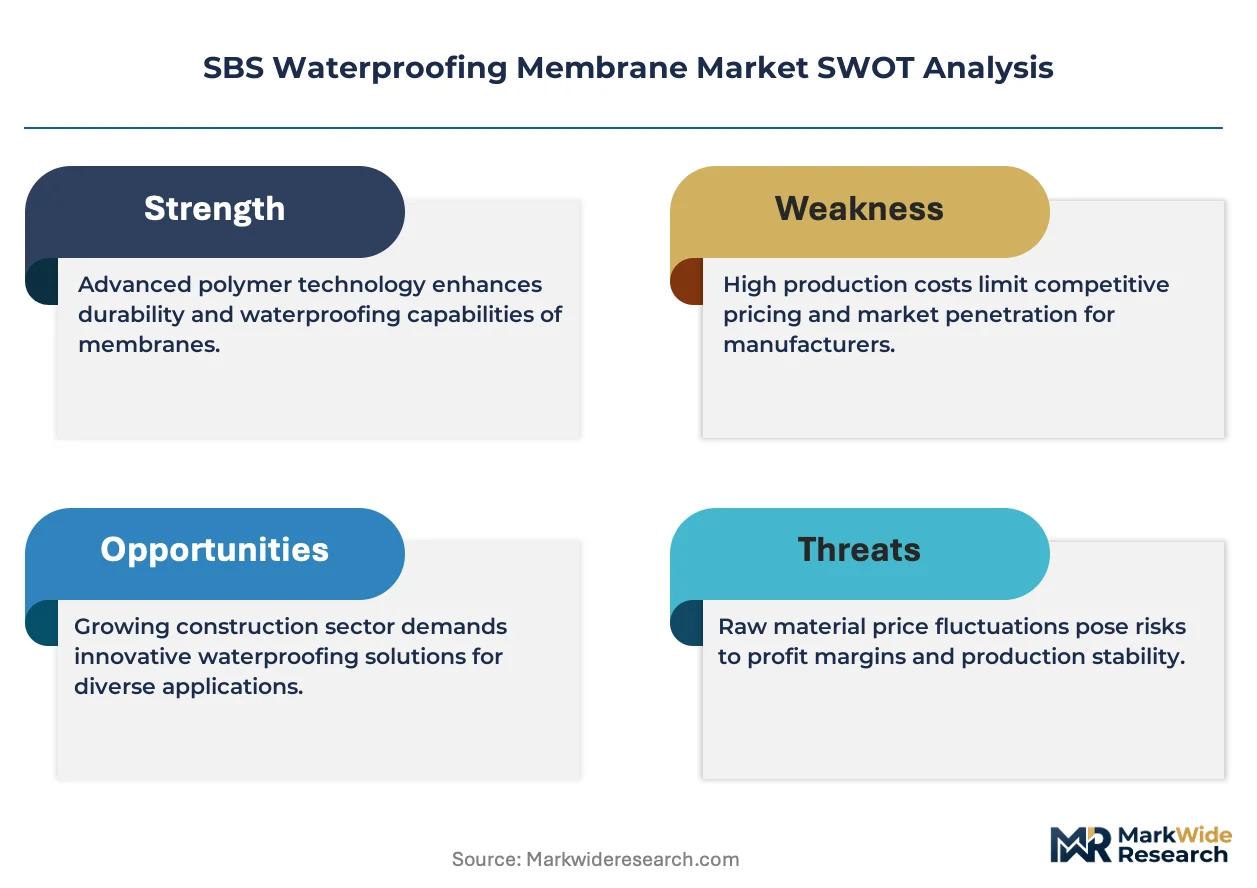
- Bitumen input cost volatility:Refinery capacity constraints and crude oil price fluctuations compress margin predictability for manufacturers reliant on asphalt-based formulations.
- REACH chemical compliance friction:European producers face constrained formulation options as ECHA restrictions on polymer modifier constituents limit substitution pathways for legacy compounds.
- APP-modified membrane substitution:Atactic polypropylene alternatives retain cost advantage in non-cycling climates, anchoring specification share in price-sensitive municipal infrastructure segments.
Strategic Opportunities
- CSRD carbon disclosure tailwinds:Corporate Sustainability Reporting Directive rules are reshaping material sourcing decisions, creating qualification leverage for suppliers with verified low-carbon polymer supply chains.
- Below-grade waterproofing convergence:Integration of drainage composites with SBS membranes is opening specification in EPA-regulated stormwater management infrastructure.
- India's building code modernization:BIS waterproofing standards for high-rise construction are creating first-mover advantage for cold-flex certified products in Mumbai and Bangalore commercial developments.
Industry Challenges
- Certification timeline compression:Multi-jurisdictional fire-rating and permeability testing requirements delay product launches as manufacturers sequence UL, FM Global, and CE marking submissions.
- Applicator skill fragmentation:Self-adhered system specification growth outpaces trained installer availability, creating quality liability exposure on high-stakes commercial roofing contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SBS Waterproofing Membrane Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bitumen, Polymeric, Thermoplastic, Composite Application: Commercial Roofing, Residential Roofing, Foundation, Parking Structures Installation Method: Adhered, Mechanically Fastened, Loose-Laid, Self-Adhered End User: Contractors, Architects, Building Owners, Developers |
| Companies Covered | Johns Manville, GAF Materials Corporation, Soprema Group, Carlisle Companies Inc., Firestone Building Products Company LLC, Sika Group, MBTechnology, Baumerk, Derbigum, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SBS Waterproofing Membrane Market Trends and Innovations
Membrane technology is pivoting toward installation-method innovation and polymer science advances that reduce field labor while extending service life in thermally stressed assemblies.
Cool-roof surfacing technology is integrating infrared-reflective granules into SBS cap sheets to reduce thermal load on commercial buildings. Building owners in sun-belt US states are specifying these assemblies to meet IECC energy code compliance paths. The technology is integrating lifecycle cooling-cost savings into contractor value propositions, compressing payback period calculations against standard dark-surfaced alternatives.
EPA stormwater regulations are mandating retention-grade membrane performance for below-grade applications in flood-prone zones. Industrial consequence includes thickness specification increases and dual-layer system requirements on federal infrastructure projects. Civil engineering firms in coastal US cities are responding by pre-qualifying suppliers with certified permeability testing protocols.
Specification authority is migrating from general contractors to building envelope consultants with forensic failure expertise. These specialists now control membrane selection on large commercial projects, displacing traditional distributor influence. Consultant-driven procurement is most visible in German and Dutch markets where warranty litigation history has elevated technical due diligence in roofing assemblies.
SBS Waterproofing Membrane Market Segmentation
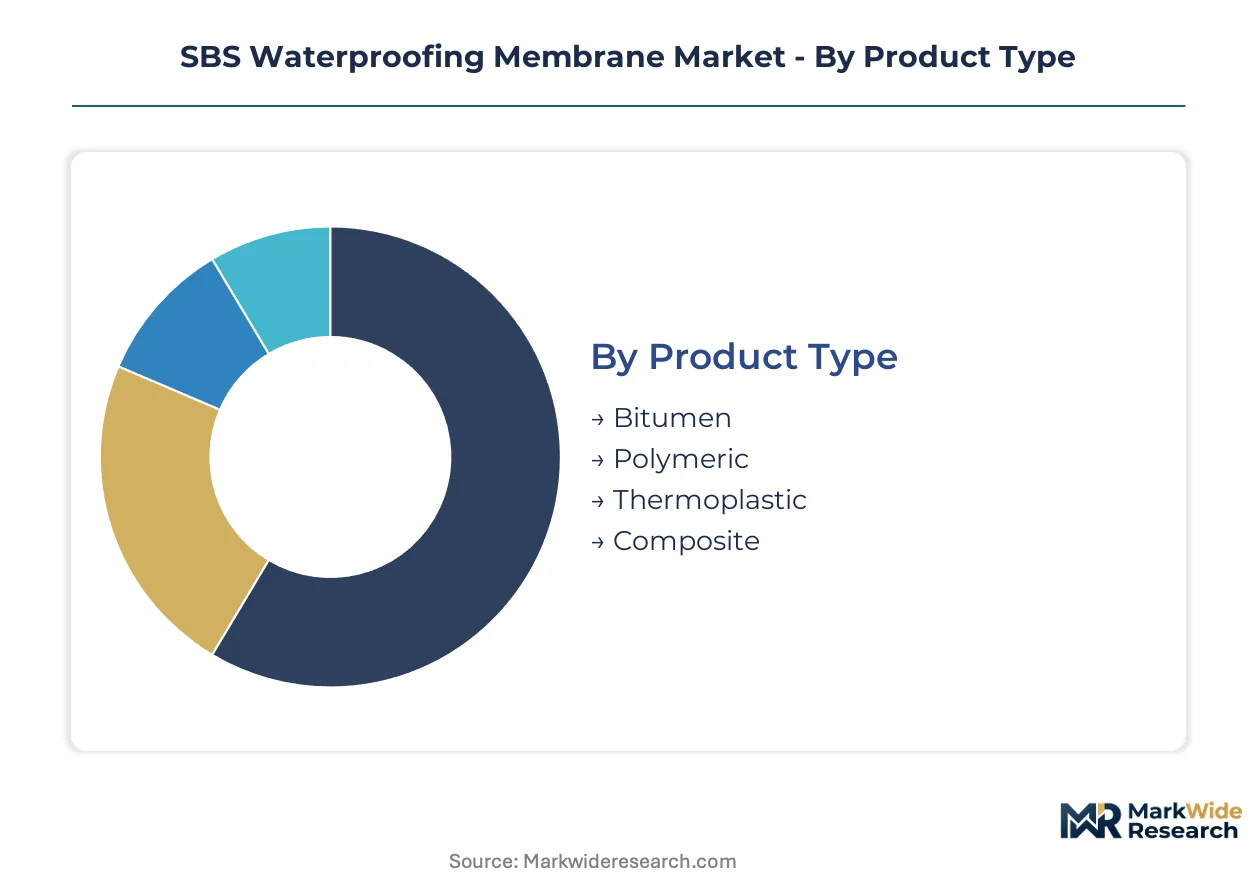
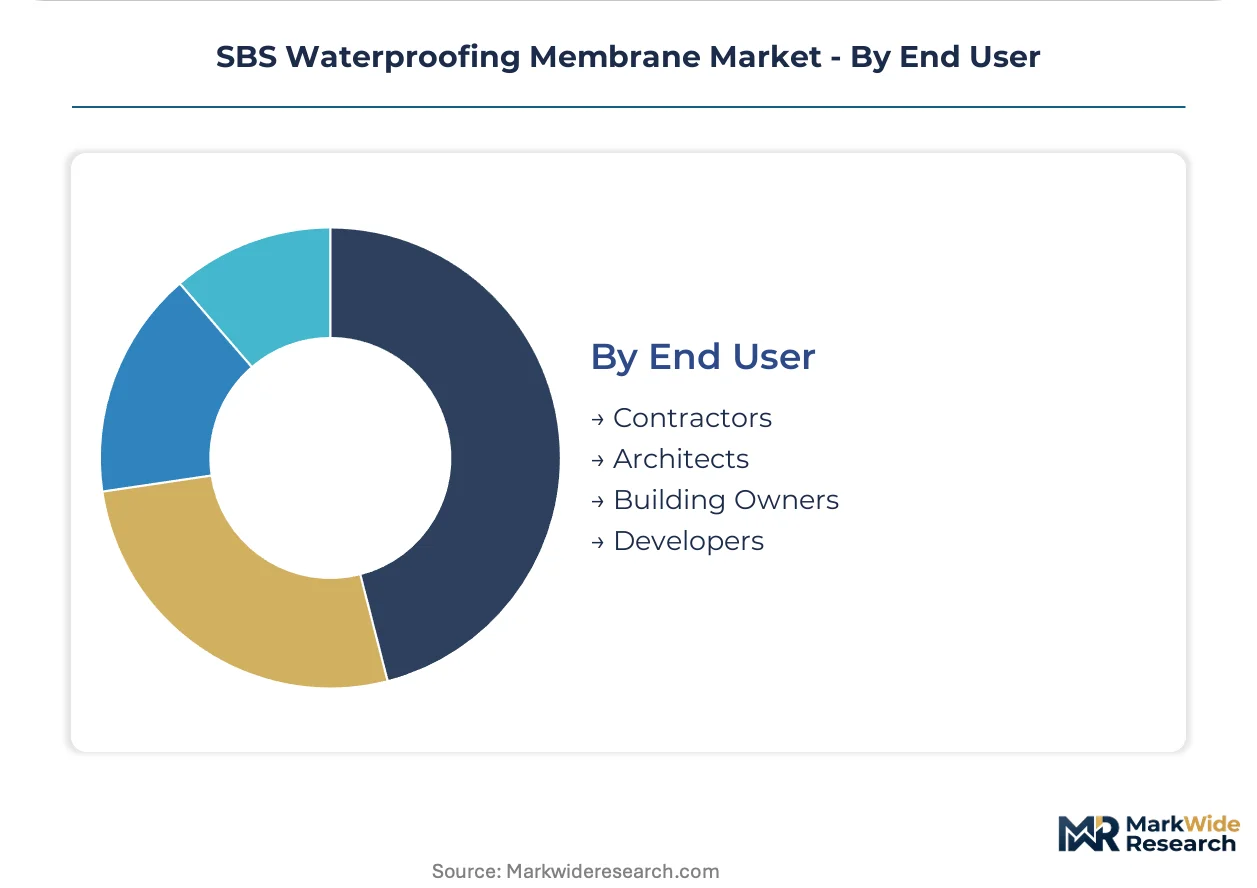
SBS waterproofing membrane specification fractures across material chemistry, installation logistics, and stakeholder authority. Manufacturers must align formulation investments with the dominant procurement channels in each segment cluster.
Product Type:
Supply concentration tilts toward bitumen compounding expertise, with polymer science capabilities determining premium positioning.
- Bitumen:Asphalt-based formulations modified with SBS elastomer dominate commercial roofing specification through contractor familiarity and cost predictability. Demand concentrates in North American reroofing cycles as building owners prioritize lifecycle durability over first cost amid energy code tightening.
- Polymeric:Advanced thermoplastic formulations deliver superior chemical resistance and elongation performance for below-grade and industrial containment applications. Specification is accelerating in Germany's retrofit sector under EU Green Deal carbon performance requirements for existing building stock.
- Thermoplastic:Heat-weldable membrane systems enable seam integrity in complex geometries without adhesive curing delays.
- Composite:Multi-layer assemblies integrating drainage media and root barriers serve intensive green roof specifications.
Bitumen absorbs the bulk of installed capacity; polymeric is expanding most quickly.
Application:
Cost tier stratification separates high-stakes commercial assemblies from price-sensitive residential volumes.
- Commercial Roofing:Multi-layer SBS systems with high-performance cap sheets dominate flat and low-slope assemblies on office, retail, and institutional buildings. Specification authority has migrated to building envelope consultants with forensic failure expertise, displacing traditional distributor influence in German and Dutch markets.
- Foundation:Below-grade waterproofing demands retention-grade membrane performance with dual-layer system requirements on EPA-regulated federal infrastructure projects in flood-prone US coastal cities.
- Residential Roofing:Single-ply and self-adhered SBS variants compete with asphalt shingles on cost in steep-slope applications.
- Parking Structures:Traffic-bearing membrane systems with protective wearing surfaces address chloride exposure and thermal cycling in multi-level concrete decks.
Commercial roofing absorbs the bulk of installed capacity; foundation applications are climbing the fastest.
Installation Method:
Volume concentration favors mechanically fastened and fully adhered systems, with self-adhered technology disrupting labor economics.
- Self-Adhered:Factory-applied adhesive layers eliminate open-flame permitting complexity and reduce labor coordination costs on restricted-access commercial sites. North American contractors are expanding specification share as stricter energy codes compress project timelines.
- Mechanically Fastened:Screw and plate attachment systems anchor membranes in high-wind zones without adhesive curing windows. Demand persists in sun-belt US states where cool-roof surfacing technology with infrared-reflective granules reduces thermal load.
- Adhered:Cold-applied or hot-mopped bitumen bonding remains standard for multi-ply redundancy in critical assemblies.
- Loose-Laid:Ballasted systems with concrete pavers or river stone suit applications where deck penetration is prohibited.
Mechanically fastened absorbs the bulk of installed capacity; self-adhered is gaining share fastest.
End User:
Customer type determines specification authority, with procurement patterns shifting from general contractors to technical specialists.
- Contractors:Installation firms drive material selection based on crew skill availability, equipment access, and warranty terms. Applicator skill fragmentation creates quality liability exposure as self-adhered system specification outpaces trained installer availability.
- Architects:Design professionals specify membrane performance criteria in construction documents, though direct procurement authority varies by contract structure.
- Building Owners:Institutional and corporate portfolio managers prioritize lifecycle cost analysis and energy code compliance paths.
- Developers:Speculative construction entities emphasize first-cost containment and schedule acceleration.
Contractors absorb the bulk of procurement volume; building owners are expanding their specification influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates SBS membrane manufacturing capacity through integrated bitumen refining corridors, while Germany and the United States absorb premium specification volumes through stringent building envelope codes that disqualify conventional materials.
China
MIIT building envelope standards are accelerating substitution of conventional membranes in high-rise commercial construction. The ministry's tightened thermal performance thresholds force manufacturers to certify cold-flex ratings before project bidding. Manufacturers cluster in Shandong Province's petrochemical corridor near Qingdao, where integrated bitumen supply chains support rapid formulation scaling.
Germany
Retrofit sector demand concentrates as the EU Green Deal tightens carbon performance requirements for existing building stock. KBA transport infrastructure standards indirectly shape membrane specification through bridge deck waterproofing mandates. Industrial demand clusters in North Rhine-Westphalia's Ruhr industrial belt, where commercial roofing replacement cycles compress amid energy efficiency audits.
United States
EPA stormwater regulations mandate retention-grade membrane performance for below-grade applications in flood-prone coastal zones. IECC energy code compliance paths in sun-belt states drive cool-roof surfacing specification with infrared-reflective granules. Contractor networks concentrate in Texas and Florida metropolitan corridors, where self-adhered system adoption reduces open-flame permitting complexity.
India
BIS waterproofing standards for high-rise construction create first-mover advantage for cold-flex certified products in Mumbai and Bangalore commercial developments. The Bureau of Indian Standards' evolving technical committees are aligning with international elongation testing protocols. Manufacturing investment clusters in Gujarat's chemical processing zone near Vadodara, where imported SBS polymer supply chains intersect with domestic bitumen refining.
France
ANSM healthcare facility construction guidelines indirectly influence membrane specification through hospital roofing durability requirements. The country's national building regulation (RT2012/RE2020) trajectory tightens thermal bridge control in commercial envelopes. Specification authority concentrates in Paris-Saclay research corridor projects, where building envelope consultants with forensic expertise control procurement decisions.
SBS Waterproofing Membrane Market Competitive Landscape
Top-tier vendors anchor specification channels through bitumen compounding expertise and certified testing protocols, while mid-tier fabricators compete on regional availability and installation support. The vendor base stratifies across integrated petrochemical groups, specialized membrane formulators, and regional distribution-focused entities. Two dominant competitive moves are evident: backward integration into polymer modifier supply chains, and strategic partnerships with building envelope consultants who control procurement authority on large commercial projects.
Within the integrated petrochemical tier, Johns Manville and GAF Materials Corporation represent North American manufacturing scale archetypes, while Soprema Group exemplifies European specification channel dominance through bitumen formulation heritage. Sika Group occupies a position bridging construction chemical integration with membrane system bundling. These three entities anchor competitive positioning across distinct geographic corridors without overlapping manufacturing footprints.
| Leading Market Players |
|---|
| Johns Manville |
| GAF Materials Corporation |
| Soprema Group |
| Carlisle Companies Inc. |
| Firestone Building Products Company LLC |
| Sika Group |
| MBTechnology |
| Baumerk |
| Derbigum |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal carbon performance mandates gate qualified supply access and premium-tier pricing power, forcing manufacturers to certify low-carbon polymer sourcing before bidding on German retrofit contracts while disqualifying uncertified competitors from high-margin specification channels.
Pricing Analysis
Margin tightening in standard-grade bitumen formulations reflects crude oil price volatility and refinery capacity constraints compressing manufacturer predictability. Three-tier pricing structure across premium cold-flex certified, standard APP-competing, and economy municipal-grade levels separates specification authority. Price differentiation hinges on UL/FM Global fire-rating certification and verified polymer modifier elongation performance. Municipal infrastructure buyers exhibit highest price sensitivity; building envelope consultants controlling German commercial procurement show lowest.
Supply Chain Analysis
Dual-sourcing requirements from building envelope consultants and federal infrastructure contractors mandate multi-supplier qualification for SBS polymer modifiers and bitumen feedstocks. Supply concentrates in China's Shandong petrochemical corridor, Germany's Ruhr industrial belt, and Texas-Gulf Coast refining clusters. Raw material dependencies span styrene-butadiene elastomer, oxidized asphalt, and polyester reinforcement carriers. Single-source vulnerability from concentrated polymer modifier production creates qualification bottlenecks. Distribution runs through specification-channel distributors and direct contractor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into polymer modifier supply chains and captive bitumen refining capacity represents the decisive competitive lever, with first-movers securing cost predictability and carbon disclosure advantages under tightening EU CSRD rules.
For Market Incumbents: Anticipate APP-modified membrane substitution pressure in price-sensitive municipal segments by accelerating cold-flex certification investments and locking specification-channel distributor relationships. Prioritize capacity addition in Gujarat's chemical processing zone to capture India's BIS standards modernization. Defensive consolidation through polymer compounding expertise acquisition mitigates REACH formulation constraint risks. For New Entrants and Emerging Players: Building envelope consultants with forensic failure expertise offer the most penetrable specification channel, displacing traditional distributor influence in German and Dutch procurement. Target India's high-rise commercial developments in Mumbai and Bangalore where BIS cold-flex certification creates first-mover advantage. Below-grade waterproofing convergence with EPA-regulated stormwater infrastructure presents white-space opportunity. Go-to-market leverage rests on certified permeability testing protocols and drainage composite bundling. For Investors and Strategic Acquirers: CSRD carbon disclosure rule enforcement acceleration is the leading indicator that low-carbon polymer supply chain verification will separate acquisition targets from stranded assets. Long-term viability favors vertically integrated formulators with captive modifier production and multi-jurisdictional fire-rating certification libraries. Watch for MIIT building envelope standard tightening in China as inflection signal for specification-grade membrane demand compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Modifiers | Captive SBS elastomer supply secures margin predictability against crude-linked bitumen volatility. |
| Multi-Jurisdictional Certification Investment | Simultaneous UL, FM Global, and CE marking submission compresses product launch timelines. |
| Building Envelope Consultant Partnership | Forensic expertise relationships displace distributor influence in German specification channels. |
| Below-Grade System Bundling | Drainage composite integration opens EPA-regulated stormwater infrastructure specification. |
| Low-Carbon Supply Chain Verification | CSRD-compliant polymer sourcing creates qualification leverage in EU Green Deal retrofit wave. |
Research Methodology
Multi-period observation of MIIT building envelope standard enforcement, EU Green Deal renovation permit issuance, and EPA stormwater infrastructure project awards anchored the trend analysis, supplemented by interviews with commercial roofing contractors, building envelope consultants, polymer procurement leads at membrane formulators, and technical R&D directors at integrated petrochemical groups. Secondary validation drew from ECHA REACH restriction updates, BIS technical committee deliberations, SEC manufacturing capacity disclosures, and customs trade data on SBS polymer imports. Bottom-up project pipeline tracking and top-down construction spend forecasts were triangulated against manufacturer shipment data.
Segment-weighting across product type, installation method, application, and end-user procurement authority shaped the analytical framework. Modeled dimensions included bitumen versus polymeric chemistry tiers, self-adhered versus mechanically fastened logistics, commercial roofing versus below-grade foundation demand, and contractor versus building owner specification influence. CAGRs were derived from elasticity-adjusted demand curves and replacement cycle compression factors. Industry-specific inputs incorporated IECC energy code adoption trajectories and cool-roof surfacing technology penetration rates.
Caveats apply where crude oil price volatility, REACH chemical restriction expansion, or applicator skill fragmentation could materially shift the outlook. Forecasts reflect assumptions on regulatory timeline adherence and certification backlog clearance. Deviation in EU Green Deal renovation funding allocation or MIIT enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Asia-Pacific Cross-Laminated Timber Market
Building & Construction Materials
US Steel Rebar Market
Building & Construction Materials
North America UPVC Doors and Windows Market
Building & Construction Materials
Drywall Compound and Drywall Mud Market
Building & Construction Materials
North America Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Nordic Solar Shades Market
Building & Construction Materials
Prefabricated Bathroom Modules Market
Building & Construction Materials
North America Particle Board Market
Building & Construction Materials
Electrically Dimmable Exterior Window Systems for Premium Cabins Market
Building & Construction Materials
Curtain Wall Market
Building & Construction Materials
Stone Veneer Market
Building & Construction Materials
Plastic Fencing Market
Building & Construction Materials
Welded Wire Mesh Market
Building & Construction Materials
Global Builder Hardware Market
Building & Construction Materials
Global Panelized and Modular Building System Market
Building & Construction Materials
North America Industrial Flooring Market