
 Separation Machinery Market | 2026-2036
Separation Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Separation Machinery Market Analysis
The EU Green Deal's industrial emissions benchmarks are consolidating demand for energy-efficient separation systems across European process industries. Alfa Laval leverages its centrifuge technology leadership to anchor retrofit contracts in Nordic biorefining clusters. GEA Group competes through thermal separation specialization, sustaining installed-base service revenue across German chemical processing corridors.
Separation machinery encompasses centrifuges, filters, separators, and screens engineered to isolate components from heterogeneous process streams based on density, particle size, or phase state, typically operating at pressures from vacuum to 100 bar and temperatures spanning cryogenic to 400°C. Membrane filtration technology leads technology adoption in wastewater treatment applications where effluent quality mandates tighten, while magnetic separation registers the fastest structural growth in battery material recovery circuits. Solid-liquid separation commands the largest application share in mining and minerals processing, though liquid-liquid separation captures premium margin pools in pharmaceutical active ingredient manufacturing.
EPA effluent limitation guidelines shape US equipment procurement timelines for municipal wastewater utilities, while REACH chemical substance restrictions in Europe force material compatibility upgrades in seal and gasket specifications. China's MEE enforces discharge permits that mandate continuous monitoring integration with separation systems. Stakeholders must evaluate regulatory convergence between carbon accounting standards and process energy intensity metrics when prioritizing R&D allocation across centrifuge, membrane, and thermal technology portfolios.
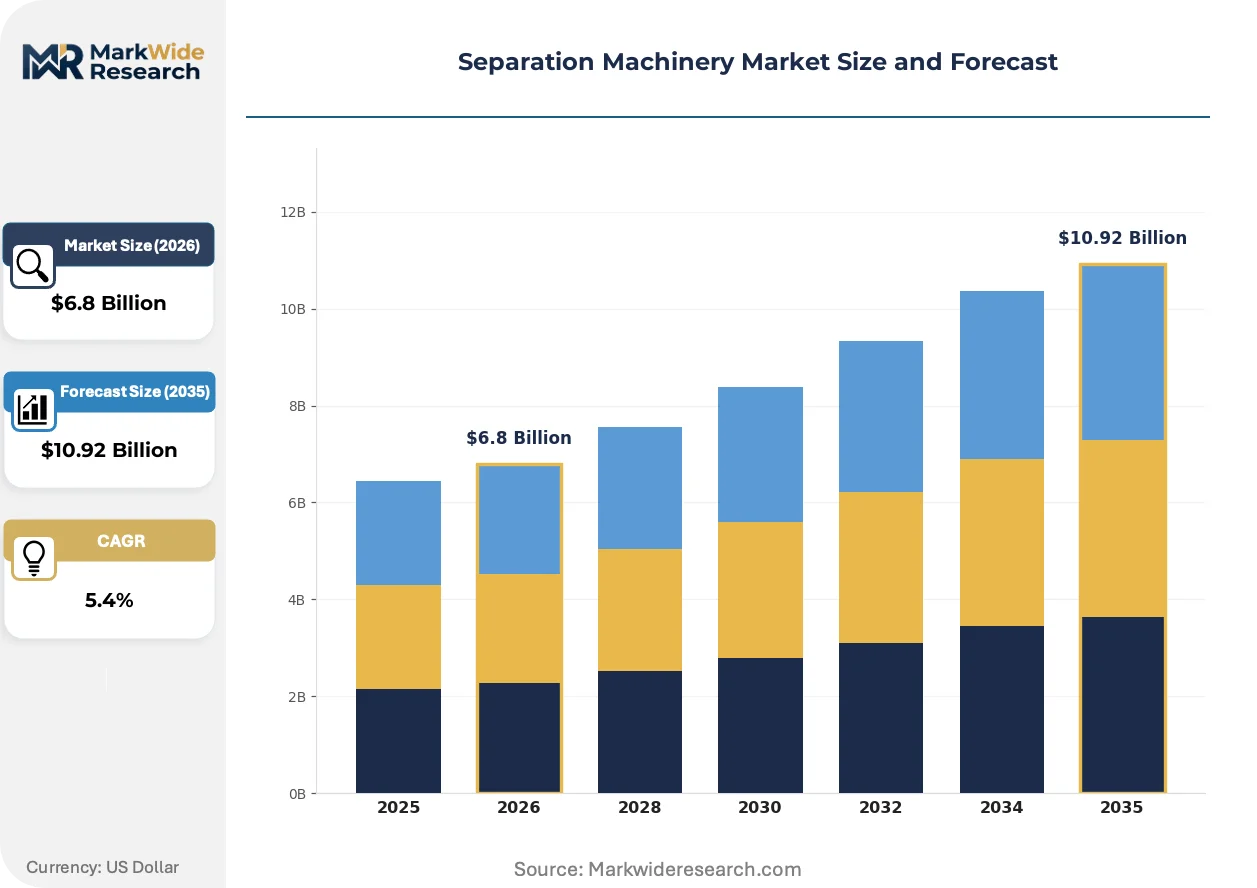
Market Dynamics
Energy intensity mandates under the EU Green Deal and China's dual carbon goals are forcing process industries to retire thermal separation systems ahead of depreciation schedules, creating replacement pull for centrifuge and membrane technologies.
Growth Catalysts
- REACH material restrictions:European chemical processors must upgrade seal and gasket specifications in legacy separation equipment, triggering retrofit demand across German and French industrial corridors.
- CDSCO compliance requirements:India's pharmaceutical manufacturing hubs under PLI scheme incentives are installing solid-liquid separation systems to meet active ingredient purity standards.
- Membrane filtration:Wastewater treatment utilities in Germany and Japan are expanding deployments as effluent quality mandates tighten under national discharge permit systems.
Market Restraints
- Specialized alloy supply concentration:Duplex stainless steel and superalloy procurement depends on a limited supplier base in Nordic and Japanese metallurgical centers, exposing equipment manufacturers to input cost volatility.
- Technical limitation in high-solids streams:Membrane fouling rates in mining tailings and biomass processing applications exceed economic cleaning cycle thresholds, restricting technology penetration in solid-liquid separation.
- EPA effluent guideline friction:US municipal procurement timelines compress under regulatory uncertainty as guideline revisions pend, delaying capital commitment for continuous monitoring integration.
Strategic Opportunities
- Battery material recovery circuits:Magnetic separation technology is capturing lithium, cobalt, and nickel from end-of-life batteries and production scrap as electric vehicle manufacturing scales.
- EU AI Act compliance infrastructure:Separation system vendors can embed predictive maintenance algorithms and autonomous control modules to meet emerging algorithmic transparency requirements in European process industries.
- Direct-to-utility channel expansion:Equipment manufacturers are bypassing traditional EPC intermediaries to contract directly with wastewater utilities for membrane filtration packages, compressing sales cycles and capturing service revenue.
Industry Challenges
- Cross-disciplinary engineering scarcity:Integration of membrane science, process control, and materials engineering expertise is concentrated in German, Swiss, and Japanese technical universities, constraining workforce scaling for system OEMs.
- Legacy DCS integration complexity:Brownfield separation upgrades in established chemical processing corridors require protocol translation between modern IoT-enabled equipment and proprietary distributed control systems from 1990s installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Separation Machinery Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifuges, Filters, Separators, Screens Technology: Membrane Filtration, Thermal Separation, Magnetic Separation, Settling End User: Food & Beverage, Pharmaceutical, Chemical Processing, Wastewater Treatment Application: Liquid-Liquid Separation, Solid-Liquid Separation, Gas Separation, Particle Separation |
| Companies Covered | Alfa Laval, GEA Group, ANDRITZ, Mitsubishi Kakoki Kaisha, Russell Finex, SWECO, Ferrum AG, Parkson Corporation, Gruppo Pieralisi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Separation Machinery Market Emerging Trajectories
Digital twin architectures and autonomous control systems are compressing the gap between equipment commissioning and steady-state operation, while regulatory pressure on embodied carbon accelerates materials substitution in high-pressure centrifuge housings.
Advanced ceramic membrane technology is integrating alumina and silicon carbide substrates with graphene oxide surface modifications to achieve fouling resistance in high-temperature process streams. Food and beverage processors in Italy and Spain are piloting these systems for protein concentration and dairy fractionation. The technology is integrating predictive cleaning algorithms that reduce chemical consumption and extend operational cycles between maintenance events.
China's MEE discharge permit enforcement is mandating continuous monitoring integration with all new separation system installations in municipal and industrial wastewater treatment. Equipment suppliers must now certify real-time data transmission protocols to provincial environmental authorities as a condition of commercial operation. Pharmaceutical and electronics manufacturing facilities in Jiangsu and Guangdong provinces face the steepest compliance timelines, compressing procurement decisions toward bundled monitoring-separation packages.
Service contract unbundling is fragmenting traditional aftermarket relationships as large chemical processors and mining operators bring predictive maintenance capabilities in-house. Third-party sensor analytics platforms are displacing OEM service agreements for condition monitoring in North American and Australian mineral processing corridors. Mining majors in Western Australia and Chile are recruiting centrifuge specialists directly from equipment vendors to staff internal reliability engineering teams.
Separation Machinery Market Segmentation
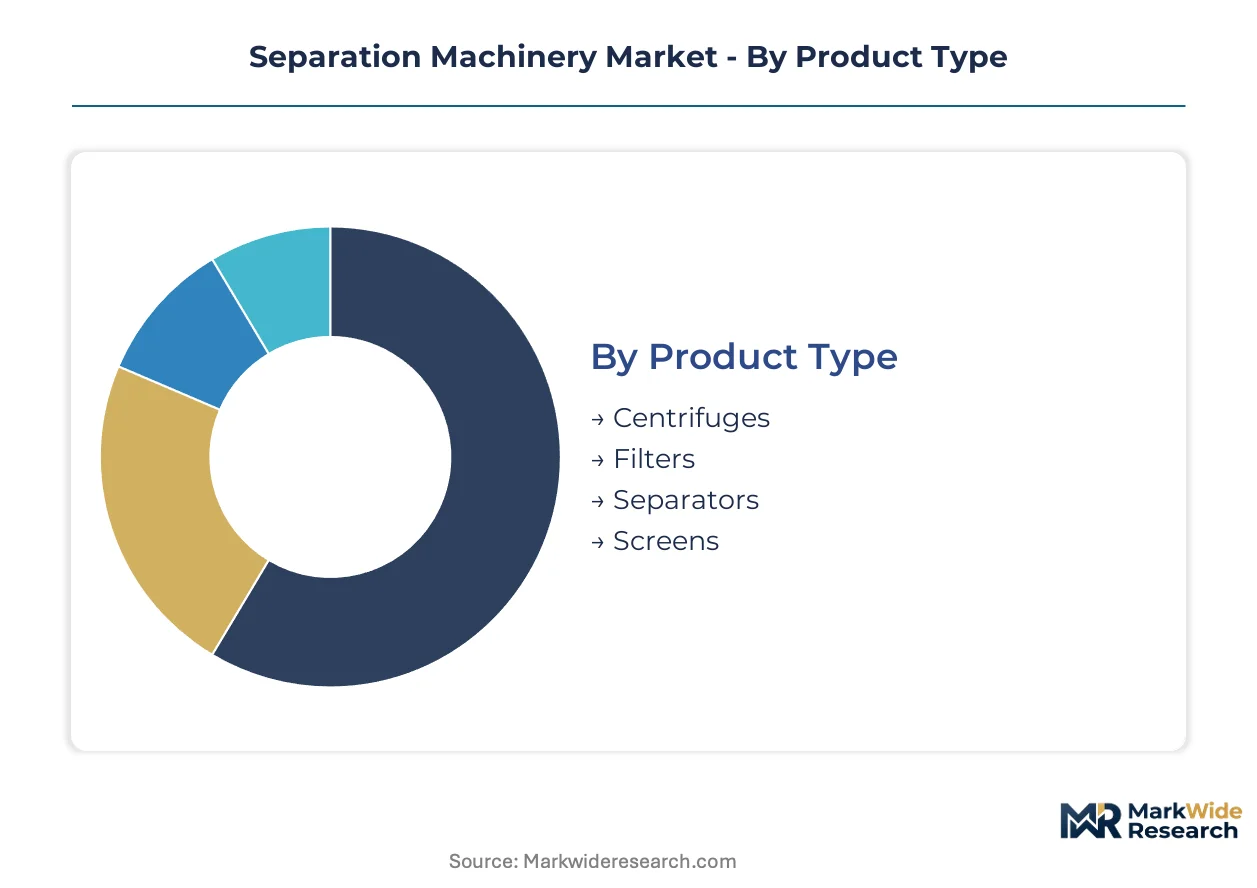
Separation machinery procurement patterns diverge sharply across product architectures and process intensities. Capital allocation decisions in this market track closely to energy intensity mandates and effluent compliance timelines rather than generic capacity expansion cycles.
Product Type:
Centrifuge systems demand the highest upfront capital commitment among all product categories, with pressure-rated housings and precision-balanced rotors driving equipment costs well above filtration alternatives.
- Centrifuges:High-speed rotational systems generate centrifugal forces exceeding 10,000 g-force for density-based phase separation. German chemical processors and Nordic biorefiners are retiring thermal systems ahead of depreciation schedules under EU Green Deal energy benchmarks, pulling replacement demand toward decanter and disk-stack configurations.
- Filters:Pressure-driven media systems span cartridge, bag, and pressure-leaf architectures with operating envelopes from vacuum to 100 bar. India's pharmaceutical corridors under CDSCO compliance mandates are installing solid-liquid filtration trains for active ingredient purification, capitalizing on PLI scheme incentives.
- Separators:Gravity-assisted or coalescing systems isolate immiscible liquid phases without rotational energy input. Food and beverage processors in Italy and Spain deploy these for edible oil clarification and dairy cream separation.
- Screens:Aperture-based classification equipment sorts particulates by size in mining and aggregate processing. Australian and Chilean mineral processing corridors specify high-tensile wire mesh for dewatering tailings streams.
Most installed capacity flows through centrifuge and filter systems. Expansion is steepest in screens as battery material recovery circuits scale.
Technology:
Technology selection in this market hinges on energy efficiency differentials against incumbent thermal methods, with membrane and magnetic alternatives capturing share from legacy evaporation and distillation.
- Membrane Filtration:Selective permeability barriers using polymeric or ceramic substrates achieve molecular-level separation without phase change. Wastewater treatment utilities across Germany and Japan are expanding submerged and cross-flow configurations as national discharge permit systems tighten effluent quality mandates.
- Thermal Separation:Evaporation, distillation, and crystallization systems consume latent heat for phase transition. German chemical processing corridors sustain significant installed-base service revenue despite accelerating retirements under carbon intensity pressures.
- Magnetic Separation:High-gradient or rare-earth drum systems extract ferromagnetic and paramagnetic materials from process streams. Lithium, cobalt, and nickel recovery from end-of-life batteries and production scrap is climbing fastest as electric vehicle manufacturing scales.
- Settling:Gravity sedimentation and flotation systems separate dispersions by density differential. Mining tailings management in Western Australia and Chile relies on thickener and clarifier installations for water recovery.
Membrane filtration commands the largest share of new project awards. Magnetic separation is gaining share fastest in battery material circuits.
End User:
End-user segmentation reveals divergent procurement rhythms, with pharmaceutical and food processors prioritizing validation documentation while wastewater utilities emphasize lifecycle operating cost.
- Food & Beverage:Hygienic-design equipment for dairy fractionation, protein concentration, and edible oil processing. Italian and Spanish processors pilot advanced ceramic membranes with graphene oxide surface modifications for fouling resistance.
- Pharmaceutical:GMP-validated systems for active ingredient isolation and sterile filtration. CDSCO compliance requirements and PLI scheme incentives in India are concentrating capital deployment in solid-liquid separation trains.
- Chemical Processing:Corrosion-resistant equipment for solvent recovery and intermediate purification. REACH material restrictions force seal and gasket upgrades across German and French industrial corridors.
- Wastewater Treatment:Municipal and industrial effluent polishing systems. China's MEE mandates continuous monitoring integration with all new installations in Jiangsu and Guangdong provinces.
Chemical processing retains the deepest installed base. Pharmaceutical end-use is expanding most quickly on compliance-driven replacement cycles.
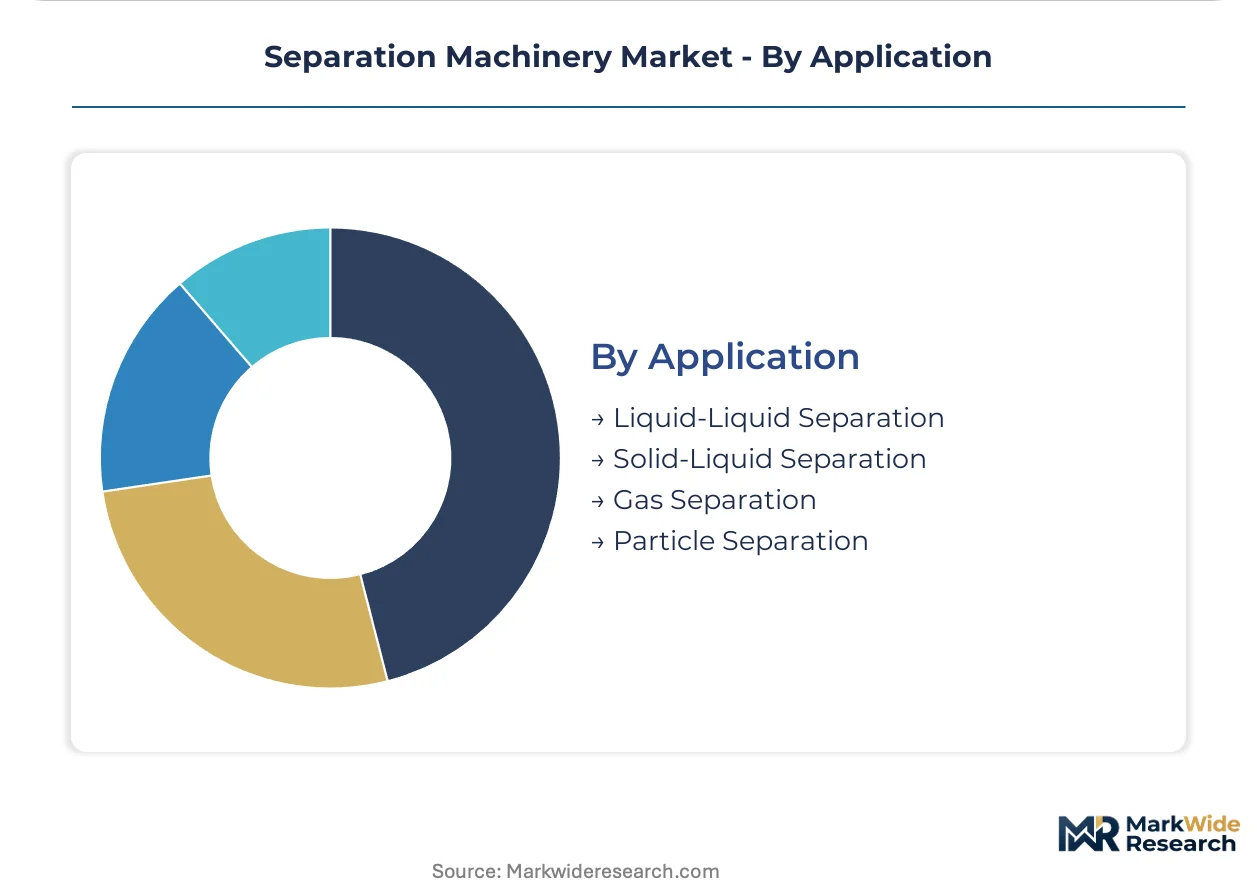
Application:
Application segmentation tracks process stream complexity, with multi-phase separations commanding premium pricing against single-phase alternatives.
- Liquid-Liquid Separation:Coalescing, centrifugal, or membrane-based isolation of immiscible fluids. Pharmaceutical active ingredient manufacturing captures premium margin pools for solvent extraction and purification stages.
- Solid-Liquid Separation:Filtration, centrifugation, or sedimentation of particulates from fluid carriers. Mining and minerals processing commands the largest volume share for tailings dewatering and concentrate recovery.
- Gas Separation:Membrane, adsorption, or cryogenic systems for air fractionation and process gas purification. Industrial gas suppliers deploy these for nitrogen and oxygen production.
- Particle Separation:Size-based classification using screens, hydrocyclones, or air classifiers. Aggregate processing and recycling operations specify these for product sizing.
Solid-liquid separation dominates installed capacity. Liquid-liquid separation is climbing fastest on pharmaceutical capacity expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Process engineering talent concentrates in German technical universities and Swiss polytechnics, anchoring European centrifuge innovation. Japanese metallurgical expertise underpins rare-earth magnetic separation advances. Indian pharmaceutical corridors attract capital deployment under production-linked incentive schemes.
Germany
Chemical processors in the Rhine-Ruhr industrial belt are retiring thermal separation systems ahead of depreciation schedules. REACH material restrictions force seal and gasket upgrades across legacy equipment installations. Bavarian biorefining clusters are contracting for decanter centrifuge retrofits under EU Green Deal energy intensity benchmarks.
China
Jiangsu and Guangdong provinces face compressed procurement timelines for bundled monitoring-separation packages. MEE discharge permit enforcement mandates continuous data transmission protocols to provincial environmental authorities. Yangtze River Delta pharmaceutical and electronics manufacturing facilities are integrating real-time compliance infrastructure with new membrane installations.
India
CDSCO compliance requirements are concentrating capital investment in solid-liquid separation trains across active ingredient manufacturing. PLI scheme incentives accelerate equipment procurement timelines in pharmaceutical corridors. Maharashtra and Gujarat production hubs are installing validated filtration systems to meet export purity standards.
Japan
Wastewater treatment utilities are expanding membrane filtration deployments under tightening national effluent quality mandates. METI efficiency standards push industrial users toward centrifuge alternatives to thermal separation. Kansai region chemical processors are upgrading disk-stack configurations for solvent recovery applications.
United States
EPA effluent limitation guideline revisions are compressing municipal procurement timelines for continuous monitoring integration. Mining operators in Western Australia and Chilean mineral corridors are recruiting centrifuge specialists directly from equipment vendors. Third-party sensor analytics platforms are displacing OEM service agreements across North American mineral processing installations.
Separation Machinery Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the separation machinery sector. The vendor base spans consolidated centrifuge specialists, diversified filtration conglomerates, and regional membrane fabricators. Three archetypes dominate: European precision-engineering houses, Asian scale manufacturers, and North American aftermarket service platforms. Competitive moves concentrate on vertical integration into specialized alloy supply and predictive maintenance algorithm development.
Within the European precision-engineering tier, Alfa Laval and GEA Group exemplify the capital-intensive centrifuge archetype, while ANDRITZ occupies a diversified position spanning filtration and thermal technologies. These manufacturers represent contrasting strategic postures toward energy transition mandates, with some anchoring retrofit revenue streams and others pivoting toward membrane hybrid systems.
| Leading Market Players |
|---|
| Alfa Laval |
| GEA Group |
| ANDRITZ |
| Mitsubishi Kakoki Kaisha |
| Russell Finex |
| SWECO |
| Ferrum AG |
| Parkson Corporation |
| Gruppo Pieralisi |
| Others |
Supply Flow & Price Mechanics
EU Green Deal carbon intensity benchmarks gate qualified supply for premium-tier centrifuge and membrane systems, restricting vendor eligibility to manufacturers with certified low-carbon production footprints and locking out economy-tier competitors from retrofit contracts in German and French chemical processing corridors.
Pricing Analysis
Bundled predictive maintenance contracts now command 15-25% premiums over unbundled equipment-only transactions across European biorefining clusters. Three-tier pricing structure across premium, standard, and economy levels stratifies by alloy grade certification and real-time monitoring integration depth. Cost compression in standard-tier membrane packages is intensifying because Indian pharmaceutical manufacturers under PLI scheme procurement timelines prioritize capital efficiency over lifecycle service bundling. Municipal wastewater utilities in Japan exhibit lowest price sensitivity due to 20-year total-cost-of-ownership mandates, while Australian mining operators drive hardest equipment-only negotiations.
Supply Chain Analysis
India's phased manufacturing program and China's dual carbon goals are reshaping sourcing patterns for separation machinery components, forcing OEMs to qualify alternative forging and casting suppliers outside traditional Nordic-Japanese metallurgical centers. Duplex stainless steel and superalloy procurement draws from concentrated supplier bases in Germany, Japan, and Sweden, with rare-earth magnetic materials for battery recovery systems anchored in Chinese processing capacity. Single-source vulnerability in high-grade titanium castings for pressure-rated centrifuge housings exposes equipment manufacturers to input cost volatility. Distribution runs through EPC intermediaries for greenfield projects while direct-to-utility contracting expands for membrane retrofit packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities concentrate in India's pharmaceutical corridors, where CDSCO compliance timelines and PLI scheme incentives compress procurement cycles relative to European REACH-mandated retrofit delays, enabling faster capital recovery for equipment suppliers willing to localize assembly.
For Market Incumbents: Extend predictive maintenance algorithm development to capture service revenue displaced by third-party sensor analytics platforms in Australian and Chilean mineral processing corridors. Anchor retrofit contracting capacity in Nordic biorefining clusters under EU Green Deal energy benchmark deadlines. Backward integration into specialized alloy supply hedges against Nordic and Japanese metallurgical center concentration risk. For New Entrants and Emerging Players: Enter via ceramic membrane technology for high-temperature food and beverage applications in Italy and Spain, where graphene oxide surface modification expertise remains scarce among established vendors. Target battery material recovery circuits for magnetic separation equipment as electric vehicle manufacturing scales lithium, cobalt, and nickel recovery demand. Pursue direct-to-utility channel partnerships in Germany and Japan to bypass EPC intermediaries and compress sales cycles. For Investors and Strategic Acquirers: Roll-up economics work for regional membrane fabricators with certified MEE compliance infrastructure because China's discharge permit enforcement mandates continuous monitoring integration as a condition of commercial operation, creating captive demand for bundled technology-service providers. Five-to-ten year viability hinges on regulatory convergence between carbon accounting standards and process energy intensity metrics. Watch for inflection in EPA effluent guideline finalization timelines, which would unlock compressed municipal procurement cycles in the United States.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialized Alloy Supply | Captive supply of duplex stainless steel and superalloys insulates German and Japanese OEMs from Nordic metallurgical center volatility. |
| Predictive Maintenance Algorithm Development | Embedded autonomous control modules meet EU AI Act transparency requirements while defending service revenue against third-party analytics displacement. |
| Direct-to-Utility Channel Expansion | Bypassing EPC intermediaries for membrane filtration packages in Germany and Japan compresses sales cycles and captures lifecycle service contracts. |
| Ceramic Membrane Technology Scale-Up | Alumina and silicon carbide substrates with graphene oxide modifications address fouling resistance gaps in Italian and Spanish dairy fractionation. |
| Battery Material Recovery Circuit Entry | High-gradient magnetic separation systems extract lithium, cobalt, and nickel from end-of-life batteries as electric vehicle manufacturing scales. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers at German chemical processors, procurement leads at Indian pharmaceutical manufacturers, aftermarket service heads at Australian mining operations, and municipal utility planning officers in Japan with secondary validation against customs and trade data, SEC filings from listed equipment manufacturers, MEE discharge permit registries, and EU Green Deal implementation progress reports. Bottom-up equipment shipment tallies triangulated against top-down process industry capital expenditure surveys.
Segment-weighting approaches modeled centrifuge, filter, separator, and screen product categories alongside membrane, thermal, magnetic, and settling technology alternatives, with end-use splits across food and beverage, pharmaceutical, chemical processing, and wastewater treatment applications. CAGRs derived from regression analysis against regulatory compliance timeline acceleration, energy intensity mandate enforcement schedules, and production-linked incentive scheme disbursement patterns. Forecast inputs incorporated alloy price indices, effluent standard revision calendars, and battery material recovery circuit deployment pipelines.
Inputs from provincial environmental authorities in Jiangsu and Guangdong, METI efficiency standard filings, and CDSCO compliance certification databases were available through the study window; gaps in real-time procurement data from private pharmaceutical manufacturers introduce uncertainty bands around Indian capacity expansion timing. Forecasts reflect assumptions on regulatory enforcement consistency and alloy supply elasticity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Global Welding Market
Construction Equipment
Vibratory Plate Compactors Market
Construction Equipment
Refurbished Construction Equipment Market
Construction Equipment
Tower Crane Rental Market
Construction Equipment
Global Dragline Excavator Market
Construction Equipment
US Welding Consumables Market
Construction Equipment
Tower Crane Market
Construction Equipment
Concrete Demolition Professional Equipment Market
Construction Equipment
Yard Crane Market
Construction Equipment
Construction Equipment Attachments Market
Construction Equipment
ASEAN Construction Equipment Rental Market
Construction Equipment
Bulldozer Rental Market
Construction Equipment
Japan Waterjet Cutting Machines Market
Construction Equipment
Metal Machinery Market
Construction Equipment
Line Boring Machine Market
Construction Equipment
Cutting and Bending Machine Market