
 Grinding Machinery Market | 2026-2036
Grinding Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Grinding Machinery Market Outlook
Subscription-based spindle monitoring and predictive maintenance software is restructuring how grinding machinery vendors capture lifetime value from installed bases. DMG MORI leverages integrated sensor-to-cloud platforms to lock in aftermarket revenue streams across European automotive supplier parks. Okuma Corporation anchors its competitive position through proprietary OSP control architecture that reduces third-party service dependency. ANCA Pty Ltd specializes in laser measurement and automated wheel dressing systems for cutting-tool resharpening workflows.
Grinding machinery encompasses precision material-removal equipment employing bonded abrasive wheels rotating at controlled speeds to achieve dimensional tolerances typically within 2-5 micrometers on hardened ferrous and non-ferrous workpieces. These machines perform finish machining operations where milling or turning leaves insufficient surface integrity for bearing races, hydraulic spindles, and aerospace turbine components. CNC Grinding commands the dominant technology position due to its capacity for unmanned operation and in-process gauging feedback loops that reduce scrap rates in high-mix manufacturing environments. Surface Grinder configurations retain stable demand from job shops processing dies, molds, and flat precision components where capital budgets favor proven mechanical architectures over full five-axis complexity. Tool & Cutter Grinder segments concentrate margin pools in specialized resharpening services for solid-carbide and high-speed steel cutting tools used in medical device and mold-making applications.
FDA quality system regulations for orthopedic implant manufacturers mandate documented surface finish traceability that elevates demand for certified grinding processes with automated measurement integration. EPA metalworking fluid emission standards and OSHA silica exposure limits are accelerating wet-grinding system upgrades and closed-loop coolant filtration investments across US metal fabrication facilities. The EU Machinery Directive's updated conformity requirements for emergency stop functionality and noise exposure are forcing retrofit decisions on pre-2010 conventional grinding installations. Stakeholders must weigh the capital efficiency of control-system retrofits against full machine replacement as regulatory compliance windows tighten and energy-efficiency benchmarking becomes a procurement filter in automotive supply chain audits.
Market Dynamics
Electric drivetrain manufacturing is compressing tolerance specifications for shaft and bearing grinding, forcing automotive suppliers to replace legacy cylindrical grinders with CNC platforms capable of sub-micron repeatability.
Growth Catalysts
- EU Machinery Directive compliance mandates:Emergency stop and noise exposure upgrades on pre-2010 conventional machines are accelerating replacement cycles across German Mittelstand tool-and-die shops.
- Orthopedic implant surface traceability:FDA quality system regulations mandate documented finish certification, elevating demand for automated measurement-integrated grinding processes in medical device manufacturing.
- Closed-loop coolant systems:EPA metalworking fluid emission standards and OSHA silica exposure limits are driving wet-grinding upgrades with filtration investments across US metal fabrication facilities.
Market Restraints
- High-purity abrasive wheel supply concentration:Synthetic diamond and cubic boron nitride grit production clusters in limited Asian supply basins, creating input cost volatility for precision grinding consumables.
- CNC control architecture switching costs:Proprietary OSP and Fanuc ecosystems lock buyers into single-vendor service dependencies, raising total cost of ownership for multi-brand machine parks.
- Electrochemical machining substitution:Hard-turning and abrasive flow finishing processes are capturing finish-machining applications previously reserved for precision grinding in aerospace blade root geometries.
Strategic Opportunities
- India manufacturing capacity expansion:PLI scheme incentives for automotive component localization are creating first-time precision grinding demand among domestic tier-two suppliers.
- Sensor-to-cloud spindle monitoring:Predictive maintenance software subscriptions are restructuring vendor revenue capture from installed bases across European automotive supplier parks.
- Hybrid additive-subtractive workflows:Near-net-shape metal deposition followed by finish grinding is opening machine tool specifications for directed energy deposition repair applications.
Industry Challenges
- CNC programming and metrology skill scarcity:Shops struggle to hire operators capable of integrating in-process gauging feedback loops with five-axis grinding kinematics.
- Retrofit versus replacement capital decisions:Tightening EU conformity windows force stakeholders to weigh control-system upgrades against full machine replacement amid energy-efficiency benchmarking pressures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grinding Machinery Market |
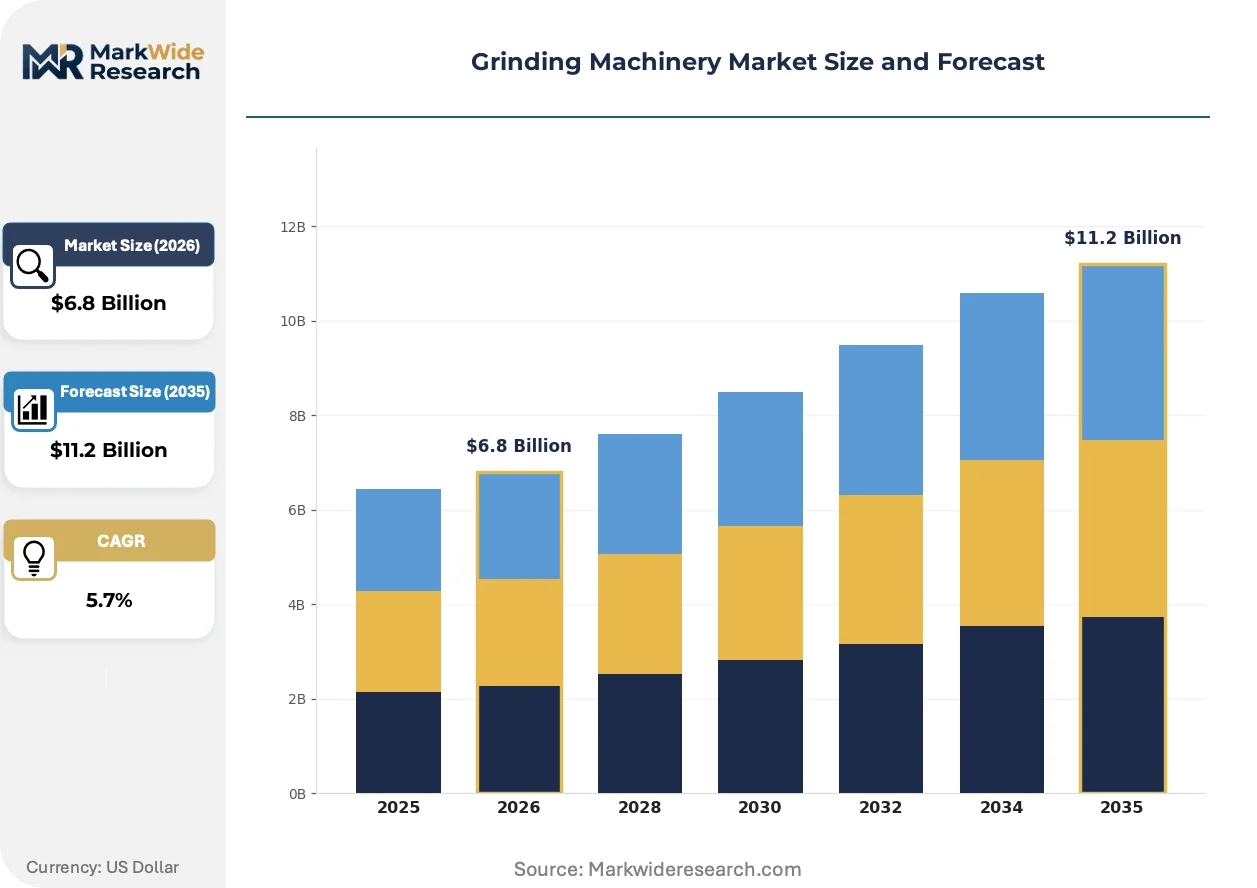
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cylindrical Grinder, Surface Grinder, Tool & Cutter Grinder, Bench Grinder Technology: Conventional Grinding, CNC Grinding, Gear Grinding, Centerless Grinding Material: Metal, Plastic, Ceramic, Wood End User: Aerospace, Automotive, Manufacturing, Electronics |
| Companies Covered | Amada Machine Tools, DANOBAT, ANCA Pty Ltd, DMG MORI, Fives, Körber AG, JTEKT Corporation, Okuma Corporation, Gleason Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grinding Machinery Market Strategic Shifts
Laser measurement and automated wheel dressing systems are converging with traditional grinding platforms, compressing setup times and enabling unmanned resharpening workflows for solid-carbide cutting tools.
Intelligent grinding spindles equipped with vibration, temperature, and force sensors are integrating edge-computing analytics for real-time process optimization. Tier-one automotive suppliers in Germany and Japan are deploying these platforms for electric drivetrain shaft production, where the technology is integrating predictive quality control directly into the material-removal sequence.
REACH chemical restrictions and F-Gas Regulation phase-down schedules are pressuring manufacturers to eliminate perfluorinated compounds from grinding coolants and mist suppression systems. Metalworking fluid formulators are accelerating biodegradable synthetic alternatives, with the most stringent compliance timelines affecting gear grinding operations in EU-based automotive transmission plants.
Tool-and-die job shops are unbundling after-sales service contracts from initial equipment purchases, instead procuring spindle monitoring and wheel dressing as discrete subscription tiers. This reconfiguration is most visible in North American mold-making clusters, where buyers favor operational expenditure models over capital-intensive ownership structures for precision surface grinding capacity.
Grinding Machinery Market Segmentation
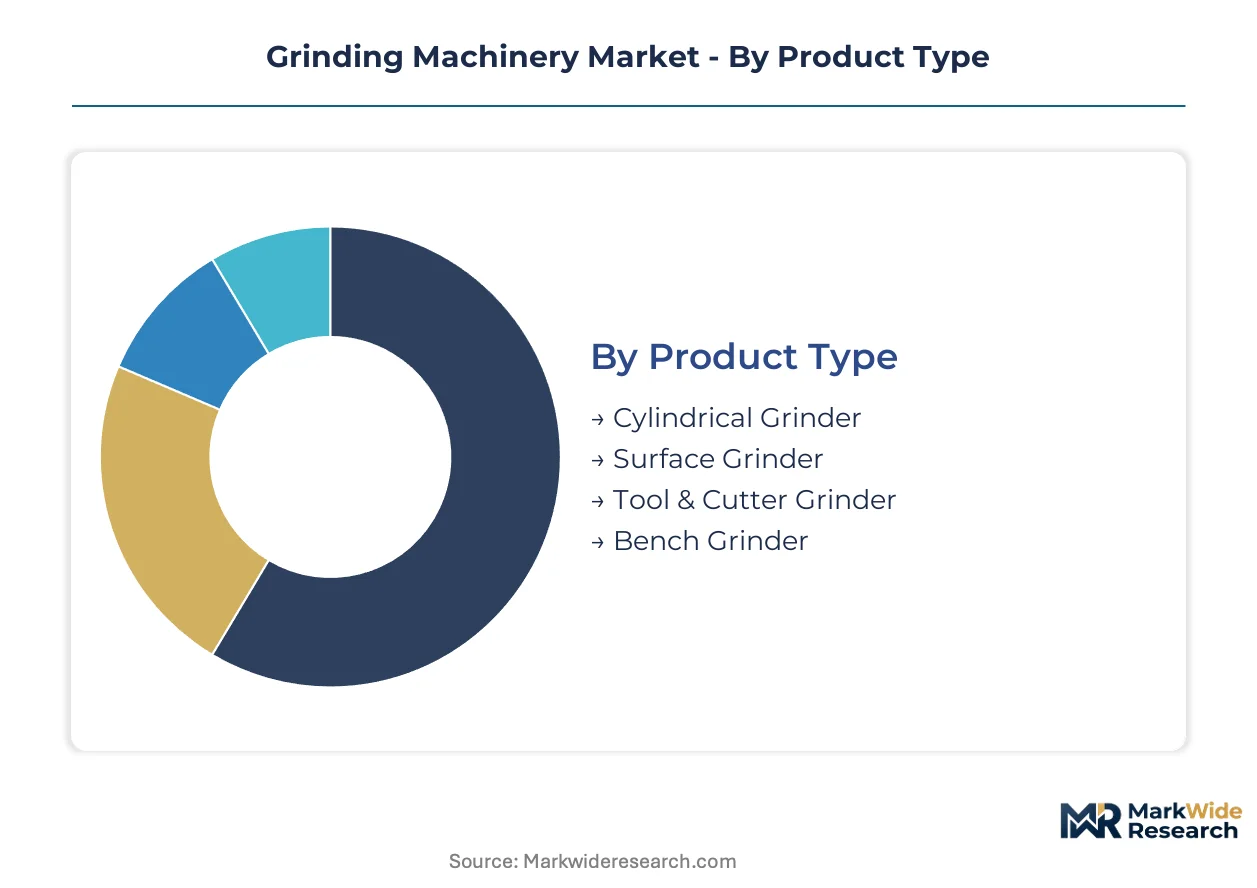
Grinding machinery segmentation reveals how upgrade cycles and compliance mandates concentrate demand across distinct equipment categories. Each dimension—product type, technology, material, and end user—carries specific replacement pressures that shape procurement timing and vendor selection criteria.
Product Type:
Replacement cycles for precision grinding equipment accelerate where tighter tolerances and regulatory mandates converge, forcing capital allocation toward platforms with integrated measurement and automation capabilities.
- Cylindrical Grinder:These machines achieve sub-micron repeatability on hardened shafts and bearing races through programmable wheel infeed and workpiece rotation. German automotive suppliers are retiring pre-2010 conventional units to meet EU Machinery Directive emergency-stop and noise-exposure requirements for electric drivetrain component production.
- Surface Grinder:Flat-surface finishing platforms employ reciprocating table or rotary table configurations for dies, molds, and precision plates. North American mold-making clusters favor subscription-based spindle monitoring over capital-intensive ownership, restructuring procurement toward operational expenditure models.
- Tool & Cutter Grinder:Specialized resharpening workflows for solid-carbide and high-speed steel cutting tools integrate laser measurement and automated wheel dressing.
- Bench Grinder:Compact fixed-grit platforms serve maintenance shops and light fabrication with minimal automation.
Cylindrical Grinder sits at the top of the volume ranking, with Tool & Cutter Grinder climbing the fastest.
Technology:
Control architecture determines service dependencies and total cost of ownership, locking buyers into vendor ecosystems that shape long-term maintenance expenditure patterns.
- CNC Grinding:Computer-numerical control platforms enable unmanned operation through in-process gauging feedback loops that reduce scrap rates. High-mix manufacturing environments in automotive supplier parks demand these systems for unmanned shifts and real-time quality verification.
- Conventional Grinding:Manual or semi-automatic mechanical architectures persist where capital budgets constrain investment and skill availability limits programming complexity. German Mittelstand tool-and-die shops face retrofit-versus-replacement decisions as EU conformity windows tighten for pre-2010 installations.
- Gear Grinding:Continuous generating or form-grinding processes produce hardened gear profiles with specified surface integrity for transmission applications.
- Centerless Grinding:Through-feed or in-feed configurations achieve high-volume cylindrical finishing without workpiece centering, suited to long production runs.
CNC Grinding dominates installed value, while Gear Grinding gains share fastest on electric drivetrain tolerance compression.
Material:
Workpiece material properties dictate abrasive selection, coolant chemistry, and machine rigidity specifications that segment procurement requirements across industries.
- Metal:Ferrous and non-ferrous alloys constitute the core application set, with hardened steels requiring cubic boron nitride or synthetic diamond abrasives. EPA metalworking fluid emission standards and OSHA silica exposure limits are driving wet-grinding system upgrades with closed-loop filtration across US metal fabrication facilities.
- Ceramic:Brittle, high-hardness workpieces demand specialized wheel specifications and reduced infeed rates to prevent fracture.
- Plastic:Thermoset and thermoplastic materials require modified coolant systems to prevent thermal distortion and surface degradation.
- Wood:Specialized abrasive grades address cellulose fiber structure and resin content in tool resharpening applications.
Metal commands the largest addressable base, with Ceramic expanding most quickly on aerospace thermal barrier coating applications.
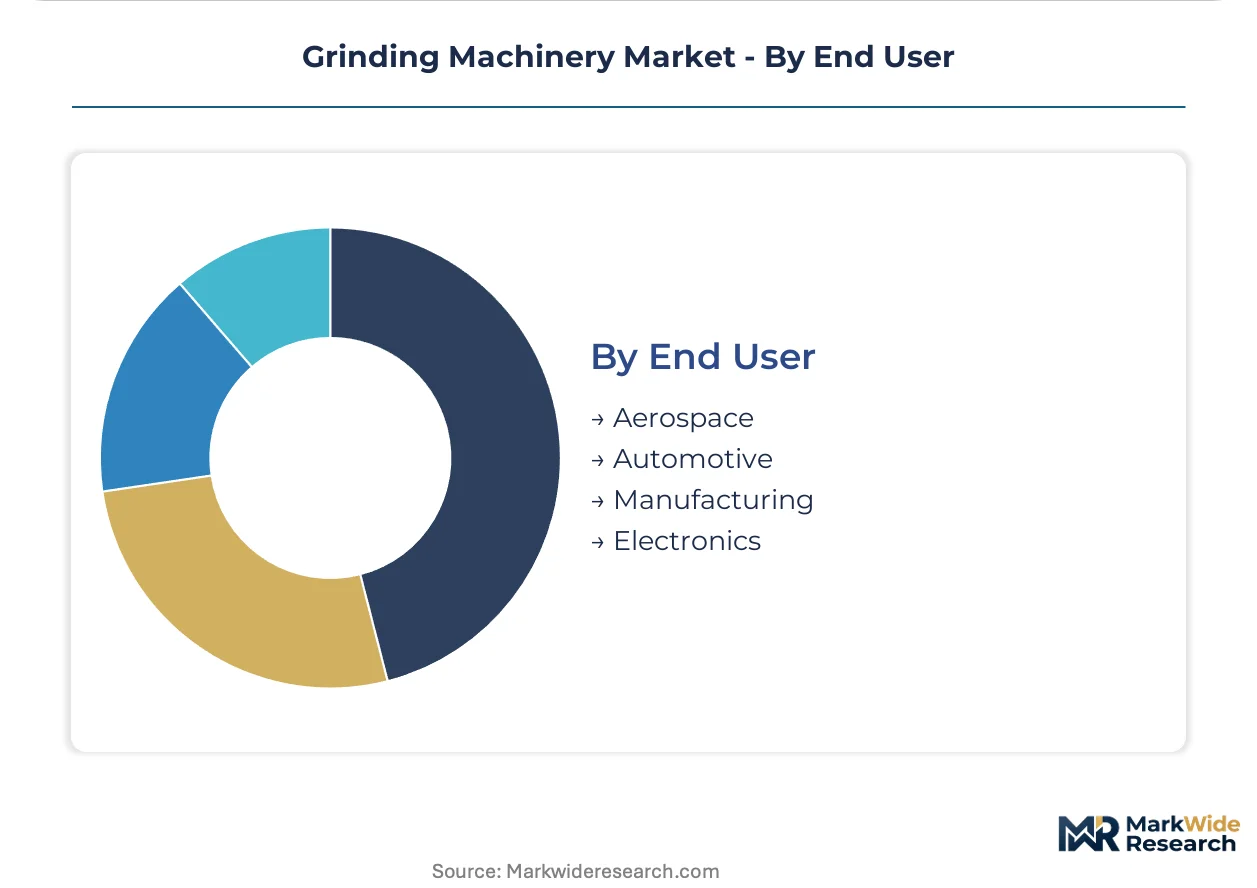
End User:
Industry-specific quality system mandates and tolerance requirements create divergent specification pressures that shape grinding platform selection and measurement integration priorities.
- Automotive:Electric drivetrain manufacturing compresses shaft and bearing tolerance specifications, forcing tier-one suppliers to replace legacy cylindrical grinders with sub-micron repeatability platforms. German and Japanese automotive parks deploy intelligent spindles with vibration and temperature sensors for predictive quality control integrated directly into material-removal sequences.
- Aerospace:Turbine blade root geometries and bearing races demand documented surface finish traceability with automated measurement integration. Hard-turning and abrasive flow finishing processes are capturing some finish-machining applications previously reserved for precision grinding in specific component families.
- Manufacturing:General metal fabrication and job shop operations span die-making, mold repair, and precision component finishing with varied volume and mix requirements.
- Electronics:Miniaturized components and semiconductor packaging materials require specialized micro-grinding and ultra-precision finishing platforms.
Automotive leads end-user demand volume, with Aerospace posting the steepest specification escalation trajectory on regulatory documentation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands precision grinding capacity investment while China scales domestic machine tool production for automotive supply chains. Regulatory compliance windows and electric drivetrain tolerance compression are redirecting capital across divergent industrial bases.
Germany
Mittelstand tool-and-die shops anchor replacement cycles for cylindrical and gear grinding equipment as electric drivetrain manufacturing compresses shaft tolerance specifications. The EU Machinery Directive's emergency-stop and noise-exposure mandates accelerate retirement of pre-2010 conventional installations. Stuttgart and Munich automotive supplier parks deploy intelligent spindles with predictive quality control for bearing race production.
United States
EPA metalworking fluid emission standards and OSHA silica exposure limits drive wet-grinding system upgrades with closed-loop coolant filtration across metal fabrication facilities. FDA quality system regulations for orthopedic implant manufacturers mandate documented surface finish traceability with automated measurement integration. Detroit-area automotive tier-one suppliers retrofit cylindrical grinding capacity for electric axle shaft programs.
China
Domestic machine tool builders expand CNC grinding output to serve localized automotive component manufacturing. MIIT equipment upgrade guidelines and dual carbon goals pressure metalworking facilities toward energy-efficient platform replacement. Yangtze River Delta precision component clusters absorb imported European gear grinding technology for transmission production.
India
PLI scheme incentives for automotive component localization create first-time precision grinding demand among domestic tier-two suppliers. BIS machinery safety standards and import substitution policies redirect procurement toward qualified domestic vendors. Pune and Chennai automotive supplier parks install cylindrical grinding capacity for electric two-wheeler drivetrain components.
Japan
Intelligent grinding spindle platforms with edge-computing analytics penetrate electric drivetrain shaft production at tier-one automotive suppliers. METI productivity enhancement programs subsidize CNC retrofitting for conventional grinding installations in subcontractor networks. Nagoya and Osaka precision manufacturing clusters integrate predictive maintenance subscriptions for unmanned grinding operations.
Grinding Machinery Market Competitive Environment
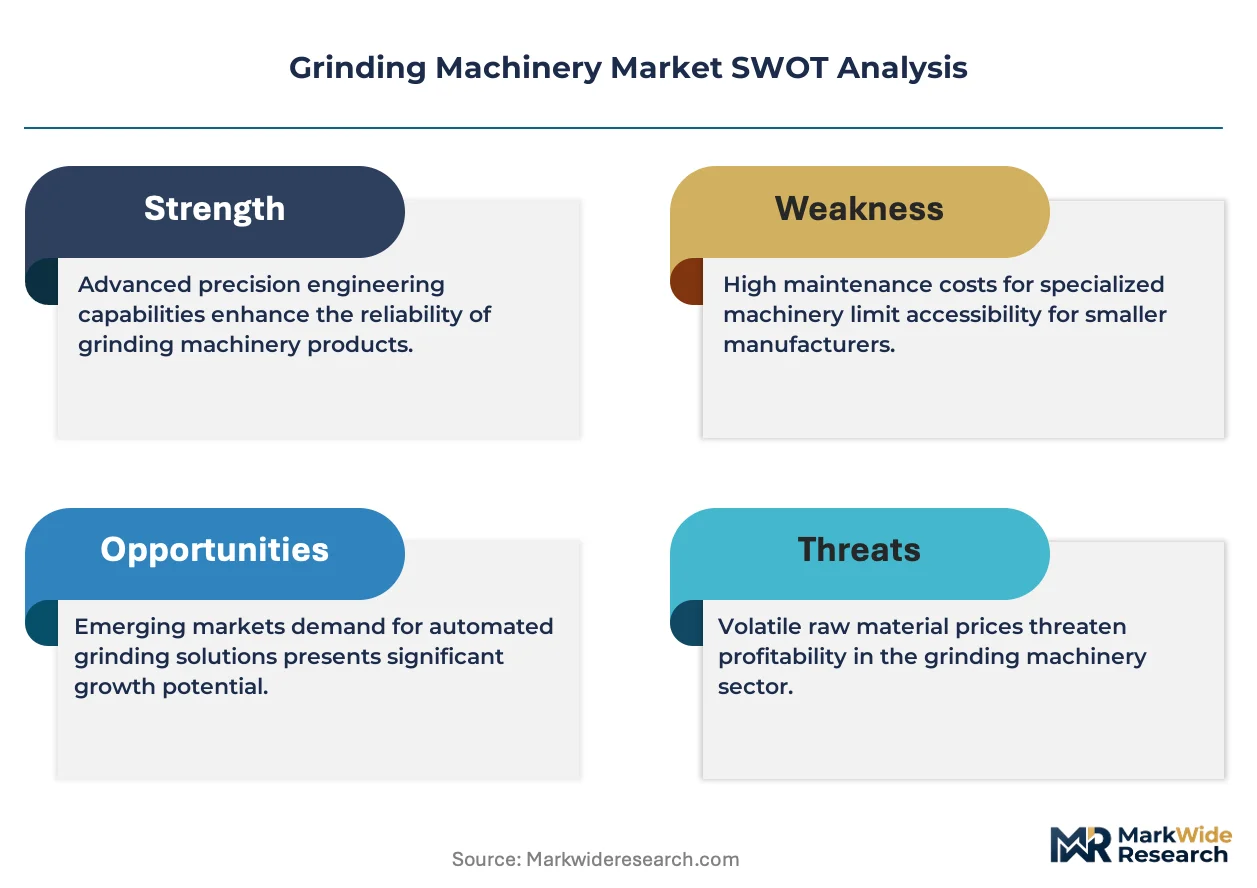
Top-tier vendors anchor premium CNC platform supply, while mid-tier specialists and regional fabricators occupy distinct price-performance bands. Japanese and German headquartered companies concentrate proprietary control architecture development, locking service dependencies and recurring revenue streams. Three strategic archetypes dominate: integrated machine tool conglomerates with sensor-to-cloud platforms, precision grinding specialists with automated measurement systems, and regional builders serving cost-sensitive replacement demand. Competitive moves center on spindle monitoring software subscriptions and control-system retrofit partnerships for compliance-driven upgrade cycles.
Within the integrated conglomerate tier, DMG MORI and Okuma Corporation exemplify vendors capturing aftermarket value through proprietary control ecosystems and predictive maintenance platforms. ANCA Pty Ltd occupies a specialist position in laser measurement and automated wheel dressing systems for cutting-tool resharpening workflows. These three companies represent contrasting archetypes: sensor-to-cloud platform integration, proprietary CNC architecture lock-in, and application-specific automation specialization.
| Leading Market Players |
|---|
| Amada Machine Tools |
| DANOBAT |
| ANCA Pty Ltd |
| DMG MORI |
| Fives |
| Körber AG |
| JTEKT Corporation |
| Okuma Corporation |
| Gleason Corporation |
| Others |
Value Chain & Pricing Dynamics
CNC programming and metrology specialists concentrated in southern Germany and western Japan command wage premiums that widen pricing spreads between premium-tier CNC platforms and economy-grade conventional grinders. Labor-cost differentials between these high-skill manufacturing clusters and emerging machine tool production zones in India and Vietnam translate directly into three-tier pricing stratification across global procurement markets.
Pricing Analysis
Capacity additions in China's Yangtze River Delta machine tool corridor are reshaping price floors for mid-range cylindrical grinding equipment. Three-tier pricing structure across premium, standard, and economy levels separates sensor-integrated CNC platforms with predictive maintenance subscriptions from mechanically simpler job-shop configurations. Pricing pressure stems from domestic Chinese builders capturing share in cost-sensitive replacement cycles. Tier-two automotive suppliers in India exhibit the highest price sensitivity, while German Mittelstand tool-and-die shops prioritize specification compliance over acquisition cost.
Supply Chain Analysis
Dual-sourcing qualification mandates from tier-one automotive suppliers in Germany and Japan prevent single-source dependency on Taiwanese spindle bearing manufacturers or Chinese cast iron bed suppliers. Synthetic diamond and cubic boron nitride abrasive grit production concentrates in China, Japan, and limited South Korean supply basins. Supply chain risk centers on tariff exposure for precision ball screw imports from specific trade-restricted jurisdictions. Distribution runs through authorized dealer networks with captive service capabilities rather than open wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grinding machinery procurement has shifted toward late-cycle quality specifications as electric drivetrain tolerance compression elevates demand for sub-micron repeatability platforms with integrated measurement traceability.
For Market Incumbents: Cement aftermarket revenue capture through sensor-to-cloud spindle monitoring subscriptions that lock in multi-year service dependencies across European automotive supplier parks. Deepen upstream control over precision ball screw and linear guide production to insulate margin structures from input cost volatility. Electrochemical machining substitution in aerospace blade root geometries represents the most pressing technology threat requiring defensive R&D response. For New Entrants and Emerging Players: Tier-two automotive suppliers in India's PLI scheme corridors offer the most penetrable white-space opportunity for first-time precision grinding capacity installation. Target cylindrical grinding configurations for electric two-wheeler drivetrain components where domestic qualification requirements redirect procurement from established European vendors. Partner with local machine tool distributors possessing existing relationships with Pune and Chennai automotive clusters to accelerate market access without direct sales infrastructure buildout. For Investors and Strategic Acquirers: Industrial automation conglomerates with existing CNC control architecture ecosystems are the most active acquirers in this space, seeking precision grinding specialists to fill capability gaps in sensor-integrated finishing workflows. Acquisition targets with laser measurement and automated wheel dressing IP command valuation premiums. Watch for inflection when tier-one automotive suppliers begin mandating predictive maintenance subscription inclusion in new equipment procurement specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Spindle Monitoring Platform Integration | Sensor-to-cloud subscriptions from DMG MORI capture recurring revenue from German automotive parks. |
| Proprietary CNC Architecture Lock-in | Okuma Corporation's OSP ecosystem reduces third-party service dependency for tier-one suppliers. |
| Laser Measurement System Specialization | ANCA Pty Ltd's automated wheel dressing dominates cutting-tool resharpening workflow margins. |
| Closed-loop Coolant Filtration Deployment | Wet-grinding upgrades satisfy EPA emission standards across US metal fabrication facilities. |
| EU Machinery Directive Retrofit Partnerships | Control-system upgrades capture replacement cycles in German Mittelstand tool-and-die shops. |
Study Parameters
Bottom-up end-use demand modeling reconciled against top-down machine tool production tracking forms the analytical core of this study. Primary interviews with maintenance directors at automotive tier-one suppliers, plant engineers in German Mittelstand tool-and-die shops, OEM procurement teams specifying grinding capacity, and aftermarket service heads at distributor networks informed demand-side assumptions. Secondary validation drew from customs trade data for machine tool imports, SEC 10-K filings of listed equipment manufacturers, MIIT equipment upgrade guidelines, and BIS machinery safety standard documentation.
Historical trendline analysis of replacement cycle timing and regulatory compliance windows established baseline growth patterns across the projection horizon. Segmentation modeling spanned product type, control technology, workpiece material, and end-use industry vertical with additional granularity for electric drivetrain versus internal combustion component specifications. CAGRs were derived from installed base aging analysis correlated with capital expenditure survey data. Forecast inputs incorporated EU Machinery Directive enforcement timelines, EPA metalworking fluid emission standard phase-ins, and PLI scheme incentive disbursement schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to electrochemical machining substitution rates in aerospace applications and synthetic diamond abrasive supply concentration shifts. Deviation in tier-one automotive supplier predictive maintenance subscription adoption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Europe Construction Equipment Market
Construction Equipment
Self-Driving Dumpers Machine Market
Construction Equipment
Static and Rotating Equipment Market
Construction Equipment
Yard Crane Market
Construction Equipment
Construction Wearable Technology Market
Construction Equipment
Construction Pump Market
Construction Equipment
Welding Equipment Market
Construction Equipment
Italy Construction Equipment Market
Construction Equipment
Tunneling Equipment Market
Construction Equipment
Manual Welding Positioner Market
Construction Equipment
Latin America Construction Equipment Market
Construction Equipment
Drone-Based Solutions in Construction Market
Construction Equipment
Hydraulic Spreader Market
Construction Equipment
Australia Mobile Cranes Rental Market
Construction Equipment
South Korea Heavy Construction Equipment Rental Market
Construction Equipment
Thermal Spray Equipment Market