
 Global Intelligent Sanitary Ware Market | 2026-2036
Global Intelligent Sanitary Ware Market Size, Share, and Industry Trends Forecast 2026-2036
Global Intelligent Sanitary Ware Market Foresight
Modular smart-toilet systems that separate the ceramic base from the electronic seat and bidet module is rebalancing how facility managers evaluate lifecycle costs versus upfront capital. TOTO leverages its integrated washlet manufacturing to anchor premium positioning across Japanese and North American hospitality channels. Kohler competes through broad distribution control, while LIXIL Group extends its reach via standardized connectivity protocols that reduce installation complexity for property developers.
Intelligent sanitary ware comprises ceramic and non-ceramic fixtures embedded with sensor arrays, microprocessors, and connectivity modules to deliver automated flushing, temperature-controlled cleansing, and usage analytics. Infrared sensor technology dominates commercial restroom deployments due to proven reliability in high-traffic environments, while voice recognition and artificial intelligence segments attract R&D investment from brands targeting residential premiumization. Smart toilets concentrate margin pools through recurring consumable and service attach rates, whereas sensor faucets represent the most mature category with price-driven competition among facility management procurement.
EPA WaterSense certification shapes North American product access by mandating flow-rate maximums that intelligent fixtures must demonstrate under test conditions. The EU Ecodesign Directive and CE marking requirements enforce standby power limits and material recyclability standards that manufacturers must satisfy for European market entry. China's GB standards and MIIT connectivity regulations add compliance layers for Wi-Fi-enabled models. Stakeholders must monitor divergence between regional interoperability standards and decide whether to develop platform-agnostic firmware or commit to geography-specific product variants.
Market Dynamics
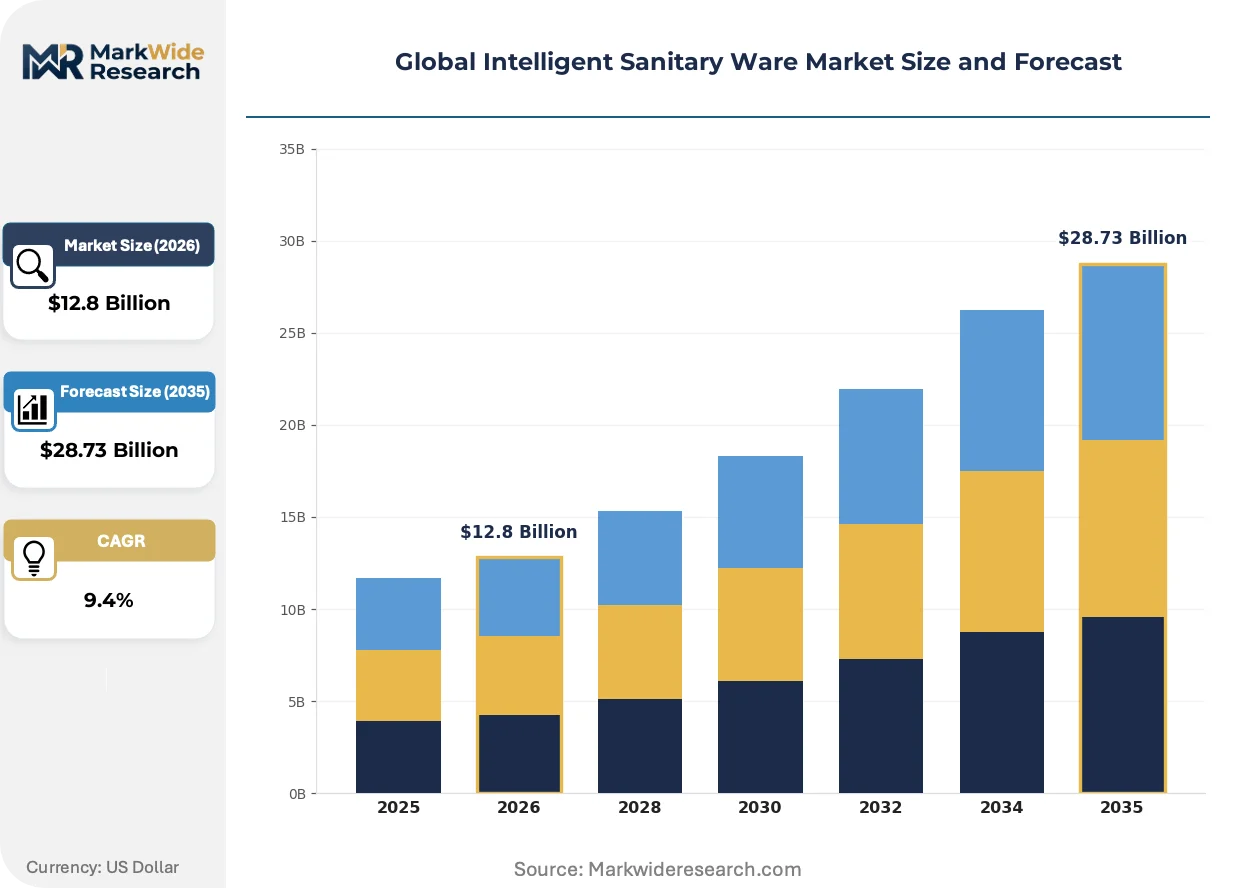
Water-efficiency mandates from EPA WaterSense and EU Ecodesign are forcing accelerated replacement cycles across commercial real estate portfolios, while modular system architectures are compressing lifecycle cost calculations for facility managers evaluating capital deployment.
Growth Catalysts
- EPA WaterSense mandates:Flow-rate maximums for sensor-based fixtures are accelerating fixture replacement in US commercial buildings and hospitality properties.
- Smart hospitality installations:Dubai and Singapore hotel chains are specifying integrated intelligent suites as competitive differentiation amenities.
- China's tier-one property development:Premium residential towers in Shanghai, Beijing, and Shenzhen are standardizing connected sanitary systems in new construction specifications.
Market Restraints
- Ceramic-electronic integration complexity:Tight coupling between ceramic bases and electronic modules creates repair cost inflation and extended downtime risks.
- Regional standard fragmentation:Divergence between EPA WaterSense, EU Ecodesign, and China's GB standards forces firmware variant proliferation.
- Sensor reliability thresholds:Infrared arrays in high-traffic environments face calibration drift that degrades user experience and increases maintenance frequency.
Strategic Opportunities
- India's underpenetrated premium residential segment:Tier-one cities Mumbai and Bangalore show rising developer interest in smart bathroom specifications for luxury projects.
- Voice-AI convergence:Integration of natural language processing with bidet controls creates differentiation in residential premiumization.
- Aftermarket seat-module retrofit:Separable electronic bidet modules enable upgrade paths for existing ceramic installations without full fixture replacement.
Industry Challenges
- Installation technician skill gaps:Plumbers lack training for Wi-Fi commissioning and firmware configuration required for connected fixture deployment.
- Multi-certification timeline compression:Simultaneous pursuit of EPA WaterSense, CE marking, and MIIT connectivity approvals extends product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Intelligent Sanitary Ware Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $28.73 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Toilets, Sensor Faucets, Automatic Urinals, Touchless Bidets, Intelligent Showers Technology: Infrared Sensors, Voice Recognition, Wi-Fi Connectivity, Bluetooth, Artificial Intelligence Application: Residential Bathrooms, Commercial Restrooms, Hospitality Facilities, Healthcare Institutions, Educational Establishments End User: Property Developers, Facility Management Firms, Hospitality Chains, Healthcare Providers, Educational Administrators |
| Companies Covered | Roca, Orans Co, TOTO, Jaquar, INAX, LIXIL Group, Duravit, Hengjie, Kohler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Intelligent Sanitary Ware Market Shifts & Advancements
Intelligent sanitary ware is pivoting from standalone automation toward platform-integrated building systems, with sensor data streams becoming inputs for energy management and predictive maintenance workflows.
Modular seat-and-base separation is decentralizing procurement authority in commercial facilities. Property developers in Singapore and Dubai are sourcing ceramic bases from traditional suppliers while negotiating electronic modules separately through building automation integrators. This architecture compresses capital allocation flexibility and fragments vendor relationships across the installation lifecycle.
EU Ecodesign Directive standby power limits are forcing component redesign across European-bound product lines. Manufacturers must demonstrate sub-watt idle consumption under test conditions certified by notified bodies. Residential smart toilet categories face the steepest compliance cost inflation as heating elements and always-on connectivity modules dominate power budgets.
Facility management procurement is consolidating around lifecycle cost models that unbundle upfront fixture price from ten-year maintenance and consumable projections. US healthcare and hospitality portfolios are leading this transition, with procurement teams demanding sensor reliability data and spare parts availability guarantees before specification approval. This behavior shift compresses price-only competition and elevates service infrastructure as a selection criterion.
Global Intelligent Sanitary Ware Market Segmentation
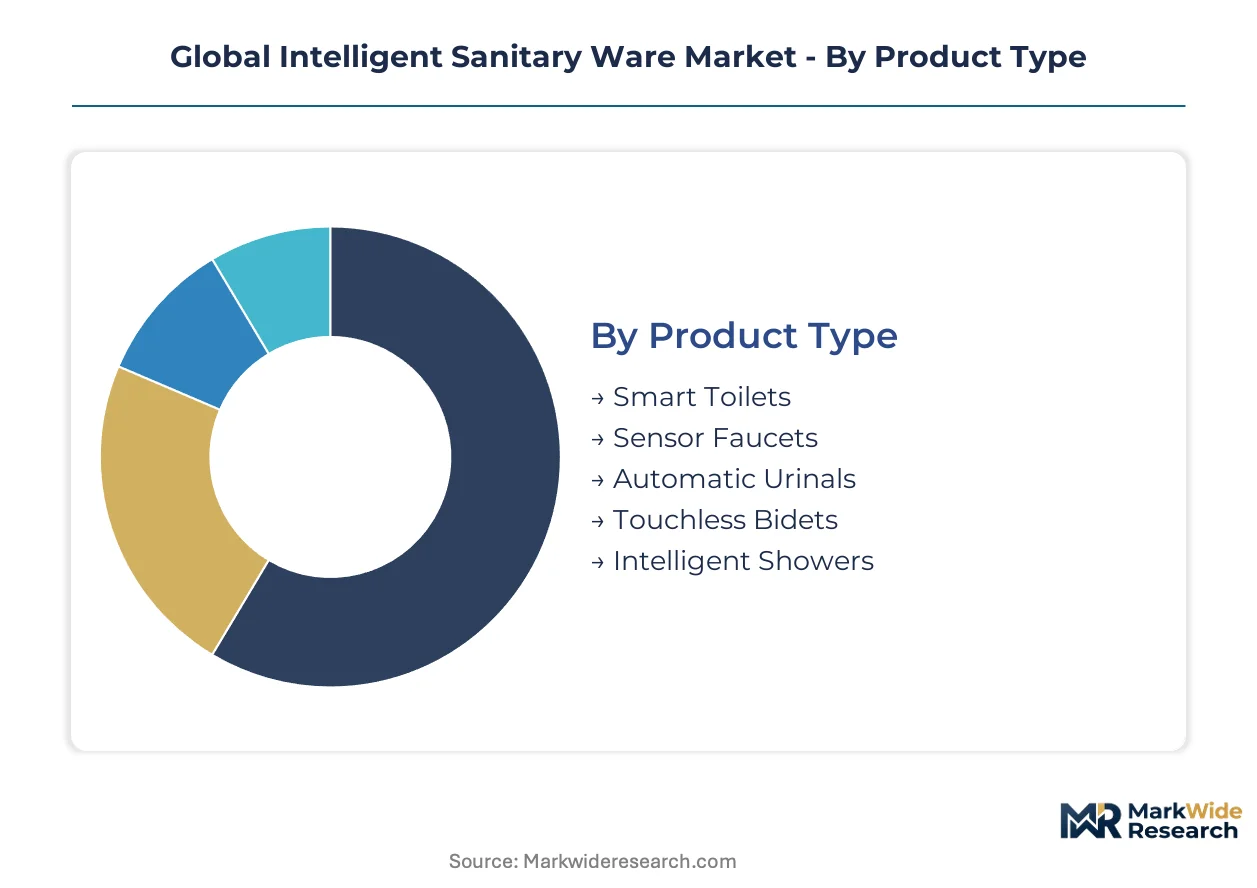
Intelligent sanitary ware segmentation reveals divergent margin structures across product categories, with ceramic-electronic integration complexity creating tiered investment profiles. Technology choices separate high-traffic commercial specifications from residential premiumization plays, while application context determines sensor reliability requirements and connectivity protocol selection.
Product Type:
Volume concentrates in sensor faucets and automatic urinals, while premium margin pools accumulate in fully integrated smart toilet systems with separable electronic modules.
- Smart Toilets:Ceramic bases paired with electronic bidet modules deliver temperature-controlled cleansing, automated flushing, and usage analytics. Demand clusters in China's tier-one cities where property developers specify integrated suites in premium residential towers, driven by competitive differentiation mandates.
- Sensor Faucets:Infrared-activated fixtures dominate commercial restroom deployments with proven reliability in high-traffic environments. US healthcare and hospitality portfolios are consolidating procurement around lifecycle cost models that unbundle upfront price from ten-year maintenance projections.
- Automatic Urinals:Waterless and low-flow variants address EPA WaterSense flow-rate maximums in US commercial buildings.
- Touchless Bidets:Aftermarket seat-module retrofits enable upgrade paths for existing ceramic installations without full fixture replacement.
- Intelligent Showers:Temperature and flow control systems with digital interfaces attract R&D investment for residential premiumization.
Mature deployment sits with sensor faucets. Newer deployment is concentrated in smart toilets with modular architectures.
Technology:
Application context drives technology selection, with reliability requirements in commercial settings favoring proven sensing modalities over experimental interfaces.
- Infrared Sensors:Dominant technology for commercial restroom deployments due to calibration stability in high-traffic environments. Facility managers in Dubai and Singapore hospitality chains specify infrared arrays for their proven uptime metrics and lower maintenance frequency.
- Voice Recognition:Natural language processing integration with bidet controls creates differentiation in residential premiumization segments. EU Ecodesign standby power limits force component redesign as always-on listening modules consume idle power budgets.
- Wi-Fi Connectivity:Enables remote diagnostics and usage analytics for facility management platforms. China's MIIT connectivity regulations add compliance layers for firmware certification.
- Bluetooth:Short-range pairing for residential user preference storage and mobile app control.
- Artificial Intelligence:Usage pattern recognition and predictive maintenance algorithms attract R&D investment from brands targeting building automation integration.
Proven reliability sits with infrared sensors. Steepest expansion trajectory is concentrated in voice-AI convergence for residential specifications.
Application:
End-use environment determines sensor durability specifications, connectivity requirements, and procurement authority structures.
- Residential Bathrooms:Premium new construction and renovation projects specify connected sanitary systems. Property developers in Shanghai, Beijing, and Shenzhen are standardizing intelligent suites as baseline specifications in luxury towers.
- Commercial Restrooms:High-traffic environments demand sensor reliability guarantees and spare parts availability commitments. US facility management procurement teams now require ten-year maintenance projections before specification approval.
- Hospitality Facilities:Dubai and Singapore hotel chains deploy integrated intelligent suites as competitive differentiation amenities.
- Healthcare Institutions:Infection control protocols drive touchless fixture mandates with stringent hygiene certification requirements.
- Educational Establishments:Budget-constrained procurement favors durable sensor faucets with minimal maintenance requirements over full intelligent suite installations.
Standardized procurement sits with commercial restrooms. Fragmented vendor relationships are concentrated in hospitality facilities with modular system architectures.
End User:
Purchasing authority fragments across the installation lifecycle as modular architectures separate ceramic base procurement from electronic module specification.
- Property Developers:Control upfront specification for new construction, increasingly sourcing ceramic bases separately from electronic modules through building automation integrators. Singapore and Dubai developers are leading this procurement decentralization.
- Facility Management Firms:Consolidate lifecycle cost evaluation authority, demanding sensor reliability data and consumable attach rate projections. US healthcare and hospitality portfolios are compressing price-only competition through this behavior shift.
- Hospitality Chains:Specify integrated intelligent suites as brand-standard amenities with centralized procurement negotiations.
- Healthcare Providers:Infection control committees drive touchless fixture mandates with clinical durability requirements.
- Educational Administrators:Capital budget constraints favor lowest-total-cost-of-ownership specifications over premium feature sets.
Centralized specification authority sits with hospitality chains. Dispersed procurement decision-making is concentrated in commercial real estate with modular system adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates production capacity for ceramic bases and electronic modules, while consumption divides across hospitality-driven installations in the UAE and Singapore, premium residential specifications in Japan, and commercial retrofit demand in the United States. Regulatory divergence across these markets shapes firmware variant requirements and certification timelines.
United States
Commercial real estate portfolios and hospitality chains drive sensor-based fixture replacements under EPA WaterSense flow-rate mandates. Healthcare institutions enforce touchless mandates through infection control protocols. Facility management procurement in New York and Chicago now demands ten-year maintenance projections before specification approval.
China
Property developers in Shanghai, Beijing, and Shenzhen standardize connected sanitary systems in premium residential towers as baseline luxury specifications. MIIT connectivity regulations add firmware certification layers for Wi-Fi-enabled models. The Yangtze River Delta hosts manufacturing clusters for ceramic-electronic integration.
Japan
Integrated washlet systems anchor residential premiumization with established consumer acceptance. METI efficiency standards and JIS certification requirements shape product development. Osaka and Nagoya manufacturing bases supply hospitality channels across Asia-Pacific with proven reliability metrics.
United Arab Emirates
Dubai hospitality chains deploy integrated intelligent suites as competitive differentiation amenities. MOHAP building codes influence smart bathroom specifications in new hotel construction. Procurement decentralization separates ceramic base sourcing from electronic module negotiation through building automation integrators.
Singapore
Hotel chains and premium residential developers specify modular smart-toilet architectures that fragment vendor relationships. The Building and Construction Authority promotes water-efficiency standards that accelerate sensor faucet deployment. Marina Bay and Orchard Road clusters concentrate high-specification installations.
Global Intelligent Sanitary Ware Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across ceramic manufacturing, electronic module production, and integrated system assembly. The market structure tiers across full-suite integrators, component suppliers, and regional fabricators. Three strategic archetypes dominate: integrated Japanese manufacturers with washlet heritage, European design-led brands with distribution control, and Chinese scale producers with cost-optimized electronic modules. Competitive moves concentrate on modular architecture licensing and lifecycle service infrastructure buildout.
Among integrated Japanese manufacturers, TOTO and LIXIL Group exemplify full-suite positioning through captive washlet technology and standardized connectivity protocols. European design-led specialists include Roca and Duravit, which occupy positions emphasizing aesthetic differentiation and hospitality channel relationships. Chinese scale production concentrates in Hengjie and Orans Co, representing cost-optimized electronic module supply for aftermarket retrofit applications.
| Leading Market Players |
|---|
| Roca |
| Orans Co |
| TOTO |
| Jaquar |
| INAX |
| LIXIL Group |
| Duravit |
| Hengjie |
| Kohler |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap ceramic specialists in China's Yangtze River Delta have consolidated electronic module sourcing through captive joint ventures, tightening pricing discipline across sensor faucet and smart toilet categories while resisting margin erosion from modular procurement fragmentation.
Pricing Analysis
Cost-down pressure on standard-grade sensor faucets accelerates because facility management procurement teams in US healthcare and hospitality portfolios now mandate ten-year lifecycle cost guarantees before specification approval. Three-tier pricing structure across premium, standard, and economy levels separates EPA WaterSense-certified fixtures from basic infrared models and voice-AI residential units. Price differentiation hinges on certification grade and after-sales service bundling, with commercial buyers exhibiting highest sensitivity to upfront capital outlay while residential premium segments absorb feature premiums for connectivity and AI integration.
Supply Chain Analysis
Dual-sourcing requirements from Dubai and Singapore hospitality chains now mandate qualified ceramic base suppliers from China alongside electronic module vendors from Japan or South Korea. Manufacturing draws from Changzhou ceramic clusters, Osaka washlet component foundries, and Penang sensor assembly operations. Raw material dependencies span alumina for ceramic bases, silicon wafers for infrared arrays, and rare-earth magnets for voice-coil actuators. Single-source vulnerability concentrates in proprietary washlet heating element designs. Distribution runs through building automation integrators for modular architectures and traditional plumbing wholesalers for integrated systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play where multi-certification timeline compression and installation technician skill gaps force sub-scale component vendors toward exit or acquisition.
For Market Incumbents: Anchor service infrastructure as the primary retention mechanism against modular procurement fragmentation threatening integrated system margins. Defensive moves require backward integration into ceramic-electronic bonding processes to compress repair downtime liabilities, plus certification investment spanning EPA WaterSense, EU Ecodesign, and MIIT connectivity to extend product launch windows. Threat substitution from voice-AI residential specialists demands preemptive platform-agnostic firmware development. For New Entrants and Emerging Players: Voice-AI convergence with natural language bidet control offers a technology-first wedge into Japan's residential premiumization segment where established washlet acceptance lowers education costs. White-space targets concentrate in India's Mumbai and Bangalore luxury residential towers and aftermarket seat-module retrofit channels for existing ceramic installations in European renovation markets. Go-to-market positioning through building automation integrators rather than traditional plumbing distribution bypasses incumbent channel lock-in. For Investors and Strategic Acquirers: Distressed-cycle entries favor electronic module specialists with MIIT-certified firmware stacks and spare parts logistics networks in China's Pearl River Delta manufacturing corridor. Long-term viability across the projection horizon rests on service attach rate sustainability rather than hardware shipment volume. Acquisition target archetypes include regional fabricators with dormant EPA WaterSense certifications and established hospitality channel relationships. Signal to watch: facility management procurement mandate expansion from ten-year maintenance projections to outcome-based uptime guarantees.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Architecture Licensing | Enables property developers in Singapore to fragment vendor relationships across installation lifecycle. |
| Multi-Certification Investment | Compresses EPA WaterSense, EU Ecodesign, and MIIT approval timelines for unified product platforms. |
| Service Infrastructure Buildout | Captures lifecycle revenue pools as US healthcare procurement demands spare parts availability guarantees. |
| Voice-AI R&D Partnership | Differentiates residential premium offerings against TOTO and LIXIL washlet heritage positioning. |
| Aftermarket Retrofit Channel Development | Unlocks upgrade paths for existing ceramic installations without full fixture replacement costs. |
Research Methodology
Document review covered EPA WaterSense certification databases, EU Ecodesign Directive implementing measures, and MIIT connectivity regulation filings, complemented by interviews with facility management procurement directors, building automation integrators, ceramic manufacturing plant managers, and hospitality chain specification architects. Secondary validation drew from customs trade data for ceramic sanitary ware imports, SEC 10-K filings of listed building products conglomerates, and property developer tender documents from Shanghai and Dubai. Bottom-up shipment estimates triangulated against top-down construction spending allocations across commercial real estate and hospitality sectors.
Segment-level value outputs derived from product-type splits across smart toilets, sensor faucets, and automatic urinals, technology modalities spanning infrared sensors and voice-AI interfaces, and application contexts separating residential bathrooms from commercial restrooms and hospitality facilities. CAGRs were computed from fitted growth curves against regulatory mandate implementation schedules and property development pipeline data. Industry-specific forecast inputs incorporated EPA WaterSense retrofit acceleration timelines and China's tier-one city luxury residential specification rates.
Several conditions sit outside the modeled scope, including potential divergence between regional interoperability standards forcing geography-specific firmware variants, and ceramic-electronic integration complexity breakthroughs that could alter repair cost structures. Forecasts reflect documented assumptions regarding sensor reliability thresholds and installation technician training pipeline expansion. Deviation in multi-certification timeline compression or hospitality capital expenditure cycles would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
South Africa Wall Putty Market
Building & Construction Materials
Non-Residential Polished Concrete Market
Building & Construction Materials
Plumbing Fixtures Market
Building & Construction Materials
Oriented Strand Board (OSB) Market
Building & Construction Materials
Latin America Prefab Wood Buildings Market
Building & Construction Materials
Plumbing Fixtures and Fittings Manufacturing Market
Building & Construction Materials
China Concrete Superplasticizer Market
Building & Construction Materials
Europe Sandwich Panels Market
Building & Construction Materials
Piping Systems Market
Building & Construction Materials
US Residential and Commercial Roofing Materials Market
Building & Construction Materials
United States Gutter Guards Market
Building & Construction Materials
Fire Hydrant System Market
Building & Construction Materials
Barn Door Hardware Market
Building & Construction Materials
Seal Coat Market
Building & Construction Materials
Household Mosaic Tiles Market
Building & Construction Materials
Europe I-Joist Market