
 Aerated Autoclaved Concrete (AAC) Market | 2026-2036
Aerated Autoclaved Concrete (AAC) Market Size, Share, and Industry Trends Forecast 2026-2036
Aerated Autoclaved Concrete (AAC) Market Outlook
CE marking under the EU Construction Products Regulation is collapsing the supplier base for AAC exports into European projects. Xella International leverages its pan-European plant network to sustain specification-grade output for German passive-house builders. H+H International anchors Nordic supply through its integrated lime-sand sourcing in Denmark. UltraTech Cement Ltd. competes on cost in South Asian infrastructure tenders where imported European panels face duty disadvantages.
Aerated autoclaved concrete is a lightweight precast building material manufactured from quartz sand, lime, cement, gypsum, water, and aluminum powder that generates hydrogen gas to create porous cellular structure during autoclave curing at approximately 200°C and 12 bar pressure, yielding densities from 300 to 800 kg/m³ with compressive strength ranging 2 to 8 N/mm² for structural and non-structural applications. Block products dominate volume shipments for load-bearing masonry in mid-rise residential construction across emerging economies, while panel systems command premium positioning in commercial facade and cladding applications where factory-precise dimensional tolerance reduces on-site labor. Wall construction applications absorb the majority of AAC consumption, though fire protection specifications in high-occupancy commercial buildings are driving specification upgrades to thicker, reinforced panel grades.
EMA's construction product oversight through harmonized EN standards shapes European AAC performance benchmarks, while India's BIS certification requirements for autoclaved cellular concrete blocks govern domestic manufacturing quality and import eligibility. China's GB standards administered by SAMR mandate thermal conductivity thresholds that favor higher-density AAC formulations in northern heating zones. Stakeholders must monitor how evolving embodied-carbon disclosure rules under the EU CSRD and comparable frameworks elsewhere reshape material procurement criteria for green-building certifications.
Market Dynamics
EU Green Deal embodied carbon disclosure rules are compressing specification timelines for AAC suppliers serving German and French passive-house developments, forcing accelerated certification upgrades across the value chain.
Growth Catalysts
- EU CSRD mandates:Corporate sustainability reporting requirements are pulling AAC into commercial facade specifications across Denmark and Sweden as developers seek lower embodied-carbon alternatives to traditional concrete cladding.
- China's dual carbon goals:Provincial green building codes in Jiangsu and Zhejiang are tightening thermal conductivity thresholds, directing public housing procurement toward higher-density AAC formulations.
- India's PLI scheme for construction materials:Production-linked incentives for domestic manufacturing are accelerating capacity additions near limestone-rich clusters in Rajasthan and Gujarat.
Market Restraints
- Aluminum powder price volatility:The hydrogen-generating agent essential for AAC's cellular structure faces supply concentration from Chinese specialty chemical producers, creating margin pressure during energy price spikes.
- Autoclave equipment lead times:German and Italian pressure vessel manufacturers command 18-24 month delivery schedules, throttling capacity expansion for mid-scale entrants in emerging markets.
- Structural height limitations:AAC's compressive strength ceiling of 8 N/mm² restricts load-bearing applications to mid-rise construction, ceding high-rise core-and-shell markets to reinforced concrete.
Strategic Opportunities
- Panel-to-facade integration:Factory-cast AAC cladding with embedded thermal breaks is displacing conventional curtain wall assemblies in Nordic commercial retrofits seeking single-source envelope solutions.
- India's affordable housing pipeline:The Pradhan Mantri Awas Yojana urban mission is channeling volume demand toward block-grade AAC in tier-2 and tier-3 city construction.
- Carbon credit monetization:Verified emission reduction frameworks under ISO 14064 are enabling AAC producers to capture premium pricing from green bond-financed developments in Singapore and Hong Kong.
Industry Challenges
- Autoclave operator certification gaps:High-pressure vessel licensing requirements in India and Southeast Asia outpace vocational training capacity, constraining plant utilization rates.
- Dimensional tolerance enforcement:Factory QA systems must achieve sub-2mm deviation to meet EN 771-4 specifications for German passive-house panel contracts, demanding capital-intensive metrology upgrades.
- Logistics fragmentation:AAC's low bulk density relative to compressive strength creates empty backhaul inefficiencies in truck-based distribution networks serving dispersed Indian construction sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerated Autoclaved Concrete (AAC) Market |
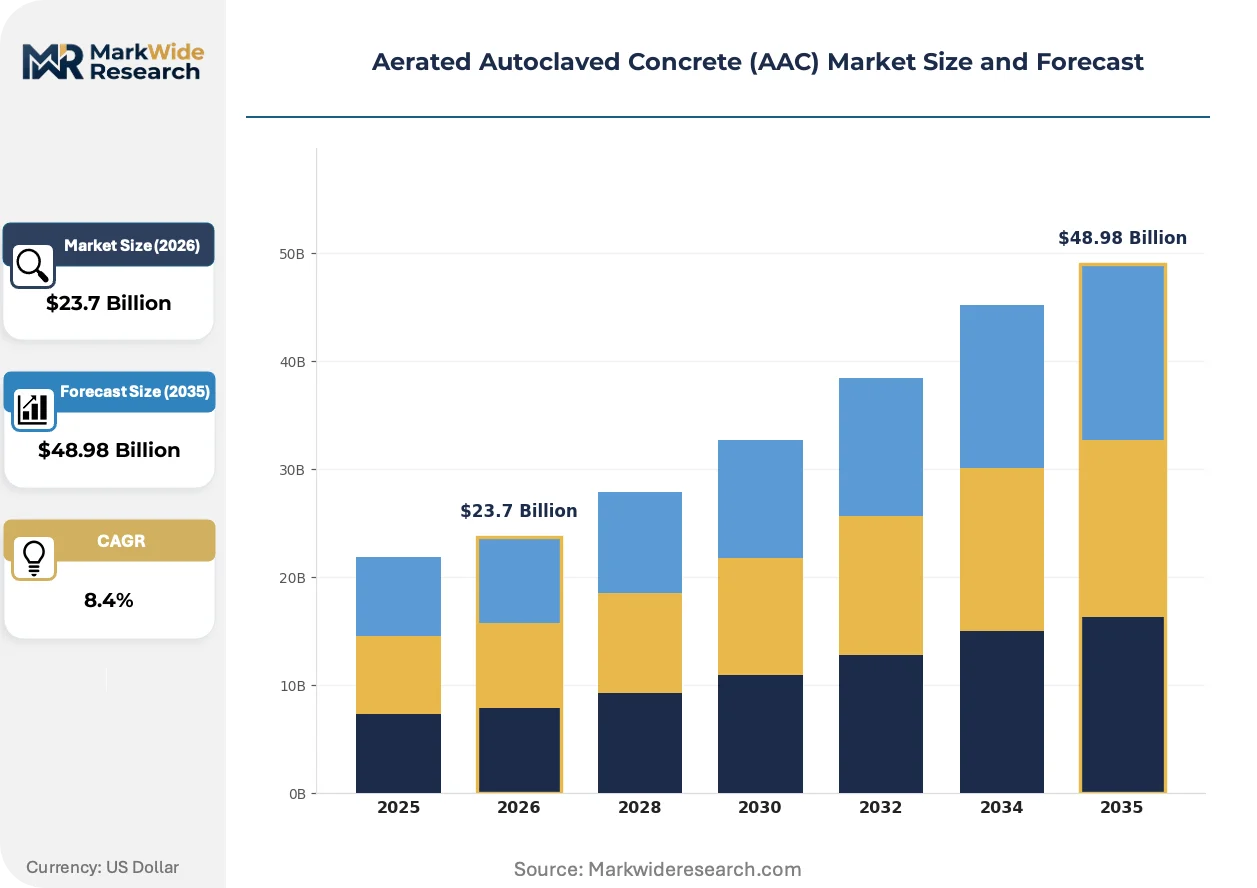
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $48.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Block, Panel, Slab, Pre-cast End Use: Residential, Commercial, Industrial, Infrastructure Application: Wall Construction, Roof Construction, Fire Protection, Sound Insulation Distribution Channel: Direct Sales, Online, Retail, Wholesale |
| Companies Covered | Xella International, H+H International, UltraTech Cement Ltd., ACICO Group, Biltech Building Elements Ltd., Aercon Florida LLC, Buildmate Projects Pvt. Ltd., AKG Gazbeton, Solbet Sp Z.O.O, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerated Autoclaved Concrete (AAC) Market Strategic Shifts
Digital fabrication and chemistry modifications are converging to expand AAC's addressable envelope beyond traditional masonry replacement, opening specification pathways in high-performance commercial construction.
Low-calcium fly ash substitution for quartz sand is displacing conventional raw material ratios in Chinese and Indian AAC production, cutting clinker content by 15-20 percent while maintaining autoclave curing performance. State-owned construction conglomerates in Shandong province are piloting these formulations at scale. The shift is compressing reliance on imported silica sand and aligning output with industrial byproduct circularity targets.
REACH authorization timelines for aluminum powder classification are forcing European AAC producers to reformulate hydrogen-generation chemistry or secure dedicated supply contracts with pre-registered importers. The ECHA substance evaluation process is extending raw material qualification cycles from six to fourteen months. German and Polish manufacturers are responding by backward-integrating into specialty aluminum flake production.
Developer procurement teams are unbundling envelope performance guarantees from traditional masonry subcontractor packages, creating direct specification relationships with AAC panel fabricators. This disintermediation is most visible in French commercial new-builds pursuing RE2020 thermal performance compliance, where facade system warranties now anchor contract structures rather than general contractor risk pools.
Aerated Autoclaved Concrete (AAC) Market Segmentation
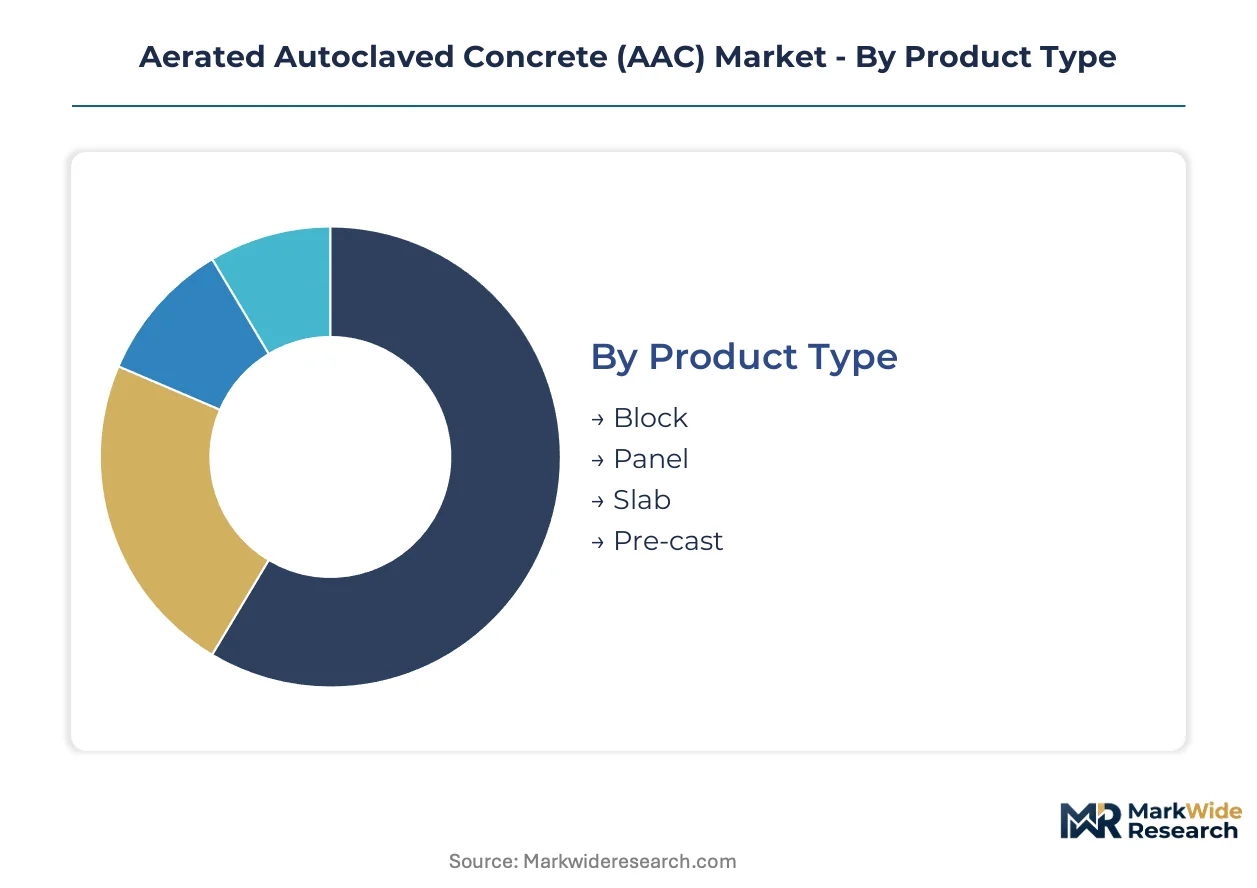
AAC's porous cellular structure creates divergent value propositions across product formats, while end-use applications expose the material to distinct regulatory and performance benchmarks. Understanding segment boundaries clarifies where specification-grade premiums materialize versus commodity volume plays.
Product Type:
Block shipments dominate domestic construction across emerging economies where masonry contractors source locally, while panel systems travel longer distances to serve commercial facade integrators in regulated markets.
- Block:Rectangular masonry units with densities from 400 to 600 kg/m³ serve load-bearing walls in mid-rise residential construction. Demand concentrates in India's tier-2 and tier-3 cities under the Pradhan Mantri Awas Yojana mission, where BIS-certified domestic producers compete on landed cost against imported European alternatives facing duty disadvantages.
- Panel:Factory-cast reinforced elements with sub-2mm dimensional tolerance anchor commercial envelope specifications. German passive-house developers under EU Green Deal embodied carbon rules specify these for facade assemblies, with Nordic retrofits adopting panel-to-facade integration for single-source thermal performance guarantees.
- Slab:Horizontal floor and roof elements span intermediate structural bays in low-rise industrial construction across China's Jiangsu province green building pilots.
- Pre-cast:Custom-molded architectural components serve non-structural cladding applications where geometric complexity exceeds standard panel capabilities.
Block commands the established base. The steepest expansion runs through Panel.
End Use:
Cost tier differentiation separates volume-driven residential procurement from premium commercial specifications where thermal performance warranties anchor contract structures.
- Residential:Single-family and multi-family construction absorbs block-grade AAC for partition and load-bearing walls. India's Rajasthan and Gujarat limestone clusters feed this segment through PLI-accelerated domestic capacity, with thermal efficiency mandates in northern heating zones favoring higher-density formulations.
- Commercial:Office, retail, and hospitality developments specify reinforced panels for facade and fire-rated envelope assemblies. French new-builds pursuing RE2020 compliance unbundle performance guarantees from general contractors, creating direct procurement relationships with AAC fabricators.
- Industrial:Warehouse and manufacturing facilities deploy slab systems for column-free roof spans where dead load reduction offsets steel framing costs.
- Infrastructure:Transportation and utility projects utilize block for non-structural enclosures, with sound insulation specifications driving adoption near rail corridors.
Residential holds the volume anchor. Commercial generates the specification premiums.
Application:
Volume concentration in vertical envelope systems contrasts with specialized horizontal and safety-rated applications commanding technical qualification barriers.
- Wall Construction:Vertical envelope systems in load-bearing and non-load-bearing configurations absorb the majority of AAC consumption. China's GB standards administered by SAMR mandate thermal conductivity thresholds that shape formulation choices across northern and southern climate zones.
- Fire Protection:Thicker reinforced panel grades rated for extended fire resistance serve high-occupancy commercial buildings under EMA construction product oversight through harmonized EN standards. Specification upgrades here command 20-40% price premiums over standard wall grades.
- Roof Construction:Slab and panel systems reduce dead loads in flat roof assemblies, particularly in seismic zones where mass reduction improves structural resilience.
- Sound Insulation:Higher-density formulations with closed-cell optimization address acoustic separation requirements in multi-tenant residential and hospitality construction.
Wall Construction anchors shipment volumes. Fire Protection unlocks margin expansion.
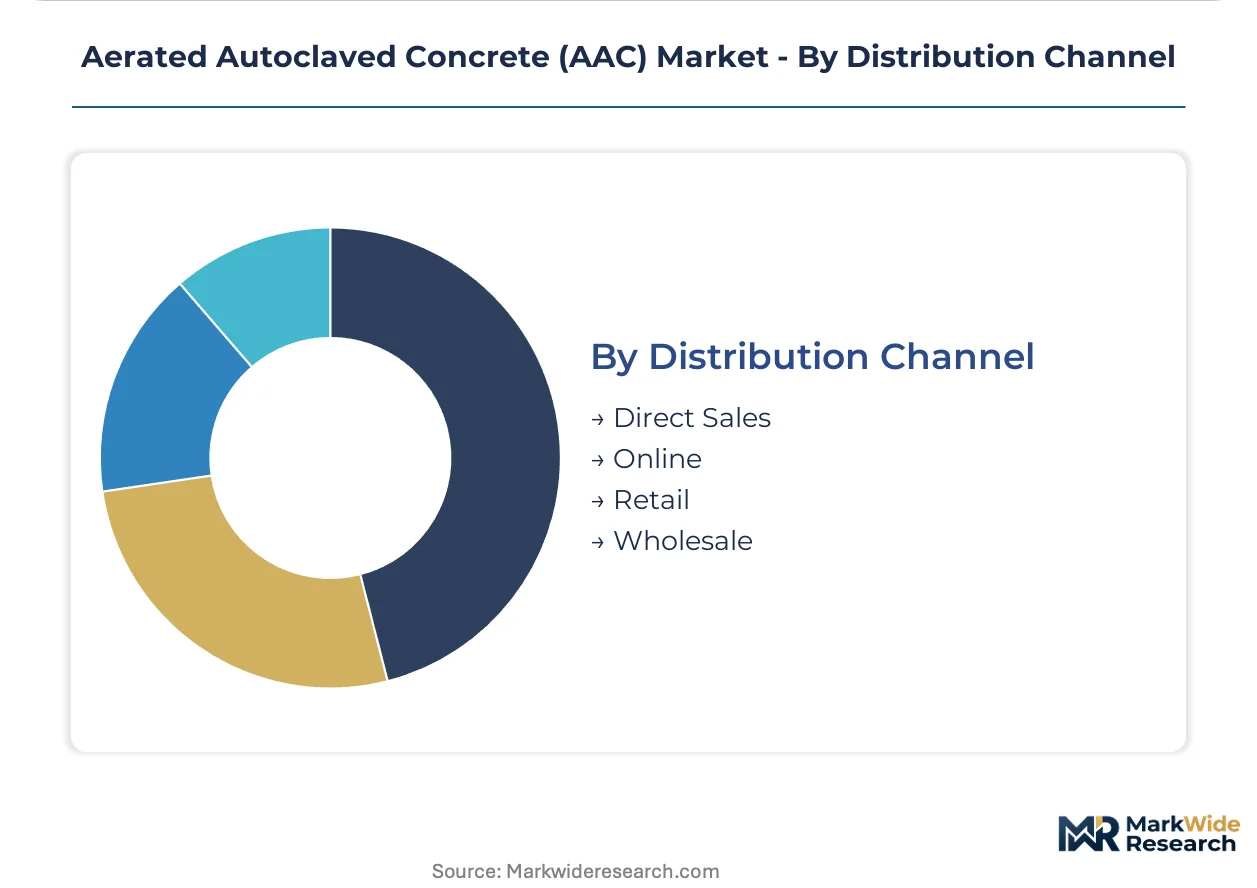
Distribution Channel:
Customer-type fragmentation separates project-direct procurement by developers from fragmented contractor sourcing through intermediaries.
- Direct Sales:Large-scale developers and facade integrators contract mill-direct for panel systems with embedded thermal breaks, particularly in Nordic commercial retrofits seeking single-source envelope solutions. This channel captures specification-grade premiums and long-term warranty relationships.
- Wholesale:Regional distributors aggregate block volumes for masonry contractor networks serving dispersed Indian construction sites, though empty backhaul inefficiencies plague truck-based distribution given AAC's low bulk density relative to compressive strength.
- Retail:Small-project contractors and individual builders source standard block grades through construction material yards with limited technical support.
- Online:Digital procurement platforms emerge for standardized block specifications in markets with transparent BIS or GB certification databases, though panel systems remain relationship-driven.
Wholesale retains the volume base. Direct Sales climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Hamburg-Stockholm rail freight corridor underwrites Nordic AAC distribution efficiency, while the Rhine-Danube waterway network enables German producers to reach Central European construction sites at competitive landed cost.
Germany
Passivhaus-certified residential towers in Berlin and Munich specify reinforced AAC panels for thermal bridge-free envelopes. EMA harmonized EN standards govern performance benchmarks under the EU Construction Products Regulation. The Rhine-Ruhr industrial corridor hosts integrated lime-sand processing clusters supplying specification-grade raw material to autoclave plants.
India
Urban housing missions in tier-2 cities like Jaipur and Lucknow channel block-grade AAC demand for mid-rise masonry construction. BIS certification mandates for autoclaved cellular concrete blocks restrict import eligibility and protect domestic manufacturing. Rajasthan's limestone-rich Jodhpur-Jaisalmer belt anchors PLI-accelerated capacity additions from UltraTech Cement Ltd. and regional competitors.
China
Public housing procurement in Jiangsu and Zhejiang provinces directs volume toward higher-density AAC formulations meeting stringent thermal conductivity thresholds. GB standards administered by SAMR differentiate northern heating zone requirements from southern cooling-dominant specifications. Shandong province state-owned construction conglomerates pilot fly ash-substituted formulations at industrial scale.
France
Commercial new-builds pursuing RE2020 thermal performance compliance unbundle envelope procurement from general contractor risk pools. EU Green Deal embodied carbon disclosure rules compress specification timelines for facade system warranties. The Lyon-Grenoble manufacturing axis supplies precision-cast panels to Paris-region passive-house developments.
Denmark
Nordic commercial retrofits adopt panel-to-facade integration for single-source thermal performance guarantees. EU CSRD corporate sustainability reporting requirements pull AAC into commercial specifications across Copenhagen and Aarhus. H+H International's integrated lime-sand sourcing in northern Jutland anchors regional supply security.
Aerated Autoclaved Concrete (AAC) Market Competitive Environment
Listed leaders compete with private specialists across capital access and specification-grade certification depth. The vendor base fragments between pan-European scale operators, regional cement conglomerates with AAC divisions, and emerging market block specialists serving cost-sensitive masonry contractors. Three archetypes dominate: integrated building materials giants with captive raw material sourcing, standalone AAC pure-plays focused on panel system innovation, and construction-chemical conglomerates backward-integrating into specialty aluminum flake production. Capacity expansion and strategic partnerships represent the dominant competitive moves, as autoclave equipment lead times from German and Italian pressure vessel manufacturers stretch eighteen to twenty-four months.
Among European-based fabricators, Xella International and H+H International exemplify the integrated archetype with pan-European plant networks sustaining specification-grade output. UltraTech Cement Ltd. represents the diversified materials giant model, leveraging cement distribution infrastructure to compete on landed cost in South Asian infrastructure tenders. These three occupy positions across the premium specification and volume commodity tiers respectively.
| Leading Market Players |
|---|
| Xella International |
| H+H International |
| UltraTech Cement Ltd. |
| ACICO Group |
| Biltech Building Elements Ltd. |
| Aercon Florida LLC |
| Buildmate Projects Pvt. Ltd. |
| AKG Gazbeton |
| Solbet Sp Z.O.O |
| Others |
Value Chain & Pricing Dynamics
Fly ash substitution for quartz sand in Chinese and Indian AAC production is simultaneously displacing imported silica sand dependence and compressing raw material cost differentials between coastal and inland manufacturing clusters. This chemistry shift redraws supply geography around industrial byproduct availability while eroding the freight-cost premiums that once protected regional sand quarries.
Pricing Analysis
Volume-discount tiering structures dominate AAC procurement, with three-tier pricing separating specification-grade reinforced panels from standard block and economy-grade masonry units. Price differentiation hinges on EN 771-4 dimensional tolerance certification and factory-integrated thermal break engineering for Nordic facade contracts. Cost compression in block-grade shipments is intensifying because Rajasthan limestone clusters feed PLI-accelerated domestic capacity additions. Masonry contractors serving India's tier-2 cities exhibit acute price sensitivity, while German passive-house developers prioritize thermal performance warranties over unit economics.
Supply Chain Analysis
Eighteen-to-twenty-four month autoclave equipment lead times from German and Italian pressure vessel manufacturers are constraining capacity expansion timelines across emerging market entrants. Geographic supply concentration centers on China, India, and Germany, with Shandong province state-owned conglomerates and Rajasthan limestone belts anchoring raw material processing. Aluminum powder for hydrogen generation draws from Chinese specialty chemical producers, creating single-source vulnerability during energy price spikes. Distribution runs through project-direct contracts for panel systems and wholesale aggregation for dispersed block shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward developer procurement teams unbundling envelope performance guarantees from general contractor risk pools, fragmenting traditional masonry subcontractor intermediation.
For Market Incumbents: Fortify specification-grade certification depth against REACH authorization timelines compressing raw material qualification cycles. Deepen backward integration into specialty aluminum flake production to secure pre-registered supply channels. Anchor plant networks near limestone-rich clusters in Rajasthan and Jodhpur-Jaisalmer belts to defend landed cost position against import competition. For New Entrants and Emerging Players: After-sales technical support gaps in autoclave operator certification present white-space targets across India and Southeast Asia where vocational training capacity lags licensing requirements. Tier-3 Indian cities under Pradhan Mantri Awas Yojana urban missions offer the most penetrable geography for block-grade volume entry. Pursue direct procurement relationships with affordable housing developers bypassing wholesale distribution inefficiencies. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed European panel specialists holding EN-certified plant networks but limited Asian market access. Long-term viability frames around carbon credit monetization pathways under ISO 14064 for green bond-financed developments. Watch for EU CSRD disclosure rule acceleration as inflection signal pulling AAC into commercial facade specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Flake Production | ECHA substance evaluation timelines are forcing captive supply of hydrogen-generating agents. |
| Panel-to-Facade System Integration | Single-source envelope solutions capture RE2020 compliance premiums in French commercial new-builds. |
| Fly Ash Formulation Scale-Up | Shandong province pilots align output with industrial byproduct circularity targets under dual carbon goals. |
| Autoclave Operator Training Certification | BIS-mandated licensing gaps in India constrain plant utilization rates for mid-scale entrants. |
| Carbon Credit Verification Framework | ISO 14064 protocols enable premium pricing from Singapore and Hong Kong green bond developments. |
Study Parameters
Desk research of harmonized EN standards documentation, BIS certification registries, and SAMR GB standard filings preceded structured interviews with autoclave plant managers, facade integrator procurement leads, and construction chemical R&D directors. Primary fieldwork with masonry contractor networks and affordable housing mission officials validated secondary trade flow data from customs records and limestone cluster production disclosures. Bottom-up capacity assessments and top-down demand modeling were triangulated against EU Green Deal regulatory impact timelines.
Variance decomposition across product type, end-use vertical, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories calibrated to provincial green building code adoption curves and PLI scheme disbursement schedules. Modeled inputs incorporated aluminum powder price volatility indices and autoclave equipment order backlogs from German pressure vessel manufacturers.
Underlying assumptions cover sustained EU CSRD disclosure compliance and China's dual carbon goal enforcement, with deviation risk concentrated in REACH authorization delays and aluminum powder supply concentration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Oriented Strand Board (OSB) Market
Building & Construction Materials
Metal Roofing Market
Building & Construction Materials
Opening Trim Weatherstrips Market
Building & Construction Materials
Industrial Flooring Market
Building & Construction Materials
North America Steel Roofing Market
Building & Construction Materials
Particleboard Market
Building & Construction Materials
Warm Mix Asphalt Market
Building & Construction Materials
Steel Roofing Market
Building & Construction Materials
North America Ceiling Tiles Market
Building & Construction Materials
Glazed Tiles Market
Building & Construction Materials
Italy Oriented Strand Board Market
Building & Construction Materials
Saudi Arabia Tiles Market
Building & Construction Materials
Seal Coat Market
Building & Construction Materials
Asia-Pacific Cross-Laminated Timber Market
Building & Construction Materials
US Commercial Windows Market
Building & Construction Materials
Point Supported Glass Curtain Wall Market