
 Big Data in Construction Market | 2026-2036
Big Data in Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Big Data in Construction Market Analysis
Multi-source procurement of geospatial and sensor analytics is consolidating around platform providers with construction-native data architectures. Autodesk Inc. leverages its BIM 360 ecosystem to anchor design-to-operations workflows across heavy civil projects. Oracle Corporation competes through Primavera Cloud integrations that sustain enterprise-grade portfolio visibility for infrastructure owners. Microsoft Corporation extends Azure Digital Twins capabilities to occupy the middleware layer between field IoT and back-office ERP systems.
Big Data in Construction encompasses the capture, aggregation, and algorithmic processing of structured and unstructured information generated across project lifecycles, typically involving terabyte-scale datasets from IoT sensors, drone imagery, and ERP transaction logs to enable predictive scheduling and resource optimization. Machine Learning applications currently dominate commercial deployments by converting historical schedule variance into forward risk signals, while Cloud Computing infrastructure supports the elastic storage requirements of real-time jobsite telemetry. Data Analytics services targeting Cost Estimation extract margin pools by automating quantity takeoffs against fluctuating commodity indices, reducing bid preparation cycles for general contractors.
OSHA safety data reporting requirements and the EPA's construction stormwater enforcement framework shape demand for environmental and incident tracking platforms in the US market, while ISO 19650 BIM standards govern information management protocols across Commonwealth procurement jurisdictions. Stakeholders must monitor how emerging EU AI Act risk classifications apply to automated construction scheduling algorithms, as compliance scope will determine platform architecture investments and vendor qualification criteria for publicly funded builds.
Market Dynamics
BIM-to-field data pipelines are compressing project feedback loops, forcing contractors to restructure procurement around real-time analytics rather than retrospective reporting. This structural shift rewards firms that embed sensors during preconstruction phases.
Growth Catalysts
- ISO 19650 Mandates:Commonwealth procurement frameworks now require structured data handovers, compelling general contractors to deploy common data environments across project portfolios.
- Digital Twin Integration:Infrastructure owners in Germany and Singapore are specifying physics-based simulations for operational handover, creating pull-through demand for sensor-anchored construction datasets.
- Federal Infrastructure Spending:US metropolitan corridor developments tie funding eligibility to telemetry-enabled progress tracking, accelerating IoT deployment on heavy civil sites.
Market Restraints
- Sensor Hardware Concentration:MEMS accelerometer and LIDAR module supply concentrates among East Asian contract manufacturers, exposing projects to semiconductor allocation volatility.
- Cloud Storage Cost Structure:Petabyte-scale retention of drone imagery and vibration time-series data generates recurring opex burdens that erode margin on fixed-price contracts.
- Interoperability Friction:Proprietary data schemas from competing BIM platforms prevent seamless aggregation across subcontractor tiers, fragmenting analytics value.
Strategic Opportunities
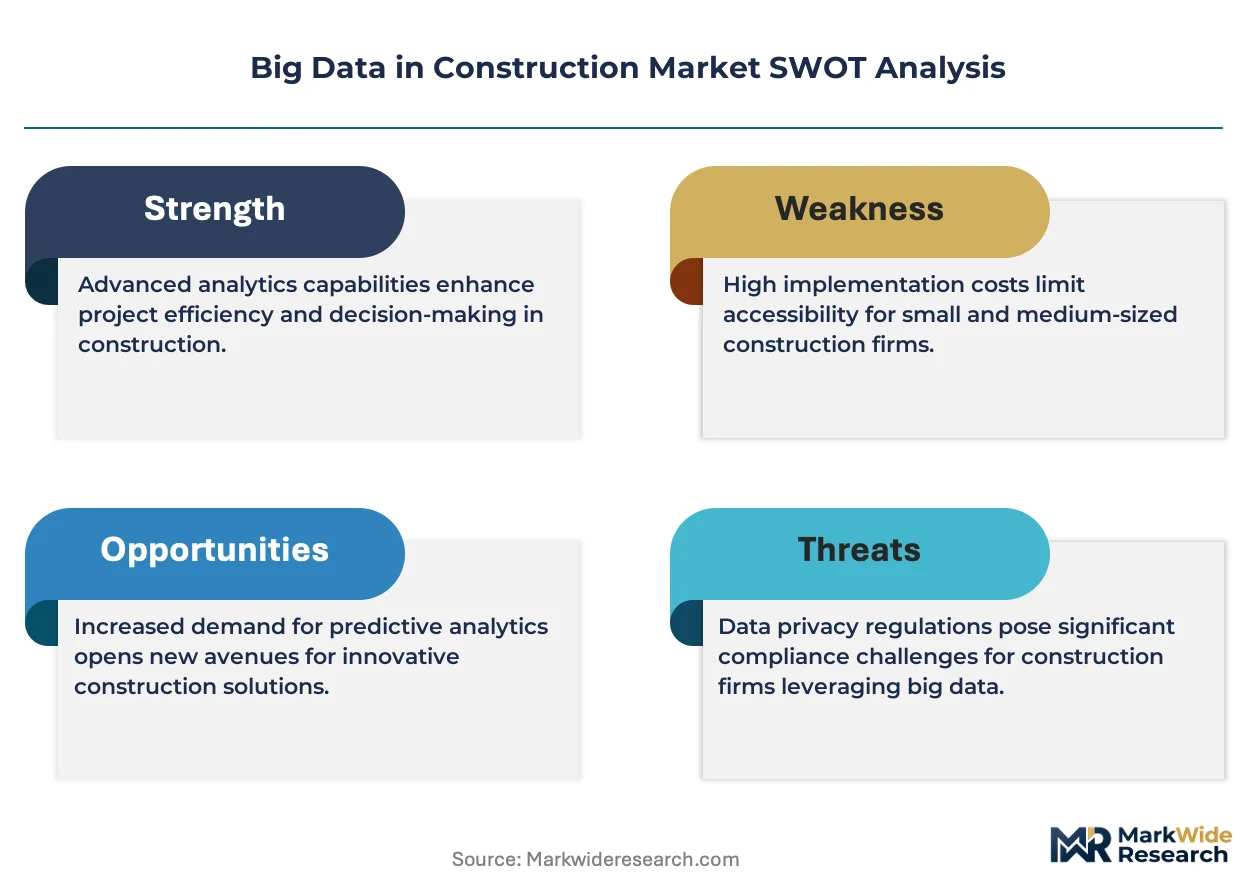
- EU AI Act Compliance Services:Automated scheduling algorithms face emerging risk classification requirements, creating advisory and platform re-architecture revenue streams for construction technology vendors.
- Retrofit Analytics:Existing building stock in Japan and South Korea lacks embedded sensors, opening aftermarket deployment of wireless structural health monitoring systems.
- Edge-Cloud Convergence:On-site GPU clusters processing video analytics locally before cloud upload reduce latency for safety-critical applications while trimming bandwidth costs.
Industry Challenges
- Data Engineering Talent Scarcity:Construction firms compete with technology sectors for pipeline architects capable of normalizing unstructured field data into analytics-ready schemas.
- Legacy ERP Integration:Decades-old financial systems in established contractors resist API connectivity, forcing expensive middleware development for bidirectional data flows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Big Data in Construction Market |
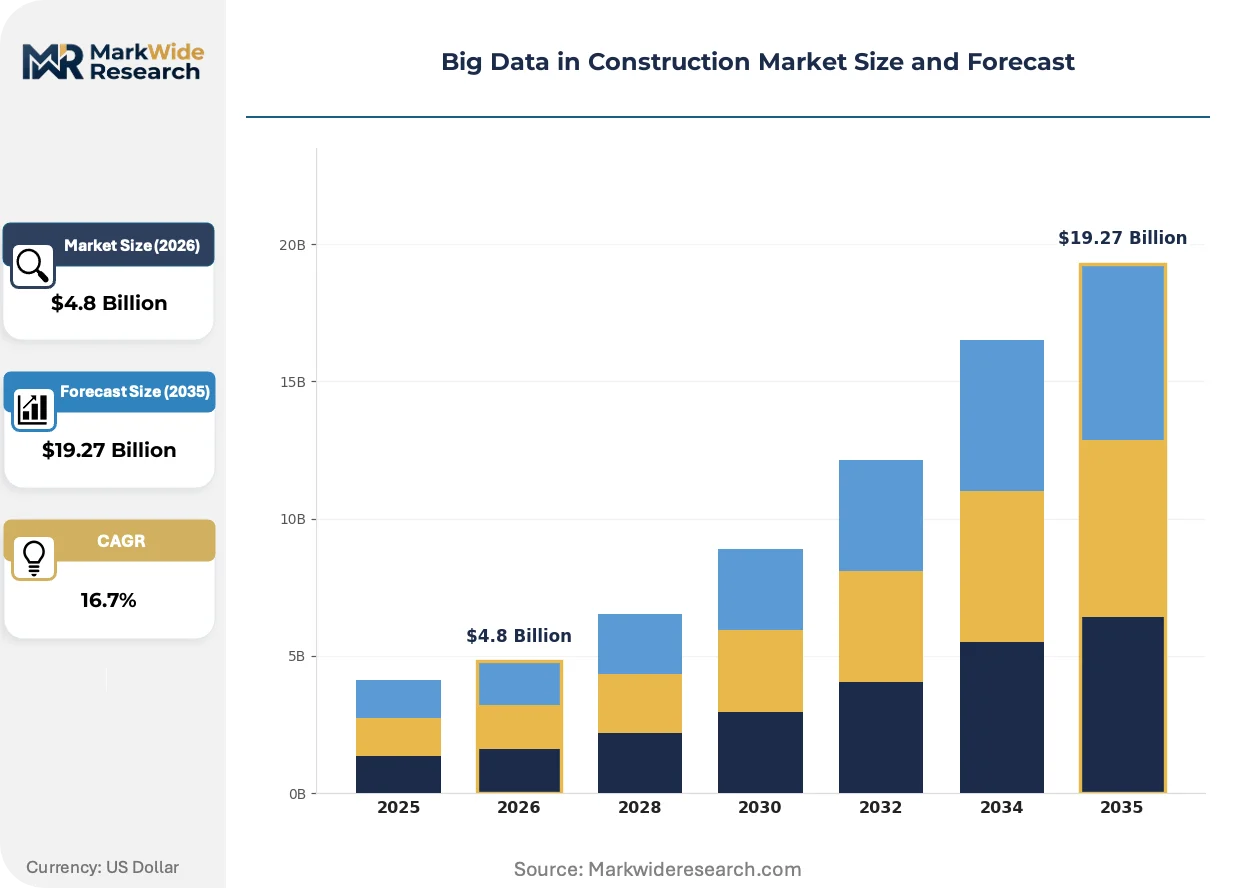
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Data Analytics, Cloud Computing, IoT Application: Project Management, Risk Assessment, Cost Estimation, Quality Control End User: Contractors, Project Managers, Architects, Engineers Data Type: Structured Data, Unstructured Data, Real-time Data, Historical Data |
| Companies Covered | Accenture plc, Oracle Corporation, Google LLC, Autodesk Inc., SAP SE, Microsoft Corporation, International Business Machines Corporation, Bentley Systems Incorporated, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Big Data in Construction Market Emerging Trajectories
Generative design algorithms and federated learning architectures are redistributing analytical workloads across distributed jobsites. These capabilities are compressing the gap between field data capture and executive decision-making.
Computer vision systems trained on OSHA incident databases are automating hazard recognition in crane operation zones and excavation perimeters. Heavy civil contractors in Texas and California are deploying these tools on federally funded transportation projects. The technology is automating safety officer coverage gaps during night shifts and remote site phases.
The EU AI Act's risk-based classification framework is imposing documentation and human oversight requirements on construction scheduling algorithms that automate resource allocation. Infrastructure owners in France and the Netherlands are now requiring algorithmic impact assessments as contract preconditions. Design-build firms serving public clients are restructuring data science teams to satisfy audit trail mandates.
Subscription-based analytics procurement is displacing perpetual license models among mid-tier general contractors. Firms prefer operational expenditure treatment for predictive scheduling and cost estimation tools rather than capitalizing software investments. This shift is most pronounced among contractors bidding on UK and Australian public infrastructure frameworks with tight working capital constraints.
Big Data in Construction Market Segmentation
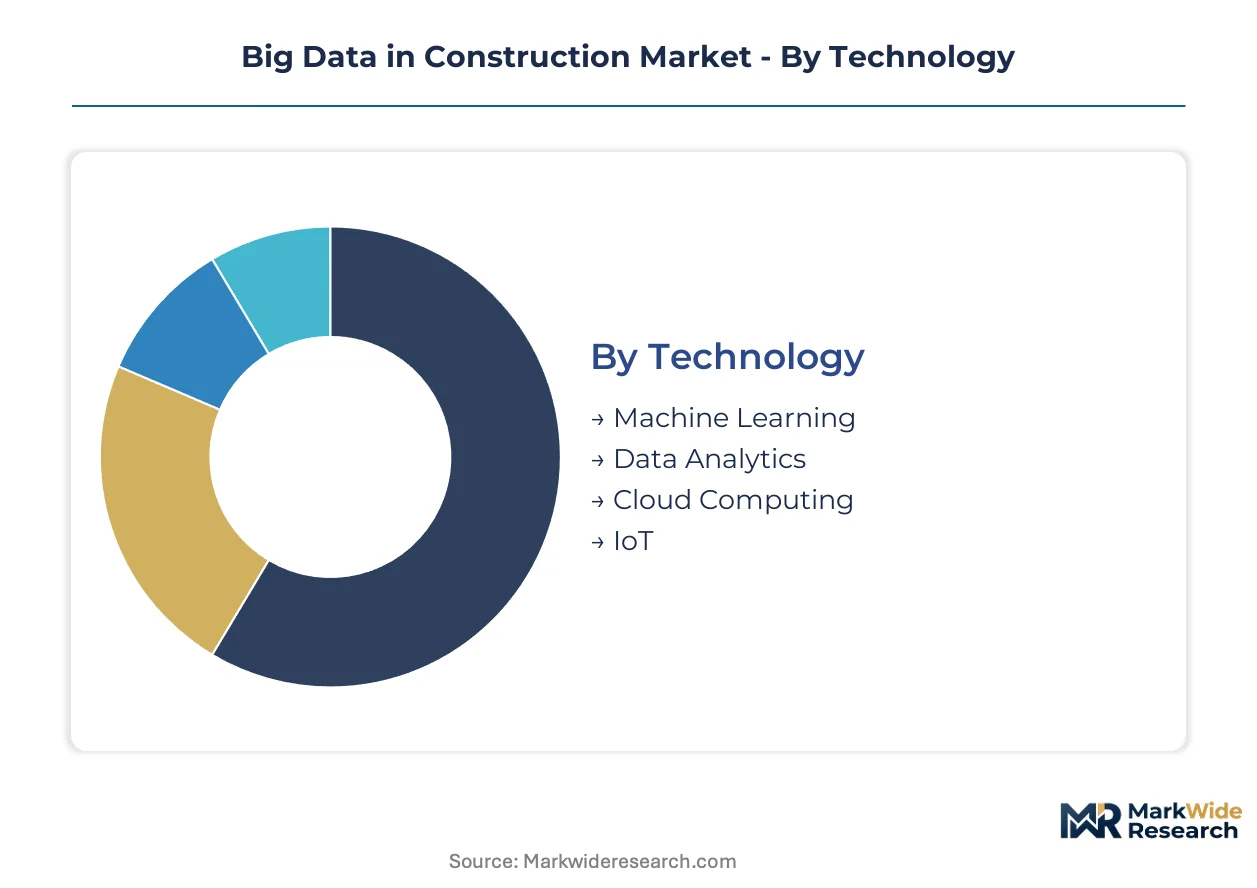
Big data architectures in construction fragment across distinct technical layers and stakeholder workflows, with integration depth determining whether solutions operate as standalone platforms or embed within existing enterprise systems. Procurement patterns diverge sharply between heavy civil contractors seeking field-native telemetry and design firms prioritizing cloud-based collaboration environments.
Technology:
Integration depth varies from embedded edge processing to standalone cloud platforms, with standalone deployments dominating early-phase pilots while embedded systems capture operational scale.
- Machine Learning:Predictive algorithms convert historical schedule variance into forward risk signals for project controls teams. Demand concentrates among North American heavy civil contractors bidding on federally funded transportation corridors where schedule certainty determines bond eligibility.
- Data Analytics:Descriptive and diagnostic dashboards aggregate ERP transaction logs with drone imagery for quantity takeoff automation. Mid-tier general contractors in UK and Australian procurement frameworks favor these tools to compress bid preparation cycles against fluctuating commodity indices.
- Cloud Computing:Elastic storage infrastructure supports petabyte-scale retention of vibration time-series and video telemetry.
- IoT:Sensor networks capture real-time structural health and environmental conditions from embedded MEMS devices.
Volume placements concentrate in Data Analytics; the faster expansion belongs to Machine Learning.
Application:
Cost tier stratification separates enterprise-grade portfolio platforms from point solutions targeting specific workflow bottlenecks, with premium pricing attaching to systems spanning multiple project phases.
- Project Management:Integrated scheduling and resource allocation platforms synchronize BIM models with field progress tracking. Infrastructure owners in Germany and Singapore specify these capabilities for digital twin handover requirements, creating pull-through demand for sensor-anchored datasets.
- Cost Estimation:Automated quantity takeoff tools extract margin pools by normalizing subcontractor bids against commodity price feeds. US metropolitan corridor developments tie federal funding eligibility to telemetry-enabled progress validation, accelerating adoption among unionized general contractors.
- Risk Assessment:Probabilistic models quantify schedule and cost contingency reserves from historical variance patterns.
- Quality Control:Computer vision systems flag dimensional deviations and material defects from drone and fixed-camera feeds.
Commercial density clusters around Cost Estimation; Project Management is gaining share fastest as BIM mandates deepen.
End User:
Customer type segmentation reflects divergent data literacy levels and procurement authority, with contractors controlling capital budgets and architects influencing specification standards.
- Contractors:Field-facing organizations deploy IoT and machine learning for safety monitoring and equipment optimization. Texas and California heavy civil operators automate hazard recognition in crane zones and excavation perimeters to close coverage gaps during night shifts.
- Project Managers:Portfolio-level visibility tools aggregate cross-project analytics for enterprise resource planning.
- Architects:Design-phase generative algorithms explore structural and energy performance permutations from parametric constraints.
- Engineers:Structural and MEP specialists use physics-based simulations validated against as-built sensor data.
Procurement volume tilts toward Contractors; Architects show the steepest adoption trajectory as ISO 19650 mandates reshape deliverable standards.
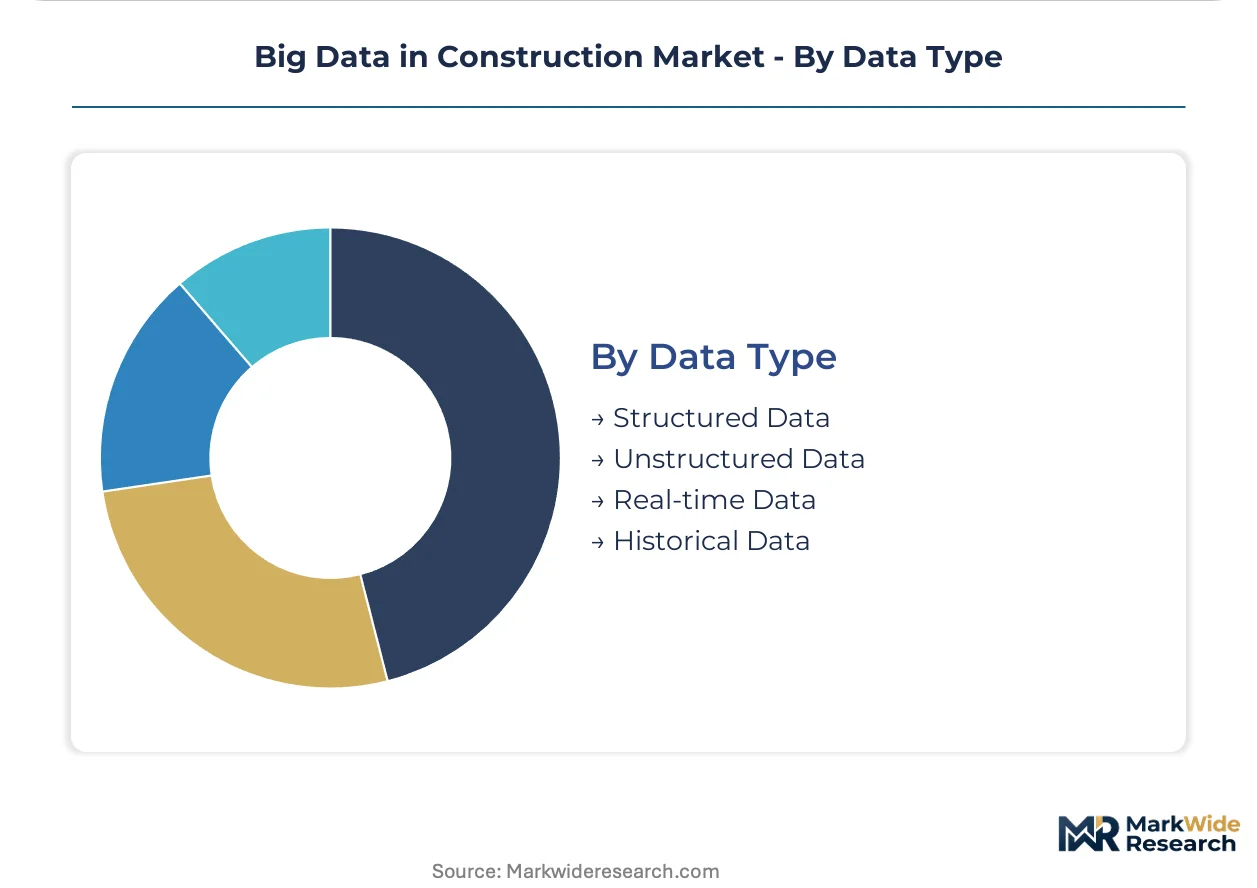
Data Type:
Maturity gradients separate established structured data pipelines from emerging unstructured processing capabilities, with real-time streams commanding premium infrastructure investment.
- Structured Data:Relational databases house ERP transactions, contract metadata, and standardized BIM element properties. Commonwealth procurement frameworks now mandate structured data handovers, compelling general contractors to deploy common data environments across portfolios.
- Real-time Data:Streaming telemetry from accelerometers, temperature sensors, and GPS trackers enables immediate anomaly detection. Edge-cloud convergence architectures process video analytics locally before cloud upload, trimming bandwidth costs for safety-critical applications.
- Unstructured Data:Drone imagery, voice memos, and handwritten field notes require normalization pipelines.
- Historical Data:Archival project records train machine learning models and benchmark performance baselines.
Deployment scale favors Structured Data; Real-time Data is climbing fastest as sensor hardware costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's cloud infrastructure anchors North American platform development, while East Asian sensor manufacturing clusters supply hardware for telemetry networks. Federal infrastructure spending and BIM mandates in Commonwealth jurisdictions drive deployment velocity across OECD markets.
United States
OSHA safety data reporting requirements and the EPA's construction stormwater enforcement framework accelerate environmental and incident tracking platform procurement. Federal infrastructure spending ties funding eligibility to telemetry-enabled progress validation on metropolitan corridor developments. Heavy civil contractors in Texas and California deploy computer vision systems for automated hazard recognition in crane zones.
Germany
Infrastructure owners specify physics-based simulations for operational handover, creating pull-through demand for sensor-anchored construction datasets. The EU AI Act's risk-based classification framework imposes documentation requirements on automated scheduling algorithms. Digital twin mandates in Bavaria and North Rhine-Westphalia accelerate BIM-to-field data pipeline consolidation.
Singapore
Smart nation infrastructure programs mandate digital twin integration for public works, compressing project feedback loops through real-time analytics. The Building and Construction Authority enforces strict data handover protocols for government projects. Marina Bay and Jurong Lake District developments anchor regional demand for IoT-embedded construction monitoring.
United Kingdom
ISO 19650 mandates require structured data handovers across Commonwealth procurement frameworks, compelling common data environment deployment. Subscription-based analytics procurement displaces perpetual license models among mid-tier general contractors bidding on tight working capital constraints. London's Crossrail 2 and HS2 extensions concentrate platform adoption in the Southeast.
Australia
Public infrastructure frameworks with working capital constraints favor operational expenditure treatment for predictive scheduling tools. State-level BIM mandates in New South Wales and Victoria align with ISO 19650 protocols for structured information management. Sydney Metro and Melbourne Airport Link projects drive federated learning architecture trials.
Big Data in Construction Market Vendor Landscape
Strategic partnerships dominate the current landscape as platform providers anchor design-to-operations workflows. The vendor base concentrates around three tiers: enterprise software conglomerates with construction-native modules, specialized BIM platform providers, and cloud infrastructure operators occupying middleware layers. Autodesk Inc. and Oracle Corporation exemplify the integrated-platform archetype, while Microsoft Corporation and Google LLC represent the cloud-middleware vector. Competitive intensity centers on API ecosystem breadth and federated data architecture capabilities.
Within the enterprise-software tier, Oracle Corporation and SAP SE occupy positions anchored by project portfolio management heritage. Autodesk Inc. exemplifies the design-native platform archetype, leveraging BIM 360 ecosystem penetration across heavy civil workflows. Microsoft Corporation sits within the cloud infrastructure layer, extending Azure Digital Twins capabilities to bridge field IoT and back-office ERP systems. These three companies collectively represent the dominant competitive positioning across data pipeline, analytics engine, and middleware segments.
| Leading Market Players |
|---|
| Accenture plc |
| Oracle Corporation |
| Google LLC |
| Autodesk Inc. |
| SAP SE |
| Microsoft Corporation |
| International Business Machines Corporation |
| Bentley Systems Incorporated |
| Siemens AG |
| Others |
Supply Flow & Price Mechanics
Edge-cloud convergence in video analytics and structural health monitoring is compressing infrastructure costs while redistributing value capture toward GPU hardware suppliers and edge-computing integrators. This technical transition simultaneously erodes margins on pure cloud-storage plays and concentrates pricing power among firms controlling on-site processing capabilities.
Pricing Analysis
Service bundling separates sensor hardware warranty periods from analytics platform subscriptions, with premium tiers incorporating predictive maintenance algorithms and regulatory compliance documentation. Three-tier pricing structure across premium, standard, and economy levels reflects data retention duration, API call volume limits, and human analyst support hours. Cost compression in the economy tier is intensifying because mid-tier general contractors favor operational expenditure treatment over capitalized software investments. Unionized heavy civil contractors bidding on federally funded corridors show the least price sensitivity due to bond eligibility requirements for telemetry validation.
Supply Chain Analysis
MEMS accelerometer and LIDAR module supply rests on Taiwanese semiconductor foundries, South Korean sensor packaging houses, and Japanese precision optics manufacturers. Raw material dependencies span silicon wafers, rare-earth dopants for laser diodes, and specialized polymers for ruggedized sensor housings. Single-source vulnerability concentrates in advanced LIDAR chipsets where patent thickets limit qualified suppliers. Distribution runs through construction technology distributors serving metropolitan corridor developments and direct enterprise sales for infrastructure owner-operator accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machine learning inference at the network edge is displacing centralized cloud analytics in safety-critical construction applications, creating a technology-transition window where legacy platform architectures face obsolescence pressure.
For Market Incumbents: Lock in sensor-anchored data pipeline control by acquiring edge-computing hardware specialists and embedding predictive algorithms directly into BIM-to-field workflows. The threat of federated learning architectures redistributing analytical workloads across distributed jobsites demands vertical integration into on-site GPU cluster deployment. Certification investment in EU AI Act compliance documentation creates switching costs for infrastructure owners in France and the Netherlands.
For New Entrants and Emerging Players: Mid-tier general contractors in UK and Australian procurement frameworks with tight working capital constraints represent the most penetrable buyer archetype. White-space targets include subscription-based retrofit analytics for Japan's existing building stock and wireless structural health monitoring systems for South Korean infrastructure. Go-to-market leverage concentrates on outcome-based pricing tied to schedule variance reduction rather than software seat licenses.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by enterprise software conglomerates seeking construction-native data architectures. Long-term viability favors platform providers with API ecosystem breadth spanning BIM, ERP, and IoT middleware layers. The inflection signal to watch is federal infrastructure spending authorization velocity in US metropolitan corridors, which determines telemetry deployment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Infrastructure Deployment | On-site GPU clusters reduce latency for OSHA-mandated safety monitoring in Texas and California. |
| EU AI Act Compliance Certification | Algorithmic impact assessments satisfy French and Dutch infrastructure owner contract preconditions. |
| Sensor Hardware Backward Integration | Captive MEMS supply mitigates East Asian semiconductor allocation volatility for heavy civil contractors. |
| Federated Learning Architecture Development | Distributed model training across jobsites preserves data sovereignty under Singapore's smart nation protocols. |
| Common Data Environment Platform Integration | ISO 19650-mandated structured handovers lock in recurring subscription revenue from UK general contractors. |
Methodological Framework
SEC 10-K filings, hyperscaler capex disclosures, and construction industry trade publications formed the secondary backbone of data collection. Primary interviews with heavy civil project controls directors, BIM platform engineers, infrastructure owner procurement leads, and construction technology integration specialists validated quantitative assumptions. Bottom-up and top-down triangulation cross-referenced sensor hardware shipment data against platform subscription growth metrics.
Bottom-up modeling segmented addressable market by technology layer, application workflow, and end-user procurement authority across the analysis window. Machine learning, data analytics, cloud computing, and IoT deployment patterns were projected against BIM mandate adoption curves and federal infrastructure spending authorization trajectories. CAGRs derived from historical platform penetration rates in early-adopter jurisdictions and sensor hardware cost decline curves.
Revisions become necessary when EU AI Act enforcement timelines accelerate, MEMS supply chain disruptions persist beyond semiconductor allocation cycles, or federal infrastructure spending authorization stalls. Forecasts reflect assumptions about ISO 19650 mandate expansion pace and digital twin specification adoption by German and Singaporean infrastructure owners. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Infrastructure
IoT in Commercial Construction Market
Smart Infrastructure
Smart Concrete Market
Smart Infrastructure
Digital Twin-Enabled Structural Health Monitoring Test Platforms Market
Smart Infrastructure
Construction 4.0 Market
Smart Infrastructure
Global IoT in Construction Market
Smart Infrastructure
Smart Infrastructure Market
Smart Infrastructure
Smart Hydrants Market
Smart Infrastructure
Asia-Pacific Smart Building Market
Smart Infrastructure
Bridge and Tunnel Condition Assessment Sensor Networks and Test Platforms Market
Smart Infrastructure
Smart Airport Construction Market
Smart Infrastructure
Infrastructure Solution Integration Service Market
Smart Infrastructure
Smart Pipeline Networks Market
Smart Infrastructure
US Smart Building Market