
 US Ceiling Tiles Market | 2026-2036
US Ceiling Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
US Ceiling Tiles Market Insights
The gap between premium acoustic performance and commodity price points is shifting procurement patterns across the US Ceiling Tiles Market. Armstrong World Industries Inc. leverages its vertically integrated mineral fiber supply chain to sustain margin leadership in healthcare and education specifications. USG Corporation competes on gypsum-based product breadth, while Rockfon anchors the high-performance fiberglass segment with stone wool technology optimized for open-plan commercial environments.
Ceiling tiles are rigid surfacing panels engineered for overhead interior applications, typically manufactured from mineral fiber, fiberglass, gypsum, or metal substrates with NRC (Noise Reduction Coefficient) ratings between 0.50 and 0.95 for acoustic control. Their primary purpose spans sound absorption, fire resistance, and aesthetic integration within commercial and institutional building envelopes. Mineral Fiber Tiles occupy the mature volume core of the market, while Fiberglass variants capture premium specification growth driven by open-ceiling design trends. Healthcare Facilities represent the fastest-growing end-user channel, as infection-control protocols and cleanability standards reshape material selection criteria away from porous legacy products.
EPA regulations under TSCA Title VI constrain formaldehyde content in composite wood substrates, directly limiting material choices for wood-based ceiling products and elevating mineral fiber alternatives. OSHA workplace noise standards and ICC fire-safety codes further dictate acoustic performance and flame-spread ratings that manufacturers must certify through third-party testing. Stakeholders must monitor evolving state-level building electrification mandates and embodied-carbon disclosure rules, as California's CALGreen framework and similar state codes begin incorporating ceiling assemblies into whole-building carbon accounting.
Market Dynamics
EPA's formaldehyde emission standards under TSCA Title VI are compressing material options for wood-based ceiling substrates, accelerating mineral fiber substitution across commercial construction specifications.
Growth Catalysts
- Healthcare Infection Control Protocols:Joint Commission standards for cleanability are driving specification of non-porous, disinfectant-resistant ceiling systems in acute care facilities.
- Sun Belt Construction Concentration:Commercial building permits in Texas and Florida are outpacing national renovation cycles, concentrating demand for rapid-install ceiling assemblies.
- OSHA Workplace Noise Standards:Stricter enforcement of permissible exposure limits is mandating NRC-rated acoustic treatments in open-plan offices and manufacturing environments.
Market Restraints
- Mineral Wool Input Volatility:Energy-intensive production of slag wool and rock wool faces natural gas price swings that compress manufacturer margins.
- Midwest Supply Concentration:Bulk mineral fiber production clusters in Indiana and Ohio, creating freight cost penalties for Sun Belt project deliveries.
- Legacy Suspension Grid Interoperability:Existing T-bar infrastructure limits adoption of dimensionally incompatible panel formats without full system replacement.
Strategic Opportunities
- California CALGreen Carbon Accounting:Embodied-carbon disclosure mandates for ceiling assemblies create first-mover advantage for manufacturers with EPD-certified low-carbon formulations.
- Biophilic Design Integration:Living ceiling systems combining acoustic panels with integrated irrigation are penetrating wellness-focused corporate headquarters.
- Direct-to-Contractor Digital Platforms:E-procurement channels are disintermediating traditional distribution for standardized commercial specifications.
Industry Challenges
- Acoustic Engineer Talent Scarcity:Specialized expertise in room acoustics modeling is concentrated among aging consultants, constraining specification support for complex healthcare and performing arts projects.
- Third-Party Fire Certification Timelines:UL and ICC-ES testing backlogs for new product formulations extend commercialization cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Ceiling Tiles Market |
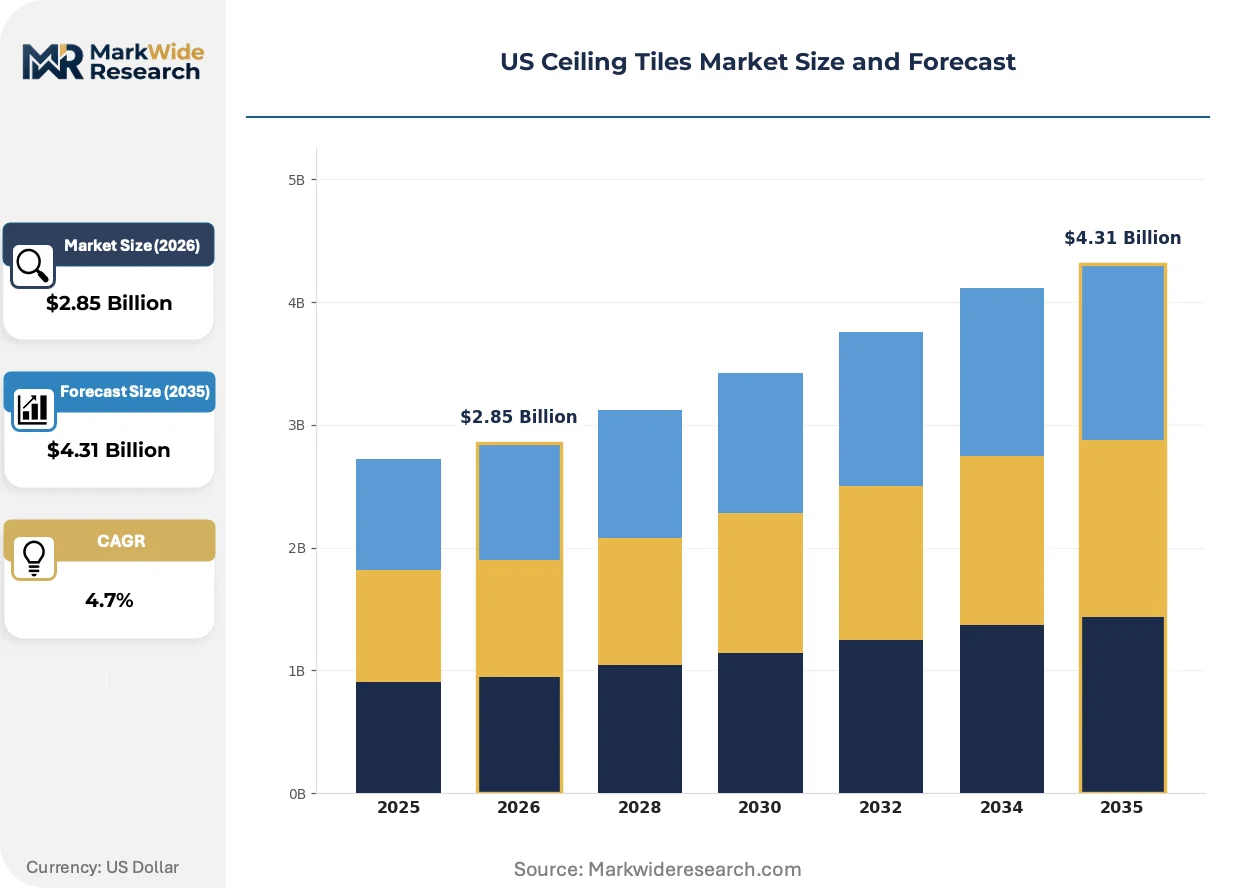
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.31 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acoustic Tiles, Decorative Tiles, PVC Tiles, Mineral Fiber Tiles Installation Type: Suspended, Direct Attach, Grid System, Tongue and Groove End User: Commercial Buildings, Residential Spaces, Educational Institutions, Healthcare Facilities Material: Gypsum, Wood, Metal, Fiberglass |
| Companies Covered | Rockfon, Hunter Douglas, Armstrong World Industries Inc., SAS International, Gordon Incorporated, USG Corporation, OWA Ceiling Systems Inc., Ceilume, CertainTeed, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Ceiling Tiles Market Trends and Innovations
Digital manufacturing and embedded sensor integration are redefining ceiling assemblies from passive surfacing to active building infrastructure, compressing traditional specification boundaries between aesthetics, acoustics, and environmental monitoring.
Smart ceiling panels with integrated air quality sensors and occupancy detection are automating HVAC responsiveness in commercial buildings. Facility managers in Class A office towers are specifying these systems at accelerating rates. The technology is automating energy optimization by eliminating the lag between environmental drift and mechanical system adjustment.
EPA enforcement of TSCA Title VI formaldehyde limits is constraining composite wood substrate options for ceiling products. Manufacturers are reformulating toward mineral fiber and gypsum alternatives to maintain market access. Healthcare and education specifications are responding fastest, with procurement teams now requiring third-party emission certifications as standard bid prerequisites.
Design-build firms are consolidating specification authority previously dispersed among architects and acoustical consultants. Ceiling system selection is compressing into earlier project phases, with performance guarantees bundled into turnkey contracts. Texas and Florida commercial projects are exhibiting this shift most prominently, where speed-to-occupancy pressures override traditional design-bid-build sequencing.
US Ceiling Tiles Market Segmentation
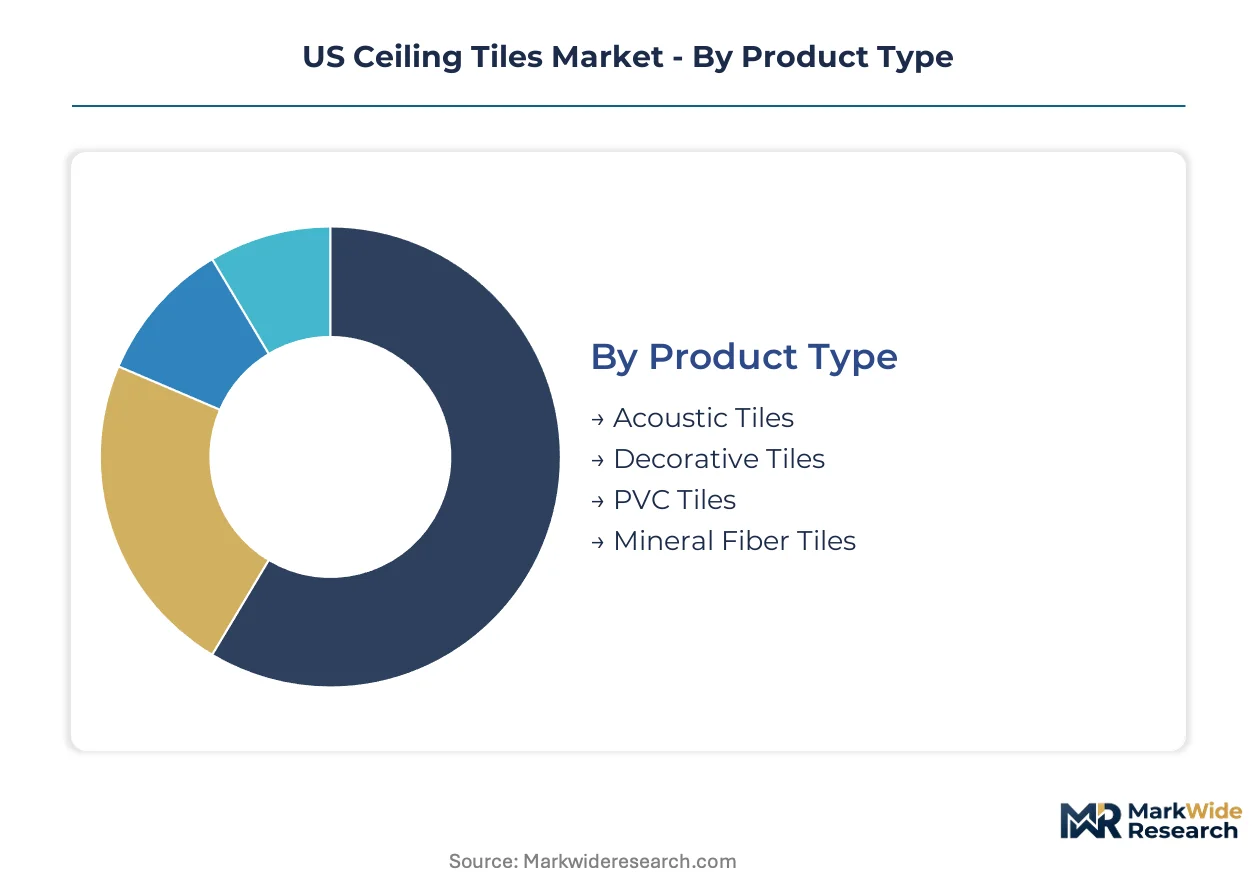
Ceiling tile procurement splits across four distinct dimensions, each reflecting how building owners balance acoustic performance, fire safety, and installation speed. Material chemistry and mounting method together determine lifecycle cost and code compliance pathways.
Product Type:
Cost tier separates commodity bulk buyers from premium specification seekers in this category.
- Mineral Fiber Tiles:Compressed mineral wool and recycled content form the volume core, delivering NRC ratings of 0.70-0.95 at moderate price points. Demand concentrates in Texas and Florida commercial construction, where rapid-install specifications favor familiar 2x2 and 2x4 formats with established supply chains.
- Acoustic Tiles:Engineered porosity and surface perforation optimize sound absorption coefficients for open-plan offices and call centers. Healthcare Facilities in the Sun Belt are expanding specification of cleanable acoustic surfaces that meet Joint Commission disinfection protocols.
- Decorative Tiles:Surface embossing, metallic finishes, and custom printing serve corporate headquarters and hospitality lobbies where visual impact overrides pure functional performance.
- PVC Tiles:Thermoplastic formulations offer moisture resistance and washability for food service, laboratories, and pool enclosures where humidity and chemical exposure degrade fiber-based alternatives.
Mineral Fiber Tiles lead volumes today; Acoustic Tiles are gaining share fastest.
Installation Type:
Application environment dictates mounting complexity and labor cost structure.
- Suspended:T-bar grid systems hung from structural decks dominate commercial retrofit and new construction, enabling rapid panel replacement and mechanical access. Sun Belt states favor this method for speed-to-occupancy pressures in speculative office builds.
- Direct Attach:Adhesive or screw-mounted panels attach directly to substrate, eliminating grid cost and headroom loss. Educational Institutions specify this for gymnasiums and corridors where ceiling height is constrained and acoustic treatment is secondary.
- Grid System:Engineered aluminum or steel suspension components integrate with specific panel dimensions, creating interdependent specification ecosystems that lock in manufacturer relationships.
- Tongue and Groove:Interlocking edges create continuous visual planes with concealed fasteners, penetrating wellness-focused corporate headquarters where biophilic design demands seamless wood-look or custom-printed surfaces.
Suspended systems anchor current deployment; Direct Attach methods are climbing the fastest as school districts prioritize budget containment.
End User:
Customer type determines performance certification requirements and replacement cycle frequency.
- Healthcare Facilities:Infection-control protocols mandate non-porous, disinfectant-resistant surfaces with EPA-compliant emission profiles. Acute care construction in Texas and Florida is expanding fastest among all end-user channels.
- Commercial Buildings:Class A office towers and retail centers balance acoustic comfort with aesthetic flexibility, driving specification of modular systems that accommodate tenant improvement cycles.
- Educational Institutions:K-12 and university construction prioritizes budget durability and fire safety ratings over premium acoustic performance, with procurement centralized at state or district levels.
- Residential Spaces:Basement finishing and home theater applications represent a fragmented, price-sensitive channel served through big-box retail and contractor direct channels.
Commercial Buildings sustain the largest installed base; Healthcare Facilities show the steepest expansion trajectory.
Material:
Supply concentration and energy intensity separate margin profiles across substrate categories.
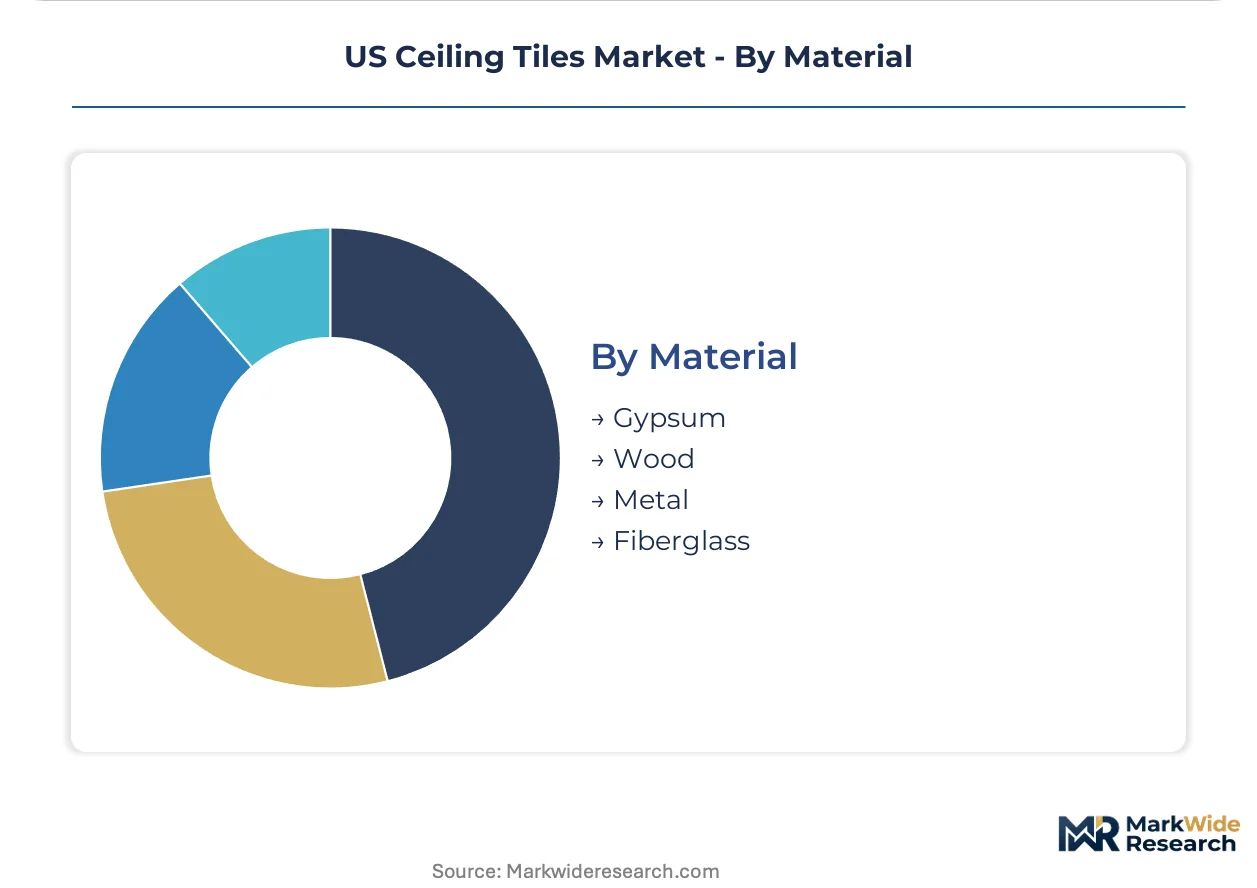
- Gypsum:Calcined gypsum core with paper or fiberglass facings delivers inherent fire resistance and dimensional stability. Production clusters in Indiana and Ohio create freight penalties for Sun Belt deliveries.
- Fiberglass:Fine glass fiber mat construction achieves high NRC ratings at low product weight, penetrating open-ceiling design trends in corporate headquarters where exposed structure demands lightweight overhead treatment.
- Metal:Aluminum and steel panels offer durability, recyclability, and integrated HVAC compatibility for airports, transit stations, and industrial environments.
- Wood:Veneer and solid wood products face EPA TSCA Title VI formaldehyde constraints, compressing specification to low-emitting certified lines in healthcare and education markets.
Gypsum formulations dominate current specification; Fiberglass alternatives are expanding most quickly as open-plan commercial design accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas commercial construction outpaces California renovation cycles by a wide margin, while Florida healthcare facility development accelerates faster than Northeast institutional spending. Regional demand concentrates in Sun Belt states where speed-to-occupancy pressures reshape procurement patterns.
Texas
Speculative office builds in Dallas-Fort Worth and Houston generate concentrated demand for rapid-install suspended ceiling assemblies. EPA TSCA Title VI compliance shapes material selection for wood-based substrates in mixed-use developments. San Antonio medical district construction anchors healthcare specification growth for infection-resistant mineral fiber systems.
Florida
Acute care facility expansion in Tampa and Orlando drives specification of non-porous, disinfectant-resistant ceiling surfaces. OSHA workplace noise standards enforce NRC-rated acoustic treatments in Miami Class A office towers. Jacksonville distribution center construction favors budget mineral fiber formats with established supply chain availability.
California
CALGreen embodied-carbon disclosure mandates elevate EPD-certified low-carbon formulations in Los Angeles and San Francisco commercial projects. Title 24 energy codes integrate ceiling assemblies into whole-building performance modeling. Silicon Valley corporate headquarters specify biophilic design elements and smart ceiling panels with embedded environmental sensors.
New York Metro
Historic building renovation in Manhattan prioritizes fire-rated gypsum systems that meet ICC codes while preserving ceiling height. New Jersey healthcare construction follows Joint Commission protocols for cleanable acoustic surfaces. Connecticut educational institutions specify direct-attach methods for budget-constrained K-12 corridors and gymnasiums.
Midwest Manufacturing Belt
Indiana and Ohio mineral fiber production clusters create freight cost penalties for distant project deliveries. Chicago commercial retrofit sustains demand for standard 2x2 and 2x4 panel formats with legacy T-bar grid compatibility. Michigan automotive facility construction applies OSHA noise exposure limits to mandate high-NRC acoustic treatments in manufacturing environments.
US Ceiling Tiles Market Competitive Landscape
Top-tier vendors anchor specification-driven healthcare and education channels, while mid-tier fabricators compete on price for commodity commercial construction. The market structure reflects moderate consolidation around mineral fiber supply chain control. Three archetypes dominate: vertically integrated substrate producers, gypsum-specialist diversified building materials firms, and fiberglass-focused premium acoustic specialists. Competitive moves concentrate on backward integration into mineral wool supply and geographic expansion toward Sun Belt demand centers.
Among established US-based manufacturers, Armstrong World Industries Inc., USG Corporation, and Rockfon occupy positions across distinct material technology tiers. Armstrong exemplifies the integrated mineral fiber archetype with captive supply chain control. USG represents the gypsum-diversified model leveraging fire-resistance expertise across building envelope categories. Rockfon anchors the stone wool fiberglass segment optimized for open-plan commercial specifications. These three firms collectively shape procurement standards through specification relationships with healthcare systems and educational purchasing cooperatives.
| Leading Market Players |
|---|
| Rockfon |
| Hunter Douglas |
| Armstrong World Industries Inc. |
| SAS International |
| Gordon Incorporated |
| USG Corporation |
| OWA Ceiling Systems Inc. |
| Ceilume |
| CertainTeed |
| Others |
Pricing and Supply Chain Analysis
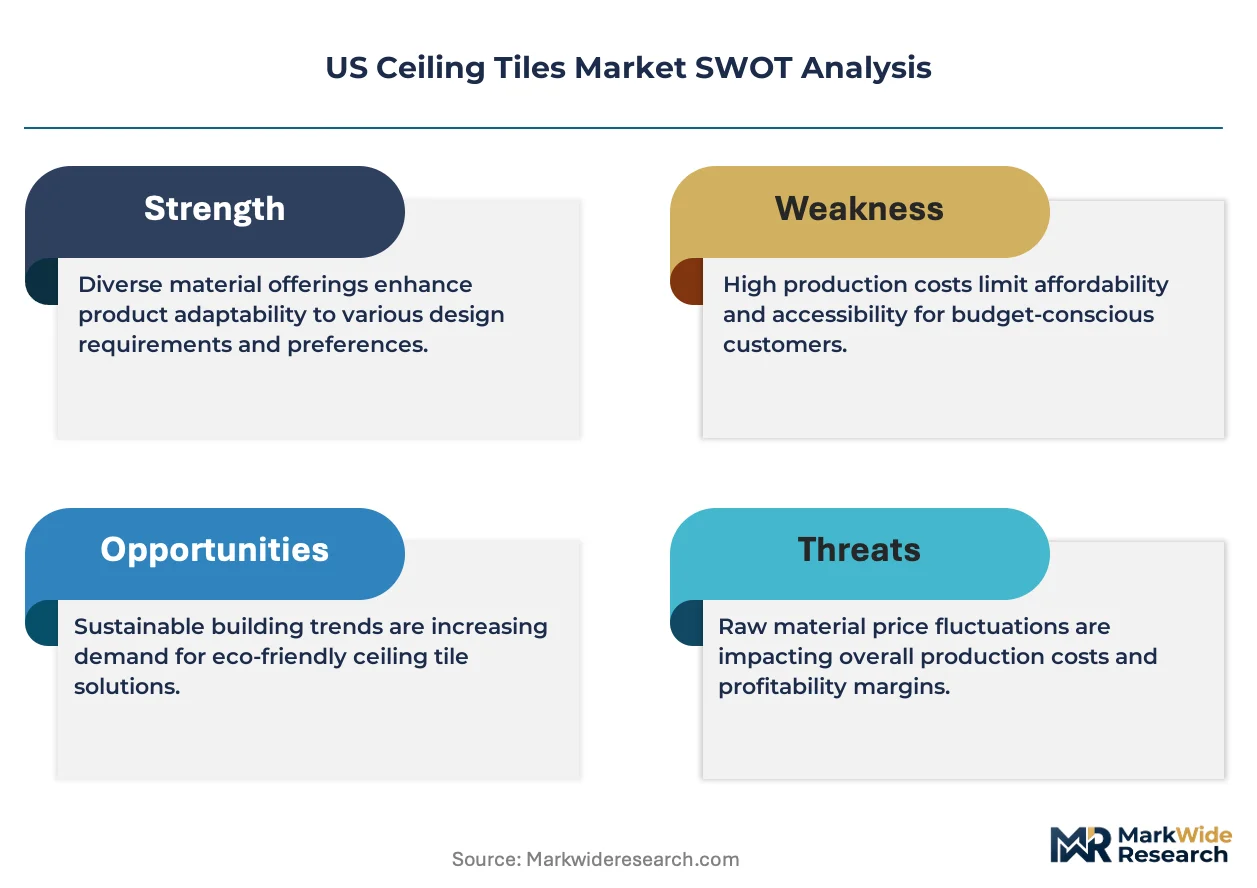
EPA TSCA Title VI formaldehyde emission standards gate qualified supply and premium-tier pricing access, compressing wood-based substrate options while elevating mineral fiber and gypsum alternatives that command specification premiums in healthcare and education procurement.
Pricing Analysis
Capacity additions in Texas and Florida are reshaping price floors for rapid-install suspended assemblies, yet three-tier pricing structure across premium, standard, and economy levels persists. Price differentiation hinges on NRC acoustic certification tier and Joint Commission cleanability compliance, with healthcare specifications least sensitive and K-12 educational procurement most cost-constrained. Cost compression in commodity mineral fiber intensifies because Midwest production clusters face freight penalties to Sun Belt demand centers.
Supply Chain Analysis
Domestic-content mandates under Buy America provisions for federal healthcare construction are reshaping sourcing toward Indiana and Ohio mineral fiber production clusters. Raw material dependencies center on slag wool, recycled newsprint, and perlite ore, with supply chain risk anchored in single-source vulnerability for specialized acoustic-grade fiberglass mat. Distribution runs through regional building materials distributors and direct-to-contractor digital platforms for standardized specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Ceiling Tiles Market reads as a late-cycle quality story, with demand shifting decisively toward infection-resistant, low-emitting premium specifications that reward qualified manufacturers with pricing power.
For Market Incumbents: Anchor specification relationships with healthcare systems and educational purchasing cooperatives through captive mineral fiber supply chain control. Invest in EPD-certified low-carbon formulations to capture California CALGreen first-mover advantage, while defending against fiberglass specialists penetrating open-plan commercial segments with lightweight stone wool technology. For New Entrants and Emerging Players: The price-point gap between premium acoustic-rated healthcare systems and economy-grade educational specifications creates entry terrain for mid-tier challengers. Target direct-attach gypsum assemblies in Midwest K-12 corridors where budget containment overrides brand loyalty, leveraging digital procurement channels to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Roll-up economics work for regional ceiling system fabricators because specification authority is consolidating into design-build firms that bundle performance guarantees. The long-term viability window favors platforms with backward integration into mineral wool supply and UL certification infrastructure. Watch OSHA noise standard enforcement intensity as the inflection signal for acoustic treatment demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Wool Supply | Captive slag wool production insulates margins from natural gas price volatility in Indiana and Ohio clusters. |
| EPD Certification for Low-Carbon Formulations | California CALGreen compliance creates specification preference in Los Angeles and San Francisco commercial projects. |
| Smart Ceiling Panel Development | Embedded air quality sensors and occupancy detection automate HVAC responsiveness in Class A office towers. |
| Direct-to-Contractor Digital Platform Launch | E-procurement channels disintermediate traditional distribution for standardized 2x2 and 2x4 commercial specifications. |
| Healthcare System Partnership Expansion | Joint Commission cleanability protocols lock in long-term supply relationships for infection-resistant mineral fiber systems. |
Research Methodology
Bottom-up healthcare and education construction modeling reconciled against top-down mineral fiber production tracking forms the analytical core. Primary interviews with facilities managers at Texas and Florida hospital systems, acoustical consultants, GPO procurement directors, and ceiling system distributors combined with secondary validation from EPA TSCA filings, OSHA enforcement databases, UL certification registries, and state-level building permit records. Triangulation against customs data for fiberglass mat imports and SEC 10-K disclosures from building materials firms anchored supply-side estimates.
Input-output matrices mapped product type, installation method, end-user channel, and material chemistry dimensions across the projection horizon. CAGRs derived from regression analysis of historical permit data against specification trend indices, with forecast inputs including Sun Belt commercial construction velocity and healthcare infection-control protocol adoption curves.
The model assumes a particular technology adoption path for smart ceiling panels with embedded sensors; alternative pathways for wireless building automation would alter the outlook. Forecasts reflect assumptions regarding EPA enforcement consistency, state-level carbon accounting expansion, and mineral wool energy cost trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Canada Asphalt Shingles Market
Building & Construction Materials
France Oriented Strand Board Market
Building & Construction Materials
Waterproofing Solution Market
Building & Construction Materials
Indonesia Cement Market
Building & Construction Materials
North America Metallic Barn Doors Market
Building & Construction Materials
Vietnam Ceramic Tiles Market
Building & Construction Materials
France Ceramic Tiles Market
Building & Construction Materials
US Geosynthetics Market
Building & Construction Materials
Asia-Pacific Flanges Market
Building & Construction Materials
North America Siding and Decking Market
Building & Construction Materials
Composite Slate Roofing Market
Building & Construction Materials
Autoclave Aerated Concrete Market
Building & Construction Materials
Steel Rebar Market
Building & Construction Materials
EMEA Prestressed Concrete (PC) Wire and Strand Market
Building & Construction Materials
Runway Pavement Grade Asphalt Market
Building & Construction Materials
Europe AAC Blocks and Panels Market