
 North America Gutter Guards Market | 2026-2036
North America Gutter Guards Market Size, Share, and Industry Trends Forecast 2026-2036
North America Gutter Guards Market Analytics
EPA stormwater runoff regulations is recalibrating how municipalities and homeowners evaluate gutter protection systems across the United States and Canada. Amerimax Home Products leverages its broad retail distribution network to sustain volume leadership in big-box channels. Leaf Filter North differentiates through professional installation partnerships that control customer acquisition costs. Gutterglove specializes in stainless steel micro-mesh engineering that commands premium positioning in debris-heavy climates.
Gutter guards are mechanical screening devices installed over roof drainage channels to block leaves, pine needles, and sediment while permitting water passage, typically fabricated from aluminum sheets, stainless steel weave, or vinyl extrusions with aperture sizes ranging from 50 to 500 microns depending on debris type. Their primary commercial purpose is preventing gutter clogging, basement flooding, and fascia board rot in residential and commercial structures. Mesh products dominate unit volume due to accessible price points and DIY compatibility, while surface tension systems capture disproportionate margin pools through professional-channel exclusivity. Aluminum leads material demand for its corrosion resistance and formability, though copper commands architectural specification in upscale residential segments.
FEMA floodplain mapping updates and the International Building Code adoption across U.S. jurisdictions shape product performance requirements and installation liability standards. Health Canada and the U.S. Consumer Product Safety Commission monitor material safety in vinyl formulations and metal coatings. Stakeholders must track evolving municipal green infrastructure mandates that may classify gutter guards as qualifying stormwater best management practices, altering specification authority from homeowners to civil engineers.
Market Dynamics
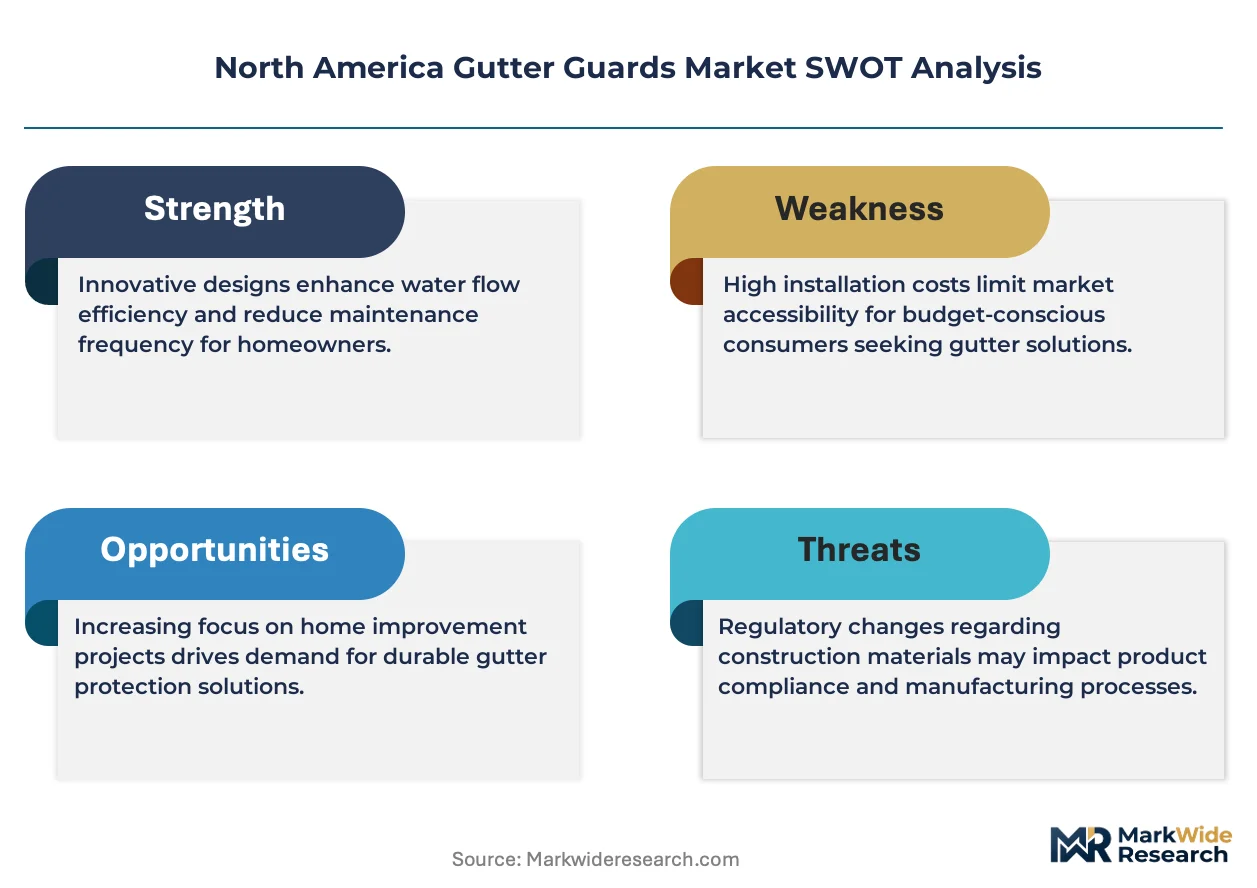
EPA stormwater management guidelines are recalibrating municipal specification authority across the United States and Canada, shifting purchase decisions from individual homeowners toward civil engineering departments and green infrastructure procurement officers.
Growth Catalysts
- FEMA Floodplain Mapping Updates:Revised flood risk assessments in coastal and riverine zones are mandating improved drainage infrastructure, directly expanding gutter guard specification in high-risk counties across Florida, Louisiana, and Texas.
- Pine Needle Debris Concentration:Southeastern United States homeowners face unique clogging challenges from coniferous vegetation, driving premium micro-mesh adoption in Georgia, the Carolinas, and Alabama.
- DIY Channel Expansion:Big-box retail networks are broadening consumer access to aluminum mesh systems, lowering installation barriers for residential property owners in suburban and exurban markets.
Market Restraints
- Aluminum Price Volatility:Raw material cost fluctuations in primary aluminum markets compress margin stability for extruded gutter guard manufacturers serving price-sensitive segments.
- Surface Tension System Concentration:Professional installation channel dependence creates bottleneck risk, as certified contractor availability limits surface tension product penetration in rural Canadian provinces and remote U.S. markets.
- Vinyl Formulation Scrutiny:Health Canada and the U.S. Consumer Product Safety Commission monitoring of plasticizer compounds constrains low-cost vinyl product positioning in regulated jurisdictions.
Strategic Opportunities
- Green Infrastructure Mandates:Municipal stormwater best management practice classifications could reclassify gutter guards as qualifying infrastructure, opening specification to civil engineering procurement in Chicago, Toronto, and Vancouver metropolitan areas.
- Copper Architectural Specification:Upscale residential segments in California, Colorado, and Pacific Northwest markets present untapped demand for corrosion-resistant copper systems in custom home construction.
- Micro-Mesh Technology Convergence:Integration of stainless steel weave engineering with smart home moisture monitoring systems creates premium positioning for connected gutter protection in tech-forward housing developments.
Industry Challenges
- Installation Certification Complexity:Divergent municipal building code adoption timelines across U.S. states create compliance fragmentation, forcing manufacturers to maintain multiple product variants for jurisdictional approval.
- Contractor Channel Capacity Constraints:Professional installation partnerships require sustained training investment, as qualified technician scarcity limits surface tension system rollout velocity in secondary markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Gutter Guards Market |
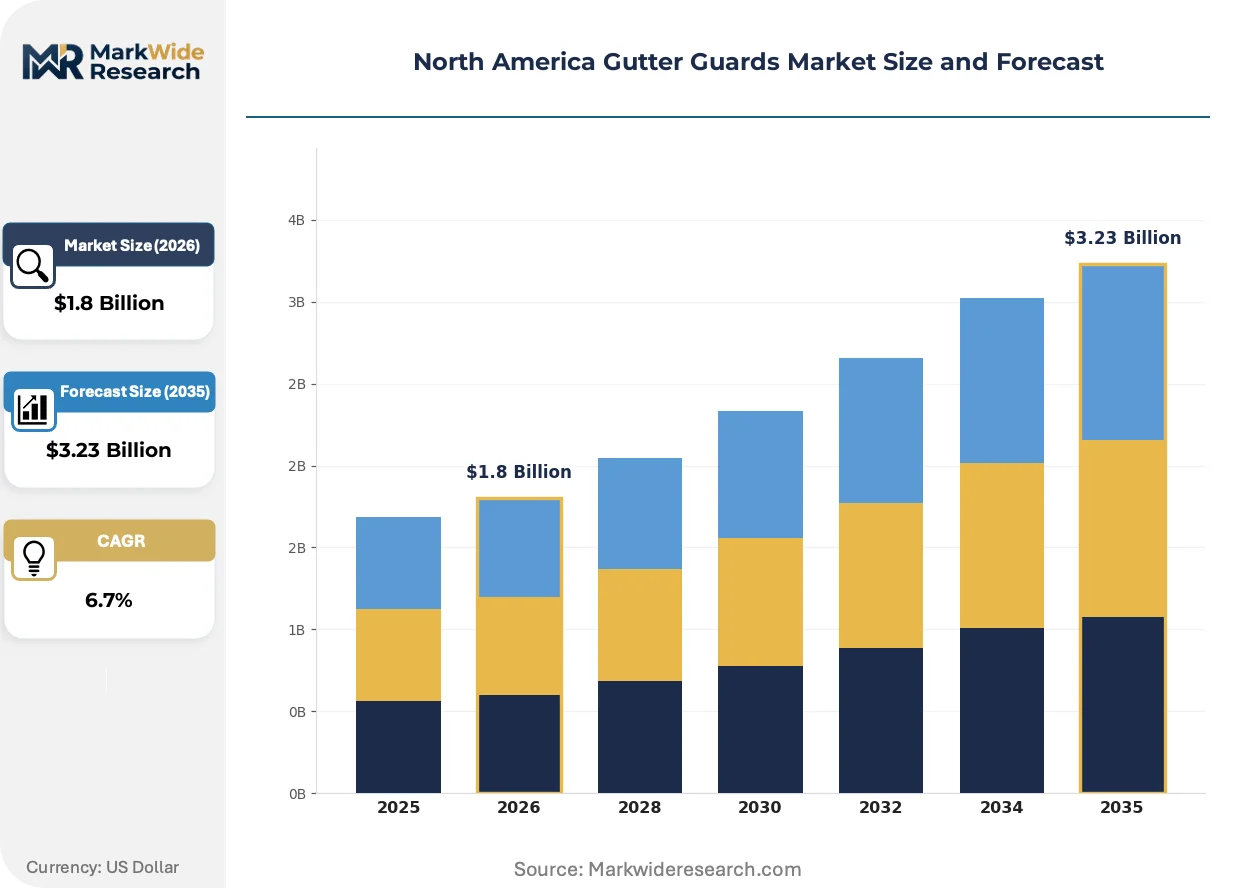
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mesh, Surface Tension, Reverse Curve, Bottle Brush Material: Aluminum, Stainless Steel, Vinyl, Copper Installation Type: DIY, Professional, Retrofit, New Construction End User: Residential, Commercial, Industrial, Municipal |
| Companies Covered | Amerimax Home Products, Gutterglove, Leaf Filter North, HomeCraft Gutter Protection, All American Gutter Protection, Gutter Helmet, Allied Gutter Protection, Gutter Guards America, LeafGuard Brand of Gutter Protection, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Gutter Guards Market Evolving Landscape
Product engineering and procurement patterns are diverging across price tiers, with material science advances in micro-mesh fabrication running parallel to channel restructuring in how residential buyers access installation services.
Stainless steel micro-mesh systems are expanding into debris-heavy climate zones previously dominated by aluminum alternatives. Pacific Northwest and Northeast U.S. homeowners are adopting these products at accelerated rates due to superior pine needle and shingle grit filtration. This material transition is expanding into premium residential segments, compressing price elasticity for basic mesh alternatives while elevating performance benchmarks across the category.
The International Building Code adoption across U.S. jurisdictions is tightening installation liability standards and product performance documentation requirements. Manufacturers must now submit third-party testing data for wind uplift and water throughput capacity to secure municipal approval. Surface tension system providers face the steepest compliance burden, as their proprietary designs require individualized engineering review in code-stringent states including Florida and California.
Homeowner buying patterns are fragmenting between self-installation and turnkey service models. DIY-oriented buyers in Midwest and Southwest markets prioritize big-box accessibility and aluminum price points, while coastal and Northern buyers gravitate toward professional installation guarantees. This bifurcation is most visible in metropolitan statistical areas exceeding one million population, where contractor network density supports surface tension system penetration unavailable in rural markets.
North America Gutter Guards Market Segmentation
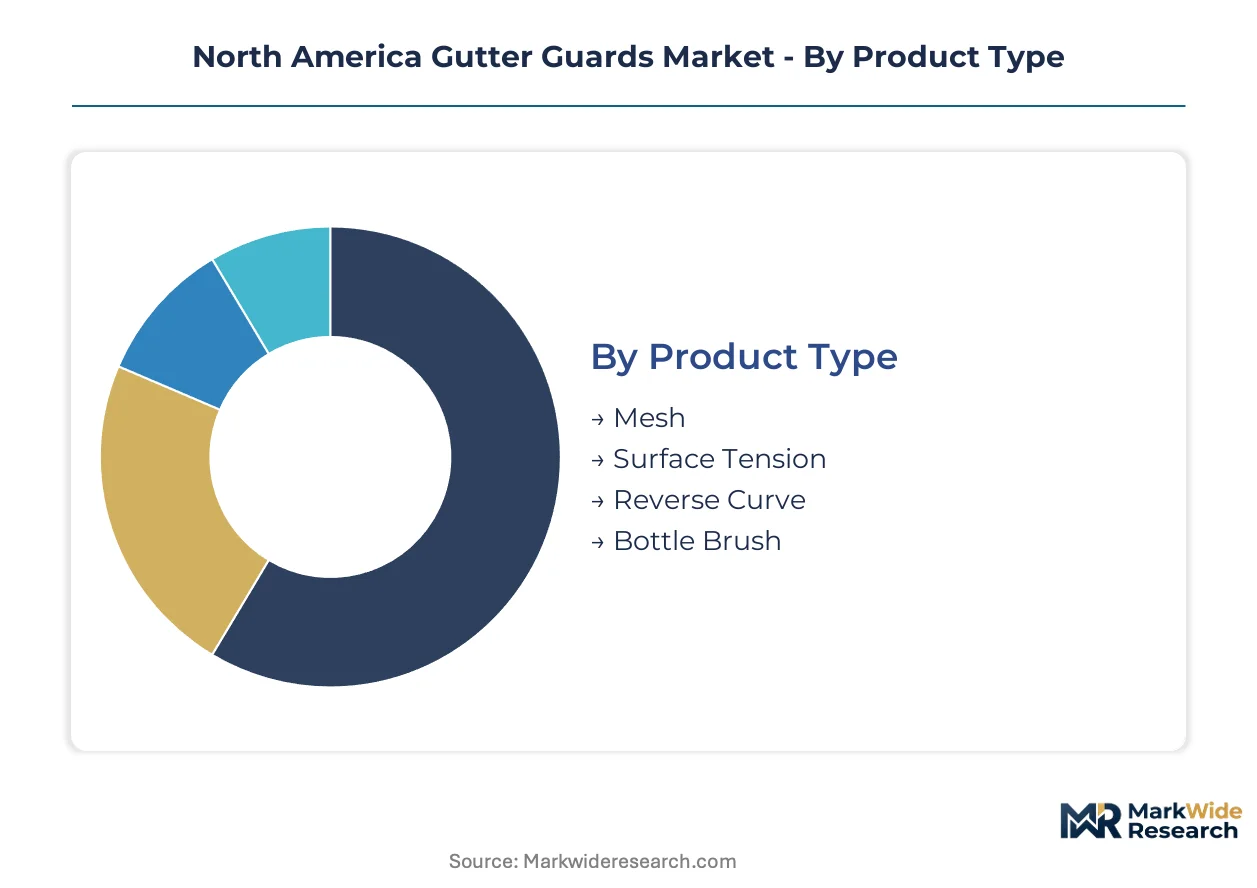
Gutter guard specification diverges sharply across climate zones, building codes, and procurement channels. Understanding where each segment sits—standalone homeowner purchase versus embedded contractor specification—determines pricing power and distribution strategy.
Product Type:
Integration depth varies: mesh and surface tension systems penetrate both DIY retail and professional channels, while reverse curve and bottle brush products remain contractor-dependent.
- Mesh:Aluminum or stainless steel screens with aperture sizes from 50 to 500 microns filter leaves and sediment while permitting water throughput. Demand clusters in Southeastern United States counties where pine needle debris volume strains lesser systems. EPA stormwater guidelines in Florida and Georgia municipalities are elevating mesh to specified infrastructure status.
- Surface Tension:Curved metal profiles exploit water adhesion physics to draw rainfall into gutters while shedding debris. Professional installation exclusivity in California and Pacific Northwest markets sustains margin premiums unavailable to self-install alternatives. FEMA floodplain mapping updates in coastal Louisiana and Texas counties are mandating improved drainage performance that surface tension systems deliver.
- Reverse Curve:Engineered lip designs separate water from debris through surface tension physics. Health Canada building code adoptions in Ontario and British Columbia are tightening performance documentation requirements for these proprietary systems.
- Bottle Brush:Cylindrical bristle inserts sit inside gutters to trap debris while water flows beneath. Rural Canadian provinces and remote U.S. mountain markets with limited contractor density favor this low-complexity solution.
Volume placements concentrate in Mesh; the faster expansion belongs to Surface Tension.
Material:
Cost tier stratification separates commodity aluminum from architectural-grade copper, with stainless steel capturing premium positioning in debris-heavy climates.
- Aluminum:Corrosion-resistant extrusions dominate unit economics through formability and accessible price points. Big-box retail networks across Midwest and Southwest U.S. states stock aluminum mesh systems for suburban DIY buyers. Raw material cost volatility from primary aluminum markets compresses margin stability for manufacturers serving price-sensitive segments.
- Stainless Steel:Micro-mesh weave engineering commands specification in coniferous vegetation zones where pine needles defeat aluminum alternatives. Pacific Northwest and Northeast U.S. homeowners are adopting these products at accelerated rates due to superior shingle grit filtration.
- Vinyl:Extruded plastic formulations compete at entry price points in warm-climate markets. U.S. Consumer Product Safety Commission monitoring of plasticizer compounds constrains positioning in regulated jurisdictions.
- Copper:Architectural-grade material specifies into custom home construction in Colorado and California upscale segments where aesthetic integration with premium roofing commands priority.
Aluminum captures the highest shipment volumes; copper climbs the fastest among premium residential specifications.
Installation Type:
Customer type fragmentation splits procurement between self-directed homeowners and turnkey service buyers, with building lifecycle stage determining retrofit versus new construction timing.
- DIY:Big-box accessible systems with snap-fit or screw-mount designs enable homeowner self-installation. Suburban and exurban markets across Midwest and Southwest U.S. states favor this channel for aluminum mesh products.
- Professional:Certified contractor networks install surface tension and reverse curve systems with performance guarantees. Metropolitan statistical areas exceeding one million population support this channel density unavailable in rural Canadian provinces.
- Retrofit:Gutter guard addition to existing drainage infrastructure addresses clogging failures in mature housing stock. Southeastern U.S. counties with aging residential inventory drive replacement demand.
- New Construction:Builder specification at rough-in stage captures cost efficiencies and code compliance integration. International Building Code adoption timelines across U.S. jurisdictions shape product approval requirements for this segment.
Professional installation generates the highest revenue per unit; new construction is gaining share fastest as green infrastructure mandates expand.
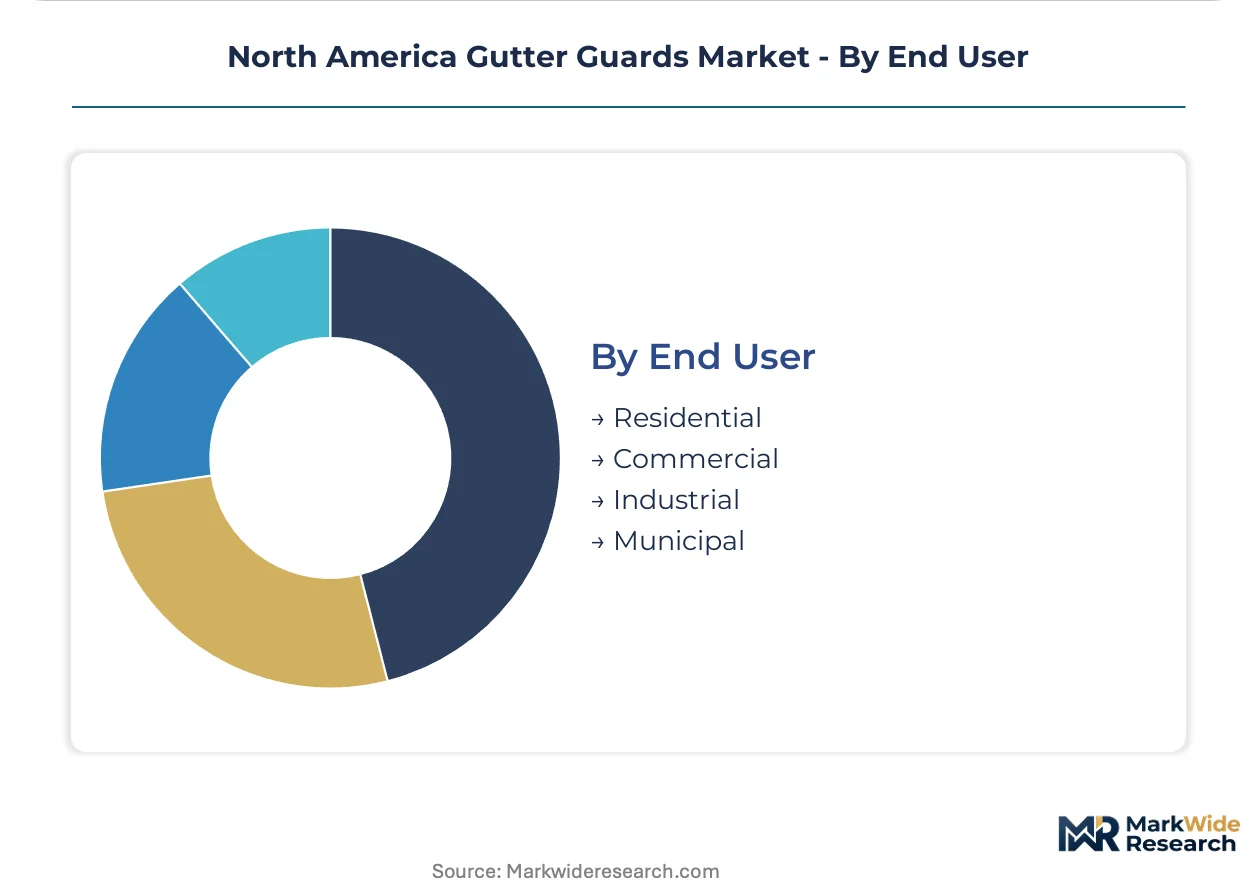
End User:
Application context shifts specification authority from individual decision-makers to institutional procurement officers as scale increases.
- Residential:Single-family and multifamily property owners purchase through retail or contractor channels based on debris type and climate exposure. Pine needle concentration in Georgia and the Carolinas drives premium micro-mesh uptake.
- Commercial:Property management firms and facility operators specify systems for retail centers, office parks, and hospitality assets. Liability concerns from basement flooding and fascia damage elevate professional installation preference.
- Industrial:Manufacturing and warehousing facilities with large roof footprints require engineered drainage solutions. EPA stormwater discharge permits in industrial zones are elevating gutter guard classification toward best management practice status.
- Municipal:Civil engineering departments specify gutter guards as green infrastructure components in Chicago, Toronto, and Vancouver metropolitan stormwater management programs.
Residential dominates unit placements; municipal procurement shows the steepest expansion trajectory as regulatory frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Atlanta anchors North American gutter guard demand, with metropolitan statistical areas across the Southeast driving premium micro-mesh specification for pine needle filtration.
Southeastern United States
Georgia and the Carolinas generate concentrated demand for stainless steel micro-mesh systems that filter coniferous debris. EPA stormwater management guidelines in Florida counties are elevating gutter guards to specified infrastructure status. Atlanta and Charlotte metropolitan areas host contractor network density that supports professional installation channels for surface tension systems.
Southwestern United States
Texas and Arizona homeowners prioritize aluminum mesh products through big-box retail channels for dust and monsoon debris management. FEMA floodplain mapping updates in Houston and Dallas counties mandate improved drainage performance. San Antonio and Austin metro areas exhibit accelerated DIY adoption for suburban housing stock retrofit.
Pacific Northwest
Washington and Oregon markets command premium positioning for stainless steel systems filtering heavy rainfall and evergreen debris. Health Canada building code adoptions in British Columbia influence performance documentation requirements across the Cascadia corridor. Seattle and Portland metropolitan areas concentrate professional installation partnerships for surface tension technology.
Midwestern United States
Illinois, Ohio, and Michigan markets split between DIY aluminum mesh and contractor-installed systems based on urban density. International Building Code adoption timelines across Chicago and Detroit metropolitan areas shape product approval requirements. Cleveland and Indianapolis suburban corridors favor accessible price points for aging residential inventory retrofit.
Canada
Ontario and British Columbia provinces lead national specification with green infrastructure procurement emerging in Toronto and Vancouver municipal programs. Health Canada monitoring of vinyl formulation safety constrains low-cost product positioning. Calgary and Edmonton markets in Alberta exhibit demand for debris-heavy climate solutions in new construction segments.
North America Gutter Guards Market Competitive Landscape
Premium-margin players sit above commodity-margin players across installation-channel exclusivity, with surface tension specialists commanding contractor-dependent pricing power while aluminum mesh fabricators compete through retail accessibility. The vendor base organizes into three strategic archetypes: retail-distributed volume leaders, professional-channel exclusivity holders, and micro-mesh engineering specialists. Dominant competitive moves include geographic expansion of certified contractor networks and portfolio diversification into connected home integration.
Within the retail-distributed tier, Amerimax Home Products occupies a position exemplifying broad-channel volume leadership. Among professional-installation exclusivity holders, Leaf Filter North and Gutterglove represent contrasting approaches to contractor network control and premium material specification. These three entities anchor the competitive structure, with each exemplifying distinct margin-tier positioning across the North American market.
| Leading Market Players |
|---|
| Amerimax Home Products |
| Gutterglove |
| Leaf Filter North |
| HomeCraft Gutter Protection |
| All American Gutter Protection |
| Gutter Helmet |
| Allied Gutter Protection |
| Gutter Guards America |
| LeafGuard Brand of Gutter Protection |
| Others |
Value Network & Pricing Analysis
Primary aluminum ingot costs cascade through extrusion tolling, coating application, and retail markups to stratify final product positioning across DIY and professional installation tiers. Raw material volatility from commodity exchanges compresses margin buffers for manufacturers serving big-box channels while stainless steel micro-mesh specialists maintain pricing power through proprietary weave engineering and certified contractor exclusivity.
Pricing Analysis
Performance-guaranteed throughput anchors value-based pricing for surface tension systems installed by certified contractors in FEMA-designated floodplain counties across Florida, Louisiana, and Texas. Three-tier pricing structure across premium, standard, and economy levels separates architectural copper specifications from aluminum mesh DIY products and entry vinyl alternatives. Cost compression in aluminum extrusion tiers is intensifying because LME price swings force margin trade-offs between volume maintenance and profitability. Suburban Midwest homeowners exhibit highest price sensitivity through big-box procurement, while coastal municipalities specifying stormwater infrastructure show lowest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Chinese stainless steel micro-mesh weaving capacity that Pacific Northwest and Northeast installers depend on for debris-heavy climate performance. Primary aluminum smelting concentrates in Canada, domestic U.S. Pacific Northwest, and Gulf Coast regions, while copper architectural grades source from Chilean mining operations and domestic refining. Tariff exposure on Chinese steel weave inputs threatens cost stability for premium micro-mesh fabricators serving coniferous vegetation markets. Distribution runs through dual-channel structures: big-box retail networks for self-install aluminum products and certified contractor partnerships for professional-grade surface tension systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in gutter protection is becoming a vertical-integration race, with upstream control over stainless steel micro-mesh weaving and downstream capture of certified installer networks representing the decisive levers for margin defense.
For Market Incumbents: Acquire proprietary micro-mesh weaving technology to secure supply continuity for premium debris-filtration products targeting Southeastern pine needle markets. Consolidate regional certified installer networks in Atlanta, Charlotte, and Houston metropolitan areas to defend against emerging direct-to-consumer surface tension entrants. EPA stormwater infrastructure classification shifts threaten to displace homeowner-driven specification with municipal engineering procurement, requiring preemptive certification investment. For New Entrants and Emerging Players: Capture municipal green infrastructure procurement emerging in Chicago, Toronto, and Vancouver stormwater management programs where gutter guards qualify as best management practices. Target copper architectural specification in Colorado and California custom home construction where aesthetic integration commands premium positioning. Partner with regional roofing contractors for new construction rough-in specification rather than competing for saturated retrofit replacement demand. For Investors and Strategic Acquirers: FEMA floodplain mapping updates mandating improved drainage in coastal counties is the leading indicator that professional-installation surface tension providers will outperform DIY-accessible alternatives across the analysis window. Focus acquisition screening on stainless steel micro-mesh engineering specialists with Health Canada and International Building Code documentation already secured. Watch for municipal procurement officer hiring in Great Lakes and Pacific Northwest metropolitan areas as signal of specification authority shift from residential to civil engineering channels.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Contractor Network Expansion | Controls customer acquisition costs in Atlanta and Charlotte metropolitan areas where surface tension penetration depends on installation density. |
| Stainless Steel Micro-Mesh Backward Integration | Captures weaving technology to secure supply for Pacific Northwest and Northeast debris-heavy climate specifications. |
| Municipal Procurement Certification | Positions products for Chicago and Toronto green infrastructure mandates elevating gutter guards to engineered stormwater status. |
| Copper Architectural Grade Introduction | Penetrates Colorado and California upscale residential segments where roofing aesthetic integration commands specification priority. |
| Smart Home Moisture Monitoring Integration | Creates premium positioning in tech-forward housing developments through connected gutter protection system convergence. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this North American gutter guards market assessment. Primary interviews with building materials procurement managers, certified gutter installation contractors, municipal stormwater engineering officers, and big-box retail category buyers combined with EPA guideline documentation, FEMA floodplain mapping databases, and Health Canada product safety filings. Bottom-up shipment analysis across aluminum extrusion, stainless steel weave, and copper architectural grades triangulated against top-down construction spending and housing stock age data.
Data-stream reconciliation across product type, material grade, installation channel, and end-user application dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume and value trajectories incorporating housing starts, retrofit replacement cycles, and municipal infrastructure spending patterns. Industry-specific inputs included International Building Code adoption timelines across U.S. state jurisdictions and green infrastructure procurement emergence in Canadian metropolitan areas.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to aluminum commodity price volatility, municipal stormwater regulation evolution, and certified contractor network expansion velocity. Forecasts reflect documented assumptions about housing construction trends and regulatory classification shifts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Decks Market
Building & Construction Materials
Residential Energy Efficient Windows Market
Building & Construction Materials
India Particle Board Market
Building & Construction Materials
Steel Wire Rope Products Market
Building & Construction Materials
Concrete Formwork System Market
Building & Construction Materials
Fiberboard Ceiling Market
Building & Construction Materials
Drainage System Market
Building & Construction Materials
Clay Roof Tiles Market
Building & Construction Materials
European Cross-Laminated Timber Market
Building & Construction Materials
Construction Elastomers Market
Building & Construction Materials
Engineered Wood Market
Building & Construction Materials
Australia Steel Rebar Market
Building & Construction Materials
Global Steel Sections Market
Building & Construction Materials
Architectural Membrane Market
Building & Construction Materials
Saudi Arabia Sanitaryware Market
Building & Construction Materials
India Ceramic Tiles Market