
 Global Commercial Insulation Market | 2026-2036
Global Commercial Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Commercial Insulation Market Foresight
Project finance tied to green building certifications is tilting procurement power toward contractors with capital-light leasing models. Owens Corning leverages its fiberglass manufacturing scale to lock in multi-year supply agreements with national distributors. Saint-Gobain anchors its position through backward integration into raw mineral sourcing across multiple continents. Kingspan Group specializes in prefabricated insulated panel systems that compress installation timelines for commercial developers.
Commercial insulation encompasses thermally resistant materials engineered to reduce heat transfer in non-residential structures, with mineral wool typically achieving thermal conductivity values between 0.030 and 0.045 W/mK depending on density and binder composition. These materials primarily serve to stabilize indoor temperatures, attenuate sound transmission, and contain fire spread across building envelopes and mechanical systems. Fiberglass retains volume leadership across new construction channels, while polyurethane foam captures premium margin pools in retrofit applications where space constraints demand higher R-values per inch. Mineral wool competes aggressively in fire-rated assemblies across high-rise commercial complexes and government buildings.
The EU Green Deal and REACH framework in Europe, alongside the EPA's energy efficiency mandates and state-level stretch codes in the United States, are tightening permissible thermal transmittance values and restricting certain flame retardant chemistries. Japan's METI building energy standards and China's GB codes for commercial construction are similarly elevating baseline insulation performance requirements. Stakeholders must monitor regulatory divergence between jurisdictions to avoid product certification fragmentation that could complicate cross-border manufacturing strategies.
Market Dynamics
Retrofit-intensive urban corridors across the United States, the United Kingdom, and Japan are compressing installation timelines and forcing material substitution toward higher R-value-per-inch systems that fit constrained envelope spaces.
Growth Catalysts
- EU Green Deal thermal performance mandates:Building renovation wave targets are accelerating deep retrofit activity across Germany and France, pulling mineral wool and polyurethane foam into government-backed efficiency programs.
- Healthcare facility thermal envelope upgrades:Hospital and clinic construction across North America and Europe is expanding demand for fire-rated insulation assemblies that meet stricter energy codes.
- Prefabricated panel systems:Offsite manufacturing methods are compressing commercial construction schedules and concentrating specification power with contractors capable of integrated envelope delivery.
Market Restraints
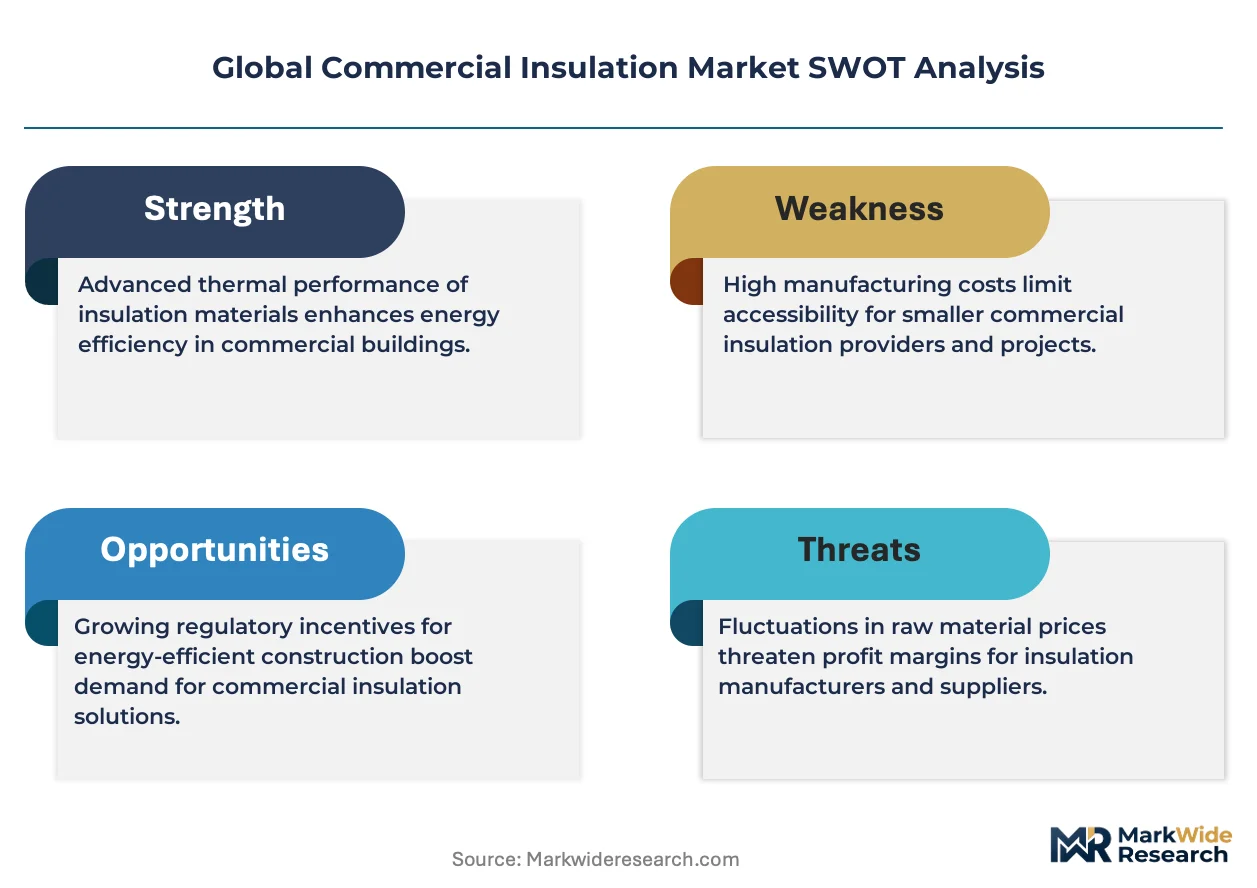
- Binder chemistry restrictions under REACH:European flame retardant regulations are forcing reformulation of mineral wool and fiberglass products, elevating R&D costs and certification timelines.
- Petrochemical feedstock volatility:Polyurethane foam insulation faces margin pressure from isocyanate and polyol price swings tied to crude oil and natural gas markets.
- Skilled installer scarcity:Deep retrofit markets lack sufficient trained labor for spray foam and blown-in applications, constraining project throughput in dense urban zones.
Strategic Opportunities
- Japan's METI building energy standard revisions:Commercial construction codes are elevating baseline insulation performance, opening import channels for high-performance systems.
- Green building certification-linked project finance:LEED and BREEAM requirements are tilting procurement toward contractors with capital-light leasing models and verified low-carbon material sourcing.
- Building-integrated photovoltaics convergence:Insulation manufacturers partnering with solar envelope developers can capture shared-specification value in net-zero commercial projects.
Industry Challenges
- Multi-jurisdiction product certification fragmentation:Divergent fire safety and thermal performance testing protocols between the EPA's state-level stretch codes, EU harmonized standards, and Japan's JIS requirements complicate cross-border manufacturing strategies.
- Legacy building stock assessment complexity:Retrofit projects require invasive envelope diagnostics that extend sales cycles and elevate pre-construction engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Commercial Insulation Market |
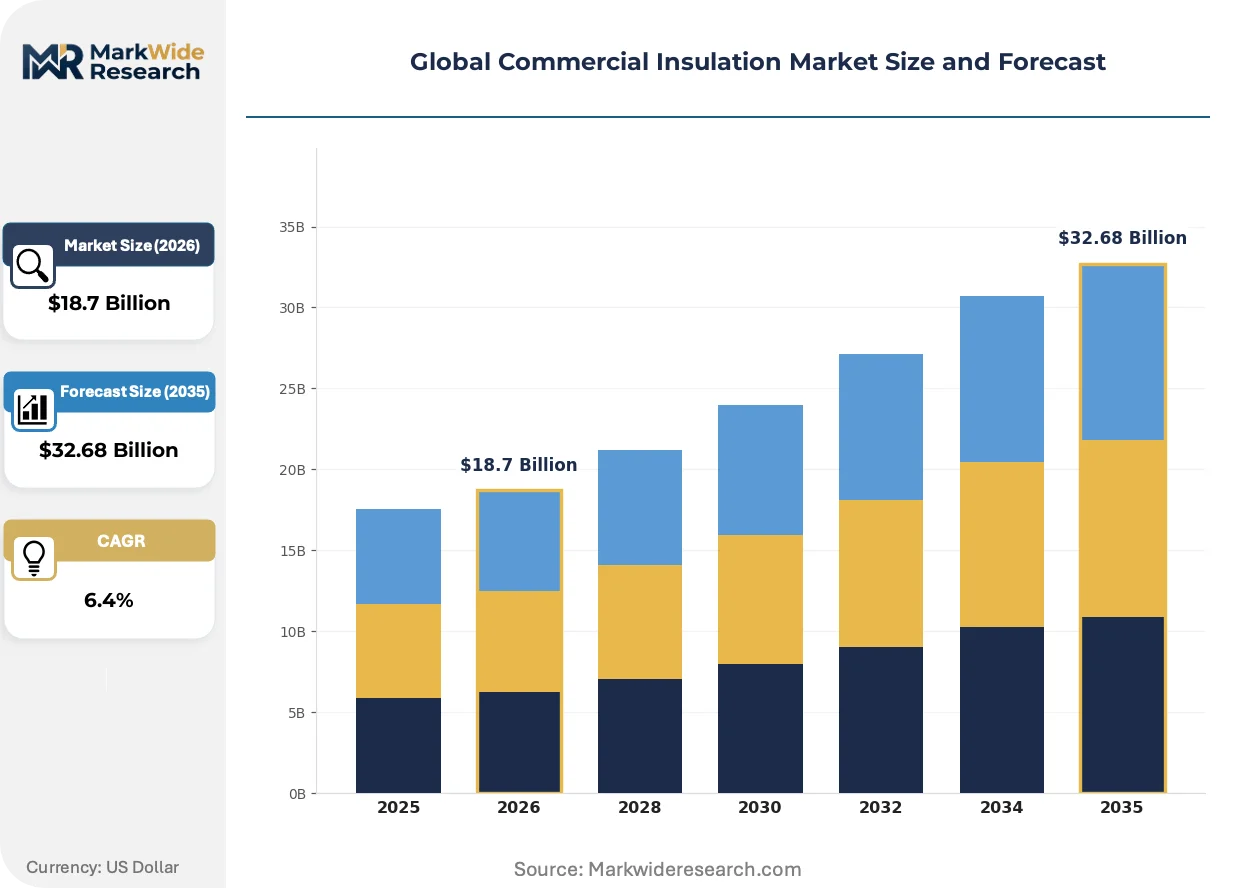
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Wool, Fiberglass, Polyurethane Foam, Polystyrene, Reflective Foil, Cellular Glass Application: Building Envelope, HVAC Systems, Roofing, Industrial Equipment, Acoustic Control, Fire Protection End User: Commercial Complexes, Educational Institutions, Hospitality, Healthcare Facilities, Government Buildings, Sports Facilities Installation Type: New Construction, Renovation, Retrofitting, Prefabricated Panels, Spray Application, Mechanical Fastening |
| Companies Covered | ROCKWOOL International A/S, BASF SE, Owens Corning, GAF Materials Corporation, Johns Manville, Saint-Gobain, Knauf Insulation, Dow Inc., Kingspan Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Commercial Insulation Market Shifts & Advancements
Material science advances and procurement model evolution are compressing the traditional specification pathway between manufacturer and end-user, with digital tools and performance guarantees displacing conventional bid-based purchasing.
Aerogel-enhanced blanket systems are hybridizing silica-based thermal barriers with flexible substrates to deliver R-values exceeding fiberglass in sub-inch thicknesses. Data center and cold storage developers are specifying these systems for envelope zones where floor-to-ceiling height constraints prohibit conventional insulation depths. The technology is hybridizing premium retrofit economics with space-constrained commercial verticals previously served by vacuum panels.
REACH framework amendments are restricting halogenated flame retardants in mineral wool binders, forcing European manufacturers toward bio-based and phosphorus chemistry alternatives. Industrial consequence includes extended product recertification timelines and elevated testing costs for exports into the European Economic Area. High-rise commercial complexes and government buildings—segments with stringent fire rating requirements—are responding by diversifying supplier bases to include North American and Asian producers with compliant formulations.
Performance-guaranteed energy savings contracts are displacing traditional material-specify-install sequences in commercial retrofit channels. National distributors and energy service companies are capturing specification authority previously held by architects and general contractors. This shift is most visible in the United States, where IRA-linked tax incentives and utility demand-side management programs are concentrating project origination with financiers rather than building owners.
Global Commercial Insulation Market Segmentation
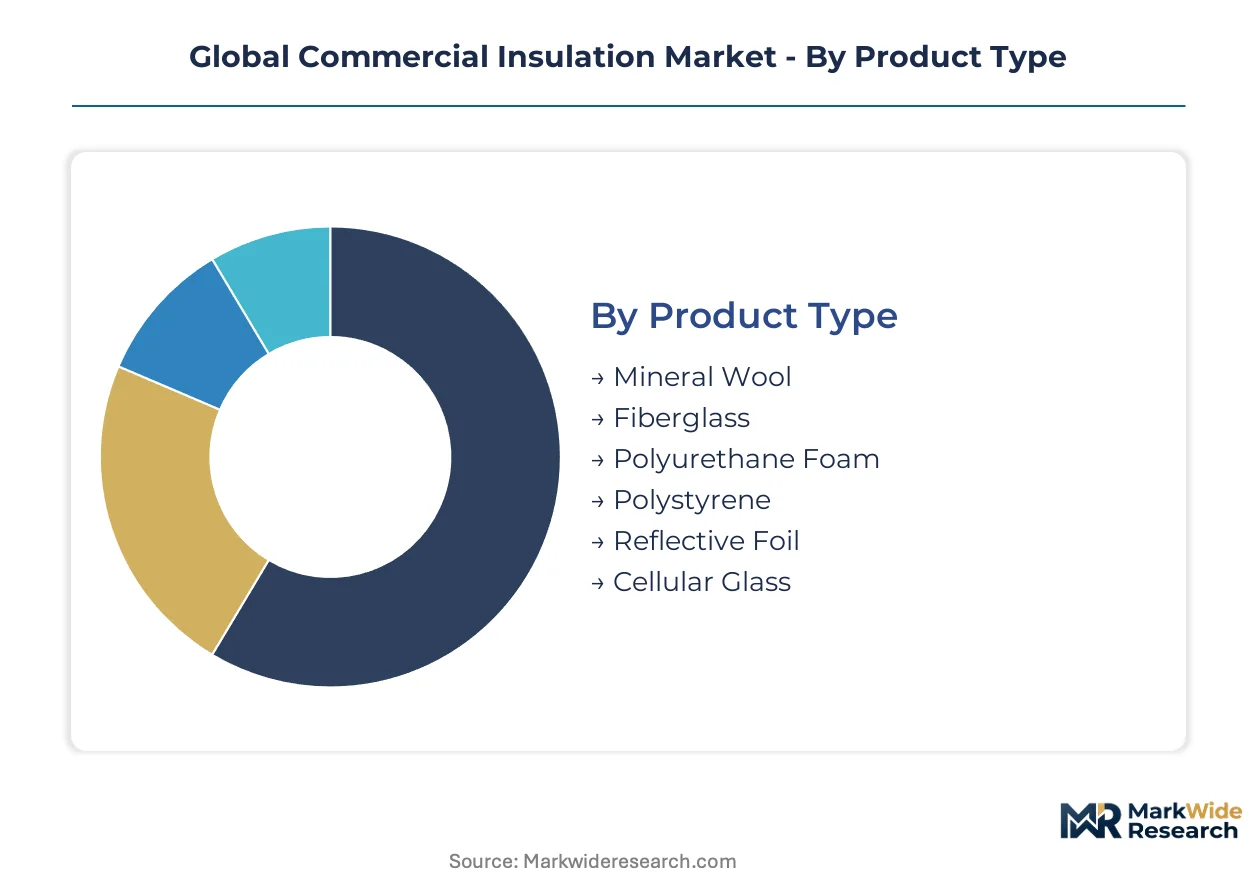
Commercial insulation procurement splits across material chemistry, building system placement, and project delivery method. Specification power concentrates with contractors who control installation timelines and energy performance guarantees.
Product Type:
Cost tier stratification separates commodity mineral-based systems from premium synthetic foams and advanced aerogel composites.
- Mineral Wool:Stone or slag fibers bound with phenolic or bio-based resins achieve thermal conductivity of 0.030–0.045 W/mK. Hospital construction across Germany and France specifies mineral wool for fire-rated curtain wall assemblies under EU Green Deal renovation mandates. REACH flame retardant restrictions are forcing European producers toward phosphorus-based binder reformulations.
- Fiberglass:Borosilicate glass fibers deliver the lowest installed cost per R-value among commercial-grade materials. Owens Corning locks in multi-year supply agreements with national distributors across the United States, capturing volume leadership in new construction channels. EPA energy efficiency mandates and state-level stretch codes in California and New York are tightening baseline thermal transmittance requirements.
- Polyurethane Foam:Closed-cell spray systems achieve R-6 per inch in envelope cavities where space constraints prohibit thicker assemblies.
- Polystyrene:Expanded and extruded boards serve below-grade commercial foundations and inverted roofing systems.
- Reflective Foil:Aluminum-faced radiant barriers address attic and metal building applications in warm-climate zones.
- Cellular Glass:Foam glass blocks provide compressive strength and moisture immunity for industrial process equipment and cryogenic piping.
Fiberglass holds installed capacity. Polyurethane foam is rotating up the share rankings.
Application:
Volume concentrates in envelope thermal barriers, with mechanical systems and specialty fire assemblies commanding premium pricing.
- Building Envelope:Wall, roof, and foundation insulation accounts for the majority of material tonnage in commercial construction. Deep retrofit corridors across the United Kingdom and Japan are compressing installation timelines and forcing substitution toward higher R-value-per-inch systems. Kingspan Group captures specification authority through prefabricated insulated panel systems that accelerate envelope completion.
- HVAC Systems:Ductwork and mechanical equipment insulation stabilizes temperature delivery and attenuates operational noise. Data center developers in the United States specify aerogel-enhanced blanket systems for mechanical rooms where floor-to-ceiling height constraints prohibit conventional insulation depths. IRA-linked tax incentives are concentrating project origination with energy service companies rather than building owners.
- Roofing:Tapered polyiso and mineral wool boards address thermal bridging in commercial flat roof assemblies.
- Industrial Equipment:Process piping and vessel insulation serves manufacturing, power generation, and petrochemical facilities.
- Acoustic Control:High-density mineral wool and fiberglass batts reduce sound transmission in open-plan offices and entertainment venues.
- Fire Protection:Intumescent and mineral fiber systems contain flame spread in high-rise commercial complexes and government buildings.
Building envelope commands volume leadership. HVAC systems are climbing the fastest specification rankings.
End User:
Customer type determines fire rating requirements, energy code stringency, and procurement route complexity.
- Commercial Complexes:Office towers and retail centers drive standardized specification through repeat developer relationships. LEED and BREEAM certification requirements are tilting procurement toward contractors with capital-light leasing models and verified low-carbon material sourcing across the United States and United Kingdom.
- Healthcare Facilities:Hospital and clinic construction demands fire-rated assemblies that meet stricter energy codes than general commercial stock. North American healthcare expansion is pulling mineral wool and polyurethane foam into government-backed efficiency programs.
- Educational Institutions:School districts and university systems balance first-cost constraints against long-term energy savings guarantees.
- Hospitality:Hotels and resorts prioritize acoustic performance and rapid construction schedules.
- Government Buildings:Federal, state, and municipal projects mandate domestic content and certified installer networks.
- Sports Facilities:Arenas and stadiums require specialized roofing and mechanical insulation for large-span structures.
Commercial complexes hold installed capacity. Healthcare facilities are rotating up the share rankings.
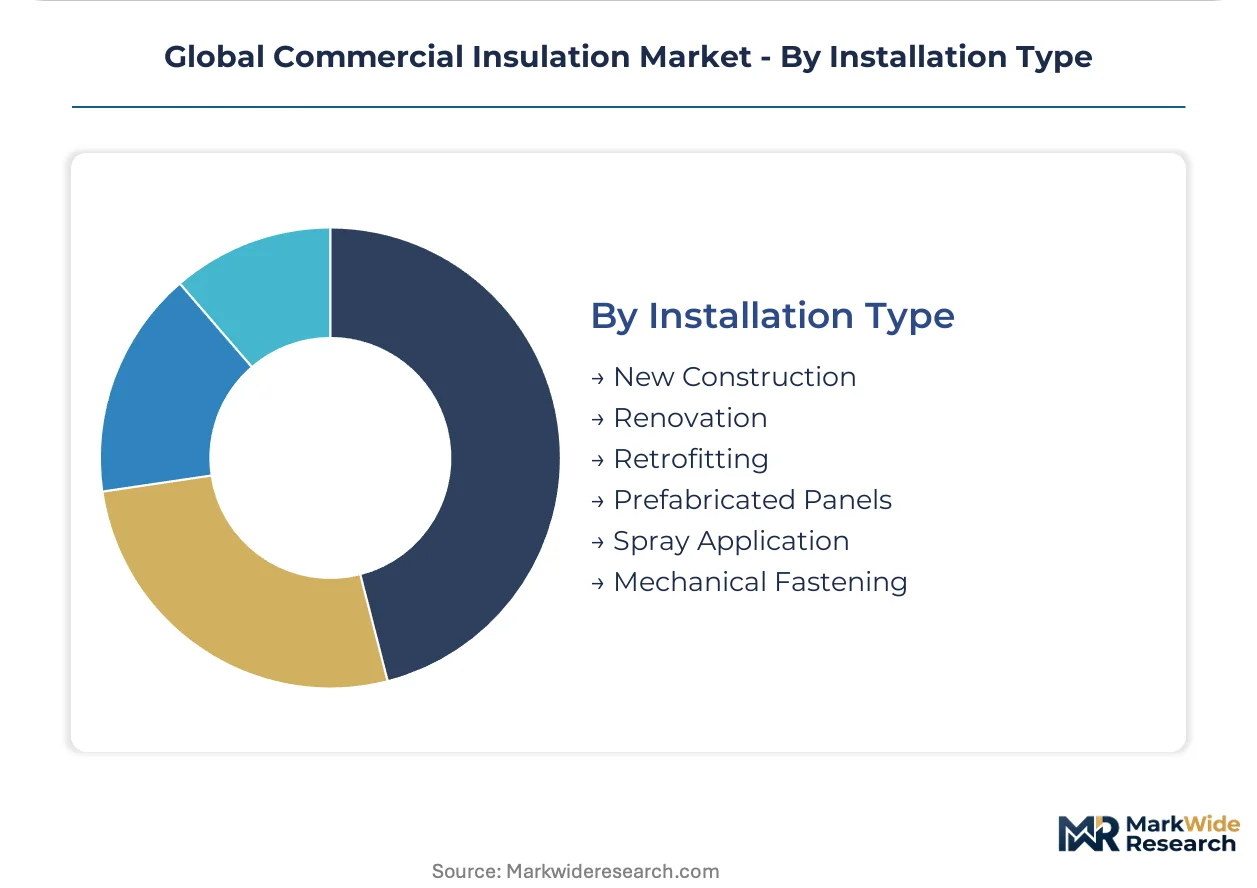
Installation Type:
Delivery method shapes margin structure, with prefabricated and spray systems capturing premium pricing over commodity batt installation.
- New Construction:Greenfield commercial projects allow integrated envelope design and bulk material procurement. Saint-Gobain anchors position through backward integration into raw mineral sourcing across multiple continents, securing cost advantage in batt and board production.
- Renovation:Occupied building upgrades demand dust control, phased scheduling, and minimal disruption protocols.
- Retrofitting:Deep energy retrofits in dense urban zones face skilled installer scarcity for spray foam and blown-in applications. Japan's METI building energy standard revisions are elevating baseline insulation performance and opening import channels for high-performance systems.
- Prefabricated Panels:Offsite manufacturing compresses construction schedules and concentrates specification power with integrated envelope contractors.
- Spray Application:Polyurethane and cellulose foam systems achieve air sealing and thermal resistance in irregular cavities.
- Mechanical Fastening:Insulation anchors and cladding attachment systems serve rainscreen and ventilated facade assemblies.
New construction holds installed capacity. Prefabricated panels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deep retrofit contractors and national distributors concentrate procurement power in Germany, the United States, Japan, the United Kingdom, and France. Hospital developers and data center operators in these markets specify fire-rated and high-R-value systems under tightening energy codes.
United States
Healthcare facility construction across Texas and California drives mineral wool demand for fire-rated curtain wall assemblies. EPA energy efficiency mandates and state-level stretch codes in New York and Massachusetts tighten baseline thermal transmittance values. Retrofit-intensive urban corridors in Chicago and Boston compress installation timelines toward higher R-value-per-inch polyurethane systems.
Germany
Commercial building renovation waves under the EU Green Deal accelerate deep retrofit activity in Berlin and Munich. REACH flame retardant restrictions force mineral wool producers toward phosphorus-based binder reformulations. Industrial clusters in the Rhine-Ruhr region concentrate specification authority with contractors delivering integrated envelope solutions.
Japan
METI building energy standard revisions elevate baseline insulation performance for commercial construction in Tokyo and Osaka. Data center developers in Yokohama specify aerogel-enhanced blanket systems where floor-to-ceiling height constraints limit conventional insulation depths. Import channels open for high-performance systems from European and North American producers.
United Kingdom
LEED and BREEAM certification requirements tilt procurement toward contractors with capital-light leasing models in London and Manchester. Government-backed efficiency programs pull mineral wool and polyurethane foam into hospital and clinic construction across the Midlands. Prefabricated panel systems gain share fastest in commercial retrofit channels.
France
EU Green Deal thermal performance mandates accelerate material substitution toward lower-carbon insulation systems in Paris and Lyon. High-rise commercial complexes specify fire-rated mineral wool assemblies under stricter energy codes than general commercial stock. National distributors lock in multi-year supply agreements with integrated envelope contractors.
Global Commercial Insulation Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three tiers. Consolidated fiberglass and mineral wool producers anchor volume leadership through backward integration into raw mineral sourcing. Mid-scale polyurethane foam specialists capture premium margins in retrofit applications. Emerging aerogel composite developers target space-constrained verticals with sub-inch thickness solutions. Dominant competitive moves include strategic partnerships with national distributors and capacity expansion in prefabricated panel systems.
Among scale-driven manufacturers, Owens Corning and Saint-Gobain exemplify channel-controlling archetypes with captive supply networks across multiple continents. Kingspan Group occupies a specialist position in prefabricated insulated panel systems that compress commercial construction schedules. These three entities represent distinct competitive vectors: fiberglass manufacturing scale, backward-integrated mineral sourcing, and integrated envelope delivery capability.
| Leading Market Players |
|---|
| ROCKWOOL International A/S |
| BASF SE |
| Owens Corning |
| GAF Materials Corporation |
| Johns Manville |
| Saint-Gobain |
| Knauf Insulation |
| Dow Inc. |
| Kingspan Group |
| Others |
Supply & Pricing Matrix
Rhine-Alpine freight corridors linking Rotterdam to Milan transmit petrochemical feedstock cost volatility directly into polyurethane foam pricing tiers, concentrating margin pressure on European converters while amplifying price differentiation between mineral-based batt producers and synthetic foam specialists serving space-constrained retrofit markets.
Pricing Analysis
Cost-plus contracts with polyol and isocyanate indexation dominate polyurethane foam procurement, tethering finished goods pricing to crude oil and natural gas benchmarks. Three-tier pricing structure across premium aerogel composites, standard mineral wool systems, and economy fiberglass batts separates specification authority by project complexity and certification grade. Cost compression in mid-tier mineral wool is intensifying because REACH-mandated binder reformulations are elevating R&D and recertification overhead. Healthcare facility developers exhibit the lowest price sensitivity due to fire-rating mandates, while commercial office developers in competitive leasing markets drive aggressive economy-tier negotiation.
Supply Chain Analysis
Export-control restrictions on advanced silica aerogel manufacturing equipment limit technology transfer to Asian production facilities, constraining capacity expansion for premium thermal barrier systems. Raw material sourcing draws from borosilicate glass fiber production concentrated in the United States and Germany, slag and stone wool feedstock anchored in Scandinavian and Chinese metallurgical operations, and petrochemical polyol supply tethered to Gulf Coast and Rotterdam refining complexes. Single-source vulnerability runs through European phosphorus-based flame retardant chemistry currently qualifying under REACH amendments. Distribution runs through national distributor networks that have captured specification authority via performance-guaranteed energy savings contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent insulation manufacturers face structural substitution pressure from building-integrated photovoltaic envelope systems that capture shared-specification value in net-zero commercial projects, requiring defensive repositioning around integrated thermal-solar offerings.
For Market Incumbents: Entrench specification authority by backward integration into raw mineral sourcing across multiple continents, securing cost advantage in batt and board production against volatile petrochemical feedstock competitors. Expand prefabricated panel capacity in Germany and the United Kingdom to compress installation timelines and lock out modular construction challengers. Counter aerogel substitution threats by hybridizing fiberglass with thin-film radiant barrier substrates for data center verticals.
For New Entrants and Emerging Players: Japan's underpenetrated deep retrofit corridor offers white-space access as METI code revisions elevate baseline performance requirements beyond domestic supply capability. Target healthcare facility fire-rated assemblies in North America where incumbent mineral wool producers face extended REACH-driven recertification timelines. Enter through capital-light leasing models tied to IRA-linked tax incentive monetization, bypassing traditional distributor gatekeepers.
For Investors and Strategic Acquirers: EU Green Deal thermal performance mandate implementation reshapes the acquisition landscape toward contractors with verified low-carbon material sourcing and integrated envelope delivery capability. Long-term viability centers on prefabrication scale and cross-border certification agility rather than commodity manufacturing footprint. Watch for divergence between EPA state-level stretch codes and EU harmonized standards as the inflection forcing portfolio geographic rebalancing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Mineral Sourcing | Saint-Gobain's captive supply networks across multiple continents secure cost advantage in batt production. |
| Prefabricated Panel Capacity Expansion | Kingspan Group's offsite manufacturing compresses commercial construction schedules and concentrates specification authority. |
| REACH-Compliant Binder Reformulation | European mineral wool producers face extended recertification timelines, elevating acquisition appeal of North American and Asian compliant formulations. |
| Performance-Guaranteed Energy Savings Contracts | National distributors and energy service companies displace architect specification authority in United States retrofit channels. |
| Aerogel-Enhanced Composite Development | Data center developers in Yokohama and Chicago specify sub-inch thickness systems where floor-to-ceiling constraints prohibit conventional insulation depths. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and industry association technical reports. Primary interviews engaged plant managers at mineral wool and fiberglass production facilities, procurement leads at national commercial distributors, energy service company contract originators, and technical R&D directors at polyurethane foam system houses. Secondary validation drew from EPA energy efficiency mandate documentation, ECHA REACH amendment registers, METI building energy standard revision notices, and SEC 10-K disclosures from publicly traded building materials manufacturers. Bottom-up capacity and demand modeling triangulated against top-down construction spend forecasts across the analysis window.
Forecast inputs considered material chemistry segmentation, building system placement, project delivery method, and regional regulatory cluster stringency. Modeled dimensions span mineral wool, fiberglass, polyurethane foam, and advanced aerogel composites by envelope, HVAC, and specialty fire protection applications across new construction and retrofit installation types. CAGRs derived from regression against historical construction permit data, energy code adoption curves, and green building certification penetration rates. Industry-specific inputs include REACH flame retardant restriction implementation timelines and IRA-linked tax incentive program uptake velocity.
Macroeconomic conditions sit as an overlay; deviation in commercial construction lending rates, petrochemical feedstock pricing, or cross-border trade policy would shift the trajectory. Forecasts reflect assumptions regarding regulatory harmonization pace, skilled installer labor availability, and green building certification market adoption. Material shifts in EU-EPA regulatory divergence or breakthrough aerogel manufacturing cost reduction would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
HVAC and Fire Protection Insulation Market
HVAC Systems
Reverse Flame Steam Boiler Market
HVAC Systems
Europe Boiler System Market
HVAC Systems
Thermostatic Faucet Market
HVAC Systems
Residential Hydronic Underfloor Heating Market
HVAC Systems
HVAC Control System Market
HVAC Systems
Hospital HVAC Systems Market
HVAC Systems
Global Building Thermal Insulation Market
HVAC Systems
Freeze and Thaw Systems Market
HVAC Systems
North America Scrubber System Market
HVAC Systems
Roof Vents Market
HVAC Systems
US Commercial HVAC Rooftop Units Market
HVAC Systems
Gas Wall Hung Boilers Market
HVAC Systems
North America Building Thermal Insulation Market
HVAC Systems
Split Air Conditioning Systems Market
HVAC Systems
Industrial Hood Ventilation Market