
 Concrete Resurfacer Market | 2026-2036
Concrete Resurfacer Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete Resurfacer Market Insights
A widening capital-intensity gap between integrated chemical conglomerates and regional flooring specialists is rotating competitive advantage toward backward-integrated resin producers. Sika AG leverages captive polymer supply chains to command specification-grade positioning in European infrastructure tenders. BASF SE anchors its resurfacer portfolio through R&D intensity in urethane-modified cement chemistry. RPM International Inc. competes through brand strength across retail contractor channels in North America.
Concrete resurfacer denotes a thin-applied repair material, typically 3–25 mm in thickness, composed of Portland cement blended with polymer modifiers, silica fume, or epoxy binders to restore structural integrity and surface finish to deteriorated concrete substrates. The material cures to compressive strengths exceeding 35 MPa while bonding chemically and mechanically to prepared existing concrete, serving primarily to extend service life of pavements, industrial floors, and building facades without full-depth replacement. Cementitious formulations dominate volume due to lower material cost and familiar application protocols among general contractors, while epoxy systems capture disproportionate margin pools in industrial settings demanding chemical resistance and rapid return-to-service. Polymer-based segments register the fastest expansion as specifiers prioritize crack-bridging flexibility and reduced permeability in freeze-thaw climates. Residential application growth lags commercial and infrastructure channels where lifecycle-cost analysis drives procurement decisions.
ASTM C1708 governs resurfacer bond strength testing in the United States, while EU Construction Products Regulation mandating CE marking under EN 1504-3 shapes product development priorities for structural repair mortars across member states. The US EPA regulates volatile organic compound content in epoxy-based systems through 40 CFR Part 59, pushing manufacturers toward waterborne polymer technologies. Stakeholders must monitor evolving federal infrastructure procurement standards and state-level Buy America provisions that increasingly determine qualification for public works resurfacer contracts.
Market Dynamics
Polymer-modified cementitious formulations are displacing conventional Portland-only overlays as infrastructure owners prioritize freeze-thaw durability and reduced permeability in cold-climate applications. This material transition concentrates competitive advantage among resin producers with captive polymer supply chains.
Growth Catalysts
- Infrastructure Investment and Jobs Act:US municipal bridge deck and roadway rehabilitation budgets are expanding, directing specification-grade demand toward low-shrinkage resurfacer systems.
- Polymer-modified chemistry:Enhanced crack-bridging flexibility and freeze-thaw resistance are accelerating adoption in German federal highway networks under Deutsche Bahn and Autobahn GmbH mandates.
- Lifecycle-cost procurement:Commercial and infrastructure channels are prioritizing total cost of ownership analysis over first-cost purchasing, favoring high-performance cementitious formulations.
Market Restraints
- Epoxy resin cost volatility:Petrochemical feedstock price swings compress margin pools in industrial chemical-resistant applications.
- Application skill concentration:Proper surface preparation and placement expertise clusters among specialized flooring contractors, limiting addressable contractor base.
- ASTM C1708 compliance burden:Bond strength testing protocols add qualification timeline friction for new market entrants seeking public works contracts.
Strategic Opportunities
- Waterborne polymer technologies:EPA 40 CFR Part 59 VOC restrictions are creating specification openings for low-emission formulations in US industrial settings.
- Facade restoration segment:Building envelope repair applications remain underpenetrated relative to horizontal infrastructure, offering volume expansion potential.
- EU Construction Products Regulation:CE marking requirements under EN 1504-3 are consolidating specification authority around certified structural repair mortar producers.
Industry Challenges
- Certification timeline compression:EN 1504-3 and ASTM C1708 parallel testing requirements extend product qualification cycles for multi-jurisdiction suppliers.
- Surface preparation labor scarcity:Shot blasting and scarification equipment operation skills are concentrating among aging contractor workforces in North America.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete Resurfacer Market |
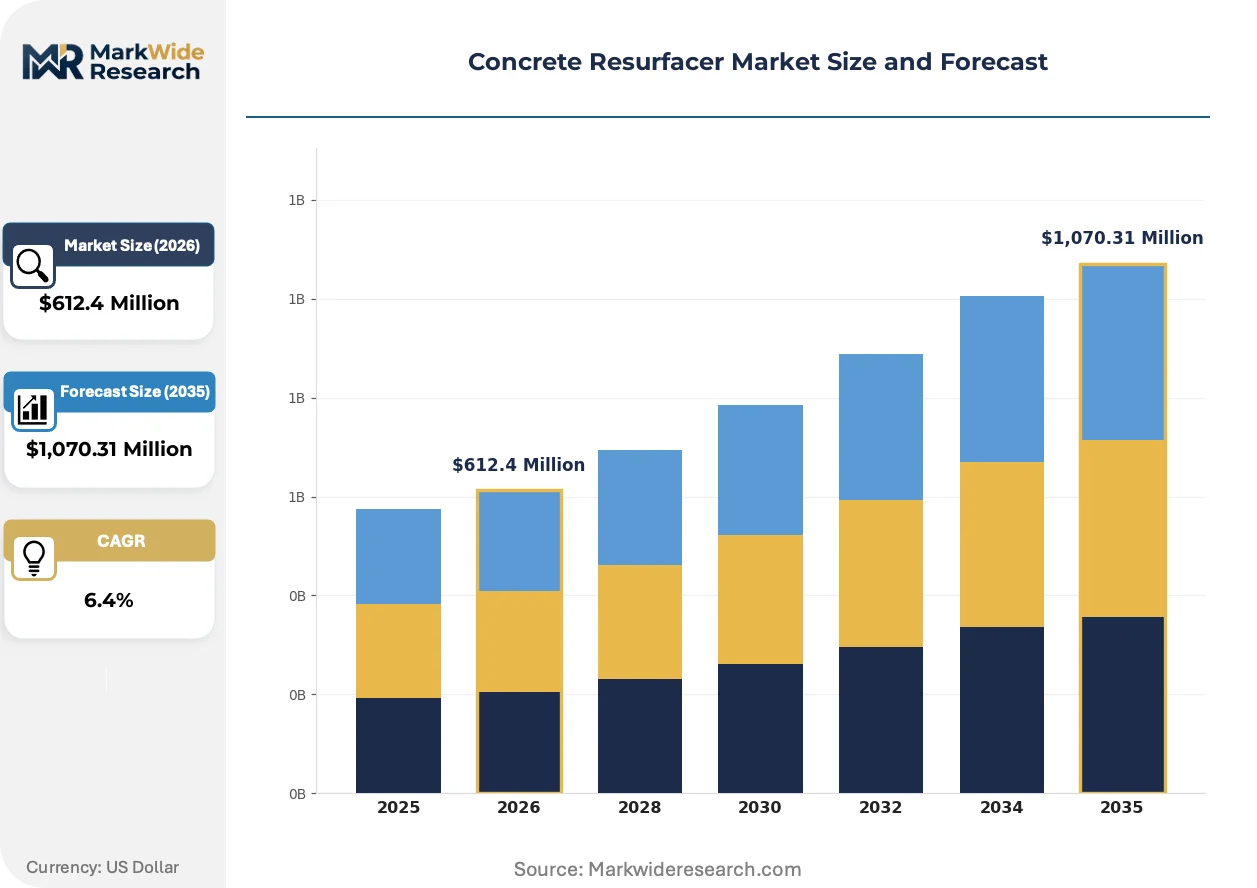
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,070.31 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer-based, Epoxy, Cementitious, Latex Application: Residential, Commercial, Industrial, Infrastructure End User: Contractors, Homeowners, Building Managers, Property Developers Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | Sika AG, BASF SE, The QUIKRETE Companies, RPM International Inc., Holcim Group, Elite Crete Systems, H.B. Fuller Company, Flowcrete Group Ltd., Saint-Gobain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete Resurfacer Market Trends and Innovations
Formulation chemistry, regulatory compliance architecture, and procurement methodology are undergoing simultaneous recalibration. These intersecting shifts are compressing traditional competitive advantages while opening specification pathways for technology-forward suppliers.
Hybrid urethane-modified cement chemistry is bifurcating the specification landscape between high-performance infrastructure tenders and commodity repair applications. German Autobahn GmbH and Deutsche Bahn are mandating these systems for structural concrete repairs. The technology is compressing market share for conventional Portland-only overlays in cold-climate jurisdictions.
REACH chemical registration requirements and EU Green Deal embodied-carbon disclosure mandates are reshaping raw material sourcing decisions for European producers. Manufacturers are reformulating with lower-carbon binders to maintain CE marking eligibility. Cold-climate infrastructure specifications are most affected, with German federal tenders now requiring Environmental Product Declarations.
Lifecycle-cost analysis is displacing first-cost procurement in municipal infrastructure departments. Engineering consultants are embedding total cost of ownership models into resurfacer selection criteria. This behavioral shift is most visible in US bridge deck rehabilitation programs under expanded federal funding allocations.
Concrete Resurfacer Market Segmentation
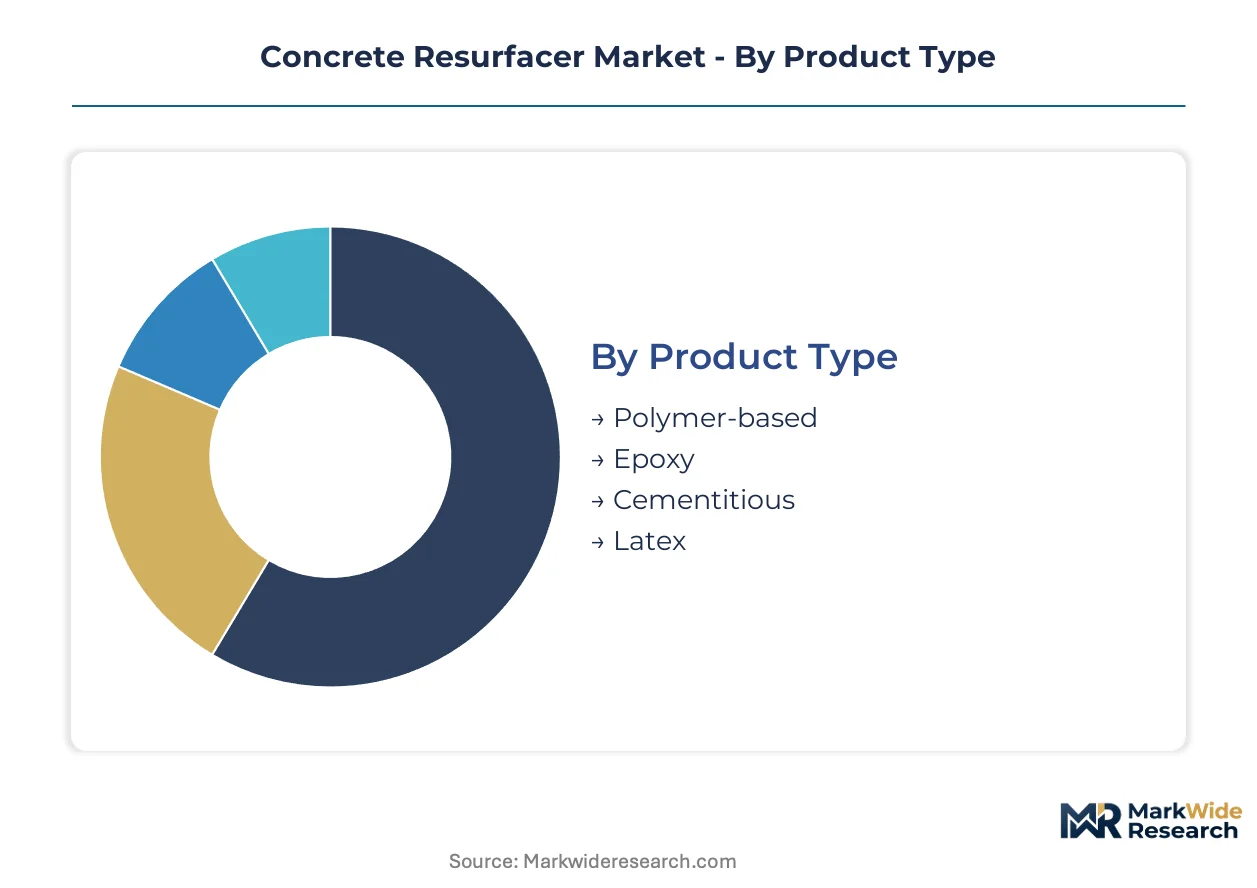
Segmentation in concrete resurfacer markets reveals how formulation chemistry, application setting, and procurement channel each concentrate margin pools differently. Specification-grade infrastructure tenders favor polymer-modified systems with certified performance data, while retail channels move volume through familiar cementitious brands.
Product Type:
Domestic production dominates cementitious formulations with localized raw material sourcing, while epoxy and polymer-based systems rely more heavily on imported resin feedstocks.
- Polymer-based:These formulations incorporate acrylic or vinyl acetate copolymers to enhance flexural strength and bond adhesion. German Autobahn GmbH and Deutsche Bahn specifications now mandate these systems for structural repairs, displacing conventional overlays in cold-climate tenders.
- Epoxy:Two-component thermosetting systems deliver chemical resistance and rapid return-to-service for industrial flooring. US EPA 40 CFR Part 59 VOC restrictions are compressing addressable markets while creating openings for waterborne alternatives.
- Cementitious:Portland cement blends with silica fume or fly ash dominate volume through lower material cost and familiar application protocols among general contractors.
- Latex:Styrene-butadiene rubber emulsions improve freeze-thaw durability in exterior horizontal applications.
Cementitious formulations command the established base. The steepest expansion runs through polymer-based systems.
Application:
Cost-tier stratification separates specification-grade infrastructure work from commodity residential projects, with lifecycle-cost procurement driving divergence.
- Infrastructure:Bridge decks, roadways, and transit facilities under US Infrastructure Investment and Jobs Act funding require ASTM C1708 bond strength certification and low-shrinkage performance. Municipal engineering consultants embed total cost of ownership models into selection criteria.
- Commercial:Retail, hospitality, and office building floors prioritize rapid cure times and aesthetic finish. Building envelope restoration remains underpenetrated relative to horizontal infrastructure.
- Industrial:Manufacturing floors and chemical processing areas demand chemical-resistant epoxy systems despite petrochemical feedstock price volatility.
- Residential:Driveway and patio applications lag commercial channels where first-cost purchasing dominates homeowner decision-making.
Infrastructure applications concentrate specification authority. Commercial flooring is climbing the fastest as building envelope repair gains traction.
End User:
Customer-type fragmentation separates skilled applicators from price-sensitive DIY purchasers, with capability scarcity clustering among specialized flooring contractors.
- Contractors:Specialized flooring applicators control specification influence through surface preparation expertise and equipment access. Shot blasting and scarification skills concentrate among aging workforces in North America.
- Building Managers:Facility maintenance departments prioritize lifecycle cost analysis for multi-tenant commercial properties.
- Property Developers:New construction and renovation projects specify resurfacer systems during design phase for podium decks and parking structures.
- Homeowners:Retail channel purchasers drive volume in DIY repair kits with limited technical performance requirements.
Professional contractors anchor the revenue base. Building managers are expanding most quickly as facility lifecycle planning matures.
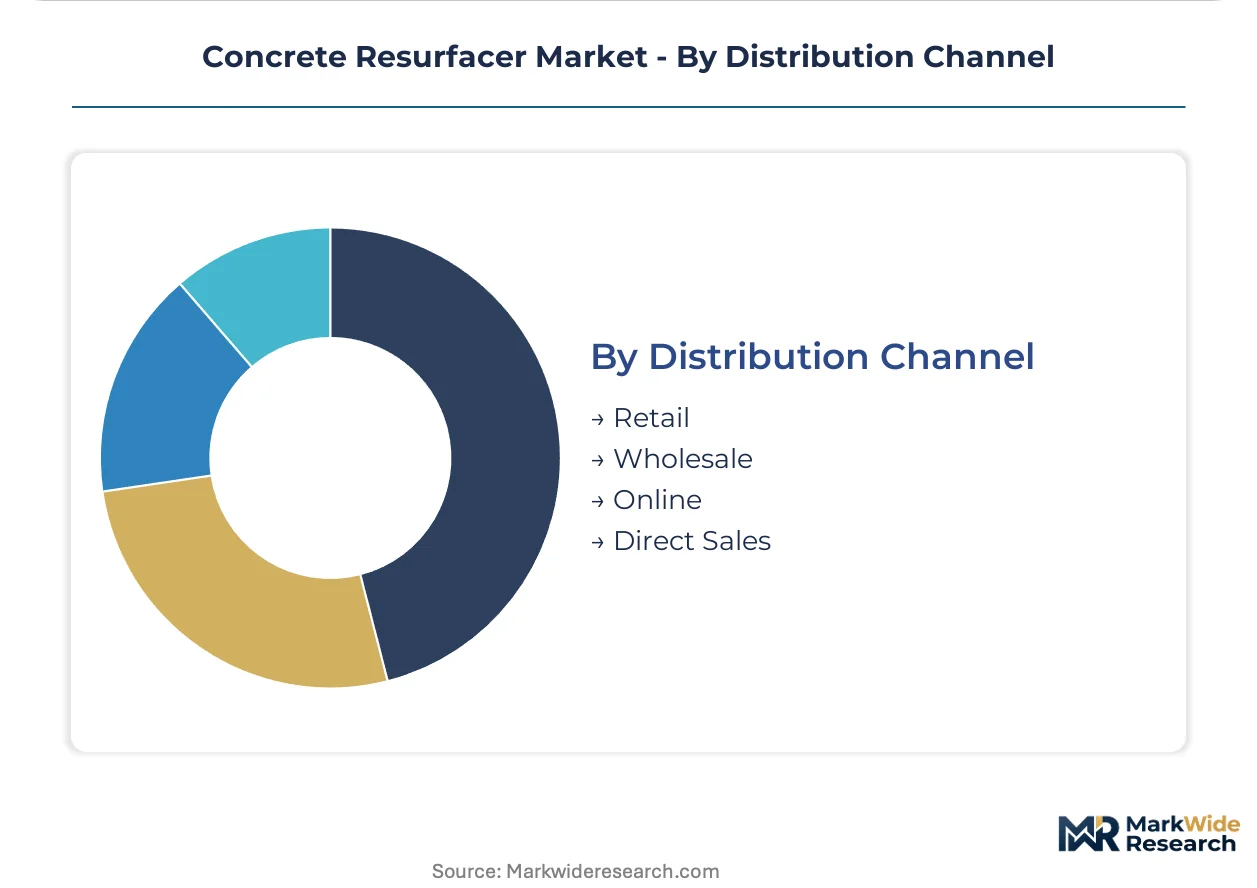
Distribution Channel:
Supply concentration varies by channel, with direct sales capturing specification-grade tenders while retail fragments across regional building material chains.
- Wholesale:Distributors serving commercial contractors stock certified products with batch consistency documentation. EN 1504-3 CE marking requirements consolidate specification authority around certified structural repair mortar producers.
- Direct Sales:Manufacturers bypass intermediaries for large infrastructure projects requiring technical support and custom formulation.
- Retail:Home improvement centers move bagged cementitious products with limited polymer modification for residential repair applications.
- Online:E-commerce channels serve small contractors and homeowners with standard formulations, though freight costs limit bulk material viability.
Wholesale distribution commands the established contractor base. Direct sales are gaining share fastest as infrastructure project scale increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German infrastructure tenders where Autobahn GmbH mandates low-shrinkage systems, while US municipal buyers under the Infrastructure Investment and Jobs Act face tighter budget constraints. This asymmetry reshapes competitive positioning across Atlantic markets.
United States
Municipal bridge deck rehabilitation drives specification-grade demand under expanded federal funding allocations. EPA 40 CFR Part 59 regulates VOC content in epoxy systems, pushing manufacturers toward waterborne alternatives. Chicago's transit authority and Texas DOT procurement clusters concentrate contractor expertise in cold-climate polymer-modified applications.
Germany
Deutsche Bahn and Autobahn GmbH specifications mandate polymer-modified cementitious systems for structural concrete repairs. EU Construction Products Regulation requires CE marking under EN 1504-3 for structural repair mortars. The Rhine-Ruhr industrial corridor anchors formulation R&D clusters serving federal highway network tenders.
China
High-speed rail concrete maintenance and urban metro expansion create volume demand for rapid-cure resurfacers. GB standards govern cementitious repair material performance in infrastructure applications. The Yangtze River Delta manufacturing belt concentrates domestic producers serving state-owned railway contractors.
Canada
Provincial transportation departments prioritize freeze-thaw resistant formulations for roadway rehabilitation budgets. Health Canada oversees chemical safety in construction material imports. Ontario's Golden Horseshoe and British Columbia's Lower Mainland concentrate specification influence among engineering consultants.
Australia
Coastal infrastructure corrosion protection drives demand for low-permeability resurfacer systems in bridge and wharf applications. The TGA regulates chemical components in imported polymer systems. Sydney and Melbourne metropolitan procurement clusters favor lifecycle-cost analysis over first-cost purchasing.
Concrete Resurfacer Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the concrete resurfacer market. Integrated chemical conglomerates with captive polymer supply chains command premium positioning in European infrastructure tenders, while regional flooring specialists compete on application speed and contractor channel relationships. Three archetypes dominate: backward-integrated resin producers, brand-driven retail distributors, and specialized flooring system integrators. Competitive moves concentrate on formulation R&D partnerships and specification-grade certification acquisition.
Among Swiss and German chemical conglomerates, Sika AG and BASF SE occupy positions exemplifying polymer supply chain integration. RPM International Inc. anchors the North American contractor channel tier. These three represent distinct competitive vectors: captive raw material control, urethane-modified cement chemistry R&D intensity, and retail brand strength across flooring applicator networks.
| Leading Market Players |
|---|
| Sika AG |
| BASF SE |
| The QUIKRETE Companies |
| RPM International Inc. |
| Holcim Group |
| Elite Crete Systems |
| H.B. Fuller Company |
| Flowcrete Group Ltd. |
| Saint-Gobain |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements with municipal infrastructure departments lock in polymer-modified cementitious supply access while anchoring price visibility across freeze-thaw climate jurisdictions. These contracts insulate backward-integrated producers from epoxy resin feedstock volatility while compressing margin pools for spot-market dependent competitors.
Pricing Analysis
Configured-to-order pricing for specification-grade infrastructure tenders commands substantial premiums over standard bagged cementitious products sold through retail channels. Three-tier pricing structure across premium, standard, and economy levels separates ASTM C1708-certified structural repair mortars from commercial flooring formulations and DIY residential kits. Pricing pressure stems from petrochemical feedstock swings in epoxy systems, with municipal buyers under Infrastructure Investment and Jobs Act funding showing lowest price sensitivity due to lifecycle-cost procurement mandates.
Supply Chain Analysis
Just-in-time inventory strategies dominate contractor-channel distribution, while strategic stockpiling of polymer latex emulsions concentrates among German and Swiss integrated producers preparing for EN 1504-3 certification surges. Supply concentrates in Germany, the United States, and China, with raw material dependencies on Portland cement clinker, acrylic and vinyl acetate copolymers, and epoxy resin feedstocks. Single-source vulnerability in specialty polymer modifiers creates chokepoint exposure, particularly for CE marking compliance. Distribution runs through wholesale distributors serving certified commercial contractors, with direct sales capturing large-scale infrastructure tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in building envelope restoration and waterborne polymer segments, as lifecycle-cost procurement creates specification niches beyond incumbent infrastructure dominance.
For Market Incumbents: Shield specification-grade positioning through captive polymer supply chain expansion and accelerated EN 1504-3 certification acquisition. Threats from regional flooring specialists with faster application protocols compress margins in commercial channels. Backward integration into acrylic emulsion production anchors cost structures against resin price volatility. For New Entrants and Emerging Players: CE marking fast-track programs under EU Construction Products Regulation open specification pathways for structural repair mortar producers lacking legacy infrastructure relationships. White-space targets include Australian coastal corrosion protection and Canadian provincial freeze-thaw roadway programs. Go-to-market leverage rests on waterborne polymer formulations addressing EPA 40 CFR Part 59 VOC restrictions. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with polymer formulation R&D capabilities and existing ASTM C1708 test data libraries. Long-term viability over the projection horizon favors producers with demonstrated specification authority in German federal highway tenders. Signal to monitor: EN 1504-3 certification timeline compression as consolidation catalyst.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Emulsions | Sika AG and BASF SE leverage captive supply chains to command German infrastructure specification tiers. |
| Waterborne Formulation Development | EPA 40 CFR Part 59 compliance creates procurement openings in US industrial chemical-resistant applications. |
| EN 1504-3 Certification Acquisition | CE marking mandates consolidate specification authority around certified structural repair mortar producers. |
| Building Envelope Segment Expansion | Facade restoration remains underpenetrated relative to horizontal infrastructure, offering volume expansion. |
| Direct Sales Infrastructure Buildout | Infrastructure Investment and Jobs Act project scale increases favor manufacturer-technical support relationships. |
Research Methodology
Operator-level perspectives from municipal infrastructure procurement officers, specialized flooring contractors, polymer formulation chemists, and commercial building facility managers anchored the qualitative base. Primary interview data combined with secondary validation from EPA 40 CFR Part 59 regulatory filings, EN 1504-3 certification databases, US DOT bridge rehabilitation program disclosures, and Deutsche Bahn technical specifications. Bottom-up volume triangulation across product type, application setting, and distribution channel converged with top-down macroeconomic anchoring.
Sensitivity analysis tested forecast robustness against polymer feedstock price volatility, infrastructure funding allocation shifts, and certification timeline compression scenarios. Segmentation dimensions modeled include formulation chemistry grade, application environment, procurement channel structure, and regional regulatory cluster. CAGRs derived from regression analysis of historical specification-grade adoption rates, overlaid with Infrastructure Investment and Jobs Act disbursement schedules and EU Green Deal embodied-carbon disclosure trajectories.
Underlying assumptions cover sustained federal infrastructure funding authorization, stable REACH chemical registration requirements, and gradual waterborne polymer technology maturation, with deviation risk concentrated in epoxy resin cost spikes and surface preparation labor scarcity. Revision becomes warranted when EN 1504-3 certification backlogs exceed eighteen months or Infrastructure Investment and Jobs Act appropriations face congressional rescission.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Cement Roofing Sheets Market
Building & Construction Materials
Russia Cross Laminated Timber Market
Building & Construction Materials
Structural Insulated Panels (Sips) Market
Building & Construction Materials
Gutter and Downspout Market
Building & Construction Materials
Egypt Prefab Wood Buildings Market
Building & Construction Materials
Precast Concrete Members Market
Building & Construction Materials
Asphalt Shingles Market
Building & Construction Materials
GCC Ceramic Tiles Market
Building & Construction Materials
Moisture Resistant Plaster Boards Market
Building & Construction Materials
Gypsum Concrete Market
Building & Construction Materials
Global Shotcrete/Sprayed Concrete Market
Building & Construction Materials
US Glass Curtain Wall Market
Building & Construction Materials
Cement Sacks Market
Building & Construction Materials
India Manufacturing Market
Building & Construction Materials
Rubber Expansion Joints Market
Building & Construction Materials
Europe Building Materials Market