
 Breast Cancer Core Needle Biopsy Market | 2026-2036
Breast Cancer Core Needle Biopsy Market Size, Share, and Industry Trends Forecast 2026-2036
Breast Cancer Core Needle Biopsy Market Intelligence
A shortage of breast imaging specialists is unwinding procedural capacity across outpatient networks. Hologic, Inc. leverages integrated specimen radiography systems to sustain workflow efficiency in high-volume screening programs. Becton, Dickinson and Company anchors its position through disposable needle portfolios that dominate hospital supply chains. Cook Medical competes on ergonomic device designs that reduce operator fatigue during ultrasound-guided procedures.
Breast cancer core needle biopsy refers to percutaneous extraction of tissue specimens using hollow needles typically 14- to 9-gauge in diameter, often with vacuum assistance to retrieve contiguous core samples for histopathological analysis. The technique replaces open surgical biopsy for initial diagnosis of palpable and non-palpable lesions identified through mammography or other imaging modalities. Vacuum-assisted device types command premium positioning due to larger tissue yields and reduced sampling error rates that pathologists prefer for receptor profiling. Ultrasound-guided procedure types lead in procedural volume because of real-time visualization, portability, and lower capital requirements compared to stereotactic suites. Tissue markers within device types represent a recurring revenue stream as clip deployment follows most vacuum-assisted biopsies to guide subsequent localization.
FDA 510(k) clearance pathways govern device commercialization in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for Class IIa and IIb biopsy systems. The FDA's quality system regulation and ISO 13485 standards shape manufacturing protocols that vendors must maintain for market access. Stakeholders should monitor reimbursement coding revisions for image-guided biopsy procedures and evolving pathology laboratory consolidation patterns that influence device procurement centralization.
Market Dynamics
The transition from surgical excisional biopsy to percutaneous core needle sampling is compressing hospital inpatient capacity requirements while expanding outpatient procedural throughput across cancer networks.
Growth Catalysts
- FDA 510(k) pathway efficiency:Streamlined premarket notification for Class II biopsy devices accelerates commercialization timelines for vacuum-assisted systems in the United States.
- Receptor profiling demand:Pathology laboratories require larger contiguous tissue specimens for immunohistochemical analysis, driving uptake of 9-gauge vacuum-assisted devices.
- Ultrasound suite proliferation:Portable imaging systems enable community breast centers to perform real-time guided biopsies without stereotactic infrastructure investment.
Market Restraints
- Stainless steel needle supply concentration:Specialty hypotube manufacturing clusters in Germany and Switzerland create single-source vulnerability for 14-gauge disposable components.
- EU MDR clinical evidence burden:Class IIa biopsy systems now require post-market surveillance data and notified body re-certification, extending approval cycles by 12-18 months.
- Magnetic resonance substitute procedures:MRI-guided vacuum biopsy platforms capture complex lesion cases that stereotactic systems previously dominated, fragmenting device procurement.
Strategic Opportunities
- India community screening expansion:National breast cancer control program targets 70 million women by 2030, creating demand for low-cost handheld biopsy devices in tier-2 cities.
- Artificial intelligence imaging convergence:Deep learning algorithms for lesion detection integrate with ultrasound guidance, reducing operator dependence and training barriers.
- Same-day diagnosis protocols:Rapid on-site evaluation partnerships between radiology and pathology enable immediate result delivery, commanding premium reimbursement in integrated delivery networks.
Industry Challenges
- Interventional radiologist training pipeline:Fellowship programs produce insufficient breast imaging specialists to match procedural volume expansion in outpatient networks.
- Legacy PACS integration complexity:Vacuum-assisted biopsy systems require DICOM connectivity upgrades that strain capital budgets at independent imaging centers.
- Specimen radiography workflow bottlenecks:Pathology laboratories face capacity constraints processing core samples for immediate adequacy assessment during procedures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breast Cancer Core Needle Biopsy Market |
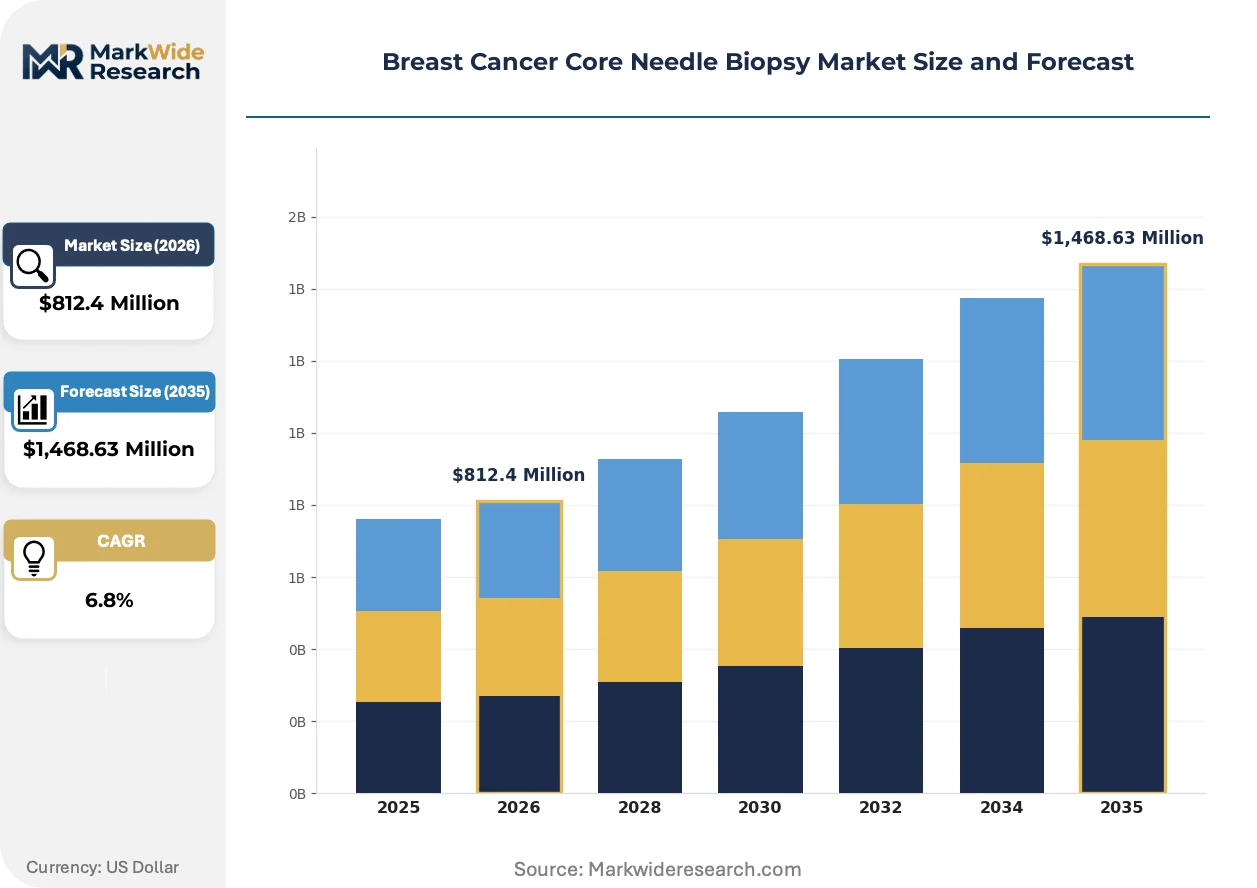
| Market Size in 2026 | $812.4 Million |
| Market Size in 2035 | $1,468.63 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Ultrasound-Guided, Stereotactic, MRI-Guided, Vacuum-Assisted Device Type: Biopsy Needles, Vacuum-Assisted Devices, Guidance Systems, Tissue Markers End User: Hospitals, Diagnostic Laboratories, Specialty Clinics, Cancer Treatment Centers Application: Diagnostic, Therapeutic, Research, Monitoring |
| Companies Covered | Hologic, Inc., Becton, Dickinson and Company, Argon Medical Devices, Cook Medical, Stryker Corporation, Intact Medical Corporation, Ethicon Surgical Technologies, Leica Biosystems Nussloch GmbH, Devicor Medical Products, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breast Cancer Core Needle Biopsy Market Strategic Shifts & Innovations
Device miniaturization and automated tissue handling are reconfiguring procedural economics while regulatory harmonization efforts reshape competitive entry barriers across major jurisdictions.
Single-insertion multi-sample biopsy needles are decomposing the traditional trade-off between specimen adequacy and procedural time. Ambulatory surgery centers adopt these systems to maximize throughput within fixed reimbursement windows. The technology is decomposing capital equipment requirements for smaller facilities previously excluded from vacuum-assisted biopsy service lines.
EU Medical Device Regulation post-market surveillance mandates now require systematic clinical follow-up data for Class IIb biopsy systems. Manufacturers must establish quality management systems exceeding ISO 13485 baselines and maintain vigilance reporting through EUDAMED. European imaging networks are consolidating procurement to amortize compliance costs across higher device volumes.
Pathology laboratory consolidation is compressing device vendor access to purchasing committees. National reference laboratories now centralize biopsy instrument standardization across regional hospital systems, displacing individual facility autonomy. This concentration is most visible in the United States, where Quest Diagnostics and LabCorp networks influence needle gauge preferences through specimen handling protocols.
Breast Cancer Core Needle Biopsy Market Segmentation
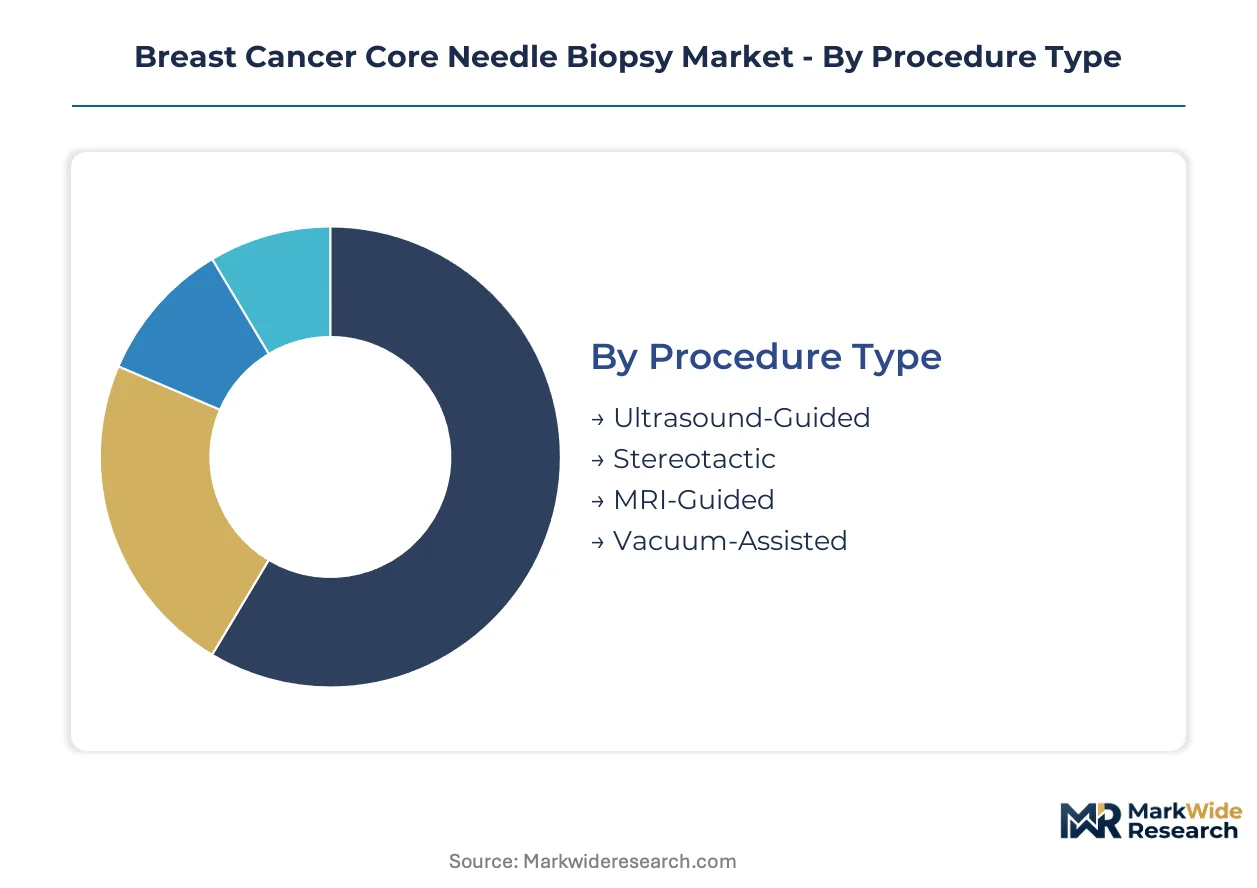
Device selection in breast biopsy hinges on lesion characteristics, imaging modality availability, and pathology laboratory requirements. Segmentation reveals how regulatory pathways and reimbursement structures allocate revenue across procedure types and device categories.
Procedure Type:
FDA 510(k) clearance timelines vary substantially across guidance modalities, with ultrasound systems clearing faster than stereotactic suites requiring additional mechanical safety validation.
- Ultrasound-Guided:Real-time visualization enables portable deployment in community breast centers without capital-intensive stereotactic infrastructure. Community health networks in the United States favor this modality for same-day diagnosis protocols that maximize outpatient throughput.
- Stereotactic:Fixed-coordinate mammography guidance targets calcifications and architectural distortions invisible to ultrasound. Academic medical centers retain these systems for complex lesion cases, though MRI-guided platforms are capturing share in this segment.
- MRI-Guided:Targets lesions detected only on contrast-enhanced magnetic resonance imaging.
- Vacuum-Assisted:Retrieves contiguous multi-core specimens through single needle insertion.
Established volume favors Ultrasound-Guided; emerging adoption favors MRI-Guided.
Device Type:
Cost tiers separate disposable consumables from capital equipment, with recurring revenue streams concentrating in single-use components.
- Biopsy Needles:14-gauge to 9-gauge hollow needles manufactured from specialty stainless steel hypotubes. Hypotube supply concentration in Germany and Switzerland creates procurement vulnerability for disposable needle vendors serving hospital supply chains.
- Vacuum-Assisted Devices:Integrated suction systems retrieve larger contiguous specimens for immunohistochemical receptor profiling. Pathology laboratory consolidation in the United States drives standardization toward 9-gauge systems that reduce sampling error rates.
- Guidance Systems:Stereotactic and MRI-compatible biopsy platforms requiring DICOM PACS integration.
- Tissue Markers:Metallic clips deployed post-biopsy for subsequent surgical localization.
Disposable revenue concentrates in Biopsy Needles; capital investment flows toward Vacuum-Assisted Devices.
End User:
Customer type determines procurement centralization, with national laboratory networks displacing individual facility autonomy.
- Hospitals:Integrated delivery networks consolidate device standardization across radiology and pathology departments. Quest Diagnostics and LabCorp specimen handling protocols influence needle gauge preferences through centralized purchasing committees.
- Diagnostic Laboratories:Reference laboratories process core samples for immediate adequacy assessment. Capacity constraints in these facilities create workflow bottlenecks that vacuum-assisted systems address through larger initial yields.
- Specialty Clinics:Breast imaging centers operate ultrasound-guided biopsy suites.
- Cancer Treatment Centers:Comprehensive oncology networks coordinate biopsy-to-treatment pathways.
Procurement scale favors Hospitals; procedure growth favors Cancer Treatment Centers.
Application:
Maturity gradients separate established diagnostic workflows from emerging therapeutic applications.
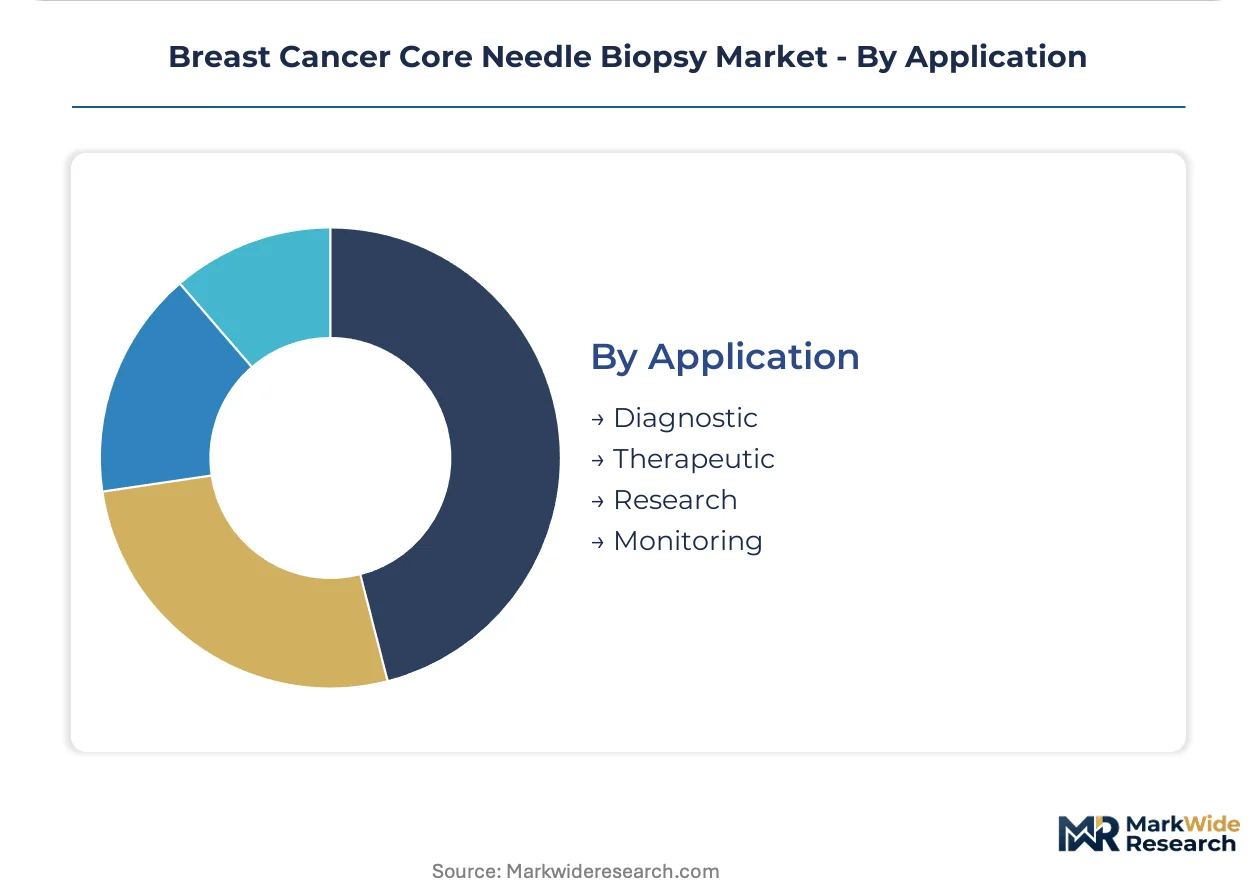
- Diagnostic:Initial histopathological confirmation of malignant or benign lesions. Receptor profiling requirements for hormone and HER2 status drive demand toward larger vacuum-assisted specimens that support comprehensive immunohistochemical analysis.
- Therapeutic:Excisional equivalent for complete removal of small benign lesions. Ambulatory surgery centers adopt single-insertion multi-sample needles to maximize reimbursement window throughput.
- Research:Tissue banking for biomarker discovery and clinical trial enrollment.
- Monitoring:Serial biopsy for neoadjuvant therapy response assessment.
Volume concentration remains in Diagnostic; steepest expansion trajectory appears in Therapeutic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) pathways anchor procedural volume expansion in the United States, while EU MDR compliance cycles reshape device procurement across European imaging networks. National screening programs and reimbursement clarity determine adoption velocity in each jurisdiction.
United States
Community breast centers convert surgical suites to percutaneous biopsy capacity under Medicare reimbursement clarity for image-guided procedures. FDA quality system regulation mandates ISO 13485 manufacturing protocols that vendors maintain for market access. The Dallas-Fort Worth metroplex concentrates ambulatory surgery center networks deploying same-day diagnosis protocols.
Germany
Specialty hypotube manufacturing clusters supply stainless steel components for 14-gauge disposable needles serving hospital supply chains. EU Medical Device Regulation post-market surveillance requirements extend approval cycles for Class IIa biopsy systems. Stuttgart-based precision engineering firms dominate hypotube production for European device vendors.
India
The national breast cancer control program targets 70 million women by 2030, creating demand for low-cost handheld biopsy devices in tier-2 cities. CDSCO medical device registration requirements govern commercialization timelines for imported vacuum-assisted systems. Maharashtra's Mumbai-Pune corridor anchors diagnostic laboratory consolidation influencing device standardization.
Japan
PMDA premarket approval pathways emphasize clinical evidence standards for vacuum-assisted devices entering reimbursement listings. METI industrial policy supports domestic manufacturing of imaging-compatible biopsy platforms. The Osaka-Kobe industrial zone concentrates precision medical device production for Asia-Pacific distribution.
United Kingdom
NHS breast screening program procurement centralizes device standardization across regional radiology networks. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards while streamlining UK-specific approvals. London's academic medical centers coordinate pathology laboratory networks processing core samples for receptor profiling.
Breast Cancer Core Needle Biopsy Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the biopsy device ecosystem. The vendor base concentrates around integrated imaging system vendors, disposable needle specialists, and ergonomic device designers competing on distinct value vectors. Three archetypes dominate: capital equipment integrators bundling specimen radiography, supply chain anchors controlling disposable volumes, and ergonomic innovators reducing operator fatigue. M&A activity targets pathology workflow integration, while strategic partnerships secure hypotube supply continuity.
Among US-based integrated system vendors, Hologic, Inc. and Stryker Corporation occupy positions exemplifying the capital equipment archetype, anchoring high-volume screening program workflows through bundled imaging and specimen handling platforms. Becton, Dickinson and Company represents the disposable supply chain anchor, with hospital supply chain penetration sustaining recurring revenue concentration. These three firms illustrate how technology integration, manufacturing scale, and distribution density constitute distinct competitive moats.
| Leading Market Players |
|---|
| Hologic, Inc. |
| Becton, Dickinson and Company |
| Argon Medical Devices |
| Cook Medical |
| Stryker Corporation |
| Intact Medical Corporation |
| Ethicon Surgical Technologies |
| Leica Biosystems Nussloch GmbH |
| Devicor Medical Products, Inc. |
| Others |
Cost & Logistics Intelligence
Scale economies in stainless steel hypotube production anchor price floors for disposable biopsy needles, concentrating manufacturing capacity in German and Swiss precision engineering clusters while compressing margins for secondary device vendors. This supply concentration enables tier-1 manufacturers to command premium positioning for vacuum-assisted systems, whereas community breast centers in price-sensitive markets face procurement trade-offs between specimen quality and per-procedure cost.
Pricing Analysis
Geographic price spreads of 40-60% separate US hospital procurement from tier-2 city deployments in India, where CDSCO registration costs and import duties amplify landed costs. Three-tier pricing structure across premium vacuum-assisted platforms, standard spring-loaded core systems, and economy manual needles reflects FDA 510(k) certification investment and after-sales service bundling. Pricing pressure stems from pathology laboratory consolidation in the United States, where Quest Diagnostics and LabCorp networks standardize toward 9-gauge systems that reduce sampling error rates. Ambulatory surgery centers exhibit highest price sensitivity, while academic medical centers prioritize receptor profiling accuracy over per-unit cost.
Supply Chain Analysis
Inventory lead times of 16-24 weeks for specialty hypotubes strain just-in-time procurement at disposable needle vendors serving hospital supply chains. Manufacturing concentrates in Germany, Switzerland, and Japan, where precision engineering clusters feed stainless steel components to device assemblers in the United States and Europe. Raw material dependencies include medical-grade stainless steel, polymer housing materials, and vacuum pump subassemblies sourced from industrial automation suppliers. Single-source vulnerability in Stuttgart-based hypotube production creates exposure to EU MDR compliance disruptions. Distribution runs through GPO contracts and national laboratory networks that centralize standardization decisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists across community screening networks and AI-guided procedural workflows, as specialist shortages and imaging infrastructure gaps create service-layer niches that integrated incumbents under-serve.
For Market Incumbents: Compound defensive positioning through backward integration into hypotube manufacturing and pathology workflow software partnerships that lock in specimen handling protocols. Vacuum-assisted device vendors face substitution threat from MRI-guided platforms capturing complex lesion cases; priority lever rests on CE marking pathway acceleration under EU MDR to sustain European market access. Capacity addition in Maharashtra's Mumbai-Pune corridor addresses India's national screening program procurement at cost-advantaged scale. For New Entrants and Emerging Players: AI imaging convergence gaps in ultrasound-guided biopsy training create white-space for algorithm-integrated handheld devices that reduce operator dependence. Tier-2 Indian cities and Southeast Asian community health networks represent most penetrable geographies, where low-cost disposable needles displace surgical excisional biopsy. Go-to-market angle emphasizes same-day diagnosis protocol partnerships with radiology-pathology networks commanding premium reimbursement. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among disposable needle specialists with GPO contract density and tissue marker clip deployment attach rates. Long-term viability over the projection horizon favors vendors with pathology laboratory integration software and DICOM PACS connectivity platforms. Acquisition target archetype: mid-cap ergonomic device designers with FDA 510(k) clearance backlogs and ultrasound guidance specialization. Signal to watch: CDSCO registration acceleration for imported vacuum-assisted systems entering India's national screening program procurement.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined premarket notification compresses commercialization timelines for vacuum-assisted biopsy systems in US cancer networks. |
| CE Marking Pathway Investment | EU MDR compliance for Class IIa devices extends approval cycles but secures access to consolidated European imaging procurement. |
| Hospital System Partnership | Integrated delivery network contracts standardize needle gauge preferences across radiology and pathology departments. |
| Software Companion Development | AI lesion detection algorithms integrated with ultrasound guidance reduce training barriers and operator fatigue. |
| Reimbursement Strategy | CPT coding alignment for image-guided biopsy procedures maximizes outpatient throughput in Medicare-covered networks. |
Research Approach
Desk research of FDA 510(k) clearance databases, EU MDR notified body certifications, and hospital procurement contract filings preceded structured interviews with interventional radiologists, biomedical engineers, GPO contracts managers, and pathology laboratory directors. Secondary validation drew from CMS Medicare reimbursement data, CDSCO medical device registration records, and ISO 13485 quality system audit reports. Bottom-up procedure volume modeling across ultrasound-guided, stereotactic, and MRI-guided modalities triangulated with top-down device revenue estimates from disposable needle and vacuum-assisted system manufacturers.
Variance decomposition across procedure type, device category, end-user concentration, and geographic regulatory cluster shaped analytical framework outputs over the projection horizon. Segmentation dimensions modeled include guidance modality, needle gauge specification, vacuum assistance level, and hospital versus ambulatory surgery center deployment. CAGRs were derived from installed base expansion rates and replacement cycle dynamics, with immunohistochemical receptor profiling demand and AI imaging convergence serving as primary volume drivers.
Forecasts assume regulatory continuity in FDA 510(k) pathways, EU MDR post-market surveillance requirements, and CDSCO import registration frameworks; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pelvic Muscle Probes Market
Medical Devices
Europe Wearable Medical Devices Market
Medical Devices
Capsule Endoscope and Workstations Market
Medical Devices
North America Refractive Surgery Devices Market
Medical Devices
Global Cranial and Facial Implants Market
Medical Devices
Medical Device Films Market
Medical Devices
Electric Heated Eye Mask Market
Medical Devices
Global Cranial Fixation and Stabilization Systems Market
Medical Devices
Electroencephalography Devices Market
Medical Devices
Global Trauma Fixation Devices Market
Medical Devices
Gum Grafting Market
Medical Devices
Gastric Bands Market
Medical Devices
Smart Medical Loupes Market
Medical Devices
IV Therapy and Vein Access Devices Market
Medical Devices
3D Printed Hip and Knee Implants Market
Medical Devices
High Volume Dispensing Systems Market