
 Global Cranial Fixation and Stabilization Systems Market | 2026-2036
Global Cranial Fixation and Stabilization Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cranial Fixation and Stabilization Systems Market Foresight
Neurosurgical specialist shortages across OECD health systems is redrawing competitive boundaries for implant manufacturers. Medtronic leverages its navigation-integrated hardware portfolio to sustain premium positioning in computer-assisted cranial procedures. Stryker Corporation anchors North American trauma repair channels through dense hospital GPO relationships. Johnson & Johnson competes on manufacturing scale across its DePuy Synthes and Ethicon franchises.
Cranial fixation and stabilization systems encompass titanium and resorbable plates, cranial mesh constructs, miniplates, and screws designed to restore structural integrity after craniotomy, trauma, or tumor resection, with titanium alloys specified for strength-to-weight ratios exceeding 100 ksi yield strength and resorbable polymers formulated for 12-24 month degradation profiles matching bone remodeling timelines. Cranial mesh and patient-specific 3D printed implants command margin premiums due to geometric complexity and OR time savings, while screw and miniplate volumes dominate unit economics across trauma and cranioplasty applications. Navigation systems and stereotactic guidance technology segments are expanding fastest as hospitals bundle hardware with software-enabled surgical planning workflows.
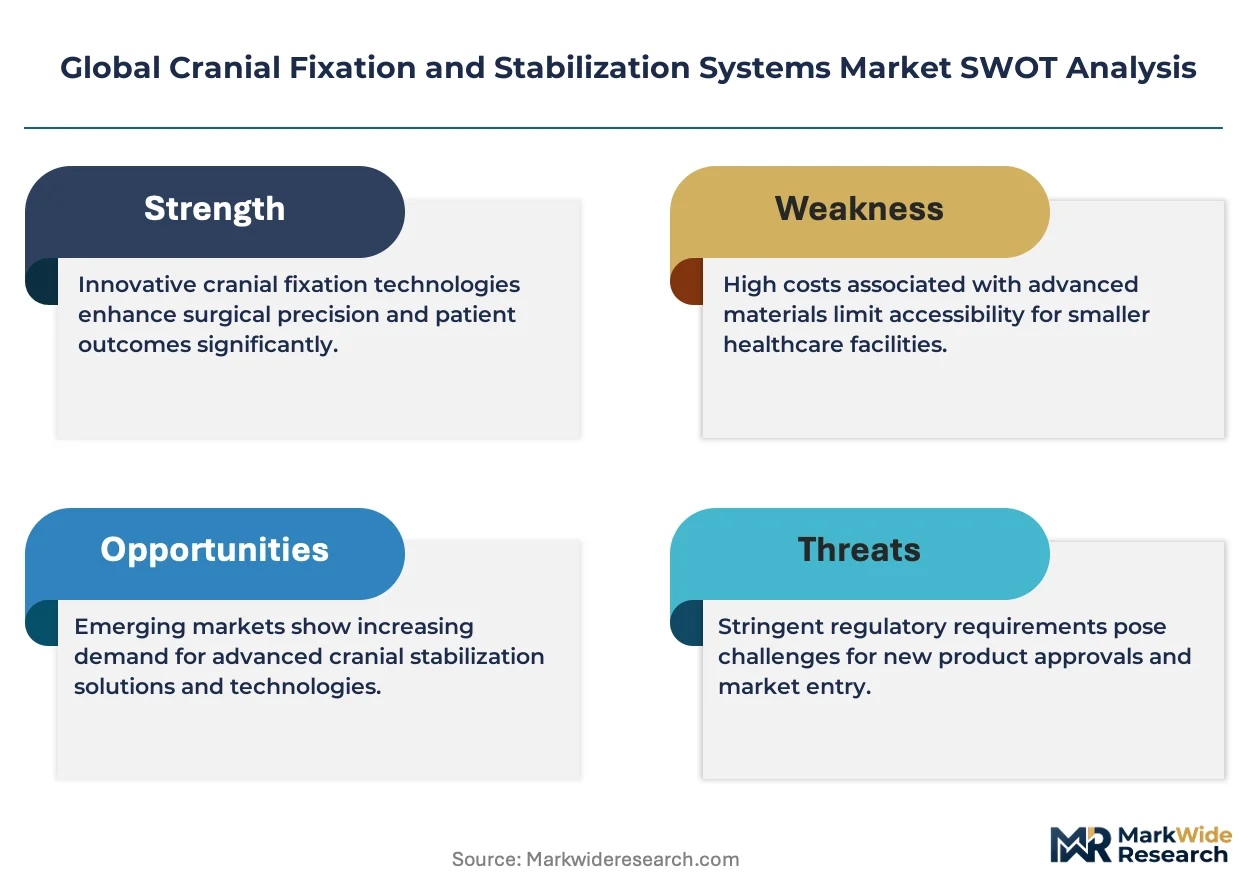
FDA 510(k) premarket notification requirements, EU MDR technical documentation mandates, and ISO 13485 quality management standards collectively elevate barriers for new entrants while accelerating consolidation among established manufacturers with regulatory infrastructure. Japan's PMDA and China's NMPA are tightening biocompatibility testing protocols for permanent cranial implants, diverting R&D resources toward extended clinical validation programs. Stakeholders must monitor reimbursement alignment between navigation system capital expenditures and procedure-specific DRG codes as bundled payment models expand.
Market Dynamics
Patient-specific 3D printed titanium implants are compressing surgical planning cycles while forcing manufacturers to reconfigure production workflows around additive manufacturing protocols and point-of-care printing partnerships with neurosurgery centers.
Growth Catalysts
- EU MDR technical documentation mandates:Manufacturers with established quality management systems capture market access advantages as smaller competitors exit due to compliance cost burdens.
- Computer-assisted cranial navigation:Stereotactic guidance technology bundles with hardware sales, expanding average contract values across German and Japanese hospital procurement channels.
- Trauma repair applications:Emergency department volumes in the United States drive consistent demand for screw and miniplate systems with standardized sizing protocols.
Market Restraints
- Titanium powder supply concentration:Additive manufacturing feedstock sourcing depends on a limited supplier base in China and Russia, exposing production schedules to geopolitical disruption.
- Resorbable polymer degradation variability:Patient-specific metabolic rates create unpredictable implant performance, complicating clinical validation requirements for 12-24 month degradation profiles.
- FDA 510(k) pathway friction:Substantial equivalence determinations for patient-specific implants require predicate device matching that constrains geometric innovation.
Strategic Opportunities
- India's neurosurgery infrastructure expansion:Government hospital modernization programs create first-mover advantages for manufacturers establishing local technical training centers.
- Navigation-software convergence:Surgical planning platforms integrating AI-powered trajectory mapping open recurring revenue streams beyond hardware sales cycles.
- Brazil's ANVISA fast-track pathway:Priority review designation for breakthrough cranial devices accelerates market entry timelines relative to standard PMA-equivalent processes.
Industry Challenges
- Additive manufacturing technician scarcity:Qualified operators for titanium laser powder bed fusion systems command premium compensation, constraining production scaling.
- ISO 13485 audit cycle compression:Notified body capacity limitations extend recertification timelines, freezing product modifications during review periods.
- Legacy ERP integration with MES platforms:Real-time production traceability requirements demand expensive middleware development for established manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cranial Fixation and Stabilization Systems Market |
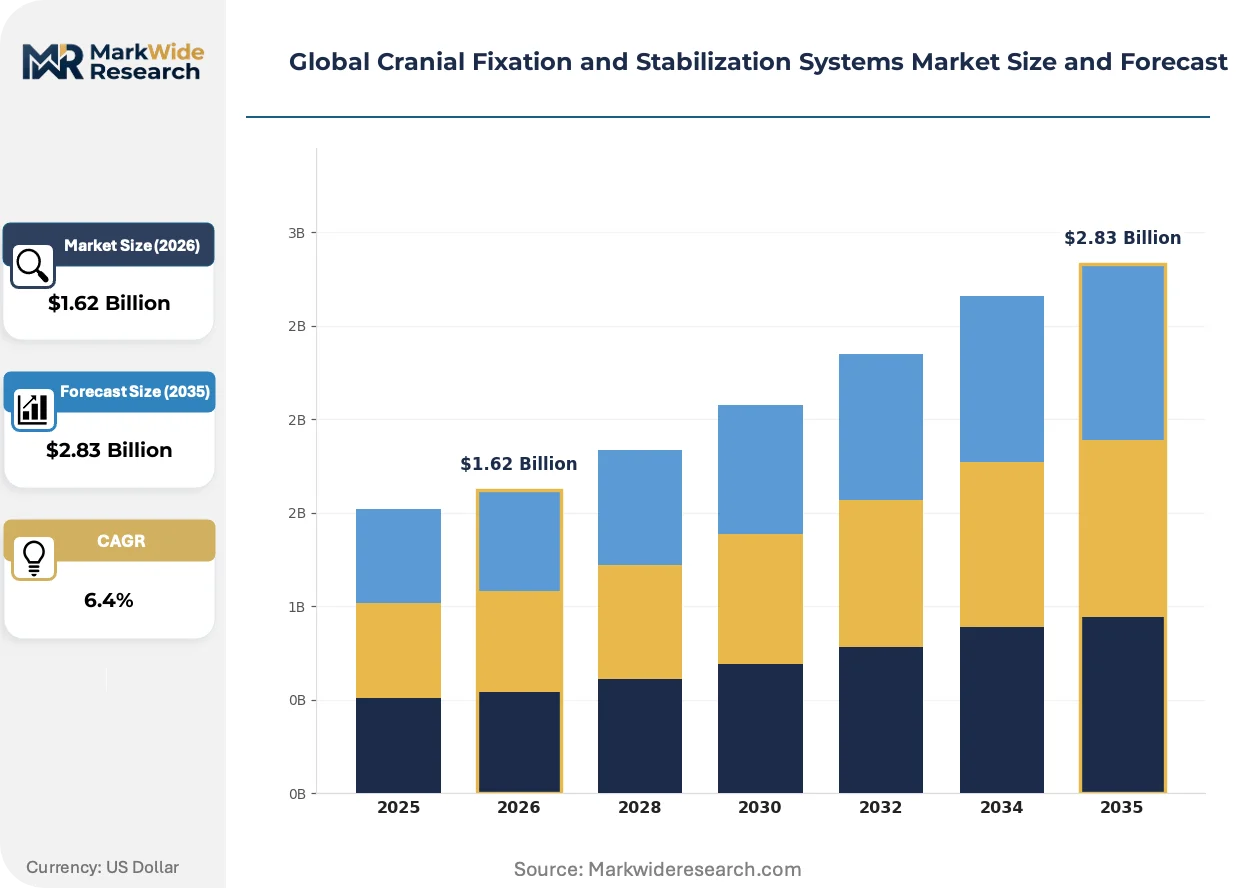
| Market Size in 2026 | $1.62 Billion |
| Market Size in 2035 | $2.83 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Titanium Plates, Resorbable Plates, Cranial Mesh, Miniplates, Screws Technology: 3D Printed Implants, Computer-Assisted Surgery, Navigation Systems, Stereotactic Guidance Application: Trauma Repair, Tumor Resection, Cranioplasty, Neurosurgical Procedures, Reconstructive Surgery End User: Neurosurgery Centers, Specialty Clinics, Ambulatory Surgical Centers, Research Institutes |
| Companies Covered | Johnson & Johnson, Medtronic, Stryker Corporation, Integra LifeSciences, B. Braun Melsungen AG, Zimmer Biomet Holdings, KLS Martin Group, DePuy Synthes, evonos GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cranial Fixation and Stabilization Systems Market Shifts & Advancements
Digital manufacturing workflows and regulatory data harmonization are redefining competitive moats in cranial implant production. Manufacturers now compete on design-to-implant velocity rather than catalog breadth alone.
Patient-specific 3D printed titanium cranial mesh is miniaturizing feature resolution below 100 microns, enabling anatomic matching previously impossible with milled stock plates. Neurosurgery centers in Germany and Japan are adopting these constructs for complex cranioplasty cases requiring orbital rim reconstruction. This capability is compressing OR time by eliminating intraoperative bending while is miniaturizing the addressable market for standard mesh geometries.
EU MDR Article 10 technical documentation requirements are extending clinical evaluation report preparation timelines by 8-14 months for Class III implantable devices. Manufacturers are responding by consolidating product portfolios to focus resources on highest-margin SKUs. The cranial fixation segment faces particular pressure as notified bodies apply stricter biocompatibility testing protocols to permanent titanium implants.
Hospital procurement teams are unbundling navigation system service contracts from initial capital purchases, demanding separate pricing for software maintenance, hardware warranty, and clinical training. This shift compresses upfront contract values while extending vendor relationship duration. The United States academic medical center segment leads this behavior, with GPOs standardizing three-year service term minimums across member hospitals.
Global Cranial Fixation and Stabilization Systems Market Segmentation
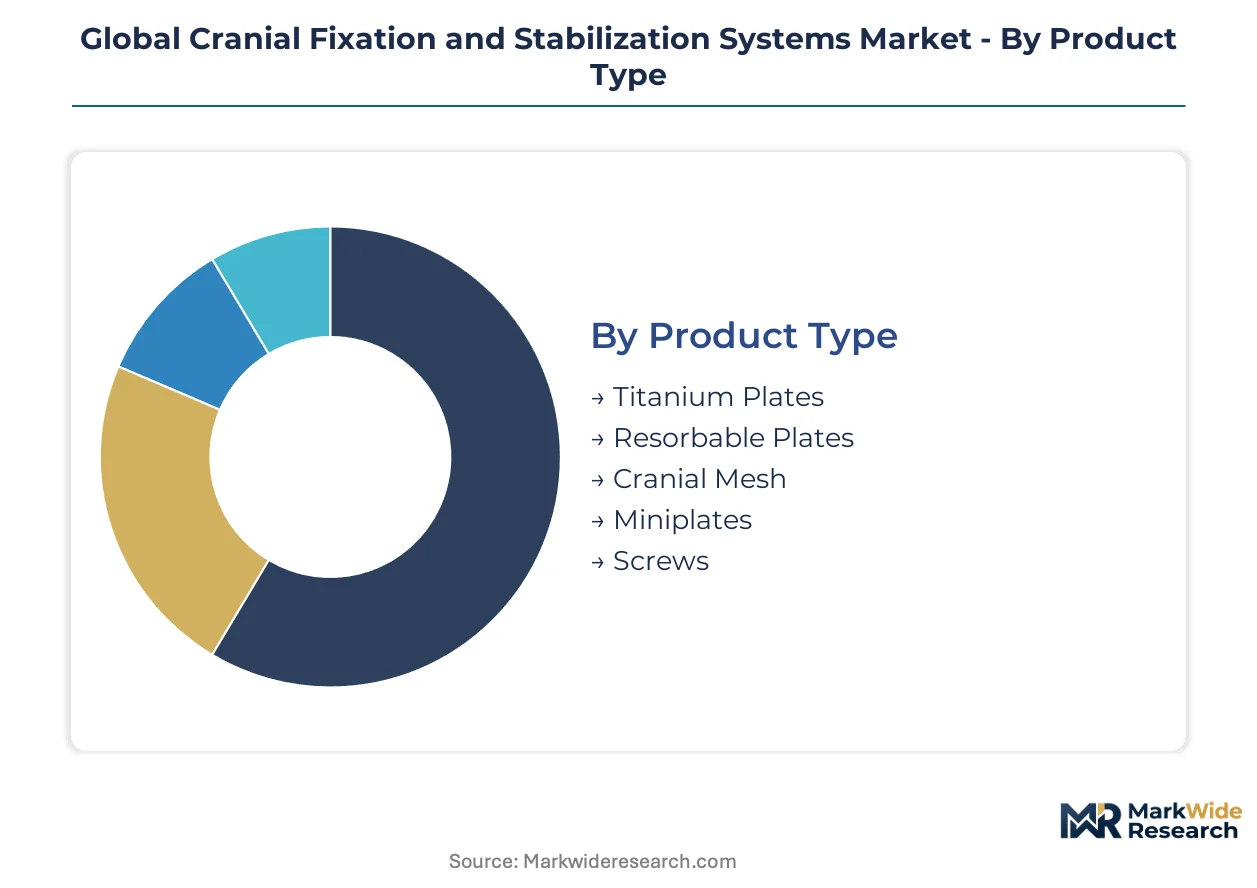
Segmentation in cranial fixation systems reveals distinct procurement patterns across trauma networks, academic medical centers, and specialized neurosurgery hubs. Manufacturers align product portfolios to OR workflow requirements and reimbursement pathways rather than clinical indication alone.
Product Type:
Titanium plate systems dominate domestic hospital procurement in the United States and Germany, while resorbable polymer platforms concentrate export demand from Japan and South Korea where regulatory pathways favor bioresorbable innovation.
- Titanium Plates:Titanium alloys specified for yield strength exceeding 100 ksi enable thin-profile designs that reduce palpability complications. Demand concentrates in Level I trauma centers across Texas, California, and Florida where craniotomy volumes sustain standardized inventory protocols. FDA 510(k) predicate device matching constrains geometric innovation but accelerates regulatory clearance timelines.
- Cranial Mesh:Patient-specific 3D printed titanium mesh commands margin premiums through anatomic matching below 100-micron feature resolution. German and Japanese neurosurgery centers adopt these constructs for complex orbital rim reconstructions, compressing OR time by eliminating intraoperative bending.
- Resorbable Plates:Polylactic acid and polyglycolic acid copolymers formulated for 12-24 month degradation profiles match bone remodeling timelines in pediatric applications. PMDA biocompatibility testing protocols in Japan divert R&D resources toward extended clinical validation.
- Miniplates:Low-profile titanium constructs address facial fracture fixation with standardized screw hole patterns enabling rapid intraoperative assembly. Emergency department volumes in US urban centers drive consistent demand for trauma repair applications.
- Screws:Self-tapping and self-drilling variants reduce surgical steps in time-critical trauma interventions. Unit economics favor high-volume production runs with diameter standardization across 1.0mm to 2.0mm specifications.
Titanium plate systems command the established base. The steepest expansion runs through patient-specific cranial mesh.
Technology:
Navigation and stereotactic platforms concentrate in high-volume academic centers with capital equipment budgets, while 3D printing capabilities spread through distributed manufacturing partnerships reducing implant lead times.
- 3D Printed Implants:Laser powder bed fusion of Ti-6Al-4V ELI powder enables topology-optimized lattice structures that balance strength with reduced modulus mismatch to native bone. Additive manufacturing technician scarcity constrains production scaling at contract manufacturers serving US and European hospital networks.
- Navigation Systems:Optical and electromagnetic tracking platforms integrate with preoperative imaging to enable real-time instrument guidance during tumor resection. German hospital procurement channels bundle hardware with software-enabled surgical planning workflows, expanding average contract values.
- Computer-Assisted Surgery:Robotic arm positioning and haptic feedback systems reduce tremor in microsurgical approaches to skull base lesions. Capital expenditure requirements limit deployment to tertiary referral centers with dedicated neurosurgery service lines.
- Stereotactic Guidance:Frame-based and frameless systems enable precise biopsy and electrode placement with sub-millimeter accuracy. Japanese neurosurgery centers lead adoption for functional neurosurgical applications including deep brain stimulation.
Navigation systems anchor the revenue base. The steepest expansion trajectory runs through 3D printed implant workflows.
Application:
Trauma repair applications sustain consistent demand through emergency department volumes, while cranioplasty and tumor resection concentrate in scheduled surgical schedules with longer procurement cycles.
- Trauma Repair:Acute subdural hematoma evacuation and depressed skull fracture fixation require rapid implant availability with standardized sizing protocols. US hospital GPO relationships prioritize supply chain reliability over product differentiation in this segment.
- Tumor Resection:Meningioma and glioma surgeries demand patient-specific constructs for large cranial defects exceeding standard plate dimensions. German neurosurgery centers combine navigation systems with custom implants for complex skull base approaches.
- Cranioplasty:Secondary reconstruction following decompressive craniectomy addresses bone flap resorption and infection complications. Resorbable polymer adoption concentrates in pediatric cases where permanent implant growth restriction poses long-term concerns.
- Neurosurgical Procedures:Functional interventions including epilepsy surgery and deep brain stimulation require minimal access approaches with specialized fixation systems. Japanese academic medical centers lead volume in this specialized application.
- Reconstructive Surgery:Post-oncologic and congenital defect correction combines cranial fixation with soft tissue reconstruction. Brazilian and Indian hospital systems are expanding adoption as neurosurgery infrastructure modernizes.
Trauma repair commands the established base. The steepest expansion runs through tumor resection applications bundled with navigation technology.
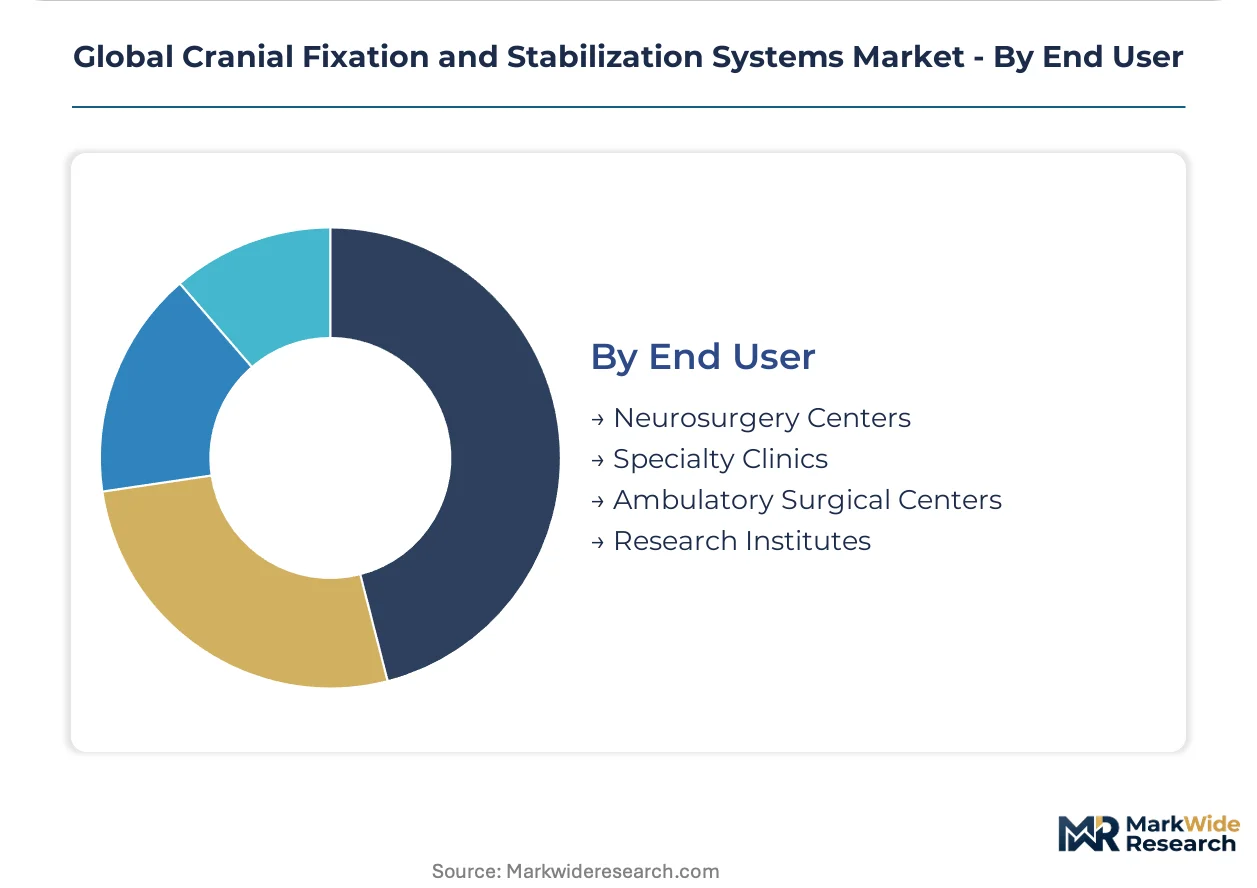
End User:
Neurosurgery centers concentrate capital equipment procurement and complex case volumes, while ambulatory surgical centers expand into routine cranioplasty with streamlined implant protocols.
- Neurosurgery Centers:Tertiary referral hospitals with dedicated neurosurgery service lines combine high case volumes with research participation enabling early technology adoption. German university hospitals and US academic medical centers lead navigation system deployment.
- Specialty Clinics:Focused craniofacial and neurosurgical practices concentrate elective cranioplasty and revision procedures. Patient-specific 3D printed implant adoption concentrates in these settings where surgeon-designer collaboration streamlines preoperative planning.
- Ambulatory Surgical Centers:Outpatient cranioplasty and hardware removal procedures expand as anesthesia protocols and infection control standards enable same-day discharge. US Medicare reimbursement alignment with procedure-specific DRG codes shapes site-of-service migration.
- Research Institutes:Preclinical and clinical trial participation drives demand for investigational device exemptions and custom fabrication partnerships. ISO 13485 quality management requirements extend to research manufacturing protocols.
Neurosurgery centers command the established base. The steepest expansion runs through ambulatory surgical centers capturing site-of-service migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways anchor the United States as the regulatory benchmark for cranial implant manufacturers worldwide. EU MDR technical documentation mandates and Japan's PMDA biocompatibility protocols create divergent compliance requirements across major markets. Hospital procurement patterns in Germany, Japan, and the United States concentrate demand for navigation-integrated systems and patient-specific 3D printed constructs.
United States
Level I trauma centers in Texas, California, and Florida sustain standardized inventory protocols for titanium plate systems. FDA 510(k) predicate device matching constrains geometric innovation but accelerates regulatory clearance timelines for manufacturers. Academic medical centers in the Northeast Corridor lead unbundling of navigation system service contracts from capital purchases.
Germany
University hospitals in Bavaria and North Rhine-Westphalia combine high case volumes with early adoption of patient-specific 3D printed titanium mesh. EU MDR notified body capacity limitations extend recertification timelines, freezing product modifications during review periods. The Stuttgart industrial cluster concentrates additive manufacturing technician training programs for laser powder bed fusion systems.
Japan
PMDA tightening of biocompatibility testing protocols for permanent cranial implants diverts R&D resources toward extended clinical validation. Kanto region academic medical centers lead adoption of stereotactic guidance systems for functional neurosurgical applications. Osaka-based neurosurgery hubs drive demand for resorbable polymer platforms in pediatric cranioplasty cases.
China
NMPA regulatory harmonization efforts accelerate market entry timelines for multinational manufacturers with established quality management systems. Yangtze River Delta hospital networks expand neurosurgery infrastructure modernization programs. Shanghai medical device clusters concentrate domestic production of titanium powder feedstock for additive manufacturing workflows.
Brazil
ANVISA fast-track pathway designation for breakthrough cranial devices accelerates market entry relative to standard PMA-equivalent processes. São Paulo and Rio de Janeiro hospital systems drive adoption of navigation-integrated hardware as neurosurgery service lines expand. Southeastern state procurement teams prioritize supply chain reliability for trauma repair applications.
Global Cranial Fixation and Stabilization Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in cranial fixation and stabilization systems. Johnson & Johnson and Medtronic leverage diversified medical device portfolios to bundle hardware with navigation software and service contracts. Stryker Corporation anchors North American trauma repair channels through dense hospital GPO relationships. Competitive moves concentrate on M&A to acquire additive manufacturing capabilities and strategic partnerships with neurosurgery centers for point-of-care printing workflows.
Among integrated medical technology conglomerates, Johnson & Johnson, Medtronic, and Stryker Corporation exemplify the scale-driven archetype through diversified hardware portfolios and navigation system integration. B. Braun Melsungen AG and KLS Martin Group represent European specialist manufacturers with concentrated cranial fixation expertise. Zimmer Biomet Holdings occupies a position bridging orthopedic and neurosurgical applications, while evonos GmbH & Co. KG exemplifies the precision-engineering specialist tier in German medical device manufacturing.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Medtronic |
| Stryker Corporation |
| Integra LifeSciences |
| B. Braun Melsungen AG |
| Zimmer Biomet Holdings |
| KLS Martin Group |
| DePuy Synthes |
| evonos GmbH & Co. KG |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation contracts for titanium powder feedstock lock in supply access and price visibility for additive manufacturing workflows, while unbundled navigation system service agreements compress upfront contract values across German and US academic medical center procurement channels.
Pricing Analysis
Geographic price spreads of 15-25% separate North American trauma repair contracts from European custom implant procurements. Three-tier pricing structure across patient-specific cranial mesh, navigation-integrated systems, and standard miniplate portfolios differentiates by customization level and after-sales clinical training bundling. Cost compression in standard titanium screw and miniplate segments intensifies as hospital GPOs consolidate volume commitments. Ambulatory surgical centers exhibit highest price sensitivity due to Medicare DRG reimbursement constraints, while German university hospitals prioritize OR time savings over unit cost.
Supply Chain Analysis
China and Russia concentrate titanium sponge and alloy powder production for laser powder bed fusion feedstock. Manufacturing draws from limited qualified suppliers of Ti-6Al-4V ELI powder, specialized additive manufacturing equipment, and certified polymer resins for resorbable platforms. Single-source vulnerability in titanium powder sourcing exposes production schedules to geopolitical disruption and export licensing friction. Distribution runs through hospital GPO consolidated purchasing agreements in the United States, direct university hospital contracts in Germany, and regional distributor networks in Brazil and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Navigation-software convergence is repositioning cranial fixation from discrete hardware sales toward platform-ecosystem economics, with AI-powered surgical planning workflows creating recurring revenue attachment points beyond implant procurement cycles.
For Market Incumbents: Shield premium positioning in computer-assisted cranial procedures by deepening additive manufacturing technician training pipelines and securing point-of-care printing partnerships with German and Japanese neurosurgery centers. Consolidate regulatory infrastructure advantages under EU MDR and FDA 510(k) pathways to raise compliance barriers against emerging entrants lacking clinical validation resources. For New Entrants and Emerging Players: Brazil's ANVISA fast-track pathway for breakthrough cranial devices offers accelerated market entry timelines relative to standard PMA-equivalent processes. Target India's government hospital modernization programs for neurosurgery infrastructure expansion, establishing local technical training centers as beachheads. Lead with resorbable polymer platforms in pediatric cranioplasty applications where metabolic degradation variability creates whitespace for innovative formulation claims. For Investors and Strategic Acquirers: Additive manufacturing specialist contract manufacturers with ISO 13485 certification and laser powder bed fusion capacity represent priority acquisition targets as production scaling constraints tighten. Long-term viability hinges on navigation-software convergence revenue durability and reimbursement alignment with bundled payment models. Watch for FDA 510(k) clearance velocity for patient-specific implants as inflection indicator for geometric innovation feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Point-of-Care Printing Partnership | Neurosurgery centers in Germany and Japan compress implant lead times through distributed manufacturing workflows. |
| Navigation-Software Integration | AI-powered trajectory mapping platforms create recurring revenue streams beyond hardware replacement cycles. |
| EU MDR Technical Documentation Investment | Established manufacturers capture market access advantages as notified body capacity constraints freeze product modifications. |
| Additive Manufacturing Technician Pipeline | Stuttgart industrial cluster training programs address laser powder bed fusion operator scarcity constraining production scaling. |
| Reimbursement Strategy Alignment | Hospital procurement teams unbundle service contracts from capital purchases, demanding three-year minimum terms. |
Research Methodology
A spread of perspectives from neurosurgeons, hospital purchasing committees, biomedical engineers, and GPO contracts managers converged on the working assumptions for cranial fixation demand modeling. Primary interviews with regulatory affairs specialists at notified bodies and FDA submission consultants validated pathway timeline assumptions. Secondary sources included FDA 510(k) premarket notification databases, EU MDR technical documentation guidance, hospital procurement contract filings, and CMS Medicare DRG reimbursement schedules. Bottom-up implant volume estimates triangulated against top-down market value reconstructions.
Segmentation dimensions modeled span product type, technology platform, application indication, and end-user facility category across the analysis window. CAGRs derived from procedure volume growth trajectories, technology substitution curves for navigation systems, and pricing evolution in patient-specific versus standard implant portfolios. Forecast inputs incorporated neurosurgery center expansion rates in India and Brazil, additive manufacturing technician supply constraints, and EU MDR notified body capacity limitations.
Underlying assumptions cover titanium powder supply continuity, reimbursement stability for computer-assisted procedures, and regulatory pathway harmonization, with deviation risk concentrated in geopolitical feedstock disruption and PMDA biocompatibility protocol tightening. Recalibration cycles align with material shifts in navigation system adoption curves, bundled payment model expansion, and point-of-care printing partnership formation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
I.V. Fluid Warmer Market
Medical Devices
Global Electromyography Devices Market
Medical Devices
Contact Lens Lubricant Market
Medical Devices
Global Microcatheter Market
Medical Devices
Argentina Ultrasound Devices Market
Medical Devices
Smart Lenses Market
Medical Devices
Gutta Percha Obturator Market
Medical Devices
Dynamic Spinal Tethering Systems Market
Medical Devices
Bronchial Blocker Devices Market
Medical Devices
Ligament Stabilizers Market
Medical Devices
Patellar Implant Market
Medical Devices
Neuromuscular Transmission Monitor Market
Medical Devices
Minimally Invasive Spine Technologies Market
Medical Devices
Australia General Surgical Devices Market
Medical Devices
Middle East and Africa C-Arms Market
Medical Devices
Biologic Injectors Market