
 3D Printed Hip and Knee Implants Market | 2026-2036
3D Printed Hip and Knee Implants Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printed Hip and Knee Implants Market Outlook
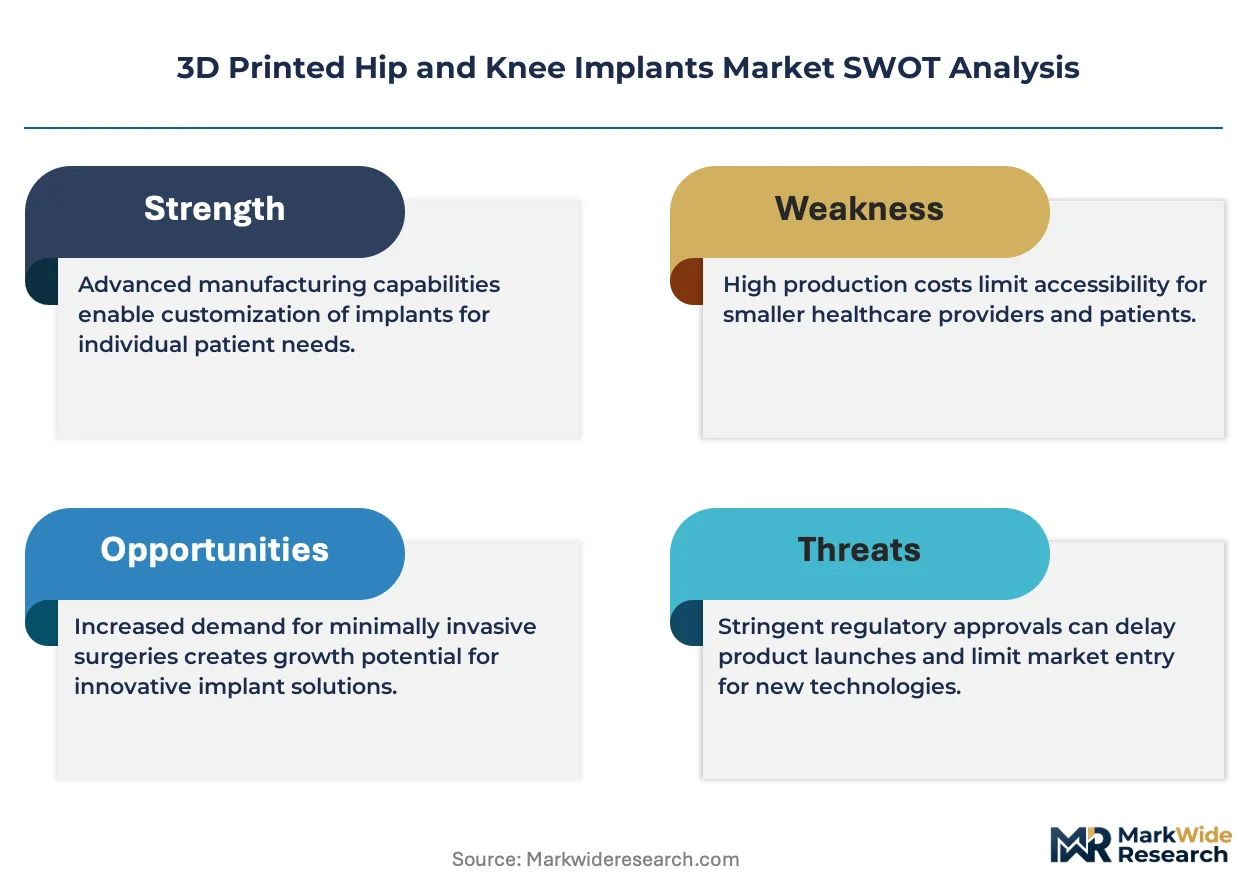
The split between premium patient-matched titanium lattice implants and commodity cobalt-chrome off-the-shelf components is realigning procurement budgets across hospital systems. Stryker Corporation leverages its integrated metal printing facilities to control supply timelines for complex acetabular cups. Zimmer Biomet Holdings anchors its competitive stance through deep specialization in knee implant geometries optimized for selective laser sintering.
3D printed hip and knee implants are additively manufactured orthopedic prostheses, typically fabricated from titanium alloys or cobalt-chrome powders through electron beam melting or selective laser sintering, with porosities engineered between 300-600 micrometers to promote osseointegration and long-term fixation. These devices serve the primary commercial purpose of replacing or resurfacing damaged joint surfaces with geometries matched to individual patient anatomy from CT or MRI datasets. Hip implants produced via electron beam melting capture the dominant share of current revenue as hospitals prioritize porous acetabular cups with proven bone ingrowth performance. Knee implants represent the fastest-expanding category as personalized tibial trays and femoral condyles reduce revision rates in younger, active patient cohorts.
FDA 510(k) pathways and EU MDR conformity assessments shape product development timelines and clinical evidence requirements for titanium alloy lattice structures seeking commercial approval. ISO 5832 standards for surgical implant materials and ASTM F3055 specifications for additively manufactured medical devices establish the metallurgical and dimensional benchmarks that manufacturers must satisfy. Stakeholders should monitor how FDA draft guidance on patient-specific device sizing intersects with hospital value-analysis committee criteria for custom implant reimbursement.
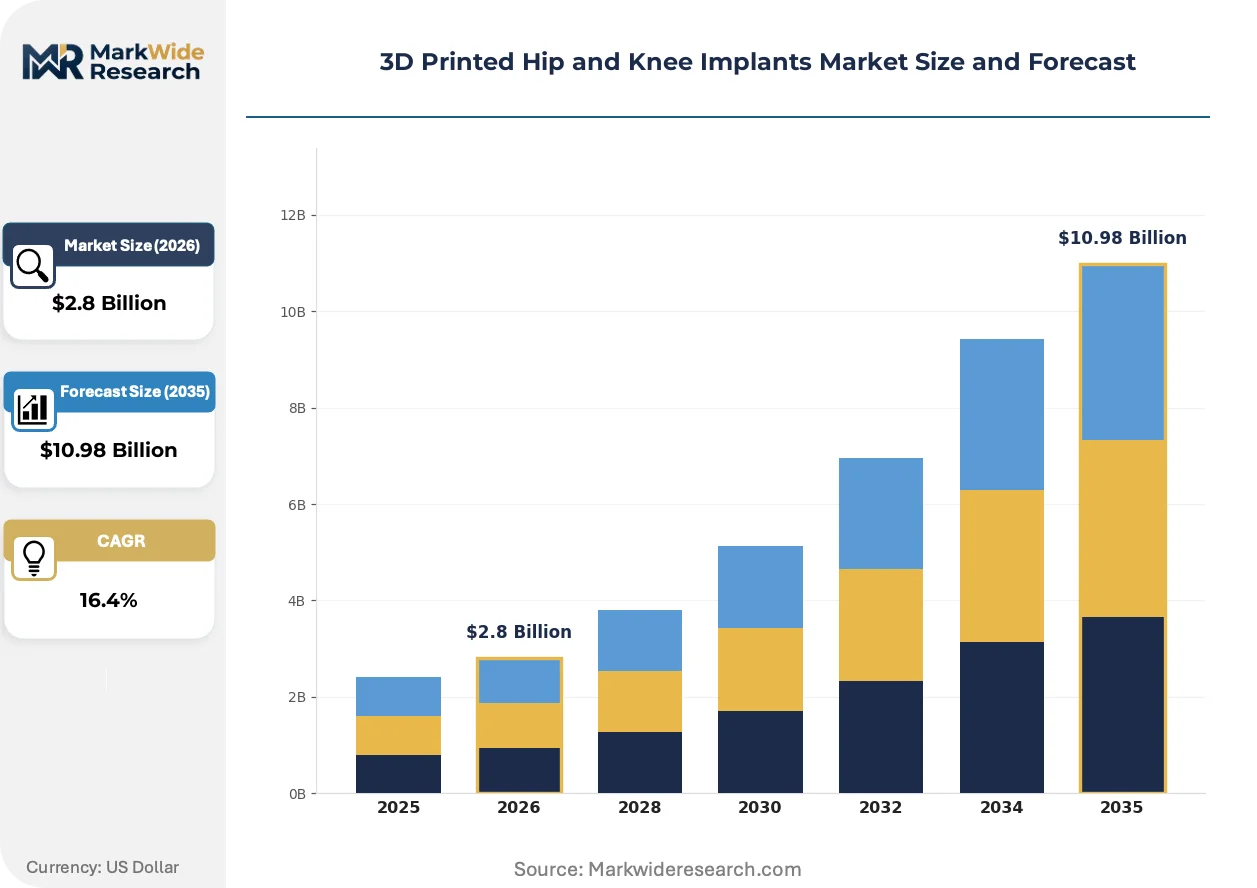
Market Dynamics
Patient-matched titanium lattice implants are compressing traditional cobalt-chrome procurement cycles as hospitals reallocate capital toward additive manufacturing workflows that promise reduced revision rates and shorter operative times.
Growth Catalysts
- FDA 510(k) Streamlining:The FDA's additive manufacturing guidance for medical devices accelerates titanium lattice acetabular cups through premarket notification pathways. Orthopedic hospitals in Germany integrate these clearances into value-analysis protocols.
- Electron Beam Melting:This powder-bed fusion technology produces porous structures with 300-600 micrometer porosities that accelerate osseointegration. University hospitals deploy EBM systems for revision arthroplasty with measurable bone ingrowth performance.
- Younger Patient Cohorts:Active patients under 55 drive demand for personalized knee geometries that withstand higher mechanical loads. Custom tibial trays from CT datasets reduce polyethylene wear and extend implant longevity.
Market Restraints
- Titanium Powder Volatility:Spherical Ti-6Al-4V ELI powder prices fluctuate with aerospace demand cycles, compressing gross margins for implant manufacturers without captive supply agreements.
- EBM Equipment Concentration:Arcam systems dominate electron beam melting hardware, creating single-source dependency for hospitals scaling patient-specific programs.
- EU MDR Clinical Evidence Burden:The Medical Device Regulation's enhanced requirements for additively manufactured implants extend conformity assessment timelines and inflate notified body costs.
Strategic Opportunities
- India's Orthopedic Infrastructure:CDSCO regulatory harmonization with ISO 5832 standards creates entry pathways for titanium lattice implants as private hospital chains expand joint replacement capacity.
- AI-Driven Geometry Optimization:Machine learning algorithms converge with selective laser sintering to generate patient-matched implants from incomplete imaging datasets, expanding addressable cases.
- Point-of-Care Manufacturing:Hospital-based metal printing cells bypass traditional supply chains, enabling same-week implant production for urgent revision cases.
Industry Challenges
- Additive Manufacturing Technicians:Shortages of certified EBM/SLS operators limit hospital program expansion despite capital equipment availability.
- ASTM F3055 Validation:Dimensional tolerance verification for lattice structures requires specialized metrology equipment that strains quality assurance budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printed Hip and Knee Implants Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hip Implants, Knee Implants, Biocompatible Materials, Personalized Components Delivery Mode: Surgical Procedure, Outpatient Services, In-hospital Treatment, Telemedicine End User: Orthopedic Clinics, Hospitals, Rehabilitation Centers, Prosthetic Providers Technology: Fused Deposition Modeling, Selective Laser Sintering, Stereolithography, Electron Beam Melting |
| Companies Covered | Smith & Nephew plc, restor3d, Stryker Corporation, 3D Systems Corporation, Exactech Inc., Zimmer Biomet Holdings, Medtronic plc, Stratasys Ltd., Johnson & Johnson (DePuy Synthes), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printed Hip and Knee Implants Market Strategic Shifts
Software-defined implant workflows are collapsing the traditional boundaries between diagnostic imaging, surgical planning, and device fabrication, creating closed-loop systems that compress delivery timelines from weeks to days.
Selective laser sintering of cobalt-chrome femoral components is decentralizing production authority from centralized manufacturing plants to hospital-based printing cells. Academic medical centers in the United States deploy these systems for urgent revision cases that cannot accommodate standard supply lead times. Distributed manufacturing networks challenge traditional orthopedic device distribution economics.
The EU MDR's enhanced requirements for patient-specific device documentation are accelerating investment in digital quality management systems. Notified bodies demand traceable parameter records for every build job, forcing manufacturers to retrofit legacy additive systems with comprehensive data logging. German university hospitals lead compliance integration, establishing templates that smaller EU markets adopt.
Surgeon preference for porous titanium acetabular cups over cemented cobalt-chrome alternatives is restructuring procurement evaluation criteria in US value-analysis committees. Hospital systems now weight osseointegration performance metrics more heavily than initial implant cost in capital allocation decisions. This behavioral shift concentrates demand among manufacturers with validated lattice architectures.
3D Printed Hip and Knee Implants Market Segmentation
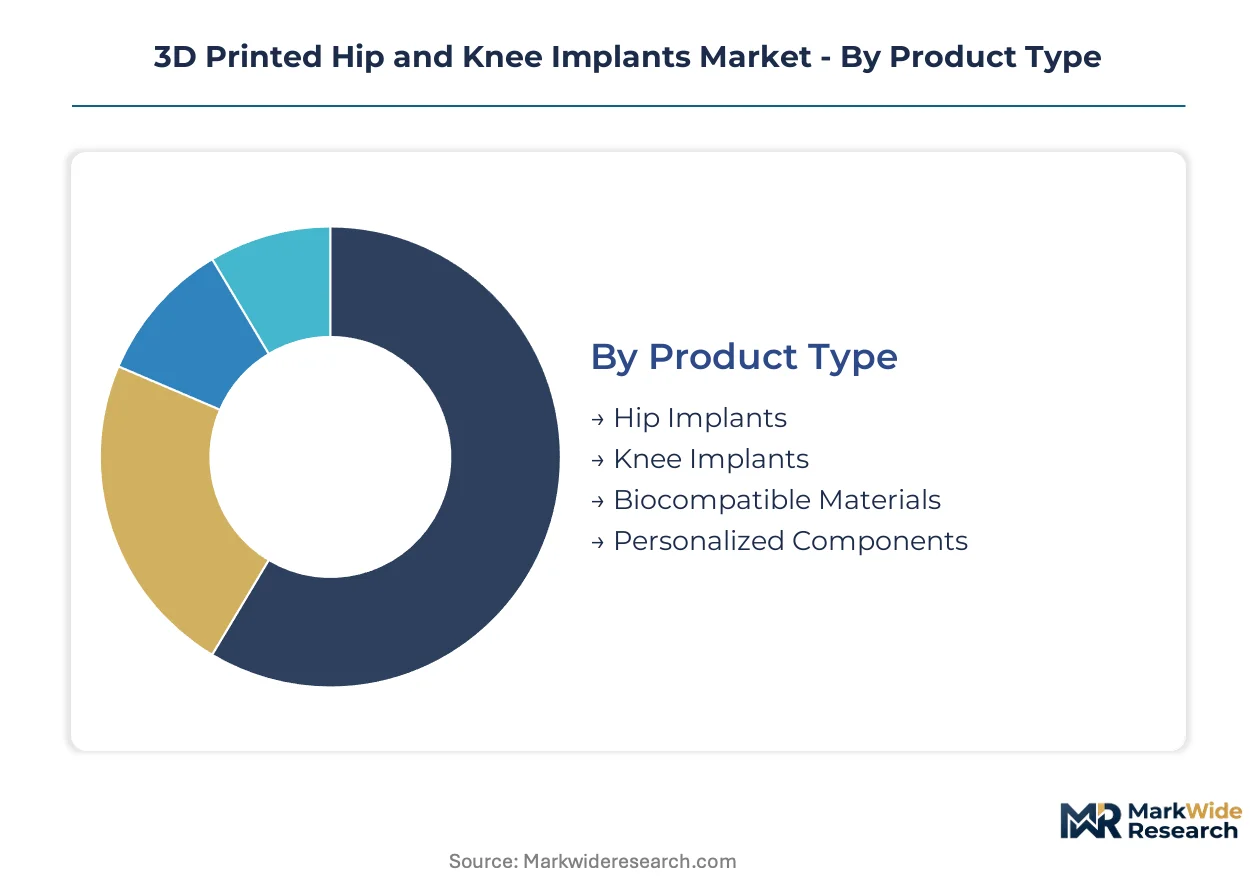
Segmentation in the 3D printed hip and knee implants market separates high-volume standardized components from premium patient-matched geometries. Procurement decisions hinge on whether hospitals prioritize inventory efficiency or revision-rate reduction.
Product Type:
Volume concentrates in off-the-shelf cobalt-chrome components while premium flows to titanium lattice structures with engineered porosities.
- Hip Implants:Acetabular cups fabricated via electron beam melting dominate current revenue as porous titanium architectures demonstrate superior osseointegration in revision arthroplasty. German university hospitals anchor procurement volume for these components.
- Knee Implants:Patient-matched tibial trays and femoral condyles from CT datasets address younger, active patient cohorts demanding mechanical durability. Demand climbs fastest in US orthopedic hospitals expanding personalized implant programs.
- Biocompatible Materials:Ti-6Al-4V ELI powder and cobalt-chrome alloys constitute the metallurgical foundation for all additive orthopedic devices.
- Personalized Components:Custom geometries from incomplete imaging datasets expand addressable cases through AI-driven reconstruction algorithms.
Today's leader: Hip Implants. Tomorrow's challenger: Knee Implants.
Delivery Mode:
Procedure location determines reimbursement pathways and capital equipment requirements for implant integration.
- Surgical Procedure:Operating room deployment of 3D printed implants requires sterile field protocols and surgeon-specific instrumentation kits. US value-analysis committees weight operative time reduction heavily in procurement decisions.
- In-hospital Treatment:Integrated care pathways bundle implant costs with revision risk warranties. German hospital systems pioneered these arrangements for complex acetabular reconstructions.
- Outpatient Services:Ambulatory surgical centers adopt selective laser sintered components for straightforward primary arthroplasty cases.
- Telemedicine:Remote surgical planning and implant design review compress preoperative timelines for rural patient access.
Revenue concentrates in Surgical Procedure. Margins expand fastest in Telemedicine-enabled preoperative planning.
End User:
Customer type splits between high-volume arthroplasty centers and specialized revision-focused institutions.
- Hospitals:Academic medical centers in the United States deploy hospital-based metal printing cells for urgent revision cases. These institutions capture premium pricing for same-week implant production.
- Orthopedic Clinics:Specialized joint replacement centers concentrate demand for patient-matched knee geometries. Younger patient demographics drive volume in these settings.
- Rehabilitation Centers:Postoperative care facilities influence implant selection through long-term functional outcome data.
- Prosthetic Providers:External manufacturers supply standardized components to cost-sensitive health systems.
Procurement authority sits with Hospitals. Orthopedic Clinics gain share through outcome-based contracting.
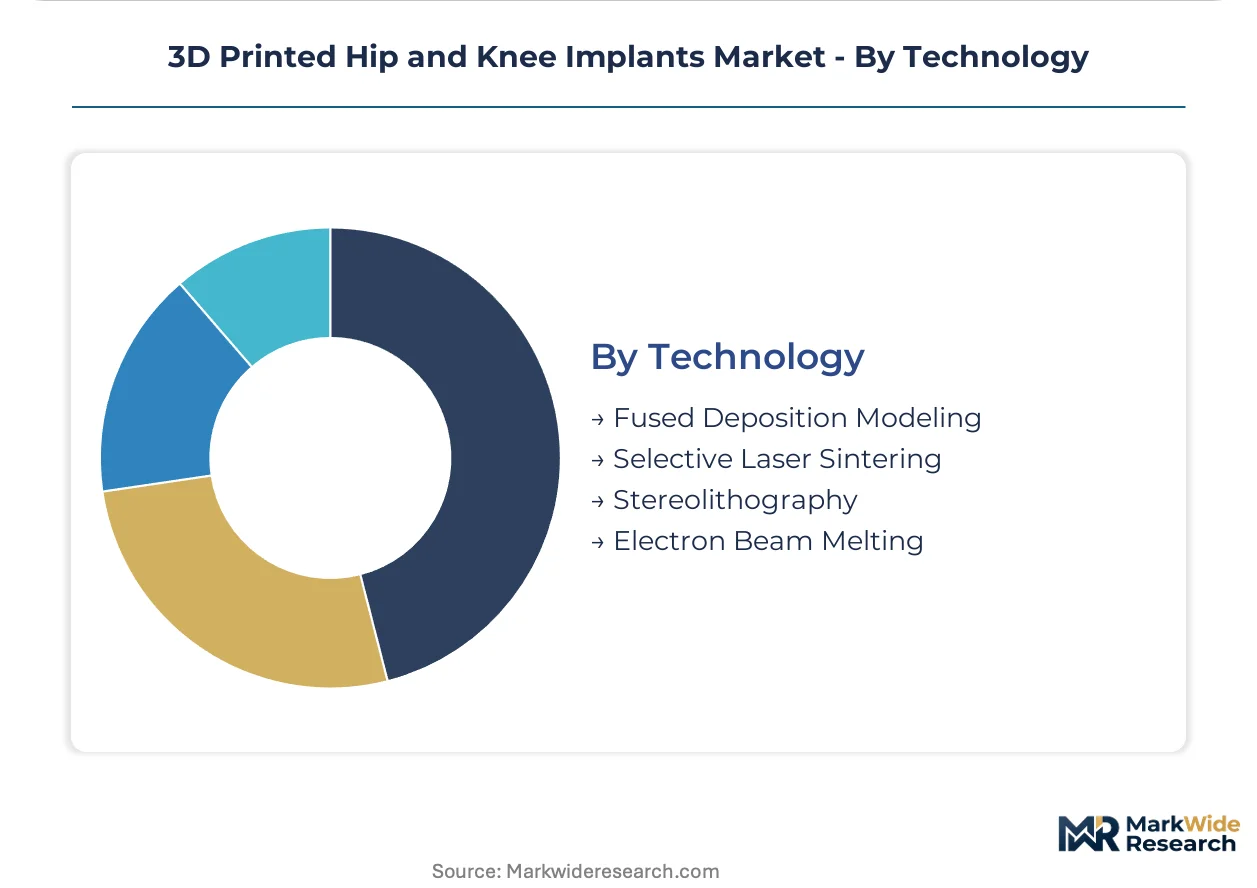
Technology:
Equipment selection locks hospitals into specific powder-bed fusion ecosystems with divergent capital and operating cost profiles.
- Electron Beam Melting:Arcam systems produce 300-600 micrometer porosities optimal for bone ingrowth in acetabular applications. University hospitals in Germany anchor installed base expansion.
- Selective Laser Sintering:Cobalt-chrome femoral components from these systems decentralize production authority to hospital-based cells. US academic centers lead point-of-care manufacturing adoption.
- Fused Deposition Modeling:Polymer-based surgical guides and preoperative models support implant placement accuracy.
- Stereolithography:Resin-based prototyping accelerates design iteration for patient-specific geometries.
Clinical validation favors Electron Beam Melting. Selective Laser Sintering climbs fastest through distributed manufacturing networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized additive manufacturing technicians concentrate in German university hospitals and US academic medical centers, anchoring regional capability clusters that shape procurement patterns for patient-specific implant programs.
United States
FDA 510(k) streamlining for titanium lattice acetabular cups accelerates commercial entry as orthopedic hospitals expand value-analysis protocols. Academic medical centers in Massachusetts and California deploy hospital-based metal printing cells for urgent revision cases. The Mayo Clinic and Cleveland Clinic anchor demand for same-week implant production.
Germany
University hospitals in Bavaria and Baden-Württemberg integrate electron beam melting into revision arthroplasty workflows with measurable bone ingrowth performance. EU MDR conformity assessments for additively manufactured devices extend timelines but establish templates smaller EU markets adopt. Charité Berlin and Heidelberg University Hospital concentrate procurement authority for porous titanium architectures.
India
Private hospital chains in Maharashtra and Karnataka expand joint replacement capacity as CDSCO regulatory harmonization with ISO 5832 standards creates entry pathways for titanium lattice implants. Younger patient demographics in Delhi-NCR and Mumbai drive demand for personalized knee geometries. Apollo Hospitals and Fortis Healthcare anchor volume concentration.
Japan
PMDA regulatory frameworks for patient-specific medical devices shape development timelines as university hospitals in Tokyo and Osaka adopt selective laser sintering for cobalt-chrome femoral components. METI industrial policy supports additive manufacturing infrastructure. Keio University Hospital and Osaka University Hospital lead clinical validation programs.
United Kingdom
Specialized orthopedic centers in London and Manchester concentrate demand for patient-matched implants as MHRA post-Brexit regulatory pathways diverge from EU MDR. NHS value-analysis committees weight revision-rate reduction in procurement decisions. The Royal National Orthopaedic Hospital and Wrightington Hospital anchor regional expertise.
3D Printed Hip and Knee Implants Market Competitive Environment
Capital-heavy producers compete with asset-light designers across divergent equipment ownership models. The market structure consolidates around integrated metal printing facilities and specialized geometry optimization software. Three archetypes dominate: diversified orthopedic conglomerates with captive additive capacity, pure-play 3D printing technology vendors, and emerging patient-specific implant specialists. Competitive moves concentrate on strategic partnerships between equipment manufacturers and hospital systems, plus technology licensing arrangements that transfer lattice design IP.
Among diversified orthopedic conglomerates, Stryker Corporation and Zimmer Biomet Holdings exemplify the integrated-facility archetype with controlled supply timelines for complex geometries. Within the pure-play technology tier, 3D Systems Corporation represents equipment-centric positioning. These three anchors illustrate how competitive positioning splits between manufacturing control and design specialization.
| Leading Market Players |
|---|
| Smith & Nephew plc |
| restor3d |
| Stryker Corporation |
| 3D Systems Corporation |
| Exactech Inc. |
| Zimmer Biomet Holdings |
| Medtronic plc |
| Stratasys Ltd. |
| Johnson & Johnson (DePuy Synthes) |
| Others |
Value Chain & Pricing Dynamics
Ti-6Al-4V ELI powder costs cascade from aerospace demand cycles through implant manufacturer margins to hospital procurement committees, with spherical titanium feedstock volatility compressing gross margins for producers lacking captive supply agreements while premium patient-matched geometries sustain pricing power through demonstrated revision-rate reduction.
Pricing Analysis
Bundled service contracts that wrap implant costs into revision risk warranties compete against unbundled per-unit transactional pricing for off-the-shelf cobalt-chrome components. Three-tier pricing structure across premium patient-matched titanium lattice, standard modular implants, and economy cobalt-chrome commodity separates procurement budgets by osseointegration performance and customization depth. Price differentiation hinges on FDA 510(k) clearance tier and hospital volume scale, with academic medical centers extracting discounts through outcome-based contracting. Pricing pressure stems from EU MDR conformity assessment inflation, while ambulatory surgical centers exhibit highest price sensitivity and German university hospitals show least sensitivity due to bundled warranty value.
Supply Chain Analysis
Direct-to-hospital channels handle patient-matched implant demand while traditional orthopedic distributors manage standardized component flows. Manufacturing concentrates in the United States, Germany, and Sweden where Arcam EBM systems anchor electron beam melting capacity. Raw material dependencies center on spherical Ti-6Al-4V ELI powder, cobalt-chrome alloy feedstock, and argon gas for build chamber atmospheres. Single-source vulnerability permeates the Arcam equipment installed base, with hospital programs facing operational disruption from any supplier production halt. Distribution runs through GPO contracts for high-volume buyers and direct manufacturer relationships for patient-specific programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA 510(k) streamlining for titanium lattice structures accelerates commercial entry and compresses development timelines for validated additive manufacturing workflows.
For Market Incumbents: Extend lattice design IP portfolios through strategic licensing arrangements that transfer geometric optimization algorithms to hospital-based printing cells. Deepen backward integration into titanium powder supply through long-term offtake agreements with spherical feedstock producers, defending against aerospace demand cycle volatility that threatens margin stability in patient-matched implant tiers.
For New Entrants and Emerging Players: Capture India's private hospital chain expansion as CDSCO regulatory harmonization with ISO 5832 standards lowers entry barriers for titanium lattice implants in Maharashtra and Karnataka. Target younger patient cohorts demanding personalized knee geometries through AI-driven reconstruction from incomplete imaging datasets, penetrating the fastest-expanding segment with software-defined workflow differentiation.
For Investors and Strategic Acquirers: Consolidation pressure builds where hospital-based metal printing cells require captive additive capacity to sustain same-week production timelines for urgent revision cases. Long-term viability favors asset-light geometry optimization software vendors over capital-heavy equipment manufacturers, with acquisition targets clustering around patient-specific implant specialists possessing validated FDA clearances. Watch EU MDR notified body capacity constraints as the inflection signal for European market access bottlenecks.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | FDA 510(k) streamlining accelerates titanium lattice acetabular cups through premarket notification pathways. |
| Hospital System Partnership | Academic medical centers in Massachusetts deploy hospital-based metal printing cells for urgent revision cases. |
| Backward Integration | Captive titanium powder agreements insulate margins from aerospace demand cycle volatility. |
| Software Companion Development | AI-driven geometry optimization expands addressable cases from incomplete CT and MRI datasets. |
| Reimbursement Strategy | US value-analysis committees weight revision-rate reduction over initial implant cost in procurement decisions. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, EU MDR notified body databases, hospital procurement records, and ISO 5832 standard documentation. Bottom-up implant volume modeling triangulated against top-down market sizing across the analysis window.
Segment-weighting approaches distributed volume and value across hip implants, knee implants, biocompatible materials, and personalized components, with technology splits between electron beam melting and selective laser sintering further disaggregating the forecast. CAGRs derived from procedure volume growth, technology adoption curves, and regulatory pathway velocity. Industry-specific inputs included titanium powder price indices, EBM equipment installed base counts, and EU MDR conformity assessment timeline data.
Underlying measurement precision varies by segment; patient-matched titanium lattice implants carry tighter precision than commodity cobalt-chrome components due to concentrated manufacturer disclosure. Forecasts reflect documented assumptions regarding FDA clearance velocity, EU notified body capacity, and hospital capital expenditure cycles. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Vortex Mixer Market
Medical Devices
Deep Brain Stimulator Market
Medical Devices
Medical Device Cros Market
Medical Devices
Global Neurology Ultrasonic Aspirators Market
Medical Devices
Mexico Spinal Surgery Devices Market
Medical Devices
Global Tympanostomy Products Market
Medical Devices
Catheter Securement Devices Market
Medical Devices
Bone Fixation Plates Market
Medical Devices
Micro Balloon Catheter Market
Medical Devices
Asia-Pacific Refractive Surgery Devices Market
Medical Devices
Image-Based Cytometer Market
Medical Devices
South Africa Digital X-Ray Devices Market
Medical Devices
Europe Artificial Organs and Bionic Implants Market
Medical Devices
Laparoscopic Electrodes Market
Medical Devices
Canada Aesthetic Devices Market
Medical Devices
China Artificial Organs and Bionic Implants Market