
 Breast Biopsy Market | 2026-2036
Breast Biopsy Market Size, Share, and Industry Trends Forecast 2026-2036
Breast Biopsy Market Analysis
Hospital procurement of breast biopsy systems is tilting toward bundled imaging-device contracts that lock in long-term service revenue. Hologic Inc. leverages its integrated mammography-to-biopsy platform to control upgrade cycles within installed bases. Becton Dickinson and Company anchors its position through deep needle portfolio specialization across core and vacuum-assisted methods. Danaher Corporation competes on workflow automation, embedding specimen handling into broader diagnostic laboratory networks.
Breast biopsy encompasses the extraction of tissue specimens from suspected breast lesions using needle-based or surgical techniques, typically guided by ultrasound, stereotactic X-ray, or magnetic resonance imaging, with specimen cores ranging from millimeters to grams depending on method. Its primary purpose is histopathological confirmation of malignancy prior to treatment planning. Vacuum-assisted biopsy devices command premium pricing due to larger tissue yields and lower sampling error rates versus fine needle aspiration. Imaging systems segment growth tracks directly to 3D mammography retrofit cycles in hospital radiology departments. Diagnostic centers represent the fastest-growing end user channel as outpatient breast imaging networks expand regional access.
The US FDA governs device premarket clearance through the 510(k) pathway while the EU MDR imposes strengthened clinical evidence requirements for breast biopsy needle classifications. These frameworks elevate R&D costs for new entrants but protect incumbent manufacturers with established quality management systems. Stakeholders must monitor reimbursement parity between hospital-based and freestanding diagnostic center procedures, as site-of-service differentials increasingly influence capital placement decisions.
Market Dynamics
Hospital procurement teams are consolidating breast biopsy capital purchases into multi-year imaging platform agreements that bundle device hardware, software licenses, and preventive maintenance into single contractual frameworks.
Growth Catalysts
- Screening program expansion:National breast cancer detection initiatives in Germany, France, and Japan are expanding eligible age cohorts and shortening screening intervals, directly lifting procedure volumes in hospital radiology departments.
- EU MDR clinical evidence requirements:Strengthened post-market surveillance mandates for Class IIa and IIb biopsy needle classifications are accelerating replacement of legacy devices with next-generation systems that demonstrate superior histological yield rates.
- Vacuum-assisted tissue acquisition:Diagnostic centers are prioritizing single-insertion devices that harvest larger contiguous cores, reducing sampling error rates and repeat biopsy rates in outpatient settings.
Market Restraints
- Stainless steel and nitinol input costs:Biopsy needle manufacturers face margin compression from specialty alloy price volatility, with medical-grade wire feedstock accounting for substantial material cost exposure in disposable device portfolios.
- Concentrated imaging system supply:Three equipment vendors control the installed base of stereotactic guidance platforms in the United States, creating gatekeeper effects for complementary biopsy device placement.
- Fine needle aspiration substitution:Cytological screening methods retain cost advantages in resource-constrained clinical environments, limiting penetration of core needle and vacuum-assisted alternatives in select geographies.
Strategic Opportunities
- Freestanding diagnostic center buildout:Brazil, Mexico, and South Korea present underpenetrated outpatient imaging infrastructure where dedicated breast care networks can capture screening-to-biopsy referral flows outside hospital systems.
- Artificial intelligence-integrated pathology workflows:Deep learning algorithms applied to whole-slide imaging of biopsy specimens are converging with laboratory information systems to compress diagnostic turnaround times from days to hours.
- Remote service telemetry:Predictive maintenance modules embedded in vacuum-assisted biopsy consoles enable manufacturers to unbundle service contracts and capture recurring revenue through cloud-connected device monitoring.
Industry Challenges
- Interventional radiology fellowship pipeline:Shortages of procedural specialists trained in ultrasound-guided core needle techniques are creating capacity constraints in community hospital settings where screening volumes exceed operator availability.
- 510(k) submission complexity:FDA premarket review timelines for novel biopsy needle designs have extended substantially, requiring extensive predicate device comparisons and mechanical testing protocols that delay commercialization schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breast Biopsy Market |
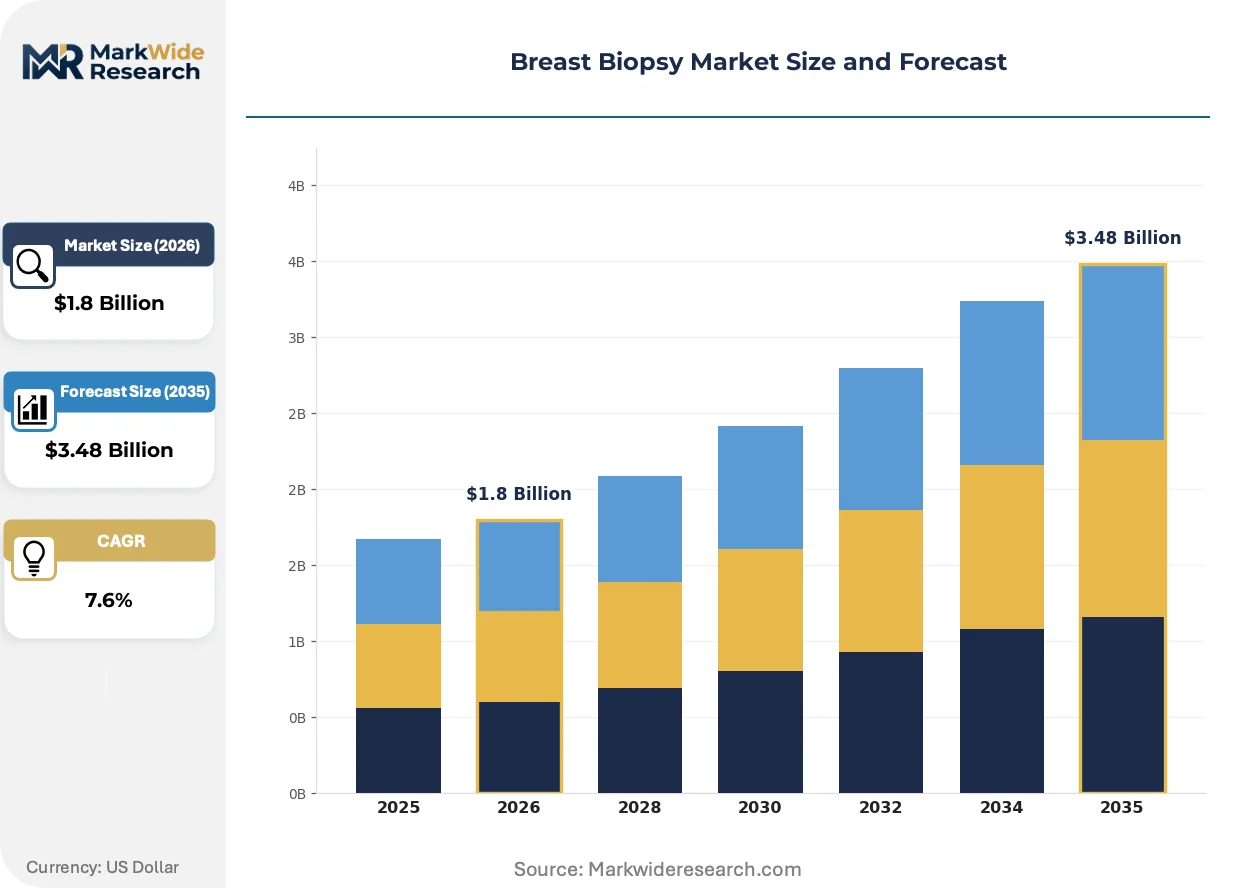
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Method: Fine Needle Aspiration, Core Needle, Vacuum-assisted, Surgical Product Type: Biopsy Needles, Imaging Systems, Markers, Biopsy Devices End User: Hospitals, Diagnostic Centers, Research Laboratories, Clinics Application: Cancer Diagnosis, Lesion Evaluation, Histopathological Analysis, Biopsy Guidance |
| Companies Covered | Hologic Inc., Becton Dickinson and Company, Danaher Corporation, Argon Medical Devices, Merit Medical Systems, Cook Medical, Siemens Healthineers, GE Healthcare, Mammotome Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breast Biopsy Market Emerging Trajectories
Device miniaturization and real-time imaging fusion are compressing the technical gap between diagnostic accuracy and patient throughput, forcing manufacturers to engineer systems that serve dual imperatives simultaneously.
Contrast-enhanced spectral mammography is migrating from research protocols into community hospital breast imaging departments. Radiology groups in the United Kingdom and Netherlands are adopting this technology to localize non-palpable lesions prior to biopsy. The shift is enabling more precise needle placement in dense breast tissue, reducing false-negative rates and supporting shorter procedure times.
EU MDR Article 10 technical documentation requirements are compelling manufacturers to generate clinical performance data for biopsy needle portfolios that previously relied on predicate equivalency. Device firms with legacy CE markings under the MDD must now conduct prospective studies or systematic literature reviews to support renewed certifications. Small and mid-size suppliers are responding by narrowing product ranges to concentrate resources on highest-volume SKUs.
Diagnostic centers are unbundling device procurement from long-term service agreements that historically locked purchasers into single-vendor ecosystems. Purchasing managers in Spain, Italy, and Australia are negotiating à la carte maintenance contracts and third-party calibration services. This pattern is most visible in mid-sized outpatient networks with sufficient technical staff to perform routine servicing internally.
Breast Biopsy Market Segmentation
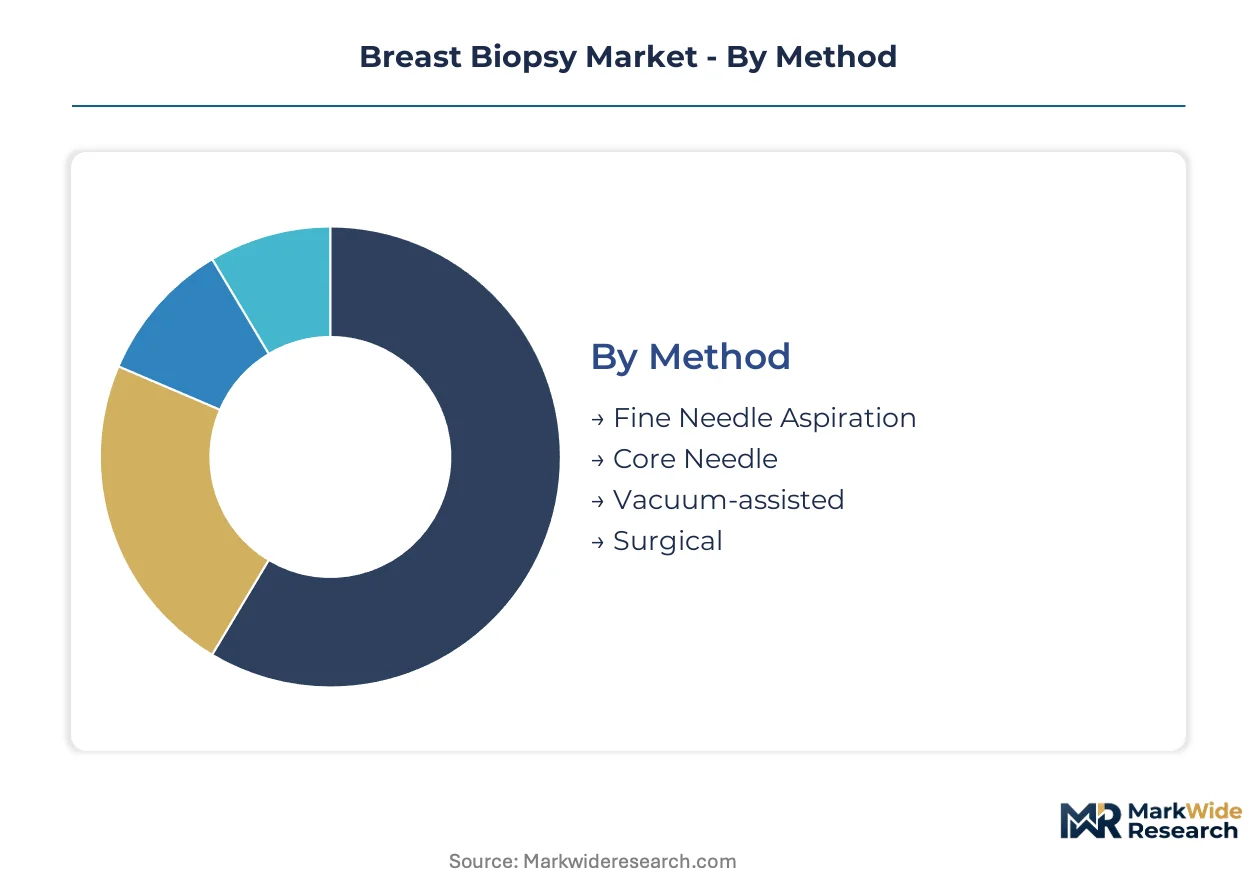
Segmentation in the breast biopsy market reveals how procurement decisions, clinical workflows, and reimbursement pathways diverge across technical methods and care settings. Understanding these partitions exposes where capital concentrates versus where volume expansion accelerates.
Method:
Cost tier stratification across biopsy methods determines capital intensity, consumable revenue streams, and site-of-service economics.
- Vacuum-assisted:Single-insertion systems harvest contiguous tissue cores through automated suction mechanisms, yielding specimens sufficient for immunohistochemical staining. Demand concentrates in United States outpatient diagnostic centers where bundled reimbursement favors lower repeat-procedure rates. Premium pricing reflects lower sampling error versus core needle alternatives.
- Core Needle:Spring-loaded or vacuum-assisted manual devices extract cylindrical tissue samples via 14-18 gauge needles under imaging guidance. Hospital radiology departments in Germany and France favor these systems for their balance of diagnostic yield and capital efficiency amid constrained equipment budgets.
- Fine Needle Aspiration:Cytological sampling via 21-25 gauge needles enables rapid on-site adequacy assessment with minimal tissue trauma. Resource-constrained clinics in Brazil and Mexico deploy these methods where pathology infrastructure limits histological processing capacity.
- Surgical:Excisional or incisional procedures under general anesthesia retrieve larger tissue volumes for definitive margin assessment. Academic medical centers reserve these for lesions with discordant imaging-pathology findings or patient-specific anatomical constraints.
Vacuum-assisted commands the established base. The steepest expansion runs through core needle methods as EU screening programs drive procedure volume without proportional capital budget growth.
Product Type:
Application-specific design requirements separate devices engineered for tissue acquisition from those optimized for lesion localization and imaging coordination.
- Biopsy Devices:Integrated console systems combining vacuum-assisted or core needle mechanisms with specimen collection chambers and real-time imaging interfaces. Diagnostic centers in South Korea and Australia prioritize these for throughput optimization in high-volume screening networks.
- Biopsy Needles:Disposable stainless steel or nitinol instruments ranging from 8-gauge vacuum cannulas to 25-gauge aspiration needles. United States manufacturers face margin pressure from specialty alloy price volatility concentrated in medical-grade wire feedstock markets.
- Imaging Systems:Stereotactic X-ray, ultrasound, and MRI-compatible guidance platforms with motorized needle positioning and 3D lesion localization. Hospital procurement teams in the United Kingdom bundle these into multi-year mammography platform agreements.
- Markers:Metallic or bioabsorbable clips deployed post-biopsy to flag lesion sites for subsequent surgical excision or surveillance imaging. European adoption accelerates under EU MDR requirements for traceable implantable device documentation.
Biopsy devices anchor installed base revenue through service contracts. The steepest climb belongs to markers as localization precision demands intensify alongside conservative management protocols.
End User:
Customer type dictates capital deployment cycles, reimbursement capture, and technical staffing requirements across the care continuum.
- Diagnostic Centers:Freestanding outpatient facilities specializing in breast imaging and image-guided procedures, often operating outside hospital cost structures. Networks in Spain and Italy are unbundling device procurement from long-term service agreements to negotiate à la carte maintenance.
- Hospitals:Integrated health systems with interventional radiology departments, surgical oncology services, and in-house pathology laboratories. United States hospitals consolidate biopsy capital purchases into imaging platform agreements that lock in preventive maintenance revenue.
- Clinics:Community-based primary care or women's health settings with limited imaging infrastructure, typically referring complex cases to specialized centers. These sites concentrate fine needle aspiration utilization where immediate cytological readout suffices.
- Research Laboratories:Academic and pharmaceutical trial sites conducting prospective studies on novel biomarker validation or device performance. EU MDR Article 10 clinical evidence requirements funnel contract research toward these facilities.
Hospitals retain the deepest installed base. The sharpest volume gains flow through diagnostic centers as regional screening networks expand access outside urban hospital catchments.
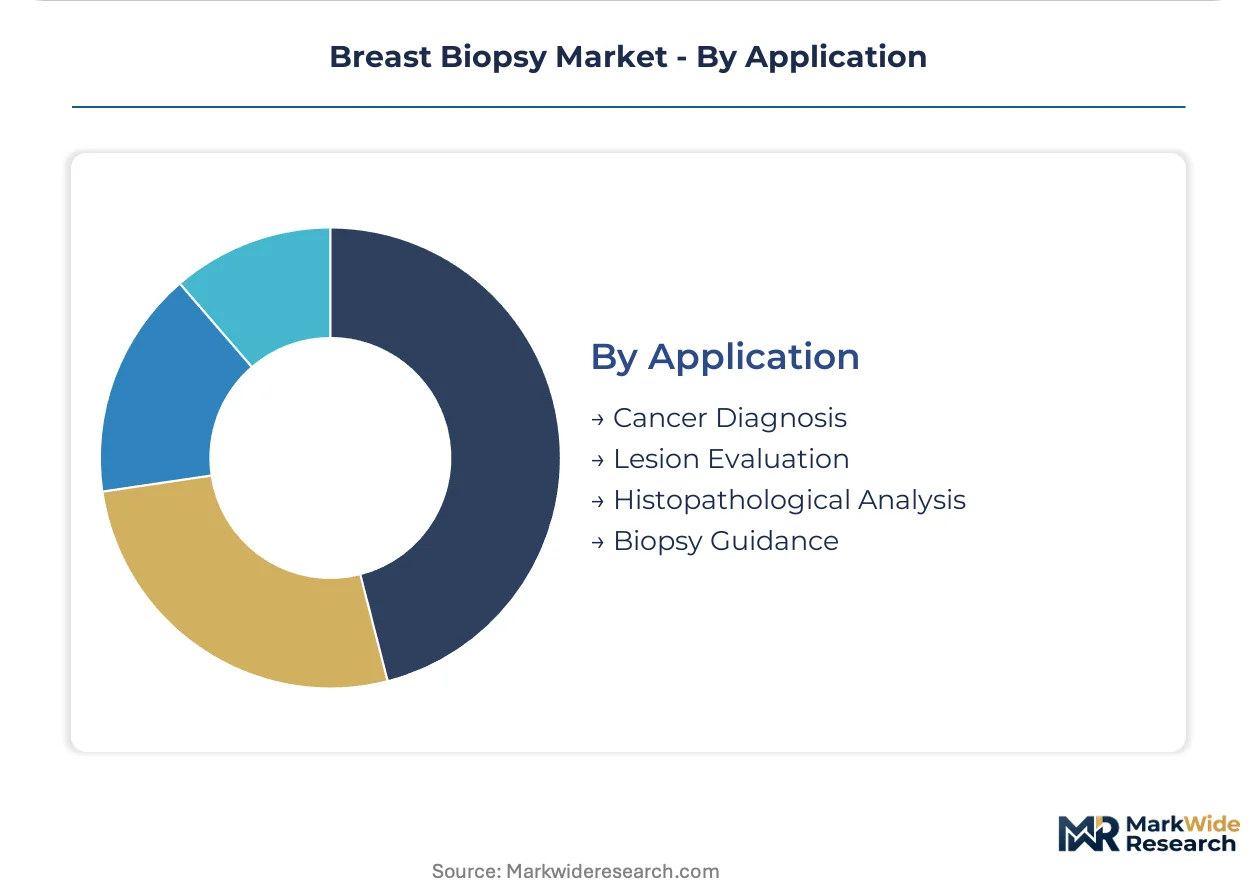
Application:
Volume distribution across clinical use cases tracks the progression from screening detection through definitive diagnosis and treatment planning.
- Cancer Diagnosis:Histopathological confirmation of malignancy to stage disease and guide therapeutic decisions including surgery, chemotherapy, or radiation. Screening program expansions in Japan and Germany directly lift procedure volumes for this indication.
- Lesion Evaluation:Characterization of imaging-detected abnormalities with indeterminate features to determine surveillance intervals versus intervention. Dense breast tissue protocols in the Netherlands and United Kingdom increasingly deploy contrast-enhanced spectral mammography prior to biopsy.
- Histopathological Analysis:Tissue acquisition for specialized studies including hormone receptor status, HER2 amplification, and genomic profiling. Academic medical centers drive demand for vacuum-assisted methods yielding sufficient material for multiplex testing.
- Biopsy Guidance:Real-time imaging coordination and needle navigation systems enabling precise targeting of non-palpable lesions. Artificial intelligence integration is compressing procedure times and reducing operator variability in high-throughput settings.
Cancer diagnosis holds the procedural volume base. The most rapid expansion tracks through lesion evaluation as screening sensitivity improvements generate more biopsy-eligible findings requiring characterization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket review standards anchor the United States as the procedural volume leader, while EU MDR Article 10 requirements reshape device certification timelines across European markets. National screening program expansions in Germany, France, and Japan directly lift hospital radiology department throughput.
United States
Breast cancer screening programs drive procedure volumes through hospital radiology departments and freestanding diagnostic centers. The FDA 510(k) pathway governs device premarket clearance with tightened mechanical testing protocols for novel needle designs. Hologic Inc. leverages its integrated mammography-to-biopsy platform to control upgrade cycles within installed bases concentrated in metropolitan hospital networks.
Germany
National breast cancer detection initiatives expand eligible age cohorts and shorten screening intervals, lifting core needle procedure volumes in hospital settings. EU MDR strengthened clinical evidence requirements accelerate replacement of legacy devices with next-generation systems. Siemens Healthineers anchors imaging system supply in Bavaria and North Rhine-Westphalia through bundled mammography platform agreements.
France
Screening program expansion drives diagnostic center buildout outside traditional hospital catchments. ANSM post-market surveillance mandates align with EU MDR technical documentation requirements for Class IIa biopsy needle classifications. Paris and Lyon metropolitan clusters concentrate vacuum-assisted device adoption as outpatient breast imaging networks expand regional access.
Japan
METI-coordinated national cancer control programs extend screening eligibility to younger demographic cohorts. PMDA device approval pathways require substantial predicate comparisons for needle mechanism innovations. Tokyo and Osaka medical device clusters concentrate interventional radiology capacity where screening volumes exceed operator availability in community hospital settings.
Brazil
Underpenetrated outpatient imaging infrastructure presents dedicated breast care network expansion opportunities outside hospital systems. ANVISA regulatory frameworks govern importation and clinical validation of vacuum-assisted biopsy consoles. São Paulo and Rio de Janeiro diagnostic centers concentrate fine needle aspiration utilization where pathology infrastructure limits histological processing capacity.
Breast Biopsy Market Vendor Landscape
Integrated imaging-device platforms and specialized needle portfolios split the market between ecosystem-locked vendors and component-focused suppliers. Three equipment vendors control the installed base of stereotactic guidance platforms in the United States, creating gatekeeper effects for complementary biopsy device placement. Strategic archetypes include full-stack imaging-to-biopsy integrators, disposable needle specialists, and workflow automation platform providers. Competitive moves concentrate on multi-year imaging platform bundling and predictive maintenance telemetry unbundling.
Among integrated platform vendors, Hologic Inc. and Siemens Healthineers exemplify the imaging-to-biopsy ecosystem archetype through mammography-to-biopsy console integration. Becton Dickinson and Company anchors the disposable needle specialist tier with deep portfolio coverage across core and vacuum-assisted methods. These three entities occupy positions that reflect divergent bets on capital intensity versus consumable recurring revenue capture.
| Leading Market Players |
|---|
| Hologic Inc. |
| Becton Dickinson and Company |
| Danaher Corporation |
| Argon Medical Devices |
| Merit Medical Systems |
| Cook Medical |
| Siemens Healthineers |
| GE Healthcare |
| Mammotome Inc. |
| Others |
Supply Flow & Price Mechanics
Medical-grade nitinol wire feedstock concentration in United States and German specialty alloy foundries anchors margin distribution downstream toward vacuum-assisted biopsy console manufacturers with captive needle production. Stainless steel price volatility propagates through disposable device portfolios, compressing margins for pure-play needle suppliers while integrated imaging-device vendors capture service-contract premiums.
Pricing Analysis
United States diagnostic centers pay 40-60% premiums over Brazilian clinics for identical vacuum-assisted biopsy consoles due to bundled service obligations and FDA-validated quality tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by imaging integration depth, with premium tiers commanding exclusivity through mammography-platform bundling. Cost compression in core needle segments intensifies because EU hospital procurement consolidates volume across fewer vendors. Price sensitivity peaks among freestanding diagnostic centers in Spain and Italy unbundling maintenance contracts, while United States hospital systems show lowest sensitivity due to locked-in upgrade cycles.
Supply Chain Analysis
United States export controls on precision wire-drawing equipment constrain Chinese and Russian manufacturers from replicating medical-grade nitinol cannula production. Supply concentrates in United States, Germany, and Japan for specialty alloy feedstock, with Taiwan and South Korea dominating precision needle grinding equipment. Raw material dependencies center on medical-grade stainless steel, nitinol shape-memory alloys, and polymer specimen collection chambers. Single-source vulnerability persists for 8-gauge vacuum cannula production where two German suppliers control global capacity. Distribution runs through hospital procurement committees and diagnostic center purchasing managers negotiating multi-year imaging platform agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where FDA 510(k) clearance histories and EU MDR quality management certifications erect decade-scale barriers against unproven entrants. Switching costs lock hospital radiology departments into imaging-device ecosystems that resist needle vendor substitution.
For Market Incumbents: Insulate installed-base revenue by embedding predictive maintenance telemetry into vacuum-assisted biopsy consoles, converting capital sales into recurring cloud-service streams. Deepen backward integration into medical-grade nitinol wire production to offset alloy price volatility threatening disposable margins. Counter emerging entrant pressure from AI-integrated pathology workflow startups by accelerating software companion submissions to FDA. For New Entrants and Emerging Players: Brazilian and Mexican outpatient imaging infrastructure presents the most penetrable white-space for dedicated breast care networks outside hospital procurement hierarchies. South Korean diagnostic center buildout offers secondary expansion terrain where imaging-device bundling remains less entrenched. Target fine needle aspiration device niches in resource-constrained Latin American clinics where pathology infrastructure gaps limit core needle adoption, then bridge toward vacuum-assisted systems through distributor partnerships with established imaging vendors. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across AI-integrated pathology software segments as cloud deployment models displace on-premise laboratory information systems. Five-to-ten year viability favors targets with FDA 510(k) predicate device libraries and EU MDR technical documentation portfolios already assembled. Monitor reimbursement parity negotiations between hospital-based and freestanding diagnostic center procedures as the signal for capital placement inflection; material shifts toward site-neutral payment would accelerate diagnostic center volume capture and reshape device vendor consolidation targets.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market access for novel needle designs against predicate-heavy review timelines. |
| CE Marking Pathway | Unlocks EU MDR-compliant distribution through strengthened clinical evidence documentation. |
| Hospital System Partnership | Secures multi-year imaging platform bundling that locks out competing needle vendors. |
| Software Companion Development | Integrates AI pathology workflows that compress diagnostic turnaround from days to hours. |
| Reimbursement Strategy | Captures site-of-service parity payments that favor freestanding diagnostic center placement. |
Methodological Framework
A standing panel of interventional radiologists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers provided ongoing calibration against secondary validation through FDA 510(k) clearance databases, EU MDR Article 10 technical documentation registries, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up procedure volume estimates triangulated with top-down imaging system installed base counts across the analysis window.
Scenario-bracketing framed demand projections across method, product type, end user, and application segmentation dimensions, with regional regulatory cluster overlays capturing FDA, EU MDR, PMDA, and ANVISA pathway divergences. CAGRs derived from fitted growth curves anchored to screening program expansion schedules and capital replacement cycles. Industry-specific inputs included alloy feedstock price indices and interventional radiology fellowship completion rates.
Practitioners should monitor EU MDR post-market surveillance enforcement intensity and United States site-of-service reimbursement rulemaking for early signals of device replacement acceleration or diagnostic center volume migration. Forecasts reflect assumptions of stable alloy supply and continued screening program eligibility expansions; material shifts in specialty metals trade policy or national cancer control program funding would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
United States Biopsy Devices Market
Diagnostic Devices
Sleep Apnea Diagnostic Systems Market
Diagnostic Devices
Diagnostic Ophthalmic Devices Market
Diagnostic Devices
Coronary Heart Disease Diagnostic Imaging Devices Market
Diagnostic Devices
Pelvic Floor Diagnostics Market
Diagnostic Devices
Non-Hospital-Based Point-Of-Care Diagnostic Products Market
Diagnostic Devices
Calprotectin Serum Immunoassay Market
Diagnostic Devices
Skin Moisture Detectors Market
Diagnostic Devices
Animal Pregnancy Test Kits Market
Diagnostic Devices
Ophthalmic Diagnostic Equipment Market
Diagnostic Devices
Digital Diagnostic Audiometer Market
Diagnostic Devices
PCR and Real-Time PCR Molecular Diagnostics Market
Diagnostic Devices
Contactless Vital Sign Monitoring Device Validation Test Platforms Market
Diagnostic Devices
Diagnostic Stopper Market
Diagnostic Devices
Global Dermatology Diagnostic Devices Market
Diagnostic Devices
Global Dental Caries Detectors Market