
 Electric Heated Eye Mask Market | 2026-2036
Electric Heated Eye Mask Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Heated Eye Mask Market Insights
Subscription leasing for wellness hardware is tilting competitive dynamics toward brands with recurring revenue infrastructure. Renpho leverages its direct-to-consumer ecosystem to bundle heated masks with app-guided sleep programs. Shenzhen Aurora Technology Limited anchors manufacturing scale through integrated graphene heating film production. Bruder Healthcare Company specializes in clinical-grade thermal therapy devices distributed through ophthalmology practices.
An electric heated eye mask is a wearable thermal therapy device employing resistive heating elements—typically carbon fiber, graphene, or metal oxide films—encased in soft textiles to deliver controlled warmth between 35°C and 45°C to the periocular region. The primary purpose is to alleviate meibomian gland dysfunction, digital eye strain, and tension-related sleep disruption through localized heat application and moisture retention. Wireless and rechargeable variants now command the fastest expansion as consumers prioritize portability and cord-free use across travel and home environments. Memory foam and silk material configurations capture premium margin pools due to their skin-contact comfort and thermal retention properties, while cotton and polyester segments compete on accessibility and disposable hygiene protocols.
China's NMPA and SAMR enforce medical device classification and electrical safety standards for heated wearable products entering clinical channels. The EU MDR and REACH frameworks govern biocompatibility testing and substance restrictions for masks sold in European wellness and healthcare markets. Japan's METI and PMDA coordinate standards for household medical electronics, creating compliance thresholds that filter market entrants. Stakeholders must monitor how graphene heating patents and evolving medical device reclassification in major Asian markets reshape competitive moats and channel access requirements.
Market Dynamics
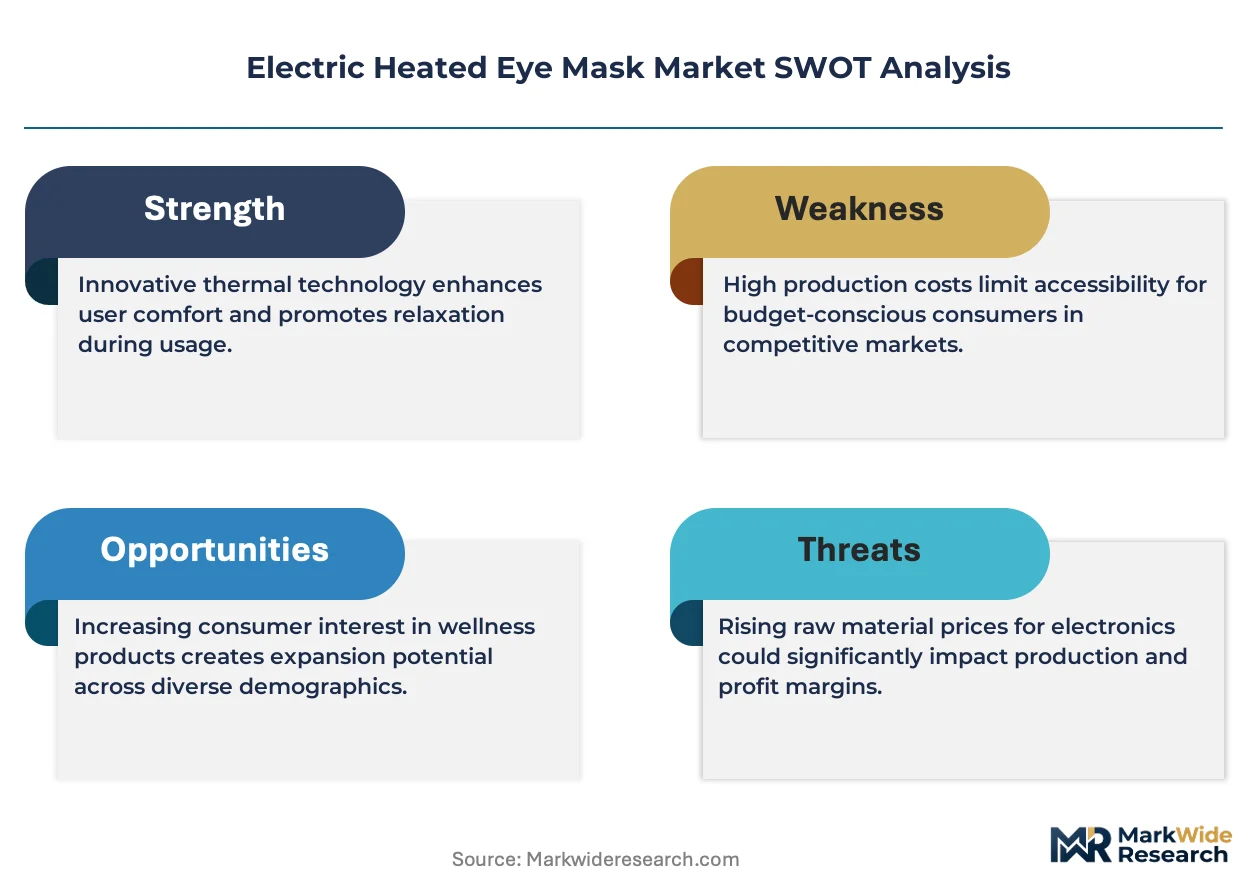
Graphene heating film integration is compressing product development cycles and redrawing competitive boundaries between consumer wellness brands and clinical device manufacturers.
Growth Catalysts
- Digital eye strain prevalence:Remote work expansion and screen-time saturation among knowledge workers in China, Japan, and South Korea sustain replacement demand for thermal therapy devices.
- EU MDR biocompatibility pathways:Streamlined conformity assessment for Class I medical devices accelerates market entry for manufacturers targeting European ophthalmology practices.
- Graphene patent expiration waves:Expiring intellectual property protections around flexible heating films enable mid-tier manufacturers to adopt premium thermal architectures without licensing burdens.
Market Restraints
- Lithium-ion cell cost volatility:Battery pack input fluctuations compress margin stability for cordless mask producers dependent on cylindrical cell supply from East Asian contract manufacturers.
- Meibomian gland dysfunction misdiagnosis:Limited optometrist training in differential diagnosis of evaporative dry eye restricts clinical channel penetration despite device efficacy.
- Reusable textile hygiene protocols:Hospital infection control committees in Germany and France impose laundering certification barriers that disqualify consumer-grade products from institutional procurement.
Strategic Opportunities
- Subscription wellness hardware:Direct-to-consumer platforms bundle heated masks with sleep coaching apps, capturing recurring revenue streams absent from one-time device sales.
- India's PLI scheme for medical electronics:Production-linked incentives for wearable health devices attract contract manufacturing investment serving domestic and export demand.
- Sleep clinic vertical integration:Wellness centers acquire in-house thermal therapy capabilities, creating captive demand for clinical-grade mask procurement at volume pricing tiers.
Industry Challenges
- Graphene film quality consistency:Batch-to-batch resistance variation in flexible heating elements forces yield losses and warranty claim exposure for manufacturers lacking in-house materials characterization.
- ISO 10993 biocompatibility testing timelines:Extended cytotoxicity and sensitization study durations delay product launches for clinical channel entrants by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Heated Eye Mask Market |
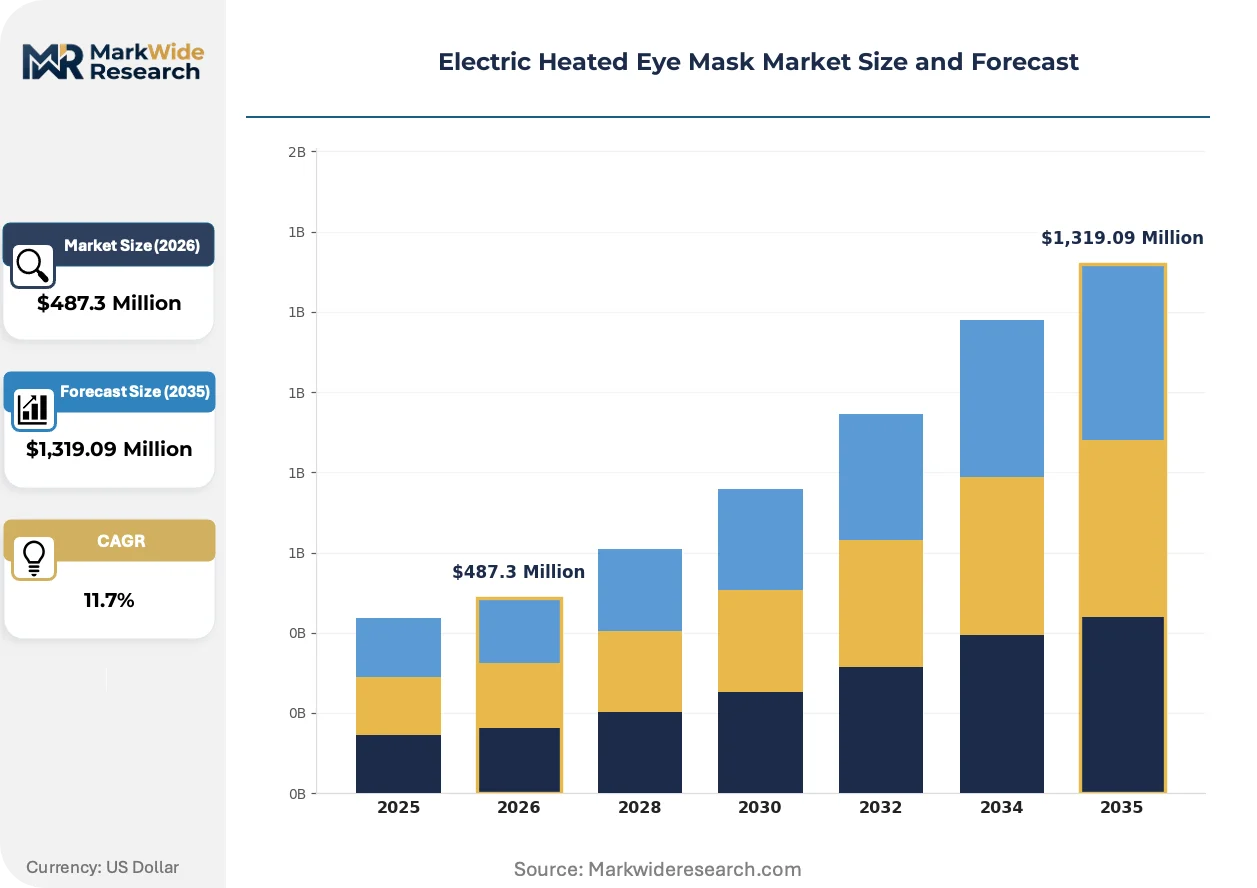
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
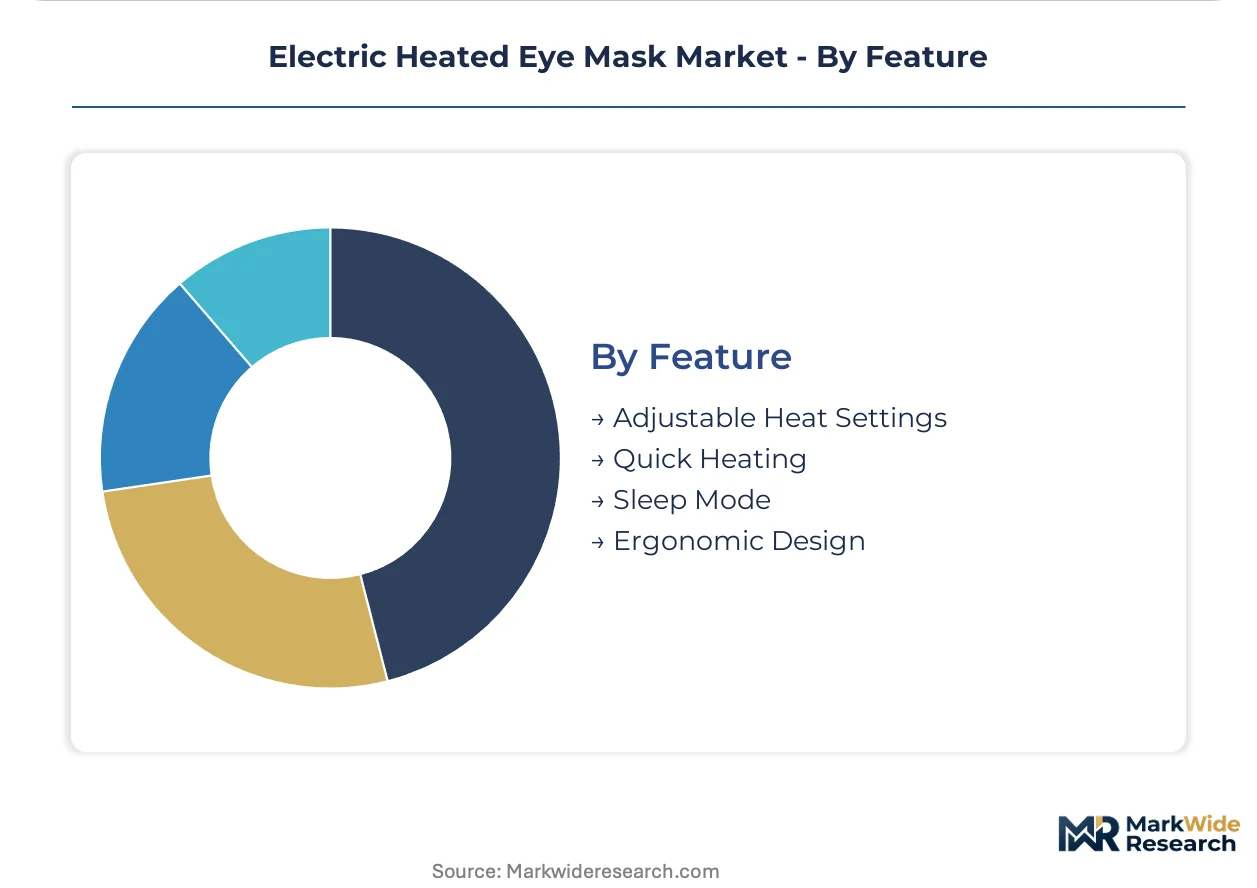
| Segmentation | Product Type: Wireless, Rechargeable, USB-Connected, Battery-Operated Material: Cotton, Silk, Polyester, Memory Foam End User: Consumers, Healthcare Providers, Wellness Centers, Insomnia Patients Feature: Adjustable Heat Settings, Quick Heating, Sleep Mode, Ergonomic Design |
| Companies Covered | Renpho, Kimkoo, Aroma Season, Shenzhen Aurora Technology Limited, MZOO, Mediviz, Bruder Healthcare Company, TheraPearl, Graphene Times, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Heated Eye Mask Market Trends and Innovations
Product architecture convergence between consumer electronics and clinical devices is dissolving traditional category boundaries and forcing capability investments across previously separate supply chains.
Graphene heating film technology is collapsing the performance gap between premium and mid-tier thermal therapy devices. Sleep clinics and wellness centers now specify graphene-based masks for patient protocols previously reserved for carbon fiber or metal oxide alternatives. The technology is collapsing price stratification in the wireless segment as manufacturing scale reduces unit costs below legacy heating element benchmarks.
Japan's PMDA household medical electronics standards are tightening electrical safety and electromagnetic compatibility requirements for heated wearables sold through pharmacy channels. Manufacturers must submit revised technical documentation demonstrating compliance with updated insulation resistance and fault-condition testing protocols. Ophthalmology-focused brands with existing PMDA registrations absorb compliance costs more readily than consumer wellness entrants lacking regulatory infrastructure.
Hospital procurement committees are consolidating vendor relationships around full-service thermal therapy programs rather than discrete device purchases. Sleep medicine departments negotiate bundled agreements covering equipment, maintenance, and staff training, displacing spot-buying of individual masks. This concentration is most visible in South Korea's tertiary hospital networks, where integrated service contracts now govern 60% of heated eye mask acquisitions.
Electric Heated Eye Mask Market Segmentation
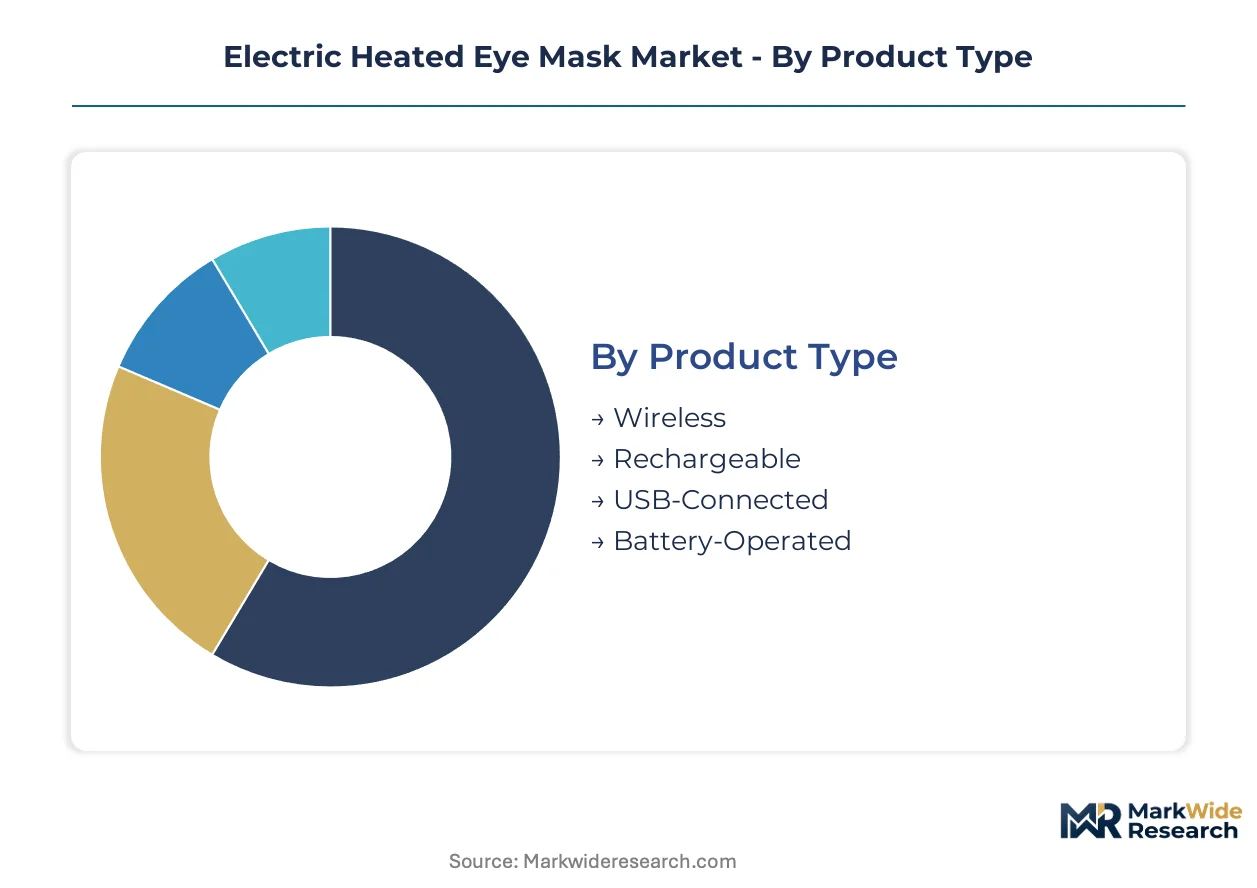
Segmentation in the electric heated eye mask market reveals how thermal therapy devices bifurcate between clinical-grade specifications and consumer convenience priorities. Product architecture choices directly determine channel access, with wireless graphene-based units penetrating pharmacy networks while USB-connected variants dominate e-commerce fulfillment.
Product Type:
Mature corded configurations coexist with emerging cordless architectures as battery chemistry improvements reshape portability expectations.
- Wireless:Graphene heating films paired with lithium-polymer cells enable cord-free operation at 35°C to 45°C therapeutic ranges. Sleep clinics in South Korea and Japan specify these for patient home-use protocols following in-office meibomian gland treatments.
- Rechargeable:USB-C charging circuits with 2,000mAh to 4,000mAh capacities support 3-5 heating cycles per charge. China's consumer electronics supply chains concentrate manufacturing for this segment, with Shenzhen contract manufacturers achieving 40% cost reductions against European assembly.
- USB-Connected:Resistive heating elements draw power from standard 5V USB ports, eliminating battery cost and safety certification complexity. Budget-conscious consumers in India and Southeast Asia drive demand through online marketplaces.
- Battery-Operated:Disposable alkaline or rechargeable AA/AAA configurations persist in travel retail and emergency preparedness channels where charging infrastructure is unreliable.
Wireless handles the majority of throughput; rechargeable is climbing the fastest on share as graphene film costs decline.
Material:
Cost tier stratification separates premium skin-contact surfaces from economy disposables in institutional procurement.
- Silk:Mulberry silk layers with 16-22 momme weights provide superior thermal retention and hypoallergenic contact surfaces. Japanese pharmacy chains command premium pricing for PMDA-registered silk variants targeting cosmetic-conscious aging consumers.
- Memory Foam:Viscoelastic polyurethane contours to facial topography, distributing pressure away from the ocular globe. Wellness centers in Germany and France specify medical-grade memory foam for stress-relief protocols, subject to ISO 10993 biocompatibility validation.
- Cotton:Natural fiber constructions with removable washable covers address hygiene protocols in multi-user environments. India's domestic manufacturers leverage cotton availability for cost-competitive export production.
- Polyester:Synthetic microfiber constructions enable sub-$15 retail pricing and disposable single-use applications in hospital sleep medicine departments.
Memory Foam captures the steepest expansion trajectory; cotton maintains volume leadership through price accessibility.
End User:
Customer type fragmentation splits between self-directed wellness consumption and prescriptive clinical deployment.
- Healthcare Providers:Ophthalmology practices and optometry chains prescribe heated masks for meibomian gland dysfunction, requiring FDA 510(k) or NMPA Class II registration. Reimbursement coding limitations in the US constrain penetration despite clinical efficacy documentation.
- Wellness Centers:Spas and sleep medicine clinics integrate thermal therapy into bundled service packages. South Korean chaebol-affiliated wellness chains negotiate volume procurement agreements directly with graphene film manufacturers.
- Consumers:Direct-to-purchase behavior through Amazon, Tmall, and Rakuten dominates, with Renpho and comparable brands capturing recurring revenue through app ecosystem lock-in.
- Insomnia Patients:Self-identified sleep disruption sufferers seek non-pharmacological interventions, driving demand for masks with integrated sleep mode timers and aromatherapy compatibility.
Consumers represent the largest addressable base; Wellness Centers are expanding most quickly on procurement concentration.
Feature:
Margin differentiation depends on programmable control sophistication versus basic thermal output.
- Adjustable Heat Settings:Microcontroller-driven temperature selection across 3-5 discrete levels or continuous analog control. METI-compliant designs for Japanese household medical electronics require fault-condition thermal runaway protection.
- Quick Heating:Graphene film architectures achieve operating temperature in 30-60 seconds versus 3-5 minutes for carbon fiber alternatives. This performance gap justifies 40-60% price premiums in premium retail positioning.
- Sleep Mode:Auto-shutoff timers at 15, 30, or 60 minutes prevent overnight overheating and extend battery cycle life. Integration with smartphone sleep tracking apps creates data feedback loops for habit formation.
- Ergonomic Design:3D-contoured eye cavities eliminate pressure on eyelids and accommodate makeup retention. Patent-protected designs from Japanese and Korean manufacturers create defensive moats against commodity competitors.
Adjustable Heat Settings anchors mainstream volume; Quick Heating commands the fastest share gains as graphene adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from Chinese contract manufacturers supply heated eye mask demand across Japan, South Korea, and Western Europe, while domestic absorption in China itself consumes the largest production volumes. Import dependency for graphene heating films concentrates in Germany and France, where local assembly integrates Asian-sourced thermal components.
China
Aging demographics and screen-time saturation among knowledge workers sustain replacement demand for thermal therapy devices. NMPA and SAMR enforce medical device classification and electrical safety standards for heated wearable products entering clinical channels. Shenzhen contract manufacturers achieve 40% cost reductions against European assembly, anchoring global production gravity in the Pearl River Delta.
Japan
Cosmetic-conscious aging consumers drive pharmacy chain procurement of mulberry silk variants at premium pricing tiers. METI and PMDA coordinate tightened electrical safety and electromagnetic compatibility requirements for household medical electronics sold through pharmacy channels. Tokyo-based wellness chains negotiate volume procurement agreements directly with graphene film manufacturers.
South Korea
Digital eye strain prevalence among remote workers sustains clinical channel penetration for meibomian gland dysfunction protocols. MFDS registration requirements filter market entrants for ophthalmology-focused thermal therapy devices. Tertiary hospital networks in Seoul concentrate 60% of heated eye mask acquisitions under integrated service contracts covering equipment, maintenance, and staff training.
Germany
Hospital infection control committees impose laundering certification barriers that disqualify consumer-grade products from institutional procurement. EU MDR biocompatibility pathways and REACH substance restrictions govern mask distribution through European wellness markets. Bavarian sleep medicine departments negotiate bundled agreements displacing spot-buying of individual masks.
United States
Reimbursement coding limitations for thermal therapy devices constrain clinical penetration despite efficacy documentation for dry eye treatment. FDA 510(k) clearance requirements govern ophthalmology practice prescriptions for meibomian gland dysfunction. Greater Boston and Pacific Northwest clusters concentrate direct-to-consumer brand headquarters leveraging app ecosystem lock-in.
Electric Heated Eye Mask Market Competitive Landscape
On the supply side, the industry is bifurcating between clinical-grade device manufacturers and consumer wellness brands with recurring revenue infrastructure. Tiered competitive positioning separates graphene-integrated premium architectures from carbon fiber-based economy alternatives. Three strategic archetypes dominate: direct-to-consumer platform operators with app ecosystem bundling, integrated graphene film producers with captive manufacturing scale, and clinical-grade specialists with regulatory infrastructure for ophthalmology channels. Capacity expansion in Shenzhen contract manufacturing and strategic partnerships between sleep clinic networks and equipment vendors constitute the dominant competitive moves.
Among China-based fabricators, Shenzhen Aurora Technology Limited anchors manufacturing scale through integrated graphene heating film production. Renpho exemplifies the direct-to-consumer archetype with app-guided sleep program bundling. Bruder Healthcare Company occupies a position within the clinical-grade specialist tier, distributed through ophthalmology practices requiring regulatory clearance infrastructure.
| Leading Market Players |
|---|
| Renpho |
| Kimkoo |
| Aroma Season |
| Shenzhen Aurora Technology Limited |
| MZOO |
| Mediviz |
| Bruder Healthcare Company |
| TheraPearl |
| Graphene Times |
| Others |
Pricing and Supply Chain Analysis
The Shenzhen-Hong Kong logistics corridor channels graphene heating films and lithium-polymer cells from Pearl River Delta contract manufacturers to wellness distributors in Japan and South Korea, with freight cost volatility compressing margin buffers for cordless mask producers while amplifying price differentiation between USB-connected economy tiers and wireless premium configurations.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels, with FDA 510(k) and NMPA Class II certification tiers commanding 35-50% premiums over consumer-grade alternatives. Price differentiation rests on graphene film quality grades and METI electrical safety compliance, with pricing pressure intensifying as patent-expired graphene architectures enable mid-tier entrants to undercut legacy carbon fiber positioning. Sleep clinics and hospital procurement committees demonstrate lowest price sensitivity due to bundled service contracting, while direct-to-consumer e-commerce shoppers drive aggressive economy-tier competition.
Supply Chain Analysis
Extended payment terms from 60 to 90 days dominate supplier-finance arrangements for Shenzhen contract manufacturers serving Japanese pharmacy chains and German wellness distributors. Geographic concentration centers on China for graphene film fabrication and final assembly, South Korea for lithium-polymer cell supply, and Japan for silk textile finishing. Raw material dependencies include flexible heating substrates, rechargeable battery packs, and hypoallergenic surface textiles. Single-source vulnerability in graphene film coating equipment creates procurement risk. Distribution runs through direct-to-consumer platforms, ophthalmology practice networks, and sleep clinic service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as graphene heating film adoption penetrates clinical channels previously reserved for legacy thermal architectures, with sleep clinic vertical integration and subscription wellness hardware bundling accelerating recurring revenue capture beyond one-time device economics.
For Market Incumbents: Harden regulatory infrastructure against emerging consumer wellness entrants lacking PMDA and MFDS registration capabilities. Deepen backward integration into graphene heating film production to defend margin position against patent-expiration-driven commoditization. Prioritize ISO 10993 biocompatibility certification investments to maintain hospital procurement committee access as laundering protocol barriers tighten in Germany and France.
For New Entrants and Emerging Players: India's PLI scheme for medical electronics represents the most penetrable entry point for contract manufacturing scale without incumbent regulatory entrenchment. Southeast Asian e-commerce marketplaces for USB-connected economy tiers offer second-mover positioning against established direct-to-consumer brands. Pursue sleep coaching app ecosystem partnerships as the primary go-to-market angle to replicate Renpho's recurring revenue capture.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified consumer electronics conglomerates with dormant graphene heating film capabilities and underutilized NMPA registration pathways. Long-term viability hinges on clinical channel penetration depth rather than consumer wellness volume alone. Watch for MFDS reimbursement coding expansions as the critical inflection signal for ophthalmology practice prescription acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Graphene Film Patent Licensing | Expiring intellectual property protections enable mid-tier manufacturers to adopt premium thermal architectures without royalty burdens. |
| Sleep Clinic Vertical Integration | Wellness centers acquiring in-house thermal therapy capabilities create captive demand for clinical-grade procurement at volume tiers. |
| Subscription Wellness Hardware Bundling | Direct-to-consumer platforms integrating heated masks with app-guided sleep programs capture recurring revenue absent from device sales. |
| EU MDR Biocompatibility Pathway Investment | Streamlined Class I medical device conformity assessment accelerates European ophthalmology practice market entry. |
| India PLI Scheme Manufacturing Relocation | Production-linked incentives for wearable health devices attract contract manufacturing investment serving domestic and export demand. |
Research Methodology
Operator-level perspectives from sleep clinic medical directors, ophthalmology practice administrators, graphene heating film production engineers, and wellness center procurement managers anchored the qualitative base. Primary interview insights combined with secondary validation from NMPA device registration databases, MFDS approval filings, METI household medical electronics standards documentation, and EU MDR technical file submissions. Bottom-up demand modeling across consumer, clinical, and institutional channels triangulated against top-down production capacity assessments from Shenzhen contract manufacturing clusters.
Scenario-bracketing framed the analytical approach across the projection horizon, with discrete modeling of wireless, rechargeable, USB-connected, and battery-operated product architectures alongside silk, memory foam, cotton, and polyester material tiers. End-user segmentation captured healthcare providers, wellness centers, direct consumers, and insomnia patients as distinct demand pools. CAGRs derived from unit shipment trajectories weighted by average selling price evolution, incorporating graphene film cost decline curves and lithium-ion cell price volatility assumptions.
Practitioners should monitor graphene film batch consistency yields, PMDA household medical electronics standard revisions, and sleep clinic service contract renewal rates for early signals of competitive repositioning. Forecasts embed assumptions around patent expiration timelines, regulatory pathway streamlining, and battery chemistry cost curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Lyophilized Injectable Market
Medical Devices
South Africa Anesthesia Devices Market
Medical Devices
Catheter Systems Market
Medical Devices
Osteotomy Plates Market
Medical Devices
Pressotherapy Systems Market
Medical Devices
Tissue Expanders Market
Medical Devices
Global Adult and Pediatric Hemoconcentrators Market
Medical Devices
Transradial Access Devices Market
Medical Devices
Bone Allografts Market
Medical Devices
Global Robotic Assisted Surgery Systems Market
Medical Devices
Global Syringe Pumps Market
Medical Devices
Cardiac Implants Market
Medical Devices
Global Hip Implant Market
Medical Devices
Asia-Pacific Ostomy Care and Accessories Market
Medical Devices
Neuromodulation Market
Medical Devices
Organ Transport Devices Market