
 High Volume Dispensing Systems Market | 2026-2036
High Volume Dispensing Systems Market Size, Share, and Industry Trends Forecast 2026-2036
High Volume Dispensing Systems Market Outlook
Pharmaceutical manufacturing is broadening its share of high volume dispensing system procurement as oral solid dose and sterile injectable producers scale batch automation. Swisslog Healthcare leverages vertical integration across pharmacy automation hardware and software to sustain enterprise contracts with hospital networks. Becton Dickinson and Co. anchors its position through R&D intensity in closed-system drug transfer devices. McKesson Corporation competes via channel control over distribution networks that bundle dispensing technology with pharmaceutical supply contracts.
High volume dispensing systems are precision-engineered equipment designed to transfer measured quantities of liquids, powders, or semi-solids at throughputs exceeding manual operator capacity, typically incorporating servo-driven pumps, load cells, and programmable logic controllers to achieve repeatability within plus-or-minus one percent. Their primary industrial purpose is to eliminate batch-to-batch variability while maintaining containment in pharmaceutical, food, and chemical processing environments. Automated dispensers dominate installed base value due to capital intensity and integration with manufacturing execution systems, while liquid dispensing systems capture expanding share as biologics and sterile formulations multiply. Pressure-driven technology leads in pharmaceutical batch production where inert gas propulsion prevents oxidation, whereas vacuum-assisted systems are displacing gravity-feed configurations in high-potency powder handling where operator exposure limits apply.
FDA 21 CFR Part 11 electronic records requirements shape software architecture and validation protocols for systems deployed in United States pharmaceutical facilities, while EMA Annex 15 qualification standards and EU GMP guidelines drive comparable documentation burdens across European manufacturing sites. OSHA containment regulations and EPA environmental exposure thresholds further constrain equipment design for chemical processing applications. Stakeholders must monitor evolving serialization mandates and traceability requirements as regulators tighten supply chain integrity enforcement without specifying implementation timelines.
Market Dynamics
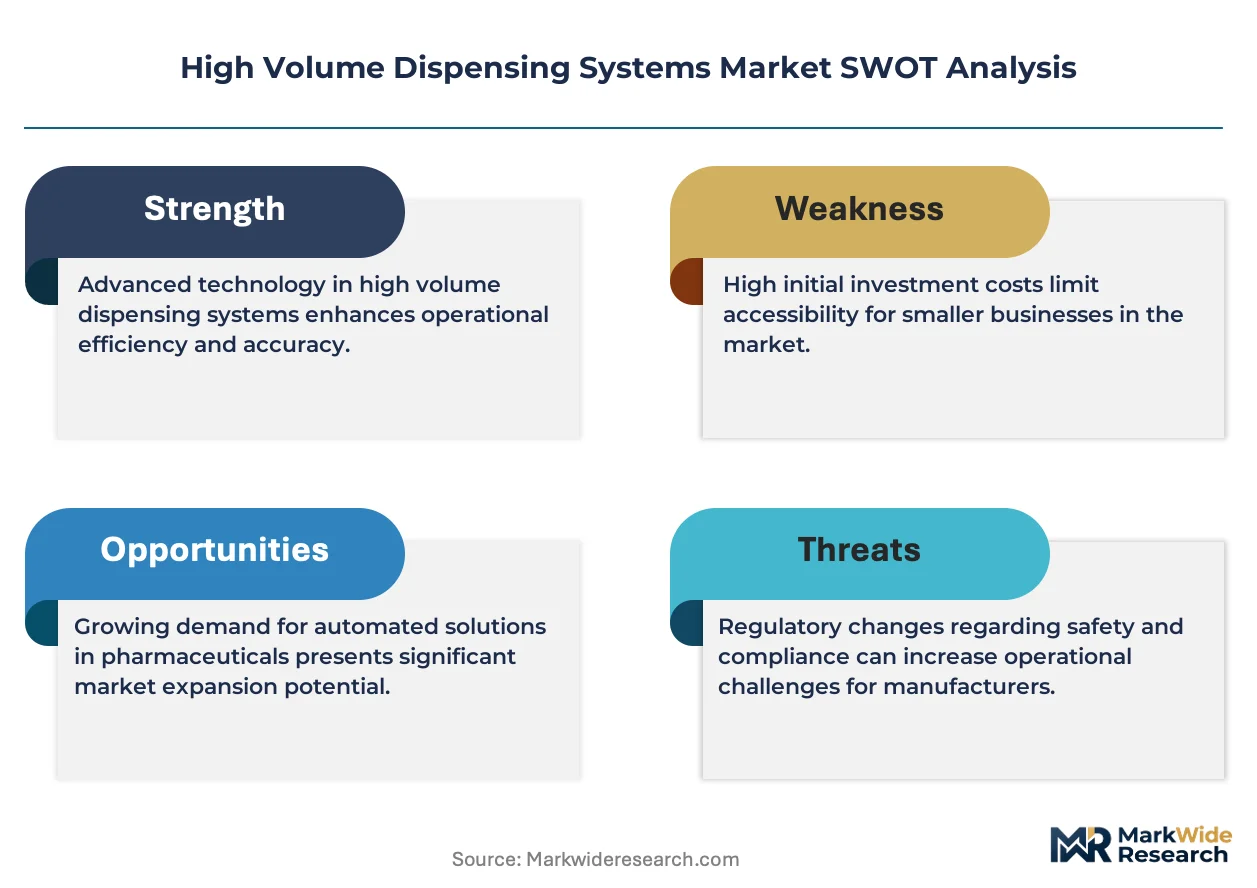
Serialization mandates across pharmaceutical supply chains are forcing manufacturers to replace legacy batch equipment with integrated dispensing platforms capable of real-time track-and-trace data capture, creating a replacement cycle independent of capacity expansion.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records and signature requirements in the United States are compelling pharmaceutical facilities to validate automated dispensing systems with audit-trail capabilities, accelerating capital deployment toward compliant platforms.
- Biologics manufacturing scale-up:Sterile injectable producers are installing pressure-driven liquid dispensing systems to handle shear-sensitive protein formulations at commercial batch volumes previously served by manual compounding.
- Contract manufacturing concentration:Germany's dense cluster of CDMOs is absorbing multi-line dispensing installations to service serialized packaging demands from multinational pharmaceutical clients.
Market Restraints
- Stainless steel and precision servo motor costs:Raw material price volatility for pharmaceutical-grade 316L stainless steel and Japanese-sourced motion control components compresses system margins and extends quoting cycles.
- Validation timeline elongation:EMA Annex 15 qualification protocols in Europe require extensive installation and operational qualification documentation, stretching project durations to 18-24 months from order.
- Modular benchtop systems:Lower-throughput, reconfigurable dispensing workstations threaten fixed-installation high-volume systems in mid-scale batch applications below 10,000 liter annual volume.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO's tightening GMP enforcement and the PLI scheme for active pharmaceutical ingredients create demand for contained powder dispensing systems in high-potency API facilities.
- Cell and gene therapy fill-finish:Precision micro-volume dispensing convergence with isolator technology opens addressable market in personalized medicine manufacturing suites requiring single-batch flexibility.
- Outcome-based service contracts:Equipment vendors are repositioning capital sales into throughput-guaranteed arrangements where payment ties to validated doses dispensed, penetrating budget-constrained hospital pharmacy central fill operations.
Industry Challenges
- Mechatronics engineering scarcity:The intersection of pharmaceutical process knowledge and precision motion control programming remains critically understaffed, extending commissioning timelines and forcing reliance on OEM field service.
- Legacy MES integration:Brownfield pharmaceutical plants running 1990s-era manufacturing execution systems face protocol incompatibility with modern dispensing controllers, requiring costly middleware development or full MES replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Volume Dispensing Systems Market |
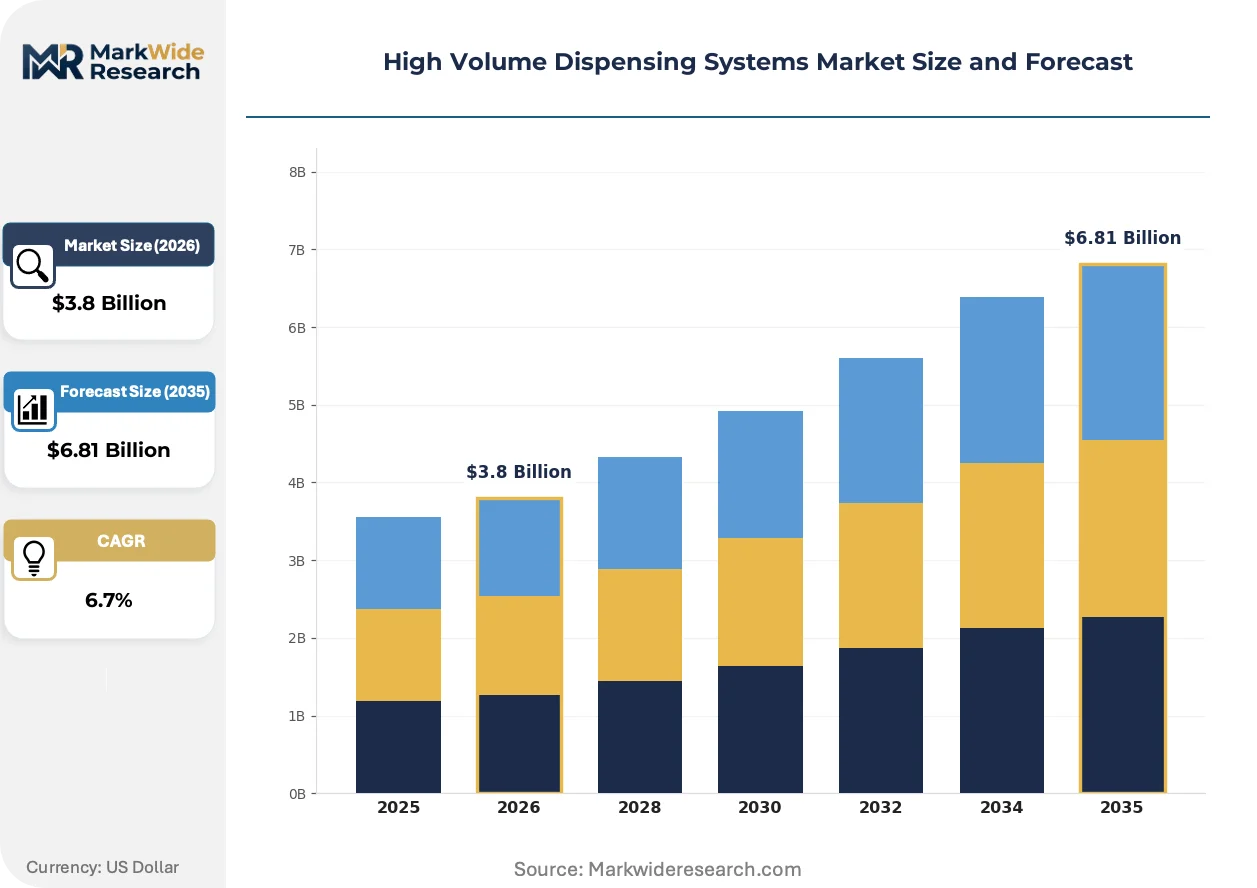
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Dispensers, Manual Dispensers, Liquid Dispensing Systems, Powder Dispensing Systems End User: Pharmaceutical Manufacturers, Food and Beverage Industry, Chemical Processing Plants, Research Laboratories Technology: Pressure-Driven, Gravity-Feed, Vacuum-Assisted, Sonic Dispensing Application: Batch Production, Continuous Production, Laboratory Use, Product Sampling |
| Companies Covered | Swisslog Healthcare, Becton Dickinson and Co., McKesson Corporation, TCGRx, Innovation Associates, Omnicell Inc., ARxIUM Inc., Graco Inc., ScriptPro LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Volume Dispensing Systems Market Strategic Shifts
Equipment architecture is pivoting from standalone mechanical systems to data-centric platforms where dispensing precision becomes inseparable from supply chain traceability and predictive maintenance capabilities.
Closed-system drug transfer devices with integrated barrier isolation technology are absorbing contamination control requirements previously addressed by separate cleanroom infrastructure. Sterile injectable manufacturers in the United States and Switzerland are adopting these platforms to reduce facility classification burdens while maintaining EU GMP Annex 1 compliance for aseptic processing. The technology is absorbing capital budget allocations that previously funded environmental monitoring and personnel garbing systems.
EMA's revised Annex 15 on qualification and validation, effective across European manufacturing sites, mandates continuous process verification rather than traditional three-batch qualification. This policy shift forces dispensing system vendors to embed process analytical technology sensors and real-time release testing algorithms into standard equipment configurations. High-volume parenteral facilities in Germany and Ireland are responding by specifying platforms with pre-validated control system architectures to compress regulatory submission timelines.
Hospital network procurement departments are consolidating dispensing equipment purchasing through group purchasing organizations, unbundling aftermarket service from initial capital acquisition. This behavioral shift compresses vendor margins on installation and training while creating independent service provider channels in North American acute care markets. The concentration of buying power within ten major United States health systems is most visible in centralized pharmacy automation tenders where total cost of ownership models displace equipment-centric evaluation criteria.
High Volume Dispensing Systems Market Segmentation
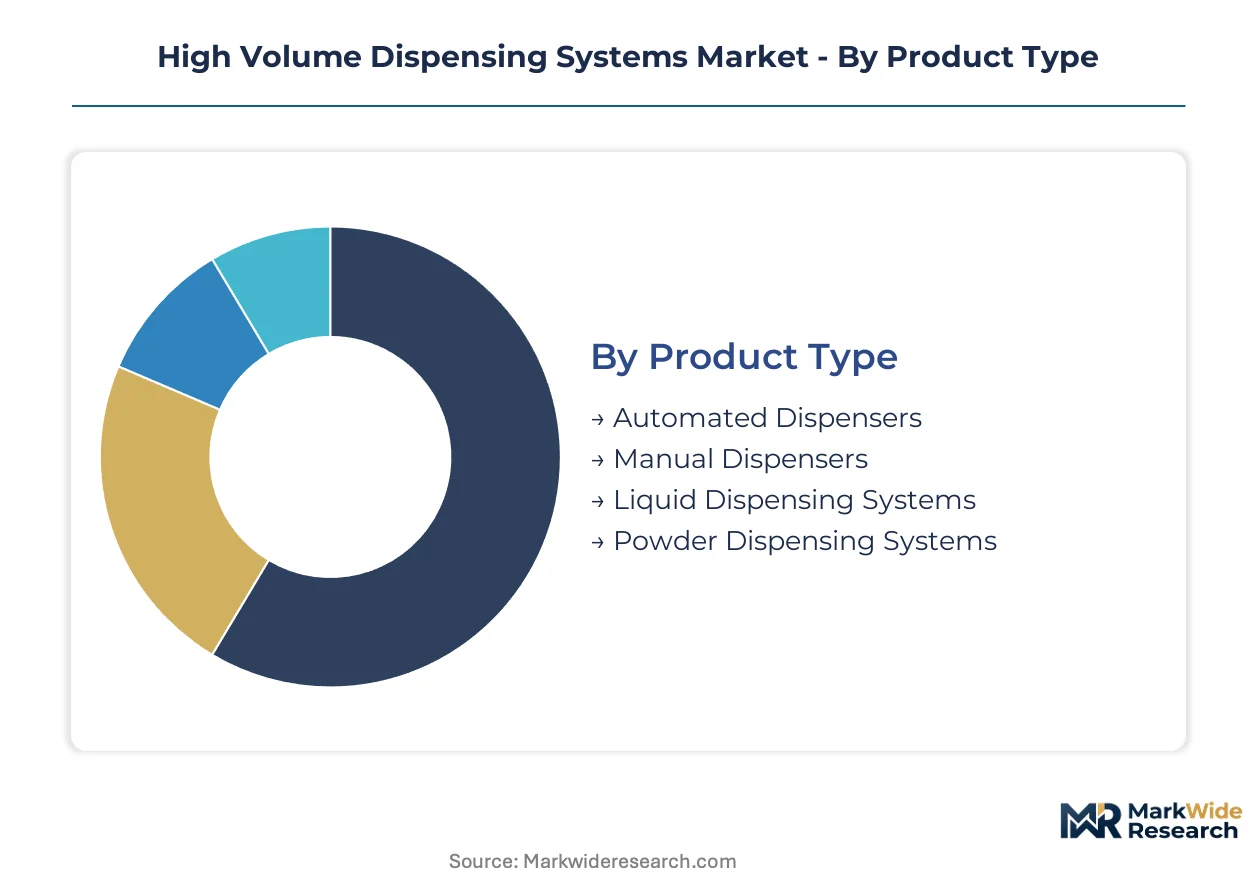
Dispensing system architectures diverge sharply across pharmaceutical, food, and chemical environments, with regulatory compliance and batch scale dictating technology selection. Each segmentation axis reveals distinct procurement patterns tied to containment requirements, automation maturity, and integration complexity with manufacturing execution systems.
Product Type:
Pressure-driven servo architectures and closed-system containment specifications define the technology tiering across product categories.
- Automated Dispensers:These systems integrate programmable logic controllers, servo-driven pumps, and real-time data capture for FDA 21 CFR Part 11 compliance. Pharmaceutical manufacturers in the United States deploy these platforms to satisfy serialization mandates while eliminating batch-to-batch variability through load cell feedback loops.
- Liquid Dispensing Systems:Pressure-driven configurations dominate sterile injectable production, where inert gas propulsion prevents oxidation of shear-sensitive protein formulations. Biologics manufacturers in Germany and Switzerland specify these systems for commercial batch volumes previously served by manual compounding.
- Manual Dispensers:Basic mechanical systems persist in low-volume research settings and developing-market facilities with limited capital budgets.
- Powder Dispensing Systems:Vacuum-assisted technology is displacing gravity-feed configurations in high-potency API handling where OSHA containment regulations limit operator exposure.
Mature deployment sits with automated dispensers. Newer deployment is concentrated in liquid dispensing systems.
End User:
Customer procurement authority and validation burden intensity separate the end-user tiers.
- Pharmaceutical Manufacturers:These facilities demand the highest specification tiers, with EMA Annex 15 qualification protocols stretching project durations to 18-24 months. CDMO clusters in Germany absorb multi-line installations to service serialized packaging demands from multinational clients.
- Chemical Processing Plants:EPA environmental exposure thresholds and OSHA containment regulations constrain equipment design for hazardous material handling. Stainless steel 316L construction and precision servo motors dominate specifications despite raw material price volatility.
- Food and Beverage Industry:Hygienic design standards and clean-in-place compatibility drive specification, though validation timelines remain shorter than pharmaceutical equivalents.
- Research Laboratories:Modular benchtop systems threaten fixed-installation high-volume platforms in mid-scale batch applications below 10,000 liter annual volume.
Revenue concentration rests with pharmaceutical manufacturers. Procurement volume is expanding fastest in chemical processing plants.
Technology:
Propulsion mechanism determines containment integrity, shear sensitivity, and integration with isolator technology.
- Pressure-Driven:Inert gas propulsion systems lead pharmaceutical batch production where oxidation prevention is critical. These platforms capture expanding share as biologics manufacturing scales up.
- Vacuum-Assisted:Negative pressure configurations dominate high-potency powder handling, absorbing contamination control requirements previously addressed by separate cleanroom infrastructure.
- Gravity-Feed:Simple mechanical systems retain position in non-hazardous liquid applications with minimal containment requirements.
- Sonic Dispensing:Ultrasonic propulsion enables precision micro-volume delivery for cell and gene therapy fill-finish applications requiring single-batch flexibility.
Pressure-driven technology holds the largest installed base. Sonic dispensing represents the steepest expansion trajectory.
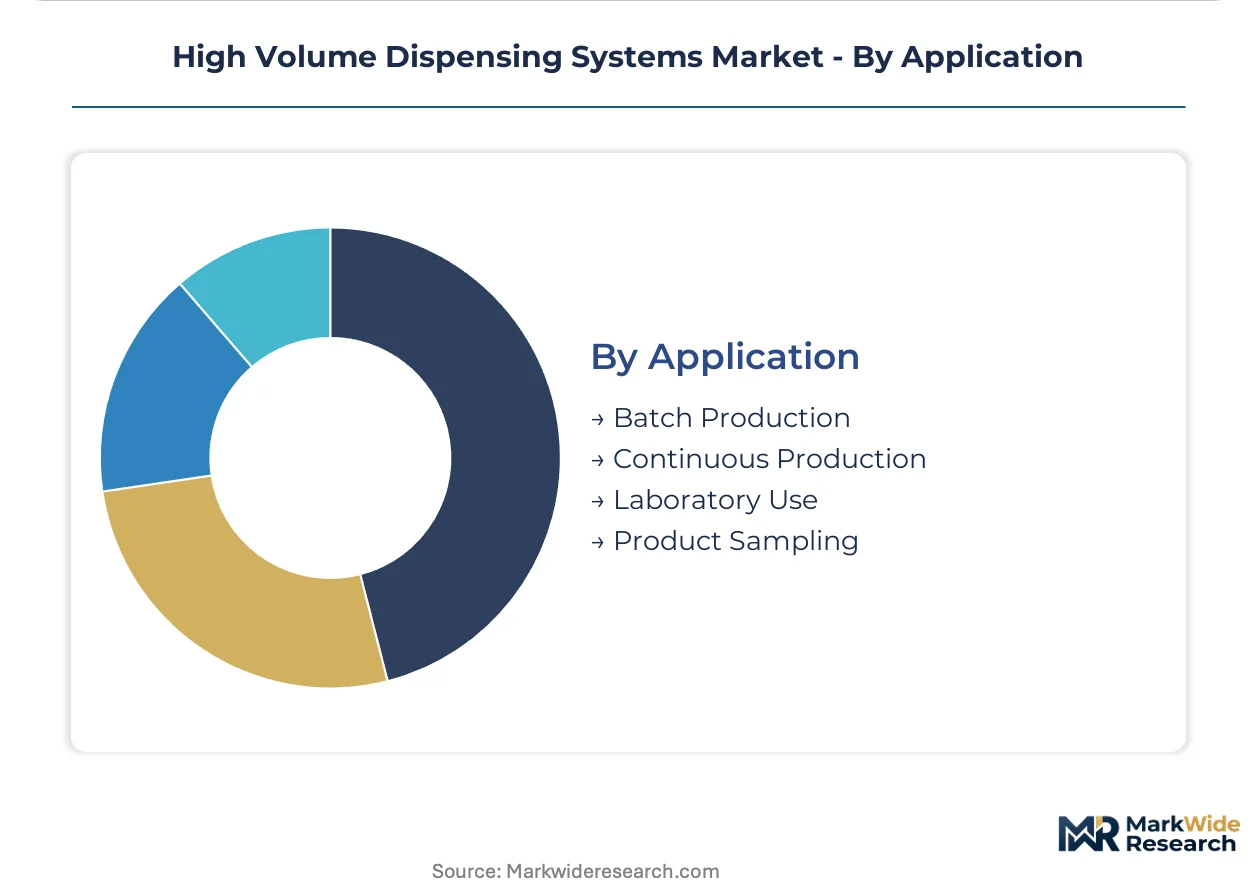
Application:
Production mode determines throughput requirements, validation protocols, and sensor integration depth.
- Batch Production:Discrete manufacturing cycles with defined start and end points dominate pharmaceutical oral solid dose and sterile injectable facilities. EMA's revised Annex 15 mandates continuous process verification, forcing embedding of process analytical technology sensors into standard equipment configurations.
- Continuous Production:Real-time release testing algorithms and predictive maintenance capabilities define this emerging deployment mode. High-volume parenteral facilities in Germany and Ireland specify pre-validated control system architectures to compress regulatory submission timelines.
- Laboratory Use:Small-scale validation and method development applications prioritize reconfigurability over throughput.
- Product Sampling:Quality control and in-process testing applications demand precision without full production-line integration.
Batch production retains dominant procurement volume. Continuous production is gaining share fastest among greenfield biologics facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for pharmaceutical manufacturing in India and China's coastal provinces are concentrating high-volume dispensing system deployment through tax incentives and streamlined customs procedures for imported precision components.
United States
FDA 21 CFR Part 11 compliance deadlines are accelerating replacement of legacy batch equipment across oral solid dose facilities. The agency's electronic records requirements compel validation protocols with audit-trail capabilities. Pharmaceutical clusters in New Jersey and North Carolina are absorbing multi-line automated dispensing installations to meet serialization mandates.
Germany
EMA Annex 15 qualification standards stretch project validation timelines to 18-24 months, favoring vendors with pre-validated control architectures. CDMO density in Baden-Württemberg and Bavaria drives concentrated procurement for serialized packaging lines serving multinational pharmaceutical clients. Stuttgart's precision engineering ecosystem supplies servo motor components to system integrators.
China
NMPA's tightening GMP enforcement for sterile injectable production is displacing manual compounding in biologics facilities. The Yangtze River Delta pharmaceutical corridor, spanning Shanghai and Suzhou, is installing pressure-driven liquid dispensing systems for commercial-scale protein formulation. Local component sourcing initiatives reduce dependence on Japanese motion control imports.
India
CDSCO's revised GMP guidelines and the PLI scheme for active pharmaceutical ingredients are creating contained powder dispensing demand in high-potency API facilities. Hyderabad's bulk drug manufacturing cluster and Ahmedabad's formulation belt are upgrading vacuum-assisted systems to meet OSHA-equivalent containment standards for export compliance.
Switzerland
Swissmedic's alignment with EU GMP Annex 1 for aseptic processing is driving closed-system drug transfer device adoption. Basel's biologics manufacturing corridor and the Lemanic region's precision instrumentation ecosystem are specifying isolator-integrated dispensing platforms. These configurations absorb capital allocations previously directed toward separate cleanroom infrastructure.
High Volume Dispensing Systems Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade system integrators commanding premium positioning against industrial fluid handling generalists. The vendor landscape organizes around three strategic tiers: diversified healthcare conglomerates with pharmacy automation portfolios, precision mechatronics specialists serving sterile manufacturing, and industrial dispensing equipment suppliers cross-selling into food and chemical applications. Competitive dynamics center on backward integration into motion control components and outcome-based service contract structuring.
Within the healthcare automation tier, Swisslog Healthcare exemplifies vertical integration across hardware and software stacks, while Becton Dickinson and Co. occupies a position anchored in closed-system containment expertise. McKesson Corporation represents channel-control archetypes that bundle dispensing technology with pharmaceutical distribution contracts. These three entities illustrate divergent paths to enterprise account penetration: captive manufacturing, R&D intensity, and supply chain leverage respectively.
| Leading Market Players |
|---|
| Swisslog Healthcare |
| Becton Dickinson and Co. |
| McKesson Corporation |
| TCGRx |
| Innovation Associates |
| Omnicell Inc. |
| ARxIUM Inc. |
| Graco Inc. |
| ScriptPro LLC |
| Others |
Value Chain & Pricing Dynamics
Captive in-house production of servo motor assemblies and precision motion control components anchors both supply security and pricing power for tier-one dispensing system vendors serving FDA-regulated pharmaceutical facilities. This backward integration shields established manufacturers from Japanese component sourcing volatility while justifying premium positioning against benchtop system competitors lacking comparable vertical control.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent above standard contract pricing apply to validated systems required for urgent serialization compliance deadlines. Project-based pricing with milestone payments dominates pharmaceutical-grade installations, where EMA Annex 15 qualification documentation and FDA 21 CFR Part 11 validation protocols differentiate certified tiers from uncertified alternatives. Cost compression in mid-scale automated dispensers is intensifying because modular benchtop systems from Asian suppliers are penetrating applications below ten thousand liter annual volume. Contract manufacturing organizations in Germany exhibit lowest price sensitivity due to pass-through mechanisms in client service agreements, while research laboratories in India display highest sensitivity to capital equipment outlays.
Supply Chain Analysis
FDA 21 CFR Part 11 and EMA Annex 15 qualification standards gate supplier access to pharmaceutical-grade dispensing system procurement, filtering component vendors through exhaustive validation documentation requirements. Manufacturing concentrates in Germany, Switzerland, and Japan, where precision engineering ecosystems feed servo motor production and stainless steel 316L fabrication for containment-critical applications. System builders draw from Japanese motion control imports, German precision machining capacity, and Indian software development labor for control system architecture. Single-source vulnerability in Japanese-sourced high-precision servo motors creates structural risk for vendors lacking qualified secondary suppliers. Distribution runs through direct OEM sales teams for pharmaceutical manufacturers, with regional system integrators serving chemical processing and food industry accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The High Volume Dispensing Systems Market functions as a cost-of-compliance arena where FDA 21 CFR Part 11 electronic records mandates erect substantial barrier-to-entry moats favoring incumbents with pre-validated control architectures and established audit-trail documentation.
For Market Incumbents: Lock in enterprise hospital network contracts through outcome-based service arrangements where payment ties to validated doses dispensed, neutralizing price competition from modular benchtop entrants. Deepen backward integration into motion control component supply by qualifying secondary servo motor sources outside Japan, reducing exposure to raw material price volatility and lead time elongation. Prioritize R&D investment in closed-system drug transfer devices with isolator integration to capture capital allocations previously directed toward separate cleanroom infrastructure. For New Entrants and Emerging Players: Launch via regional system integrator partnerships targeting chemical processing plants in India and China, where EPA-equivalent containment regulations are tightening but validation timelines remain shorter than pharmaceutical equivalents. Penetrate the cell and gene therapy fill-finish segment through precision micro-volume sonic dispensing platforms, where personalized medicine manufacturing suites require single-batch flexibility absent from incumbent fixed-installation architectures. Pursue white-label manufacturing arrangements with established European system integrators lacking in-house software development capacity. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified healthcare conglomerates seeking pharmacy automation portfolio expansion, with financial sponsor secondary buyouts viable for mid-cap precision mechatronics specialists. Long-term viability hinges on sustained regulatory enforcement of serialization mandates and traceability requirements across pharmaceutical supply chains without relaxation of qualification standards. Acquisition target archetype: precision motion control specialists with embedded pharmaceutical process knowledge and pre-validated FDA submission packages. Watch for CDSCO GMP enforcement intensity in India as inflection indicator for contained powder dispensing system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Validated Control Architecture Development | Compresses EMA Annex 15 submission timelines for German parenteral facilities. |
| Closed-System Isolator Integration | Absorbs Swissmedic-aligned EU GMP Annex 1 compliance budgets from cleanroom infrastructure. |
| Outcome-Based Service Contracting | Penetrates budget-constrained United States hospital pharmacy central fill operations. |
| Secondary Servo Motor Supplier Qualification | Reduces dependence on Japanese motion control imports amid raw material volatility. |
| Cell and Gene Therapy Micro-Volume Platform Launch | Captures personalized medicine manufacturing suites requiring single-batch flexibility. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by structured interviews with pharmaceutical manufacturing executives, regulatory affairs leads, hospital pharmacy procurement managers, and precision mechatronics engineering directors. FDA 21 CFR Part 11 guidance documents, EMA Annex 15 qualification protocols, CDSCO GMP circulars, and NMPA sterile injectable enforcement notices provided regulatory boundary conditions. Bottom-up installation and replacement cycle estimates triangulated against top-down pharmaceutical capital expenditure projections across the analysis window.
Granularity-level modeling deployed product-type, end-user, technology, and application dimensions, with additional segmentation by regional regulatory cluster reflecting FDA, EMA, and NMPA compliance tier differentiation. CAGRs derived from weighted average of replacement-driven demand and greenfield capacity expansion across oral solid dose, sterile injectable, and biologics manufacturing facilities. Forecast inputs incorporated CDMO contract velocity indices, serialization mandate implementation schedules, and stainless steel 316L price trend assumptions.
Regulatory enforcement delays, raw material supply disruptions, and modular benchtop system penetration acceleration are the dominant revision risks to installed base and revenue projections. Forecasts reflect documented assumptions regarding qualification timeline stability and OEM field service capacity constraints. A model refresh is warranted upon material change in FDA or EMA serialization mandate implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Appendage Management Market
Medical Devices
Europe Incontinence Devices and Ostomy Market
Medical Devices
Global Anti-Snoring Devices and Snoring Surgery Market
Medical Devices
Global Cerebrospinal Fluid Management Devices Market
Medical Devices
Parenteral Feeding Devices Market
Medical Devices
Japan Anesthesia Devices Market
Medical Devices
Global Pediatric Medical Devices Market
Medical Devices
Neuromodulation Devices Market
Medical Devices
Global Obstetrics Devices Market
Medical Devices
Global Active Implantable Medical Devices Market
Medical Devices
Ophthalmoscopes Market
Medical Devices
Craniomaxillofacial Plate and Installation Tools Market
Medical Devices
Global Cardiac Reader System Market
Medical Devices
Global Hemostasis Valves Market
Medical Devices
South Korea Ultrasound Devices Market
Medical Devices
Global Mobile ECG Devices Market