
 ENT Disorder Treatment Market | 2026-2036
ENT Disorder Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
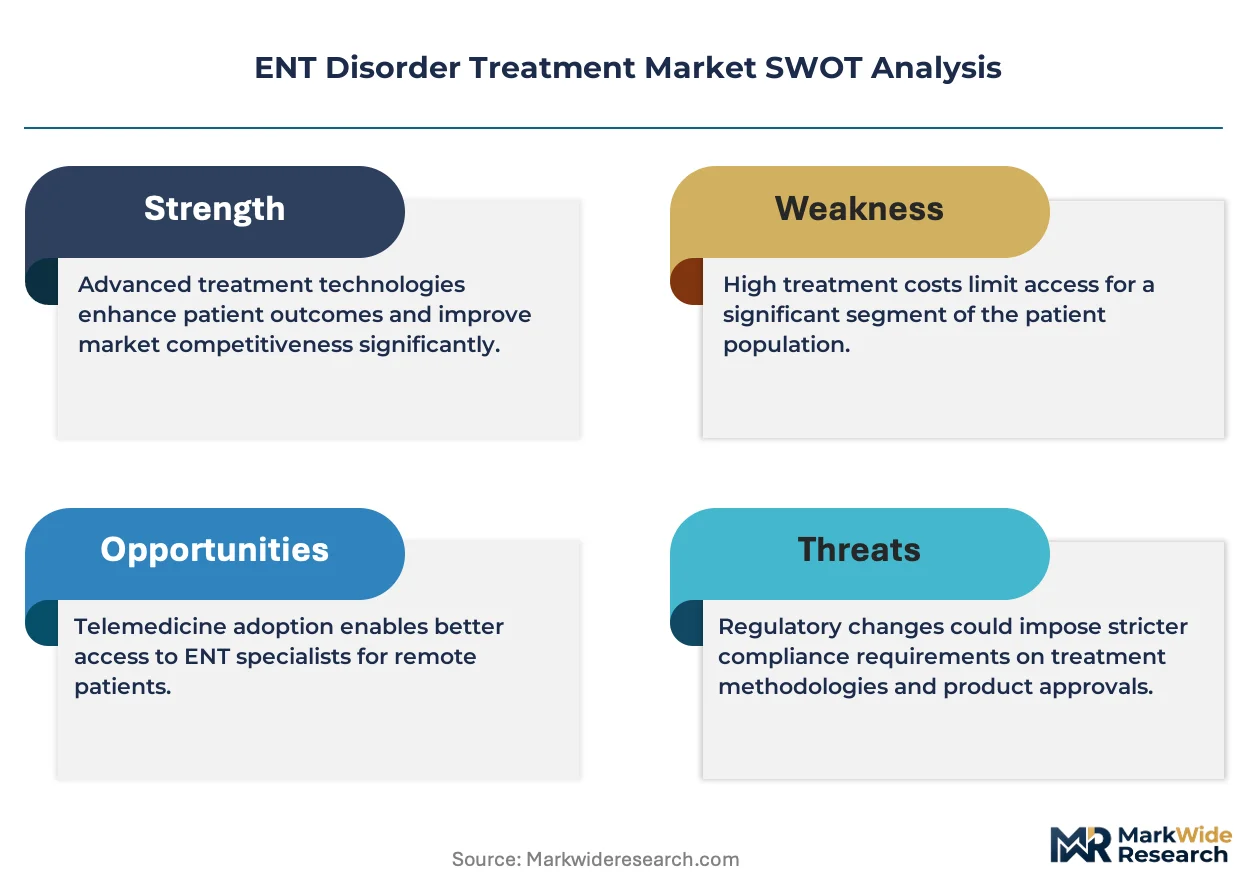
ENT Disorder Treatment Market Analysis
Germany is narrowing its ENT device manufacturing gap through targeted investments in precision surgical instrument clusters near Tuttlingen. Medtronic leverages its integrated ENT navigation platform to sustain leadership in image-guided sinus surgery systems. Johnson & Johnson anchors its competitive position through broad hospital contracting networks across North American and European acute care settings.
ENT disorder treatment encompasses pharmacological, surgical, and rehabilitative interventions addressing pathologies of the ear, nose, throat, and related structures of the head and neck, typically employing biocompatible titanium implants, antibiotic-eluting delivery systems, or programmable digital signal processors with frequency compression algorithms to restore function. Medications and hearing aids command distinct margin architectures, with pharmaceutical formulations facing compressed pricing from generic entrants while premium hearing aid platforms capture value through software-enabled personalization and direct-to-consumer channel expansion. Surgical instruments and diagnostic devices occupy a capital-equipment cycle dependent on hospital replacement schedules and ambulatory migration trends.
The FDA governs implantable hearing devices through Class III premarket approval pathways, while the EMA's Medical Device Regulation imposes enhanced clinical evidence requirements on ENT surgical tools marketed in Europe. Japan's PMDA maintains distinct reimbursement listing processes that delay commercial access for novel cochlear implant features. Stakeholders must monitor evolving regulatory divergence across these jurisdictions to anticipate compliance costs and timeline risks for product portfolio decisions.
Market Dynamics
Hospital procurement of ENT surgical instruments is accelerating as health systems modernize operating suites and ambulatory surgery centers expand sinus procedure volumes. The FDA's strengthened premarket review of implantable hearing devices is reshaping manufacturer compliance burdens across the development pipeline.
Growth Catalysts
- EMA Medical Device Regulation:Enhanced clinical evidence requirements for ENT surgical tools marketed in Europe are driving investment in robust trial infrastructure. Manufacturers building compliant data packages gain preferential market access.
- Ambulatory surgery centers:United States facilities are expanding dedicated ENT suites to capture migrating sinus and otologic procedures from inpatient settings. Capital equipment orders from ASCs are outpacing hospital replacement cycles.
- Biocompatible titanium implants:Advanced metallurgy with porous surface architecture is improving osseointegration rates in middle ear reconstruction. Surgeons are upgrading instrument sets to accommodate these precision components.
Market Restraints
- Supply concentration in precision machining:German surgical instrument clusters near Tuttlingen control critical production capacity for micro-cutting tools. Disruption risks concentrate in this geographic corridor.
- Generic pharmaceutical entrants:Antibiotic and corticosteroid formulations for chronic rhinosinusitis face pricing compression as patent expirations accelerate. Branded manufacturers are losing margin in pharmacological segments.
- PMDA reimbursement listing delays:Japan's distinct commercial access timelines for novel cochlear implant features extend revenue recognition windows. Product launches lag European and United States markets by 18-24 months.
Strategic Opportunities
- Direct-to-consumer hearing aid channels:Software-enabled personalization platforms are bypassing traditional audiologist networks. Regulatory clarity from the FDA on over-the-counter classifications is enabling this channel expansion.
- Image-guided navigation convergence:Integration of optical tracking with preoperative CT planning is hybridizing surgical workflows. Systems combining these modalities command premium positioning in academic medical centers.
- India's PLI scheme for medical devices:Domestic manufacturing incentives are attracting component suppliers for ENT diagnostic equipment. Local production capacity is scaling to serve South Asian and Middle Eastern demand.
Industry Challenges
- FDA Class III premarket approval timelines:Implantable hearing device submissions face extended review cycles with iterative information requests. Development programs require contingency capital for regulatory dialogue.
- Digital signal processor integration:Programmable frequency compression algorithms demand specialized firmware engineering talent scarce in traditional otolaryngology device firms. Recruitment competition with consumer electronics intensifies.
- Legacy hospital contracting networks:Incumbent manufacturers anchor purchasing relationships through bundled capital-equipment and consumable agreements. New entrants face switching cost barriers in consolidated health systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ENT Disorder Treatment Market |
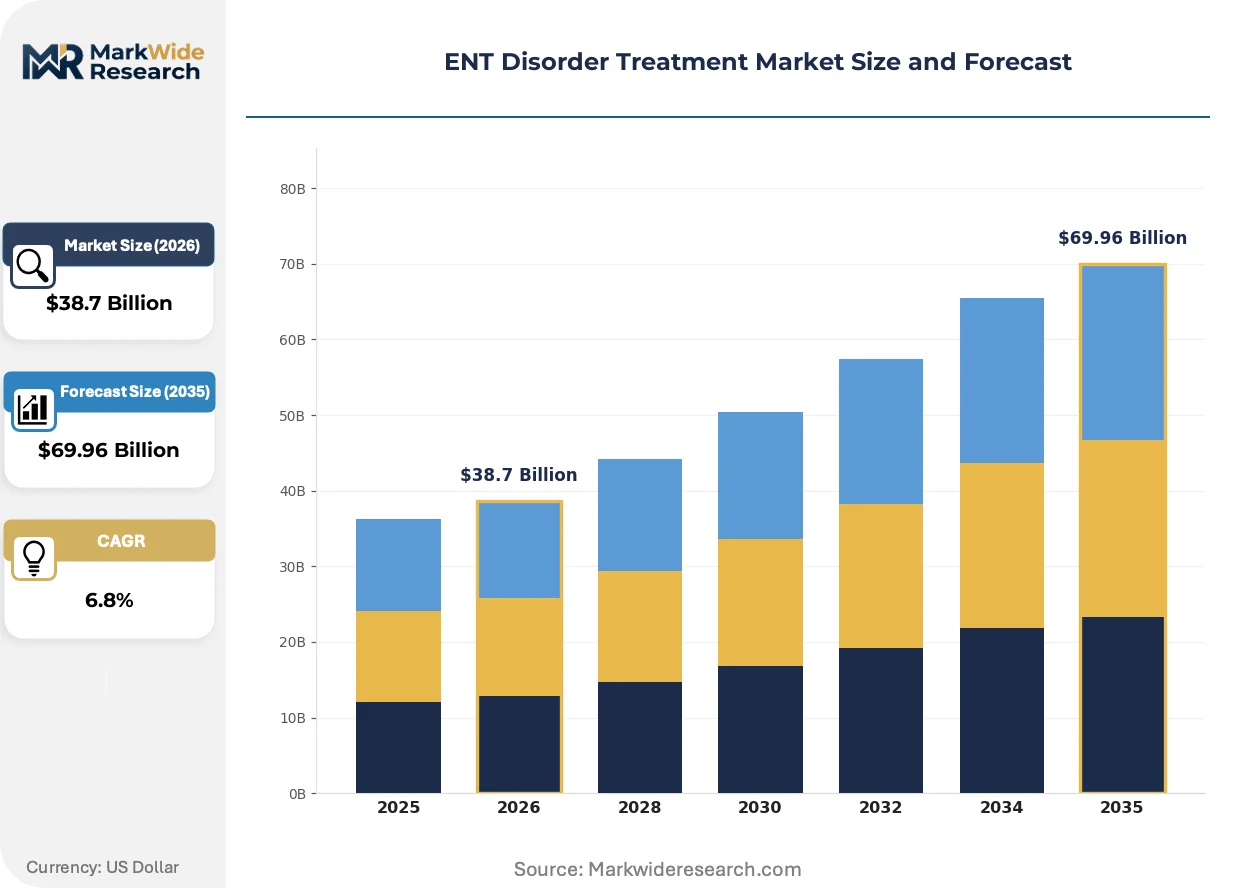
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Surgical Instruments, Diagnostic Devices, Hearing Aids Application: Hearing Loss, Sinusitis, Nasal Congestion, Throat Infections End User: Hospitals, ENT Clinics, Home Care, Rehabilitation Centers Delivery Mode: Oral, Intranasal, Topical, Injection |
| Companies Covered | Sanofi, Novartis, GlaxoSmithKline, Pfizer, AstraZeneca, Medtronic, Johnson & Johnson, Cochlear, Stryker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ENT Disorder Treatment Market Emerging Trajectories
Software-enabled personalization and surgical navigation integration are compressing traditional boundaries between diagnostic planning, intraoperative guidance, and postoperative rehabilitation. Device manufacturers are repositioning around data-driven outcome platforms rather than discrete hardware sales.
Programmable digital signal processors with frequency compression algorithms are hybridizing hearing aid architectures with real-time environmental adaptation. Premium manufacturers are embedding machine learning inference at the edge to reduce cloud dependency. United States audiologists are adopting these platforms faster than European counterparts, compressing replacement cycles for legacy analog devices.
REACH chemical safety regulations are restricting certain polymer formulations historically used in ENT implant coatings. European manufacturers are reformulating surface treatments to maintain biocompatibility certification under tightened substance restrictions. Surgical instrument suppliers with established European notified body relationships are capturing reformulation service revenue from component vendors lacking direct regulatory expertise.
Acute care networks are consolidating vendor relationships through multi-year enterprise agreements spanning surgical instruments, navigation systems, and service contracts. Independent ambulatory surgery centers are responding by forming purchasing cooperatives to match hospital negotiating leverage. This concentration dynamic is most visible in United States metropolitan markets where health system consolidation has advanced furthest.
ENT Disorder Treatment Market Segmentation
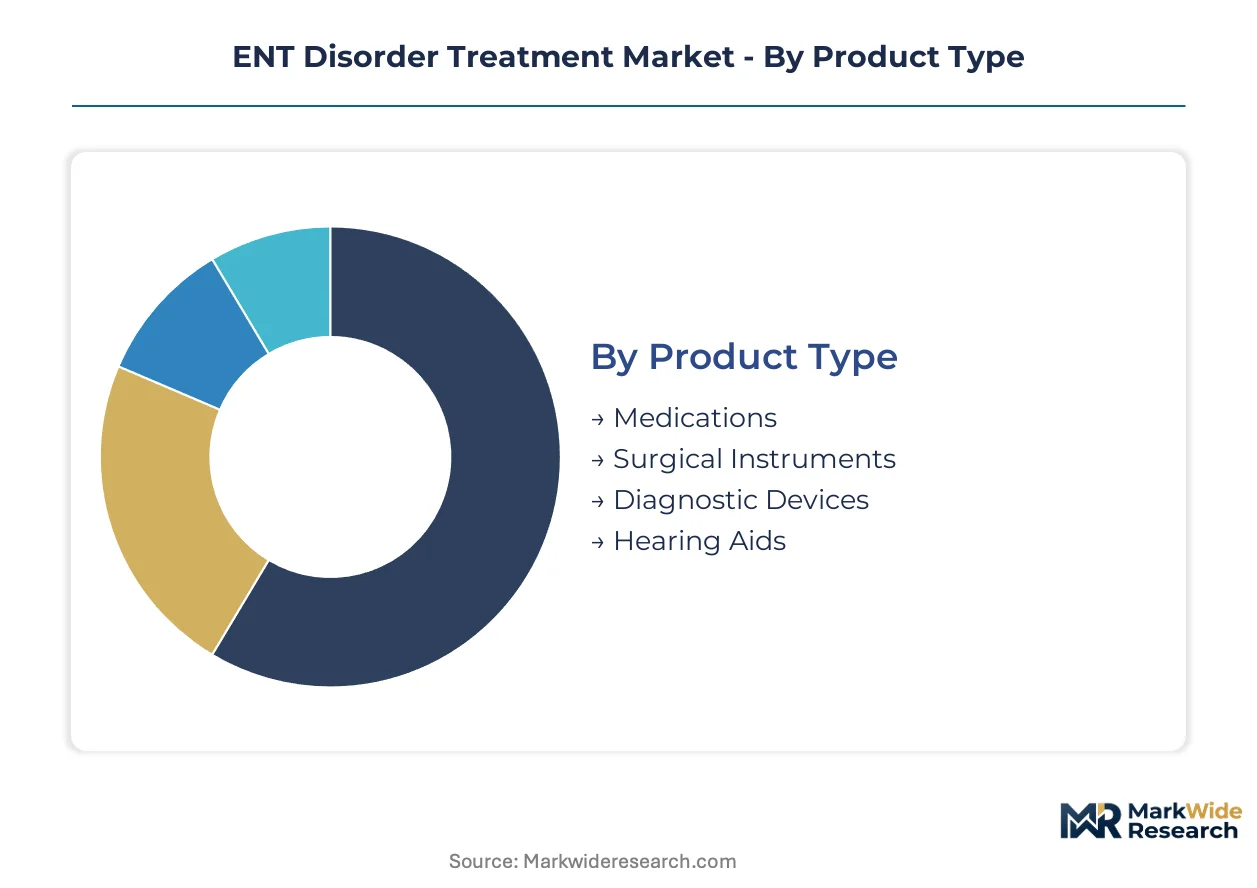
ENT disorder treatment segments reflect divergent margin architectures and capital intensity. Pharmaceutical formulations compete on generic substitution while surgical and diagnostic equipment cycles depend on health system modernization budgets.
Product Type:
Mature hardware categories dominate installed base value while emerging digital platforms reshape hearing rehabilitation economics.
- Medications:Antibiotic and corticosteroid formulations for chronic rhinosinusitis face compressed pricing from generic entrants. Branded manufacturers in the United States and Europe are losing margin share as patent cliffs accelerate.
- Surgical Instruments:Precision micro-cutting tools with biocompatible titanium construction command premium positioning in academic medical centers. German clusters near Tuttlingen control critical production capacity for these components.
- Diagnostic Devices:Endoscopic imaging systems with 4K resolution capabilities.
- Hearing Aids:Programmable digital signal processors with frequency compression algorithms.
Surgical Instruments retains volume leadership; Hearing Aids holds the steepest expansion curve.
Application:
Volume distribution tracks procedure migration from inpatient to ambulatory settings across developed markets.
- Hearing Loss:Cochlear implant and hearing aid demand concentrates in aging populations. The FDA's over-the-counter classification is accelerating direct-to-consumer channel development in the United States.
- Sinusitis:Chronic rhinosinusitis procedures are migrating to ambulatory surgery centers. United States ASCs are expanding dedicated ENT suites to capture this volume shift from hospitals.
- Nasal Congestion:Decongestant and corticosteroid spray formulations.
- Throat Infections:Antibiotic therapies and tonsillectomy procedures.
Hearing Loss commands the largest addressable population; Sinusitis demonstrates the most rapid procedure volume migration.
End User:
Customer concentration varies by capital intensity and reimbursement pathway complexity.
- Hospitals:Integrated health systems in the United States consolidate vendor relationships through multi-year enterprise agreements spanning surgical instruments, navigation systems, and service contracts. Procurement committees prioritize bundled capital-equipment and consumable arrangements.
- ENT Clinics:Specialized outpatient facilities drive hearing aid dispensing volume. Audiologist networks in Germany and the United States are adopting software-enabled personalization platforms faster than European counterparts.
- Home Care:Self-administered medication and maintenance therapies.
- Rehabilitation Centers:Postoperative voice and swallowing therapy services.
Hospitals anchor capital equipment demand; ENT Clinics are expanding most quickly in hearing device dispensing.
Delivery Mode:
Route selection determines regulatory pathway complexity and manufacturing scale economics.
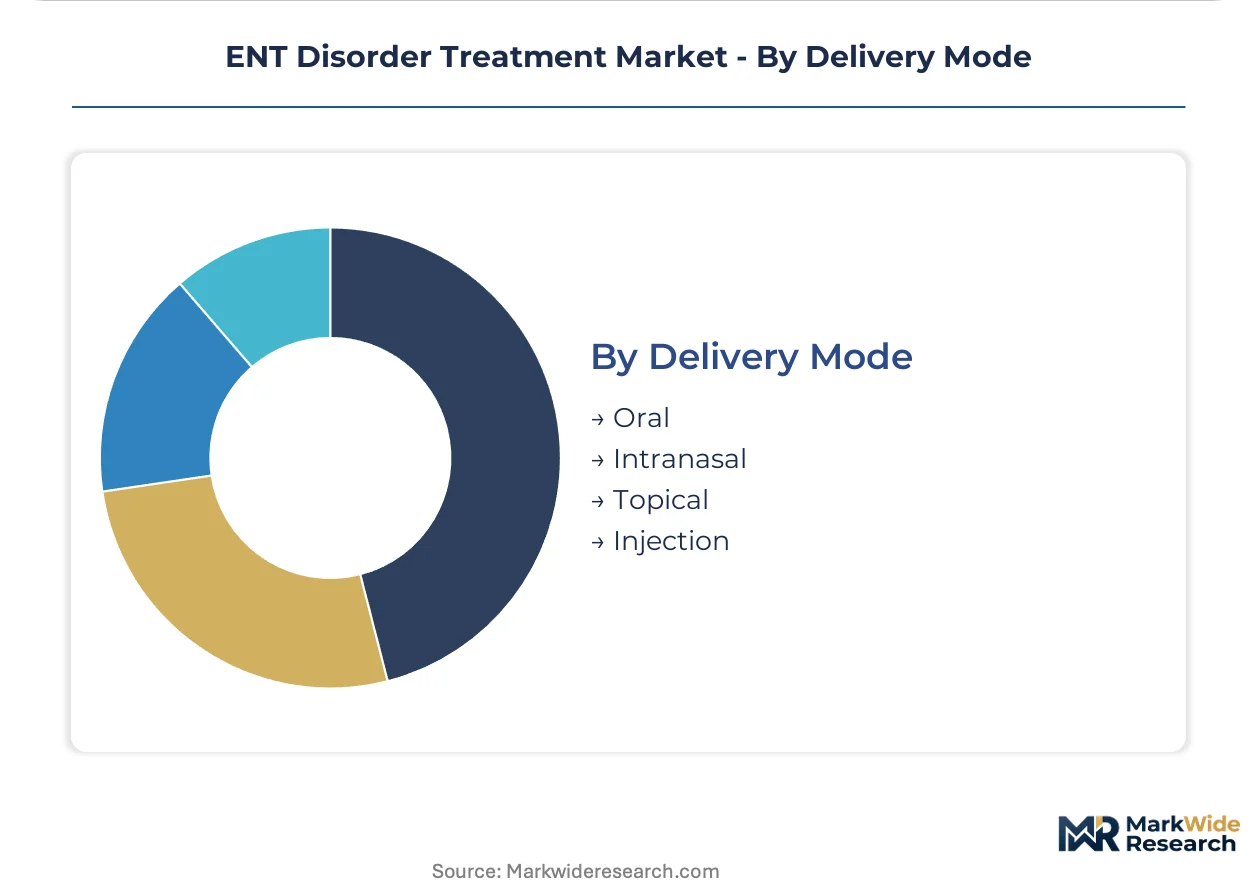
- Oral:Systemic antibiotic and corticosteroid tablets face bioequivalence competition from generic manufacturers. Formulation stability requirements favor established pharmaceutical producers with validated supply chains.
- Intranasal:Topical corticosteroid sprays for chronic rhinosinusitis require precise particle size distribution engineering. United States and European manufacturers are reformulating to meet tightened REACH chemical safety restrictions on polymer coatings.
- Topical:Ear drop and throat spray formulations.
- Injection:Depot corticosteroid preparations for severe inflammatory conditions.
Oral delivery retains prescription volume leadership; Intranasal formulations are gaining share fastest in chronic rhinosinusitis maintenance therapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision machining clusters near Tuttlingen supply critical micro-cutting tools to ENT device manufacturers worldwide. This supply-side concentration shapes procurement patterns across North American and Asian health systems.
United States
Ambulatory surgery centers in Texas and Florida are expanding dedicated ENT suites to capture migrating sinus procedures from hospitals. The FDA's over-the-counter hearing aid classification is accelerating direct-to-consumer channel development. Minneapolis and Boston anchor hearing device innovation clusters with strong ties to academic medical centers.
Germany
University hospitals in Heidelberg and Munich are adopting image-guided navigation systems for complex skull-base surgery. The EMA's Medical Device Regulation imposes enhanced clinical evidence requirements on surgical tools marketed across Europe. The Tuttlingen precision instrument cluster controls manufacturing capacity for titanium micro-implants used in middle ear reconstruction.
Japan
Aging demographics in Tokyo and Osaka are driving cochlear implant demand among elderly populations. The PMDA maintains distinct reimbursement listing processes that delay commercial access for novel implant features by 18-24 months. The Kansai region hosts manufacturing facilities serving domestic otologic device demand.
India
Chronic rhinosinusitis prevalence in Delhi and Mumbai is expanding addressable patient populations for surgical intervention. The PLI scheme for medical devices is attracting component suppliers for ENT diagnostic equipment to Gujarat and Karnataka. Domestic production capacity is scaling to serve South Asian and Middle Eastern export demand.
United Kingdom
NHS procurement consolidation in London and Manchester is favoring vendors with bundled capital-equipment and service contracts. MHRA post-Brexit regulatory pathways are diverging from EU MDR timelines for implantable hearing devices. The Cambridge-Oxford corridor hosts emerging digital health firms targeting hearing aid software personalization.
ENT Disorder Treatment Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in precision machining and materials supply. The vendor base organizes around three archetypes: diversified medical technology conglomerates with navigation system portfolios, hearing device pure-plays with software-enabled personalization platforms, and pharmaceutical manufacturers facing generic compression in rhinosinusitis therapeutics. Consolidation is accelerating through multi-year hospital enterprise agreements and ambulatory surgery center purchasing cooperative formation.
Among diversified technology conglomerates, Medtronic and Johnson & Johnson occupy positions anchoring integrated ENT navigation and surgical instrument portfolios. Cochlear exemplifies the hearing device pure-play archetype with concentrated exposure to implantable and external sound processor markets. These three companies represent distinct competitive vectors: system integration, hospital contracting scale, and specialized auditory rehabilitation technology.
| Leading Market Players |
|---|
| Sanofi |
| Novartis |
| GlaxoSmithKline |
| Pfizer |
| AstraZeneca |
| Medtronic |
| Johnson & Johnson |
| Cochlear |
| Stryker |
| Others |
Supply Flow & Price Mechanics
Undercapacity in German precision machining clusters near Tuttlingen is tightening titanium micro-implant supply and amplifying pricing power for surgical instrument manufacturers serving academic medical centers in the United States and Japan.
Pricing Analysis
FDA Class III premarket approval pathways dictate the pricing tier structure for implantable hearing devices, separating premium navigation-integrated systems from standard acoustic processors and economy analog alternatives. Price differentiation hinges on software-enabled personalization depth and CE marking tier under EMA Medical Device Regulation. Cost compression in pharmaceutical formulations is intensifying because generic antibiotic entrants for chronic rhinosinusitis are eroding branded margins. Ambulatory surgery centers exhibit the highest price sensitivity due to capital budget constraints, while integrated health systems prioritize total cost-of-ownership over unit pricing.
Supply Chain Analysis
Tariff exposure between Germany and the United States dominates supply chain risk planning for ENT surgical instrument procurement. Production gravity centers on German precision clusters for titanium micro-cutting tools, Swiss metallurgy for biocompatible alloys, and Chinese component assembly for diagnostic device housings. Raw material dependencies include surgical-grade titanium sponge, rare-earth magnets for cochlear implant sound processors, and optical-grade sapphire for endoscopic lenses. Single-source vulnerability concentrates in Tuttlingen-based micro-machining capacity. Distribution runs through hospital GPO contracts in North America, regional medical device distributors in Europe, and government procurement channels in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across the ENT disorder treatment landscape as procedure migration to ambulatory settings creates specialized vendor niches underserved by legacy hospital contracting networks.
For Market Incumbents: Insulate installed base value by embedding navigation software subscriptions into multi-year hospital enterprise agreements, countering direct-to-consumer hearing aid entrants. Deepen backward integration into titanium micro-implant production through captive supply agreements with Tuttlingen precision clusters. Prioritize FDA breakthrough device designation for programmable signal processors to extend regulatory moats.
For New Entrants and Emerging Players: India's underpenetrated diagnostic device manufacturing base offers white-space entry through PLI scheme incentives in Gujarat and Karnataka. Target software-enabled hearing aid personalization platforms for ENT clinic dispensing networks in Germany and the United States, bypassing incumbent audiologist channel control. Pursue reimbursement strategy partnerships with regional payers to accelerate commercial access timelines.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across hearing aid pure-plays as direct-to-consumer channels displace traditional retail infrastructure. Five-to-ten year viability favors platform integrators with navigation system portfolios over component-dependent surgical instrument suppliers. Watch FDA over-the-counter classification enforcement as the signal indicating channel structure permanence.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | Class III premarket approval for implantable hearing devices anchors United States commercial access timelines. |
| CE Marking Pathway | EMA Medical Device Regulation compliance enables European market entry for surgical navigation systems. |
| Hospital System Partnership | Multi-year enterprise agreements with United States acute care networks secure capital equipment replacement cycles. |
| Software Companion Development | Machine learning-enabled personalization platforms differentiate hearing aid offerings from analog competitors. |
| Reimbursement Strategy | PMDA listing optimization accelerates Japan commercial access for novel cochlear implant features. |
Methodological Framework
The analysis maps surgical instruments, diagnostic devices, hearing aids, and pharmaceutical formulations, each validated through hospital procurement managers, biomedical engineers, GPO contracts specialists, and otolaryngology clinicians. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) and PMA filings, EMA MDR technical documentation, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up segment sizing and top-down macro triangulation cross-check volume and value estimates across the analysis window.
Assumptions held fixed include regulatory pathway timelines, ambulatory surgery center migration rates, and titanium raw material cost trajectories, while patient population demographics and reimbursement policy shifts were varied across sensitivity scenarios. Segmentation dimensions modeled include product type, application, end user, and delivery mode, with geographic regulatory clusters as an overlay. CAGRs were derived from fitted growth curves anchored to historical procedure volumes and equipment replacement cycles, incorporating software-enabled platform adoption rates and generic pharmaceutical erosion patterns as industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in healthcare capital expenditure budgets, trade policy between Germany and the United States, or PMDA reimbursement listing timelines would shift the trajectory. Forecasts reflect documented assumptions regarding procedure migration, regulatory clearance velocity, and supply chain concentration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ENT
US Hearing Aids Market
ENT
Denmark Hearing Aids Market
ENT
Head and Neck Squamous Cell Carcinoma Market
ENT
Custom Hearing Aids Market
ENT
North America Hearing Aid Market
ENT
Hearing Amplifiers Market
ENT
ENT Examination Chair Market
ENT
Europe Hearing Aids Market
ENT
Ear Health Market
ENT
Interventional ENT Devices Market
ENT
Hearing Implants Market
ENT
Nasal Polyps Treatment Market
ENT
Global Audiological Devices Market
ENT
Global Acute Otitis Media Treatment Market
ENT
Surgical ENT Devices Market
ENT
Nasal Sampling Lines Market