
 Biopsy Devices Market | 2026-2036
Biopsy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Biopsy Devices Market Analysis
Capital-intensity divergence between integrated manufacturers and device-only suppliers is redrawing competitive boundaries in tissue acquisition systems. Medtronic leverages its end-to-end surgical ecosystem to bundle biopsy instruments with imaging navigation platforms. Becton, Dickinson and Company anchors its position through vertical control over needle production and sterile packaging infrastructure. Hologic competes by dominating the vacuum-assisted segment with proprietary tissue harvesting technology.
Biopsy devices are precision-engineered instruments designed to extract tissue specimens for histopathological examination, typically featuring hollow needles with cutting mechanisms sized between 14 and 20 gauge for percutaneous access. These systems serve the essential clinical function of obtaining diagnostic material without open surgical intervention, enabling early-stage disease detection and molecular profiling. Vacuum-assisted devices command premium positioning due to their superior tissue yield in breast and prostate procedures, while ultrasound-guided technology leads procedural volume across outpatient settings. Robotic-assisted biopsy systems represent the fastest-growing technology segment as hospitals seek to standardize needle placement accuracy and reduce operator-dependent variability.
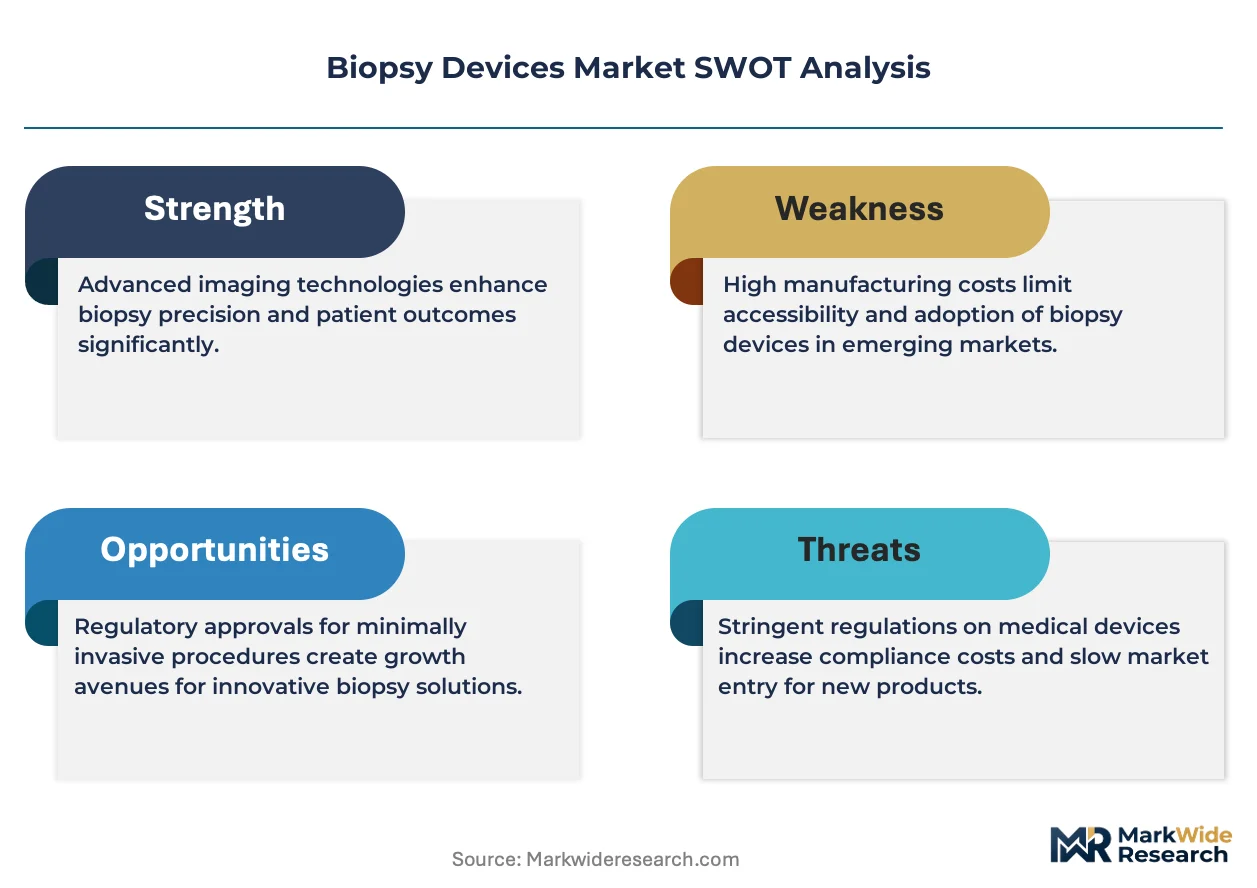
The FDA enforces 510(k) clearance requirements for all new biopsy needle designs, while the EU Medical Device Regulation mandates clinical evidence for Class IIa and above tissue sampling instruments. These frameworks elevate barriers for emerging manufacturers and redirect R&D investment toward predicate device equivalence studies. Stakeholders must monitor reimbursement coding changes for image-guided procedures and anticipate how CMS physician fee schedule adjustments will alter site-of-service economics.
Market Dynamics
Robotic-assisted biopsy systems are compressing the procedural learning curve and forcing capital equipment decisions at mid-tier hospitals that previously relied on manual needle placement techniques.
Growth Catalysts
- EU MDR clinical evidence mandates:The Medical Device Regulation's stricter documentation requirements for Class IIa tissue sampling instruments is accelerating consolidation toward manufacturers with established predicate device portfolios and regulatory affairs infrastructure.
- Hospital-based oncology expansion:University medical centers across Germany are consolidating interventional radiology services into centralized percutaneous biopsy programs, creating dedicated procurement budgets for vacuum-assisted and image-guided systems.
- Ultrasound-guided outpatient migration:Ambulatory surgical centers are capturing prostate and breast biopsy volume from inpatient settings, driving demand for portable, plug-and-play needle guidance platforms with reduced sterilization requirements.
Market Restraints
- Stainless steel needle supply concentration:Three specialized European metallurgical suppliers control premium-grade hypodermic tubing for 14-20 gauge biopsy instruments, exposing device manufacturers to input cost volatility and allocation risk during demand spikes.
- FDA 510(k) predicate device dependence:New entrants face structural barriers establishing substantial equivalence when incumbent manufacturers hold extensive cleared device lineages, redirecting R&D expenditure toward incremental modifications rather than novel cutting mechanisms.
- Core needle yield limitations in fibrotic tissue:Standard spring-loaded devices demonstrate inadequate specimen quality in cirrhotic liver and desmoplastic tumor contexts, creating substitution vulnerability to fine-needle aspiration alternatives in hepatology and pancreatic oncology workflows.
Strategic Opportunities
- Japan's PMDA fast-track pathway for robotic surgery:The Pharmaceuticals and Medical Devices Agency's Sakigake designation offers prioritized review for computer-assisted biopsy navigation systems, creating regulatory arbitrage for manufacturers with CE-marked European platforms.
- Liquid biopsy complementarity positioning:Tissue sampling device manufacturers can bundle histopathological instruments with circulating tumor DNA collection workflows, capturing integrated diagnostic budgets at comprehensive cancer centers pursuing multi-modal biomarker strategies.
- Rural hospital hub-and-spoke networks:Regional health systems in the US are centralizing complex image-guided procedures at tertiary centers while deploying teleproctoring-connected biopsy devices at affiliated community hospitals, creating distributed equipment demand with centralized service contracts.
Industry Challenges
- Interventional radiologist workforce constraints:The Society of Interventional Radiology reports insufficient fellowship-trained operators to staff expanding percutaneous biopsy programs, forcing hospitals to deploy general radiologists with abbreviated procedural training or delay service line launches.
- Robotic system integration complexity:Hospitals purchasing computer-assisted needle placement platforms face extended implementation timelines reconciling proprietary software with existing PACS, EMR, and imaging modality architectures, delaying revenue recognition for capital equipment vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biopsy Devices Market |
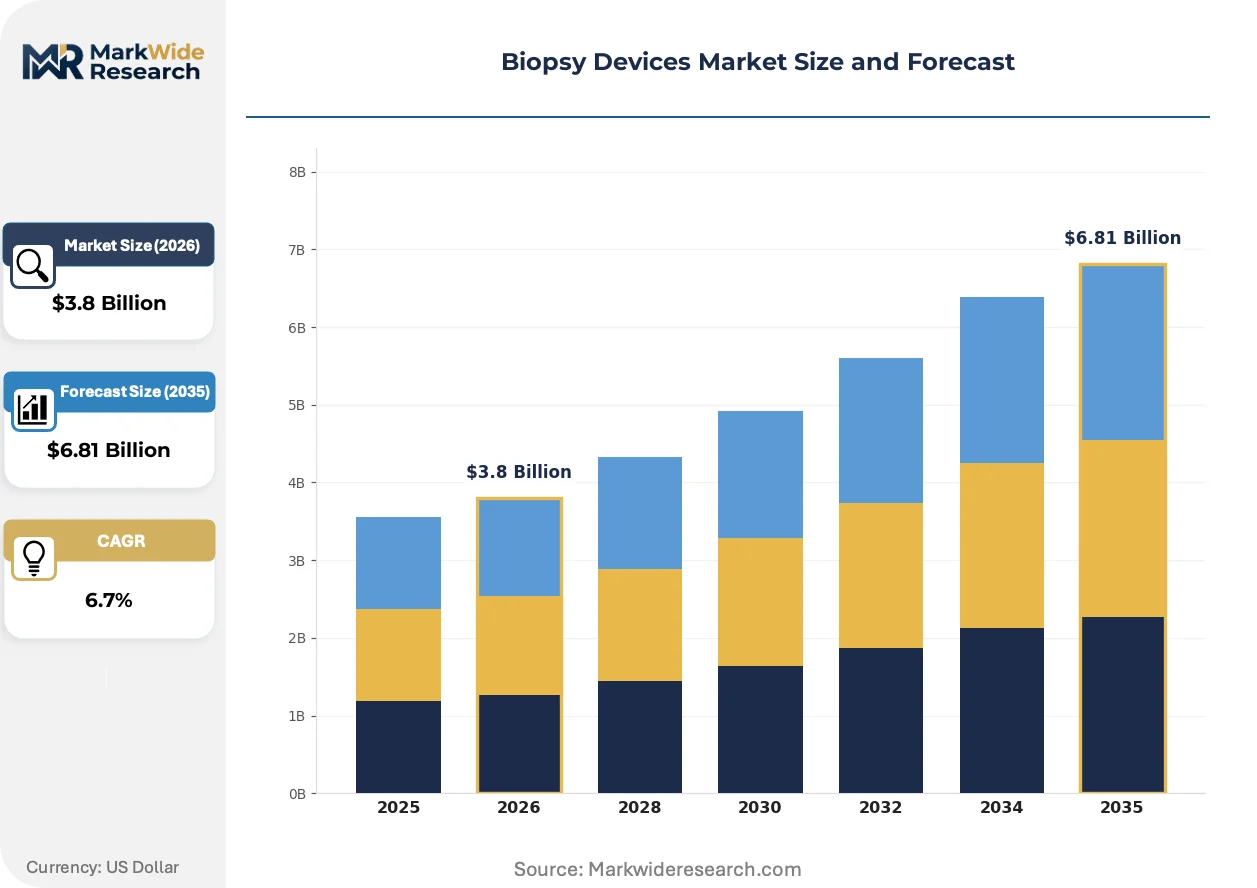
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Core Needle, Fine Needle, Vacuum-Assisted, Surgical End User: Hospitals, Clinics, Diagnostic Laboratories, Research Institutions Application: Oncology, Infectious Disease, Autoimmune Disorders, Neurology Technology: Ultrasound-Guided, CT-Guided, MRI-Guided, Robotic-Assisted |
| Companies Covered | Medtronic, Boston Scientific Corporation, Becton, Dickinson and Company, Devicor Medical Products, Cardinal Health, Hologic, Argon Medical Devices, Cook Medical, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biopsy Devices Market Emerging Trajectories
Disposable sterile biopsy needle kits are displacing reusable instrument reprocessing workflows across outpatient settings, while artificial intelligence-enabled imaging analysis is compressing the time between tissue acquisition and pathological diagnosis.
Single-use vacuum-assisted biopsy systems is bifurcating the market between premium integrated console platforms and simplified handheld devices. Academic medical centers in Germany and the Netherlands are adopting full-specification systems with real-time specimen radiography and automated tissue handling. Community hospitals and ambulatory centers are selecting stripped-down handheld alternatives that sacrifice advanced features for capital efficiency and reduced sterilization infrastructure. This technology trajectory is bifurcating vendor business models between equipment-leasing arrangements and high-volume disposable contracts.
The EU Medical Device Regulation's enhanced post-market surveillance requirements are extending clinical evidence obligations to legacy predicate devices previously grandfathered under the Medical Device Directive. Manufacturers must now compile systematic literature reviews and real-world performance data for Class IIa needle systems cleared before 2021. Breast biopsy device portfolios face the steepest compliance burden given their high procedural volume and established adverse event reporting databases, prompting several suppliers to prune marginal SKUs rather than sustain documentation costs.
Pathology laboratories are unbundling tissue acquisition from histological processing through independent specimen transport networks. Third-party logistics providers now offer temperature-controlled courier services between ambulatory biopsy sites and centralized diagnostic facilities, enabling small-volume purchasers to access academic pathology expertise without maintaining in-house laboratory infrastructure. This channel restructuring is most pronounced in the US Southeast, where regional health systems are consolidating diagnostic pathology services while expanding geographically dispersed biopsy collection points.
Biopsy Devices Market Segmentation
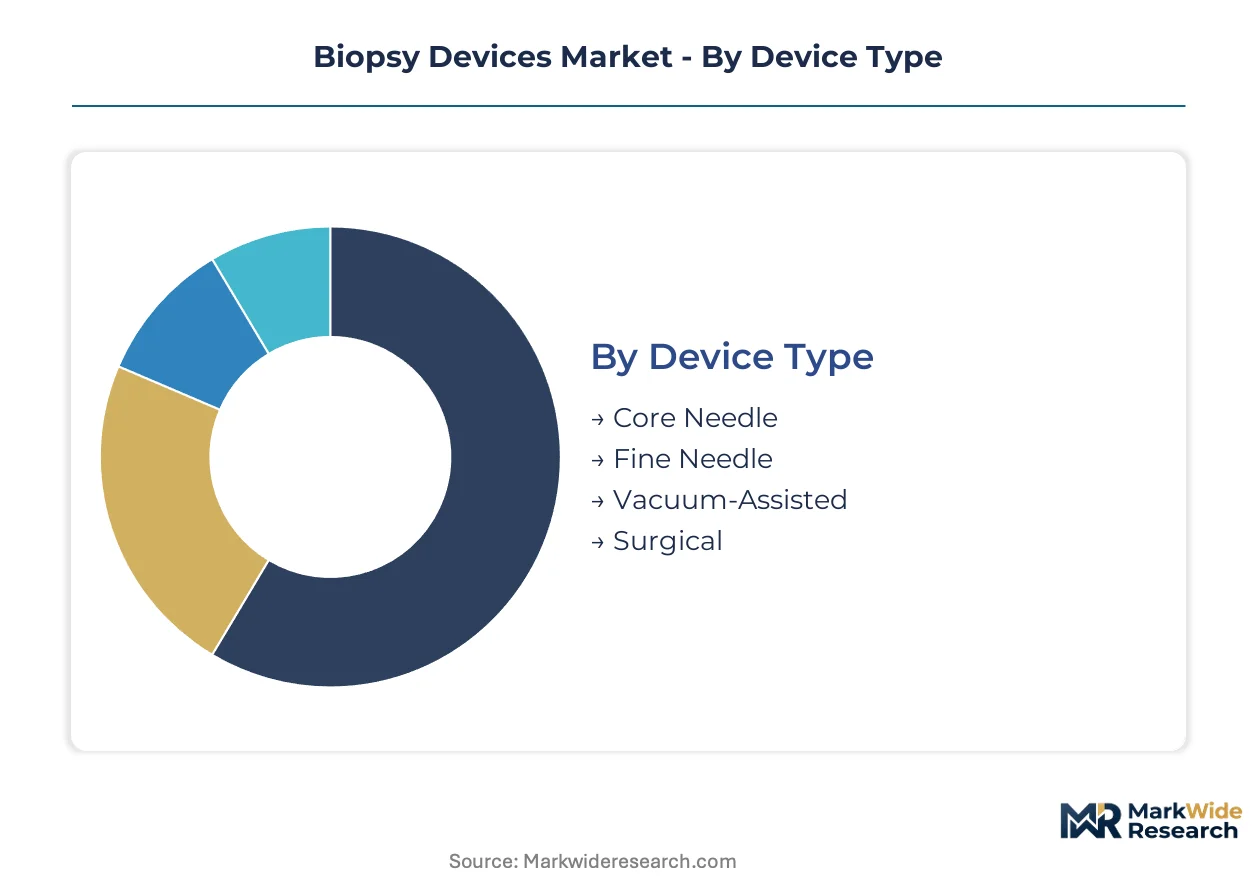
Biopsy device segmentation reveals how regulatory pathways, reimbursement structures, and procedural site economics fragment procurement behavior across clinical settings. Understanding these divides exposes where manufacturers can capture premium positioning versus commodity volume.
Device Type:
FDA 510(k) clearance requirements vary substantially by cutting mechanism, with vacuum-assisted systems facing enhanced documentation burdens for tissue yield validation compared to spring-loaded alternatives.
- Vacuum-Assisted:These systems employ negative pressure aspiration to harvest contiguous tissue cores through a single needle insertion. Hologic dominates breast and prostate applications through proprietary tissue harvesting technology. German university medical centers are consolidating procurement around these platforms for interventional radiology service lines.
- Core Needle:Spring-loaded mechanisms fire an inner trocar and outer cutting cannula to extract cylindrical specimens. Standard 14-20 gauge configurations serve as the workhorse for liver, kidney, and soft-tissue procedures. Stainless steel tubing supply concentration among three European metallurgical suppliers creates input cost volatility for manufacturers.
- Fine Needle:21-25 gauge aspiration devices extract cellular material rather than intact tissue architecture. Cytopathology workflows in hepatology favor these instruments for cirrhotic liver assessment where core needle yield proves inadequate.
- Surgical:Open excisional instruments target lesions requiring complete removal rather than sampling. Hospital-based oncology departments deploy these for definitive diagnostic-therapeutic procedures.
Established volume favors Core Needle; emerging adoption favors Vacuum-Assisted.
End User:
Capital equipment intensity and sterilization infrastructure requirements create sharp procurement differentiation between integrated health systems and independent diagnostic facilities.
- Hospitals:Tertiary centers command the full technology spectrum from manual needles to robotic navigation platforms. Mid-tier institutions face forced capital decisions as robotic systems compress procedural learning curves.
- Diagnostic Laboratories:Third-party logistics networks now enable these facilities to unbundle tissue acquisition from histological processing. Temperature-controlled courier services connect ambulatory biopsy sites to centralized pathology expertise.
- Clinics:Ambulatory surgical centers capture prostate and breast volume through portable, plug-and-play guidance platforms with reduced sterilization requirements.
- Research Institutions:Academic medical centers in the Netherlands and Germany adopt full-specification systems with real-time specimen radiography for biomarker studies.
Procurement scale concentrates in Hospitals; flexibility requirements favor Clinics.
Application:
Specimen quality demands and molecular profiling complexity determine device selection across disease categories.
- Oncology:Molecular characterization requirements drive demand for vacuum-assisted systems that preserve tissue architecture for immunohistochemistry and next-generation sequencing. Comprehensive cancer centers pursue multi-modal biomarker strategies combining tissue sampling with liquid biopsy workflows.
- Infectious Disease:Fine-needle aspiration dominates deep-seated abscess and lymph node sampling where rapid organism identification takes priority over histological structure.
- Autoimmune Disorders:Renal and salivary gland biopsies follow standardized protocols with core needle instruments.
- Neurology:MRI-guided platforms enable stereotactic brain biopsy with minimal trajectory deviation.
Revenue concentration sits with Oncology; procedure volume expansion favors Infectious Disease.
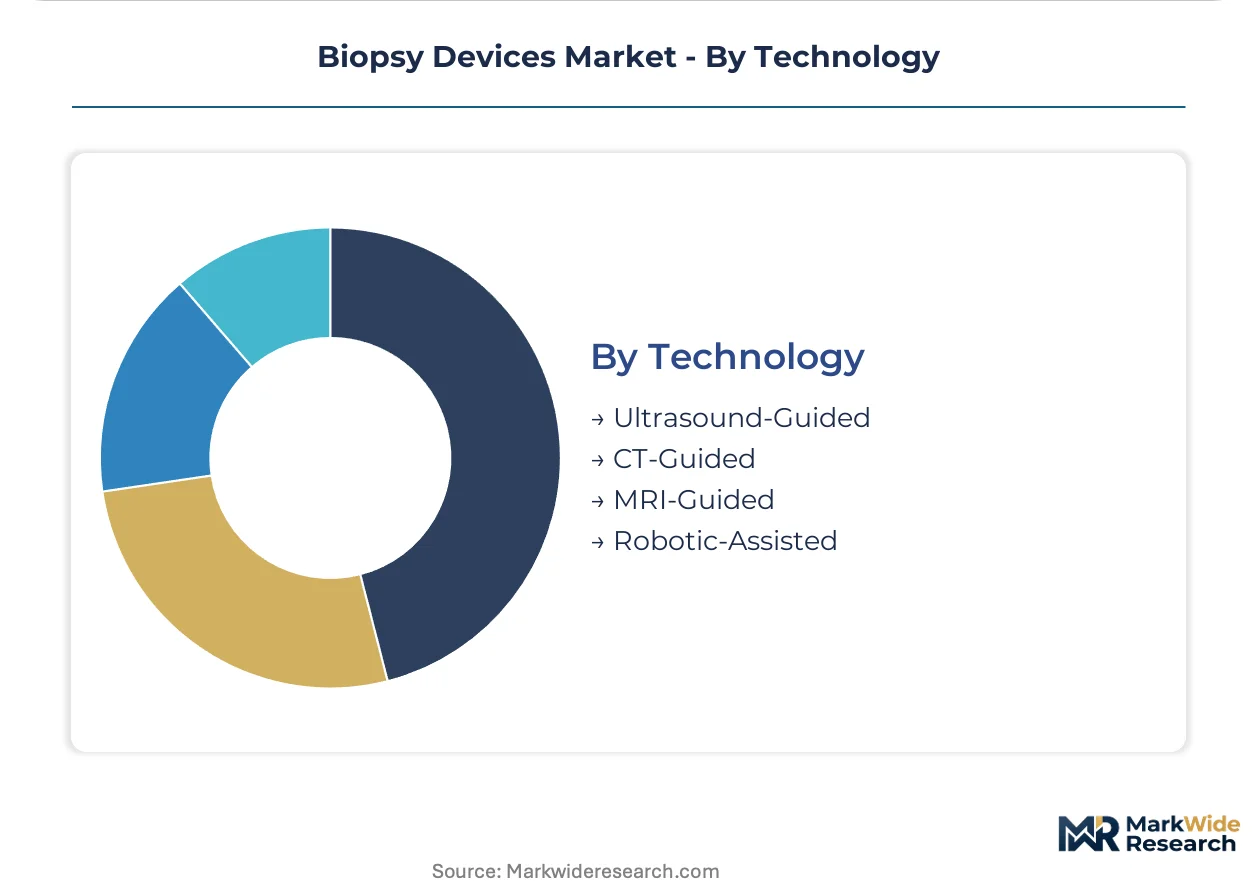
Technology:
Imaging modality integration and software architecture compatibility shape hospital purchasing committees.
- Robotic-Assisted:Computer-assisted needle placement standardizes trajectory accuracy and reduces operator-dependent variability. Japan's PMDA Sakigake designation offers prioritized review for these navigation systems.
- Ultrasound-Guided:Real-time visualization without ionizing radiation dominates outpatient breast, thyroid, and prostate procedures. Portable systems enable ambulatory surgical center expansion.
- CT-Guided:Cross-sectional imaging targets deep thoracic and abdominal lesions beyond sonographic windows.
- MRI-Guided:Magnetic resonance compatibility enables brain and pelvic soft-tissue targeting with superior contrast resolution.
Ultrasound-Guided commands current procedural volume; Robotic-Assisted climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in biopsy device procurement varies sharply across geographies, with German university hospitals absorbing premium vacuum-assisted systems while Indian diagnostic chains prioritize cost-efficient core needle alternatives. The United States sits at the midpoint, where ambulatory surgical centers drive volume through mid-tier ultrasound-guided platforms.
United States
Hospital-based oncology departments are expanding percutaneous biopsy programs, creating dedicated procurement budgets for image-guided systems. The FDA's 510(k) pathway shapes product development priorities through predicate device equivalence requirements. Greater Boston's academic medical centers are consolidating interventional radiology services into centralized diagnostic hubs.
Germany
University medical centers are consolidating interventional radiology services, concentrating demand for vacuum-assisted and robotic-assisted platforms. The EU Medical Device Regulation mandates clinical evidence for Class IIa tissue sampling instruments, elevating compliance costs. Bavaria's hospital networks are standardizing on integrated console platforms with real-time specimen radiography.
Japan
Comprehensive cancer centers are pursuing multi-modal biomarker strategies combining tissue sampling with liquid biopsy workflows. The PMDA's Sakigake designation offers prioritized review for computer-assisted biopsy navigation systems, creating regulatory arbitrage. Tokyo's metropolitan hospital clusters are deploying robotic-assisted systems to standardize needle placement accuracy.
China
Mid-tier hospitals are facing forced capital equipment decisions as robotic systems compress procedural learning curves. The NMPA enforces clinical trial requirements for novel cutting mechanisms, extending time-to-market for indigenous manufacturers. Shanghai's tertiary centers are establishing hub-and-spoke networks with teleproctoring-connected devices at affiliated community hospitals.
India
Diagnostic laboratory chains are unbundling tissue acquisition from histological processing through third-party logistics networks. The CDSCO's medical device registration framework is tightening quality standards for imported needle systems. Maharashtra's private hospital networks are capturing outpatient biopsy volume through portable ultrasound-guided platforms.
Biopsy Devices Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in biopsy devices, with capital-intensity divergence redrawing competitive boundaries. Medtronic leverages end-to-end surgical ecosystems to bundle instruments with imaging navigation platforms, while Becton, Dickinson and Company anchors position through vertical control over needle production infrastructure. Three strategic archetypes dominate: integrated surgical ecosystem providers, precision needle manufacturing specialists, and vacuum-assisted technology innovators. Competitive moves concentrate on M&A for predicate device portfolios and strategic partnerships for robotic navigation software integration.
Among US-based diversified medical technology corporations, Medtronic and Boston Scientific Corporation exemplify the integrated ecosystem archetype, bundling biopsy instruments with broader surgical and navigation portfolios. Becton, Dickinson and Company represents the vertical integration model, with control extending from metallurgical supply through sterile packaging. Hologic occupies a distinct position within the vacuum-assisted specialization tier, dominating breast and prostate applications through proprietary tissue harvesting technology. These three anchors illustrate how regulatory infrastructure, manufacturing depth, and segment focus stratify competitive positioning across hospital procurement committees.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Becton, Dickinson and Company |
| Devicor Medical Products |
| Cardinal Health |
| Hologic |
| Argon Medical Devices |
| Cook Medical |
| Olympus Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term disposable supply contracts lock in both stainless steel needle tubing allocation and price visibility for device manufacturers navigating EU MDR compliance costs. These arrangements concentrate procurement leverage among integrated players with established predicate device portfolios.
Pricing Analysis
After-sales service contracts and preventive maintenance agreements drive lifetime value for robotic-assisted biopsy platforms. Three-tier pricing structure across premium, standard, and economy levels separates integrated console systems from handheld vacuum-assisted devices and commodity core needle alternatives. Price differentiation hinges on FDA 510(k) predicate lineage depth and CE marking tier under EU MDR. Cost compression in mid-tier ultrasound-guided systems is intensifying because ambulatory surgical centers prioritize capital efficiency over advanced imaging integration. Community hospitals exhibit highest price sensitivity; academic medical centers in Germany absorb premium positioning.
Supply Chain Analysis
Italy, Germany, and Sweden anchor premium-grade hypodermic tubing production for 14-20 gauge biopsy instruments. Manufacturing draws from specialized European metallurgical suppliers, medical-grade polymer compounders, and sterile packaging converters. Single-source vulnerability concentrates in stainless steel needle supply among three dominant metallurgical houses. Distribution runs through hospital procurement committees, GPO contracts, and third-party logistics networks connecting ambulatory sites to centralized pathology laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biopsy devices market sits in a cyclical recovery phase driven by hospital capital expenditure normalization following pandemic-era deferred equipment purchases.
For Market Incumbents: Shield market position through backward integration into needle metallurgy and captive sterile packaging infrastructure. Consolidate predicate device portfolios to reduce EU MDR documentation burden across marginal SKUs. Prioritize GPO contract renewal timing ahead of mid-tier hospital robotic system adoption waves. For New Entrants and Emerging Players: Anchor in Japan's PMDA Sakigake fast-track pathway for computer-assisted navigation systems, exploiting regulatory arbitrage against established CE-marked platforms. Target India's diagnostic laboratory chains with cost-optimized core needle alternatives. Pursue teleproctoring-enabled device partnerships with US rural hospital hub-and-spoke networks. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated needle manufacturers with EU MDR-compliant predicate portfolios and established reimbursement coding relationships. Long-term viability over a multi-year horizon favors platforms combining tissue sampling with liquid biopsy workflow integration. Monitor FDA 510(k) clearance velocity for robotic-assisted systems as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market entry through predicate device equivalence for novel cutting mechanisms. |
| CE Marking Pathway | Unlocks EU MDR-compliant access to German university medical center procurement committees. |
| Hospital System Partnership | Secures long-term disposable supply contracts with integrated interventional radiology service lines. |
| Software Companion Development | Enables AI-enabled imaging analysis integration with existing PACS and EMR architectures. |
| Reimbursement Strategy | Aligns device positioning with CMS physician fee schedule adjustments for image-guided procedures. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with interventional radiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) databases, EU MDR notified body filings, CMS Medicare reimbursement data, and hospital procurement system records. Bottom-up and top-down triangulation cross-validated manufacturer shipment data with institutional purchasing patterns.
Across the analysis window, the forecasting framework modeled volume and value trajectories by device type, guidance technology, end-user setting, application area, and regional regulatory cluster. CAGRs were derived from fitted growth curves anchored to historical procedural volume expansion and capital equipment replacement cycles. Forecast inputs incorporated EU MDR compliance cost pass-through assumptions and robotic system adoption elasticity estimates.
Material uncertainties — regulatory timeline slippage, stainless steel supply allocation disruptions, and interventional radiologist workforce constraints — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these factors. Recalibration cycles align with material shifts in hospital capital budgeting and reimbursement policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Global Dermatology Diagnostic Devices Market
Diagnostic Devices
Hemoglobin Testing Devices Market
Diagnostic Devices
Portable Cancer Screen Devices Market
Diagnostic Devices
Hearing Screening Diagnostic Devices Market
Diagnostic Devices
Animal Pregnancy Test Kits Market
Diagnostic Devices
Thrombus Precursor Protein Market
Diagnostic Devices
Skin Moisture Detectors Market
Diagnostic Devices
Pelvic Floor Diagnostics Market
Diagnostic Devices
Contactless Vital Sign Monitoring Device Validation Test Platforms Market
Diagnostic Devices
Bronchial Biopsy Devices Market
Diagnostic Devices
North America Saliva Test Devices Market
Diagnostic Devices
Navigated Biopsy Needles Market
Diagnostic Devices
Procalcitonin Antibody Market
Diagnostic Devices
Europe Breath Analyzer Market
Diagnostic Devices
Sleep Apnea Diagnostic Systems Market
Diagnostic Devices
Global Breath Analyzer Market