
 Smart Medical Loupes Market | 2026-2036
Smart Medical Loupes Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Medical Loupes Market Insights
Multi-source component procurement for LED drivers and prismatic optics is pivoting toward captive in-house production as supply chain reliability becomes a competitive differentiator. Carl Zeiss Meditec anchors its position through backward integration into precision glass molding at its German facilities. Orascoptic competes by sustaining exclusive relationships with North American dental distributors. Designs for Vision specializes in custom prescription TTL configurations for individual practitioners.
Smart medical loupes are wearable magnification devices combining Galilean or Keplerian optical systems with LED illumination, digital image sensors, or AR overlays to enhance visual acuity during precision procedures. Working distances typically range from 340 mm to 550 mm with magnification fields between 2.5x and 6.0x, enabling ergonomic posture during extended surgeries. TTL loupes dominate unit volume due to their lightweight sealed construction and fixed declination angle optimized for dental applications. LED-integrated configurations command premium positioning as clinicians prioritize shadow-free illumination without separate headlight apparatus. Digital and augmented reality segments are attracting R&D investment from manufacturers seeking to overlay patient imaging data directly within the surgeon's visual field.
FDA 510(k) premarket notification requirements govern optical medical device classifications in the United States, while the EU Medical Device Regulation mandates notified body conformity assessment for loupes sold in European member states. ISO 10993 biocompatibility testing and IEC 60601-1 electrical safety standards further constrain material selection and battery subsystem design. Stakeholders must monitor evolving cybersecurity guidance for wireless-enabled digital loupes as connectivity features proliferate across product portfolios.
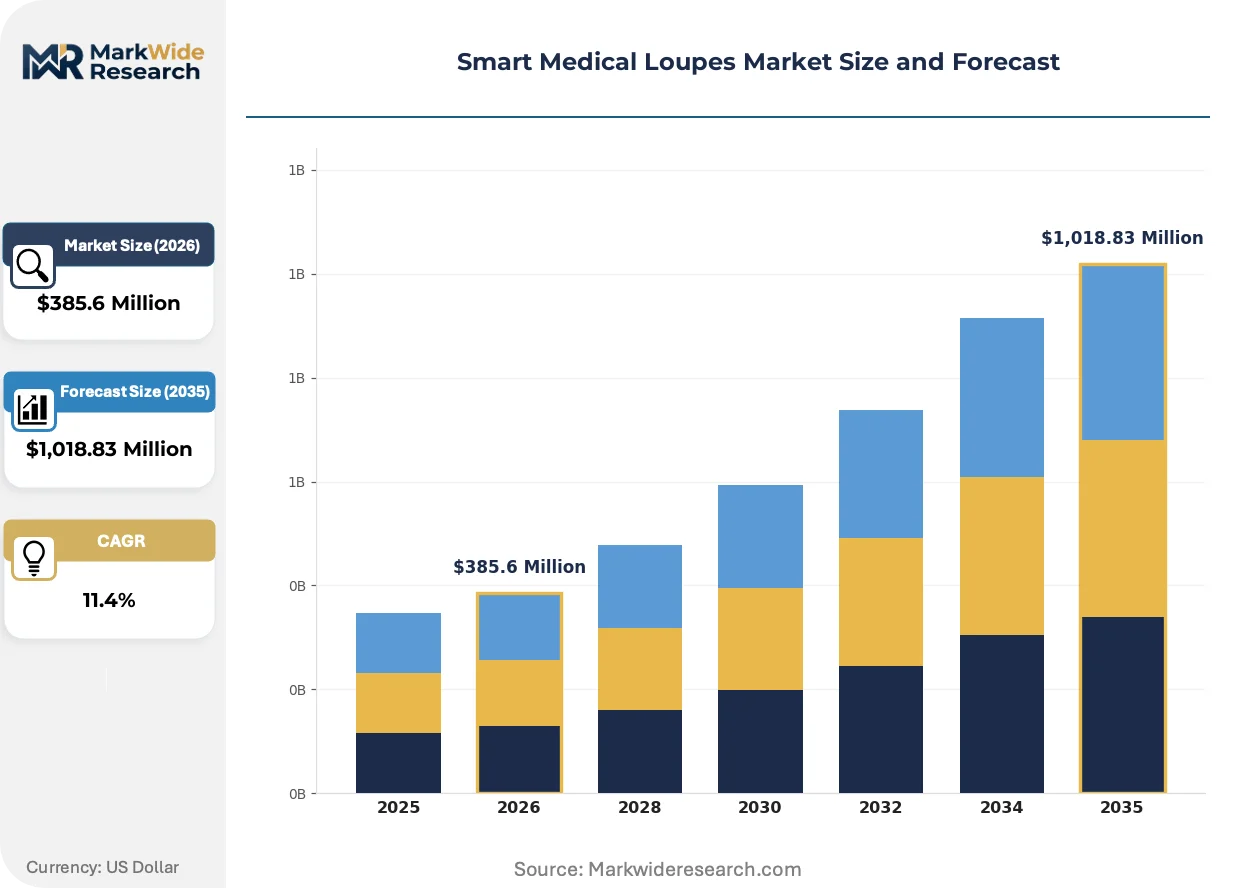
Market Dynamics
LED-integrated TTL configurations are displacing modular headlight systems as dental surgeons prioritize single-device ergonomics and shadow-free illumination during extended procedures. This hardware consolidation is compressing supplier margins while elevating optical performance benchmarks across procurement specifications.
Growth Catalysts
- FDA 510(k) Pre-market Notification:Streamlined clearance pathways for Class II optical devices accelerate commercialization timelines for manufacturers with established predicate devices. Dental distributors prioritize stocked SKUs with active 510(k) clearances.
- Keplerian Prism Optics:High-magnification surgical suites in ophthalmology and neurosurgery are adopting prismatic systems for superior edge-to-edge clarity. German precision optics clusters near Oberkochen supply critical glass-molding expertise.
- Extended Reality Convergence:AR overlay capabilities for patient imaging data are attracting R&D investment from device manufacturers seeking differentiation beyond magnification. Early deployments target orthopedic navigation and microvascular reconstruction.
Market Restraints
- Prismatic Glass Supply Concentration:Precision-molded optical glass production concentrates among three German and Japanese suppliers. Geopolitical friction or energy cost spikes in these corridors transmit directly to component lead times.
- Battery Subsystem Certification Burden:IEC 60601-1 electrical safety testing and ISO 10993 biocompatibility protocols extend development cycles for wireless-enabled digital loupes. Smaller manufacturers lack capital to parallel-track multiple certification streams.
- Fixed-Focus TTL Limitations:Through-the-lens designs with fixed working distances and declination angles frustrate multi-specialty practitioners requiring variable magnification fields. Flip-up Galilean alternatives capture share in surgical segments demanding flexibility.
Strategic Opportunities
- EU MDR Conformity Assessment:Notified body certification requirements for loupes sold in European member states create compliance moats for established manufacturers. Early MDR registrants gain preferential placement in hospital procurement frameworks.
- India Dental Infrastructure Expansion:Private dental clinic chains in Mumbai, Delhi, and Bangalore are modernizing operatories with imported precision optics. Import duty structures favor complete-device shipments over component sourcing.
- Wireless Image Sensor Integration:CMOS sensor miniaturization and low-latency transmission protocols are converging to enable real-time video capture for training and remote consultation. Teaching hospitals represent initial anchor demand.
Industry Challenges
- Optical Design Talent Scarcity:Precision lens design expertise concentrates among aging specialists in Germany and Japan. Knowledge transfer gaps threaten pipeline depth for next-generation AR-optical fusion engineering.
- Multi-Regulatory Parallel Tracking:Simultaneous FDA 510(k), EU MDR, and NMPA (China) submissions strain regulatory affairs bandwidth. Divergent cybersecurity guidance for wireless-enabled devices compounds documentation complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Medical Loupes Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,018.83 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: TTL Loupes, Flip-up Loupes, Headlight-integrated Loupes, Custom Loupes Technology: Optical, LED, Digital, Augmented Reality Application: Dentistry, Surgery, Orthopedics, Veterinary End User: Clinics, Hospitals, Research Institutes, Individual Practitioners |
| Companies Covered | Carl Zeiss Meditec, Orascoptic, Designs for Vision, SurgiTel, Sheer Vision, HEINE Optotechnik, Seiler Instrument, PeriOptix, LumaDent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Medical Loupes Market Trends and Innovations
Digital augmentation layers are merging with established optical hardware, creating hybrid devices that transcend magnification utility. Manufacturers now compete on software integration depth and clinical workflow embedding rather than optical specifications alone.
Micro-OLED display panels are modularizing within loupe-mounted AR subsystems, enabling patient vitals and pre-operative imaging to overlay the surgical field without gaze displacement. Neurosurgical departments at academic medical centers are piloting these configurations for deep-brain procedures. The technology is modularizing previously discrete visualization steps into continuous intraoperative guidance.
EU MDR Article 10 technical documentation requirements are mandating clinical evidence portfolios for optical medical devices previously self-certified under the Medical Devices Directive. Manufacturers must now commission post-market surveillance studies and risk management files exceeding prior CE-marking thresholds. German and French notified bodies are experiencing backlog delays exceeding fourteen months, compressing European launch timelines.
Academic medical centers are consolidating loupe procurement through centralized biomedical engineering committees rather than individual practitioner purchasing. These committees evaluate total cost-of-ownership including sterilization compatibility, warranty terms, and training support. The shift is most pronounced in US multi-hospital systems seeking standardization across residency programs.
Smart Medical Loupes Market Segmentation
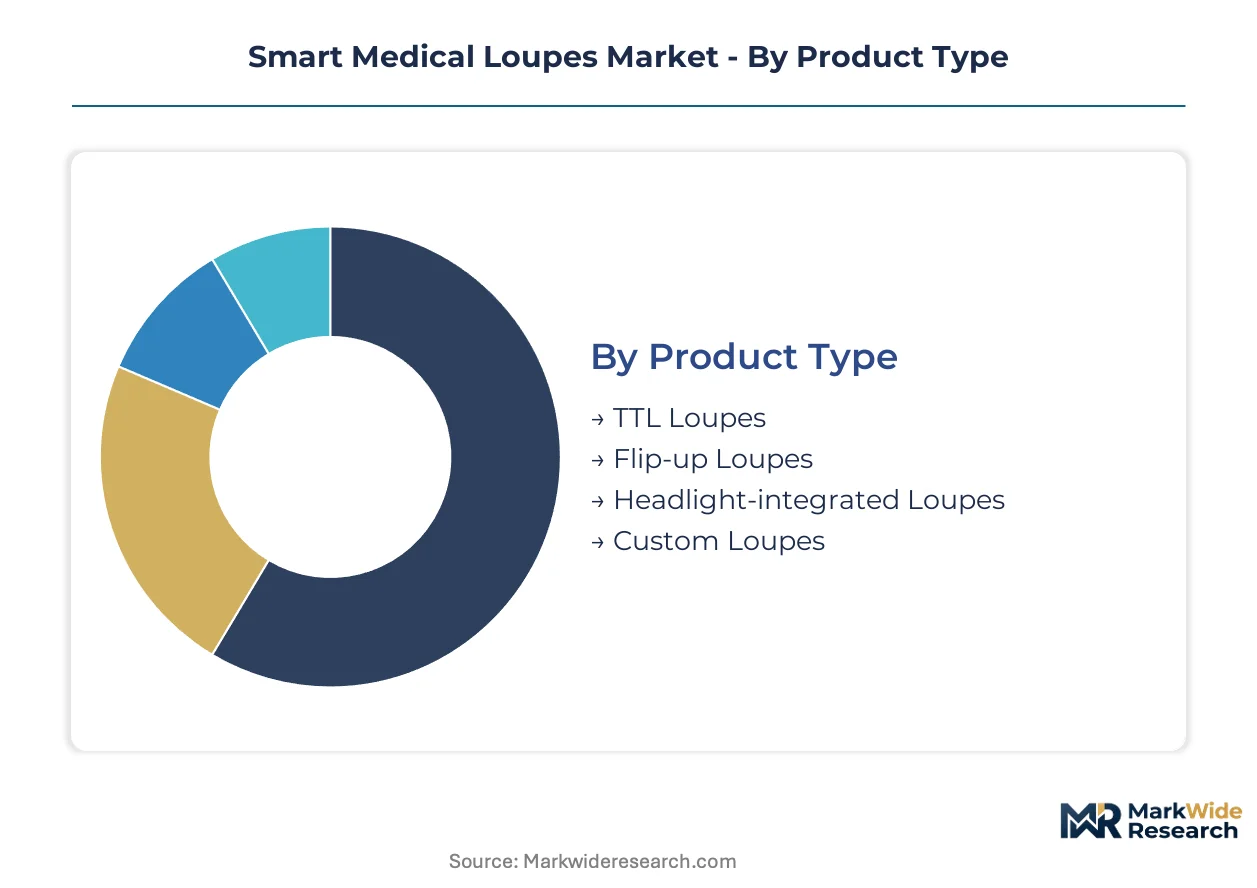
Segmentation in smart medical loupes reveals how procurement specifications diverge across clinical settings and practitioner workflows. Product architecture, illumination integration, and end-user purchasing authority each reshape competitive positioning and margin structures differently.
Product Type:
Standardized sealed configurations dominate high-volume dental procurement, while adjustable mechanical designs capture surgical flexibility requirements.
- TTL Loupes:Through-the-lens designs fuse magnification optics directly into carrier lenses with fixed declination angles between 15 and 45 degrees. Dental clinics across the United States and Germany specify TTL configurations for resident standardization programs, prioritizing lightweight sealed construction over adjustability.
- Flip-up Loupes:Hinged mounting systems permit rapid transition between magnified and unmagnified vision during multi-phase procedures. Orthopedic and general surgical suites in academic medical centers favor flip-up mechanics for the flexibility to alternate between loupe-assisted dissection and unaided visualization.
- Headlight-integrated Loupes:Coaxial LED modules eliminate separate headlight apparatus through unified housing designs. Demand concentrates among oral surgeons performing extended full-mouth reconstructions.
- Custom Loupes:Individual pupillary distance measurements and prescription lens integration accommodate anatomic variation outside standard ranges. Designs for Vision and similar specialists serve practitioners with complex refractive requirements.
Leading the category by volume: TTL Loupes. Growing fastest: Headlight-integrated Loupes.
Technology:
Cost tiers separate mature optical hardware from emerging digital augmentation platforms requiring substantial R&D investment.
- Optical:Galilean and Keplerian lens systems deliver magnification through precision-ground glass without electronic components. German precision optics clusters near Oberkochen supply critical glass-molding expertise for high-endurance surgical applications.
- LED:Integrated solid-state illumination modules attach coaxially to loupe frames, delivering shadow-free field lighting at color temperatures between 4000K and 5500K. Battery subsystem certification under IEC 60601-1 constrains design freedom for wireless-enabled configurations.
- Digital:CMOS image sensors and miniature displays enable video capture and adjustable magnification without optical lens changes. Teaching hospitals represent initial anchor demand for training documentation capabilities.
- Augmented Reality:Micro-OLED display overlays project patient imaging data and real-time vitals within the surgeon's visual field. Neurosurgical departments at academic medical centers pilot AR configurations for deep-brain navigation.
Optical and LED technologies command current revenue concentration. AR configurations are gaining share fastest as manufacturers seek differentiation beyond magnification specifications.
Application:
Procedure complexity and reimbursement levels determine willingness to absorb premium pricing for advanced optical configurations.
- Dentistry:Restorative and endodontic procedures require working distances between 340mm and 420mm with magnification fields of 2.5x to 3.5x. Private dental clinic chains in India are modernizing operatories with imported precision optics.
- Surgery:Microvascular and plastic surgery applications demand 4.0x to 6.0x magnification with extended working distances up to 550mm. Prismatic Keplerian systems from German manufacturers dominate this specification band.
- Orthopedics:Joint reconstruction and spine procedures balance magnification needs with mobility requirements for large operative fields. Flip-up configurations capture preference for the flexibility to survey extended anatomy.
- Veterinary:Companion animal dentistry and exotic species surgery replicate human optical requirements at lower price points. Distribution runs through specialized veterinary equipment suppliers rather than human medical channels.
Dentistry leads by procedure volume. Surgery commands the highest average selling prices per unit.
End User:
Purchasing authority consolidation is shifting procurement from individual practitioners toward institutional committees evaluating total cost-of-ownership.
- Clinics:Private dental and outpatient surgical practices maintain direct purchasing relationships with manufacturer sales representatives. Individual practitioners retain authority over loupe selection in smaller group practices.
- Hospitals:Centralized biomedical engineering committees now evaluate sterilization compatibility, warranty terms, and training support across multi-hospital systems. Standardization across residency programs compresses vendor diversity.
- Research Institutes:Academic medical centers pilot emerging AR and digital configurations for clinical workflow validation. Procurement prioritizes technology access over unit economics.
- Individual Practitioners:Solo practitioners and early-career residents purchase entry-level configurations through distributor financing programs. Price sensitivity peaks in this segment.
Clinics currently lead unit volume. Hospital procurement committees are expanding their share fastest through system-wide standardization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision-molded optical glass from German manufacturing clusters near Oberkochen and Jena supplies critical lens components for high-endurance surgical applications worldwide. Demand concentration varies sharply across regulatory environments and reimbursement structures.
United States
Dental clinic chains and academic medical centers drive procurement of LED-integrated TTL configurations for resident standardization programs. FDA 510(k) premarket notification requirements govern Class II optical device classifications, with dental distributors prioritizing stocked SKUs holding active clearances. The Greater Boston and Pacific Northwest surgical corridors concentrate demand for prismatic Keplerian systems in microvascular specialties.
Germany
Precision optics manufacturing clusters in Baden-Württemberg and Thuringia supply critical glass-molding expertise for Keplerian prism systems. EU Medical Device Regulation notified body conformity assessments mandate expanded clinical evidence portfolios, with German and French notified bodies experiencing backlog delays exceeding fourteen months. Oberkochen-based manufacturers anchor backward integration into captive glass production.
India
Private dental clinic chains in Mumbai, Delhi, and Bangalore are modernizing operatories with imported precision optics as oral healthcare infrastructure expands. Central Drugs Standard Control Organization import regulations and duty structures favor complete-device shipments over component sourcing. Maharashtra and Karnataka concentrate procurement decision-making for multi-clinic dental networks.
Japan
Ophthalmology and neurosurgery suites in Tokyo and Osaka academic centers specify high-magnification prismatic configurations for edge-to-edge clarity requirements. Ministry of Economy, Trade and Industry industrial standards and Pharmaceuticals and Medical Devices Agency device registrations constrain market entry timelines. Nagoya-area precision manufacturing maintains optical component supply relationships with domestic surgical device assemblers.
China
Teaching hospitals in Beijing and Shanghai pilot digital and augmented reality configurations for surgical training documentation and intraoperative navigation. National Medical Products Administration submissions run parallel to FDA and EU MDR tracks, straining regulatory affairs bandwidth for wireless-enabled devices. Yangtze River Delta manufacturing clusters are developing domestic optical glass molding capabilities to reduce import dependency.
Smart Medical Loupes Market Competitive Landscape
Global majors compete with regional champions across regulatory certification depth and distributor relationship exclusivity. Market structure tilts toward consolidation at the premium optical tier while fragmenting across entry-level configurations. Three archetypes dominate: vertically integrated precision optics specialists, distributor-exclusive regional champions, and custom prescription configurators. Competitive moves concentrate on backward integration into glass molding and exclusive distributor lockups.
Within the precision optics tier, Carl Zeiss Meditec anchors German manufacturing heritage through captive production capabilities. Orascoptic and Designs for Vision occupy distinct positioning vectors—Orascoptic exemplifying North American distributor-channel dominance, Designs for Vision representing individual-practitioner customization specialization. These three entities collectively illustrate how competitive advantage derives from supply chain control, channel access, or bespoke configuration depth rather than interchangeable optical specifications.
| Leading Market Players |
|---|
| Carl Zeiss Meditec |
| Orascoptic |
| Designs for Vision |
| SurgiTel |
| Sheer Vision |
| HEINE Optotechnik |
| Seiler Instrument |
| PeriOptix |
| LumaDent |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between FDA 510(k)-cleared configurations and uncertified imports manifests in both pricing premiums and supply chain sourcing patterns. German and Japanese precision optics command three-to-five-fold price multiples over Asian alternatives, with warranty bundling and training support driving total cost-of-ownership divergence across procurement committees.
Pricing Analysis
Warranty and service-bundling structures separate premium German manufacturers from entry-level competitors, with extended coverage and resident training programs embedded in institutional contracts. Pricing stratifies across premium, standard, and economy tiers based on optical certification grade and LED subsystem IEC 60601-1 compliance status. Cost compression in the economy tier intensifies as Indian dental clinic chains negotiate volume procurement of complete-device shipments. Individual practitioners exhibit highest price sensitivity, while academic medical center committees prioritize sterilization compatibility and warranty terms over unit cost.
Supply Chain Analysis
Freight cost escalation for precision-molded optical glass has compressed margins on trans-Atlantic component shipments, favoring regional assembly strategies. Supply concentrates in Germany, Japan, and emerging Yangtze River Delta facilities for critical lens substrates. Production draws from prismatic glass, CMOS sensors, and lithium-polymer battery cells as core inputs. Single-source vulnerability in German glass-molding expertise threatens lead time stability for Keplerian configurations. Distribution runs through North American dental distributors and European hospital procurement frameworks as dominant downstream channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story, with EU MDR notified body certification creating fourteen-month backlog moats that defend established manufacturers against unqualified entrants.
For Market Incumbents: Deploy captive glass-molding capacity expansion in Baden-Württemberg to secure prismatic optics supply against Japanese competitor encroachment. Deepen exclusive distributor lockups with North American dental chains before MDR-registrant competitors clear European notified body queues. Battery subsystem certification investment represents the priority defensive lever against wireless-enabled digital entrant disruption.
For New Entrants and Emerging Players: Launch via direct-to-clinic digital sales models targeting Indian private dental chains in Maharashtra and Karnataka, bypassing established distributor relationships. White-space concentration sits with AR-overlay configurations for orthopedic navigation, where regulatory pathways remain unsettled and incumbent R&D investment lags neurosurgical applications. Teaching hospital pilot programs offer the most penetrable anchor demand for CMOS-integrated training documentation systems.
For Investors and Strategic Acquirers: Re-rating potential sits with precision optics specialists possessing captive glass-molding capabilities given EU MDR compliance backlog duration. Long-term viability over the next decade favors manufacturers with parallel FDA 510(k), EU MDR, and NMPA submission capacity. Watch German notified body processing velocity as the critical inflection signal for European market access timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Certification | Fourteen-month backlog creates compliance moats for early registrants in hospital procurement frameworks. |
| Backward Integration into Glass Molding | Oberkochen-based captive production secures prismatic optics supply against geopolitical friction. |
| Wireless Image Sensor Integration | CMOS miniaturization enables real-time surgical training documentation for academic medical centers. |
| Exclusive Distributor Partnerships | North American dental channel lockups defend market share against emerging AR configuration competitors. |
| AR Overlay Development | Micro-OLED integration for patient imaging data attracts R&D investment beyond magnification specifications. |
Research Methodology
Multi-period observation of FDA 510(k) clearance timelines, EU MDR notified body backlog durations, and precision optics import patterns anchored the trend analysis, supplemented by interviews with hospital biomedical engineering committee directors, dental clinic procurement managers, German precision optics manufacturing executives, and GPO contracts specialists. Secondary validation drew from FDA device classification databases, EUDAMED registration records, German foreign trade statistics, and hospital capital equipment procurement disclosures. Bottom-up demand modeling across product type, technology, application, and end-user segments triangulated against top-down optical device market sizing.
Segment-weighting approaches distributed revenue projections across TTL, flip-up, headlight-integrated, and custom loupe configurations, with technology tiers spanning optical, LED, digital, and augmented reality platforms. Application segmentation captured dentistry, surgery, orthopedics, and veterinary end-uses, while end-user splits tracked clinics, hospitals, research institutes, and individual practitioners. CAGRs were derived from install-base replacement cycles, clinic modernization rates in India, and AR configuration adoption curves across academic medical centers. Forecast inputs included LED driver component lead times, precision glass molding capacity utilization, and wireless-enabled device cybersecurity guidance evolution.
Regulatory approval delays, supply chain disruption in German optics clusters, and faster-than-expected CMOS sensor cost declines are the dominant revision risks to modeled projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Single Use Contact Lenses Market
Medical Devices
Nasal Implant Market
Medical Devices
Skull Deformity Implants Market
Medical Devices
Global Transdermal Skin Patches Market
Medical Devices
Walking Aids Market
Medical Devices
Global Oxygen Conservation Devices Market
Medical Devices
Global Endodontic Reparative Cement Market
Medical Devices
Ligament Stabilizers Market
Medical Devices
Wearable Medical Technology Market
Medical Devices
Engine-Driven Endodontic File Market
Medical Devices
Physiotherapy Laser Wrist Watch Market
Medical Devices
Needle-Free IV Connectors Market
Medical Devices
Medical Bionic Implant/Artificial Organs Market
Medical Devices
Small Bone and Joint Devices Market
Medical Devices
Contact and Intraocular Lenses Market
Medical Devices
Allergic Rhinitis Treatment Device Market