
 Gastric Bands Market | 2026-2036
Gastric Bands Market Size, Share, and Industry Trends Forecast 2026-2036
Gastric Bands Market Foresight
High-precision silicone elastomer specifications is collapsing the gap between premium and mid-tier gastric band offerings. Ethicon sustains broad surgical portfolio leverage across bariatric suites. Medtronic anchors its position through deep laparoscopic instrument integration. Apollo Endosurgery differentiates with specialized endolumenal innovation pipelines.
Gastric bands are implantable silicone devices with inflatable inner balloons, designed to restrict stomach volume and induce early satiety through laparoscopic placement around the upper stomach. Adjustable gastric bands dominate procedural volumes due to reversible fill-port calibration that tailors restriction to patient progression. Bariatric clinics and surgical centers capture the densest margin pools as case volumes shift toward outpatient settings. Non-adjustable variants occupy cost-sensitive segments where revision tolerance remains low.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements govern market entry timelines and clinical evidence burdens for manufacturers. ISO 10993 biocompatibility testing and ASTM F2063 fatigue standards further constrain material selection and validation protocols. Stakeholders must monitor reimbursement recalibrations by CMS and Germany's G-BA as these bodies weigh gastric band efficacy against sleeve gastrectomy alternatives.
Market Dynamics
Adjustable gastric band systems are displacing non-adjustable alternatives as bariatric clinics prioritize reversible, patient-calibrated restriction mechanisms that reduce revision surgery rates and extend device lifecycle value.
Growth Catalysts
- FDA 510(k) Pre-market Notification:Streamlined clearance pathways for predicate device submissions accelerate time-to-market for silicone elastomer band iterations, encouraging incremental innovation cycles.
- Bariatric Clinic Outpatient Migration:Surgical centers in the United States and Germany are consolidating laparoscopic case volumes into ambulatory settings, driving demand for compact, portable adjustment systems.
- Silicone Elastomer Specification Convergence:High-precision material standards are collapsing performance gaps between premium and mid-tier offerings, expanding addressable patient pools across reimbursement tiers.
Market Restraints
- Medical-Grade Silicone Supply Concentration:Raw material sourcing depends on a limited base of ISO 10993-certified polymer suppliers, creating vulnerability to pharmaceutical sector demand surges.
- EU MDR Technical Documentation Burden:Extended clinical evidence requirements and notified body capacity constraints are lengthening certification timelines for new market entrants.
- Sleeve Gastrectomy Substitution:Metabolic surgery alternatives with superior long-term weight loss outcomes are capturing patient preference and payer authorization in established markets.
Strategic Opportunities
- Brazil ANVISA Regulatory Alignment:Convergence with international standards is reducing import friction for CE-marked devices, opening private-pay surgical segments in São Paulo and Rio de Janeiro corridors.
- Telemedicine-Integrated Fill-Port Calibration:Remote adjustment protocols paired with connected monitoring devices enable post-operative care extension into rural and underserved catchment areas.
- Japan PMDA Priority Review Designation:Expedited pathways for obesity devices addressing metabolic syndrome comorbidities offer first-mover positioning in an aging, surgical-candidate population.
Industry Challenges
- Laparoscopic Technique Specialization Gap:Declining gastric band procedure volumes in training programs are reducing surgeon pipeline depth, constraining expansion into secondary markets.
- ASTM F2063 Fatigue Validation Complexity:Accelerated lifecycle testing requirements demand extended capital equipment investment and specialized biomechanical engineering talent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gastric Bands Market |
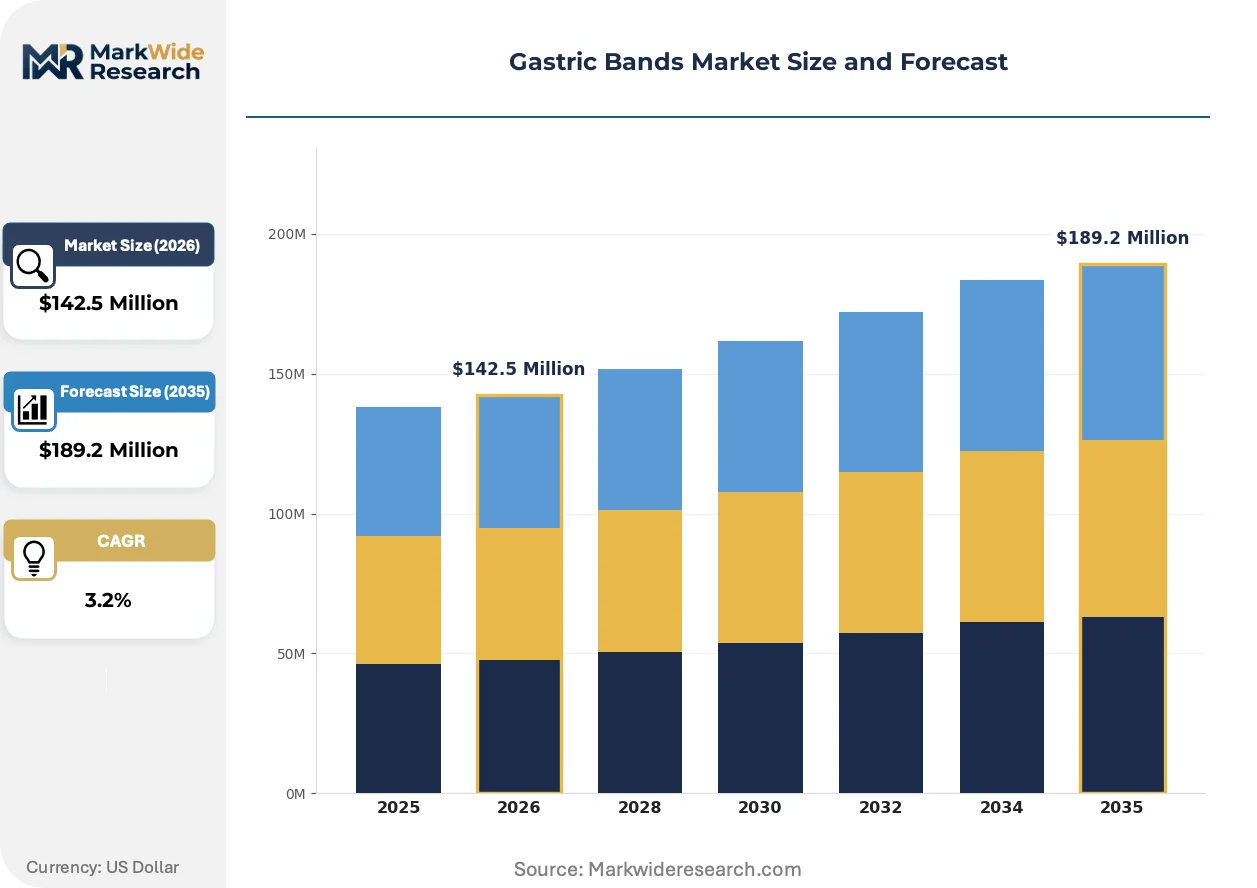
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $189.2 Million |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adjustable Gastric Bands, Non-Adjustable Gastric Bands, Lap-Band Systems, Realize Band, Swedish Adjustable Gastric Band, Others Application: Obesity Treatment, Bariatric Surgery, Weight Management, Metabolic Syndrome Intervention, Diabetes Control, Digestive Health Enhancement End User: Bariatric Clinics, Surgical Centers, Private Hospitals, Ambulatory Surgical Units, Specialized Weight Loss Centers, Academic Medical Facilities Deployment: Hospital-Based, Outpatient Clinics, Ambulatory Surgical Centers, Specialty Care Facilities, Private Practices, Wellness Centers |
| Companies Covered | Apollo Endosurgery, Ethicon, Johnson & Johnson, Cousin Biotech, Medtronic, Intuitive Surgical, Olympus Corporation, Helioscopie, ReShape Lifesciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gastric Bands Market Shifts & Advancements
Miniaturization of implantable components and digital integration are redefining device architecture, while regulatory harmonization efforts and shifting care delivery models reshape competitive requirements across manufacturing and distribution layers.
Next-generation gastric band systems are miniaturizing fill-port mechanisms and internal balloon geometries to reduce foreign body sensation and erosion incidence. Bariatric surgeons in high-volume United States and German centers are adopting these profiles for outpatient same-day discharge protocols. The technology is miniaturizing hardware footprints while maintaining pressure-calibration precision, compressing the differentiation space between established portfolios and emerging entrants.
EU MDR post-market surveillance mandates are intensifying clinical follow-up obligations and periodic safety reporting frequency for implantable obesity devices. Manufacturers must now maintain extended patient registries and real-world evidence collection infrastructure across multiple member states. Adjustable band categories face the steepest compliance cost escalation as legacy predicate devices require retrospective clinical data remediation.
Hospital procurement committees are unbundling device purchasing from procedure bundling, enabling direct-to-facility contracting for gastric band inventory. Independent surgical centers in the United States are bypassing traditional distributor markups through group purchasing organization aggregation. This disintermediation concentrates price negotiation leverage among multi-site bariatric networks while compressing margins for regional device distributors.
Gastric Bands Market Segmentation
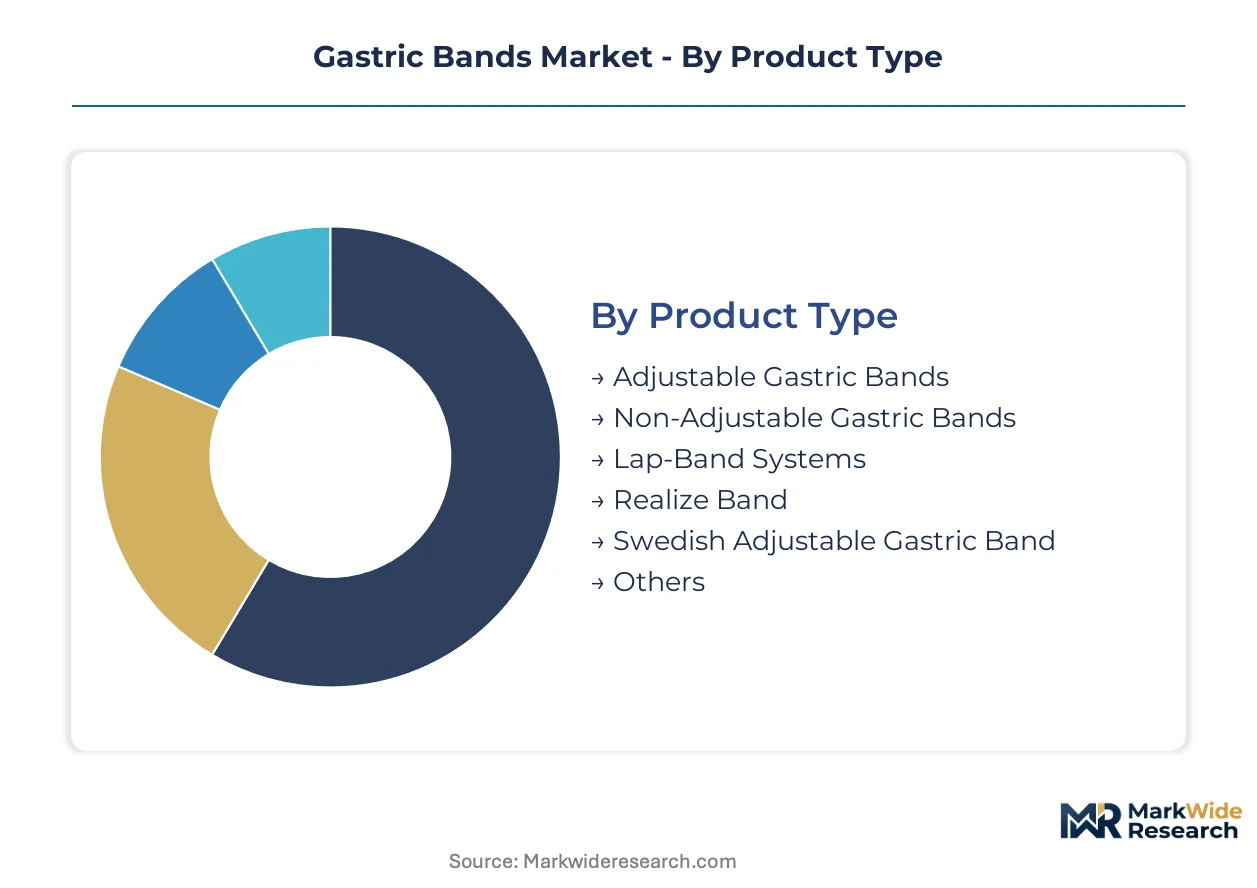
Segmentation in the gastric bands market reveals how device specifications, clinical settings, and reimbursement pathways intersect to determine procurement patterns. Understanding these divides exposes where manufacturers can defend margin and where price competition intensifies.
Product Type:
Adjustable systems flow through bariatric clinic direct purchasing channels, while non-adjustable variants concentrate in distributor-mediated hospital procurement.
- Adjustable Gastric Bands:Silicone elastomer construction with subcutaneous fill-ports enables post-implant restriction calibration. Demand concentrates in United States bariatric clinics where CMS reimbursement codes favor reversible interventions and outpatient adjustment protocols.
- Non-Adjustable Gastric Bands:Fixed-diameter polymer rings deliver permanent restriction without follow-up access ports. Germany's G-BA cost-effectiveness thresholds drive adoption in statutory insurance-covered procedures where revision tolerance is minimal.
- Lap-Band Systems:Proprietary fill-port geometries and standardized laparoscopic placement kits.
- Realize Band:Oval-shaped balloon design optimized for patient anatomy variation.
- Swedish Adjustable Gastric Band:European-origin specification with established CE-marking pedigree.
- Others:Niche configurations for specific anatomical indications or regional regulatory submissions.
Adjustable gastric bands dominate installed base. Non-adjustable gastric bands are where expansion concentrates in cost-sensitive reimbursement environments.
Application:
Cost tier stratification separates metabolic syndrome interventions commanding premium pricing from commoditized weight management protocols.
- Obesity Treatment:Primary indication driving procedural volume with established CPT coding and DRG classification.
- Bariatric Surgery:Comprehensive metabolic intervention category with bundled payment structures.
- Weight Management:Lifestyle-integrated protocols in wellness center settings with direct-pay patient segments.
- Metabolic Syndrome Intervention:Comorbidity-focused positioning targeting cardiovascular risk reduction endpoints. United States academic medical centers prioritize these indications for outcomes-based contracting with commercial payers.
- Diabetes Control:Glycemic improvement as primary endpoint with endocrinology referral pathways.
- Digestive Health Enhancement:GERD and reflux symptom modification through fundoplication-sparing approaches. German surgical centers report these cases for quality registry benchmarking against sleeve gastrectomy alternatives.
Obesity treatment anchors volume. Metabolic syndrome intervention is climbing the fastest as payers recalibrate authorization criteria.
End User:
Customer type determines service intensity, with bariatric clinics demanding highest technical support and ambulatory units prioritizing capital efficiency.
- Bariatric Clinics:Dedicated metabolic surgery facilities with standardized band adjustment protocols and patient monitoring infrastructure. United States multi-site networks negotiate direct manufacturer contracts bypassing distributor markups.
- Surgical Centers:High-volume laparoscopic procedure hubs with same-day discharge capabilities. German outpatient surgery centers leverage G-BA reimbursement for ambulatory bariatric interventions.
- Private Hospitals:Full-service institutions with mixed payer populations and inpatient observation capacity.
- Ambulatory Surgical Units:Standalone procedure facilities with compressed supply chain requirements.
- Specialized Weight Loss Centers:Integrated medical and surgical obesity management with dietician staffing.
- Academic Medical Facilities:Training programs and clinical trial sites with extended follow-up obligations.
Bariatric clinics dominate installed base. Ambulatory surgical units are gaining share fastest as case migration accelerates.
Deployment:
Geography of care delivery shapes device specification requirements, with hospital-based deployment demanding full instrument integration and private practices prioritizing portability.
- Hospital-Based:Integrated operating room ecosystems with sterilization infrastructure and emergency backup capacity.
- Outpatient Clinics:Intermediate acuity settings with limited overnight observation capabilities.
- Ambulatory Surgical Centers:Same-day discharge protocols with compressed supply chain and just-in-time inventory. United States freestanding ASCs drive demand for compact adjustment kits and remote fill-port access systems.
- Specialty Care Facilities:Disease-specific centers with focused clinical expertise and referral networks.
- Private Practices:Individual surgeon offices with direct patient relationships and flexible scheduling.
- Wellness Centers:Lifestyle intervention hubs with non-surgical weight management integration.
Hospital-based deployment retains volume leadership. Ambulatory surgical centers are where expansion concentrates as regulatory frameworks accommodate same-day metabolic procedures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of silicone elastomer gastric bands concentrate from United States and German manufacturing hubs toward Latin American and Asia-Pacific surgical markets, while import dependency shapes procurement strategies in Brazil and Japan where domestic production remains limited.
United States
Bariatric clinic networks in Texas and Florida drive adjustable band procurement volumes as ambulatory surgical centers expand same-day discharge protocols. FDA 510(k) premarket notification requirements govern device clearance timelines, with predicate device pathways accelerating iterative product launches. The Dallas-Fort Worth corridor hosts concentrated distribution infrastructure serving multi-site surgical networks across the Sun Belt.
Germany
G-BA reimbursement frameworks prioritize cost-effectiveness thresholds that sustain demand for non-adjustable bands in statutory insurance segments. EU MDR technical documentation requirements and notified body capacity constraints extend certification timelines for new market entrants. The Rhine-Ruhr metropolitan region anchors surgical device manufacturing clusters with integrated sterilization and logistics capabilities serving Western European markets.
Brazil
Private-pay surgical segments in São Paulo and Rio de Janeiro corridors absorb imported CE-marked devices as ANVISA regulatory alignment reduces import friction for international manufacturers. Brazil's national health surveillance agency convergence with ISO 13485 quality management standards streamlines market access for established European and North American suppliers. The São Paulo metropolitan area concentrates high-volume bariatric surgery centers with direct procurement relationships bypassing traditional distributor channels.
Japan
PMDA priority review designations for obesity devices addressing metabolic syndrome comorbidities create expedited pathways in an aging surgical-candidate population. Japan's Ministry of Health, Labour and Welfare reimbursement pricing surveys influence device procurement decisions in academic medical centers. The Tokyo-Osaka corridor hosts specialized metabolic surgery facilities with integrated patient monitoring infrastructure for long-term band adjustment protocols.
Australia
TGA conformity assessment procedures for Class III implantable devices require extensive clinical evidence packages that favor established manufacturers with predicate device histories. Australia's private health insurance sector drives demand for adjustable systems in elective bariatric procedures outside public hospital waiting lists. The Sydney-Melbourne corridor concentrates surgical volume with group purchasing organization aggregation compressing distributor margins.
Gastric Bands Market Competitive Landscape
Listed leaders compete with private specialists across regulatory compliance capabilities and surgical portfolio breadth. The vendor base concentrates around diversified medical technology conglomerates with integrated laparoscopic instrument ecosystems and specialized obesity device pure-plays with focused innovation pipelines. Three archetypes dominate: diversified surgical portfolio holders, endolumenal technology specialists, and regional contract manufacturers. Competitive moves center on M&A consolidation of adjustment system technologies and strategic partnerships with bariatric clinic networks for direct procurement channel access.
Within the diversified surgical portfolio tier, Johnson & Johnson and Medtronic occupy positions anchored by broad operating room ecosystem integration, while Apollo Endosurgery exemplifies the specialized endolumenal innovation archetype with focused obesity intervention pipelines. Ethicon sits within the premium-tier vector as a standalone surgical device entity, and ReShape Lifesciences represents the metabolic surgery pure-play model with concentrated band system specialization. Intuitive Surgical and Olympus Corporation anchor the robotic and endoscopic platform extension strategies respectively, leveraging installed base leverage for procedural device attachment.
| Leading Market Players |
|---|
| Apollo Endosurgery |
| Ethicon |
| Johnson & Johnson |
| Cousin Biotech |
| Medtronic |
| Intuitive Surgical |
| Olympus Corporation |
| Helioscopie |
| ReShape Lifesciences |
| Others |
Supply & Pricing Matrix
Silicone elastomer specification convergence is replacing legacy polymer grades across gastric band manufacturing, simultaneously shifting procurement geography toward ISO 10993-certified suppliers in the United States and Germany while compressing margin differentials between premium and mid-tier device tiers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across premium, standard, and economy tiers based on FDA 510(k) predicate lineage and after-sales calibration service bundling. Price differentiation hinges on CE-marking pedigree and volume scale commitments from multi-site bariatric networks. Cost compression in the mid-tier is intensifying because German G-BA cost-effectiveness thresholds are squeezing statutory insurance reimbursement bands. Ambulatory surgical centers exhibit highest price sensitivity due to compressed capital budgets, while academic medical centers prioritize outcome-linked contracting with lower elasticity.
Supply Chain Analysis
Inventory lead times for medical-grade silicone polymers have extended as pharmaceutical sector demand surges compete for ISO 10993-certified elastomer allocation. Manufacturing concentrates in the United States, Germany, and Switzerland, with raw material sourcing drawing from Dow Corning and Wacker Chemie polymer streams. Single-source vulnerability pervades the fill-port valve component tier, where specialized precision molding capacity remains captive to two European suppliers. Distribution runs through group purchasing organization aggregation serving United States bariatric clinic networks, bypassing traditional regional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gastric bands are cycling through a demand recovery phase as sleeve gastrectomy substitution pressure moderates and outpatient migration protocols stabilize reimbursement pathways for adjustable systems.
For Market Incumbents: Consolidate adjustment system technology portfolios through targeted acquisition of remote fill-port calibration platforms, neutralizing telemedicine-integrated challengers. Deepen backward integration into medical-grade silicone compounding to secure polymer allocation priority against pharmaceutical sector demand spikes. Lock in multi-year GPO contracts with United States bariatric clinic networks before ANVISA-aligned Brazilian entrants achieve CE-marking parity.
For New Entrants and Emerging Players: Post-operative remote monitoring service gaps expose white-space where incumbents under-serve rural catchment areas with limited bariatric surgeon density. Target Japan's PMDA priority review pathway for metabolic syndrome indications, leveraging expedited clearance to establish first-mover positioning ahead of EU MDR-compliant rivals. Pursue direct-to-facility contracting with São Paulo private-pay surgical centers, bypassing distributor infrastructure entirely.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed metabolic surgery pure-plays holding concentrated band system specialization but lacking laparoscopic instrument ecosystem integration. Five-to-ten year viability depends on successful pivot toward endolumenal obesity device pipelines as gastric band procedural volumes face structural decline. Watch CMS reimbursement recalibration signals for adjustable versus sleeve gastrectomy coding parity as the critical inflection indicator for portfolio reallocation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Remediation | Legacy predicate devices require retrospective clinical data investment to maintain CE-marking validity across adjustable band portfolios. |
| Telemedicine-Integrated Fill-Port Development | Remote adjustment protocols paired with connected monitoring extend post-operative care into underserved rural catchment areas. |
| Medical-Grade Silicone Backward Integration | In-house polymer compounding secures ISO 10993-certified supply priority against pharmaceutical sector demand competition. |
| Brazil ANVISA Regulatory Alignment | Convergence with international standards reduces import friction for CE-marked devices entering São Paulo private-pay segments. |
| Japan PMDA Priority Review Pursuit | Expedited pathways for metabolic syndrome comorbidities offer positioning advantage in aging surgical-candidate demographics. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with bariatric surgeons, hospital purchasing committee members, GPO contracts managers, and biomedical engineers; and secondary validation against FDA 510(k) premarket notification databases, EU MDR technical documentation filings, CMS Medicare reimbursement code updates, and German G-BA cost-effectiveness assessment records. Bottom-up procedure volume modeling triangulated against top-down manufacturer revenue segmentation across the analysis window.
Across the projection horizon, the analytical framework modeled demand by product type, application indication, end-user facility category, and deployment setting. CAGRs were derived from segmented volume projections calibrated to reimbursement pathway evolution and surgeon training pipeline depth. Forecast inputs incorporated EU MDR certification timeline delays and Brazil ANVISA regulatory convergence pace as scenario variables.
Forecasts assume regulatory continuity in FDA 510(k) clearance pathways and EU MDR post-market surveillance regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Device Regulatory Affairs Market
Medical Devices
Digital Respiratory Devices Market
Medical Devices
Global Esophageal Catheters Market
Medical Devices
Contact Thermometer Market
Medical Devices
Global Venous Blood Collection Devices Market
Medical Devices
Ventilation Devices Market
Medical Devices
Bone Allografts Market
Medical Devices
Drug Delivery Systems Market
Medical Devices
Peritoneal Catheter Systems Market
Medical Devices
Skull Clamp Market
Medical Devices
Sleep Apnea Devices Market
Medical Devices
Human Anatomy Model Market
Medical Devices
Global Doppler Ultrasound Systems Market
Medical Devices
Injection Practice Pad Market
Medical Devices
Computer-Aided Oral and Maxillofacial Surgery Market
Medical Devices
Prescription Goggles Market