
 Medical Device Films Market | 2026-2036
Medical Device Films Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Device Films Market Foresight
North American specialty film producers is recalibrating capacity toward medical-grade cleanroom extrusion to serve Class II and III device packaging needs. Amcor plc leverages its multilayer coextrusion platform to dominate high-barrier sterile packaging for implantable devices. Berry Global Inc. anchors North American supply through vertically integrated resin-to-film operations with dedicated medical lines. DuPont de Nemours Inc. differentiates via silicone-coated release films used in advanced wound care laminates.
Medical device films constitute engineered polymer membranes, typically 12–250 microns in thickness, manufactured through blown or cast extrusion with controlled crystallinity and surface energy for sterile barrier, adhesion, or breathability functions. Polyethylene formulations lead volume in flexible packaging for disposable instruments due to cost and sealability, while polypropylene films capture margin in autoclave-resistant applications requiring higher thermal tolerance. Nylon barrier layers serve device components and monitoring applications where oxygen and moisture ingress must stay below stringent thresholds.
FDA enforces biocompatibility and sterility validation under 21 CFR Part 820, while EU MDR requires notified body certification for films contacting blood or tissue. ISO 11607 governs sterile barrier systems globally, pushing film suppliers toward documented lot traceability and extractables testing. Stakeholders must monitor how ECHA REACH restrictions on phthalate plasticizers and emerging state-level perfluorinated substance bans reshape material qualification pipelines.
Market Dynamics
Medical device films face structural compression from the EU MDR's 2024 full enforcement deadline, forcing suppliers to rebuild validation dossiers and migrate toward notified body-certified cleanroom production or exit the European market entirely.
Growth Catalysts
- EU MDR Compliance Mandate:The regulation's strict biocompatibility requirements for films contacting tissue or blood are filtering out uncertified suppliers and concentrating volume among validated producers.
- Autoclave-Resistant Polypropylene:Hospitals in Germany's Tuttlingen corridor are specifying high-temperature sterilizable films for reusable surgical instrument sets, pulling material innovation toward thermal stability.
- Layer-by-Layer Assembly:Implantable device manufacturers are adopting nanolaminate barrier structures that combine nylon oxygen blocking with peelable sealant layers.
Market Restraints
- Resin Supply Concentration:Medical-grade polyethylene and polypropylene feedstocks concentrate among Gulf Coast petrochemical complexes, exposing film converters to hurricane disruption and force majeure events.
- Extractables Testing Burden:ISO 10993-18 chemical characterization requirements add 12-18 months to new film qualification, freezing formulation innovation for smaller suppliers.
- Silicone Release Film Substitution:Fluoropolymer-coated alternatives are capturing share in high-value wound care applications where silicone residuals pose biocompatibility risks.
Strategic Opportunities
- India's CDSCO Pathway:The regulator's 2023 streamlined medical device rules create first-mover advantage for film suppliers establishing local cleanroom extrusion before domestic packaging demand matures.
- Bioresorbable Film Laminates:Convergence of polylactic acid substrates with controlled-release drug coatings opens surgical mesh and orthopedic fixation applications.
- Direct Hospital Contracting:IDN procurement consolidation in the US is bypassing traditional distributor markups for high-volume sterile barrier film agreements.
Industry Challenges
- Cleanroom Operator Scarcity:Qualified technicians for medical-grade extrusion lines command 40% wage premiums over standard film production, constraining capacity expansion.
- Lot Traceability System Overhaul:EU MDR's unique device identifier requirements force film suppliers to integrate serialization down to the roll level, demanding ERP investments that mid-tier converters struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Device Films Market |
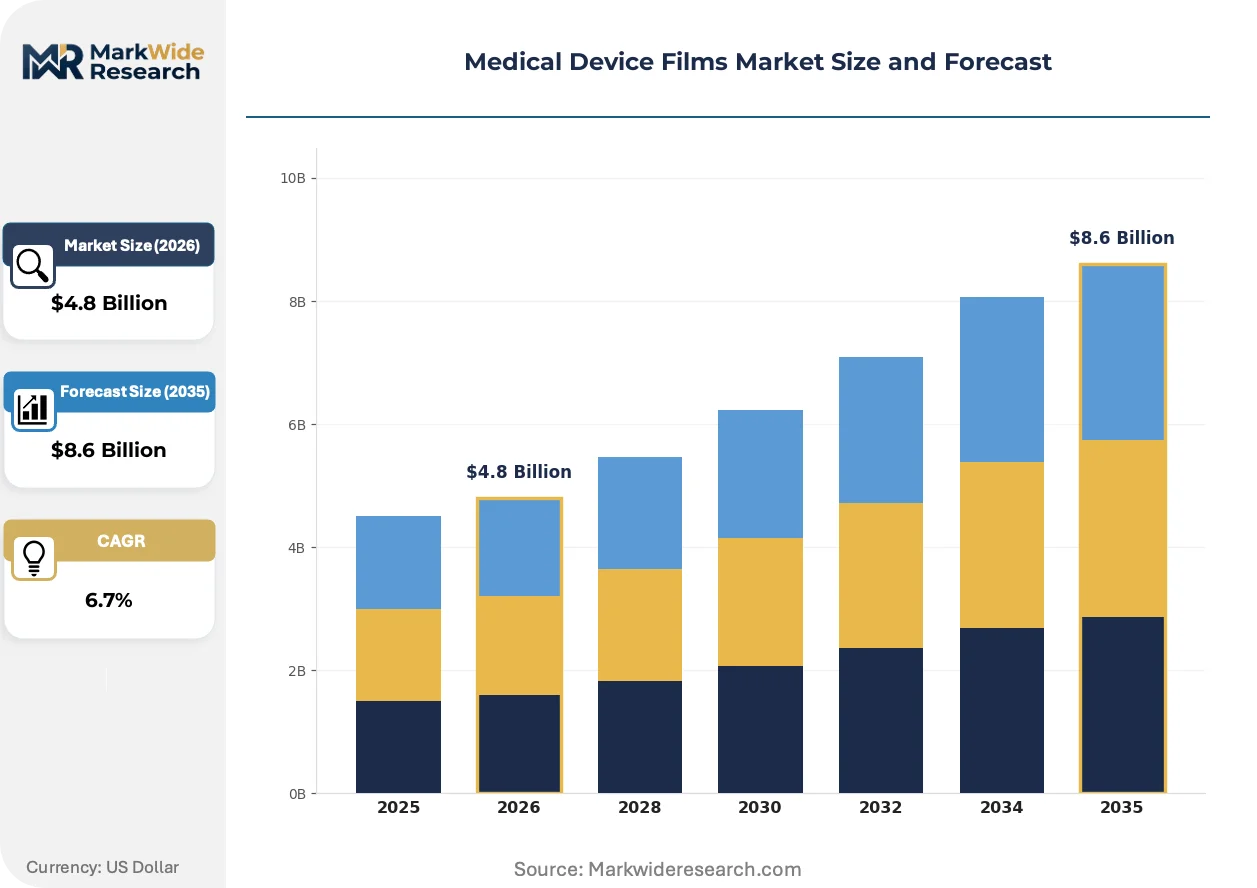
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Nylon End User: Hospitals, Clinics, Research Labs, Homecare Application: Packaging, Device Components, Wound Care, Monitoring Material: Biodegradable, Non-Biodegradable, Polymeric, Composite |
| Companies Covered | Amcor plc, Berry Global Inc., Sealed Air Corporation, Klöckner Pentaplast, Wipak Group, Constantia Flexibles Group, Mondi plc, Weigao Group, DuPont de Nemours Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Device Films Market Shifts & Advancements
Active material science and regulatory digitization are compressing development cycles for medical-grade films, while procurement centralization among hospital networks is rewiring how specifications travel from converter to end-use.
Multilayer coextrusion is converging with real-time rheology monitoring to enable dynamic thickness control during sterile barrier film production. Implantable device packagers in Switzerland and Germany are adopting these systems to reduce seal variability. The technology is converging with automated vision inspection to eliminate manual sampling bottlenecks in cleanroom environments.
REACH restrictions on phthalate plasticizers are forcing reformulation of flexible PVC films used in blood bag and tubing applications. ECHA's 2023 sunset dates for DEHP and DBP are accelerating migration to citrate-based alternatives or polyolefin displacement. Blood contact device manufacturers in the Netherlands and Denmark are qualifying non-PVC multilayer structures ahead of enforcement.
Hospital procurement teams are consolidating film specifications across multiple device categories to reduce supplier audit burden. US integrated delivery networks are compressing approved vendor lists from 15-20 film converters to 3-5 strategic partners. This concentration is most visible in the Midwest and Southeast regions where IDN merger activity has accelerated since 2022.
Medical Device Films Market Segmentation
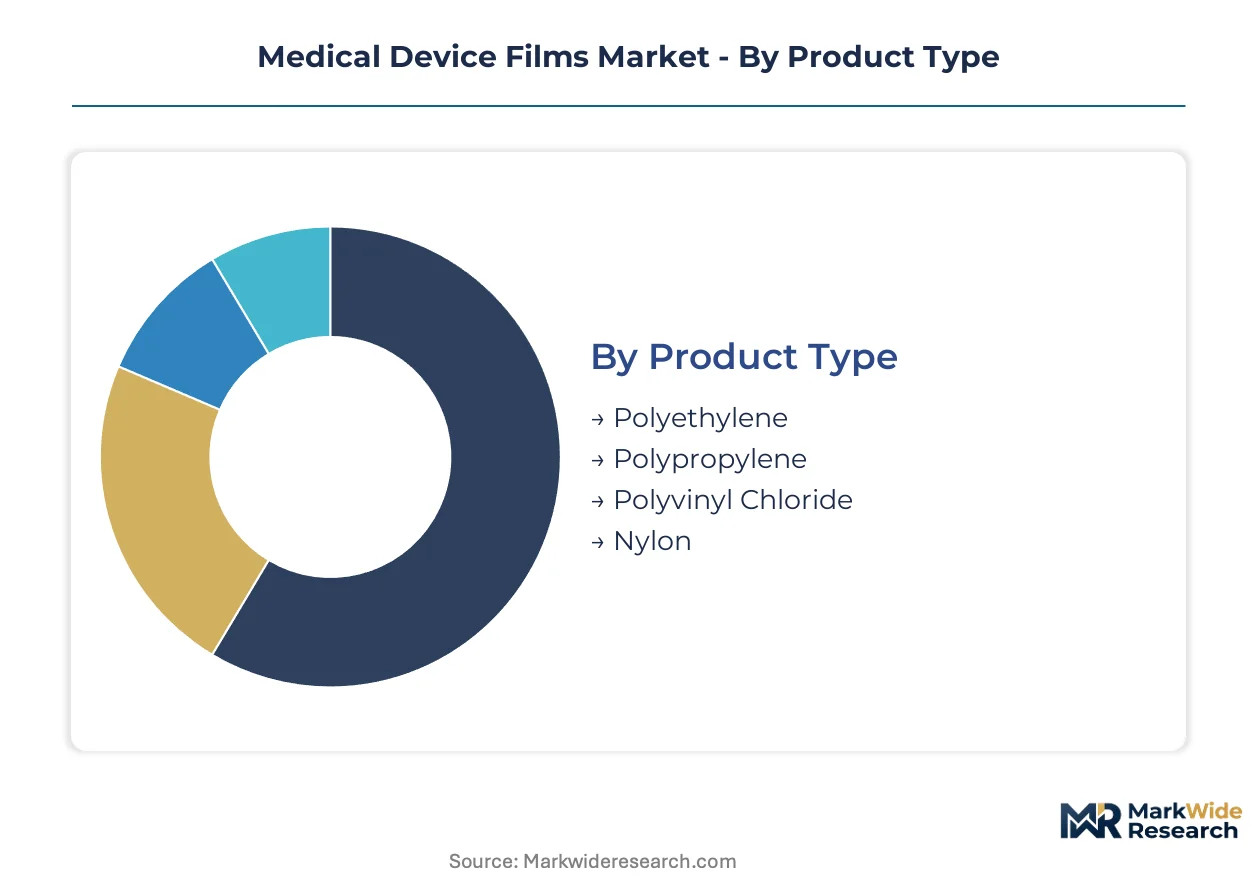
Medical device film specifications diverge sharply across sterilization methods, biocompatibility requirements, and end-use environments. Segmentation reveals how resin chemistry and application function dictate margin structures and regulatory pathways for converters.
Product Type:
Buyers in this category distinguish themselves by thermal sterilization tolerance versus cost sensitivity in single-use applications.
- Polyethylene:Low-density and linear low-density formulations dominate flexible packaging for disposable surgical instruments due to superior heat-sealability and moisture barrier performance. Hospitals in Germany's Tuttlingen corridor specify medical-grade PE for sterile barrier pouches where cost containment pressures intensify.
- Polypropylene:Cast and oriented PP films withstand autoclave cycles at 134°C, serving reusable surgical instrument sets where steam sterilization is mandatory. Swiss and German device manufacturers specify biaxially oriented PP for implantable device packaging requiring extended shelf stability.
- Polyvinyl Chloride:Plasticized PVC films retain flexibility for blood bag and tubing applications, though ECHA REACH restrictions on phthalate plasticizers force migration to citrate-based alternatives or polyolefin displacement.
- Nylon:Polyamide barrier layers deliver oxygen transmission rates below 0.5 cc/m²/day for oxygen-sensitive device components and diagnostic reagents requiring extended stability.
Polyethylene leads volumes today; polypropylene is gaining share fastest on autoclave-resistance specifications.
End User:
Procurement sophistication and validation burden separate customers across this dimension.
- Hospitals:Integrated delivery networks consolidate film specifications across multiple device categories, compressing approved vendor lists from 15-20 converters to 3-5 strategic partners. US Midwest and Southeast IDNs drive standardization through centralized procurement.
- Clinics:Outpatient surgical centers prioritize cost-efficient polyethylene sterile barriers for minor procedure kits, with limited technical staff for supplier qualification.
- Research Labs:Preclinical and analytical laboratories specify ultra-clean films with documented extractables profiles under ISO 10993-18 for biocompatibility testing substrates.
- Homecare:Patient-administered device packaging demands peelable sealant layers and printed instructions-for-use compatibility for aging populations managing chronic conditions.
Hospitals command the largest volume share; homecare applications show the steepest expansion trajectory as chronic disease management shifts to residential settings.
Application:
Functional requirements for barrier performance, breathability, or adhesion define material selection here.
- Packaging:Sterile barrier systems under ISO 11607 mandate multilayer coextrusion combining nylon oxygen blocking with peelable sealant layers for implantable devices. Swiss packagers adopt real-time rheology monitoring to reduce seal variability.
- Device Components:Membranes and films integrated into active devices—such as oxygen sensors or drug reservoir covers—require precise thickness control from 12-250 microns with validated lot traceability.
- Wound Care:Silicone-coated release films and breathable polyurethane membranes serve advanced wound dressing laminates where moisture vapor transmission rates determine clinical efficacy.
- Monitoring:Transparent, chemically resistant films protect continuous glucose monitor sensors and wearable diagnostic electrodes from moisture and mechanical damage.
Packaging consumes the greatest material tonnage; wound care applications are climbing the fastest on advanced dressing adoption.
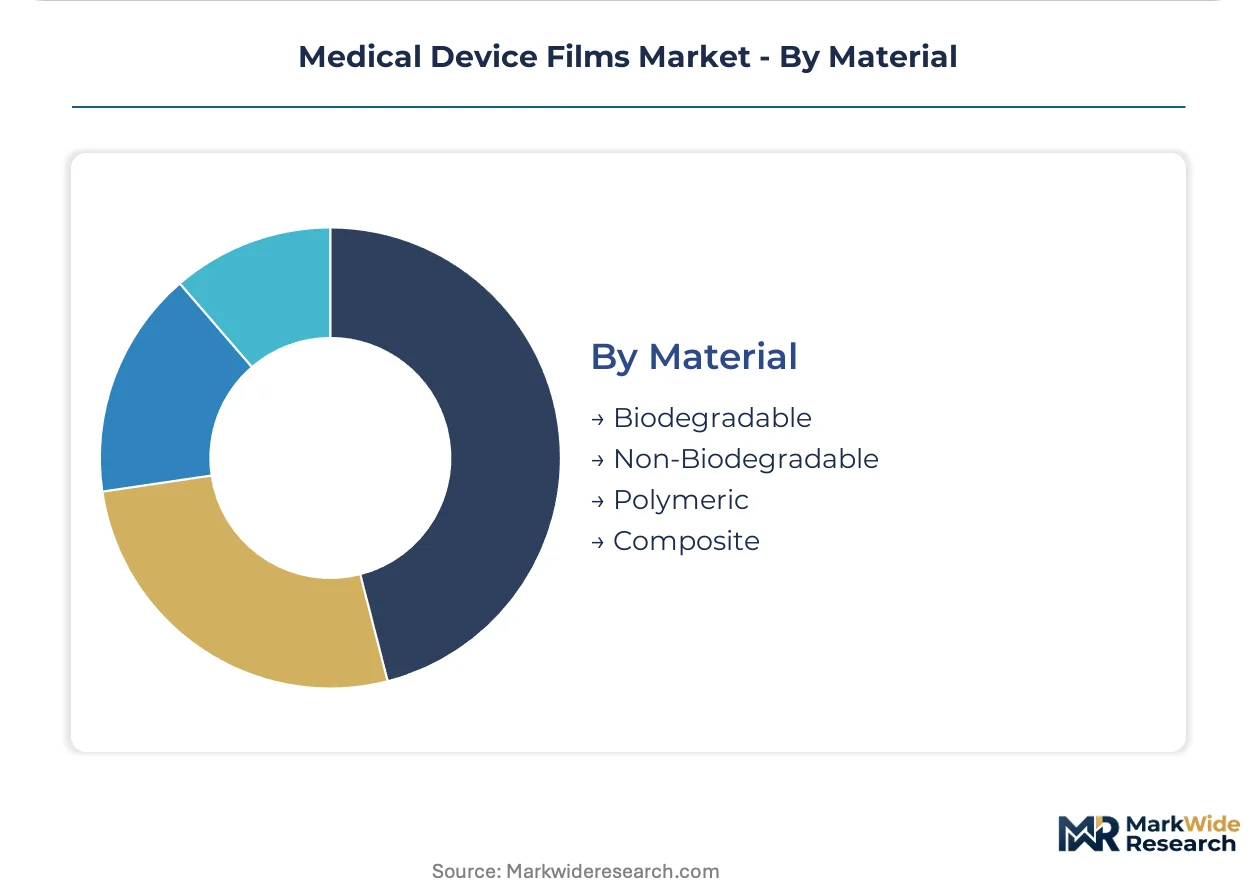
Material:
Sustainability positioning and end-of-life pathways increasingly differentiate sourcing decisions.
- Biodegradable:Polylactic acid and polyhydroxyalkanoate films target surgical mesh and orthopedic fixation where resorbable substrates eliminate secondary removal procedures. Netherlands and Denmark manufacturers qualify these ahead of ECHA enforcement timelines.
- Non-Biodegradable:Conventional polyethylene and polypropylene films retain dominance where long-term stability and established regulatory dossiers outweigh sustainability metrics.
- Polymeric:Single-resin and multilayer polyolefin structures offer the broadest sterilization compatibility and lowest extractables burden for blood-contacting applications.
- Composite:Nanolaminate barrier structures layer-by-layer assemble nylon, EVOH, and sealant polymers to achieve hermetic protection for implantable electronics and biologics.
Non-biodegradable materials anchor current volumes; biodegradable alternatives are expanding most quickly on resorbable device convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands specialized autoclave-resistant film demand while the United States drives high-barrier sterile packaging volumes through consolidated hospital procurement. Switzerland anchors precision coextrusion for implantable device applications. Japan maintains exacting quality standards for diagnostic film components. India's regulatory streamlining attracts cleanroom investment ahead of domestic demand maturation.
United States
Integrated delivery networks in the Midwest and Southeast compress approved vendor lists from 15-20 converters to 3-5 strategic partners, centralizing sterile barrier procurement. FDA enforces biocompatibility validation under 21 CFR Part 820, requiring documented lot traceability for films contacting blood or tissue. Berry Global anchors North American supply through resin-to-film operations with dedicated medical lines in the Southeast.
Germany
Hospitals in the Tuttlingen medical technology corridor specify high-temperature sterilizable films for reusable surgical instrument sets, pulling material innovation toward thermal stability. EU MDR full enforcement filters out uncertified suppliers and concentrates volume among validated producers with notified body certification. Bavaria hosts multilayer coextrusion specialists serving Swiss and German implantable device packagers.
Switzerland
Implantable device manufacturers adopt nanolaminate barrier structures combining nylon oxygen blocking with peelable sealant layers for extended shelf stability. Swissmedic maintains stringent quality agreements for films incorporated into active implantable medical devices. The Basel-Zurich corridor concentrates precision film laminators supplying European orthopedic and cardiovascular device producers.
Japan
PMDA quality standards drive diagnostic film component specifications with precise thickness control from 12-250 microns for sensor applications. METI industrial policy supports domestic medical material supply chain resilience through designated critical product categories. The Kanto region around Tokyo hosts converters serving continuous glucose monitor and wearable diagnostic electrode manufacturers.
India
CDSCO's 2023 streamlined medical device rules create first-mover advantage for film suppliers establishing local cleanroom extrusion before domestic packaging demand matures. Maharashtra and Gujarat states attract medical-grade resin compounding investments to reduce import dependency. Weigao Group exemplifies regional positioning through medical packaging operations serving South Asian hospital networks.
Medical Device Films Market Competitive Landscape
North American producers anchor one tier; European specialists hold premium-barrier positioning through MDR-certified cleanroom operations. The vendor base concentrates among multilayer coextrusion operators with validated sterile barrier dossiers and regional resin-to-film integrators with hurricane-resistant supply chains. Three archetypes dominate: diversified packaging conglomerates with medical divisions, pure-play medical film specialists, and resin producers backward-integrating into film conversion. Competitive moves center on MDR compliance certification acquisitions and Southeast Asian cleanroom capacity expansion.
Within the diversified packaging tier, Amcor plc and Berry Global Inc. represent integrated multilayer platform operators, while DuPont de Nemours Inc. exemplifies specialty materials positioning through coated film technologies. These three companies occupy positions spanning high-volume sterile barrier supply and differentiated release film applications, reflecting the market's bifurcation between scale-driven commodity production and performance-premium specialization.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Inc. |
| Sealed Air Corporation |
| Klöckner Pentaplast |
| Wipak Group |
| Constantia Flexibles Group |
| Mondi plc |
| Weigao Group |
| DuPont de Nemours Inc. |
| Others |
Supply & Pricing Matrix
Integrated delivery networks in the US Midwest and Southeast anchor contract-based pricing for sterile barrier films, compressing supplier lists from 15-20 converters to 3-5 strategic partners and concentrating volume leverage among validated producers.
Pricing Analysis
Capacity additions in Southeast Asia are reshaping price floors for standard-grade polyethylene films, though MDR-certified cleanroom production commands persistent premiums. Pricing stratifies across premium, standard, and economy tiers based on ISO 11607 certification status and lot traceability depth. Cost compression in economy-grade PE pouches intensifies as Gulf Coast resin availability fluctuates. Clinics and outpatient surgical centers exhibit highest price sensitivity, while implantable device packagers prioritize barrier performance over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, Switzerland, and the United States form a hub-and-spoke pattern serving hospital networks and device manufacturers. Medical-grade polyethylene and polypropylene feedstocks draw from Gulf Coast petrochemical complexes and Middle Eastern resin producers. Single-source vulnerability concentrates in autoclave-resistant polypropylene additives. Distribution runs through converter-direct contracts with integrated delivery networks, bypassing traditional distributor markups for high-volume sterile barrier agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as EU MDR enforcement filters volume toward notified body-certified producers and hospital procurement consolidates around validated supply chains.
For Market Incumbents: Deploy MDR certification acquisition as the primary defensive lever. Acquire mid-tier converters in Bavaria and the Basel-Zurich corridor to consolidate notified body-certified cleanroom capacity. Channel control through direct IDN contracting protects margin position against resin price volatility. For New Entrants and Emerging Players: The premium-economy price gap in autoclave-resistant films creates entry space for regional specialists. Target India's CDSCO pathway before domestic packaging demand matures. Pursue white-label supply agreements with European distributors seeking secondary sourcing options. For Investors and Strategic Acquirers: Diversified packaging conglomerates with medical divisions are the most active acquirer in this space. Five-to-ten year viability hinges on MDR dossier depth rather than scale alone. Watch for CDSCO enforcement tightening as the signal indicating Indian market maturation and valuation compression for early entrants.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Acquisition | Notified body approval unlocks EU hospital procurement access for implantable device packaging. |
| Cleanroom Capacity Expansion | India's Maharashtra and Gujarat states attract medical-grade extrusion investment ahead of demand maturation. |
| Backward Integration into Resin Compounding | Captive supply of medical-grade polypropylene reduces hurricane disruption exposure for Gulf Coast converters. |
| Direct Hospital System Partnership | IDN procurement consolidation rewards strategic suppliers with multi-year sterile barrier film agreements. |
| Bioresorbable Film Development | Polylactic acid substrate qualification opens surgical mesh applications in Netherlands and Denmark markets. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down resin-to-film supply tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital purchasing committees, GPO contracts managers, and cleanroom extrusion operators combined with secondary validation against FDA 510(k) filings, EU MDR notified body certificates, ISO 11607 test reports, and hospital procurement database extracts. Triangulation across these sources ensures segment-level accuracy.
Historical trendline analysis of autoclave-resistant film adoption and sterile barrier specification shifts informed projection parameters across the analysis window. Segmentation modeling spans material chemistry, sterilization method compatibility, end-use environment, and regional regulatory cluster. CAGRs derive from curve-fitting validated production volumes against hospital procurement consolidation patterns and MDR implementation timelines.
Caveats apply where ECHA REACH enforcement acceleration or Gulf Coast petrochemical disruption could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ambulatory Aids Market
Medical Devices
Uterine Fibroid Treatment Device Market
Medical Devices
Spain Ultrasound Devices Market
Medical Devices
Neuro Medical Devices Market
Medical Devices
Adult Water Flosser Market
Medical Devices
Pipette Controllers Market
Medical Devices
Pet Mobility Aids Market
Medical Devices
Global Osseointegration Implants Market
Medical Devices
Wireless Portable Medical Devices Market
Medical Devices
Global Medical Radiation Shielding Market
Medical Devices
Spinal Thoracolumbar Implants Market
Medical Devices
Nanotechnology in Medical Devices Market
Medical Devices
Australia Respiratory Devices Market
Medical Devices
Global Cochlear Implant Market
Medical Devices
Laparoscopic Devices Market
Medical Devices
Oxygen Delivery Units Market