
 Global Trauma Fixation Devices Market | 2026-2036
Global Trauma Fixation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Trauma Fixation Devices Market Foresight
The trauma fixation market is decoupling along material lines, with titanium alloy and carbon fiber reinforced platforms commanding premium positioning while stainless steel competes on cost in emerging markets. Smith & Nephew leverages its R&D intensity to anchor leadership in biodegradable material systems. Zimmer Biomet dominates large-scale manufacturing of intramedullary nails across North American trauma centers. Stryker controls distribution channels that sustain its footprint in spinal fixation applications.
Trauma fixation devices are orthopedic implants designed to stabilize bone fractures through mechanical fixation, typically manufactured from titanium alloys, stainless steel, or biodegradable polymers with specific yield strengths exceeding 800 MPa for load-bearing applications. Their primary purpose is to maintain anatomical alignment during osseous healing while permitting early mobilization. Intramedullary nails and bone plates represent the most mature product categories where margin pools have compressed, whereas carbon fiber reinforced and biodegradable material segments attract premium pricing due to radiolucency and elimination of secondary removal surgeries. The application landscape tilts heavily toward orthopedic trauma, though craniofacial surgery and maxillofacial procedures are gaining traction as minimally invasive techniques expand eligible patient populations.
FDA 510(k) clearance pathways and the EU MDR framework impose stringent biocompatibility and mechanical testing requirements that shape product development timelines and market access conditions for manufacturers. China's NMPA and Japan's PMDA maintain parallel but divergent standards for titanium alloy purity and fatigue testing that complicate global registration strategies. Stakeholders must monitor how REACH restrictions on nickel release and evolving FDA guidance on patient-specific 3D-printed implants will alter material selection and manufacturing location decisions.
Market Dynamics
China's NMPA localization mandates for titanium alloy production are compressing global supply chains while simultaneously redirecting procurement flows toward domestic Chinese manufacturers, forcing multinational orthopedic device firms to restructure their Asia-Pacific manufacturing footprints.
Growth Catalysts
- EU MDR framework harmonization:The Medical Device Regulation's consolidated conformity assessment pathways reduce redundant testing burdens for trauma fixation platforms seeking multi-country European market access.
- Carbon fiber reinforced implants:These radiolucent systems eliminate MRI artifact interference and secondary removal surgeries, commanding premium positioning in specialized orthopedic trauma centers across Germany and Switzerland.
- Japan's aging surgical population:METI-funded hospital infrastructure upgrades expand trauma center capacity in Osaka and Nagoya clusters, concentrating demand for intramedullary nail systems.
Market Restraints
- Titanium sponge supply concentration:Russian and Ukrainian feedstock disruptions have elevated raw material input costs for alloy production, compressing margins on stainless steel-competing product lines.
- REACH nickel release restrictions:ECHA's tightening thresholds on implantable device metal ion leaching force reformulation of legacy stainless steel plate compositions.
- Biodegradable polymer degradation variability:Inconsistent hydrolysis rates in polylactic acid screws create clinical uncertainty that slows adoption in load-bearing fracture applications.
Strategic Opportunities
- India's trauma center expansion:CDSCO fast-track approvals for imported orthopedic implants align with government hospital procurement upgrades in Maharashtra and Tamil Nadu.
- 3D-printed patient-specific plates:FDA's evolving guidance on additive manufacturing quality systems creates regulatory runway for topology-optimized fixation geometries matched to individual fracture morphologies.
- Ambulatory surgical center channel penetration:Same-day discharge protocols for stable fracture repairs open procurement relationships outside traditional hospital supply chains.
Industry Challenges
- Biocompatibility testing capacity bottlenecks:ISO 10993 cytotoxicity and sensitization study backlogs at contract laboratories extend product launch timelines by 8-14 months.
- Legacy ERP integration with UDI compliance:Hospital supply chain systems struggle to ingest FDA-mandated unique device identifiers for implant tracking.
- Cross-jurisdiction fatigue testing standard divergence:Japan's PMDA maintains distinct cyclic loading protocols that require separate validation from FDA 510(k) submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Trauma Fixation Devices Market |
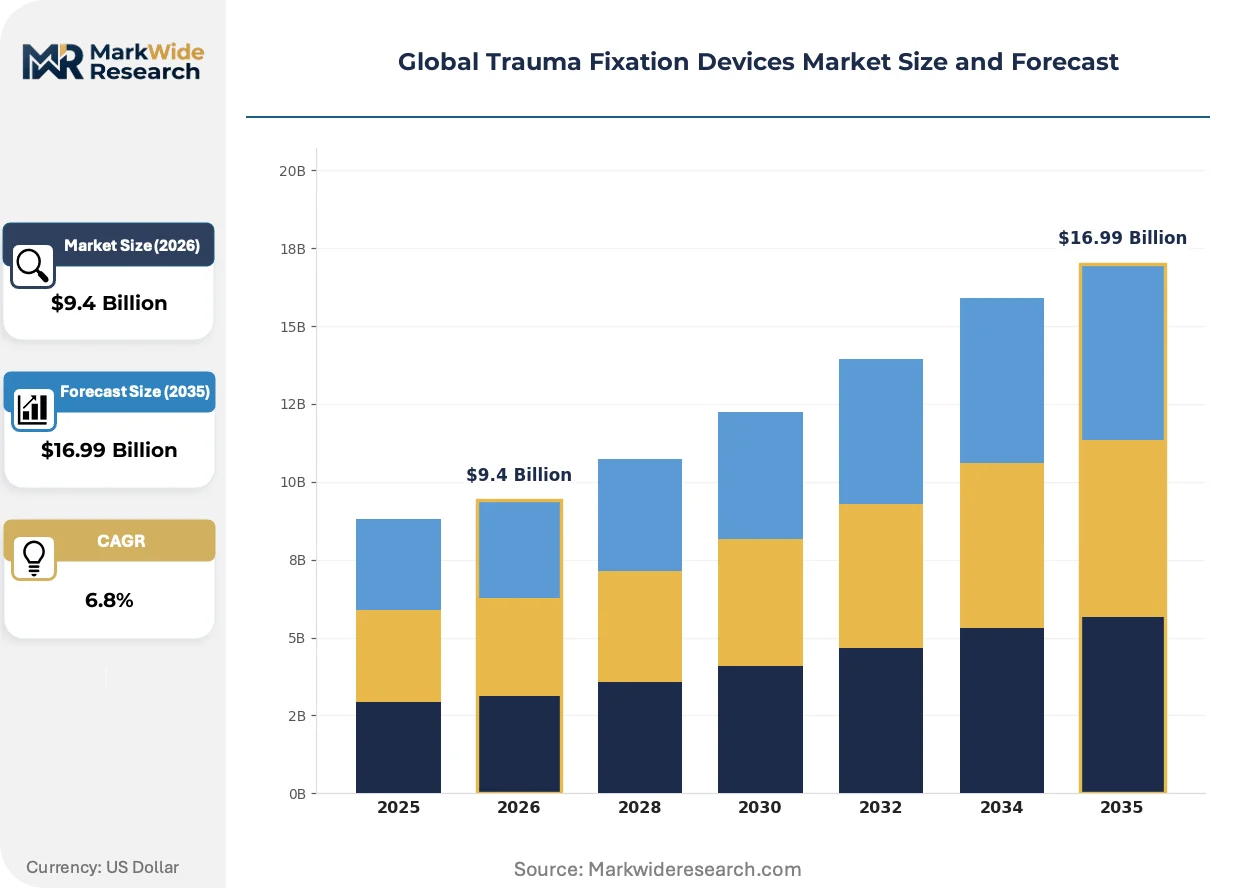
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.99 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: External Fixators, Intramedullary Nails, Bone Plates, Screws, Kirschner Wires Technology: Biodegradable Materials, Titanium Alloy, Stainless Steel, Carbon Fiber Reinforced, Polymers Application: Orthopedic Trauma, Craniofacial Surgery, Spinal Fixation, Veterinary Surgery, Maxillofacial Procedures End User: Orthopedic Clinics, Trauma Centers, Ambulatory Surgical Centers, Rehabilitation Facilities, Specialized Hospitals |
| Companies Covered | Smith & Nephew, Arthrex, Johnson & Johnson, Medtronic, Orthofix, Stryker, B Braun, CONMED, Zimmer Biomet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Trauma Fixation Devices Market Shifts & Advancements
Material science convergence with digital surgical planning is dismantling the traditional titanium-stainless steel duopoly in trauma fixation, while regulatory frameworks race to catch up with additive manufacturing and biodegradable platform validation.
Carbon fiber reinforced polyetheretherketone (CFR-PEEK) composite plates is rewriting competitive positioning in high-performance trauma fixation. Academic medical centers in Switzerland and specialized sports medicine clinics in Germany are adopting these systems for extremity fractures at threefold the rate of general hospitals. The technology is compressing titanium alloy's historical monopoly in radiolucent applications while simultaneously eliminating secondary hardware removal revenue streams.
REACH restrictions on nickel release are forcing material substitutions across European trauma fixation portfolios. ECHA's 2023 amendment lowering implantable device metal ion thresholds has triggered stainless steel composition reformulations and accelerated titanium alloy migration in plate and screw systems. French and German orthopedic device distributors report inventory mix shifts toward nickel-free alternatives within six months of enforcement.
Surgeon preference for single-use sterile-packed instrument kits is consolidating purchasing decisions at the health system level rather than individual hospital departments. Integrated delivery networks in the United States and hospital groups in the United Kingdom are negotiating enterprise contracts that bundle implants with proprietary instrumentation. This concentration is most visible in North American Level I trauma centers where standardization committees now override individual surgeon brand preferences.
Global Trauma Fixation Devices Market Segmentation
Trauma fixation device procurement concentrates differently across product, material, and channel dimensions, with capital requirements and reimbursement pathways creating divergent margin structures. Manufacturers align R&D portfolios and manufacturing footprints to capture specific segment premiums rather than pursuing horizontal coverage.
Product Type:
Intramedullary nails and bone plates demand the heaviest upfront tooling investment for precision forging and surface finishing capabilities.
- Intramedullary Nails:These load-bearing implants require high-yield-strength titanium alloy forging with fatigue resistance exceeding 800 MPa for femoral and tibial applications. North American Level I trauma centers in Houston and Baltimore concentrate demand for reamed and unreamed nail systems driven by high-energy fracture volumes from motor vehicle trauma.
- Bone Plates:Locking compression plates and limited-contact dynamic compression systems stabilize periarticular fractures through fixed-angle screw interfaces. German university hospitals in Berlin and Munich drive adoption of anatomically contoured plates for complex distal radius and proximal humerus reconstructions.
- External Fixators:Modular pin-bar constructs enable temporary stabilization of open fractures and limb lengthening procedures.
- Screws:Cortical and cancellous bone screws provide fragment fixation across plate systems and standalone applications.
- Kirschner Wires:Smooth and threaded wire configurations stabilize small bone fragments in hand and foot surgeries.
Intramedullary nails absorb the bulk of installed capacity; external fixators are expanding most quickly in combat casualty and disaster response applications.
Technology:
Material selection stratifies by radiolucency requirements, nickel sensitivity concerns, and secondary surgery elimination priorities.
- Titanium Alloy:Ti-6Al-4V and Ti-6Al-7Nb formulations dominate load-bearing applications with specific strength-to-weight ratios and osseointegration properties. Japanese orthopedic centers in Osaka and Nagoya concentrate demand for high-purity titanium systems compliant with PMDA fatigue testing protocols.
- Biodegradable Materials:Polylactic acid and polyglycolic acid copolymer screws and pins eliminate hardware removal surgeries through controlled hydrolysis. Swiss sports medicine clinics in Zurich and Lausanne drive premium adoption for ankle and wrist fracture applications where implant retention risks long-term complications.
- Stainless Steel:316L and 22Cr-13Ni-5Mn compositions compete on cost in emerging market trauma centers.
- Carbon Fiber Reinforced:CFR-PEEK composite plates eliminate MRI artifact interference in post-operative monitoring.
- Polymers:High-performance thermoplastics serve temporary fixation and pediatric applications.
Titanium alloy commands the dominant installed base; biodegradable materials are climbing the fastest as REACH nickel restrictions and patient preference for single-procedure outcomes intensify.
Application:
Clinical workflow complexity and reimbursement density determine which applications justify specialized instrument sets and surgeon training investments.
- Orthopedic Trauma:Long bone, pelvic, and periarticular fracture fixation constitutes the core volume driver with established DRG reimbursement pathways. United Kingdom trauma networks in Birmingham and Manchester concentrate demand for integrated nailing and plating systems serving regional catchment populations exceeding two million.
- Maxillofacial Procedures:Mandibular and zygomatic fracture fixation requires mini-plate and micro-screw systems with precise contouring capabilities. South Korean academic medical centers in Seoul deploy patient-specific 3D-printed titanium plates for complex panfacial reconstructions.
- Craniofacial Surgery:Cranial vault and orbital reconstruction applications demand biocompatible materials with low thermal conductivity.
- Spinal Fixation:Traumatic vertebral fracture stabilization overlaps with degenerative spine product portfolios.
- Veterinary Surgery:Companion animal fracture management adapts human orthopedic designs for scaled anatomies.
Orthopedic trauma anchors the majority of manufacturing capacity; maxillofacial procedures are gaining share fastest through minimally invasive technique expansion.
End User:
Procurement authority concentration varies sharply between centralized health systems and fragmented private practice environments.
- Trauma Centers:American College of Surgeons-verified Level I and II facilities standardize implant selection through value analysis committees. California's Stanford and USC trauma centers negotiate enterprise contracts covering intramedullary nail and plate systems across multiple hospital sites.
- Ambulatory Surgical Centers:Same-day discharge protocols for stable fracture repairs create new channel opportunities outside traditional hospital supply chains. Florida and Texas ASC networks in Tampa and Dallas procure bundled implant-instrument kits for distal radius and ankle fracture procedures.
- Orthopedic Clinics:Private practice settings concentrate minor fracture fixation and post-operative monitoring.
- Specialized Hospitals:Pediatric and geriatric focused institutions demand age-adapted fixation geometries.
- Rehabilitation Facilities:Post-acute settings manage hardware retention monitoring and mobilization protocols.
Trauma centers concentrate the highest procurement volumes; ambulatory surgical centers are expanding fastest as site-of-service shifts accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston and Baltimore anchor North American demand concentration for intramedullary nail systems serving Level I trauma centers with high motor vehicle trauma volumes. Procurement standardization through value analysis committees now overrides individual surgeon preferences across California's Stanford and USC networks.
United States
Level I trauma centers in Houston and Baltimore concentrate demand for reamed and unreamed nail systems driven by high-energy fracture volumes. FDA 510(k) clearance pathways impose stringent biocompatibility testing that shapes product development timelines. California's Stanford and USC trauma centers negotiate enterprise contracts covering intramedullary nail and plate systems across multiple hospital sites.
Germany
University hospitals in Berlin and Munich drive adoption of anatomically contoured plates for complex distal radius and proximal humerus reconstructions. EU MDR framework harmonization reduces redundant testing burdens for multi-country European market access. Specialized orthopedic trauma centers across Germany and Switzerland command premium positioning for carbon fiber reinforced implants.
China
NMPA localization mandates for titanium alloy production compress global supply chains while redirecting procurement toward domestic manufacturers. The country's national medical products regulator maintains parallel but divergent standards for titanium alloy purity that complicate global registration strategies. Multinational orthopedic device firms restructure Asia-Pacific manufacturing footprints to accommodate these localization requirements.
Japan
METI-funded hospital infrastructure upgrades expand trauma center capacity in Osaka and Nagoya clusters, concentrating demand for intramedullary nail systems. PMDA maintains distinct cyclic loading protocols that require separate validation from FDA 510(k) submissions. Japanese orthopedic centers concentrate demand for high-purity titanium systems compliant with national fatigue testing protocols.
Switzerland
Academic medical centers and sports medicine clinics in Zurich and Lausanne drive premium adoption of biodegradable screws for ankle and wrist fracture applications. Swissmedic maintains rigorous standards for implantable device metal ion leaching that align with REACH restrictions. Carbon fiber reinforced PEEK composite plates from Swiss centers are expanding at threefold the rate of general hospitals.
Global Trauma Fixation Devices Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material technology and regulatory sophistication dimensions. The vendor base stratifies into three tiers: integrated multinationals with full regulatory portfolios, regional specialists with concentrated geographic footprints, and emerging domestic champions in China and India. Two dominant competitive moves are reshaping positioning: backward integration into titanium sponge supply to offset raw material cost volatility, and strategic partnerships with 3D-printing service bureaus for patient-specific implant geometries.
Within the integrated multinational tier, Smith & Nephew and Zimmer Biomet occupy positions defined by regulatory breadth and manufacturing scale. Stryker anchors the distribution-intensive archetype with channel control sustaining footprint in specialized applications. These three entities exemplify the divergence between R&D-intensive biodegradable material leadership and large-scale intramedullary nail manufacturing dominance.
| Leading Market Players |
|---|
| Smith & Nephew |
| Arthrex |
| Johnson & Johnson |
| Medtronic |
| Orthofix |
| Stryker |
| B Braun |
| CONMED |
| Zimmer Biomet |
| Others |
Supply & Pricing Matrix
Captive titanium sponge production anchors supply position and pricing power for integrated manufacturers facing volatile Russian and Ukrainian feedstock disruptions. This backward integration shields premium-tier producers from alloy cost spikes while forcing stainless steel competitors to absorb margin compression from REACH nickel compliance mandates.
Pricing Analysis
Value-based pricing anchored to elimination of secondary removal surgeries commands premium positioning for biodegradable polylactic acid screws and carbon fiber reinforced PEEK plates. Three-tier pricing structure across premium, standard, and economy levels stratifies by radiolucency certification and fatigue testing protocol compliance. Pricing pressure stems from titanium alloy input cost volatility compressing margins on stainless steel-competing product lines. Emerging market trauma centers exhibit highest price sensitivity, while Swiss and German specialized orthopedic centers accept premium positioning for nickel-free alternatives.
Supply Chain Analysis
Regional distribution centers in Switzerland and Germany operate hub-and-spoke patterns serving specialized orthopedic trauma centers with sterile-packed instrument kits. Manufacturing concentrates in China, the United States, and Germany, with NMPA localization mandates redirecting titanium alloy forging capacity toward domestic Chinese producers. Raw material dependencies span titanium sponge from Russia and Ukraine, polylactic acid resin from European polymer specialists, and carbon fiber precursors from Japanese suppliers. Single-source vulnerability in titanium sponge feedstock poses structural risk. Distribution runs through integrated delivery networks negotiating enterprise contracts across multi-site hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a material-transition phase as carbon fiber reinforced composites and biodegradable polymers displace titanium alloy dominance in radiolucent applications.
For Market Incumbents: Deepen backward integration into titanium sponge supply to offset feedstock volatility from Russian and Ukrainian disruptions. Secure captive alloy production capacity before NMPA localization mandates fully redirect Chinese procurement toward domestic manufacturers. Lock hospital system relationships through bundled implant-instrument enterprise contracts that standardize selection committees. For New Entrants and Emerging Players: 3D-printed patient-specific plate geometries offer technology-first wedge into maxillofacial reconstruction applications where FDA additive manufacturing guidance creates regulatory runway. Target South Korean academic medical centers deploying patient-specific titanium plates for complex panfacial reconstructions. Pursue CDSCO fast-track pathways for Maharashtra and Tamil Nadu government hospital procurement upgrades. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap specialists with differentiated biodegradable material platforms or captive carbon fiber composite manufacturing. Long-term viability favors R&D-intensive players with regulatory breadth across FDA 510(k), EU MDR, and PMDA submissions. Watch biodegradable polymer hydrolysis rate consistency as inflection indicator for clinical adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Sponge | Captive supply of Russian and Ukrainian feedstock alternatives insulates margin structures from alloy cost volatility. |
| CE Marking Pathway under EU MDR | Harmonized conformity assessment reduces redundant testing burdens for multi-country European trauma fixation access. |
| Hospital System Partnership | Enterprise contracts with California's Stanford and USC networks standardize procurement across Level I trauma centers. |
| Software Companion Development | Digital surgical planning integration differentiates carbon fiber reinforced platforms in German university hospitals. |
| Reimbursement Strategy | DRG pathway alignment for same-day discharge protocols opens ambulatory surgical center channel penetration in Florida and Texas. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs combining primary interviews with orthopedic trauma surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. FDA 510(k) clearance databases, EU MDR notified body submissions, NMPA registration records, and hospital procurement databases supplied validation. Bottom-up product-level modeling and top-down macroeconomic triangulation cross-checked volume and value outputs.
Granularity-level modeling captured product type, material technology, application, and end user dimensions at the country level across the analysis window. CAGRs derived from regression analysis of surgical volume trajectories, material substitution rates, and reimbursement pathway evolution. Forecast inputs incorporated trauma center capacity expansion in Osaka and Nagoya, REACH nickel restriction enforcement timelines, and biodegradable polymer hydrolysis rate clinical data maturation.
Forecast precision tightens around the base case; tail outcomes carry wider variance under titanium sponge supply disruption scenarios or accelerated EU MDR transition deadlines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Prosthetic Liners Market
Medical Devices
Global Medical Laser Systems Market
Medical Devices
Medical Device Complaint Management Market
Medical Devices
Bone Densitometer Devices Market
Medical Devices
Home Dialysis Systems Market
Medical Devices
Intraosseous Infusion Device Market
Medical Devices
Portable Ultrasonic Skin Scrubber Market
Medical Devices
Rapid Infuser Market
Medical Devices
Echogenic Catheters Market
Medical Devices
South Korea ECG Market
Medical Devices
Auto Keratometer Market
Medical Devices
South Africa Aesthetic Devices Market
Medical Devices
Organ-On-A-Chip Systems Market
Medical Devices
Global Tumor Tracking Systems Market
Medical Devices
Middle East and Africa Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
North America Organ-On-Chip Market