
 North America Refractive Surgery Devices Market | 2026-2036
North America Refractive Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Refractive Surgery Devices Market Analytics
US ophthalmic device manufacturing is restructuring around precision laser platforms and diagnostic imaging integration. Bausch & Lomb leverages its integrated contact lens and surgical portfolio to sustain recurring revenue streams across the vision care continuum. Johnson & Johnson Vision anchors its position through advanced femtosecond systems deployed in high-volume refractive centers. Alcon Inc competes with a broad cataract-refractive crossover portfolio that extends its reach into premium IOL and laser vision correction workflows.
North America refractive surgery devices comprise excimer lasers, femtosecond lasers, diagnostic aberrometers, and phakic intraocular lenses engineered to reshape corneal curvature or supplement natural lens optics, typically operating at ultraviolet wavelengths with pulse durations below 500 femtoseconds for tissue ablation precision. These systems correct myopia, hyperopia, and astigmatism by modifying optical power at the anterior segment without penetrating the globe. Femtosecond laser platforms now dominate capital expenditure allocations as flap creation and lenticule extraction displace mechanical microkeratome procedures. Ophthalmology clinics represent the fastest-growing end-user channel as physician-owned ambulatory sites expand suite-based surgery capacity and capture patients from hospital outpatient departments.
FDA 510(k) clearance requirements and ISO 13485 quality management standards govern device design validation and post-market surveillance across US and Canadian jurisdictions, elevating compliance costs for new entrants while protecting incumbent positions. The US Affordable Care Act's outpatient payment adjustments and provincial health technology assessments in Ontario and British Columbia shape reimbursement accessibility for elective refractive procedures. Stakeholders must monitor evolving FDA guidance on artificial intelligence-enabled surgical planning algorithms and state-level scope-of-practice expansions that could reshape provider competition and equipment deployment patterns.
Market Dynamics
Femtosecond laser platforms are consolidating procedure workflows across ambulatory surgical centers, compressing capital equipment replacement cycles while elevating diagnostic imaging integration requirements for ophthalmology group practices.
Growth Catalysts
- Outpatient payment adjustments:The US Affordable Care Act's reimbursement realignments incentivize same-day refractive procedures outside hospital settings, accelerating ASC suite expansion in California and Texas.
- Femtosecond precision thresholds:Pulse durations below 500 femtoseconds enable lenticule extraction techniques that displace mechanical microkeratome procedures, driving capital expenditure reallocations.
- Physician-owned clinic proliferation:Ophthalmology clinics capture patient volume from hospital outpatient departments through suite-based surgery capacity additions across the United States.
Market Restraints
- FDA 510(k) pathway friction:Premarket clearance requirements for laser platforms extend commercialization timelines, elevating compliance costs for device developers and protecting incumbent positions.
- ISO 13485 certification burden:Quality management standards governing design validation and post-market surveillance create structural barriers for new entrants across US and Canadian jurisdictions.
- Elective procedure reimbursement variability:Provincial health technology assessments in Ontario and British Columbia constrain accessibility for non-essential vision correction, limiting addressable demand.
Strategic Opportunities
- AI-enabled surgical planning:Evolving FDA guidance on algorithmic treatment optimization creates white space for diagnostic-therapeutic convergence in high-volume refractive centers.
- Texas metropolitan expansion:Underpenetrated Dallas and Houston suburbs present geographic white space for capital equipment deployment as ophthalmology group practices consolidate.
- Cross-border Canadian accessibility:Private-pay refractive corridors in Vancouver and Toronto offer channel innovation potential outside provincial single-payer constraints.
Industry Challenges
- Femtosecond laser technician scarcity:Specialized training requirements for sub-500 femtosecond platform operation outpace certified technician pipeline development in ASC settings.
- Diagnostic-therapeutic integration complexity:Aberrometer-to-laser data interoperability demands IT infrastructure capex that strains mid-sized clinic budgets.
- State scope-of-practice fragmentation:Inconsistent optometrist-ophthalmologist procedure authority across US jurisdictions complicates staffing models and equipment utilization planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Refractive Surgery Devices Market |
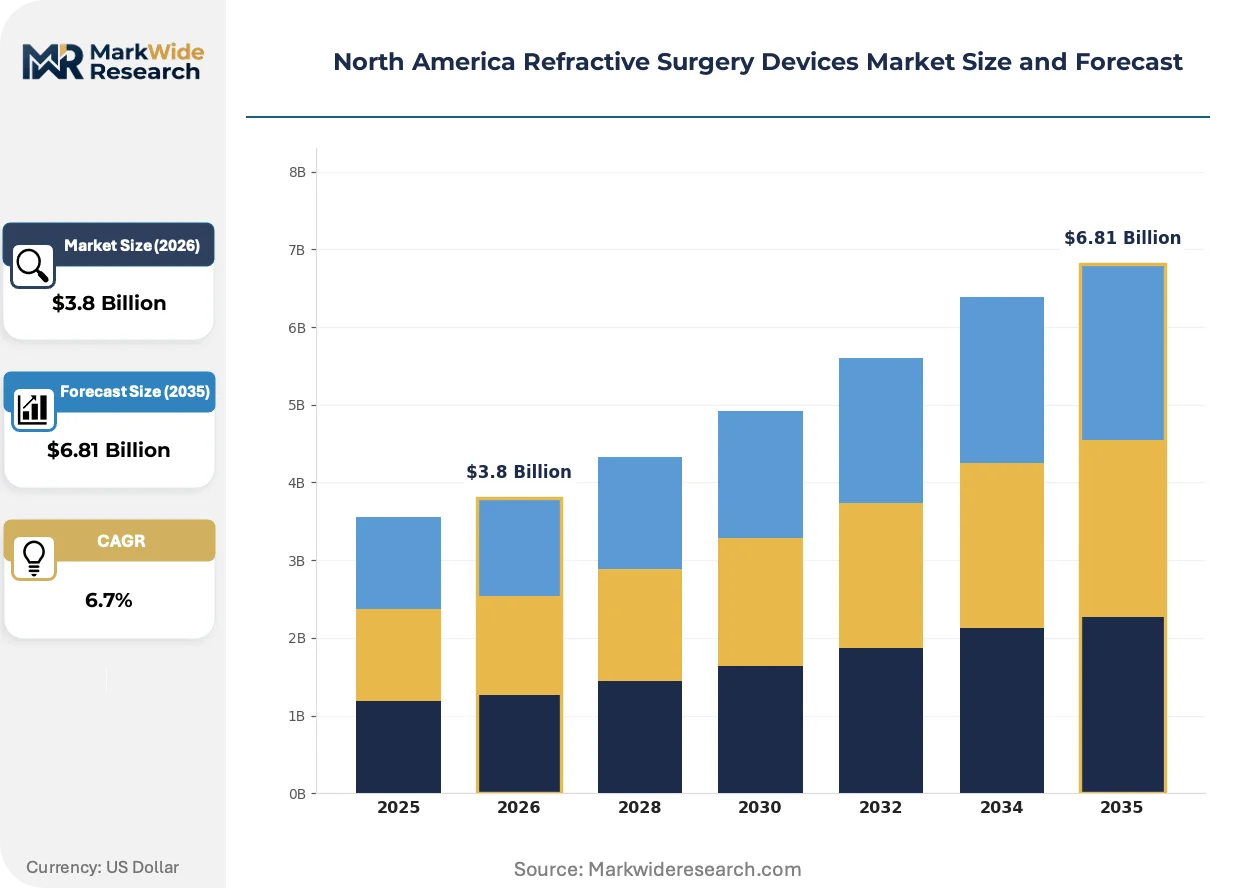
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: LASIK, PRK, SMILE, Phakic IOL Technology: Femtosecond Laser, Excimer Laser, Wavefront Technology, Manual Techniques End User: Hospitals, Ophthalmology Clinics, Ambulatory Surgical Centers, Eye Care Institutes Application: Vision Correction, Presbyopia Treatment, Astigmatism Correction, Hyperopia Management |
| Companies Covered | Bausch & Lomb, Topcon Corporation, Johnson & Johnson Vision, Ziemer Ophthalmic Systems AG, EssilorLuxottica, Alcon Inc, Nidek Co., Ltd., Lensar, Inc., Carl Zeiss Meditec AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Refractive Surgery Devices Market Evolving Landscape
Wavefront-guided diagnostic systems are converging with femtosecond delivery platforms, collapsing the traditional separation between preoperative measurement and surgical execution. This integration is compressing procedure times while elevating real-time feedback requirements.
Femtosecond laser architecture is modularizing around detachable diagnostic heads and upgradeable pulse control modules. High-volume refractive centers in California and Texas are adopting platform configurations that permit field-swappable ablation profiles without full system replacement. This modularity is enabling capital equipment lifecycle extension while preserving access to evolving lenticule extraction techniques.
FDA premarket guidance on artificial intelligence-enabled surgical planning is reshaping algorithm validation requirements for diagnostic aberrometers. Device developers must now demonstrate clinical equivalence across diverse corneal topography datasets before clearance. Ophthalmology clinics deploying these systems face documentation burdens that extend procurement cycles.
After-sales service unbundling is disrupting traditional capital equipment purchasing. Ambulatory surgical centers now negotiate diagnostic software subscriptions separately from laser platform leases, compressing vendor lock-in durations. This shift is most visible in Texas, where ophthalmology group practices leverage multi-clinic purchasing scale to demand à la carte maintenance terms.
North America Refractive Surgery Devices Market Segmentation
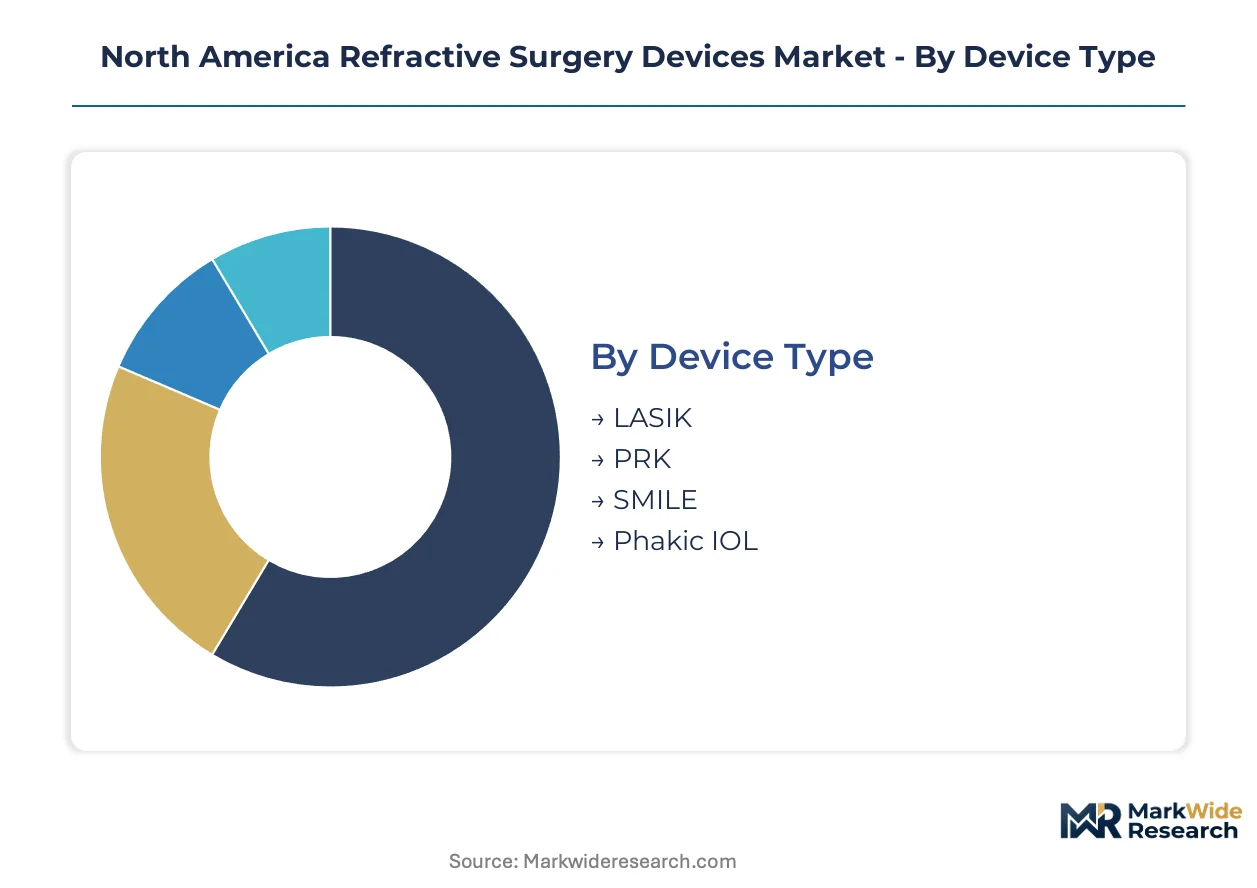
Refractive surgery device segmentation reveals distinct procurement patterns across standalone capital equipment versus integrated diagnostic-therapeutic platforms. Understanding these structural divides illuminates where capital expenditure concentrates and which configurations command premium positioning.
Device Type:
Integration depth varies sharply across procedure categories, with lenticule extraction platforms embedding diagnostic modules while surface ablation techniques retain standalone workflows.
- LASIK:Flap-based laser vision correction utilizing mechanical microkeratome or femtosecond laser for corneal flap creation before excimer ablation. Demand concentrates in California and Texas ophthalmology group practices where high patient throughput justifies dedicated suite configurations.
- SMILE:Small incision lenticule extraction performed through a single femtosecond laser platform without flap creation, reducing dry eye incidence and preserving corneal biomechanics. Adoption accelerates in ambulatory surgical centers seeking differentiated premium positioning outside hospital outpatient departments.
- PRK:Surface ablation technique removing epithelium before excimer laser treatment, suitable for thin corneas.
- Phakic IOL:Intraocular lens implantation preserving natural lens, addressing high myopia beyond laser correction limits.
LASIK leads volumes today; SMILE is gaining share fastest.
Technology:
Cost tier stratification separates capital-intensive laser platforms from lower-investment manual alternatives, with reimbursement accessibility determining adoption thresholds across end-user settings.
- Femtosecond Laser:Ultrafast pulse laser systems operating below 500 femtoseconds for precise tissue dissection without thermal damage, enabling flap creation, lenticule extraction, and arcuate incisions. Texas metropolitan markets show concentrated deployment as ophthalmology group practices consolidate purchasing power.
- Excimer Laser:Ultraviolet laser systems delivering 193nm wavelength for photoablative corneal reshaping, representing the foundational technology for myopia, hyperopia, and astigmatism correction. California high-volume refractive centers drive replacement cycles as wavelength stability and eye-tracking precision improve.
- Wavefront Technology:Aberrometry-based diagnostic systems measuring higher-order optical aberrations for customized treatment planning.
- Manual Techniques:Mechanical microkeratome and hand-held instrumentation for cost-constrained settings or specific anatomical indications.
Femtosecond platforms command the highest capital allocation; excimer systems retain the broadest installed base.
End User:
Customer type segmentation tracks the migration of refractive procedures from hospital settings toward physician-controlled environments, with facility ownership structure determining equipment financing models.
- Ambulatory Surgical Centers:Standalone same-day surgery facilities capturing elective refractive volume from hospital outpatient departments through specialized ophthalmology suites and streamlined patient throughput. California and Texas ASC networks expand fastest under US Affordable Care Act payment realignments.
- Ophthalmology Clinics:Physician-owned or group practice settings integrating diagnostic imaging with surgical capacity in suite-based configurations. Dallas and Houston suburbs present underpenetrated expansion corridors for capital equipment deployment.
- Hospitals:Academic medical centers and community hospital outpatient departments with embedded ophthalmology divisions.
- Eye Care Institutes:Research-affiliated or specialty-focused institutions combining clinical practice with training and technology evaluation.
Ophthalmology clinics lead procedure volumes today; ambulatory surgical centers are expanding most quickly.
Application:
Maturity differentiation separates established myopia correction from emerging presbyopia interventions, with patient age demographics and lens status determining addressable populations.
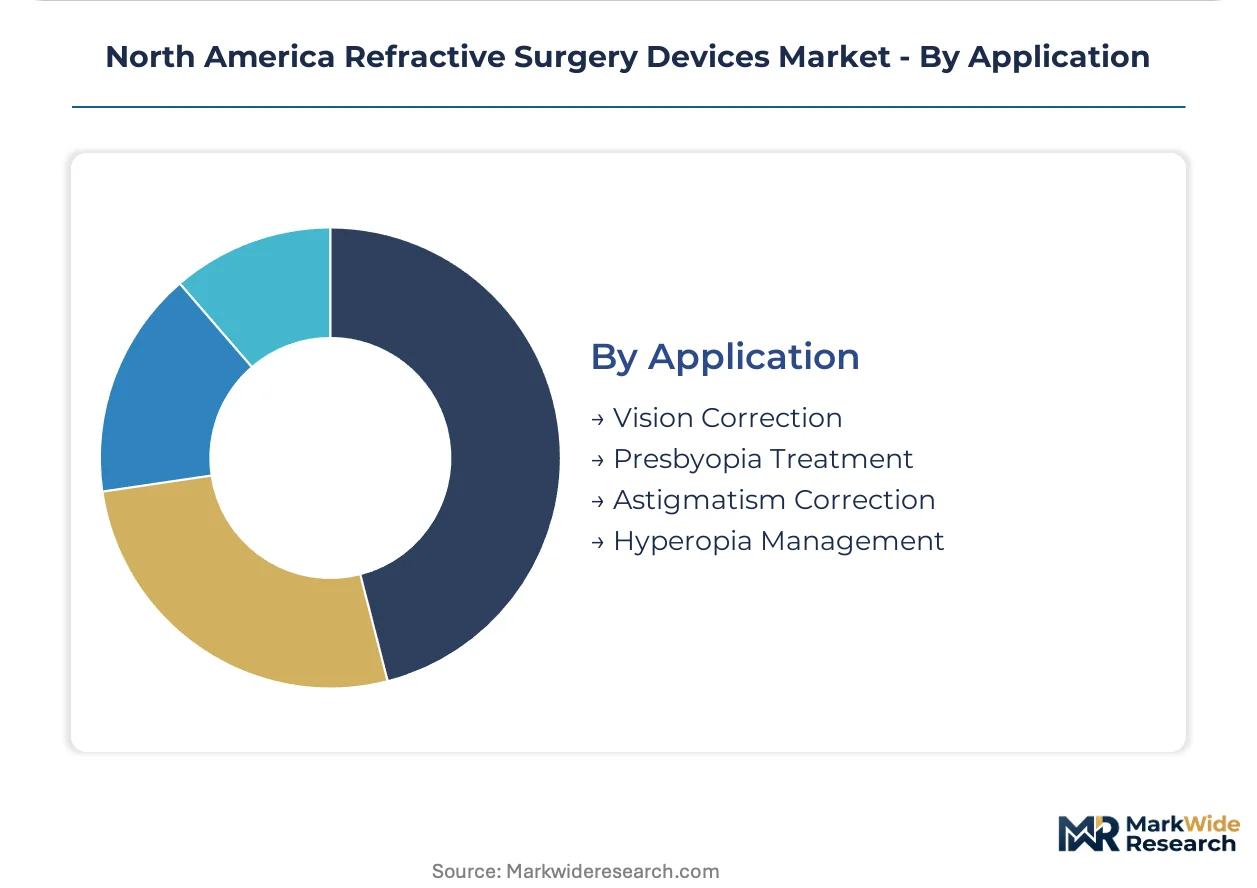
- Vision Correction:Comprehensive myopia treatment across laser and lens-based platforms, representing the foundational revenue stream for refractive surgery device manufacturers. Texas and California concentration reflects large working-age populations with high spectacle contact lens wear rates.
- Presbyopia Treatment:Corneal inlays, multifocal ablations, and lens-based interventions addressing age-related near vision loss in patients over 40. Vancouver and Toronto private-pay corridors offer channel innovation potential outside Canadian provincial single-payer constraints.
- Astigmatism Correction:Toric ablation profiles and arcuate incisions addressing corneal curvature irregularities.
- Hyperopia Management:Farsightedness correction through peripheral ablation or lens power supplementation.
Vision correction leads volumes today; presbyopia treatment is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance timelines and ISO 13485 certification costs create regulatory arbitrage that concentrates device development in established jurisdictions while pushing assembly and service operations toward lower-cost compliance environments.
United States
California and Texas ophthalmology group practices drive capital equipment purchasing through high-volume refractive centers in Los Angeles, San Francisco, Dallas, and Houston. FDA premarket approval pathways for femtosecond laser platforms shape commercialization timelines, with 510(k) submissions requiring extensive clinical equivalence documentation. The US Affordable Care Act's outpatient payment adjustments accelerate ambulatory surgical center expansion in metropolitan corridors.
Canada
Provincial health technology assessments in Ontario and British Columbia constrain reimbursement accessibility for elective refractive procedures, creating demand concentration in private-pay corridors. Health Canada regulates device licensing through the Medical Devices Bureau, with ISO 13485 quality management standards governing post-market surveillance. Vancouver and Toronto metropolitan areas present channel innovation potential outside single-payer constraints.
Mexico
Medical device manufacturing clusters in Baja California and Chihuahua serve North American supply chains through maquiladora operations that leverage proximity to US distribution networks. COFEPRIS regulatory oversight governs device registration, though many manufacturers pursue US FDA clearance as the primary market access pathway. Tijuana and Ciudad Juárez host assembly operations for precision laser components.
North America Refractive Surgery Devices Market Competitive Landscape
US producers anchor the premium-tier equipment segment; Swiss and German specialists hold precision-engineering positions in diagnostic and laser platforms. The vendor base stratifies across integrated ophthalmic conglomerates, standalone laser system developers, and diagnostic imaging specialists. Three archetypes dominate: diversified vision care conglomerates with surgical-refractive crossover portfolios, pure-play femtosecond laser developers, and precision optics specialists with aberrometer-to-laser integration capabilities. Capacity consolidation and diagnostic-therapeutic platform bundling represent the dominant competitive moves.
Among diversified vision care conglomerates, Bausch & Lomb, Johnson & Johnson Vision, and Alcon Inc exemplify the integrated portfolio archetype that spans contact lenses through surgical equipment. These entities occupy positions that leverage recurring revenue streams across the vision care continuum, with each representing a distinct geographic origin—Bausch & Lomb with North American roots, Johnson & Johnson Vision as a US-based subsidiary of a global healthcare conglomerate, and Alcon Inc as a Swiss-domiciled surgical specialist. Their market presence anchors competitive dynamics around bundled capital equipment and consumable offerings rather than standalone device sales.
| Leading Market Players |
|---|
| Bausch & Lomb |
| Topcon Corporation |
| Johnson & Johnson Vision |
| Ziemer Ophthalmic Systems AG |
| EssilorLuxottica |
| Alcon Inc |
| Nidek Co., Ltd. |
| Lensar, Inc. |
| Carl Zeiss Meditec AG |
| Others |
Value Network & Pricing Analysis
Femtosecond laser technician scarcity in California and Texas ophthalmology corridors widens pricing spreads between premium-tier integrated platforms and standard diagnostic-therapeutic bundles, as ASCs absorb elevated labor premiums or accept reduced service coverage.
Pricing Analysis
Distributor margin compression in the 15-25 percent range separates OEM-direct procurement by high-volume refractice centers from clinic-tier purchases routed through regional medical device distributors. Pricing stratifies across premium, standard, and economy tiers based on ISO 13485 certification level and after-sales service bundling intensity. Cost compression in the standard tier is intensifying because ophthalmology group practices demand unbundled software subscriptions. Price sensitivity peaks among mid-sized ophthalmology clinics in Dallas and Houston suburbs, while California ASC networks show lowest sensitivity due to patient volume scale.
Supply Chain Analysis
ISO 13485 certification gating concentrates precision laser component manufacturing in Germany, Switzerland, and the United States, with assembly operations drawing from Taiwanese optical subcomponent suppliers and Mexican maquiladora precision machining. Raw material dependencies center on rare-earth-doped laser crystals, ultraviolet-grade fused silica, and precision motion control systems. Single-source vulnerability in femtosecond oscillator chip supply from German specialty foundries elevates disruption risk. Distribution runs through authorized dealer networks serving ASC clusters in metropolitan corridors, with direct OEM relationships dominating capital equipment procurement above two-million-dollar annual device spend thresholds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America refractive surgery devices market compounds regulatory complexity into durable competitive moats, with FDA 510(k) pathway friction for AI-enabled surgical planning algorithms accelerating incumbent consolidation as clearance timelines extend.
For Market Incumbents: To counter diagnostic-therapeutic platform unbundling by Texas ophthalmology group practices, deepen backward integration into precision laser crystal supply through captive German foundry partnerships, and deploy field-swappable pulse control modules that extend capital equipment lifecycle without full system replacement. For New Entrants and Emerging Players: Direct-to-ASC digital sales channels bypass incumbent distributor lock-in, enabling white-space penetration of Vancouver and Toronto private-pay corridors outside Canadian provincial single-payer constraints, with subscription-based diagnostic software as the primary go-to-market wedge. For Investors and Strategic Acquirers: Diversified vision care conglomerates represent the most active acquirer category in this space, targeting pure-play femtosecond laser developers with FDA-cleared platforms but constrained commercial infrastructure. Five-to-ten year viability hinges on AI-enabled surgical planning algorithm validation pipelines. The signal to watch is Health Canada expedited review pathway activation for diagnostic-therapeutic convergence devices.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Surgical Planning FDA Submission | Algorithmic treatment optimization accelerates diagnostic-therapeutic convergence in high-volume California refractive centers. |
| CE Marking Pathway for Lenticule Extraction Platforms | European regulatory clearance enables Canadian market access through Health Canada recognition agreements. |
| Hospital System Partnership for ASC Network Expansion | Affiliated ambulatory surgical center development captures patient volume from hospital outpatient departments under ACA payment realignments. |
| Software Companion Development for Aberrometer Integration | Real-time diagnostic feedback loops compress procedure times while elevating platform switching costs. |
| Reimbursement Strategy for Presbyopia Interventions | Private-pay corridor positioning in Vancouver and Toronto metropolitan areas bypasses provincial health technology assessment constraints. |
Research Methodology
Bottom-up ambulatory surgical center procedure volume modeling reconciled against top-down femtosecond laser platform shipment tracking forms the analytical core of this study. Primary interviews with refractive surgeons, ASC operations directors, biomedical equipment procurement managers, and ophthalmology group practice administrators combined with secondary validation against FDA 510(k) clearance databases, ISO 13485 certification registries, hospital procurement databases, and GPO contract disclosure filings. Triangulation across these sources ensures demand-side and supply-side estimates converge.
Historical trendline analysis of capital equipment replacement cycles and diagnostic imaging integration rates informed the projection framework. Segmentation dimensions modeled include device type integration depth, technology cost tier, end-user facility ownership structure, and application maturity across myopia correction versus presbyopia intervention. CAGRs were derived from fitted growth curves calibrated to procedure volume elasticity and capital expenditure allocation patterns. Forecast inputs incorporate femtosecond laser technician pipeline development rates and state-level scope-of-practice expansion trajectories.
The model assumes a particular technology adoption path; alternative pathways for AI-enabled surgical planning algorithm clearance timelines would alter the outlook. Forecasts reflect documented assumptions regarding outpatient payment adjustment stability and provincial health technology assessment stringency. A model refresh is warranted upon material change in FDA premarket guidance for diagnostic-therapeutic convergence devices.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pressure-Volume Loop Systems Market
Medical Devices
Wireless Handheld Ultrasound Devices Market
Medical Devices
France Contraceptive Devices Market
Medical Devices
Tubal Obstruction Devices Market
Medical Devices
Dialysis Catheters Market
Medical Devices
Global Intragastric Balloon Market
Medical Devices
Veterinary Arthroscopy Device Market
Medical Devices
Personal-Use Facial and Skin Therapy Devices Market
Medical Devices
Reusable Medical Battery Market
Medical Devices
Biologic Injectors Market
Medical Devices
Benign Prostatic Hyperplasia (BPH) Treatment Devices Market
Medical Devices
Australia and New Zealand Diabetes Devices Market
Medical Devices
Veterinary X-Ray Illuminators Market
Medical Devices
France Drug Delivery Devices Market
Medical Devices
Sleep Apnea Implants Market
Medical Devices
Brazil Medical Devices Market