
 Capsule Endoscope and Workstations Market | 2026-2036
Capsule Endoscope and Workstations Market Size, Share, and Industry Trends Forecast 2026-2036
Capsule Endoscope and Workstations Market Outlook
The EU Medical Device Regulation is recalibrating conformity requirements for ingestible diagnostic systems across European markets. Medtronic leverages its vertically integrated manufacturing infrastructure to sustain regulatory compliance across multiple jurisdictions simultaneously. CapsoVision specializes in capsule designs with onboard storage that eliminates real-time transmission constraints, differentiating its portfolio from radio-frequency-dependent alternatives. Olympus Corporation anchors its competitive position through endoscopic ecosystem integration, where capsule outputs feed directly into existing visualization infrastructure.
Capsule endoscopes comprise ingestible, camera-equipped devices that capture gastrointestinal tract images using CMOS or CCD sensors with LED illumination, transmitting data wirelessly to external receivers for workstation-based review and algorithmic analysis. Visualization workstations represent the margin-intensive segment, where software-enabled image reconstruction and AI-assisted pathology detection command premium positioning against hardware-only data transmission systems. Wireless capsules lead procedural volume due to established reimbursement in gastroenterology, though oncology applications are expanding fastest as capsule platforms integrate targeted biopsy markers and therapeutic delivery mechanisms.
FDA de novo pathways and EU MDR conformity assessment procedures shape market access timelines, with both frameworks intensifying clinical evidence requirements for novel capsule technologies. Japan's PMDA and China's NMPA maintain distinct approval standards that fragment go-to-market strategies for manufacturers seeking Asia-Pacific presence. Stakeholders must monitor evolving reimbursement decisions for capsule procedures across public and private payers, as coverage determination increasingly dictates hospital procurement velocity and manufacturer revenue predictability.
Market Dynamics
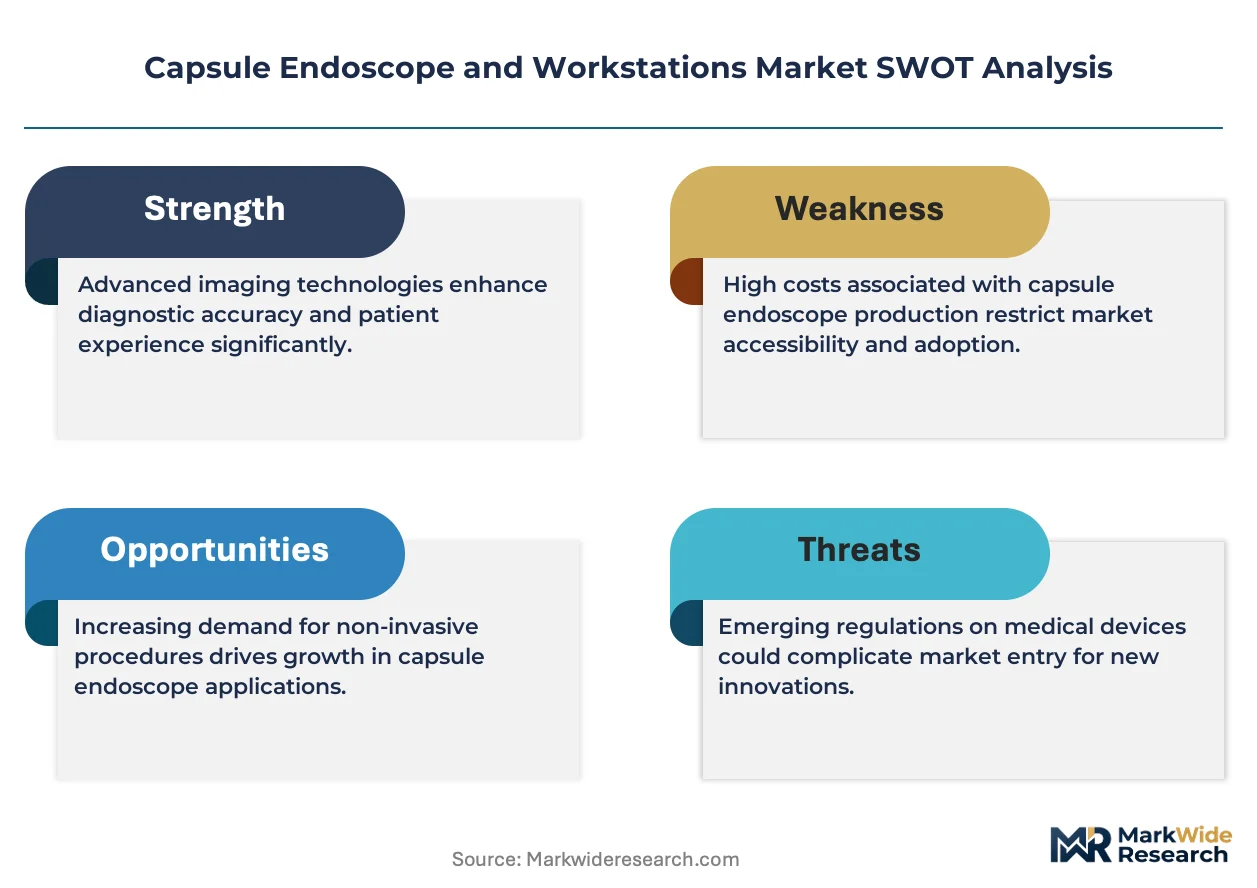
FDA de novo clearance refinements and EU MDR recalibration are compressing product development timelines while elevating clinical evidence thresholds, forcing manufacturers to front-load regulatory investment before commercialization.
Growth Catalysts
- Gastroenterology department expansion:Hospital systems across the United States are consolidating capsule-based diagnostic protocols as non-invasive alternatives to conventional endoscopy, driving procedural volume.
- AI-assisted pathology detection:Software-enabled image reconstruction capabilities embedded in visualization workstations command premium positioning against hardware-only transmission systems.
- EU MDR framework alignment:Medtronic leverages vertically integrated manufacturing infrastructure to sustain simultaneous multi-jurisdictional compliance, accelerating market access velocity.
Market Restraints
- CMOS sensor supply concentration:Specialized imaging component fabrication concentrates among East Asian foundries, exposing manufacturers to geopolitical disruption risk.
- Real-time transmission dependency:Radio-frequency-dependent capsule designs face technical limitations in anatomical regions with signal attenuation, constraining diagnostic completeness.
- Reimbursement determination lag:Public and private payer coverage decisions increasingly dictate hospital procurement velocity, creating revenue predictability friction for manufacturers.
Strategic Opportunities
- Oncology application expansion:Capsule platforms integrating targeted biopsy markers and therapeutic delivery mechanisms represent the fastest-growing procedural category.
- Onboard storage differentiation:CapsoVision's capsule designs eliminating real-time transmission constraints enable diagnostic completion in signal-challenged anatomical regions.
- Japan PMDA pathway optimization:Distinct approval standards from FDA and EU MDR create first-mover advantages for manufacturers establishing Asia-Pacific presence.
Industry Challenges
- Algorithm validation timelines:AI-assisted detection software requires extensive clinical evidence generation to satisfy FDA de novo and EU MDR conformity assessment procedures.
- Workstation integration complexity:Visualization software must feed directly into existing hospital visualization infrastructure, demanding customization for heterogeneous legacy systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Capsule Endoscope and Workstations Market |
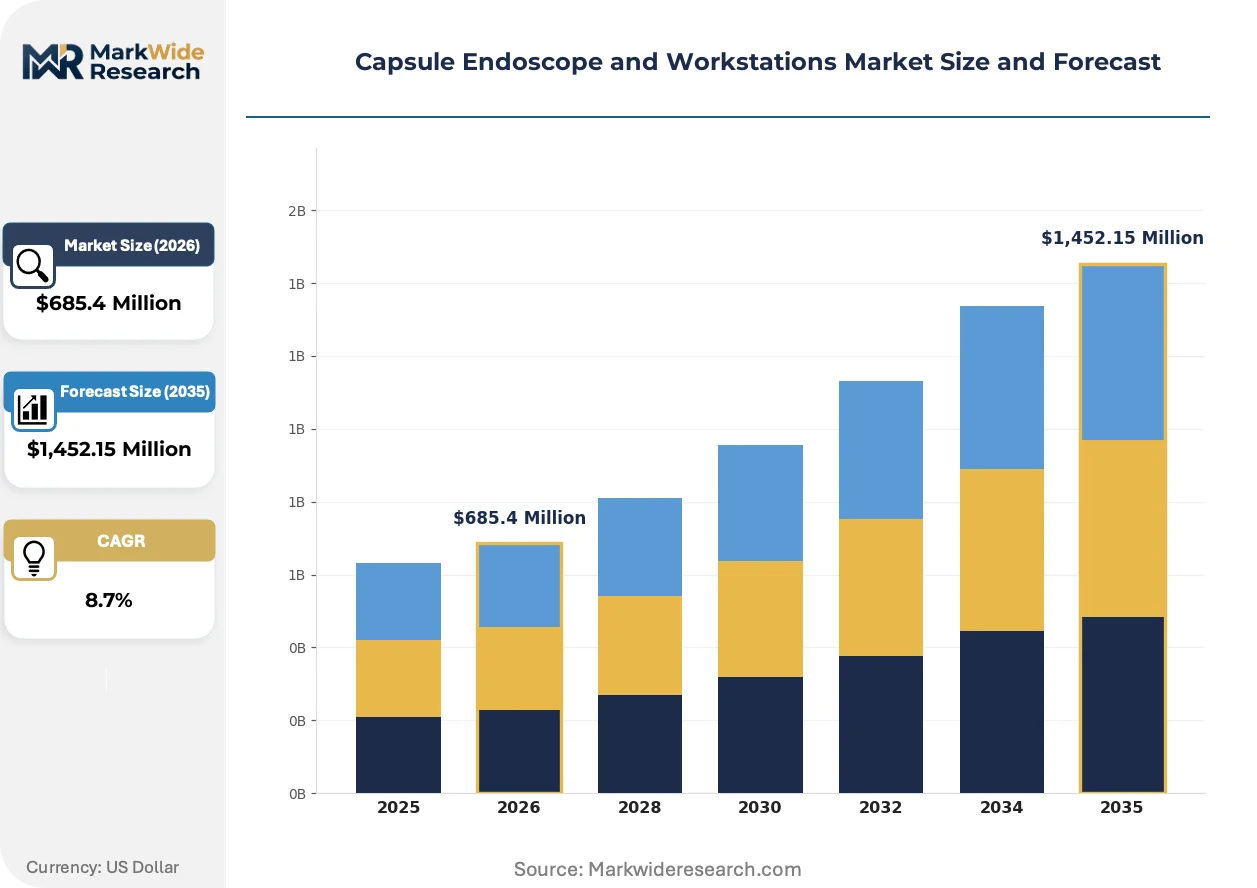
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Capsule, Visualization Workstation, Data Transmission System, Accessories End User: Hospitals, Clinics, Diagnostic Centers, Research Institutions Technology: Image Capture Technology, LED Illumination, Wireless Communication, Data Processing Algorithms Application: Gastroenterology, Oncology, Pain Management, General Surgery |
| Companies Covered | Medtronic, Olympus Corporation, CapsoVision, IntroMedic, Chongqing Jinshan Science & Technology, RF System Lab, Boston Scientific Corporation, Fujifilm Holding Corporation, Check-Cap, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Capsule Endoscope and Workstations Market Strategic Shifts
Capsule endoscope architecture is fragmenting across transmission modalities while regulatory frameworks intensify clinical evidence requirements, reshaping competitive positioning around software capabilities rather than hardware specifications.
CapsoVision's onboard storage technology is decentralizing diagnostic data capture from real-time radio-frequency transmission constraints. Gastroenterology departments in integrated delivery networks are adopting these capsules for procedures involving anatomical regions with signal attenuation. This decentralization is compressing the performance gap between wireless-dependent competitors and storage-enabled alternatives.
EU MDR conformity assessment procedures are intensifying clinical evidence requirements for novel capsule technologies. Manufacturers must generate expanded pre-market clinical data to satisfy notified body scrutiny. Capsule platforms with existing PMA approvals face shorter recertification pathways than de novo entrants.
Hospital procurement is consolidating around integrated delivery networks that negotiate enterprise-wide capsule platform and workstation contracts. Independent gastroenterology practices are losing purchasing leverage as procurement authority centralizes. This concentration is most visible across United States health systems where reimbursement determination increasingly dictates vendor selection.
Capsule Endoscope and Workstations Market Segmentation
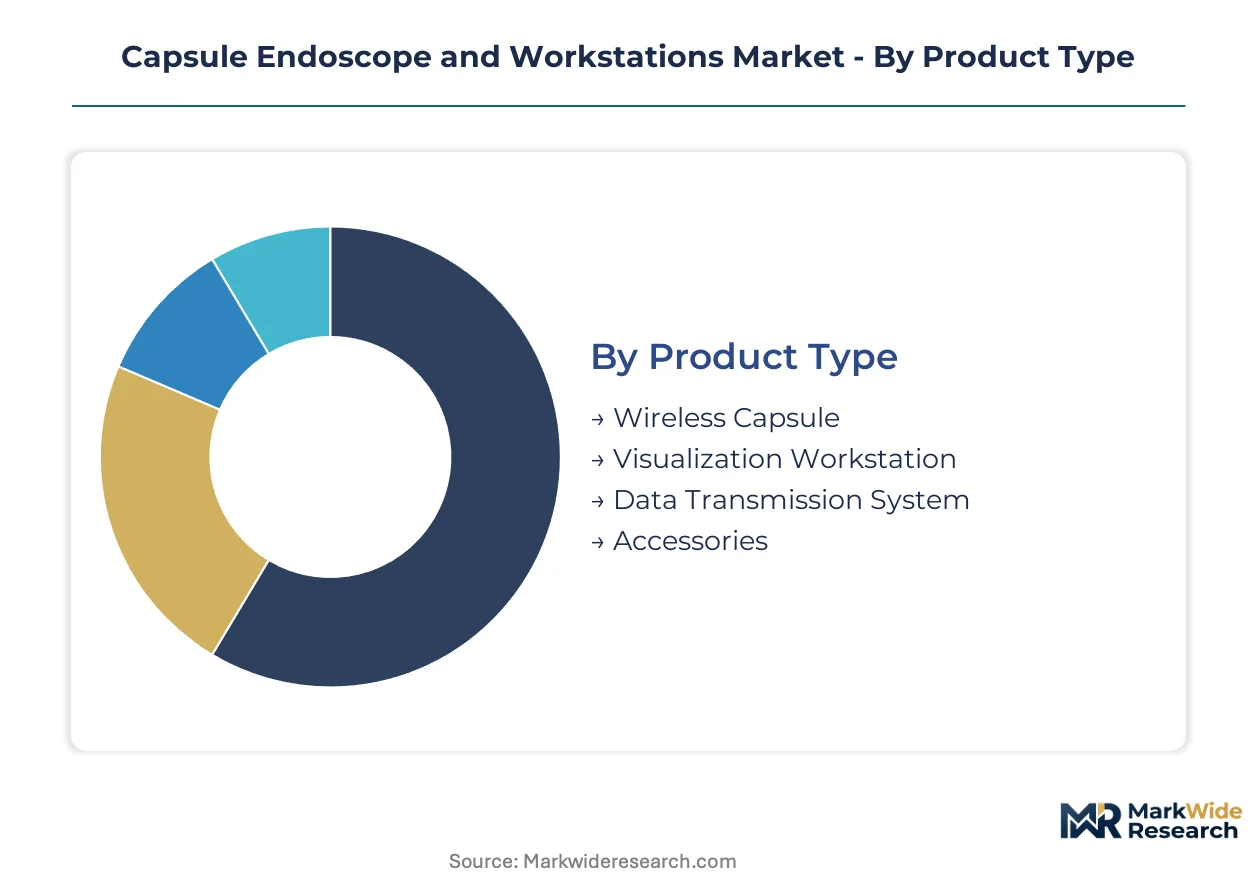
Segmentation in the capsule endoscope and workstations market reveals distinct margin profiles across hardware and software layers, with visualization workstations commanding premium positioning through algorithmic differentiation. Procurement patterns diverge sharply between integrated hospital networks and independent diagnostic facilities, reshaping vendor go-to-market strategies.
Product Type:
Volume concentrates in wireless capsules, yet margin accrues disproportionately to software-enabled workstation systems.
- Wireless Capsule:Ingestible devices equipped with CMOS or CCD sensors and LED illumination capture gastrointestinal tract images for wireless transmission to external receivers. Hospital systems in the United States are consolidating procurement of these devices as non-invasive alternatives to conventional endoscopy, though CMOS sensor supply concentration among East Asian foundries exposes manufacturers to geopolitical disruption risk.
- Visualization Workstation:Software platforms enabling image reconstruction and AI-assisted pathology detection represent the margin-intensive segment, commanding premium positioning against hardware-only alternatives. Integrated delivery networks negotiate enterprise-wide contracts for these systems, centralizing procurement authority away from independent gastroenterology practices.
- Data Transmission System:Hardware infrastructure facilitating wireless data relay from capsule to workstation, facing commoditization pressure as onboard storage alternatives eliminate real-time transmission dependencies.
- Accessories:Consumables and peripheral components including external receivers, sensor arrays, and calibration tools, capturing recurring revenue streams through replacement cycles.
Today's leader: Visualization Workstation. Tomorrow's challenger: Wireless Capsule with onboard storage differentiation.
End User:
Procurement authority is shifting toward consolidated networks, fragmenting purchasing leverage among smaller facilities.
- Hospitals:Gastroenterology departments across United States health systems are expanding capsule-based diagnostic protocols, with reimbursement determination increasingly dictating vendor selection and procurement velocity.
- Clinics:Independent gastroenterology practices are losing purchasing leverage as integrated delivery networks centralize procurement authority, constraining their access to enterprise pricing tiers.
- Diagnostic Centers:Specialized facilities focused on outpatient imaging and pathology detection, adopting workstation platforms with algorithmic capabilities to differentiate service offerings.
- Research Institutions:Academic medical centers generating clinical evidence for FDA de novo pathways and EU MDR conformity assessments, partnering with manufacturers on pre-market validation studies.
Procurement gravity centers on Hospitals. Research Institutions are gaining influence fastest through regulatory evidence generation partnerships.
Technology:
Competitive positioning is reshaping around software capabilities rather than hardware specifications as regulatory frameworks intensify clinical evidence requirements.
- Image Capture Technology:CMOS and CCD sensor architectures determine diagnostic resolution, with specialized fabrication concentrating among East Asian foundries and exposing supply chains to geopolitical disruption.
- LED Illumination:Miniaturized lighting systems enabling consistent image quality across gastrointestinal tract regions, facing thermal management constraints in compact capsule form factors.
- Wireless Communication:Radio-frequency transmission protocols face technical limitations in anatomical regions with signal attenuation, constraining diagnostic completeness and driving demand for onboard storage alternatives.
- Data Processing Algorithms:AI-assisted pathology detection software requires extensive clinical evidence generation to satisfy FDA de novo and EU MDR conformity assessment procedures, extending validation timelines.
Wireless Communication dominates procedural volume. Data Processing Algorithms are climbing the fastest as premium workstation differentiators.
Application:
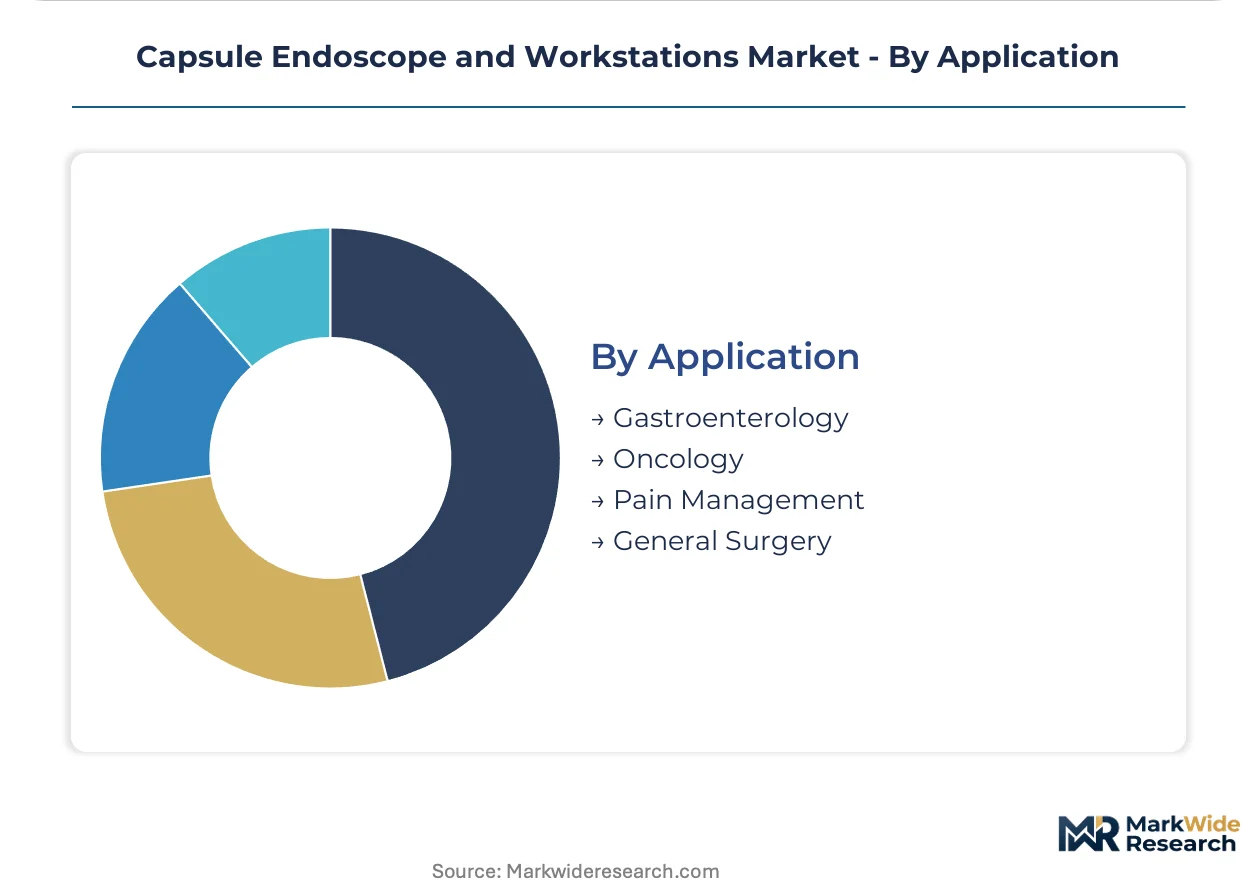
Oncology applications are expanding most quickly as capsule platforms integrate targeted biopsy markers and therapeutic delivery mechanisms.
- Gastroenterology:Established reimbursement pathways drive procedural volume for small bowel examination and occult bleeding detection, with FDA-cleared protocols enabling predictable revenue streams for manufacturers.
- Oncology:Capsule platforms integrating targeted biopsy markers and therapeutic delivery mechanisms represent the steepest expansion trajectory, though clinical evidence requirements for novel indications extend regulatory timelines.
- Pain Management:Emerging applications in targeted drug delivery to specific gastrointestinal regions, requiring specialized capsule architectures with controlled-release mechanisms.
- General Surgery:Preoperative visualization and postoperative monitoring applications, competing against established endoscopic alternatives in hospital surgical departments.
Gastroenterology anchors current revenue. Oncology is gaining share fastest through therapeutic integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capsule endoscopy technology originated in Israel during the late 1990s with Given Imaging's pioneering work, then scaled commercially through United States FDA clearances and European CE marking expansions. The technology's diffusion now spans hospital systems across five major markets with distinct regulatory and procurement characteristics.
United States
Integrated delivery networks in Texas, California, and the Northeast Corridor are consolidating enterprise-wide capsule platform contracts, with the FDA's de novo pathway refinement compressing product development timelines. Reimbursement determination by CMS and private payers increasingly dictates hospital procurement velocity. The Mayo Clinic in Rochester and Cleveland Clinic anchor clinical evidence generation partnerships with manufacturers.
Germany
University hospital systems in Bavaria and North Rhine-Westphalia are expanding capsule-based diagnostic protocols under EU MDR conformity assessment procedures. The BfArM and notified body scrutiny elevates clinical evidence thresholds for novel capsule technologies. Berlin-Brandenburg hosts regulatory consulting clusters supporting multi-jurisdictional compliance strategies for manufacturers.
Japan
PMDA maintains distinct approval standards from FDA and EU MDR, creating first-mover advantages for manufacturers establishing Asia-Pacific presence. Tokyo and Osaka metropolitan hospital networks are adopting capsule platforms for small bowel examination. The Kansai region concentrates endoscopic device distribution infrastructure serving domestic and export markets.
China
NMPA approval standards fragment go-to-market strategies for multinational manufacturers seeking domestic market access. Yangtze River Delta hospital systems in Shanghai and Jiangsu province are piloting AI-assisted pathology detection workstations. Shenzhen and Beijing host domestic capsule manufacturers competing on cost-positioning against imported alternatives.
United Kingdom
NHS England procurement frameworks centralize capsule endoscope purchasing authority away from individual hospital trusts. The MHRA post-Brexit regulatory pathway diverges from EU MDR, requiring separate conformity assessment for UK market access. London and the Southeast concentrate private diagnostic centers adopting premium workstation platforms.
Capsule Endoscope and Workstations Market Competitive Environment
Premium-margin players sit above commodity-margin players across software-enabled workstation capabilities versus hardware-only data transmission systems. The vendor base stratifies into three tiers: diversified medical technology conglomerates with vertically integrated manufacturing, specialized capsule designers with onboard storage differentiation, and regional component suppliers serving Asian markets. Strategic moves concentrate on regulatory evidence generation partnerships and workstation integration customization for heterogeneous hospital legacy systems.
Within the diversified conglomerate tier, Medtronic and Olympus Corporation exemplify players leveraging endoscopic ecosystem integration to sustain multi-jurisdictional compliance. CapsoVision occupies a specialist position representing onboard storage-enabled capsule architectures that eliminate real-time transmission constraints. These three anchors illustrate how competitive positioning reshapes around software capabilities rather than hardware specifications as regulatory frameworks intensify clinical evidence requirements.
| Leading Market Players |
|---|
| Medtronic |
| Olympus Corporation |
| CapsoVision |
| IntroMedic |
| Chongqing Jinshan Science & Technology |
| RF System Lab |
| Boston Scientific Corporation |
| Fujifilm Holding Corporation |
| Check-Cap |
| Others |
Value Chain & Pricing Dynamics
Workstation-versus-capsule margin bifurcation splits pricing power along software-hardware lines, with visualization platforms commanding premium multiples while wireless capsules face commoditization pressure from onboard storage alternatives. This divergence concentrates procurement leverage among integrated delivery networks in the United States while fragmenting vendor pricing autonomy across component tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs workstation procurement, with AI-enabled pathology detection modules separating premium tiers from hardware-only configurations. FDA de novo clearance tier and CE marking under EU MDR function as certification ladders justifying price premiums. Cost compression in wireless capsules is intensifying because CapsoVision's storage-enabled designs eliminate real-time transmission dependencies. Independent gastroenterology practices exhibit highest price sensitivity, while consolidated hospital networks leverage enterprise volume for standard-tier access.
Supply Chain Analysis
Domestic-content mandates in China's NMPA framework and India's Make in India medical device initiative are reshaping sourcing patterns for multinational manufacturers seeking Asia-Pacific market access. CMOS sensor fabrication concentrates in Taiwan, South Korea, and Japan, with specialized LED illumination components drawing from Japanese and German precision optics suppliers. Single-source vulnerability in East Asian foundry capacity exposes manufacturers to geopolitical disruption. Distribution runs through integrated delivery network procurement offices and hospital system GPO contracts in the United States, supplemented by regional distributors serving European university hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where FDA de novo pathway refinements and EU MDR recalibration continuously elevate clinical evidence thresholds, accelerating demand for validation partnerships and software-enabled differentiation.
For Market Incumbents: To counter onboard storage disruption from specialized capsule designers, Medtronic and Olympus Corporation should deepen backward integration into CMOS sensor supply chains while accelerating workstation AI validation timelines. Captive supply of imaging components reduces exposure to East Asian foundry concentration. FDA submission prioritization for algorithmic detection modules defends margin position against hardware-only competitors.
For New Entrants and Emerging Players: Capture underserved signal-challenged anatomical regions where real-time transmission fails, positioning onboard storage architectures for small bowel completion procedures. Oncology applications with therapeutic delivery integration represent the most penetrable segment given extended regulatory timelines for incumbents. Hospital system partnership models bypass GPO procurement friction.
For Investors and Strategic Acquirers: Asymmetric upside sits with workstation software specialists possessing FDA de novo clearance momentum and hospital integration capabilities. Five-to-ten year viability hinges on reimbursement determination velocity across CMS and private payers. The signal to watch is NCD coverage expansion for AI-assisted pathology detection.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA De Novo Submission | Accelerates market access for novel capsule technologies with onboard storage differentiation. |
| EU MDR Conformity Pathway | Notified body scrutiny elevates clinical evidence requirements for CE marking retention. |
| Hospital System Partnership | Integrated delivery network contracts centralize procurement authority away from independent practices. |
| Software Companion Development | AI-assisted pathology detection commands premium workstation positioning against hardware-only alternatives. |
| Reimbursement Strategy | CMS coverage determination dictates procurement velocity for gastroenterology departments. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at capsule manufacturers with secondary validation against FDA 510(k) and de novo filings, EU MDR notified body documentation, CMS reimbursement databases, and hospital procurement records. Bottom-up procedure volume estimates and top-down market sizing triangulated across data streams.
Segment-weighting approaches distributed value across product type, end user, technology, and application dimensions, with oncology therapeutic integration and onboard storage differentiation receiving distinct modeling treatment. CAGRs derived from procedure volume trajectories, reimbursement expansion scenarios, and technology substitution curves across the analysis window. Forecast inputs incorporated FDA clearance pipeline status and EU MDR recertification timelines.
Regulatory pathway delays, reimbursement determination reversals, and CMOS supply disruption are the dominant revision risks to modeled outputs. Forecasts reflect assumptions around continued de novo clearance efficiency and stable East Asian foundry capacity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Neuro Medical Devices Market
Medical Devices
Nephrostomy Devices Market
Medical Devices
China Respiratory Devices Market
Medical Devices
Global Endovascular Aneurysm Repair Devices Market
Medical Devices
Prefilled Syringe Contract Manufacturing Market
Medical Devices
Global Breast Implants Market
Medical Devices
Gastric Bands Market
Medical Devices
Global Robotic Nurse Assistant Market
Medical Devices
Europe Cardiac Rhythm Management Devices Market
Medical Devices
Global Brain Implants Market
Medical Devices
Steroid Releasing Implant Market
Medical Devices
Pacemaker Devices Market
Medical Devices
Australia Artificial Organs and Bionic Implants Market
Medical Devices
Neurotechnology Market
Medical Devices
Cholesterol Monitors Market
Medical Devices
Computer Aided Trauma Fixators Market