
 Electroencephalography Devices Market | 2026-2036
Electroencephalography Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Electroencephalography Devices Market Intelligence
China is fragmenting its EEG device supply base as domestic manufacturers scale wet-electrode production for hospital procurement tenders. Nihon Kohden Corporation anchors its position through deep channel control across East Asian diagnostic centers. Brain Products GmbH differentiates via specialized software ecosystems for cognitive research laboratories. Medtronic leverages its broader neurotechnology portfolio to cross-sell EEG systems into epilepsy monitoring units it already supplies with implantable devices.
Electroencephalography devices measure electrical activity via scalp-mounted electrodes, typically capturing signals in the 0.5–100 Hz frequency range with microvolt-level sensitivity for clinical and research applications. The primary purpose spans diagnostic neurology, sleep medicine, and emerging brain-computer interface development where real-time neural signal decoding enables direct device control. Wireless EEG systems are capturing the fastest growth trajectory as ambulatory monitoring expands beyond hospital walls into home-based epilepsy surveillance. Clinical EEG remains the margin pool anchor due to premium pricing tied to dense electrode arrays and integrated video synchronization for seizure characterization. Dry electrode technology is displacing traditional conductive gel protocols in research and consumer-adjacent segments where setup speed and subject throughput determine operational economics.
The FDA's 510(k) pathway and EU MDR classification rules for active medical devices govern market access, with software-as-a-medical-device amendments now capturing AI-enhanced EEG interpretation tools under premarket scrutiny. HIPAA in the United States and GDPR in Europe impose divergent data governance obligations on cloud-connected EEG systems that stream neural data for remote clinical review. China's NMPA has accelerated review timelines for domestically manufactured neurology equipment under innovation channel designations. Stakeholders must decide whether to architect separate regulatory submission strategies per geography or pursue unified technical file structures that satisfy the most stringent jurisdiction first.
Market Dynamics
Wireless EEG systems are compressing the traditional hospital-centric supply model as ambulatory epilepsy monitoring migrates into residential settings, forcing manufacturers to rearchitect service and validation protocols around distributed deployment.
Growth Catalysts
- DARPA-funded neural interface consortia:These research programs in the United States are accelerating procurement cycles for high-density electrode arrays capable of real-time signal decoding for brain-computer interface development.
- EU MDR software-as-a-medical-device amendments:The expanded premarket scrutiny of AI-enhanced EEG interpretation tools is legitimizing automated diagnostic platforms and expanding reimbursable clinical workflows.
- Home-based epilepsy surveillance:Patient demand for continuous monitoring outside institutional settings is pulling wireless systems through neurology practice networks and into direct-to-provider purchasing channels.
Market Restraints
- Silver-silver chloride electrode supply concentration:Wet-electrode manufacturing depends on specialized conductive materials sourced from limited East Asian chemical suppliers, exposing procurement to input cost volatility.
- GDPR-HIPAA data governance divergence:Cloud-connected EEG systems face conflicting encryption and residency requirements that fragment technical architectures and delay multi-territory launches.
- Conductive gel protocols:Traditional electrode preparation remains entrenched in tertiary hospital neurology departments where clinical staff resist workflow changes despite dry-electrode alternatives.
Strategic Opportunities
- China's NMPA innovation channel:Accelerated review timelines for domestically manufactured neurology equipment create first-mover advantages for localized production and hospital tender participation.
- Sleep medicine expansion:Polysomnography labs are adopting portable EEG systems for home sleep apnea studies, opening volume segments outside epilepsy monitoring.
- AI-EEG convergence:Machine learning pattern recognition for seizure prediction is creating reimbursable service layers that hardware vendors can capture through software subscriptions.
Industry Challenges
- Neurophysiology technologist shortage:Specialized clinical staff capable of electrode placement and artifact interpretation are concentrated in academic medical centers, constraining deployment scale.
- ISO 13485 certification timelines:Quality management system audits for wireless EEG devices are extending due to software validation requirements, delaying market entry for revised product lines.
- Legacy EMR integration:Hospital information systems require custom HL7 interfaces for EEG data streams, complicating enterprise sales cycles and implementation resourcing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electroencephalography Devices Market |
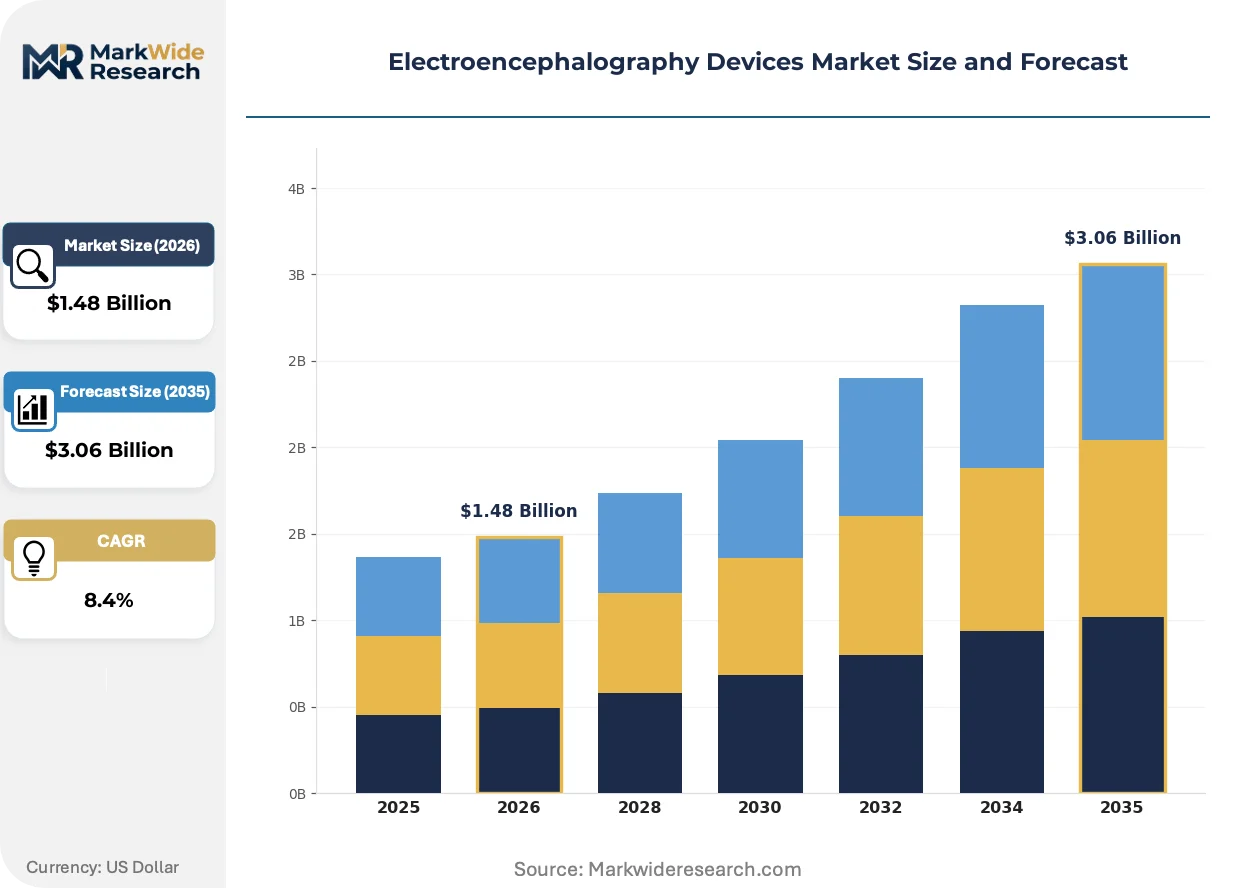
| Market Size in 2026 | $1.48 Billion |
| Market Size in 2035 | $3.06 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless EEG, Portable EEG, Clinical EEG, Ambulatory EEG End User: Hospitals, Diagnostic Centers, Research Institutions, Homecare Technology: Dry Electrode, Wet Electrode, Fiber Optic, Synchronous Recording Application: Sleep Disorders, Epilepsy Monitoring, Cognitive Research, Brain-Computer Interface |
| Companies Covered | Natus Medical Incorporated, Nihon Kohden Corporation, Compumedics Limited, Cadwell Industries, Neurosoft, Electrical Geodesics Inc., Medtronic, NeuroWave Systems Inc., Brain Products GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electroencephalography Devices Market Strategic Shifts & Innovations
Dry electrode technology is compressing setup protocols and expanding addressable use cases beyond traditional clinical environments into research and consumer-adjacent applications.
Dry electrode arrays eliminate conductive gel application through capacitive coupling or active impedance compensation, reducing preparation time from thirty minutes to under five. Academic cognitive research laboratories are adopting these systems to increase subject throughput in longitudinal studies. This hardware shift is digitizing operational economics in segments where session volume determines grant funding sustainability.
FDA evolving guidance on medical device software is capturing brain-computer interface applications under premarket validation requirements that previously applied only to hardware. Developers must now submit algorithmic performance data for neural signal decoding accuracy. Epilepsy monitoring units with integrated video-EEG synchronization are most affected, with vendors restructuring quality systems to accommodate iterative software updates.
Hospital neurology departments are unbundling after-sales service contracts from hardware procurement, opting for third-party technical support or in-house biomedical engineering coverage. Equipment financing through leasing structures is displacing capital purchase in United States academic medical centers. This purchasing behavior change is most visible in California and Massachusetts hospital networks where operating budget flexibility outweighs depreciation preferences.
Electroencephalography Devices Market Segmentation
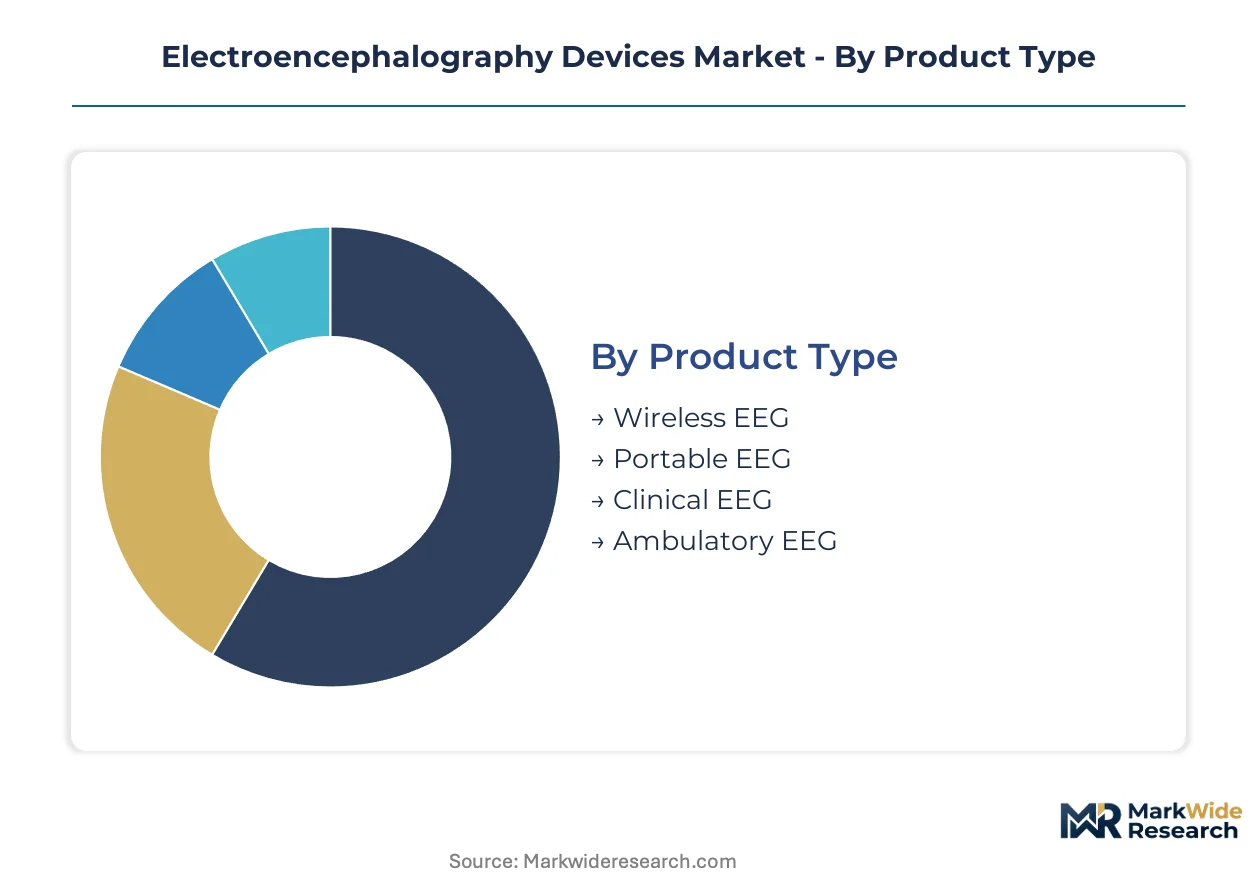
Segmentation in the electroencephalography devices market determines service architecture, regulatory pathway selection, and channel economics. Product type dictates installation complexity and recurring revenue potential. End-user concentration shapes pricing power and contract duration.
Product Type:
After-sales-service intensity varies sharply across product categories, with wireless and ambulatory systems requiring distributed technical support networks rather than centralized hospital engineering coverage.
- Wireless EEG:These systems transmit neural data via Bluetooth or proprietary radio protocols to base stations or cloud gateways, eliminating tethered connections for mobile patients. Demand concentrates in United States homecare networks where DARPA-funded brain-computer interface research programs procure high-density arrays for real-time signal decoding. Ambulatory epilepsy monitoring contracts now specify 24/7 remote technical support as a procurement requirement.
- Clinical EEG:Fixed-installation systems with 32-256 electrode arrays and integrated video synchronization dominate tertiary hospital neurology departments. European academic medical centers in Germany and Switzerland anchor procurement volume due to dense epilepsy monitoring unit infrastructure and established reimbursement for long-term video-EEG studies. These installations generate multi-year service contracts tied to electrode replacement schedules and software validation updates.
- Portable EEG:Compact units with 16-24 channels serve point-of-care diagnostics in settings lacking fixed neurophysiology infrastructure. Diagnostic centers in China's tier-2 cities are scaling procurement for outpatient epilepsy screening programs.
- Ambulatory EEG:Wearable systems with extended battery life enable 72-hour continuous monitoring outside clinical facilities. Homecare segments in California and Massachusetts hospital networks are adopting these for post-surgical seizure surveillance.
By volume, Clinical EEG leads. By growth pace, Wireless EEG is ahead.
End User:
Customer type determines contract structure, with hospitals favoring capital purchases and research institutions driving equipment leasing adoption.
- Hospitals:Tertiary neurology departments in the United States, Germany, and Japan account for the densest installed base of high-channel-count systems. These customers prioritize FDA 510(k) clearance and EU MDR certification for video-EEG synchronization modules. Procurement committees increasingly unbundle hardware from service contracts, opting for third-party technical support or in-house biomedical engineering coverage.
- Diagnostic Centers:Outpatient facilities in China's provincial capitals are expanding EEG capacity under hospital procurement tender programs. NMPA innovation channel designations accelerate regulatory approval for domestically manufactured wet-electrode systems.
- Research Institutions:Cognitive neuroscience laboratories at MIT, Stanford, and the Max Planck Institute drive demand for dry-electrode arrays with rapid setup protocols. Grant funding sustainability depends on subject throughput metrics that favor streamlined electrode preparation.
- Homecare:Residential epilepsy monitoring represents the emerging demand frontier, with wireless systems enabling continuous surveillance outside institutional settings. HIPAA compliance for cloud-connected neural data streams remains a procurement filter.
Hospitals dominate absolute unit shipments. Research institutions show the steepest expansion trajectory.
Technology:
Electrode technology selection governs preparation time, signal quality trade-offs, and operational economics across use cases.
- Dry Electrode:Capacitive coupling or active impedance compensation eliminates conductive gel application, compressing setup from thirty minutes to under five minutes. Academic cognitive research laboratories are adopting these systems to increase subject throughput in longitudinal studies.
- Wet Electrode:Silver-silver chloride compositions with conductive gel maintain signal fidelity for clinical diagnostics requiring microvolt-level sensitivity. East Asian chemical suppliers concentrate input material sourcing, exposing procurement to cost volatility.
- Fiber Optic:Optical signal transmission eliminates electrical interference in intraoperative neurophysiology settings. Specialized surgical centers in Switzerland and Japan deploy these for deep brain stimulation monitoring.
- Synchronous Recording:Time-locked multi-modal data capture combines EEG with video, EMG, or ECG streams. Epilepsy monitoring units require this capability for seizure characterization and surgical planning.
Wet Electrode retains volume leadership. Dry Electrode is gaining share fastest.
Application:
Clinical indication determines reimbursement eligibility, electrode density requirements, and software feature prioritization.
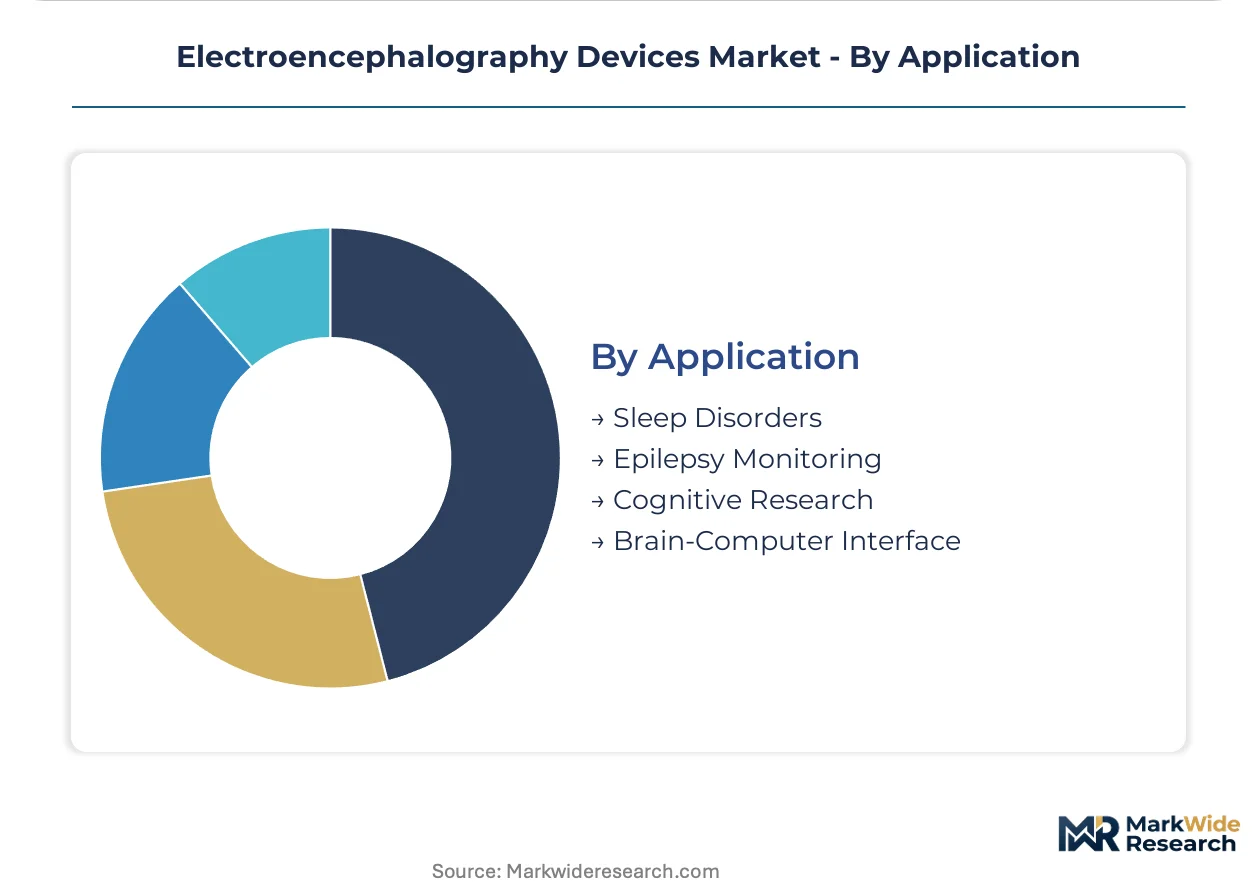
- Epilepsy Monitoring:Long-term video-EEG surveillance for seizure localization and surgical candidacy assessment represents the highest-value clinical application. United States academic medical centers and German epilepsy centers anchor demand for dense electrode arrays with integrated synchronization.
- Sleep Disorders:Polysomnography labs are adopting portable EEG systems for home sleep apnea studies, expanding addressable volume beyond traditional epilepsy segments.
- Cognitive Research:Experimental psychology and neuroscience laboratories employ EEG for event-related potential studies and brain-computer interface development. DARPA-funded consortia accelerate procurement cycles for high-density arrays.
- Brain-Computer Interface:Real-time neural signal decoding for device control is capturing FDA attention under evolving medical device software guidance. Algorithmic performance validation requirements now extend to signal processing software.
Epilepsy Monitoring leads by revenue concentration. Brain-Computer Interface shows the most rapid growth acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States academic medical centers deploy high-density electrode arrays for brain-computer interface research, while China's provincial hospitals prioritize cost-optimized wet-electrode systems for epilepsy screening programs. German epilepsy centers anchor European demand for video-EEG synchronization infrastructure.
United States
DARPA-funded neural interface consortia in Massachusetts and California accelerate procurement cycles for real-time signal decoding systems. FDA evolving guidance on medical device software now captures AI-enhanced EEG interpretation tools under premarket validation requirements. Boston and Stanford academic medical centers drive densest installed base of high-channel-count systems for epilepsy monitoring units.
Germany
Academic medical centers in Munich and Heidelberg maintain premium demand for video-EEG synchronization modules with integrated surgical planning software. EU MDR classification rules for active medical devices govern market access with expanded scrutiny of automated diagnostic platforms. The Baden-Württemberg industrial corridor concentrates specialized electrode manufacturing for intraoperative neurophysiology applications.
China
Hospital procurement tenders in tier-2 cities scale wet-electrode production for outpatient epilepsy screening programs. NMPA innovation channel designations accelerate review timelines for domestically manufactured neurology equipment. The Yangtze River Delta manufacturing cluster fragments supply base as local producers capture provincial hospital contracts.
Japan
Specialized surgical centers in Tokyo and Osaka deploy fiber optic EEG systems for deep brain stimulation monitoring. PMDA regulatory pathways align with international standards while maintaining distinct quality management system requirements. The Kanto region anchors East Asian diagnostic center infrastructure with established reimbursement for long-term video-EEG studies.
Switzerland
Specialized epilepsy centers in Zurich and Geneva prioritize synchronous recording capabilities for seizure characterization and surgical candidacy assessment. Swissmedic maintains streamlined approval pathways for CE-marked devices with supplemental national requirements. The Basel pharmaceutical corridor drives cross-border procurement of research-grade systems for cognitive neuroscience applications.
Electroencephalography Devices Market Key Industry Players
Capability concentration sits with specialized neurotechnology developers; scale advantage sits with diversified medical device conglomerates. The vendor base separates into three functional tiers: research-grade specialists, hospital-system integrators, and emerging domestic manufacturers. Dominant competitive moves include software ecosystem differentiation and regional regulatory fast-tracking through localized production.
Within the research-specialist tier, Brain Products GmbH exemplifies positioning through specialized software ecosystems for cognitive research laboratories. Nihon Kohden Corporation anchors the hospital-system integrator category with deep channel control across East Asian diagnostic centers. Medtronic occupies a diversified neurotechnology position that enables cross-selling into epilepsy monitoring units already supplied with implantable devices.
| Leading Market Players |
|---|
| Natus Medical Incorporated |
| Nihon Kohden Corporation |
| Compumedics Limited |
| Cadwell Industries |
| Neurosoft |
| Electrical Geodesics Inc. |
| Medtronic |
| NeuroWave Systems Inc. |
| Brain Products GmbH |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta manufacturing cluster anchors wet-electrode production capacity for hospital procurement tenders, compressing margins for imported systems while elevating pricing power for domestic producers with NMPA innovation channel access. This geographic concentration of conductive material processing feeds directly into tiered procurement negotiations across China's provincial hospital networks.
Pricing Analysis
United States academic medical centers command 40-60% premiums over Chinese provincial hospitals for equivalent channel-count systems, reflecting FDA 510(k) validation costs and integrated video-EEG synchronization modules. Three-tier pricing structure across premium, standard, and economy levels separates research-grade dry-electrode arrays from clinical wet-electrode installations and portable diagnostic units. Cost compression in China's tier-2 city tenders is intensifying because local manufacturers now satisfy NMPA requirements without import duties. Diagnostic centers in provincial capitals exhibit highest price sensitivity; DARPA-funded research consortia show lowest sensitivity due to grant-funded procurement cycles.
Supply Chain Analysis
Silver-silver chloride electrode feedstock draws from concentrated East Asian chemical suppliers in Japan and South Korea, with secondary refining capacity in Germany's Baden-Württemberg corridor. Wet-electrode manufacturing rests on conductive gel polymers, precision-machined electrode housings, and medical-grade cable assemblies. Single-source vulnerability in specialized conductive materials exposes procurement to input cost volatility when currency fluctuations hit yen-denominated contracts. Distribution runs through hospital procurement committees in tertiary centers, direct-to-provider channels for wireless ambulatory systems, and research institution grant administration offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as United States hospital networks consolidate neurology department purchasing through centralized GPO contracts, fragmenting vendor access to individual physicians. This consolidation shifts negotiation leverage toward multi-year enterprise agreements with unbundled service components.
For Market Incumbents: Pre-empt dry-electrode commoditization by embedding AI-enhanced interpretation software into hardware leases, creating subscription revenue layers that emerging manufacturers cannot replicate without FDA SaMD validation timelines. Secure backward integration into silver-silver chloride material processing to insulate margin structures from East Asian chemical supplier volatility. Channel control through exclusive hospital biomedical engineering training programs defends against third-party technical support entrants.
For New Entrants and Emerging Players: China's tier-3 cities and county-level hospitals present the most penetrable white-space, where NMPA innovation channel designations accelerate approval timelines and procurement tenders favor domestic manufacturers. Homecare epilepsy monitoring in California and Massachusetts hospital network catchment areas offers second-entry opportunity through direct-to-provider wireless system sales. Go-to-market angle: position 72-hour ambulatory systems as post-surgical surveillance alternatives to inpatient video-EEG, capturing operating budget flexibility.
For Investors and Strategic Acquirers: Long-term, this sits as a neurotechnology platform play because EEG hardware serves as the data acquisition layer for brain-computer interface applications capturing DARPA funding acceleration. Acquisition target archetype: dry-electrode specialists with ISO 13485 certification and software-defined signal processing architectures. Signal to watch: FDA premarket submission volume for AI-enhanced EEG interpretation tools as inflection indicator for reimbursable automated diagnostic workflow adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-as-a-Medical-Device FDA Submission | Premarket validation for AI-enhanced EEG interpretation tools unlocks reimbursable clinical workflows in academic medical centers. |
| NMPA Innovation Channel Localization | Domestic manufacturing certification accelerates hospital tender participation in China's provincial procurement programs. |
| Dry-Electrode Technology Licensing | Capacitive coupling patents enable research laboratory market entry with five-minute setup protocols versus thirty-minute gel preparation. |
| Hospital System GPO Partnership | Consolidated purchasing committees in United States networks favor enterprise agreements with unbundled technical support options. |
| Brain-Computer Interface Consortium Participation | DARPA-funded research programs in Massachusetts and California drive high-density array procurement for real-time signal decoding. |
Research Approach
A standing panel of epilepsy monitoring unit directors, biomedical engineering managers, hospital purchasing committee chairs, and neurophysiology technologists provided ongoing calibration against secondary validation from FDA 510(k) filings, EU MDR technical documentation, NMPA innovation channel approvals, and hospital procurement database extracts. This primary stakeholder input combined with regulatory submission records and GPO contract disclosures enabled bottom-up installation base modeling and top-down market sizing triangulation across product categories and end-user segments.
Scenario-bracketing framed volume and value outputs across the projection horizon, with analytical frameworks modeling product type, electrode technology, application indication, and regional regulatory cluster as core segmentation dimensions. CAGRs derived from installation base growth rates, replacement cycle compression, and average selling price trajectories incorporated DARPA funding disbursement patterns and NMPA review timeline acceleration as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by wireless ambulatory specialists or AI-software pure-plays would shift outcomes beyond modeled ranges. Cross-checking against CMS Medicare reimbursement rate filings and provincial hospital tender award databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Stabilometric Platform Market
Medical Devices
Surgical AR Systems Market
Medical Devices
Keratoprosthesis (Kpro) Market
Medical Devices
Global Electrotherapy Devices Market
Medical Devices
Crescent Ultrasonic Cleansers Market
Medical Devices
Hormonal Implants Market
Medical Devices
Foot Ulcer Sensors Market
Medical Devices
Neurotechnology Market
Medical Devices
Global Motion Preservation Devices Market
Medical Devices
Intubation Accessories Market
Medical Devices
Implantable Port Market
Medical Devices
Implantable Drug Eluting Devices Market
Medical Devices
US Pulse Oximeters Market
Medical Devices
Global Intragastric Balloon Market
Medical Devices
Global Cardiopulmonary Bypass Accessory Equipment Market
Medical Devices
Americas Medical Suction Device Market