
 Gum Grafting Market | 2026-2036
Gum Grafting Market Size, Share, and Industry Trends Forecast 2026-2036
Gum Grafting Market Outlook
Periodontists are gaining share as the primary buyer archetype for advanced grafting procedures, while general dentists' dominance in basic soft-tissue management is unwinding amid case complexity and referral consolidation. Straumann Holding AG leverages its integrated implant-to-graft portfolio to capture premium workflows. Dentsply Sirona sustains broad channel access across dental schools and group practices. Geistlich Pharma AG specializes in xenogeneic collagen matrices that anchor its position in biologic graft substitutes.
Gum grafting encompasses surgical procedures that transplant soft tissue to correct gingival recession, augment ridge volume, or protect exposed root surfaces, utilizing autogenous connective tissue, free gingival tissue, or processed biologic matrices with thickness specifications typically ranging from 1.0 to 1.5 millimeters for optimal vascularization. The primary commercial purpose centers on restoring periodontal health, preventing further attachment loss, and enabling dental implant placement in deficient sites. Connective tissue grafts occupy the largest revenue pool due to their versatility in root coverage and papilla reconstruction applications. Biologic materials in grafting represent the fastest-expanding technology segment as processed collagen and amniotic-derived products reduce donor-site morbidity. Laser therapy remains a narrower niche where margin pools concentrate in specialized periodontal practices with capital equipment investment capacity.
The FDA regulates human cells, tissues, and cellular and tissue-based products under 21 CFR Part 1271, while the EMA's Medical Device Regulation governs grafting materials marketed across European Union member states, creating divergent compliance pathways for manufacturers. ISO 13485 quality management standards and ASTM F2212 biocompatibility testing protocols further shape product development timelines and market access requirements. Stakeholders must monitor reimbursement coding revisions and biologic material classification determinations that will reshape competitive positioning in grafting portfolios.
Market Dynamics
Periodontists are consolidating advanced grafting workflows as case complexity drives referral patterns toward specialists with integrated implant-to-soft-tissue capabilities, compressing general dentist participation in multi-site recession repair.
Growth Catalysts
- Biologic material classification:The FDA's 21 CFR Part 1271 framework for human cells and tissue-based products has clarified commercialization pathways for processed collagen matrices, accelerating manufacturer investment in xenogeneic substitutes.
- Implant therapy expansion:Rising patient referrals for pre-implant ridge augmentation are channeling volume toward periodontists with grafting expertise, particularly in private practice settings with cone-beam imaging capacity.
- Aging demographics:The United States exhibits sustained procedure demand as Medicare Advantage plans expand dental benefits and patients over 65 present with cumulative attachment loss requiring intervention.
Market Restraints
- Donor-site morbidity costs:Autogenous connective tissue harvesting from the palate creates patient recovery burdens and limits same-day bilateral procedures, constraining throughput in high-volume practices.
- Supply concentration:Xenogeneic collagen matrix production clusters among Swiss and German processing facilities, exposing distributors to single-source dependencies for porcine-derived scaffolds.
- Technical limitation:Root coverage predictability drops below 50% in sites with interproximal attachment loss exceeding 3 millimeters, restricting the addressable patient population for minimally invasive tunneling techniques.
Strategic Opportunities
- Underpenetrated geographies:Brazil's private dental insurance expansion and ANVISA's streamlined biologic product registration create white space for amniotic-derived graft substitutes in São Paulo and Rio de Janeiro metropolitan markets.
- Technology convergence:Piezoelectric surgical units combined with collagen matrices are enabling flapless palatal harvesting, reducing operative time and patient discomfort in specialized periodontal practices.
- Channel innovation:Direct-to-specialist distribution platforms are bypassing traditional dental dealer networks, allowing manufacturers to capture margin and provide case-planning support for complex ridge augmentation.
Industry Challenges
- Periodontist workforce scarcity:The American Academy of Periodontology reports declining residency graduates relative to retiring specialists, creating regional access gaps for advanced grafting procedures in rural and secondary metropolitan markets.
- ISO 13485 certification timelines:Biologic graft manufacturers face 18-to-24-month quality management system implementation periods, delaying market entry for novel matrix formulations amid evolving EMA MDR requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gum Grafting Market |
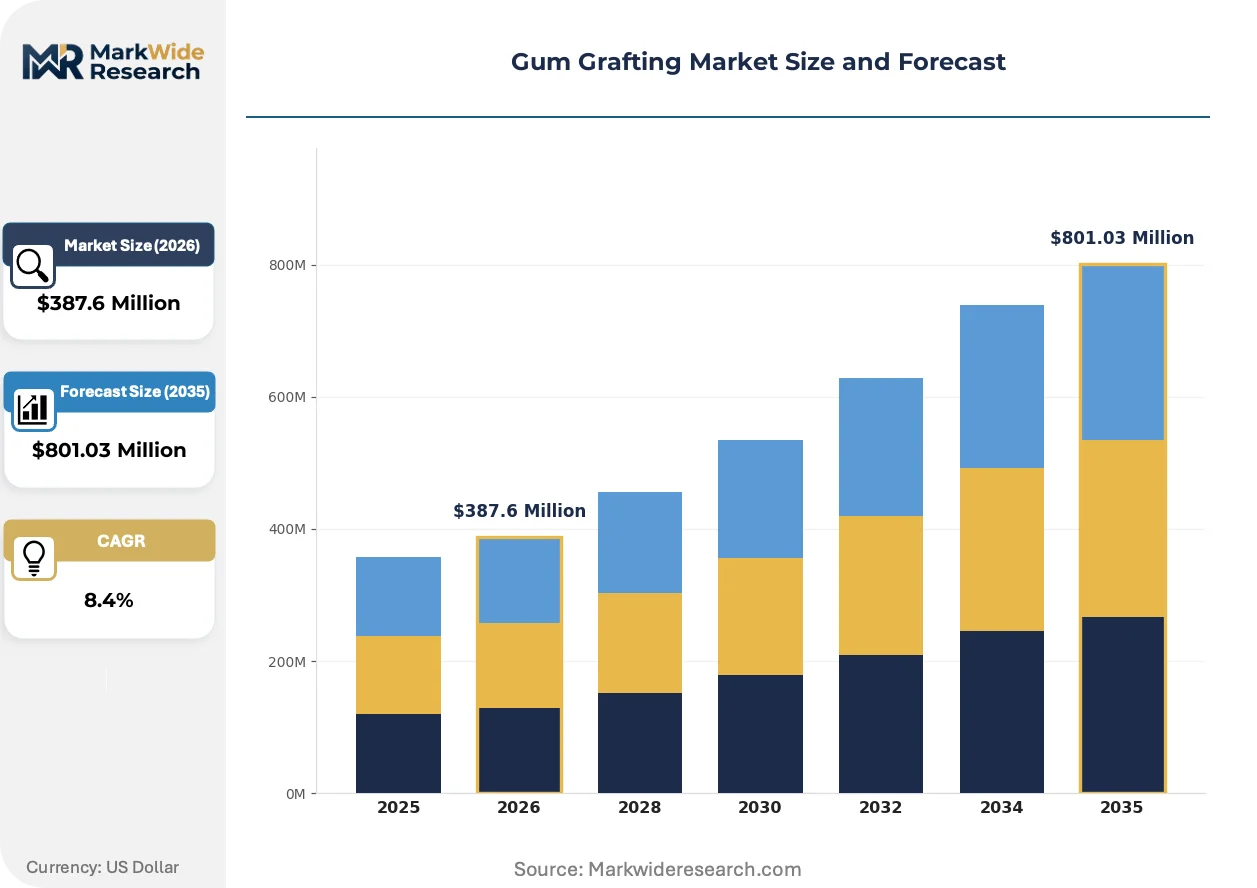
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $801.03 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Connective Tissue Grafts, Free Gingival Grafts, Pedicle Grafts, Other Grafts End User: Denturologists, Periodontists, General Dentists, Oral Surgeons Therapy Area: Periodontal Disease, Oral Cancer, Esthetic Enhancement, Implant Therapy Technology: Laser Therapy, Surgical Techniques, Biologic Materials, Guided Tissue Regeneration |
| Companies Covered | Straumann Holding AG, Dentsply Sirona, Zimmer Biomet Holdings, Inc., Geistlich Pharma AG, BioHorizons IPH, Inc., Nobel Biocare, botiss biomaterials GmbH, Den-Mat Holdings, LLC, Keystone Dental Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gum Grafting Market Strategic Shifts
Digital planning tools and advanced biomaterials are compressing treatment timelines while regulatory clarity around tissue-based products is reshaping competitive positioning among graft substitute manufacturers.
Collagen matrices derived from porcine and bovine sources are miniaturizing the surgical footprint of soft-tissue augmentation by eliminating palatal donor sites. Periodontists in high-volume US practices are adopting these substitutes for single-tooth recession defects at accelerating rates. The technology is miniaturizing operative trauma and expanding candidacy to patients who would decline autogenous harvesting.
The EMA's Medical Device Regulation (MDR) is tightening clinical evidence requirements for xenogeneic graft materials marketed across EU member states. Manufacturers must now submit biocompatibility data under updated Annex I general safety and performance requirements. Swiss and German processors are responding by consolidating CE marking responsibilities and expanding notified body relationships.
Group dental practices are consolidating procurement authority for grafting materials, displacing individual clinician purchasing autonomy. DSOs in Texas and Florida are negotiating formulary contracts that privilege specific collagen matrix brands across 50-plus location networks. This concentration is most visible in Sun Belt states where private equity-backed dental platforms have achieved critical mass.
Gum Grafting Market Segmentation
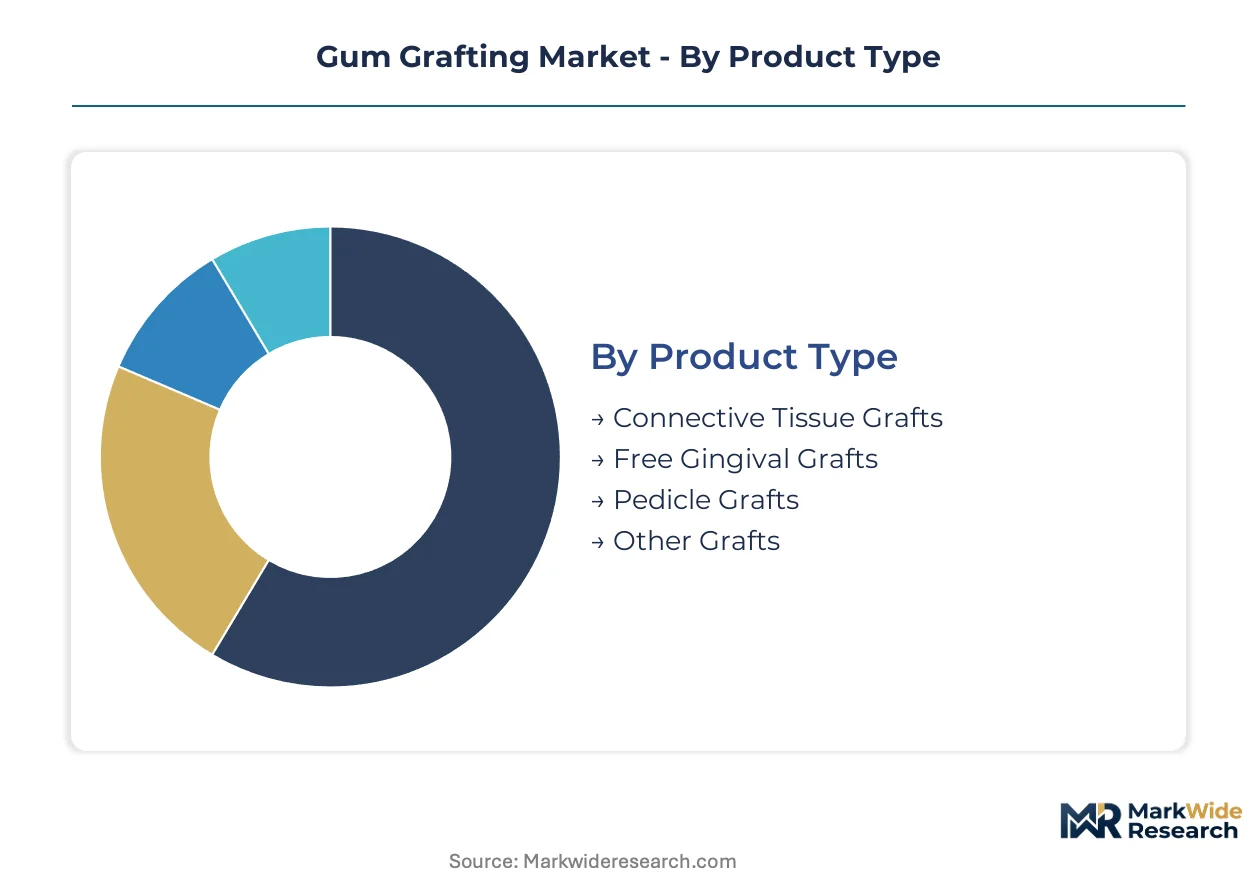
Gum grafting markets fragment across surgical technique, clinical setting, and therapeutic indication, with each axis carrying distinct reimbursement codes and regulatory classification burdens. Manufacturers configure product portfolios around these divisions to align with periodontist workflows and hospital purchasing committee requirements.
Product Type:
FDA's 21 CFR Part 1271 and EMA MDR create divergent approval pathways for autogenous versus processed allogeneic materials, shaping which graft categories manufacturers prioritize for multi-territory launches.
- Connective Tissue Grafts:Harvested from the palatal mucosa as subepithelial connective tissue with thickness specifications of 1.0 to 1.5 millimeters, these grafts achieve predictable root coverage through stable revascularization. Demand concentrates among US periodontal specialists in private practice settings where Medicare Advantage dental benefit expansion drives patient volume for recession repair.
- Free Gingival Grafts:Full-thickness epithelialized tissue harvested from the palate or edentulous ridges, these grafts excel in keratinized tissue augmentation for implant sites. Kaiser Permanente dental clinics in California and Pacific Northwest group practices specify these for pre-prosthetic ridge preparation where attached gingiva width determines long-term implant survival.
- Pedicle Grafts:Laterally or coronally advanced flap techniques preserving vascular supply through base attachment. Common in European periodontal training programs.
- Other Grafts:Includes acellular dermal matrices and amniotic-derived scaffolds regulated as human cells and tissue-based products.
Connective tissue grafts handle the majority of throughput; biologic substitutes in the Other Grafts category are gaining share fastest amid donor-site morbidity concerns.
End User:
Cost tier stratification separates high-complexity cases channeled to specialists from routine soft-tissue management retained in general practice.
- Periodontists:Board-certified specialists with three-year residency training performing multi-site recession repair and ridge augmentation for implant therapy. Texas and Florida DSOs are consolidating referral networks toward these practitioners.
- General Dentists:Primary care clinicians managing single-tooth recession with simplified tunneling techniques or referring complex cases. Their grafting volume is compressing as case complexity escalates.
- Oral Surgeons:Hospital-based practitioners handling grafting in conjunction with orthognathic surgery or trauma reconstruction. Concentrated in academic medical centers.
- Denturologists:Prosthetic specialists in Canadian and European markets performing pre-denture ridge augmentation.
Periodontists command the premium case tier; oral surgeons are expanding fastest on trauma and oncology reconstruction volume.
Therapy Area:
Application urgency separates elective esthetic procedures from disease-driven interventions with stronger reimbursement justification.
- Periodontal Disease:Root coverage and attachment loss repair in patients with cumulative tissue destruction from chronic periodontitis. Dominates procedure volume in US markets where aging demographics present with advanced recession.
- Implant Therapy:Pre- and peri-implant soft-tissue augmentation enabling prosthetic restoration in deficient ridge sites. Fastest-expanding indication as referral patterns channel patients toward integrated implant-to-graft workflows.
- Esthetic Enhancement:Elective gingival contouring and recession repair for cosmetic indication. Concentrated in affluent urban markets with limited insurance coverage.
- Oral Cancer:Reconstructive grafting following tumor resection or radiation therapy. Hospital-based with distinct coding and multidisciplinary care pathways.
Periodontal disease drives baseline throughput; implant therapy is climbing the fastest on pre-prosthetic augmentation demand.
Technology:
Supply concentration in Swiss and German processing facilities shapes which biologic technologies achieve commercial scale versus remaining niche.
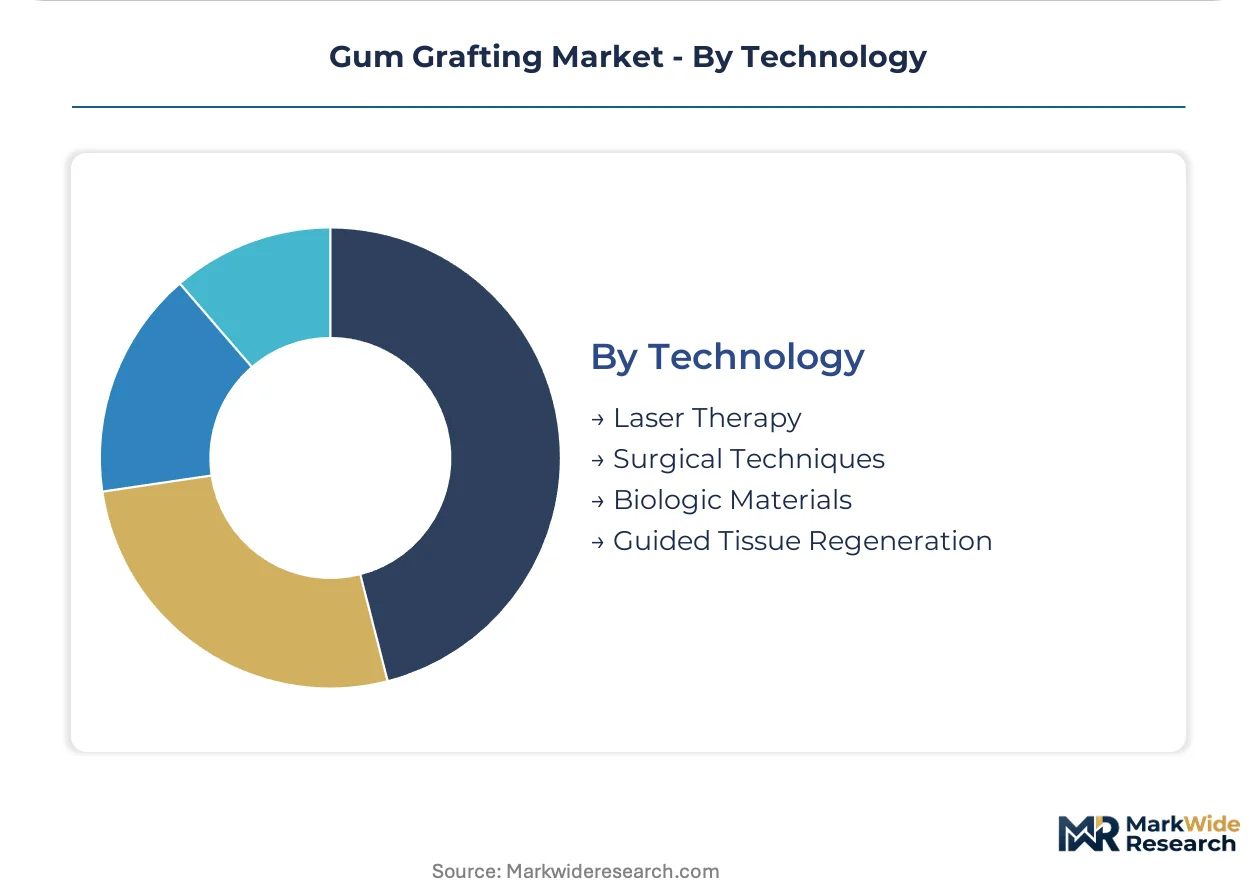
- Biologic Materials:Processed xenogeneic collagen matrices from porcine and bovine sources eliminating palatal donor sites. Geistlich Pharma AG and Swiss processing clusters dominate manufacturing.
- Surgical Techniques:Conventional flap design and suturing methods comprising the procedural standard. Taught in all accredited periodontal programs.
- Guided Tissue Regeneration:Barrier membranes combined with grafting for periodontal regeneration. Applied in intrabony defect repair.
- Laser Therapy:Soft-tissue lasers for incision and hemostasis in specialized periodontal practices with capital equipment investment capacity.
Surgical techniques handle the majority of procedures; biologic materials are expanding most quickly as matrix processing scales and regulatory pathways clarify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain logistics infrastructure underwrites European distribution of processed collagen matrices, while direct air freight corridors from Swiss manufacturing clusters serve Middle Eastern markets.
United States
Medicare Advantage dental benefit expansion drives procedure volume among patients over 65 with cumulative attachment loss. The FDA's 21 CFR Part 1271 framework governs human cells and tissue-based products, clarifying commercialization pathways for amniotic-derived graft substitutes. Texas and Florida DSO networks concentrate procurement authority across 50-plus location platforms in Dallas-Fort Worth and Miami metropolitan markets.
Germany
Periodontal residency programs in Berlin and Hamburg sustain specialist workforce pipelines for advanced grafting workflows. The EMA's Medical Device Regulation tightens clinical evidence requirements for xenogeneic materials under updated Annex I safety standards. Swiss-German processing clusters in Baden-Württemberg anchor porcine-derived collagen matrix manufacturing for EU distribution.
Brazil
Private dental insurance expansion in São Paulo and Rio de Janeiro metropolitan markets creates white space for biologic graft substitutes. ANVISA's streamlined biologic product registration accelerates market entry timelines for processed matrix formulations. Specialist periodontal practices in São Paulo's Pinheiros district adopt piezoelectric surgical units for flapless harvesting techniques.
Switzerland
Swissmedic oversight of medical device quality standards shapes manufacturing protocols for xenogeneic collagen exports. Zurich and Basel processing facilities concentrate production of porcine-derived scaffolds serving global distributor networks. The country's precision manufacturing heritage supports ISO 13485-certified biologic material processing at commercial scale.
Japan
PMDA regulatory pathways for regenerative medical products influence development timelines for novel graft formulations. Tokyo and Osaka periodontal specialists integrate cone-beam imaging with soft-tissue augmentation workflows for implant therapy. METI industrial policy supports domestic manufacturing capacity for dental biomaterials.
Gum Grafting Market Competitive Environment
Concentration sits with integrated dental conglomerates possessing captive implant-to-graft portfolios. The vendor base stratifies across three tiers: multinational platform players with broad channel access, specialized biologic material processors with Swiss-German manufacturing heritage, and regional distributors serving single-market specialists. Strategic moves center on formulary contracting with DSO networks and direct-to-specialist distribution platform development.
Within the integrated platform tier, Straumann Holding AG and Dentsply Sirona exemplify archetypes spanning implant systems through soft-tissue solutions. Geistlich Pharma AG occupies a position among specialized biologic processors with xenogeneic collagen expertise. These three anchors represent distinct competitive vectors: full-workflow integration, broad channel penetration, and biologic material specialization.
| Leading Market Players |
|---|
| Straumann Holding AG |
| Dentsply Sirona |
| Zimmer Biomet Holdings, Inc. |
| Geistlich Pharma AG |
| BioHorizons IPH, Inc. |
| Nobel Biocare |
| botiss biomaterials GmbH |
| Den-Mat Holdings, LLC |
| Keystone Dental Inc. |
| Others |
Value Chain & Pricing Dynamics
Long-term formulary contracts with DSO networks lock in both supply access and price visibility for collagen matrix manufacturers, binding Swiss-German processors to multi-year procurement agreements with Texas and Florida dental platforms while insulating them from spot-market volatility in xenogeneic scaffold sourcing.
Pricing Analysis
Volume-discount tiering separates premium biologic matrices from standard collagen substitutes and economy-grade allografts, with pricing differentiation anchored in FDA 21 CFR Part 1271 certification status and ISO 13485 quality tier. Cost compression in the economy tier is intensifying as Brazilian and Mexican distributors enter with ANVISA-registered alternatives. General dentists exhibit highest price sensitivity due to limited reimbursement for soft-tissue procedures, while periodontists in private equity-backed DSOs accept premium positioning for integrated implant-to-graft workflows.
Supply Chain Analysis
Inbound logistics costs from Swiss manufacturing clusters to US East Coast ports hinge on container availability through Rotterdam cold-chain corridors, with seasonal congestion amplifying lead time variability for temperature-sensitive collagen shipments. Production gravity centers on Switzerland, Germany, and the United States, with raw material sourcing drawing from porcine tissue processing facilities in Baden-Württemberg and bovine-derived inputs from domestic US abattoirs. Single-source vulnerability concentrates in Swiss-German xenogeneic matrix processing, exposing distributors to regulatory restriction risk under evolving EMA MDR Annex I requirements. Distribution runs through direct-to-specialist platforms and traditional dental dealer networks serving periodontal practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gum grafting market functions as a service-attach opportunity where case-planning support and digital surgical planning subscriptions expand faster than hardware revenues from collagen matrices and piezoelectric units.
For Market Incumbents: Secure formulary lock-in with Sun Belt DSO networks before regional procurement consolidation completes, while investing in backward integration into porcine tissue processing to mitigate single-source exposure from Swiss-German suppliers. Anchor defensive positioning against emerging amniotic-derived graft substitutes by accelerating FDA 510(k) pathways for next-generation collagen formulations. For New Entrants and Emerging Players: Anchor in São Paulo and Rio de Janeiro metropolitan markets where ANVISA's streamlined biologic registration creates white space for processed matrix formulations ahead of incumbent footprint expansion. Target periodontist specialists in secondary Brazilian cities with direct distribution platforms bypassing traditional dealer markups, leveraging piezoelectric surgical unit bundling to differentiate from commodity collagen suppliers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among biologic material processors with captive tissue supply agreements and ISO 13485-certified manufacturing infrastructure, positioning them for sustained cash flow quality across the mid-term projection horizon. Monitor FDA classification determinations for amniotic-derived products as the critical inflection signal for portfolio rebalancing toward xenogeneic or allogeneic graft substitutes.| Strategic Initiative | Industry Significance |
|---|---|
| Formulary Contracting with DSO Networks | Texas and Florida platforms consolidate procurement authority across 50-plus location networks, locking in volume commitments. |
| Backward Integration into Tissue Processing | Swiss-German manufacturers secure captive porcine-derived scaffold supply against single-source vulnerability in Baden-Württemberg facilities. |
| Direct-to-Specialist Distribution Platform | Bypassing traditional dental dealer networks captures margin and enables case-planning support for complex ridge augmentation workflows. |
| FDA 21 CFR Part 1271 Compliance Investment | Accelerated quality management system implementation shortens 18-to-24-month certification timelines for novel matrix formulations. |
| Piezoelectric Surgical Unit Bundling | Technology convergence with collagen matrices reduces operative time and differentiates premium positioning in specialized periodontal practices. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA MDR submission databases, hospital procurement records, and GPO contract disclosures, triangulating bottom-up procedure volume estimates with top-down manufacturer revenue analysis across the projection horizon. Primary interviews engaged periodontists, dental school faculty, DSO procurement directors, and biologic material regulatory affairs specialists. Secondary validation drew from CMS Medicare Advantage dental benefit data, American Academy of Periodontology workforce reports, and Swissmedic medical device registration databases.
Segmentation dimensions modeled include surgical technique category, clinical setting tier, therapeutic indication urgency, and technology type, with value outputs derived from pricing stratification across premium biologic matrices, standard collagen substitutes, and economy allografts. CAGRs were computed from procedure volume trajectories and ASP evolution across the analysis window. Forecast inputs incorporated aging demographic projections, Medicare Advantage dental benefit expansion curves, and periodontist workforce pipeline data from accredited residency programs.
Underlying assumptions cover stable FDA 21 CFR Part 1271 classification frameworks and sustained private dental insurance coverage expansion, with deviation risk concentrated in EMA MDR Annex I evidence requirement tightening and single-source supply disruptions from Swiss-German processing facilities. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
United States Implantable Medical Devices Market
Medical Devices
Direct Energy Medical Devices Market
Medical Devices
Digital Reading Micropipettes Market
Medical Devices
Global Limb Prosthetics Market
Medical Devices
Tourniquet Systems Market
Medical Devices
Mexican Intraocular Lens Market
Medical Devices
Next Generation Optical Biometry Devices Market
Medical Devices
Global Micro Guide Catheters Market
Medical Devices
3D Printed Brain Model Market
Medical Devices
Neurovascular Stent Market
Medical Devices
Hemorrhage Control System Market
Medical Devices
Elastomeric Infusion Pump Market
Medical Devices
Double-Lumen Biliary Catheters Market
Medical Devices
MIS Sacroiliac Joint Fusion Market
Medical Devices
Medical Face Shield Market
Medical Devices
Prefillable Inhalers Market