
 Pelvic Muscle Probes Market | 2026-2036
Pelvic Muscle Probes Market Size, Share, and Industry Trends Forecast 2026-2036
Pelvic Muscle Probes Market Analysis
Postpartum rehabilitation clinics is bifurcating from traditional urology practices as the primary demand engine for pelvic muscle probes. Everyway Medical leverages its European distribution network to sustain dominance in reimbursed clinical settings. Laborie anchors North American hospital contracts through its diagnostic-probe integration platforms. Shenzhen XFT Electronics competes aggressively on manufacturing scale for wireless probe variants across Asian markets.
Pelvic muscle probes are electrophysiological sensors designed for intracavitary or surface placement, typically incorporating conductive electrodes with impedance ranges of 1–10 kΩ for reliable electromyography signal capture, used to assess and retrain neuromuscular control of the pelvic floor. Non-invasive probes command the widest installed base due to patient compliance advantages, while wireless probes represent the fastest-growing product type as Bluetooth-enabled home-monitoring protocols mature. In-clinic delivery mode retains the deepest margin pools because of bundled reimbursement codes, though telehealth compatibility is becoming a mandatory procurement criterion for health system tenders.
The FDA 510(k) clearance framework and the EU Medical Device Regulation (MDR) impose divergent clinical-evidence requirements that fragment product launch sequencing across jurisdictions. Health Canada's Medical Devices Directorate maintains alignment with FDA predicate-device logic, simplifying cross-border dossier preparation for manufacturers already holding US clearance. Stakeholders must decide whether to prioritize MDR-compliant design architectures or preserve legacy CE-marked platforms as notified-body capacity constraints persist.
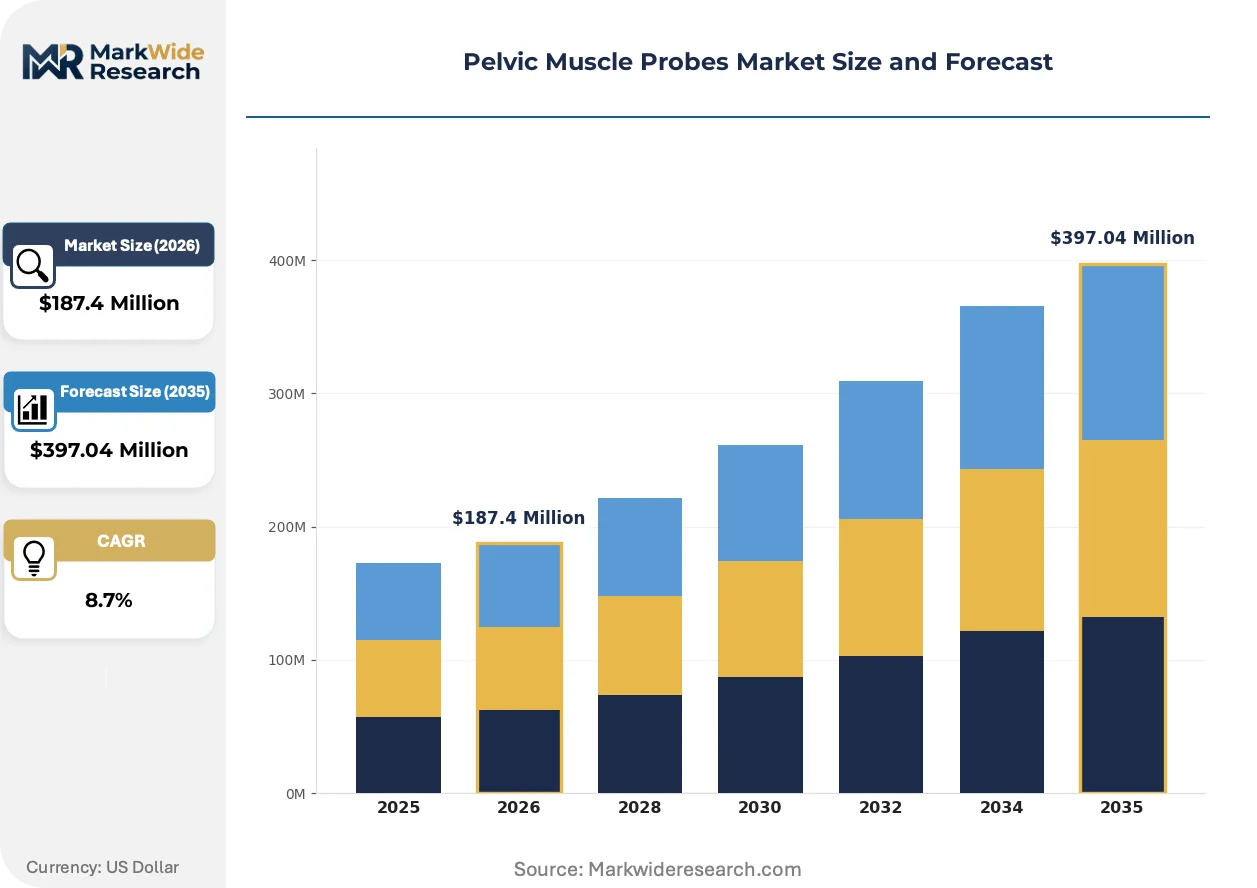
Market Dynamics
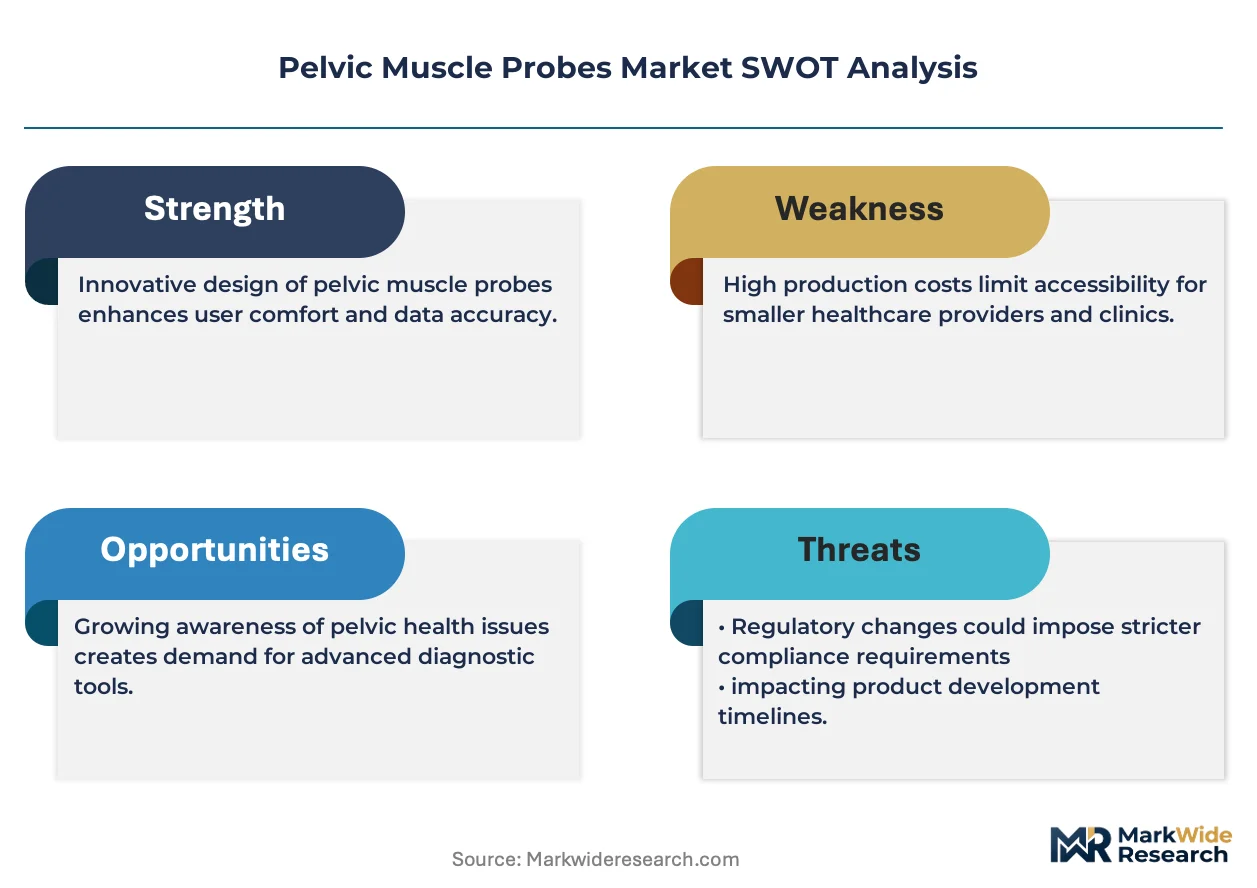
Postpartum rehabilitation clinics are capturing procurement authority from traditional urology practices as pelvic floor therapy achieves standard-of-care status across reimbursed healthcare systems.
Growth Catalysts
- Statutory Health Insurance Reimbursement:Germany's statutory health insurance funds cover pelvic floor rehabilitation, creating predictable procurement volumes and clinical adoption incentives.
- Telehealth-Compatible Hardware:Bluetooth-enabled probes with home-monitoring protocols are expanding addressable patient populations beyond clinic walls.
- Postpartum Segment Expansion:Maternity care pathways in France and the Netherlands now integrate pelvic floor assessment as routine discharge protocol.
Market Restraints
- Notified Body Capacity Constraints:EU MDR transition bottlenecks delay CE mark renewals, freezing product launch sequencing for legacy platforms.
- Silver Price Volatility:Conductive electrode manufacturing depends on silver flake supply, exposing margins to precious metals commodity swings.
- Predicate Device Pathway Narrowing:FDA 510(k) clearance increasingly demands novel clinical evidence, extending development timelines for biofeedback variants.
Strategic Opportunities
- Home-Based Monitoring Protocols:Wireless probe adoption creates recurring revenue streams through subscription-based software analytics.
- Japan's Aging Demographics:METI's preventive care initiatives for urinary incontinence in elderly populations open reimbursement pathways for sensor-based therapy.
- Convergence with Digital Therapeutics:Integration of EMG biofeedback with app-guided exercise programs positions hardware vendors within software-enabled care bundles.
Industry Challenges
- Biocompatibility Testing Backlogs:ISO 10993 cytotoxicity and sensitization studies face laboratory capacity shortages, compressing product certification windows.
- Legacy System Integration:Hospital diagnostic platforms require proprietary data formats, forcing probe manufacturers to maintain multiple firmware branches.
- Clinical Specialist Training Gaps:Pelvic floor physiotherapy certification programs lag device innovation, limiting effective utilization of multi-channel EMG systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pelvic Muscle Probes Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Invasive Probes, Non-Invasive Probes, Wireless Probes, Disposable Probes Application: Rehabilitation, Diagnostics, Pain Management, Research Delivery Mode: Telehealth, In-Clinic, Home Care, Educational Programs End User: Healthcare Providers, Research Institutions, Fitness Centers, Patients |
| Companies Covered | Everyway Medical, TensCare, Verity Medical, Bexen Medical, RehabMedic, Shenzhen XFT Electronics, Thought Technology, UROMED, Laborie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pelvic Muscle Probes Market Emerging Trajectories
Wireless connectivity protocols and algorithm-driven biofeedback are compressing the traditional divide between clinical-grade diagnostics and consumer-accessible rehabilitation tools.
Capacitive sensing arrays is supplanting traditional conductive rubber electrodes in premium probe designs. Postpartum rehabilitation clinics in Scandinavia are adopting these variants for improved signal stability during active contraction protocols. The shift is compressing price premiums between hospital-grade and home-use product tiers.
EU MDR's enhanced clinical-evidence requirements are forcing manufacturers to maintain parallel technical documentation for CE-marked and FDA-cleared variants. The regulatory divergence adds 12-18 months to synchronized launch timelines. Smaller notified bodies in Eastern Europe are losing accreditation, concentrating dossier review capacity with TÜV SÜD and BSI.
Subscription-based software licensing is unbundling hardware margins from recurring analytics revenue. Health system tenders in Germany and Austria now weight total-cost-of-ownership calculations over upfront device pricing. The purchasing model shift favors vendors with cloud-native architecture over legacy standalone systems.
Pelvic Muscle Probes Market Segmentation
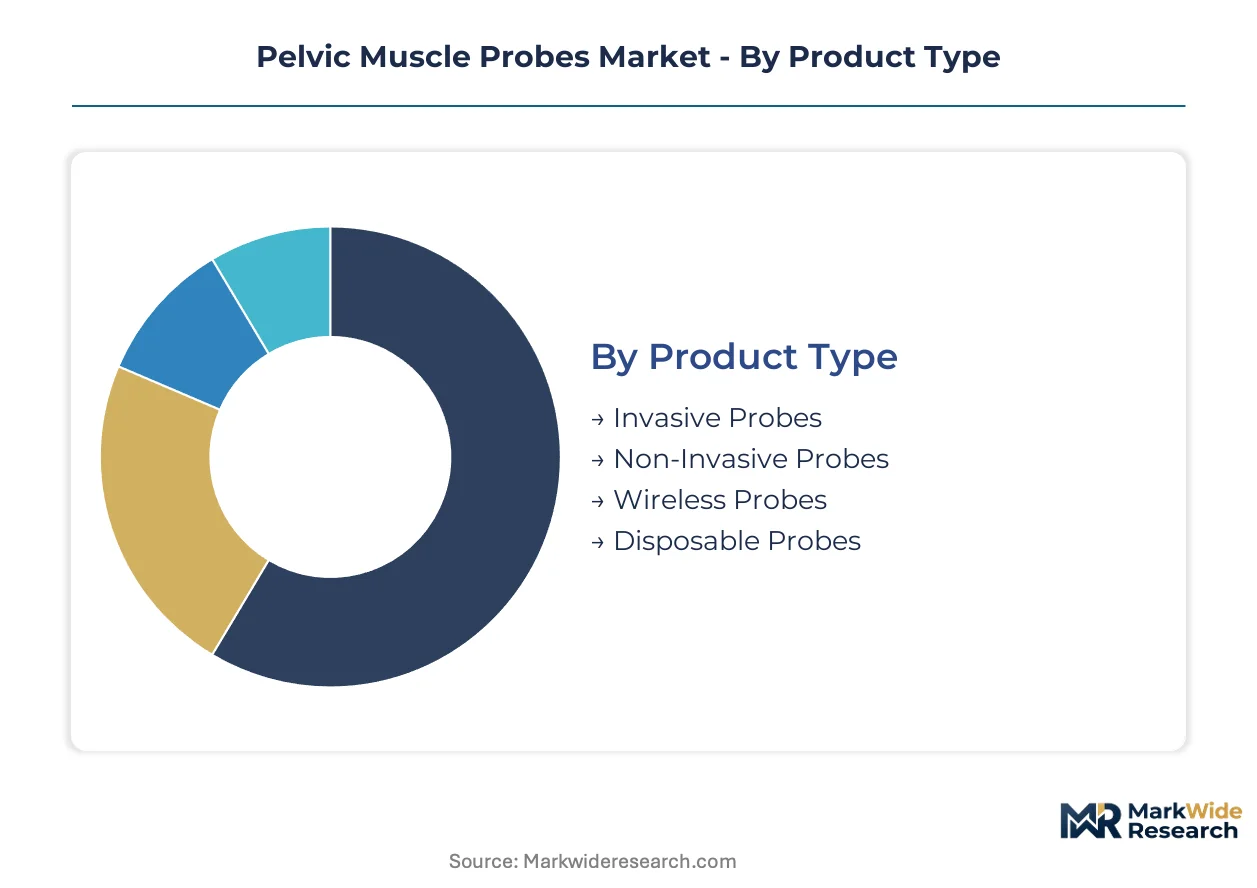
Pelvic muscle probe manufacturers must align product architectures with divergent reimbursement pathways and patient compliance requirements across clinical and home settings. Segment boundaries blur as wireless protocols and disposable designs compress traditional category distinctions.
Product Type:
Wireless variants face the strongest substitution pressure from smartphone-integrated consumer biofeedback devices, forcing manufacturers to differentiate through clinical-grade signal fidelity.
- Invasive Probes:Intracavitary sensors with conductive polymer electrodes deliver direct neuromuscular signal capture for pelvic floor EMG assessment. Postpartum rehabilitation clinics in Germany specify these for reimbursed therapeutic protocols where signal precision determines outcome metrics.
- Wireless Probes:Bluetooth-enabled devices transmit EMG data to tablet or smartphone interfaces, eliminating tethered connections that limit patient mobility during exercise protocols. Home care delivery modes in the Netherlands and France are standardizing procurement specifications around these variants as telehealth reimbursement expands.
- Non-Invasive Probes:Surface electrode arrays enable pelvic floor assessment without intracavitary placement, improving patient acceptance in conservative clinical populations.
- Disposable Probes:Single-use polymer constructions eliminate cross-contamination protocols in high-throughput rehabilitation settings.
Non-invasive probes retain volume leadership across installed base metrics; wireless probes hold the steepest expansion curve as home-monitoring protocols mature.
Application:
Cost tier differentiation separates hospital-grade diagnostic systems from consumer-accessible rehabilitation tools, with reimbursement codes determining viable price points.
- Rehabilitation:Biofeedback-guided exercise protocols using real-time EMG visualization retrain neuromuscular control after pelvic surgery or childbirth. Statutory health insurance funds in Germany and Austria bundle probe hardware into per-session reimbursement rates, creating predictable procurement volumes for clinic networks.
- Diagnostics:Multi-channel EMG systems with pressure transducer integration quantify pelvic floor dysfunction severity for surgical planning or therapy selection. Urology practices in France maintain dedicated diagnostic suites where probe specifications align with hospital information system integration requirements.
- Pain Management:Surface electrode configurations deliver electrical stimulation protocols for chronic pelvic pain syndromes.
- Research:Laboratory-grade probes with raw signal output support clinical trial endpoints and algorithm development.
Rehabilitation captures the dominant revenue share; diagnostics maintains the highest per-unit pricing power.
Delivery Mode:
Customer type fragmentation splits procurement authority between health system purchasing departments and direct-to-consumer channels with divergent specification requirements.
- In-Clinic:Provider-supervised sessions with integrated diagnostic platforms generate the deepest margin pools through bundled reimbursement codes. German rehabilitation clinics negotiate multi-year equipment leases that include probe replacement schedules and software maintenance.
- Telehealth:Remote monitoring protocols combine patient-operated wireless probes with cloud-based analytics platforms accessible to supervising physiotherapists. Health system tenders in Austria now mandate Bluetooth compatibility as a mandatory procurement criterion.
- Home Care:Patient-directed exercise programs without real-time clinical supervision require simplified user interfaces and automated compliance tracking.
- Educational Programs:University physiotherapy departments train students on standardized probe configurations for certification pathways.
In-clinic delivery sustains revenue concentration; telehealth compatibility is gaining share fastest as procurement criteria evolve.
End User:
Supply concentration among notified body-accredited manufacturers limits vendor options for healthcare providers facing MDR compliance deadlines.
- Healthcare Providers:Hospitals, rehabilitation clinics, and private physiotherapy practices purchase probes through group purchasing organizations or direct manufacturer contracts. Postpartum rehabilitation clinics in Scandinavia are adopting capacitive sensing arrays for improved signal stability during active contraction protocols.
- Patients:Direct-to-consumer sales bypass clinical gatekeepers for home-use wireless variants with simplified mobile applications. French maternity care pathways now integrate pelvic floor assessment as routine discharge protocol, expanding the addressable patient population.
- Research Institutions:Academic medical centers and contract research organizations specify laboratory-grade signal fidelity for clinical endpoint validation.
- Fitness Centers:Boutique pelvic health studios in urban Netherlands markets offer probe-assisted training as premium service tiers.
Healthcare providers dominate procurement volume; patient-directed purchasing is climbing the fastest as home-monitoring protocols achieve reimbursement parity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's medical device logistics corridor underwrites Germany's procurement dominance for pelvic muscle probes, with statutory health insurance reimbursement creating predictable demand flows through North Sea distribution networks.
Germany
Postpartum rehabilitation clinics in Bavaria and North Rhine-Westphalia drive institutional procurement volumes through bundled reimbursement codes. The Federal Joint Committee (G-BA) mandates pelvic floor therapy coverage under statutory health insurance, creating clinical adoption incentives. Munich's medical technology cluster concentrates distribution infrastructure for capacitive sensing probe variants.
United States
Hospital purchasing departments in the Northeast and California negotiate multi-year equipment leases with embedded probe replacement schedules. FDA 510(k) clearance pathways for biofeedback devices impose evolving clinical-evidence requirements that reshape product development timelines. Boston's diagnostic-probe integration platforms anchor North American hospital contract structures.
France
Maternity care pathways in Île-de-France and Auvergne-Rhône-Alpes now integrate pelvic floor assessment as routine discharge protocol, expanding addressable patient populations. ANSM maintains medical device vigilance protocols that align with EU MDR transition timelines. Parisian rehabilitation networks standardize procurement specifications around telehealth-compatible hardware.
Netherlands
Home care delivery modes in Randstad and Eindhoven regions standardize procurement around Bluetooth-enabled wireless probes as telehealth reimbursement expands. The Dutch Healthcare Authority (NZa) regulates pelvic physiotherapy tariff structures that influence equipment investment decisions. Amsterdam's health technology procurement consortia aggregate demand for cloud-native probe architectures.
Japan
METI's preventive care initiatives for urinary incontinence in elderly populations open reimbursement pathways for sensor-based therapy in Kanto and Kansai regions. The Pharmaceuticals and Medical Devices Agency (PMDA) streamlines approval processes for home-monitoring medical devices. Tokyo's aging demographics concentrate demand for wireless probe protocols with simplified user interfaces.
Pelvic Muscle Probes Market Vendor Landscape
Listed leaders compete with private specialists across reimbursement access and manufacturing scale dimensions, producing a bifurcated structure where European distributors face Asian fabricators on price-performance vectors. The vendor base clusters around three strategic archetypes: statutory reimbursement specialists leveraging health insurance contracts, wireless hardware scale players driving manufacturing cost curves, and diagnostic platform integrators embedding probes into hospital information systems. Dominant competitive moves include geographic expansion into reimbursed clinical settings and technology licensing for home-monitoring protocol compatibility.
Among European reimbursement specialists, Everyway Medical and Laborie occupy positions that exemplify divergent market access strategies. Shenzhen XFT Electronics represents the scale-driven manufacturing archetype competing across Asian markets for wireless probe variants. TensCare and Verity Medical sit within the mid-tier specialist segment serving postpartum rehabilitation clinics with targeted product configurations.
| Leading Market Players |
|---|
| Everyway Medical |
| TensCare |
| Verity Medical |
| Bexen Medical |
| RehabMedic |
| Shenzhen XFT Electronics |
| Thought Technology |
| UROMED |
| Laborie |
| Others |
Supply Flow & Price Mechanics
Multi-year equipment lease structures with embedded probe replacement schedules lock in supply access and price visibility for German rehabilitation clinics operating under statutory health insurance reimbursement. These contracts bundle hardware depreciation, consumable replenishment, and software maintenance into predictable per-session cost frameworks that insulate buyers from silver price volatility while securing manufacturer revenue streams.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates hospital-grade diagnostic systems with multi-channel EMG integration from basic home-use wireless variants. Certification grade—specifically FDA 510(k) clearance versus legacy CE-marked platforms—drives the widest price spreads, with MDR-compliant architectures commanding substantial premiums over predicate-device pathways. Pricing pressure stems from smartphone-integrated consumer biofeedback devices encroaching on wireless probe territory, compressing mid-tier margins most severely. Postpartum rehabilitation clinics exhibit the lowest price sensitivity due to bundled reimbursement codes, while direct-to-consumer channels face acute elasticity.
Supply Chain Analysis
Strategic stockpiling of silver flake and conductive polymer feedstocks dominates inventory strategy as precious metals commodity swings threaten electrode manufacturing economics. Component fabrication concentrates in Germany, China, and the United States, with Munich's medical technology cluster anchoring European capacitive sensing array production. Raw material dependencies center on silver flake for conductive electrodes, medical-grade silicone for biocompatible housings, and Bluetooth module chipsets for wireless variants. Single-source vulnerability in silver supply from concentrated mining jurisdictions poses structural risk. Distribution runs through hospital group purchasing organizations in reimbursed markets and direct-to-consumer e-commerce in home-monitoring segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as subscription-based software analytics unbundle hardware margins from recurring revenue streams, with cloud-native probe architectures displacing legacy standalone systems through interoperability mandates in health system tenders.
For Market Incumbents: Shield installed base relationships by deepening backward integration into conductive electrode manufacturing to offset silver price volatility, while accelerating MDR-compliant design architectures ahead of notified-body capacity constraints that freeze legacy platform renewals. Prioritize certification investment in ISO 10993 biocompatibility testing to compress product launch windows against laboratory capacity shortages.
For New Entrants and Emerging Players: Differentiate on telehealth-native hardware with automated compliance tracking and simplified user interfaces targeting Japan's aging demographics where METI preventive care initiatives open reimbursement pathways. Home care delivery modes in the Netherlands represent the most penetrable geography, with Dutch Healthcare Authority tariff structures favoring wireless probe procurement. Pursue software companion development partnerships with established physiotherapy platforms rather than competing on signal fidelity.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with cloud-native architecture and subscription-based analytics licensing, positioning them for sustained cash flow quality over hardware-dependent competitors. Acquisition targets should display vertical integration into electrode manufacturing or captive supply agreements with silver processors. Watch for inflection when health system tenders in Germany and Austria mandate total-cost-of-ownership calculations over upfront device pricing, signaling irreversible purchasing model shift.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR-compliant dossier preparation with TÜV SÜD or BSI secures European market access amid notified-body consolidation. |
| Hospital System Partnership | German rehabilitation clinic networks negotiate multi-year equipment leases that bundle probe replacement and software maintenance. |
| Software Companion Development | Integration with app-guided exercise programs positions hardware vendors within digital therapeutics reimbursement bundles. |
| Reimbursement Strategy | Federal Joint Committee mandates in Germany create predictable procurement volumes through statutory health insurance coverage. |
| Backward Integration | In-house production of conductive electrodes mitigates silver price volatility exposure in margin-sensitive wireless variants. |
Methodological Framework
Cross-validation between primary interviews with pelvic floor physiotherapists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers anchors the qualitative findings against secondary validation from FDA 510(k) filings, EU MDR notified-body databases, hospital procurement records, and statutory health insurance reimbursement tariff schedules. Bottom-up demand modeling across product type, application, delivery mode, and end user segments triangulates against top-down market sizing.
Sensitivity analysis around silver price volatility, notified-body capacity constraints, and telehealth reimbursement expansion informs the analytical framework across the projection horizon. Segmentation dimensions modeled include invasive versus non-invasive probe architectures, rehabilitation versus diagnostics applications, in-clinic versus telehealth delivery modes, and healthcare provider versus patient-directed purchasing channels. CAGRs derive from installed base replacement cycles, reimbursement code bundling trends, and wireless protocol adoption curves.
Material uncertainties — regulatory divergence between FDA and EU MDR pathways, precious metals commodity swings, and clinical specialist training gaps limiting multi-channel EMG utilization — sit outside the modeled envelope. Forecasts reflect assumptions about reimbursement stability and notified-body accreditation continuity. Revision becomes warranted when health system tender criteria cross thresholds mandating cloud-native architecture or total-cost-of-ownership weighting over upfront pricing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Anti-Snoring Devices and Snoring Surgery Market
Medical Devices
Controlled-Release Drug Delivery Technology Market
Medical Devices
Global Extracorporeal Shock Wave Lithotripsy Market
Medical Devices
Asthma Spacers Market
Medical Devices
Buccal Drug Delivery System Market
Medical Devices
India Hemostats Market
Medical Devices
PET Injectors Market
Medical Devices
Polymer-Based Prefilled Syringe Market
Medical Devices
Micro-Bypass Systems Market
Medical Devices
MRI Safe Biopsy Needle Market
Medical Devices
United Kingdom Neonatal and Prenatal Devices Market
Medical Devices
Single-Use Assemblies Market
Medical Devices
Airway Clearance Devices System Market
Medical Devices
Cyberknife Market
Medical Devices
Intravascular Temperature Management Systems Market
Medical Devices
IV Poles Market