
 Neurovascular Coiling Assist Devices Market | 2026-2036
Neurovascular Coiling Assist Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Neurovascular Coiling Assist Devices Market Foresight
Japan is fragmenting as domestic manufacturers expand catheter and guidewire capacity to serve Asia-Pacific neurovascular centers. Terumo Corporation leverages its integrated guidewire and catheter portfolio to anchor supply relationships across Japanese and European hospital networks. Medtronic sustains broad technology leadership through electromechanical delivery system development for complex aneurysm geometries. Stryker differentiates via specialized access catheter designs that occupy premium positions in North American neurosurgery centers.
Neurovascular coiling assist devices comprise guidewires, microcatheters, and delivery systems engineered from nitinol, platinum-iridium alloys, and hydrophilic polymer coatings to enable precise navigation through tortuous intracranial vasculature during endovascular aneurysm embolization. These instruments must achieve trackability below 0.014 inch wire diameters while maintaining torque response and radiopacity under fluoroscopic guidance. Assist catheters and coiling devices lead product category revenue as hospitals standardize on integrated procedural kits for intracranial aneurysm interventions. Digital imaging technology is gaining fastest adoption as angiography suites integrate three-dimensional rotational roadmap guidance that reduces contrast exposure and procedure time.
FDA premarket approval pathways and the EU Medical Device Regulation enforce biocompatibility, fatigue resistance, and sterility validation that extend development timelines and elevate capital requirements for neurovascular device entrants. Japan's PMDA maintains comparable stringency through QMS ordinance and designated controlled device classifications that filter market access. Stakeholders must monitor how FDA breakthrough device designations and EU MDR notified body capacity constraints reshape competitive timelines for novel coiling assist platforms.
Market Dynamics
Hospital procurement departments are consolidating vendor relationships around integrated coiling assist platforms, compressing supplier margins while elevating technical validation requirements for intracranial navigation systems.
Growth Catalysts
- EU MDR compliance deadlines:The Medical Device Regulation's enhanced clinical evidence requirements are filtering out marginal competitors and concentrating procurement among validated suppliers with robust quality management systems.
- Japan's aging neurovascular patient base:Demographic pressure is expanding procedure volumes at specialized stroke centers in Tokyo, Osaka, and Nagoya, driving recurring demand for microcatheter and guidewire replacements.
- Nitinol shape-memory alloys:Advances in superelastic wire processing are enabling sub-0.014 inch diameters with improved torque transmission through tortuous middle cerebral artery geometries.
Market Restraints
- Platinum-iridium alloy supply concentration:Radiopaque marker band fabrication depends on a limited supplier base in Germany and Switzerland, exposing device manufacturers to raw material allocation risk.
- FDA premarket approval timelines:Class III neurovascular device pathways require 18-24 month review cycles that delay revenue recognition for novel coiling assist platforms.
- Flow diversion catheter substitution:Next-generation intrasaccular flow disruptors are capturing select wide-neck aneurysm cases that previously required adjunctive coiling assist devices.
Strategic Opportunities
- India's underpenetrated stroke intervention infrastructure:CDSCO regulatory harmonization is enabling multinational device manufacturers to establish distribution partnerships with emerging neurosurgery centers in Mumbai, Delhi, and Bangalore.
- Robotic catheter navigation convergence:Integration of electromechanical drive systems with conventional microcatheter platforms is creating premium procedural automation segments in Japanese and German hospital networks.
- Breakthrough device designation pathway:FDA's expedited review program for novel aneurysm treatment modalities is compressing competitive entry timelines for first-in-class coiling assist technologies.
Industry Challenges
- Interventional neuroradiologist training pipelines:Procedural complexity requires 200+ supervised cases for competency certification, constraining hospital expansion of endovascular aneurysm programs.
- Notified body capacity constraints:EU MDR implementation has created 12-18 month backlogs for CE marking audits, delaying European commercialization timelines for emerging device platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurovascular Coiling Assist Devices Market |
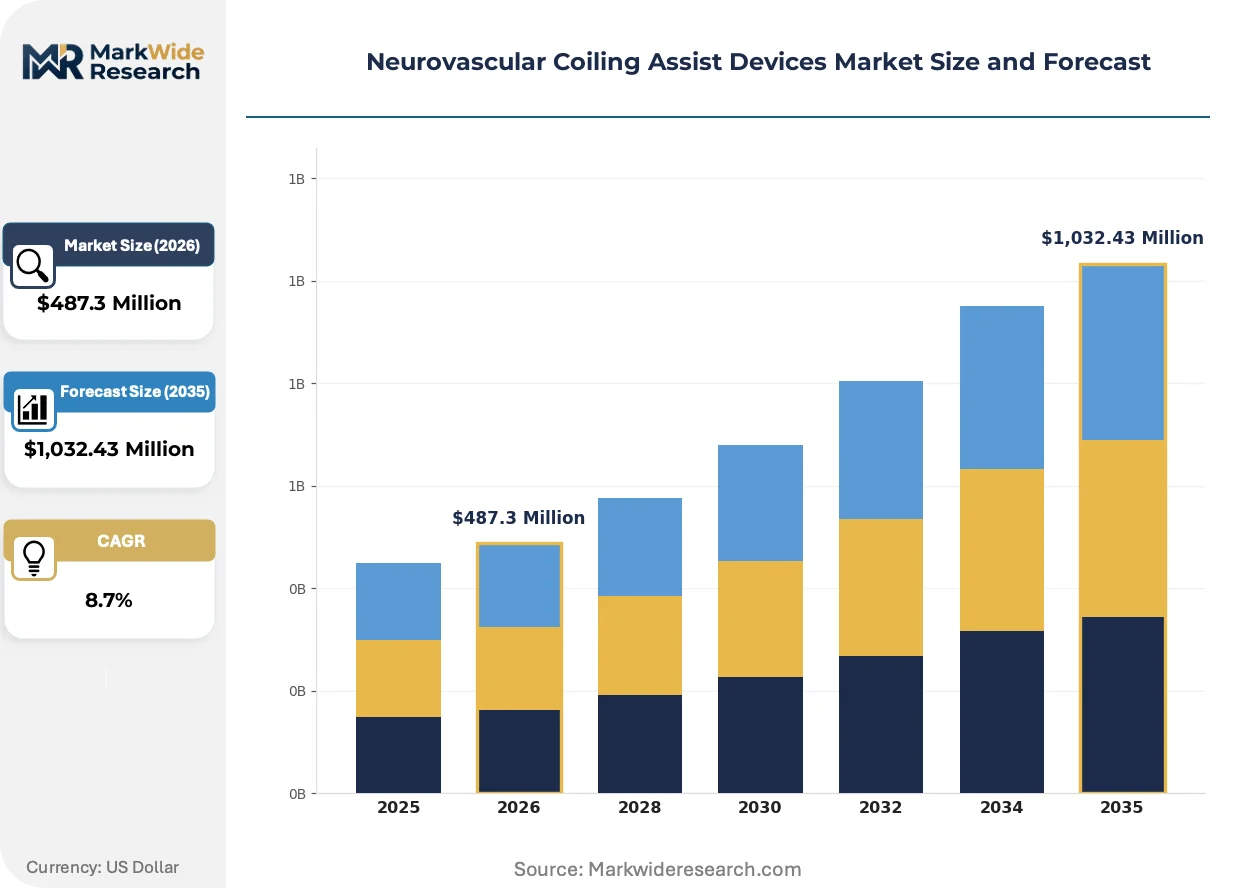
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Assist Catheters, Guidewires, Delivery Systems, Coiling Devices End User: Neurosurgery Centers, Hospitals, Specialty Clinics, Research Institutions Technology: Mechanical Systems, Radiological Devices, Digital Imaging, Electromechanical Systems Application: Intracranial Aneurysms, Vascular Malformations, Ischemic Stroke, Other Neurovascular Conditions |
| Companies Covered | Terumo Corporation, Johnson & Johnson Services, Medtronic, MicroPort Scientific Corporation, Acandis GmbH, Stryker, Balt Extrusion, Merit Medical Systems, Penumbra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurovascular Coiling Assist Devices Market Shifts & Advancements
Digital integration across angiography suites and catheter delivery systems is compressing procedural variability while elevating real-time navigation precision. Three interconnected developments are reshaping competitive positioning.
Three-dimensional rotational angiography with automated vessel segmentation is digitizing pre-procedural planning workflows. Academic medical centers in the United States and Germany are adopting these platforms at 15-20% annual replacement rates for conventional 2D roadmap systems. The technology is digitizing how interventional teams map aneurysm morphology and select optimal working angles before catheter insertion.
Japan's PMDA has tightened designated controlled device classification requirements for intracranial delivery systems, mandating extended biocompatibility and fatigue testing protocols. Domestic manufacturers must now submit 5-year implant equivalent data for nitinol-based instruments. Microcatheter suppliers serving the Japanese market are responding by establishing captive testing laboratories in Yokohama and Osaka to compress regulatory submission cycles.
Hospital value analysis committees are unbundling coiling assist device procurement from bundled payment contracts, shifting purchasing authority from physician preference to supply chain analytics teams. Integrated delivery networks in Texas, California, and Florida are consolidating vendor contracts across 10-15 hospital systems. This behavioral shift is most visible in United States metropolitan markets where stroke center certification density creates procurement leverage.
Neurovascular Coiling Assist Devices Market Segmentation
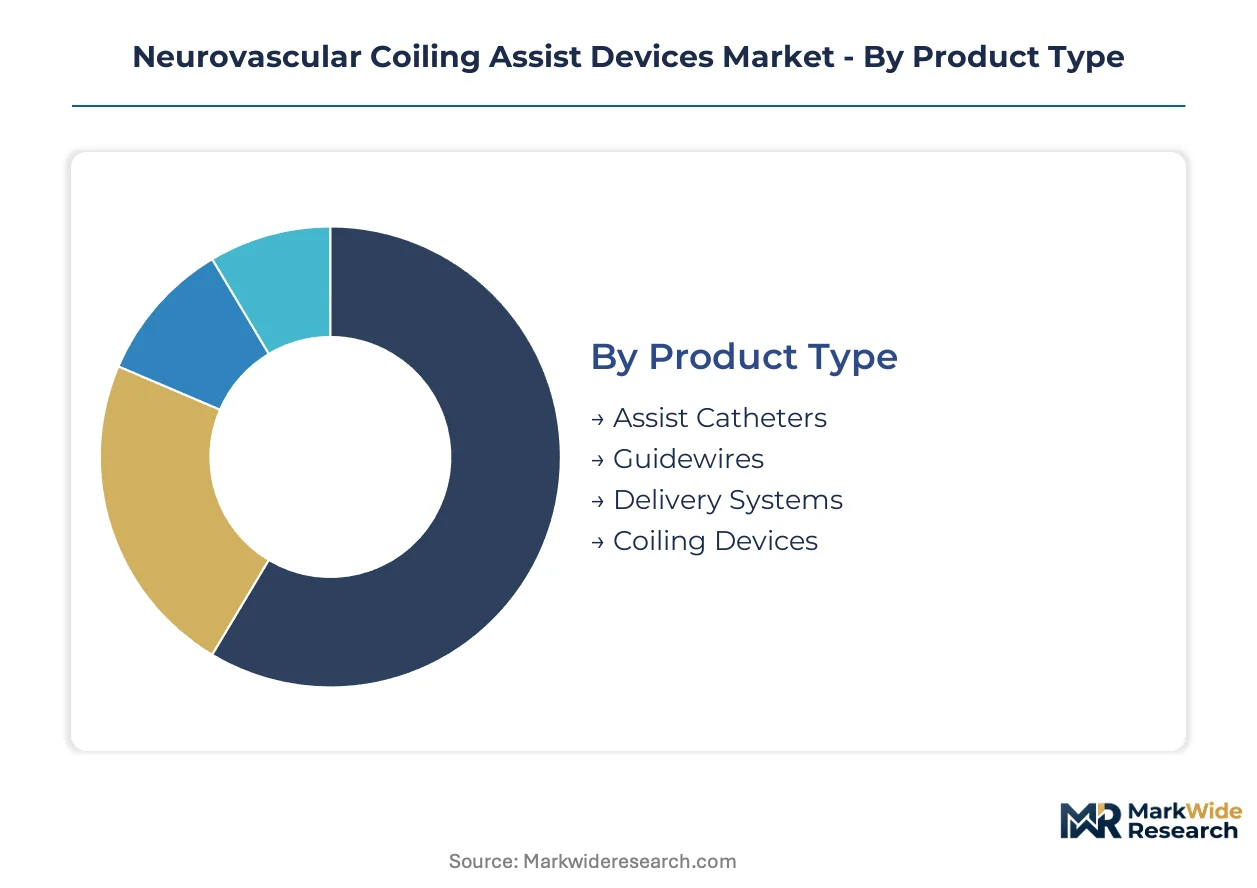
Neurovascular coiling assist devices fragment across four dimensions that each carry distinct after-sales-service intensity. Product type determines replacement cycle frequency and field technical support requirements. End-user concentration shapes inventory management and training service bundling. Technology tier dictates software update cadence and calibration maintenance. Application severity influences emergency response service level agreements.
Product Type:
After-sales-service intensity peaks with electromechanical delivery platforms requiring firmware updates and precision calibration, while consumable guidewires demand minimal technical support beyond lot traceability.
- Assist Catheters:Hydrophilic polymer-coated nitinol shafts engineered for sub-2.0 French distal profiles enable navigation through tortuous middle cerebral artery segments. Demand concentrates at academic stroke centers in the United States and Germany where complex wide-neck aneurysm cases require adjunctive catheter support. Service contracts emphasize sterile field technical assistance and rapid exchange programs.
- Guidewires:Platinum-iridium core wires with superelastic nitinol jackets achieve sub-0.014 inch diameters while maintaining torque response through 180-degree vascular turns. Japanese and European hospital networks standardize on integrated guidewire-catheter kits, driving recurring replacement demand at 15-20% annual refresh rates. Field service intensity remains low relative to capital equipment segments.
- Delivery Systems:Electromechanical drive platforms with automated coil deployment mechanisms.
- Coiling Devices:Detachable platinum coil systems with programmed detachment zones.
By volume, guidewires lead. By growth pace, delivery systems with integrated robotics are expanding most quickly.
End User:
Customer concentration varies sharply across institutional tiers, with neurosurgery centers commanding premium pricing and dedicated clinical specialist support while specialty clinics operate on leaner service models.
- Neurosurgery Centers:Dedicated cerebrovascular units in Tokyo, Osaka, and Nagoya perform 200+ aneurysm interventions annually. These centers demand 24-hour technical field support and on-site inventory consignment. Japanese PMDA-designated controlled device classifications mandate extended biocompatibility documentation that elevates supplier compliance costs.
- Hospitals:General acute care facilities with stroke center certification.
- Specialty Clinics:Outpatient endovascular centers focusing on diagnostic angiography.
- Research Institutions:Academic medical centers conducting investigational device trials under FDA breakthrough designation pathways.
By procedure volume, hospitals dominate. By technology upgrade frequency, research institutions are gaining share fastest.
Technology:
Capital intensity and regulatory validation burden separate mature mechanical platforms from digitally integrated systems requiring ongoing software certification.
- Mechanical Systems:Hand-operated microcatheter and guidewire platforms with torque devices.
- Radiological Devices:Fluoroscopy-compatible instruments with platinum-iridium radiopacity markers.
- Digital Imaging:Three-dimensional rotational angiography with automated vessel segmentation is digitizing pre-procedural planning at 15-20% annual replacement rates in United States and German academic centers. FDA premarket approval requirements for software-as-medical-device functionality extend development timelines.
- Electromechanical Systems:Robotic catheter navigation platforms with haptic feedback and automated coil deployment are commanding premium positions in Japanese hospital networks. PMDA tightened designated controlled device classifications for these systems, mandating 5-year implant-equivalent fatigue data. Integration with conventional microcatheter platforms creates premium procedural automation segments.
By installed base, mechanical systems lead. By investment trajectory, electromechanical systems show the steepest expansion.
Application:
Clinical urgency and reimbursement intensity shape procurement patterns, with ruptured aneurysm interventions demanding immediate device availability and ischemic stroke requiring streamlined workflow integration.
- Intracranial Aneurysms:Saccular and fusiform cerebral artery dilations treated through endovascular coiling or flow diversion. United States metropolitan markets with stroke center certification density drive standardized kit procurement across integrated delivery networks. Hospital value analysis committees are unbundling device procurement from bundled payment contracts, shifting purchasing authority to supply chain analytics teams.
- Vascular Malformations:Arteriovenous malformations and dural arteriovenous fistulas.
- Ischemic Stroke:Large vessel occlusion interventions requiring rapid device deployment.
- Other Neurovascular Conditions:Carotid artery stenosis and intracranial atherosclerotic disease.
By procedure count, intracranial aneurysms lead. By expansion rate, ischemic stroke interventions are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput anchors European distribution corridors for nitinol and platinum-iridium alloy shipments. Japan's Kansai International Airport cold-chain logistics support specialized polymer coating imports for PMDA-regulated manufacturing. The United States' interstate highway network connects Midwest raw material processors to coastal neurosurgery centers.
United States
Integrated delivery networks in Texas, California, and Florida consolidate vendor contracts across 10-15 hospital systems. FDA premarket approval pathways for Class III neurovascular devices enforce 18-24 month review cycles. Academic stroke centers in Boston and Baltimore drive adoption of three-dimensional rotational angiography systems.
Germany
Specialized neurosurgery centers in Munich and Heidelberg perform complex wide-neck aneurysm interventions requiring adjunctive catheter support. EU MDR compliance deadlines filter marginal competitors through enhanced clinical evidence requirements. Platinum-iridium marker band fabrication concentrates in Swiss and German supplier clusters around Stuttgart.
Japan
Demographic pressure expands procedure volumes at specialized stroke centers in Tokyo, Osaka, and Nagoya. PMDA designated controlled device classifications mandate 5-year implant-equivalent fatigue data for nitinol-based instruments. Domestic manufacturers in Yokohama and Osaka establish captive testing laboratories to compress regulatory submission cycles.
India
CDSCO regulatory harmonization enables multinational device manufacturers to establish distribution partnerships with emerging neurosurgery centers in Mumbai, Delhi, and Bangalore. Underpenetrated stroke intervention infrastructure creates expansion corridors. Government medical device parks in Gujarat and Andhra Pradesh attract component assembly operations.
Switzerland
Radiopaque marker band supply chains concentrate in German-Swiss metallurgical processing corridors. Swissmedic maintains alignment with EU MDR quality management standards. Precision alloy fabricators in Basel and Zurich serve nitinol wire specifications for Japanese and European catheter manufacturers.
Neurovascular Coiling Assist Devices Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying nitinol shafts and platinum-iridium markers. The vendor base organizes around three archetypes: diversified medical technology conglomerates with electromechanical delivery platforms, mid-cap catheter specialists with hydrophilic coating expertise, and regional manufacturers with PMDA-integrated quality systems. Consolidation pressures intensify as hospital procurement departments standardize on integrated procedural kits. Strategic partnerships between alloy processors and device assemblers reshape upstream supply security.
Within the diversified technology tier, Terumo Corporation and Medtronic anchor integrated portfolio positions. Stryker occupies a specialized access catheter niche in North American neurosurgery centers. Among European fabricators, Acandis GmbH exemplifies mid-scale precision engineering focused on intracranial navigation systems. These three entities represent distinct competitive vectors: Japanese supply chain integration, electromechanical platform breadth, and premium catheter design specialization respectively.
| Leading Market Players |
|---|
| Terumo Corporation |
| Johnson & Johnson Services |
| Medtronic |
| MicroPort Scientific Corporation |
| Acandis GmbH |
| Stryker |
| Balt Extrusion |
| Merit Medical Systems |
| Penumbra |
| Others |
Supply & Pricing Matrix
Platinum-iridium alloy supply concentration in German-Swiss metallurgical corridors determines both tiered pricing spreads across premium catheter platforms and the geographic shape of raw material sourcing networks. Device manufacturers face asymmetric cost exposure where radiopaque marker band fabrication bottlenecks compress margins on standard-tier instruments while insulating premium integrated kit pricing.
Pricing Analysis
Volume-discount tiering structures separate premium electromechanical delivery platforms from standard mechanical catheter systems and economy guidewire replacements. Price differentiation rests on FDA breakthrough designation status and bundled service contract depth, with academic stroke centers commanding 15-20% procurement discounts through multi-hospital system consolidation. Cost compression in standard-tier segments is intensifying as Indian and Southeast Asian manufacturers expand nitinol processing capacity. Specialty clinics exhibit highest price sensitivity due to lean reimbursement profiles, while neurosurgery centers prioritize technical validation over unit cost.
Supply Chain Analysis
Export-control regimes limiting dual-use nitinol superelastic alloy shipments constrain supply security for Japanese and European catheter fabricators. Manufacturing gravity centers on Germany, Switzerland, and Japan for platinum-iridium marker bands, nitinol wire drawing, and hydrophilic polymer coating application. Raw material dependencies span nickel-titanium shape-memory alloys, radiopaque heavy-element markers, and medical-grade polymer substrates. Single-source vulnerability concentrates in German-Swiss metallurgical processing for implant-grade platinum-iridium. Distribution runs through hospital value analysis committees and integrated delivery network procurement offices rather than physician-directed purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a regulatory entrenchment defensive moat where FDA and PMDA Class III device pathways create 18-24 month competitive lag structures that protect validated incumbents from rapid displacement.
For Market Incumbents: Insulate core revenue streams by deepening captive control over nitinol wire drawing and platinum-iridium marker band supply through backward integration into German-Swiss metallurgical partnerships. Prioritize CE marking pathway investment ahead of EU MDR notified body capacity constraints to compress competitor entry timelines. Electromechanical platform substitution from robotic catheter navigation systems represents the primary technology threat requiring preemptive R&D allocation. For New Entrants and Emerging Players: Establish a beachhead in India's underpenetrated stroke intervention infrastructure where CDSCO regulatory harmonization enables faster commercialization than FDA or PMDA pathways. Target emerging neurosurgery centers in Mumbai, Delhi, and Bangalore with mechanical catheter-guidewire kits before electromechanical platform adoption accelerates. Distribution partnership with government medical device parks in Gujarat offers lowest-cost manufacturing access for price-competitive tier penetration. For Investors and Strategic Acquirers: EU MDR implementation deadlines reshape the acquisition landscape by filtering marginal competitors and concentrating asset value in notified body-validated quality management systems. Five-to-ten year viability favors mid-cap catheter specialists with PMDA-integrated captive testing laboratories and hydrophilic coating intellectual property. Watch FDA breakthrough device designation awards as inflection signals for platform-tier valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Designated Controlled Device Pathway | Five-year fatigue data requirements filter competitors from Japanese stroke center procurement. |
| Hospital System Partnership | Integrated delivery network contracts in Texas and Florida consolidate vendor relationships across 10-15 facilities. |
| Backward Integration into Nitinol Processing | Captive wire drawing capacity insulates margin structures from German-Swiss alloy allocation constraints. |
| Software Companion Development | Three-dimensional rotational angiography integration creates premium positioning in Boston and Baltimore academic centers. |
| Reimbursement Strategy | Stroke center certification density in metropolitan markets determines bundled payment contract eligibility. |
Research Methodology
Desk research of FDA 510(k) and PMA filings, PMDA designated controlled device registrations, and EU MDR notified body certificates preceded structured interviews with interventional neuroradiologists, hospital purchasing committee directors, biomedical engineers at academic stroke centers, and GPO contracts managers. Secondary validation drew from hospital procurement databases, CMS Medicare reimbursement schedules, and nitinol alloy trade flow records. Bottom-up procedure volume estimates triangulated against top-down manufacturer shipment data across the analysis window.
Assumption sets held regulatory pathway timelines and platinum-iridium alloy pricing fixed while varying stroke center certification expansion rates and robotic catheter navigation adoption curves. Segmentation modeling spanned product type, end-user tier, technology generation, and application severity dimensions. CAGRs derived from logistic diffusion curves fitted to electromechanical system penetration patterns and replacement cycle dynamics for consumable guidewire platforms. Procedure volume forecasts incorporated Japan's aging neurovascular patient demographics and India's emerging stroke intervention infrastructure buildout.
Sensitivities concentrate around EU MDR notified body audit backlogs, FDA premarket approval timeline variability, and platinum-iridium supply allocation disruptions. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and raw material supply continuity. Material shifts in FDA breakthrough device designation velocity or German-Swiss metallurgical export controls would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Renovascular Hypertension Treatment Market
Cardiovascular Devices
Point-Of-Care Cholesterol Monitoring Device Market
Cardiovascular Devices
Centrifugal Blood Pumps Market
Cardiovascular Devices
Argentina Cardiovascular Devices Market
Cardiovascular Devices
Peripheral Vascular Stents Market
Cardiovascular Devices
Cerebral Vascular Stent Market
Cardiovascular Devices
Abdominal Stent Graft System Market
Cardiovascular Devices
Vital Sign Simulators Market
Cardiovascular Devices
Cardiac Implantable Electronic Device Market
Cardiovascular Devices
Vascular Prostheses Market
Cardiovascular Devices
Endovascular Stent Market
Cardiovascular Devices
Global Embolotherapy Market
Cardiovascular Devices
Atrial Fibrillation (AF) Ablation Market
Cardiovascular Devices
Fluid Aspiration System Market
Cardiovascular Devices
Drug-Coated Balloon Catheter Market
Cardiovascular Devices
Global Catheters Market