
 Global Intracranial Stents Market | 2026-2036
Global Intracranial Stents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Intracranial Stents Market Foresight
Nitinol is repositioning cobalt-chromium as the dominant superelastic alloy in self-expanding intracranial stents, reducing manufacturing costs while improving vessel conformability. Stryker leverages its neurovascular portfolio depth to sustain leadership in flow-diverter technology. Medtronic anchors its competitive stance through integrated stroke-care ecosystems spanning diagnosis to intervention. MicroPort Scientific Corporation competes aggressively on price while building manufacturing scale in Asia-Pacific.
Intracranial stents are implantable tubular mesh devices, typically laser-cut from nitinol or cobalt-chromium alloys with strut widths of 50-100 micrometers, designed to scaffold weakened cerebral vessels or redirect blood flow away from aneurysm sacs. Their primary purpose is preventing rupture or recurrence in cerebrovascular pathologies where surgical clipping carries excessive morbidity. Flow-diverter stents command the highest margin pools due to their premium positioning in complex giant aneurysm cases, while balloon-expandable platforms remain concentrated in intracranial arterial stenosis applications where precise diameter control matters. Neurosurgery centers generate the dominant volume share among end users, though ambulatory surgical centers are capturing incremental cases as minimally invasive techniques standardize.
FDA premarket approval pathways and EMA Medical Device Regulation conformity assessments shape product development timelines and clinical trial investment thresholds for manufacturers seeking transatlantic market access. Japan's PMDA imposes additional local clinical data requirements that filter out smaller applicants. WHO neurosurgical workforce benchmarks and national stroke-registry mandates in Germany and South Korea are accelerating procedure standardization. Stakeholders must monitor evolving reimbursement decisions for flow-diverter procedures across single-payer systems, as coverage determinations will dictate commercial prioritization between premium and standard device tiers.
Market Dynamics
Nitinol alloy substitution is compressing manufacturing economics while FDA and EMA tighten clinical evidence thresholds for flow-diverter PMA pathways. Neurovascular intervention infrastructure concentrates procedure volumes in tertiary centers with catheterization laboratory capacity.
Growth Catalysts
- WHO neurosurgical workforce benchmarks:National stroke-registry mandates in Germany and South Korea accelerate procedure standardization and device utilization tracking across hospital networks.
- Flow-diverter technology:Self-expanding nitinol platforms with 50-100 micrometer strut widths enable treatment of complex giant aneurysms previously requiring surgical clipping.
- Japan's PMDA framework:Local clinical data requirements filter competitor entry, protecting established manufacturers with in-country trial infrastructure.
Market Restraints
- Nitinol raw material concentration:Superelastic alloy supply chains cluster with specialized metallurgical processors, exposing stent manufacturers to input price volatility and lead-time extension.
- EMA Medical Device Regulation conformity assessments:Extended notified body review timelines delay transatlantic product launches and compress commercialization windows.
- Surgical clipping persistence:Established neurosurgical training pathways and reimbursement familiarity sustain competitive pressure for accessible anterior circulation aneurysms.
Strategic Opportunities
- Ambulatory surgical center channel:Minimally invasive technique standardization enables case migration from inpatient neurosurgery centers to lower-cost outpatient settings.
- Integrated stroke-care ecosystems:Convergence of diagnostic imaging, interventional platforms, and rehabilitation services creates bundled contracting opportunities with hospital systems.
- Asia-Pacific manufacturing scale:Regional production hubs offer cost-positioning advantages for standard stent platforms serving price-sensitive healthcare systems.
Industry Challenges
- Neurointerventionalist training pipelines:Specialized fellowship positions fail to match procedure volume growth, constraining addressable case expansion.
- Premarket approval trial design:FDA requirements for randomized controlled evidence against surgical clipping extend development timelines and escalate clinical investment thresholds.
- Flow-diverter reimbursement uncertainty:Single-payer coverage determinations for premium-tier devices remain inconsistent across national health systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Intracranial Stents Market |
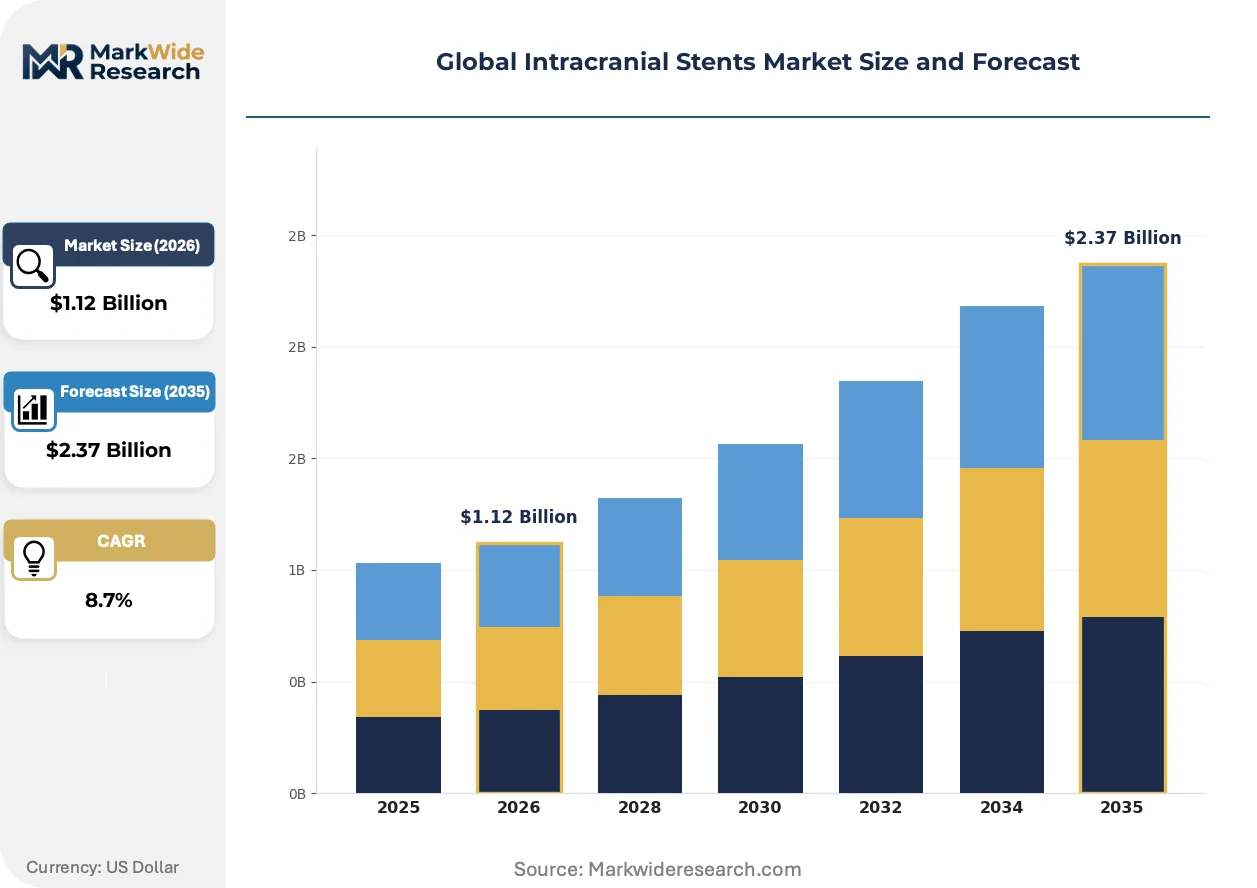
| Market Size in 2026 | $1.12 Billion |
| Market Size in 2035 | $2.37 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Expanding Stents, Balloon-Expandable Stents, Flow-Diverter Stents, Neurovascular Stents Therapy Area: Cerebral Aneurysm, Intracranial Arterial Stenosis, AVM Management, Hemorrhagic Stroke Prevention End User: Neurosurgery Centers, Interventional Radiology Units, Specialized Clinics, Research Institutes Deployment Mode: Hospital-Based Procedures, Ambulatory Surgical Centers, Minimally Invasive Setups, Specialized Neurovascular Labs |
| Companies Covered | Stryker, Medtronic, Johnson & Johnson Services, Terumo Corporation, MicroPort Scientific Corporation, Acandis GmbH, Balt Group, Phenox GmbH, Penumbra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Intracranial Stents Market Shifts & Advancements
Laser-cut nitinol manufacturing and surface modification chemistry are compressing stent profiles while regulatory science evolves around long-term implant surveillance. Device architecture and delivery system engineering dominate competitive differentiation.
Surface biofunctionalization with endothelial progenitor cell capture technology is modularizing flow-diverter design. Neurosurgery centers in the United States and Germany are adopting these platforms for giant and fusiform aneurysm cases previously deemed untreatable. The technology is modularizing competitive positioning around thrombosis risk reduction rather than pure mechanical diversion performance.
EMA Medical Device Regulation post-market clinical follow-up requirements are extending surveillance obligations for neurovascular implants. Manufacturers must maintain registry participation and periodic safety reporting across European Economic Area markets. Flow-diverter stents face the steepest compliance burden due to their permanent implant classification and complex hemodynamic interaction mechanisms.
Hospital procurement committees are consolidating vendor relationships through single-source contracts for neurovascular device portfolios. Academic medical centers in Japan and the United States are negotiating multi-year supply agreements that bundle flow-diverters, access catheters, and embolic coils. This concentration is visible most acutely in Germany, where hospital group purchasing organizations aggregate demand across state-level hospital networks.
Global Intracranial Stents Market Segmentation
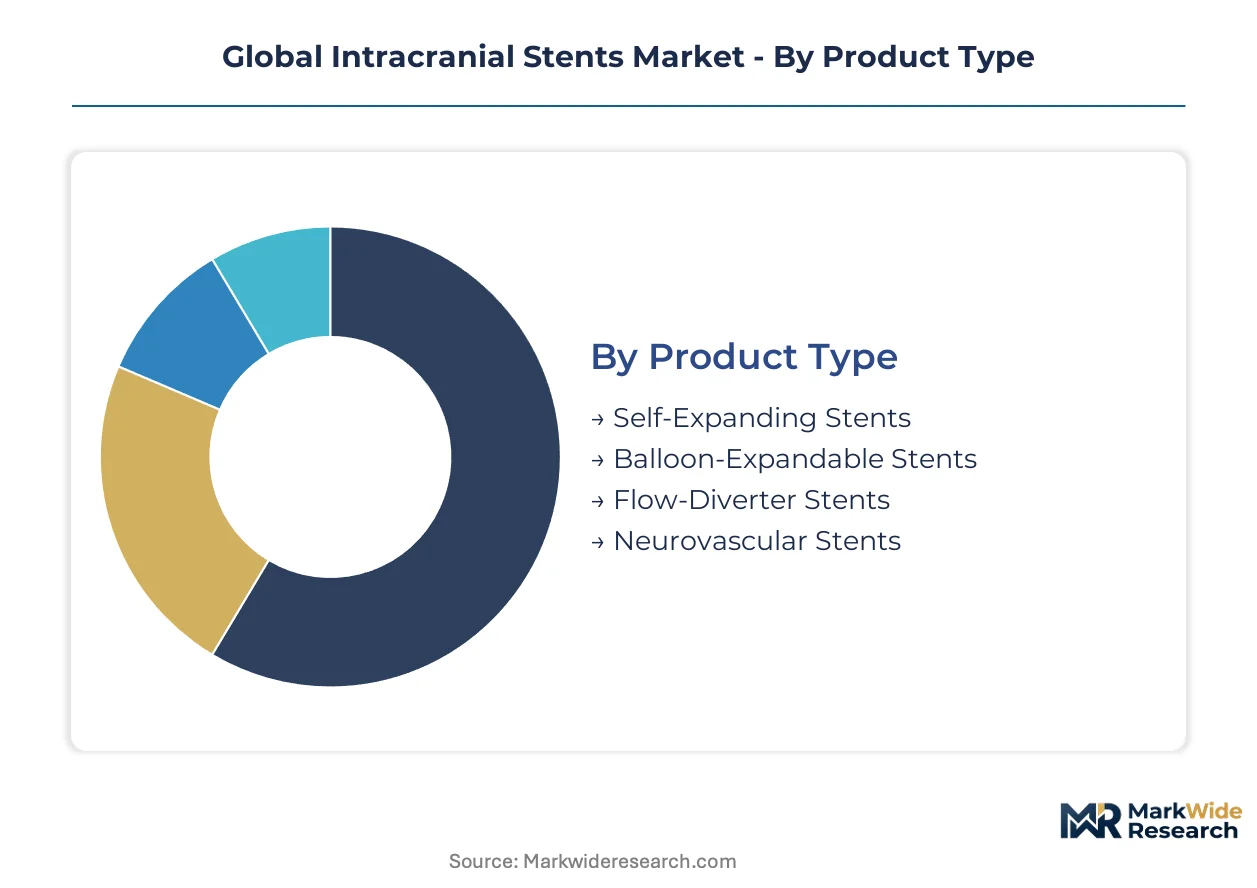
Intracranial stent segmentation reflects divergent regulatory pathways and reimbursement tiers across product architectures. Manufacturers prioritize PMA-track segments with premium pricing power while navigating MDR conformity burdens in Europe.
Product Type:
FDA premarket approval requirements stratify sharply across these architectures, with flow-diverters commanding the most extensive clinical evidence thresholds while self-expanding platforms leverage predicate device pathways.
- Flow-Diverter Stents:Dense nitinol mesh with 30-50 micrometer pore density redirects blood flow away from aneurysm sacs while preserving parent vessel patency. Neurosurgery centers in the United States and Germany concentrate demand for these devices in giant and fusiform aneurysm cases where surgical clipping carries prohibitive morbidity. Reimbursement volatility across single-payer systems constrains volume expansion despite superior clinical outcomes.
- Self-Expanding Stents:Laser-cut nitinol tubes with superelastic recovery properties deploy through microcatheters without balloon assistance. Demand clusters in Japan's tertiary stroke centers where PMDA approval pathways favor established manufacturers with local trial infrastructure. Manufacturing scale advantages in Asia-Pacific are compressing unit economics for standard platforms.
- Balloon-Expandable Stents:Cobalt-chromium or platinum-iridium platforms deliver precise diameter control via inflation deployment. Intracranial arterial stenosis applications dominate utilization.
- Neurovascular Stents:Broad-category devices spanning multiple indications with variable strut configurations and delivery system integrations.
Leading the category by volume: Self-Expanding Stents. Growing fastest: Flow-Diverter Stents.
Therapy Area:
Procedure reimbursement tiers and clinical evidence requirements segment these indications by commercial attractiveness, with hemorrhagic pathways commanding premium device pricing over ischemic applications.
- Cerebral Aneurysm:Saccular and fusiform vessel wall dilations requiring flow diversion or neck bridging. Flow-diverter adoption is displacing surgical clipping in complex posterior circulation cases across United States academic medical centers.
- Hemorrhagic Stroke Prevention:Prophylactic intervention in unruptured aneurysms with elevated rupture risk scores. German stroke-registry mandates are accelerating procedure standardization and device tracking.
- Intracranial Arterial Stenosis:Atherosclerotic narrowing of intracranial vessels treated with balloon-expandable or self-expanding scaffolds. SAMR registration requirements in China filter competitor entry.
- AVM Management:Adjunctive stent deployment for flow control in arteriovenous malformation embolization procedures. Specialized neurovascular labs generate concentrated demand.
Highest reimbursement tier: Hemorrhagic Stroke Prevention. Steepest expansion trajectory: Cerebral Aneurysm intervention.
End User:
Capital equipment requirements and specialist workforce availability determine addressable case volumes across facility types, with catheterization laboratory infrastructure acting as the binding constraint.
- Neurosurgery Centers:Tertiary hospitals with dedicated neurovascular intervention suites and 24-hour stroke response capabilities. United States and Japan concentrate the highest procedural volumes.
- Interventional Radiology Units:Cross-functional departments leveraging shared angiography infrastructure for neurovascular cases. South Korean hospital networks are expanding these capabilities.
- Specialized Clinics:Focused outpatient facilities with streamlined referral pathways. Germany's integrated stroke-care networks are piloting hub-and-spoke models.
- Research Institutes:Academic centers with investigational device exemption pathways and registry participation obligations under EMA post-market surveillance frameworks.
Dominant volume share: Neurosurgery Centers. Fastest channel growth: Interventional Radiology Units.
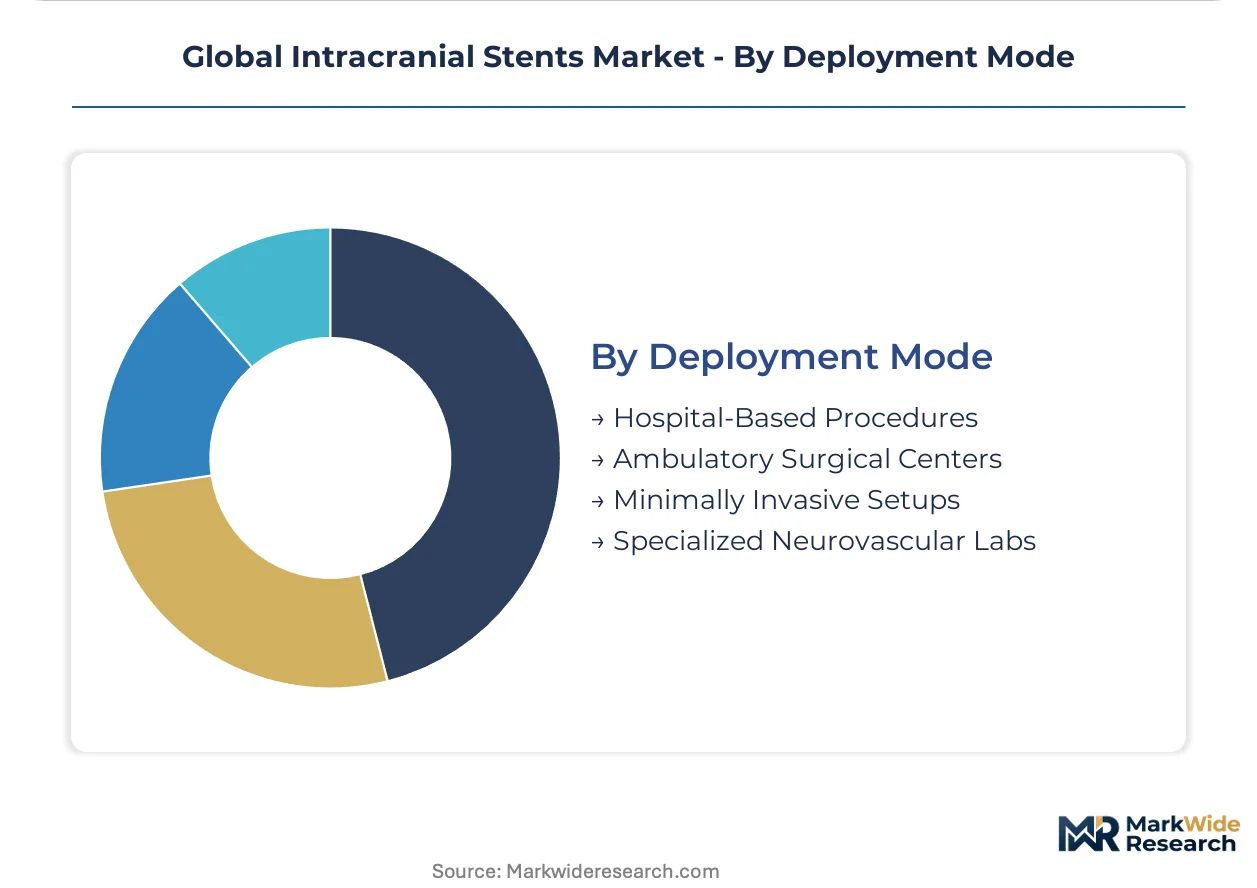
Deployment Mode:
Reimbursement site-of-service differentials and minimally invasive technique maturation are redistributing cases across inpatient and outpatient settings.
- Hospital-Based Procedures:Inpatient admissions with comprehensive ICU backup for complication management. Complex flow-diverter cases remain concentrated here.
- Ambulatory Surgical Centers:Lower-cost outpatient venues capturing standardized aneurysm cases as technique familiarity spreads. United States Medicare site-of-service payment differentials are accelerating migration.
- Minimally Invasive Setups:Hybrid operating rooms with integrated imaging and interventional capabilities. Japanese university hospitals are expanding these investments.
- Specialized Neurovascular Labs:Dedicated facilities with biplane angiography and neurointerventionalist staffing. German state hospital networks aggregate demand through group purchasing organizations.
Highest case complexity: Hospital-Based Procedures. Fastest volume shift: Ambulatory Surgical Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neurovascular device manufacturing clusters concentrate near specialized catheterization laboratory infrastructure and academic medical centers with stroke-response capabilities. Tax incentives for medical technology R&D in Massachusetts and Bavaria accelerate facility investment. Procedure volumes track directly to tertiary hospital density and neurointerventionalist training pipeline capacity.
United States
Academic medical centers in Boston and Baltimore drive flow-diverter adoption for complex posterior circulation aneurysms. FDA premarket approval pathways require randomized controlled evidence against surgical clipping, extending development timelines. The Minneapolis-St. Paul corridor hosts manufacturing operations serving domestic neurosurgery centers.
Germany
National stroke-registry mandates standardize device utilization tracking across hospital networks. EMA Medical Device Regulation conformity assessments extend notified body review timelines for transatlantic launches. The Baden-Württemberg region concentrates catheter manufacturing and neurovascular research institutes.
Japan
PMDA local clinical data requirements filter competitor entry, protecting established manufacturers with in-country trial infrastructure. Tokyo and Osaka university hospitals generate concentrated demand for self-expanding nitinol platforms. Government reimbursement panels review flow-diverter coverage annually, creating pricing uncertainty.
China
SAMR registration requirements for Class III neurovascular devices filter import competition. Shanghai and Beijing tertiary centers drive volume for intracranial arterial stenosis interventions. Domestic manufacturers exploit regional production scale for standard stent platforms serving price-sensitive provincial hospital systems.
South Korea
National stroke-registry mandates accelerate procedure standardization and device tracking across hospital networks. MFDS regulatory frameworks align with international standards while maintaining local quality system inspections. Seoul metropolitan area neurosurgery centers concentrate the highest procedural volumes in the Asia-Pacific region.
Global Intracranial Stents Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with flow-diverter technology concentrating around integrated neurovascular portfolios and standard platforms fragmenting across price-competitive suppliers. The vendor base organizes into three tiers: multinational conglomerates with stroke-care ecosystems, mid-cap device specialists with regional manufacturing scale, and niche players with single-product PMA track records. Consolidation pressure intensifies as hospital procurement committees negotiate multi-year supply agreements bundling stents, access catheters, and embolic coils.
Among diversified medical technology conglomerates, Stryker and Medtronic exemplify the integrated-ecosystem archetype, anchoring competitive positioning through comprehensive neurovascular portfolios spanning diagnosis to intervention. MicroPort Scientific Corporation occupies a position within the Asia-Pacific manufacturing-scale tier, competing on cost-positioning for standard stent platforms.
| Leading Market Players |
|---|
| Stryker |
| Medtronic |
| Johnson & Johnson Services |
| Terumo Corporation |
| MicroPort Scientific Corporation |
| Acandis GmbH |
| Balt Group |
| Phenox GmbH |
| Penumbra |
| Others |
Supply & Pricing Matrix
Nitinol laser-cutting automation is compressing unit production costs while simultaneously concentrating manufacturing scale among Asian-Pacific suppliers with metallurgical processing capabilities. This technology transition redistributes pricing power toward integrated device manufacturers capable of captive alloy sourcing, while tier-two competitors face margin compression from input cost volatility and extended lead times.
Pricing Analysis
Volume-margins split sharply between flow-diverter platforms commanding premium positioning in complex aneurysm cases and standard self-expanding stents facing commodity-like pressure. Pricing stratifies across premium, standard, and economy tiers based on FDA PMA pathway completion and neurosurgery center GPO contract scale. Cost compression in standard nitinol platforms is intensifying because Asia-Pacific manufacturers exploit regional production scale. Academic medical centers with bundled procurement agreements demonstrate lowest price sensitivity, while provincial hospital systems in price-sensitive markets exhibit highest elasticity.
Supply Chain Analysis
Regional distribution centers in Singapore, Rotterdam, and Los Angeles anchor hub-and-spoke patterns serving neurosurgery centers with 24-hour stroke-response requirements. Nitinol raw material supply clusters in the United States, Germany, and Japan with specialized superelastic alloy processors. Device assembly draws from precision laser-cutting equipment in Switzerland and catheter manufacturing in Ireland. Single-source vulnerability concentrates in superelastic titanium-nickel billet supply. Distribution runs through manufacturer-direct sales forces for flow-diverters and medical-device distributors for standard platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement consolidation is forcing weaker manufacturers out as GPOs demand multi-year portfolio contracts spanning stents, access catheters, and embolic coils.
For Market Incumbents: Extend neurovascular portfolio depth through backward integration into nitinol metallurgical processing to secure input cost stability against alloy price volatility. Deepen hospital system partnerships by bundling flow-diverters with stroke-care ecosystem components including diagnostic imaging and rehabilitation services. Anchor positioning through integrated stroke-care platforms that span diagnosis to intervention, raising switching costs for procurement committees evaluating vendor consolidation. For New Entrants and Emerging Players: Capture ambulatory surgical center channel expansion as Medicare site-of-service differentials accelerate case migration from inpatient neurosurgery centers to lower-cost outpatient venues. Target intracranial arterial stenosis applications where balloon-expandable platforms face less stringent PMA evidence thresholds than flow-diverter pathways. Prioritize Asia-Pacific manufacturing scale to serve price-sensitive provincial hospital systems with standard self-expanding stent platforms. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified medical technology conglomerates seeking neurovascular portfolio completeness. Long-term viability hinges on FDA PMA track records and established GPO contract relationships that survive procurement consolidation. Target acquisition archetypes include mid-cap device specialists with regional manufacturing scale and single-product PMA approvals. Watch flow-diverter reimbursement determinations across single-payer systems as the inflection signal distinguishing premium-tier viability from commodity pressure.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | PMA completion for flow-diverters unlocks premium pricing in complex aneurysm cases at academic medical centers. |
| CE Marking Pathway | MDR conformity assessments enable transatlantic market access for nitinol platforms across German hospital networks. |
| Hospital System Partnership | Multi-year GPO contracts bundling stents with access catheters secure volume commitments from procurement committees. |
| Software Companion Development | Imaging integration platforms for procedure planning differentiate device positioning in stroke-care ecosystems. |
| Reimbursement Strategy | Coverage determination navigation for flow-diverter procedures dictates commercial prioritization across single-payer systems. |
Research Methodology
FDA 510(k) and PMA filings, EMA MDR conformity assessment databases, and national stroke-registry publications formed the secondary backbone for procedure volume estimation and regulatory pathway mapping. Primary interviews with neurointerventionalists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers validated device utilization patterns and procurement decision criteria. Bottom-up triangulation across hospital-level procedure data and top-down cross-checks against manufacturer revenue disclosures anchored market size estimates.
Historical trendline analysis of nitinol stent adoption rates and flow-diverter procedure migration informed projection frameworks across the analysis window. Segmentation modeling incorporated product architecture, therapy area indication, end-user facility type, and deployment mode dimensions. CAGRs derived from weighted regression across procedure volume growth, pricing trajectory assumptions, and reimbursement expansion scenarios. Forecast inputs included neurointerventionalist training pipeline capacity and catheterization laboratory infrastructure investment patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to flow-diverter reimbursement determinations and nitinol supply concentration risks. Outputs reflect documented assumptions regarding regulatory pathway timelines and hospital procurement consolidation trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Chronic Venous Occlusions Treatment Market
Cardiovascular Devices
Pulmonary Stents Market
Cardiovascular Devices
Serration Balloon Catheters Market
Cardiovascular Devices
Peripheral Vascular Interventions Market
Cardiovascular Devices
Catheter-Directed Thrombolysis Market
Cardiovascular Devices
Branched Stent Grafts Market
Cardiovascular Devices
Global Advanced Balloon Catheter Market
Cardiovascular Devices
Vital Sign Simulators Market
Cardiovascular Devices
Arterial Cannula Market
Cardiovascular Devices
Intravascular Stents Market
Cardiovascular Devices
Global Vascular Embolization Market
Cardiovascular Devices
Absorbable Heart Stent Market
Cardiovascular Devices
Cardiac Ablation Technologies Market
Cardiovascular Devices
Infusion System Market
Cardiovascular Devices
Global Vascular Injury Treatment Market
Cardiovascular Devices
Global Peripheral Stent Market