
 Tinea Versicolor Treatment Market | 2026-2036
Tinea Versicolor Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Tinea Versicolor Treatment Market Outlook
Asset-light licensing arrangements for generic topical antifungals is narrowing the capital barrier for mid-size manufacturers entering dermatology supply chains. Novartis AG leverages its established dermatology portfolio to sustain shelf presence across European pharmacies. Bayer AG anchors its position through backward integration into active pharmaceutical ingredient production for azole compounds. Pfizer Inc. competes on manufacturing scale, operating high-volume cream and lotion facilities that supply multiple distribution channels.
Tinea versicolor treatment encompasses pharmaceutical and natural interventions targeting Malassezia yeast overgrowth on human skin, with topical azoles and selenium sulfide formulations serving as first-line therapies that disrupt fungal cell membrane ergosterol synthesis. The primary commercial purpose centers on restoring skin pigmentation uniformity while preventing recurrence in warm, humid climates where sebaceous activity peaks. Topical antifungals occupy the largest revenue pool due to established physician prescribing habits and favorable reimbursement for localized infections. Systemic antifungals represent the fastest-expanding segment as oral itraconazole gains traction for extensive or recalcitrant cases unresponsive to surface therapy. Antifungal shampoos retain steady demand in maintenance protocols, though margin pools remain thinner than prescription creams.
FDA oversight of topical antifungal safety profiles shapes new drug application requirements and post-market surveillance obligations for US manufacturers. EMA's MDR framework and REACH chemical compliance standards govern formulation ingredients and labeling across European markets, while India's CDSCO mandates bioequivalence documentation for generic substitutions. Stakeholders must monitor evolving pharmacovigilance reporting thresholds and environmental impact assessments for azole metabolites as regulatory stringency intensifies across major prescribing regions.
Market Dynamics
CDSCO's tightened quality standards for over-the-counter skin therapeutics in India are compressing the supplier base for topical antifungals, forcing mid-size manufacturers toward asset-light licensing models while established players absorb compliance costs through backward integration into active pharmaceutical ingredient production.
Growth Catalysts
- EMA MDR framework:Harmonized device-drug combination regulations across European markets accelerate cross-border registration for topical azole creams, reducing time-to-shelf for compliant manufacturers.
- Selenium sulfide shampoo protocols:Dermatology clinics in Maharashtra and Gujarat are expanding maintenance-phase prescribing as humid climate patterns sustain higher recurrence rates among patient populations.
- Oral itraconazole traction:Systemic therapy gains physician preference for extensive or recalcitrant cases previously managed through prolonged surface applications.
Market Restraints
- Azole API supply concentration:Backward-integrated producers in China control critical intermediate supply chains for ketoconazole and clotrimazole, exposing formulators to input volatility.
- REACH chemical compliance:ECHA's evolving environmental impact assessments for azole metabolites extend reformulation timelines and elevate registration costs for European market entrants.
- Natural remedy substitution:Tea tree oil and zinc pyrithione preparations capture price-sensitive segments in direct-to-consumer channels, eroding prescription cream volumes in mild-case populations.
Strategic Opportunities
- CDSCO bioequivalence pathway:India's streamlined generic substitution documentation creates expedited market entry for topical antifungal licensees targeting pharmacy chains.
- Telemedicine dermatology platforms:Digital diagnostic tools enable remote prescription of combination therapies, opening maintenance-protocol revenue streams beyond traditional clinic visits.
- FDA post-market surveillance data:Safety profile transparency requirements generate real-world evidence that supports label expansion for oral antifungals into pediatric indications.
Industry Challenges
- Pharmacovigilance reporting thresholds:Evolving FDA and EMA adverse event documentation standards strain quality assurance functions at mid-size manufacturers lacking integrated signal detection systems.
- Legacy cream-to-lotion formulation conversion:Equipment reconfiguration for novel vehicle delivery systems demands capital deployment that asset-light licensees cannot access without partner guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tinea Versicolor Treatment Market |
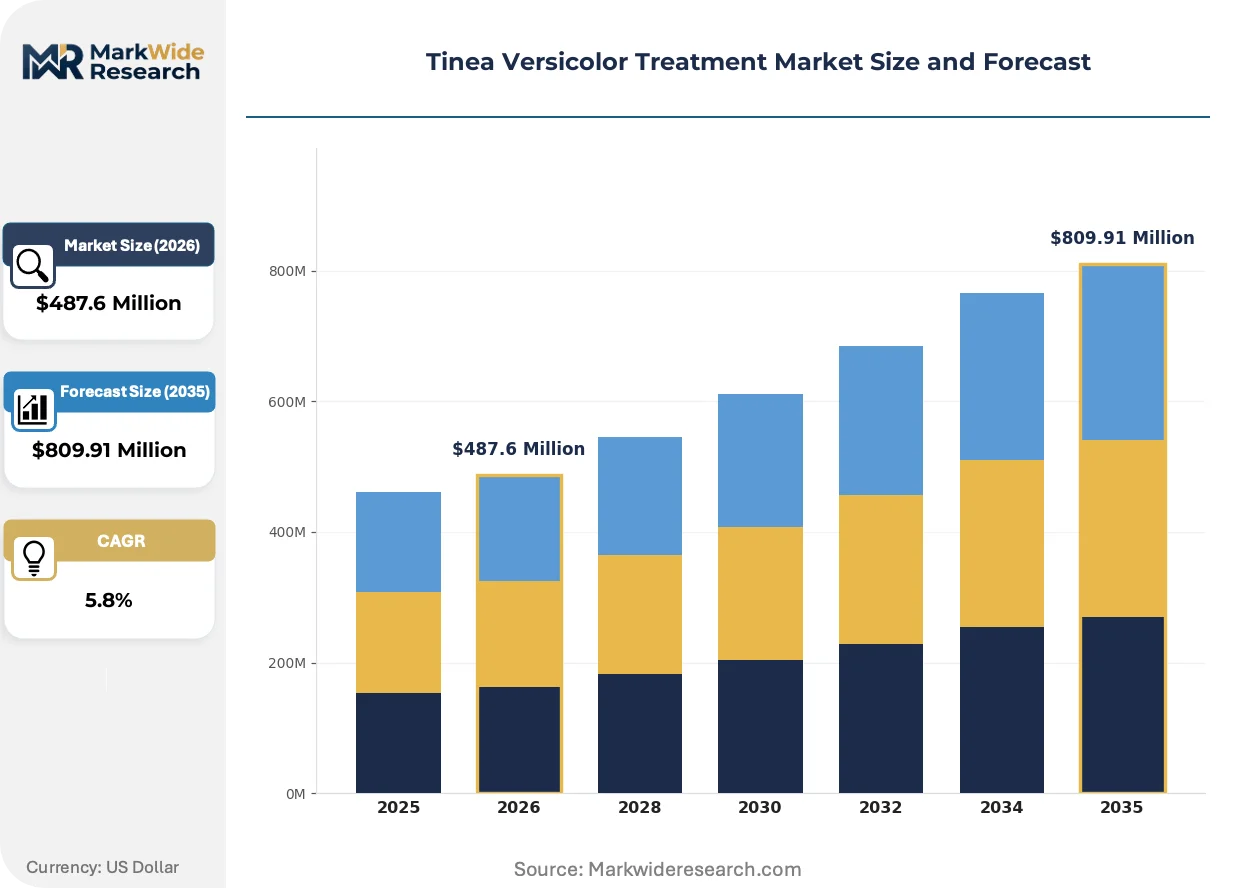
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Antifungals, Systemic Antifungals, Antifungal Shampoos, Herbal Remedies Form: Cream, Lotion, Gel, Tablet Distribution Channel: Pharmacies, Online Stores, Hospitals, Dermatology Clinics End User: Patients, Healthcare Providers, Dermatologists, Research Institutions |
| Companies Covered | Novartis AG, AbbVie Inc., Bayer AG, Astellas Pharma, Pfizer Inc., Johnson & Johnson, Sanofi, Merck & Co., Inc., GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tinea Versicolor Treatment Market Strategic Shifts
Topical antifungal development is pivoting toward combination vehicles that enhance cutaneous penetration while regulatory agencies tighten environmental metabolite tracking, reshaping both formulation science and post-market obligations.
Nano-encapsulated azole delivery systems are collapsing the efficacy gap between prescription creams and systemic therapy by enabling deeper follicular deposition of active compounds. Dermatology clinics in high-humidity coastal regions are piloting these vehicles for recalcitrant cases previously requiring oral itraconazole. The technology is collapsing the addressable market for systemic antifungals in moderate-severity presentations.
REACH chemical compliance standards now mandate environmental fate studies for azole metabolites prior to formulation approval, extending development timelines for new topical entrants. ECHA's expanded substance evaluation criteria force reformulation of established selenium sulfide shampoos to reduce aquatic toxicity profiles. European manufacturers are responding by accelerating biodegradability testing partnerships with contract research organizations.
Direct-to-consumer diagnostic applications are fragmenting the traditional referral pathway for tinea versicolor diagnosis, with patients self-identifying conditions through AI-powered skin analysis tools before pharmacy consultation. Pharmacy chains in urban India are capturing these pre-qualified buyers through private-label topical antifungal displays positioned adjacent to diagnostic kiosks. This channel compression is most visible in Mumbai and Ahmedabad, where humid climate prevalence sustains year-round category demand.
Tinea Versicolor Treatment Market Segmentation
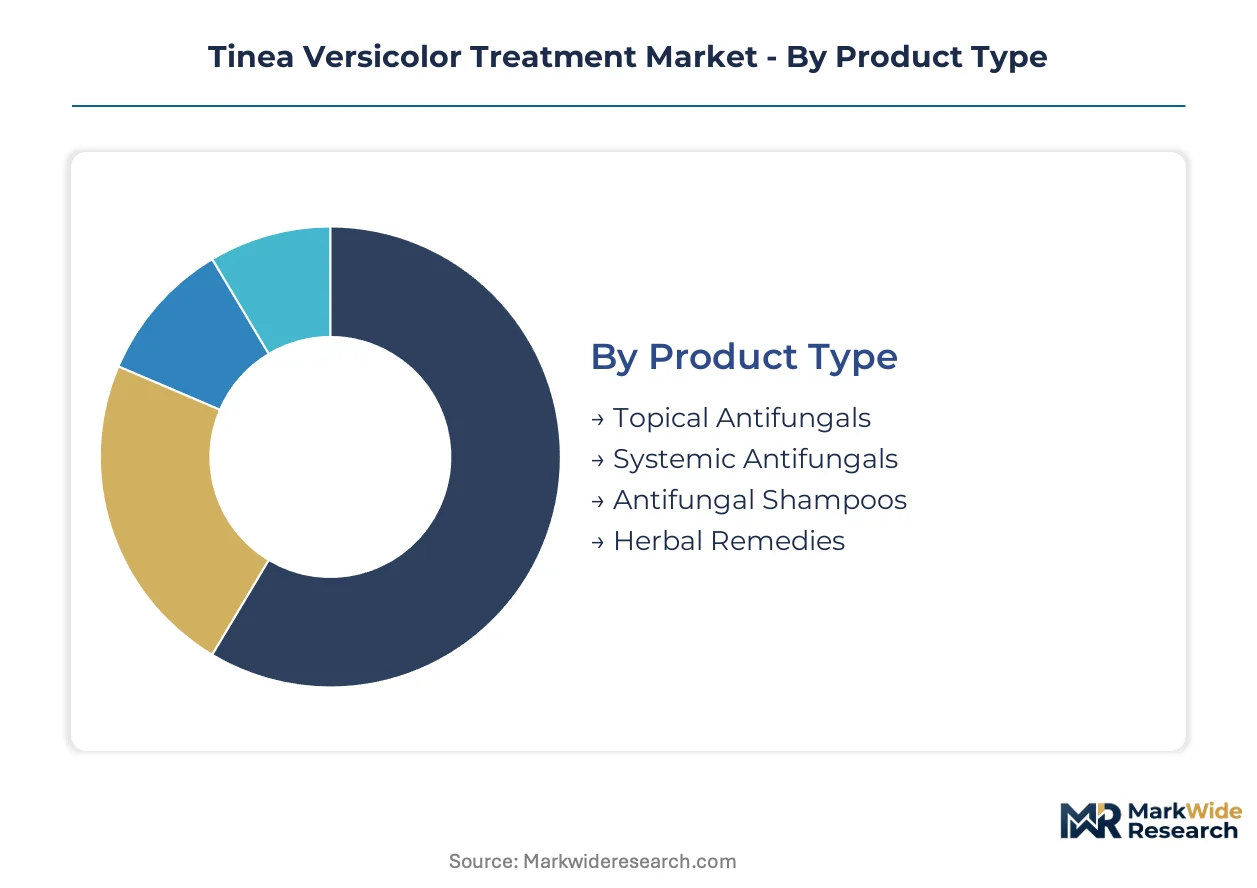
Tinea versicolor treatment markets fragment across therapeutic modality, physical delivery form, and care setting. Each segmentation axis reveals distinct margin structures and regulatory exposure profiles that shape manufacturer positioning.
Product Type:
Use-case spectrum spans surface-directed therapy through systemic intervention, with severity thresholds and recurrence risk determining selection pathways.
- Topical Antifungals:Azole-based creams and lotions targeting Malassezia cell membrane ergosterol synthesis dominate first-line prescribing across Maharashtra and Gujarat dermatology clinics. Established physician habit and favorable localized infection reimbursement sustain volume concentration despite longer treatment courses than systemic alternatives.
- Systemic Antifungals:Oral itraconazole and ketoconazole formulations address extensive or recalcitrant presentations unresponsive to surface therapy. CDSCO's tightened bioequivalence documentation for generic substitutions is compressing the supplier base while expanding addressable cases previously managed through prolonged topical applications.
- Antifungal Shampoos:Selenium sulfide and zinc pyrithione preparations serve maintenance-phase protocols in humid climate regions with elevated recurrence patterns.
- Herbal Remedies:Tea tree oil and neem-based formulations capture price-sensitive direct-to-consumer segments through pharmacy chain private-label positioning.
Established volume favors topical antifungals; emerging adoption favors systemic antifungals.
Form:
Physical delivery vehicles determine cutaneous penetration depth, patient compliance, and manufacturing capital requirements across the value chain.
- Cream:Semi-solid emulsions with occlusive properties enhance active compound retention on hyperkeratotic plaques. Maharashtra pharmacy chains report sustained preference among adult patients with localized trunk presentations.
- Lotion:Lower viscosity vehicles facilitate application across large surface areas and hair-bearing regions. Gujarat dermatology clinics favor lotions for adolescent patients with extensive back and chest involvement where cosmetic acceptability drives adherence.
- Gel:Alcohol-based matrices offer rapid drying and reduced residue, capturing demand among working-age populations in humid coastal urban centers.
- Tablet:Solid oral dosage forms for systemic therapy require bioequivalence documentation under CDSCO and FDA pathways, elevating regulatory barriers for entrants.
Cream formulations retain the deepest physician loyalty; lotions are gaining share fastest among younger patient demographics.
Distribution Channel:
Channel structure reflects the tension between diagnostic authority and convenience access in fungal skin condition management.
- Pharmacies:Brick-and-mortar retail outlets anchor volume through over-the-counter topical sales and prescription fulfillment. Mumbai and Ahmedabad chains are deploying private-label antifungal displays adjacent to AI-powered diagnostic kiosks, compressing the traditional referral pathway.
- Online Stores:Direct-to-consumer platforms capture maintenance-phase reorder traffic and price-sensitive generic substitution demand. E-pharmacy growth is accelerating in Tier-2 Indian cities where dermatologist density remains limited.
- Hospitals:Inpatient and outpatient pharmacy departments manage severe or immunocompromised patient presentations requiring systemic therapy oversight.
- Dermatology Clinics:Specialist-directed settings concentrate premium-brand prescribing and combination therapy protocols, particularly for recurrent cases in high-humidity coastal regions.
Pharmacy volume dominates transaction frequency; dermatology clinics command the steepest expansion trajectory in per-patient revenue.
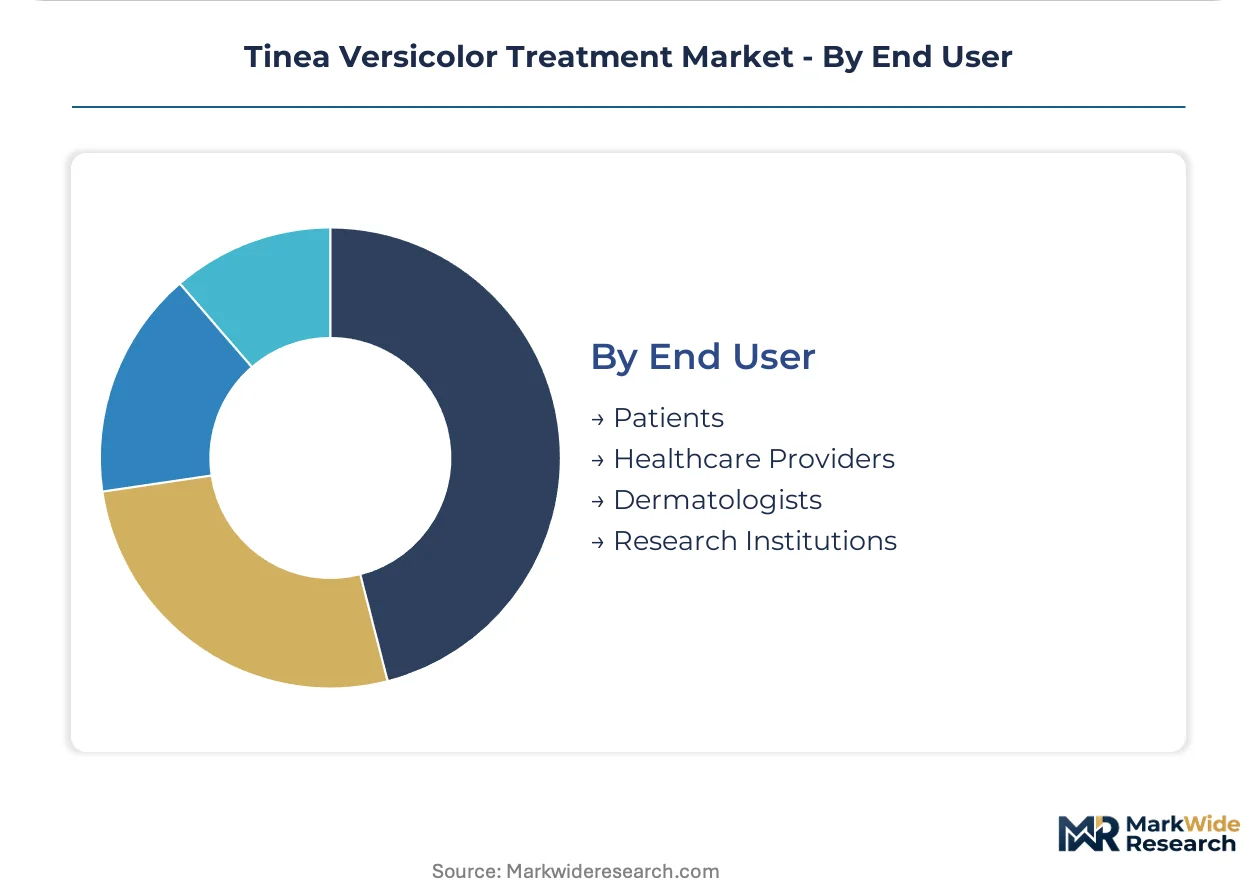
End User:
Stakeholder roles diverge across self-directed care, professional diagnosis, and clinical research functions.
- Patients:Self-identified cases through mobile diagnostic applications are fragmenting traditional care pathways, with direct-to-consumer channels capturing mild-presentation volumes previously routed through physician consultation.
- Healthcare Providers:General practitioners and primary care physicians manage uncomplicated presentations, representing high-volume, lower-margin prescribing relative to specialist channels.
- Dermatologists:Specialist practitioners concentrate recalcitrant case management and drive protocol innovation for combination and maintenance-phase therapies.
- Research Institutions:Academic medical centers conduct nano-encapsulation and novel vehicle penetration studies, generating clinical evidence that supports label expansion and formulation advancement.
Patient-directed adoption is climbing the fastest; dermatologist influence remains concentrated in premium therapeutic decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in topical antifungal APIs concentrate in Asian manufacturing hubs serving formulation facilities across North America and Europe. India maintains a positive trade balance in finished dermatology products while importing specialized azole intermediates from Chinese chemical producers.
United States
FDA post-market surveillance requirements for topical antifungal safety profiles drive quality assurance investments among domestic formulators. The agency's evolving adverse event reporting thresholds strain mid-size manufacturers lacking integrated signal detection infrastructure. Dermatology clinics in Florida and Texas sustain elevated prescription volumes due to humid subtropical climates that sustain Malassezia yeast proliferation.
India
CDSCO tightened quality standards for over-the-counter skin therapeutics are compressing the supplier base for topical antifungals. Maharashtra and Gujarat dermatology clinics are expanding procurement of selenium sulfide maintenance protocols as humid coastal patterns elevate recurrence rates. Mumbai pharmacy chains deploy private-label antifungal displays adjacent to AI-powered diagnostic kiosks, capturing self-identified cases before traditional referral pathways.
Germany
EMA's MDR framework harmonizes device-drug combination regulations, accelerating cross-border registration for topical azole creams across European markets. ECHA's REACH chemical compliance standards mandate environmental fate studies for azole metabolites, extending reformulation timelines for established selenium sulfide shampoos. Bavarian and North Rhine-Westphalian manufacturing clusters absorb these compliance costs through captive testing partnerships with contract research organizations.
China
Backward-integrated producers in Jiangsu and Zhejiang provinces control critical intermediate supply chains for ketoconazole and clotrimazole APIs. NMPA bioequivalence documentation requirements for generic topical substitutions mirror FDA pathways, elevating regulatory barriers for domestic formulators. Yangtze River Delta chemical parks concentrate azole synthesis capacity, exposing global formulators to input volatility during environmental inspection cycles.
Brazil
ANVISA's pharmaceutical quality standards for dermatology products align with ICH guidelines, facilitating import substitution for topical antifungal formulations. São Paulo and Rio de Janeiro pharmacy chains capture direct-to-consumer demand for maintenance-phase therapies in humid coastal populations. Southeast Asian API suppliers increasingly bypass European intermediaries to serve Brazilian formulators directly, reshaping procurement economics.
Tinea Versicolor Treatment Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in API and intermediate supply. The vendor base concentrates among established pharmaceutical conglomerates with dermatology portfolios and mid-size formulators pursuing asset-light licensing arrangements. Three archetypes dominate: backward-integrated API producers, high-volume manufacturing scale operators, and specialty dermatology platform holders. Competitive moves center on bioequivalence documentation acceleration and nano-encapsulation vehicle partnerships with academic medical centers.
Among Swiss-headquartered conglomerates, Novartis AG occupies a position exemplifying specialty dermatology platform strength through established pharmacy shelf presence. Bayer AG represents the backward-integrated archetype with captive azole compound production. Pfizer Inc. anchors the scale-driven tier, operating high-volume cream and lotion facilities supplying multiple distribution channels. These three entities collectively illustrate the strategic segmentation between upstream chemical control, manufacturing throughput, and clinical brand equity.
| Leading Market Players |
|---|
| Novartis AG |
| AbbVie Inc. |
| Bayer AG |
| Astellas Pharma |
| Pfizer Inc. |
| Johnson & Johnson |
| Sanofi |
| Merck & Co., Inc. |
| GlaxoSmithKline plc |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Mumbai maritime corridor's freight cost volatility transmits directly into landed cost spreads for azole-based topical formulations, compressing margins for Indian formulators lacking backward integration while amplifying price differentiation between captive-API producers and pure-play compounders sourcing from Yangtze River Delta chemical parks.
Pricing Analysis
Pharmacy chain procurement teams anchor pricing negotiations for topical antifungals across Maharashtra and Gujarat, where three-tier pricing structure across prescription-grade, pharmacy-brand, and economy generic levels stratifies by CDSCO bioequivalence certification status and volume commitment scale. Pricing pressure stems from direct-to-consumer tea tree oil substitutes capturing mild-case segments, while dermatology clinics show least price sensitivity for nano-encapsulated premium vehicles.
Supply Chain Analysis
Extended payment terms from Jiangsu and Zhejiang API producers now stretch 90-120 days for ketoconazole and clotrimazole intermediates, straining working capital at mid-size Indian formulators. Supply concentrates in Chinese chemical parks for azole synthesis, with Indian manufacturers drawing from these inputs for finished cream and lotion production. Single-source vulnerability around environmental inspection cycles in Yangtze River Delta facilities threatens input continuity. Distribution runs through pharmacy chain central warehouses and direct-to-consumer e-pharmacy platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation science capabilities—specifically nano-encapsulation vehicle development and REACH-compliant metabolite testing—sit in scarce supply relative to demand from manufacturers seeking differentiation in saturated topical antifungal markets.
For Market Incumbents: Pre-empt generic substitution pressure by accelerating captive API production for azole compounds and securing exclusive nano-encapsulation licensing partnerships with academic medical centers in humid climate regions. Defend shelf position through CDSCO bioequivalence documentation acceleration that compresses competitor entry timelines. For New Entrants and Emerging Players: Tier-2 Indian cities beyond Mumbai and Ahmedabad present underpenetrated demand for maintenance-phase selenium sulfide protocols, where dermatologist density remains thin and telemedicine platforms can substitute for physical diagnostic authority. Capture these patients through AI-powered skin analysis tool integration with e-pharmacy fulfillment. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate dermatology portfolios seeking to divest non-core topical franchises, particularly those with established CDSCO registrations but stagnant R&D pipelines. Monitor ECHA substance evaluation announcements for azole metabolites as the inflection signal—tightened environmental standards would force reformulation investments that strategic buyers could underwrite while financial sponsors retreat.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Bioequivalence Acceleration | Expedited generic substitution documentation compresses competitor entry timelines for topical azole licensees. |
| Nano-Encapsulation Partnership | Academic medical center collaborations enable deeper follicular deposition rivaling systemic itraconazole efficacy. |
| Captive Azole API Production | Backward integration into ketoconazole intermediates insulates margin from Yangtze River Delta supply volatility. |
| Telemedicine Platform Integration | Remote diagnostic tools capture maintenance-protocol revenue beyond traditional clinic visit economics. |
| REACH Metabolite Compliance | Biodegradability testing partnerships with contract research organizations secure European market access. |
Study Parameters
Operator-level perspectives from dermatology clinic procurement heads, CDSCO regulatory affairs leads, pharmacy chain category managers, and azole API plant managers anchored the qualitative base. These interviews combined with FDA post-market surveillance databases, ECHA REACH substance evaluation records, CDSCO bioequivalence filing repositories, and Indian customs import data for antifungal intermediates. Bottom-up patient volume modeling and top-down pharmaceutical market sizing triangulated demand estimates.
Scenario-bracketing around regulatory stringency variations and climate-driven recurrence rate assumptions shaped projections across the analysis window. Segmentation dimensions modeled encompassed therapeutic modality, physical delivery form, distribution channel archetype, and regional regulatory cluster. CAGRs derived from patient population growth, prescribing pattern shifts, and price trajectory assumptions for generic versus premium formulations.
Macroeconomic conditions sit as an overlay; deviation in rupee-dollar exchange rates, crude oil derivatives pricing for petrochemical feedstocks, or monsoon pattern severity affecting humid climate disease burden would shift the trajectory. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Muscle Relaxant Drugs Market
Pharmaceuticals
Hepatitis B Treatment Market
Pharmaceuticals
Antiplatelet Market
Pharmaceuticals
Retinal Drugs and Biologics Market
Pharmaceuticals
HIV Antivirals Market
Pharmaceuticals
Oral Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Direct Oral Anticoagulants Market
Pharmaceuticals
Europe Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
Atypical Antipsychotic Market
Pharmaceuticals
North America Meglitinide Market
Pharmaceuticals
Advanced Parenteral Drug Market
Pharmaceuticals
Peptide and Anticoagulant Drugs Market
Pharmaceuticals
Europe Veterinary Pharmaceuticals Market
Pharmaceuticals
Tranquilizer Drugs Market
Pharmaceuticals
Italy Opioids Market
Pharmaceuticals
Enteric Empty Capsules Sales Market