
 Fractional Flow Reserve-Computed Tomography (FFR-CT) Market | 2026-2036
Fractional Flow Reserve-Computed Tomography (FFR-CT) Market Size, Share, and Industry Trends Forecast 2026-2036
Fractional Flow Reserve-Computed Tomography (FFR-CT) Market Insights
Cardiology clinics is rebalancing toward outpatient non-invasive testing, reducing reliance on catheterization laboratories for intermediate coronary lesions. HeartFlow, Inc. leverages proprietary deep-learning algorithms to process CT angiography datasets into hemodynamic simulations. Siemens Healthineers anchors its position through integrated CT scanner and software ecosystems that streamline clinical workflows. GE HealthCare competes by embedding FFR-CT capabilities into broader cardiovascular imaging portfolios.
Fractional Flow Reserve-Computed Tomography applies computational fluid dynamics to coronary CT angiography data, generating patient-specific blood flow simulations without invasive catheter insertion; the technology requires submillimeter spatial resolution CT acquisition and specialized image processing to reconstruct three-dimensional arterial models for fractional flow reserve calculation. Coronary Diagnostics dominates application demand as physicians seek alternatives to invasive physiological assessment for stable chest pain evaluation. Cloud-Based Solutions represent the fastest-growing delivery mode, enabling remote processing of large imaging datasets and reducing on-site computational infrastructure requirements for smaller imaging centers.
FDA premarket authorization pathways shape software-as-medical-device commercialization timelines for FFR-CT algorithms in the United States, while CE marking under EU MDR governs market access across European member states. HIPAA compliance requirements influence cloud deployment architectures and data residency decisions for United States healthcare providers. Stakeholders must monitor evolving reimbursement coding decisions by national health technology assessment bodies to determine site-of-service economics for FFR-CT adoption.
Market Dynamics
Cardiology clinics are rebalancing toward outpatient non-invasive testing, reducing reliance on catheterization laboratories for intermediate coronary lesions. This structural shift compresses procedural volumes in traditional cath labs while expanding computational diagnostic workflows.
Growth Catalysts
- Reimbursement expansion in Germany:National health technology assessment bodies now cover CT-derived fractional flow reserve analysis, accelerating site-of-service economics for outpatient clinics.
- Cloud processing architectures:Remote computational infrastructure eliminates on-site server requirements for smaller imaging centers, democratizing access to hemodynamic simulation capabilities.
- FDA premarket authorization pathways:Streamlined software-as-medical-device review timelines compress commercial deployment schedules for algorithm developers in the United States.
Market Restraints
- Submillimeter CT acquisition requirements:Scanner hardware specifications limit deployment to facilities with premium imaging equipment, excluding budget-constrained community hospitals.
- EU MDR compliance timelines:Extended CE marking review periods under the Medical Device Regulation create market access friction for European commercialization.
- Invasive catheterization substitution threat:Established interventional cardiology workflows and physician training investments sustain preference for traditional fractional flow reserve measurement.
Strategic Opportunities
- Underpenetrated outpatient networks:United States cardiology clinics outside major academic medical centers represent expansion white space for non-invasive coronary assessment adoption.
- AI-enabled diagnostic convergence:Integration of deep-learning algorithms with computational fluid dynamics creates differentiated workflow automation for high-volume screening programs.
- HIPAA-compliant cloud architectures:Data residency solutions tailored to United States healthcare provider requirements unlock enterprise-scale deployment contracts.
Industry Challenges
- Computational fluid dynamics expertise scarcity:Specialized biomedical engineering talent for three-dimensional arterial model reconstruction remains concentrated in academic research institutions.
- Legacy PACS integration complexity:Picture archiving and communication system interoperability requirements extend implementation timelines for hospital network rollouts.
- Physician workflow retraining burden:Established interventional cardiologists require substantial education investment to transition diagnostic decision-making to CT-first protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fractional Flow Reserve-Computed Tomography (FFR-CT) Market |
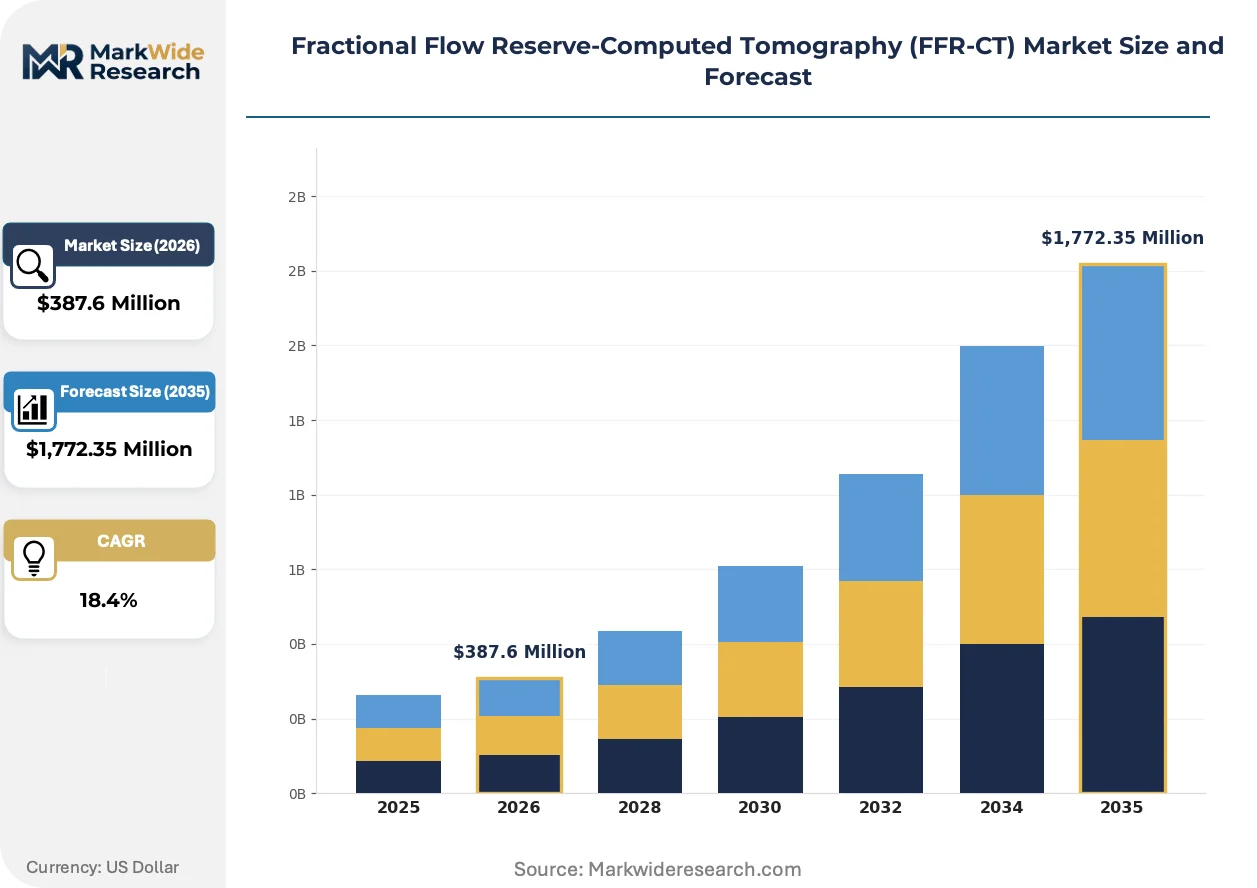
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,772.35 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Coronary Diagnostics, Non-Invasive Risk Assessment, Treatment Planning, Clinical Research End User: Hospitals, Imaging Centers, Research Institutions, Cardiology Clinics Technology: CT Imaging, Image Processing Software, Simulation Tools, Data Analytics Delivery Mode: Cloud-Based Solutions, On-Premise Software, Mobile Applications, Remote Access |
| Companies Covered | HeartFlow, Inc., Siemens Healthineers, GE HealthCare, Koninklijke Philips N.V., CathWorks Ltd., Opsens Inc., ACIST Medical Systems, Medis Medical Imaging Systems BV, Pie Medical Imaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fractional Flow Reserve-Computed Tomography (FFR-CT) Market Trends and Innovations
Computational diagnostic methods are actively displacing invasive physiological assessment across stable chest pain evaluation pathways. Three convergent developments define this transformation.
Cloud-based processing architectures are overtaking on-premise computational infrastructure as the dominant delivery mode for FFR-CT analysis. Regional imaging centers and community cardiology clinics adopt remote processing to avoid capital expenditure on specialized server hardware. This shift compresses market entry barriers for smaller facilities while concentrating computational expertise within centralized data centers.
CE marking under EU MDR governs commercialization timelines for algorithm developers seeking European market access. Extended technical documentation requirements and notified body capacity constraints delay product launches across member states. Software vendors respond by prioritizing United States FDA clearance sequences to generate revenue while awaiting European authorization.
Site-of-service economics now drive procurement decisions for coronary diagnostic workflows. Hospital administrators evaluate total cost-per-diagnostic-pathway rather than per-procedure reimbursement, favoring non-invasive CT-first protocols over catheterization laboratory utilization. This behavioral shift concentrates demand in Germany and the United States, where bundled payment models reward downstream cost avoidance.
Fractional Flow Reserve-Computed Tomography (FFR-CT) Market Segmentation
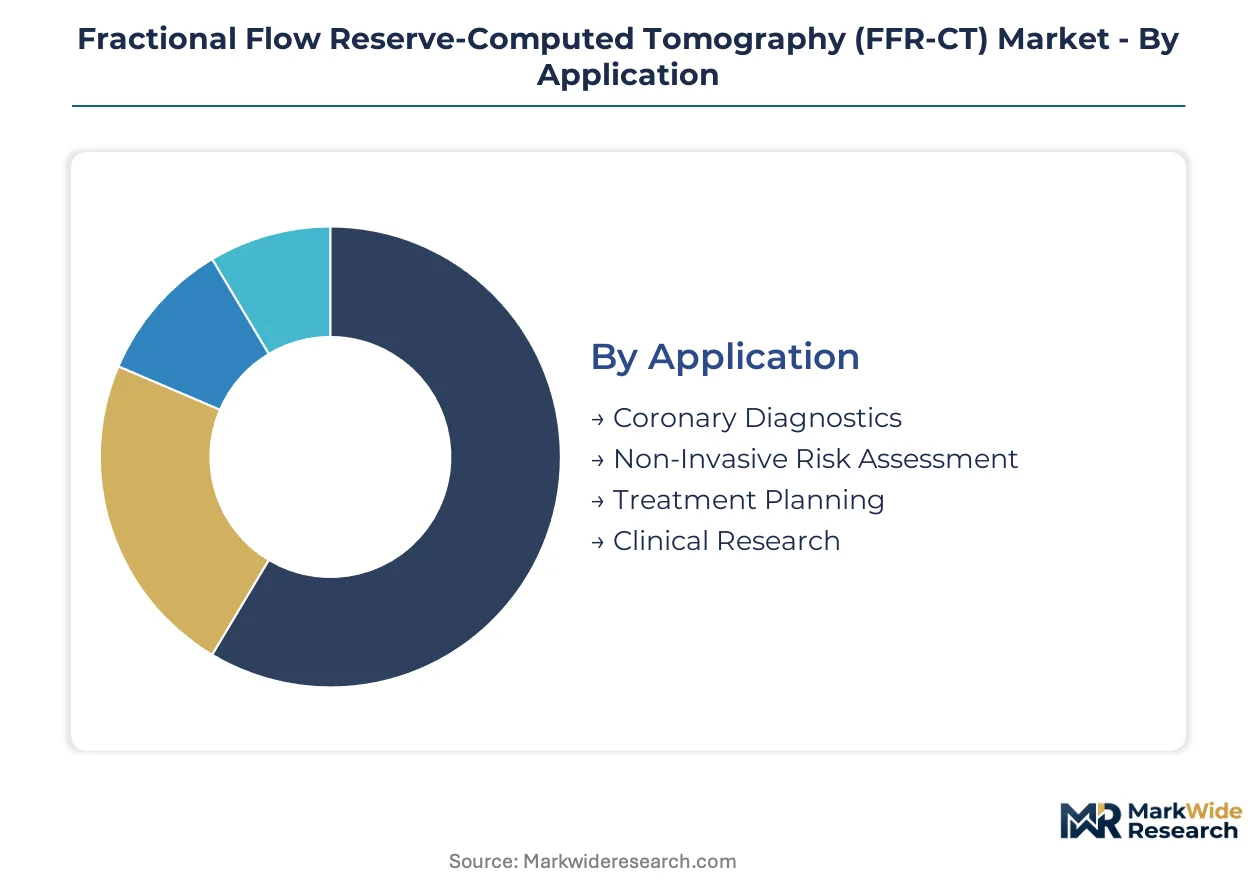
FFR-CT segmentation reveals how regulatory pathways, infrastructure requirements, and clinical workflows fragment commercial opportunity across distinct customer profiles and deployment architectures. Each category carries specific certification burdens that shape vendor go-to-market strategies and capital allocation decisions.
Application:
FDA premarket authorization under software-as-medical-device pathways governs commercialization for diagnostic applications, while CE marking under EU MDR applies to clinical research deployments across European member states.
- Coronary Diagnostics:Dominant revenue concentration where computational fluid dynamics replaces invasive catheterization for stable chest pain evaluation. Demand clusters in German outpatient cardiology clinics following national reimbursement expansion for CT-derived fractional flow reserve analysis.
- Non-Invasive Risk Assessment:Fastest-expanding application segment enabling pre-procedural screening without arterial catheter insertion. United States hospital systems adopt this pathway to reduce cath lab utilization and capture bundled payment savings under value-based care contracts.
- Treatment Planning:Supports interventional cardiologists in stent sizing and lesion preparation strategies using patient-specific hemodynamic simulations.
- Clinical Research:Academic medical centers deploy FFR-CT for prospective outcome studies and algorithm validation trials requiring institutional review board oversight.
Leading the category by volume: Coronary Diagnostics. Growing fastest: Non-Invasive Risk Assessment.
End User:
Procurement authority and infrastructure maturity separate high-volume adopters from pilot-site evaluators across the customer base.
- Hospitals:Integrated delivery networks with existing premium CT scanner fleets and enterprise PACS infrastructure. These systems absorb upfront software licensing costs to consolidate cardiovascular diagnostic workflows within centralized radiology departments.
- Cardiology Clinics:Independent outpatient facilities driving fastest adoption growth as site-of-service economics shift toward non-invasive first-line assessment. German reimbursement frameworks particularly favor this segment's expansion.
- Imaging Centers:Community-based facilities leveraging cloud-based processing to avoid on-premise server capital expenditure while offering competitive coronary CT angiography services.
- Research Institutions:Academic centers with specialized biomedical engineering talent for three-dimensional arterial model reconstruction and computational fluid dynamics algorithm development.
Hospital systems capture the largest installed base. Cardiology clinics show the steepest expansion trajectory.
Technology:
Margin concentration follows proprietary algorithm differentiation and regulatory exclusivity rather than commodity hardware components.
- Image Processing Software:Core value-capture layer where deep-learning algorithms transform raw CT datasets into patient-specific hemodynamic simulations. FDA-cleared platforms command premium pricing through exclusive processing pipelines.
- CT Imaging:Submillimeter spatial resolution acquisition hardware from Siemens Healthineers and GE HealthCare establishes the foundational data layer, though scanner vendors increasingly bundle software partnerships to differentiate equipment sales.
- Simulation Tools:Computational fluid dynamics engines requiring specialized biomedical engineering expertise for three-dimensional arterial mesh generation and boundary condition specification.
- Data Analytics:Emerging layer aggregating population-level FFR-CT outcomes for quality benchmarking and predictive risk stratification across health system networks.
Software layers extract disproportionate margin. Hardware integration determines workflow stickiness.
Delivery Mode:
Capital intensity and data residency requirements segment deployment preferences by facility scale and geography.
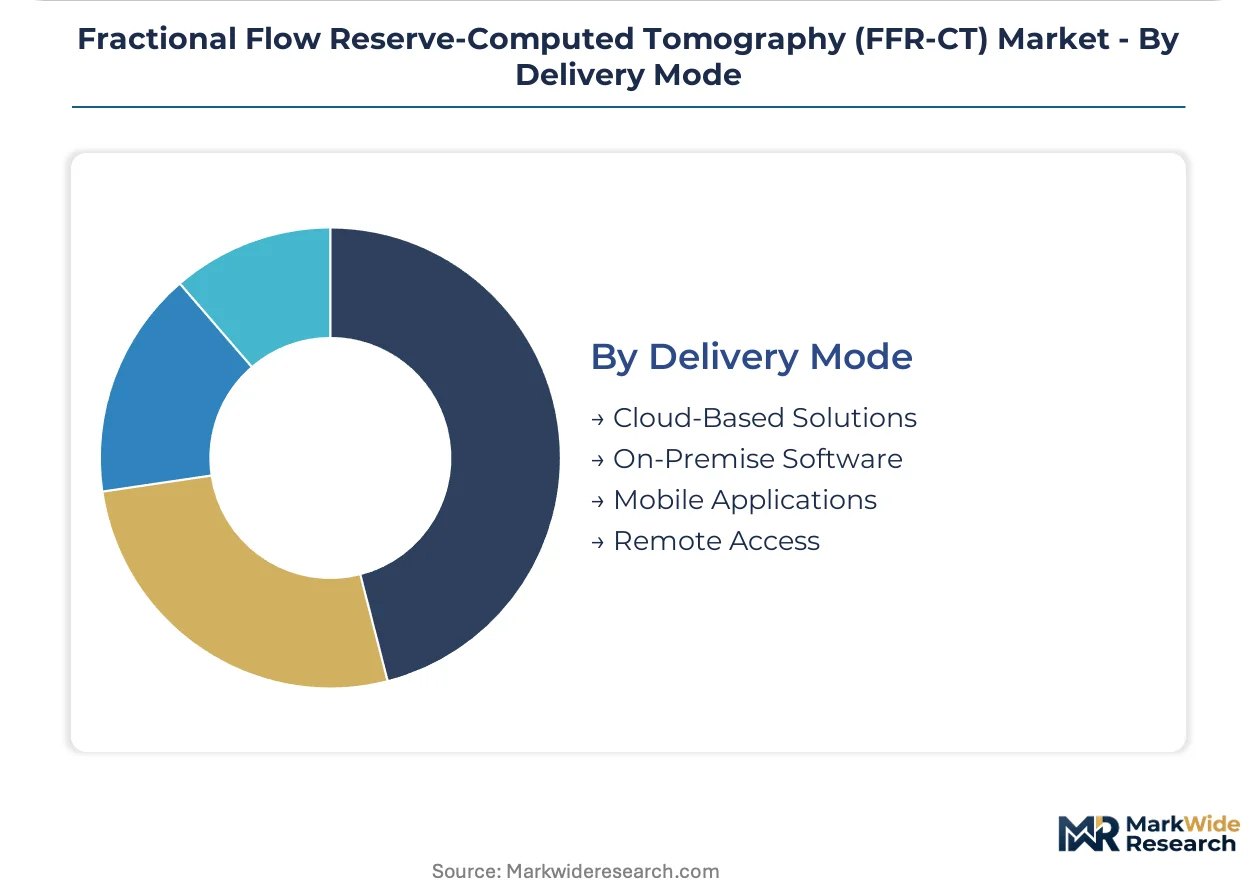
- Cloud-Based Solutions:Dominant growth trajectory as regional imaging centers and community cardiology clinics avoid specialized server hardware purchases. HIPAA-compliant architectures with United States data residency unlock enterprise health system contracts.
- On-Premise Software:Preferred by academic medical centers and large integrated delivery networks with existing computational infrastructure and strict institutional data governance policies.
- Remote Access:Enables specialist cardiologists to review hemodynamic simulations from procedural suites or consultation rooms without dedicated workstation deployment.
- Mobile Applications:Early-stage deployment for physician notification and preliminary case review, though full diagnostic interpretation remains workstation-dependent due to display resolution requirements.
Cloud delivery claims the fastest adoption velocity. On-premise retains the highest average contract value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FFR-CT technology concentrates consumption in advanced healthcare systems with established reimbursement pathways, while production of core software algorithms and imaging hardware clusters in the United States and Germany. Manufacturing of CT scanner components spans broader geographies, creating a demand-production asymmetry that shapes regional market dynamics.
United States
Hospital systems and outpatient cardiology clinics drive FFR-CT demand through value-based care contracts that reward non-invasive diagnostic pathways. FDA premarket authorization under software-as-medical-device pathways accelerates commercial deployment timelines for algorithm developers. The Boston-Cambridge corridor and Silicon Valley concentrate venture-backed computational diagnostic startups alongside established imaging equipment manufacturers.
Germany
National health technology assessment bodies now reimburse CT-derived fractional flow reserve analysis, compressing site-of-service economics for outpatient cardiology clinics. CE marking under EU MDR governs market access for software vendors seeking European authorization. The Munich and Berlin metropolitan areas host integrated delivery networks pioneering CT-first coronary assessment protocols.
Japan
PMDA regulatory pathways shape commercialization timelines for computational diagnostic software entering the Japanese market. Aging demographics and coronary disease prevalence expand the addressable patient population for non-invasive physiological assessment. The Tokyo-Osaka corridor concentrates academic medical centers with advanced CT imaging infrastructure and specialized biomedical engineering talent.
United Kingdom
National Health Service technology appraisal processes determine reimbursement eligibility for FFR-CT within integrated care systems. NICE guidance influences procurement decisions across NHS trusts evaluating coronary diagnostic pathways. London and the Greater Manchester region host pilot programs for cloud-based hemodynamic simulation services in community cardiology settings.
China
NMPA regulatory review governs market entry for imported and domestically developed computational diagnostic software. Tier-one hospitals in provincial capitals deploy premium CT scanners capable of submillimeter acquisition protocols required for FFR-CT. The Yangtze River Delta and Pearl River Delta regions concentrate private hospital networks investing in non-invasive cardiovascular diagnostic capabilities.
Fractional Flow Reserve-Computed Tomography (FFR-CT) Market Competitive Landscape
Top-tier vendors anchor integrated hardware-software ecosystems, while specialized algorithm developers occupy distinct competitive positions. The market structure reflects tiered capability concentration, with premium-tier players commanding workflow integration advantages and mid-tier specialists competing on processing speed or cost positioning. Two strategic archetypes dominate: computational platform specialists leveraging proprietary deep-learning architectures, and diversified imaging equipment manufacturers bundling software partnerships with scanner sales. Competitive moves concentrate on strategic partnerships between algorithm developers and CT manufacturers, plus geographic expansion through regulatory clearance sequencing.
Within the computational platform tier, HeartFlow, Inc. and CathWorks Ltd. exemplify pure-play specialists whose market positioning derives from exclusive algorithm development rather than hardware manufacturing. Siemens Healthineers anchors the integrated equipment-software archetype, representing diversified manufacturers that consolidate diagnostic workflows through bundled system offerings. These three companies occupy positions that illustrate the competitive tension between specialized software excellence and full-stack workflow control.
| Leading Market Players |
|---|
| HeartFlow, Inc. |
| Siemens Healthineers |
| GE HealthCare |
| Koninklijke Philips N.V. |
| CathWorks Ltd. |
| Opsens Inc. |
| ACIST Medical Systems |
| Medis Medical Imaging Systems BV |
| Pie Medical Imaging |
| Others |
Pricing and Supply Chain Analysis
Hospital procurement committees in the United States are mandating HIPAA-compliant cloud architectures for FFR-CT deployments, forcing algorithm vendors to establish domestic data residency infrastructure and compressing margins on standard software licenses while sustaining premiums for fully compliant enterprise bundles.
Pricing Analysis
Short lead-time delivery commands substantial premiums in the FFR-CT market as hospital systems accelerate diagnostic pathway overhauls under value-based care contracts. The dominant pricing model operates through tiered SaaS subscriptions stratified across premium, standard, and economy levels based on computational throughput and integration depth. Price differentiation separates FDA-cleared platforms with exclusive processing pipelines from CE-marked alternatives awaiting full clinical validation. Pricing pressure stems from cloud processing commoditization as remote computational infrastructure democratizes access. Community imaging centers exhibit highest price sensitivity, while integrated delivery networks prioritize workflow stickiness over per-unit cost.
Supply Chain Analysis
CT scanner hardware supply rests on precision manufacturing capabilities concentrated in Germany, Japan, and the United States, with submillimeter detector arrays and gantry systems drawing from specialized semiconductor foundries in Taiwan and South Korea. Deep-learning algorithm development feeds from concentrated biomedical engineering talent pools in the Boston-Cambridge corridor and Munich metropolitan region. Single-source vulnerability persists for photon-counting detector substrates, where limited qualified suppliers create procurement bottlenecks. Distribution runs through direct equipment sales forces for scanner hardware and software-as-medical-device licensing platforms for computational diagnostics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Computational fluid dynamics expertise scarcity props pricing power for algorithm developers capable of three-dimensional arterial model reconstruction, creating a supply-constrained environment where specialized talent concentration determines competitive viability.
For Market Incumbents: Hedge against invasive catheterization workflow persistence by embedding FFR-CT capabilities into broader cardiovascular imaging portfolios through strategic CT manufacturer partnerships. Prioritize backward integration into cloud infrastructure to capture recurring revenue streams and defend margin position against pure-play software competitors. Accelerate FDA clearance sequences for algorithm iterations to maintain regulatory exclusivity windows. For New Entrants and Emerging Players: The price-point gap between premium FDA-cleared platforms and economy-tier research-use-only alternatives creates immediate white-space opportunity in United States cardiology clinics outside major academic medical centers. Target German outpatient networks where reimbursement expansion has compressed site-of-service economics but incumbent penetration remains shallow. Pursue cloud-native deployment architectures to avoid capital-intensive on-premise infrastructure requirements and accelerate time-to-revenue. For Investors and Strategic Acquirers: The window for entry favors computational platform specialists with proprietary deep-learning architectures and established regulatory clearance pathways. Long-term viability hinges on algorithm differentiation durability and health system contract stickiness rather than hardware manufacturing scale. Watch FDA premarket authorization velocity and CE marking backlogs under EU MDR as inflection indicators for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance timelines create market access friction requiring prioritized regulatory investment. |
| Hospital System Partnership | Integrated delivery network contracts lock in recurring revenue and consolidate diagnostic workflows. |
| Software Companion Development | AI-enabled workflow automation differentiates platforms for high-volume screening programs. |
| Reimbursement Strategy | National health technology assessment coverage decisions determine site-of-service economics. |
| Strategic Partnership | CT manufacturer alliances bundle algorithm access with scanner sales to capture equipment procurement cycles. |
Research Methodology
Document review covered FDA 510(k) filings, CE marking technical documentation, and hospital procurement databases, complemented by interviews with interventional cardiologists, biomedical engineering directors, radiology department heads, and GPO contracts managers. Secondary validation drew from CMS Medicare reimbursement data, European health technology assessment reports, and medical device trade association publications. Bottom-up demand modeling triangulated against top-down market sizing across the analysis window.
Cross-referencing historical adoption curves with expert panel input shaped the analytical framework. Segmentation dimensions modeled encompassed application type, end-user facility scale, deployment architecture, and regional regulatory cluster. CAGRs were derived from fitting trend lines to validated data points and stress-testing against industry-specific inputs including scanner installation base expansion and cloud processing adoption velocity.
Inputs from regulatory filing databases and hospital procurement systems were available through the study window; gaps in real-time reimbursement coding decisions introduce uncertainty bands around near-term volume projections. Forecasts reflect documented assumptions regarding FDA review timeline continuity and EU MDR notified body capacity. Reimbursement policy reversals, invasive cardiology workflow entrenchment, and computational infrastructure cost trajectories warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Cardiovascular Diagnostic and Monitoring Devices Market
Cardiovascular Devices
Stent Grafts Market
Cardiovascular Devices
Global 3D Vascular Ultrasound Imaging Market
Cardiovascular Devices
Extracorporeal Membrane Oxygenation (ECMO) Market
Cardiovascular Devices
Cardiovascular Needle Market
Cardiovascular Devices
Global Nitinol Medical Devices Market
Cardiovascular Devices
Canada Cardiovascular Devices Market
Cardiovascular Devices
Endovascular Stent Market
Cardiovascular Devices
Global Resuscitation Devices Market
Cardiovascular Devices
Aortic Stents Grafts Market
Cardiovascular Devices
Anticoagulation Market
Cardiovascular Devices
Global PTA Balloon Catheter Market
Cardiovascular Devices
Cardiac Mapping Systems Market
Cardiovascular Devices
Pulmonary Stents Market
Cardiovascular Devices
Mobile Cardiac Telemetry Device Market
Cardiovascular Devices
Global Coil Wound Devices Market