
 Chronic Venous Occlusions Treatment Market | 2026-2036
Chronic Venous Occlusions Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Venous Occlusions Treatment Market Analysis
CE marking under the EU Medical Device Regulation is recalibrating the cost-of-entry calculus for venous intervention manufacturers seeking European market access. Boston Scientific Corporation leverages its endovascular portfolio to sustain leadership in catheter-based recanalization systems. Medtronic anchors its competitive position through integrated imaging-to-therapy workflows for venous procedures. Gore differentiates via proprietary expanded polytetrafluoroethylene stent grafts engineered specifically for iliocaval and femoropopliteal venous segments.
Chronic venous occlusions represent pathological luminal obstruction of deep or superficial veins resulting from thrombotic organization, fibrotic remodeling, or external compression, typically requiring intervention when hemodynamic compromise produces disabling edema, ulceration, or claudication. Catheters and stents constitute the core intervention platform, with self-expanding nitinol designs dominating iliofemoral segments due to superior conformability against compressive forces. Ambulatory surgical centers represent the fastest-growing end-user channel as reimbursement frameworks shift lower-acuity venous interventions away from inpatient settings. Minimally invasive delivery modes command premium positioning relative to open surgical bypass, though reimbursement parity gaps persist across European and North American markets.
The FDA maintains stringent premarket approval pathways for venous stents, while the EU MDR imposes enhanced clinical evidence requirements through notified body scrutiny. Japan's PMDA and Health Canada apply comparable risk-classification frameworks that manufacturers must navigate sequentially for multi-region commercialization. Stakeholders should monitor evolving real-world evidence mandates from these regulators, as post-market surveillance obligations are tightening for permanent implantable devices in the venous space.
Market Dynamics
The migration of chronic venous occlusion procedures from hospital inpatient suites to ambulatory surgical centers is compressing capital deployment timelines and forcing manufacturers to reconfigure device form factors for office-based lab settings.
Growth Catalysts
- Medicare reimbursement recalibration:CMS payment adjustments for outpatient venous interventions redirect patient volumes toward lower-cost settings, expanding addressable procedure volumes.
- EU MDR clinical evidence pathways:Enhanced notified body scrutiny elevates barriers for marginal competitors, concentrating market access among established manufacturers with robust trial infrastructure.
- Nitinol self-expanding stent platforms:Superior conformability against compressive forces in iliofemoral segments displaces balloon-expandable alternatives in high-compression anatomies.
Market Restraints
- Platinum-iridium alloy cost volatility:Electrode and marker band inputs face concentrated supply from South African and Russian mining operations, squeezing gross margins on catheter-based systems.
- FDA premarket approval timelines:Extended PMA review cycles for venous stent indications delay commercialization by 18-36 months relative to peripheral arterial equivalents.
- Conservative medical management:Compression therapy and anticoagulation protocols remain first-line for stable patients, capping procedural penetration in asymptomatic cohorts.
Strategic Opportunities
- Japan PMDA venous stent pathway:Underdeveloped reimbursement for iliofemoral interventions creates first-mover advantage for manufacturers with physician education capabilities.
- Integrated imaging-to-therapy workflows:Convergence of intravascular ultrasound with mechanical thrombectomy platforms enables single-operator procedures, reducing staffing overhead.
- Real-world evidence mandates:Post-market surveillance obligations for permanent implants create data monetization and registry service opportunities for device vendors.
Industry Challenges
- Interventional radiology workforce constraints:Fellowship-trained specialists capable of complex recanalization remain concentrated at academic medical centers, limiting procedure expansion.
- CE marking transition complexity:Legacy certificates under the Medical Device Directive expire without MDR renewal, forcing portfolio rationalization and notified body capacity bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Venous Occlusions Treatment Market |
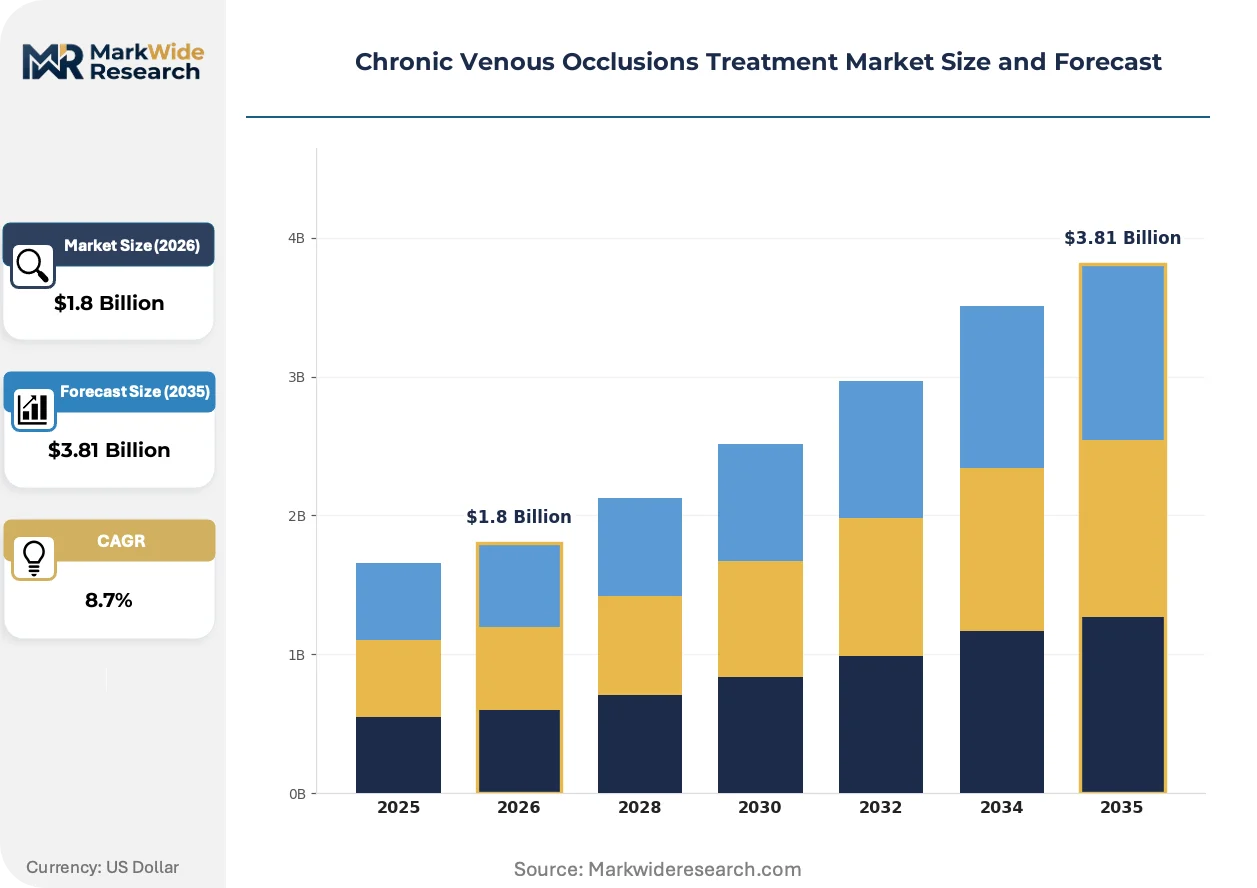
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Stents, Compression Garments, Sclerotherapy Agents End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Homecare Settings Delivery Mode: Minimally Invasive, Non-Invasive, Outpatient, Inpatient Application: Therapeutic Intervention, Palliative Care, Surgical Treatment, Diagnosis |
| Companies Covered | Boston Scientific Corporation, Medtronic, Cook Medical, Stryker, Cardinal Health, Edwards Lifesciences, Gore, 3M, AngioDynamics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Venous Occlusions Treatment Market Emerging Trajectories
Device miniaturization and procedural simplification are collapsing the skill threshold required for chronic venous intervention, expanding the eligible operator pool beyond traditional vascular specialists.
Drug-coated balloon technology is consolidating market share in femoropopliteal venous segments by reducing restenosis rates compared to plain balloon angioplasty. Ambulatory surgical centers in the United States adopt these platforms aggressively to minimize repeat intervention costs. The technology is consolidating purchasing decisions around vendors with integrated drug-device combination expertise and pharmacy benefit navigation capabilities.
EU MDR Article 120 transition deadlines are compressing notified body capacity and extending conformity assessment timelines for legacy device renewals. Manufacturers with diversified certification strategies across multiple European notified bodies maintain market access continuity. Small-to-mid-tier competitors without dedicated regulatory affairs infrastructure face portfolio attrition as certificates lapse.
Site-of-service economics are restructuring procurement authority from hospital materials management to physician-owned ambulatory entities. United States-based interventionalists in joint venture ASCs negotiate directly with manufacturers, bypassing traditional group purchasing organizations. This channel disintermediation demands revised pricing architectures and inventory consignment models tailored to smaller capital bases.
Chronic Venous Occlusions Treatment Market Segmentation
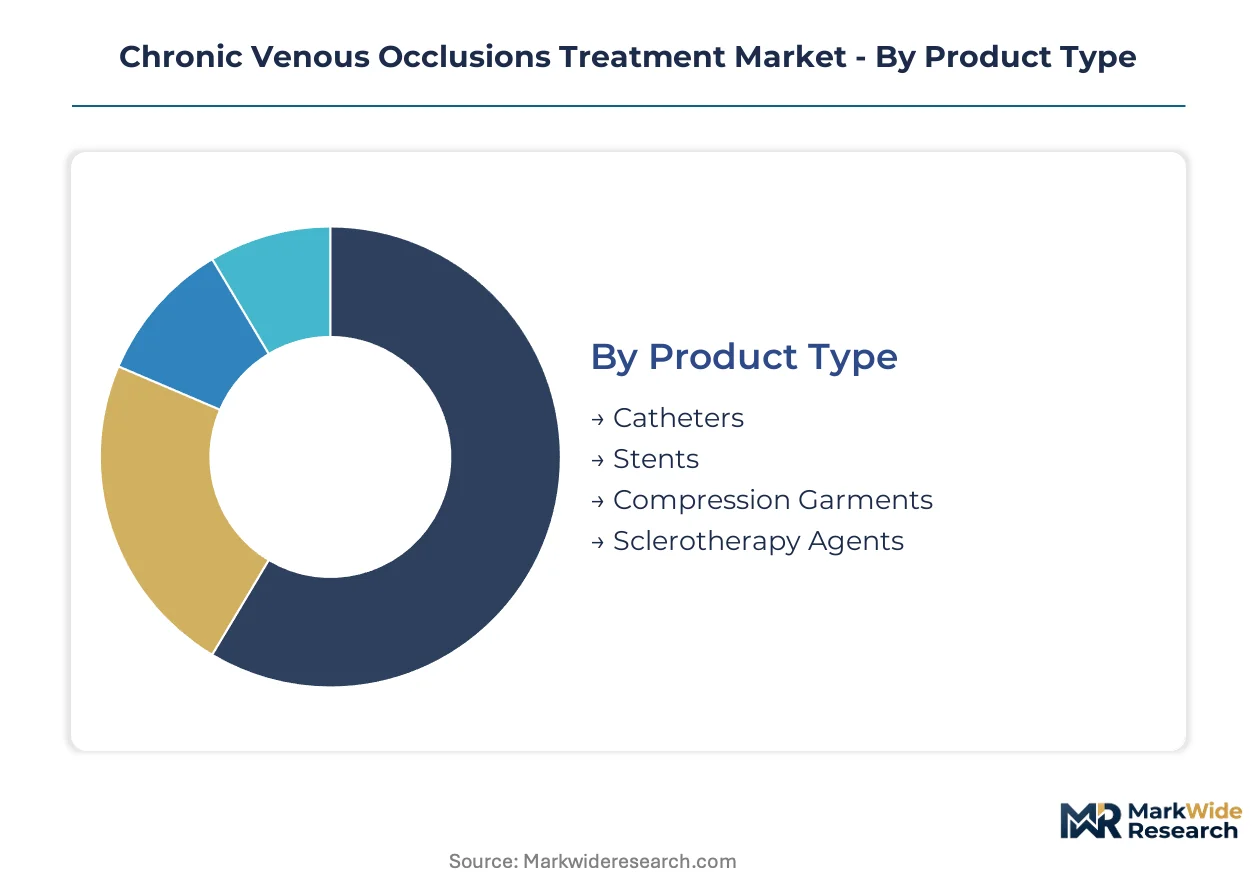
Chronic venous occlusion interventions fragment across multiple technical and commercial axes, each carrying distinct regulatory burdens and reimbursement profiles. Understanding how product categories, care settings, and procedural approaches map to FDA PMA pathways versus EU MDR conformity assessments enables manufacturers to prioritize development spend and geographic sequencing.
Product Type:
Catheters and stents face FDA Class III premarket approval requirements with 18-36 month review cycles, while compression garments and sclerotherapy agents navigate lighter 510(k) or de novo pathways.
- Catheters:Recanalization catheters incorporate hydrophilic coatings and laser-compatible shafts for crossing organized thrombus. Demand concentrates in ambulatory surgical centers across the United States as CMS reimbursement shifts lower-acuity cases away from inpatient settings. Platinum-iridium marker band cost volatility squeezes margins on radiopaque designs.
- Stents:Self-expanding nitinol platforms dominate iliofemoral segments due to superior conformability against compressive forces. Hospital systems in Germany and the United States anchor procurement volumes, though extended FDA PMA timelines delay commercialization relative to peripheral arterial equivalents.
- Compression Garments:Gradient pressure systems for post-interventional care face lighter regulatory scrutiny but compete on material breathability and patient compliance metrics.
- Sclerotherapy Agents:Liquid and foam sclerosants require pharmacy benefit navigation capabilities for outpatient reimbursement, with purchasing decisions consolidating around vendors with integrated drug-device expertise.
Leading the category by volume: Catheters. Growing fastest: Stents.
End User:
Site-of-service economics restructure procurement authority from hospital materials management to physician-owned entities, with reimbursement frameworks determining capital deployment timelines.
- Hospitals:Academic medical centers concentrate fellowship-trained interventional radiologists capable of complex recanalization, though procedure volumes face compression from CMS payment adjustments redirecting cases to lower-cost settings.
- Ambulatory Surgical Centers:Joint venture ASCs in the United States negotiate directly with manufacturers, bypassing traditional group purchasing organizations and demanding revised pricing architectures.
- Specialty Clinics:Vein-focused outpatient facilities prioritize device miniaturization and procedural simplification to expand the eligible operator pool beyond traditional vascular specialists.
- Homecare Settings:Compression therapy and wound care management extend treatment continuity, with reimbursement parity gaps persisting across European and North American markets.
Procurement concentration: Ambulatory Surgical Centers. Steepest expansion trajectory: Specialty Clinics.
Delivery Mode:
Capital intensity and staffing requirements vary sharply across delivery modalities, with minimally invasive platforms commanding premium positioning despite reimbursement parity gaps.
- Minimally Invasive:Catheter-based recanalization and stent deployment reduce recovery times versus open surgical bypass. United States Medicare reimbursement adjustments favor these modalities in outpatient settings, though European markets lag in procedural coverage harmonization.
- Non-Invasive:Compression therapy and external counterpulsation remain first-line for stable patients, capping procedural penetration in asymptomatic cohorts.
- Outpatient:Office-based lab settings demand reconfigured device form factors and inventory consignment models tailored to smaller capital bases.
- Inpatient:Reserved for complex cases requiring hemodynamic monitoring or staged interventions, with volumes compressing as site-of-service economics shift.
Volume leadership: Minimally Invasive. Fastest climb: Outpatient.
Application:
Clinical intent determines device specification requirements, with therapeutic interventions facing the steepest evidentiary burdens for permanent implants.
- Therapeutic Intervention:Recanalization and stenting for disabling edema, ulceration, or claudication require robust clinical trial infrastructure to satisfy FDA PMA and EU MDR enhanced scrutiny. Boston Scientific and Medtronic anchor competitive positioning through integrated imaging-to-therapy workflows.
- Palliative Care:Symptom management for non-ambulatory patients prioritizes compression and pharmacologic approaches over invasive intervention.
- Surgical Treatment:Open bypass procedures retain niche indication for failed endovascular approaches, with volumes declining as minimally invasive platforms displace.
- Diagnosis:Intravascular ultrasound and venography guide intervention planning, with convergence into mechanical thrombectomy platforms enabling single-operator procedures.
Category volume leader: Therapeutic Intervention. Gaining share fastest: Diagnosis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MedTech hubs in Massachusetts and Minnesota concentrate venous device innovation, with FDA PMA pathways shaping commercialization timelines. Reimbursement frameworks in Germany and Japan are recalibrating site-of-service economics for interventional procedures.
United States
Ambulatory surgical centers in Florida and Texas are capturing venous procedure volumes as CMS payment adjustments redirect cases from inpatient settings. The FDA maintains 18-36 month PMA review cycles for venous stent indications. The Minneapolis-St. Paul corridor anchors nitinol stent manufacturing and physician training infrastructure.
Germany
Hospital systems in Bavaria and North Rhine-Westphalia are expanding interventional radiology departments for complex venous recanalization. CE marking under the EU MDR imposes enhanced clinical evidence requirements through notified body scrutiny. The Munich medical technology cluster concentrates catheter manufacturing and regulatory affairs expertise.
Japan
Academic medical centers in Tokyo and Osaka are developing iliofemoral venous stent programs as PMDA reimbursement pathways mature. METI incentives support domestic production of high-value vascular implants. The Kobe biomedical innovation cluster houses specialized contract research organizations for Asian regulatory submissions.
United Kingdom
NHS England's specialized commissioning frameworks are consolidating complex venous interventions at designated vascular centers in London and Manchester. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit device regulations with EU MDR standards. The Cambridge medical technology corridor attracts venture funding for next-generation thrombectomy platforms.
India
Private hospital chains in Delhi-NCR and Maharashtra are adopting catheter-based venous interventions for medical tourism cohorts. CDSCO medical device rules impose import licensing requirements on foreign manufacturers. The Hyderabad medical device park offers tax incentives for domestic stent assembly operations.
Chronic Venous Occlusions Treatment Market Vendor Landscape
United States producers anchor the premium tier with integrated imaging-to-therapy workflows; European specialists hold positions in biocompatible graft materials. The vendor base concentrates among diversified MedTech conglomerates with vascular portfolios and mid-tier catheter specialists serving ambulatory settings. Three archetypes dominate: endovascular platform integrators, materials science specialists, and procedural workflow optimizers. M&A activity targets thrombectomy platform capabilities; geographic expansion focuses on Japan and India reimbursement development.
Within the endovascular platform tier, Boston Scientific Corporation and Medtronic exemplify integrated imaging-to-therapy positioning. Gore occupies a distinct materials science position through proprietary expanded polytetrafluoroethylene expertise. These three anchors represent divergent competitive vectors: catheter-based recanalization systems, workflow automation, and biocompatible implant engineering.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic |
| Cook Medical |
| Stryker |
| Cardinal Health |
| Edwards Lifesciences |
| Gore |
| 3M |
| AngioDynamics |
| Others |
Supply Flow & Price Mechanics
Platinum-iridium alloy spot indices from South African and Russian mining operations cascade through catheter manufacturing cost structures, compressing gross margins on radiopaque marker bands and forcing tiered pricing stratification across premium nitinol stent platforms, standard recanalization catheters, and economy compression garment lines.
Pricing Analysis
Lead-time-driven pricing premiums attach to FDA PMA-cleared stent platforms with sub-90-day manufacturing cycles, while spot inventory discounts concentrate in non-implantable compression garment tiers. Three-tier pricing structure across premium, standard, and economy levels differentiates by CE marking status and nitinol alloy grade. Pricing pressure stems from CMS reimbursement compression redirecting volumes toward ambulatory surgical centers with constrained capital bases. Physician-owned ASCs exhibit highest price sensitivity; academic medical centers with GPO contracts demonstrate lowest.
Supply Chain Analysis
Nitinol shape-memory alloy supply rests on specialized foundries in the United States and Germany, with platinum-iridium marker band feedstock concentrated in South African and Russian extraction operations. Raw material dependencies span nickel-titanium billets, hydrophilic polymer coatings, and expanded polytetrafluoroethylene graft substrates. Single-source vulnerability in noble metal electrode supply creates margin volatility exposure. Distribution runs through hospital materials management for inpatient stent procurement and direct manufacturer negotiation for ASC catheter replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR conformity assessment bottlenecks and extended FDA PMA timelines are forcing portfolio rationalization among mid-tier competitors, concentrating market access among manufacturers with dedicated regulatory infrastructure and multi-notified body certification strategies.
For Market Incumbents: Deepen backward integration into nitinol foundry operations to insulate margin structures from alloy price volatility. Expand notified body diversification across TÜV SÜD, BSI, and DEKRA to maintain CE marking continuity through MDR transition bottlenecks. Acquire thrombectomy platform capabilities to defend against workflow automation threats from integrated imaging-to-therapy competitors.
For New Entrants and Emerging Players: Ambulatory surgical center procurement committees represent the most penetrable buyer archetype, bypassing entrenched GPO relationships through direct consignment model pilots. Target Japan's underdeveloped iliofemoral venous stent reimbursement pathway with physician education-centric market development. Pursue drug-coated balloon white space in femoropopliteal segments where plain balloon angioplasty restenosis rates create substitution demand.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier catheter specialists with lapsed MDR certificates and salvageable European market positions. Long-term viability hinges on 5-10 year regulatory data generation capabilities for permanent implant portfolios. Watch FDA breakthrough device designation velocity as inflection indicator for competitive de-risking timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 120 transition deadlines compress notified body capacity and extend conformity timelines for legacy renewals. |
| Hospital System Partnership | Academic medical centers in Germany and the United States anchor procurement volumes for complex recanalization platforms. |
| Software Companion Development | Integrated imaging-to-therapy workflows from Boston Scientific and Medtronic reduce single-operator procedure staffing overhead. |
| Reimbursement Strategy | CMS payment adjustments for outpatient venous interventions redirect patient volumes toward ambulatory surgical centers. |
| FDA Submission | Premarket approval pathways for venous stents impose 18-36 month review cycles versus peripheral arterial equivalents. |
Methodological Framework
Document review covered FDA PMA filings, EU MDR technical documentation, and CMS Medicare reimbursement databases, complemented by interviews with interventional radiologists, hospital purchasing committee members, GPO contracts managers, and biomedical engineers across the United States, Germany, and Japan. Secondary sources incorporated hospital procurement databases, notified body conformity assessment records, and trade flow data for nitinol alloy and platinum-iridium feedstock. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures.
Segment-level outputs across product type, end user, delivery mode, and application dimensions were generated through the projection horizon using epidemiological prevalence models for chronic venous disease and intervention penetration rate assumptions. CAGRs were derived from log-linear regression of historical procedure volumes against reimbursement policy shift timelines and regulatory approval velocity metrics. Forecast inputs incorporated EU MDR transition deadline schedules, CMS site-of-service payment adjustments, and PMDA reimbursement pathway maturation curves.
Revisions become necessary when FDA PMA review cycle extensions, EU MDR notified body capacity constraints, or platinum-iridium supply disruptions materialize beyond modeled assumptions. Forecasts reflect documented assumptions regarding intervention penetration rates and reimbursement policy stability. A small set of named triggers—regulatory timeline slippage, noble metal price spikes, and ambulatory surgical center accreditation bottlenecks—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Lung Stent Market
Cardiovascular Devices
Absorbable Heart Stent Market
Cardiovascular Devices
Global Vascular Injury Treatment Market
Cardiovascular Devices
Intravascular Ultrasound (IVUS) System Market
Cardiovascular Devices
Cardiovascular Ultrasound Market
Cardiovascular Devices
Aortic Stents Grafts Market
Cardiovascular Devices
Global Drug Eluting Balloon Catheters Market
Cardiovascular Devices
Cardiac Rhythm Management Devices Market
Cardiovascular Devices
Drug Eluting Balloon Market
Cardiovascular Devices
Cardiac Sutures Market
Cardiovascular Devices
Cardiac Surgery Devices Market
Cardiovascular Devices
Vascular Prostheses Market
Cardiovascular Devices
Smart Blood Pressure Monitoring Devices Market
Cardiovascular Devices
Global Embolotherapy Market
Cardiovascular Devices
Chile Cardiovascular Devices Market
Cardiovascular Devices
Global Vascular Patch Market