
 Microsclerotherapy Treatment Market | 2026-2036
Microsclerotherapy Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Microsclerotherapy Treatment Market Foresight
The capital-intensity divergence between large pharmaceutical manufacturers and regional distributors is collapsing as sclerosant production shifts toward standardized, high-volume formulation. Merz Pharma GmbH & Co. KGaA leverages its European manufacturing footprint to control raw material sourcing for polidocanol and sodium tetradecyl sulfate. Kreussler anchors its position through specialized compounding capabilities that serve hospital procurement networks across Germany and Austria. QOL Medical LLC competes by concentrating on narrow therapeutic formulations for resistant vascular lesions.
Microsclerotherapy treatment involves the injection of chemical irritants—typically detergent sclerosants such as polidocanol or sodium tetradecyl sulfate—directly into superficial veins to induce endothelial damage, fibrosis, and eventual vessel obliteration, with concentrations ranging from 0.25% to 3% depending on vessel diameter and clinical indication. The foam product type segment leads volume due to superior displacement of blood within target vessels and enhanced sclerosant-to-endothelium contact time, while the solution segment retains margin strength in pediatric vascular malformation protocols where air embolism risk must be minimized. Dermatology practices represent the fastest-growing end user channel as point-of-care ultrasound integration enables real-time guidance without hospital infrastructure overhead.
The EU Medical Device Regulation and national pharmaceutical regulators such as Germany's Federal Institute for Drugs and Medical Devices impose stringent post-market surveillance and batch-release testing on sclerosant formulations, elevating compliance costs for new entrants while reinforcing incumbent quality dossiers. The US FDA maintains separate device-drug classification ambiguity for foam-generating systems, creating regulatory navigation complexity for manufacturers seeking transatlantic product harmonization. Stakeholders must monitor evolving reimbursement thresholds for cosmetic versus medically indicated procedures as payor scrutiny intensifies across European health technology assessment frameworks.
Market Dynamics
Foam-based sclerosant protocols are compressing treatment timelines while the EU Medical Device Regulation forces manufacturers to rebuild quality dossiers around post-market surveillance mandates.
Growth Catalysts
- Point-of-care ultrasound integration:Dermatology practices in Germany deploy compact imaging systems that enable real-time needle guidance without hospital infrastructure investment.
- Foam sclerosant displacement of liquid formulations:Superior blood displacement and extended endothelial contact time drive protocol conversion across French private clinic networks.
- REACH compliance standardization:Detergent-based sclerosant chemistry aligns with EU chemical safety frameworks, streamlining cross-border formulation approvals.
Market Restraints
- Active pharmaceutical ingredient concentration:Polidocanol and sodium tetradecyl sulfate supply chains cluster among European specialty chemical manufacturers, exposing buyers to input cost volatility.
- Foam-generation device classification ambiguity:The US FDA maintains unresolved device-drug jurisdiction questions that stall transatlantic product harmonization efforts.
- Air embolism risk protocols:Pediatric vascular malformation applications remain locked to liquid formulations, capping foam penetration in this indication.
Strategic Opportunities
- Underpenetrated Austrian hospital procurement networks:Kreussler's compounding capabilities face limited regional competition for standardized high-volume contracts.
- UK aesthetic clinic consolidation:Private network rollups create centralized procurement leverage that rewards suppliers with dedicated account management infrastructure.
- CSRD sustainability disclosure alignment:Early adoption of EU corporate sustainability reporting standards differentiates incumbent manufacturers in RFP evaluations.
Industry Challenges
- Phlebology technician certification pipelines:Foam preparation and ultrasound guidance require specialized training that outpaces European vocational program output.
- Batch-release testing timelines:Germany's Federal Institute for Drugs and Medical Devices extends quality verification cycles for novel formulation concentrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microsclerotherapy Treatment Market |
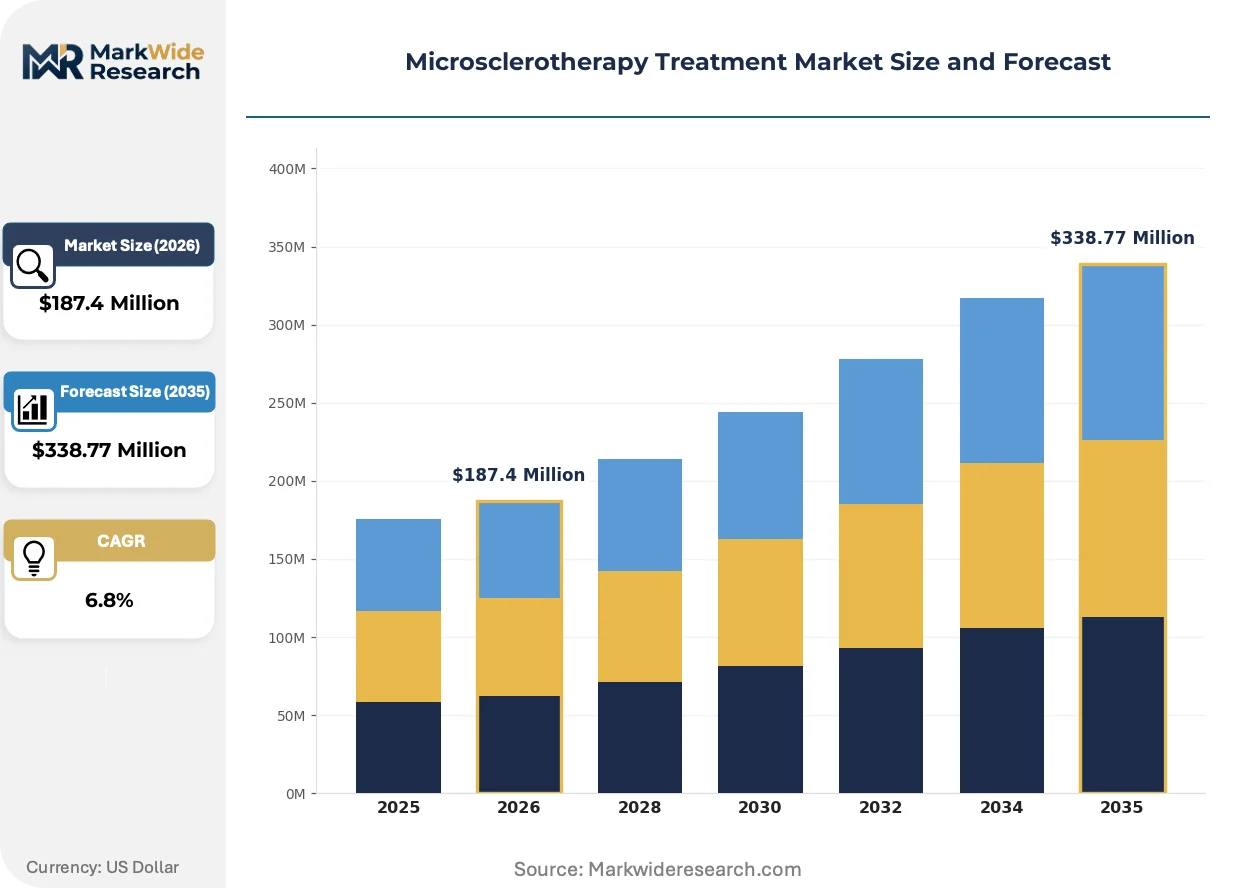
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam, Solution, Gel, Liquid Application: Varicose Veins, Spider Veins, Vascular Malformations, Cosmetic Enhancements End User: Clinics, Hospitals, Ambulatory Surgical Centers, Dermatology Practices Delivery Mode: Injectable, Topical, Surgical, Laser-Assisted |
| Companies Covered | Merz Pharma GmbH & Co. KGaA, QOL Medical LLC, McKesson Corporation, Kreussler, Provensis, STD Pharmaceuticals Product Ltd., Medtronic plc, Teleflex Incorporated, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microsclerotherapy Treatment Market Shifts & Advancements
Real-time imaging integration and regulatory disclosure requirements are compressing competitive differentiation cycles while procurement centralization rewards scale-oriented suppliers.
Portable ultrasound systems with vascular presets are miniaturizing diagnostic infrastructure requirements. Dermatology practices in France acquire handheld devices that eliminate radiology department dependency. This hardware diffusion is miniaturizing the capital barrier between hospital-based and office-based sclerotherapy service models.
The EU Medical Device Regulation mandates systematic post-market clinical follow-up for sclerosant agents. Manufacturers must deploy pharmacovigilance infrastructure that captures real-world safety data across distributed treatment settings. German notified bodies enforce this through unannounced manufacturing site audits that extend certification maintenance timelines.
Buying committees at UK private clinic networks now unbundle device procurement from consumable supply contracts. This disintermediation of traditional distributor relationships forces manufacturers to build direct field service organizations. The shift is most visible in London and Manchester metropolitan clusters where network consolidation has centralized decision-making authority.
Microsclerotherapy Treatment Market Segmentation
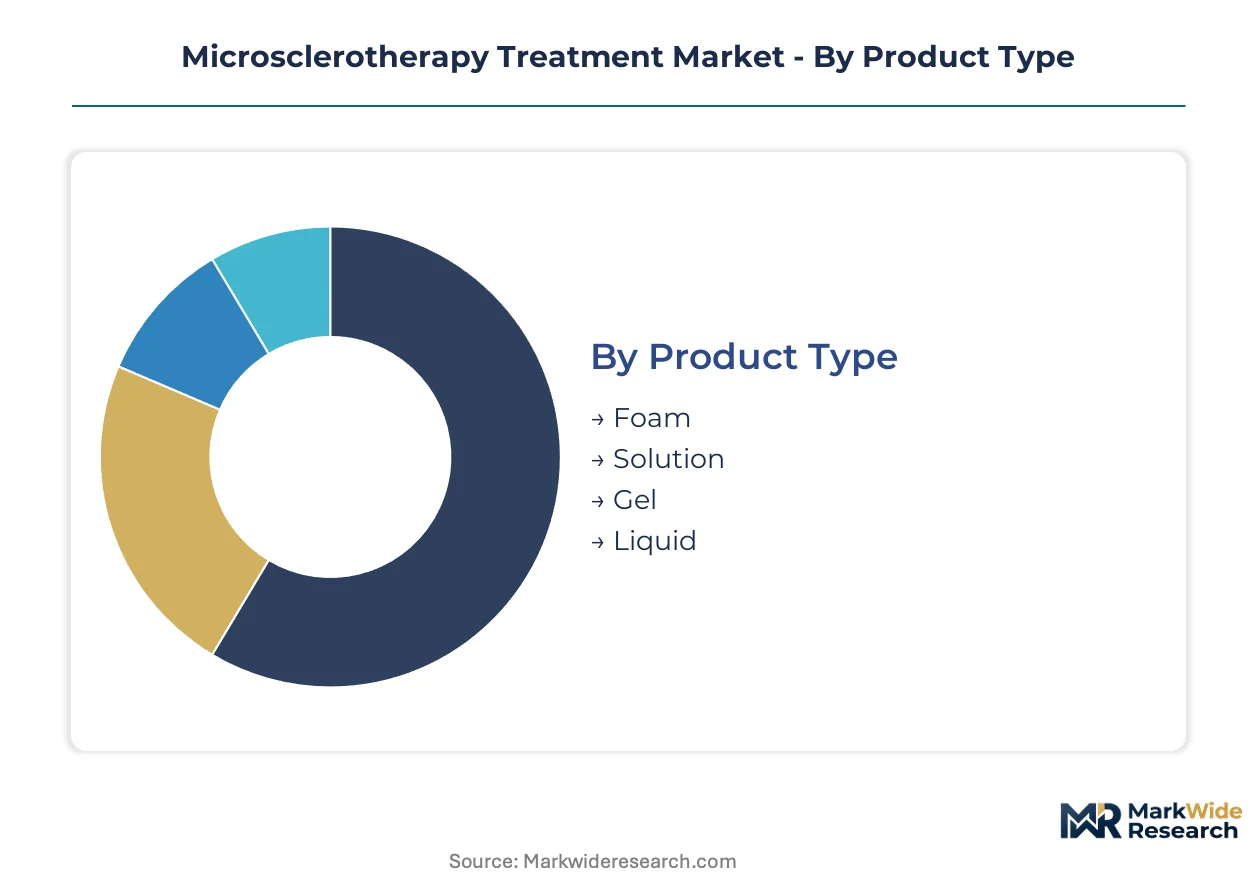
Sclerosant formulation and delivery modality determine reimbursement pathways and procurement economics across European healthcare systems. Segment boundaries are blurring as foam technology penetrates outpatient settings and ultrasound guidance standardizes across channels.
Product Type:
Margin pools concentrate in foam formulations where compounding complexity and device pairing create pricing power, while liquid concentrates compete on volume throughput in high-frequency hospital settings.
- Foam:Gas-liquid dispersions of polidocanol or sodium tetradecyl sulfate displace blood within target vessels and prolong endothelial contact time. German dermatology practices in Munich and Hamburg deploy compact ultrasound systems to guide foam injection without radiology department dependency, compressing treatment timelines and facility overhead.
- Solution:Aqueous sclerosant formulations at concentrations from 0.25% to 3% serve pediatric vascular malformation protocols where air embolism risk mandates liquid-only administration. France's hospital networks in Lyon and Marseille maintain solution purchasing contracts for congenital lesion indications that exclude foam alternatives.
- Gel:Viscous polidocanol preparations enable controlled delivery for facial telangiectasia near critical anatomical structures. Vienna aesthetic clinics favor gel viscosity for periorbital applications requiring millimeter precision.
- Liquid:Standard aqueous formulations dominate high-volume procurement tenders where unit cost optimization outweighs clinical differentiation. Austrian hospital purchasing cooperatives standardize on liquid concentrates for varicose vein protocols.
The dominant share belongs to Foam, while Solution is closing the gap fastest through pediatric protocol lock-in.
Application:
Volume distribution tracks the boundary between medically necessary procedures and self-pay aesthetic services, with reimbursement eligibility determining addressable market scope.
- Varicose Veins:Great saphenous vein incompetence and tributary dilation drive the largest procedure volume across European healthcare systems. UK's National Institute for Health and Care Excellence guidelines mandate endovenous thermal ablation first-line, reserving sclerotherapy for recurrent or accessory vein disease, compressing microsclerotherapy's reimbursable indication scope.
- Spider Veins:Telangiectasia and reticular vein treatment operates almost exclusively in private-pay aesthetic channels. London clinic networks bundle spider vein packages with laser services, creating procedure volume concentration in metropolitan catchment areas.
- Vascular Malformations:Congenital low-flow lesions in pediatric populations require liquid sclerosant protocols under general anesthesia. German university hospitals in Heidelberg and Freiburg maintain specialized interventional radiology units for these indications.
- Cosmetic Enhancements:Elective facial vein and décolletage treatments command premium pricing in private aesthetic practices. Manchester aesthetic clinic rollups centralize procurement for cosmetic sclerotherapy consumables.
Varicose Veins commands the largest procedure base, though Spider Veins is expanding most quickly through aesthetic channel consolidation.
End User:
Capital intensity and regulatory burden stratify the channel landscape, with point-of-care technology diffusion reshaping traditional site-of-service boundaries.
- Dermatology Practices:Outpatient vein clinics with handheld ultrasound capability capture procedure volume from hospital-based phlebology units. French private practices in Bordeaux and Toulouse deploy vascular presets on portable devices to eliminate radiology referral delays.
- Clinics:Dedicated vein treatment centers concentrate sclerosant purchasing volume through multi-site procurement networks. UK independent clinic groups in Birmingham and Leeds negotiate formulary standardization across their footprints.
- Hospitals:Academic medical centers retain complex malformation cases and pediatric protocols requiring anesthesia support. German university hospitals manage batch-release documentation for compounded sclerosant formulations.
- Ambulatory Surgical Centers:Same-day procedure facilities compete on throughput economics for uncomplicated varicose vein cases. Austrian ASC networks in Salzburg and Innsbruck optimize scheduling density for sclerotherapy sessions.
Dermatology Practices hold the steepest expansion trajectory, while Hospitals defend volume in complex indication segments.
Delivery Mode:
Technology pairing requirements and operator training depth determine competitive positioning across delivery modalities.
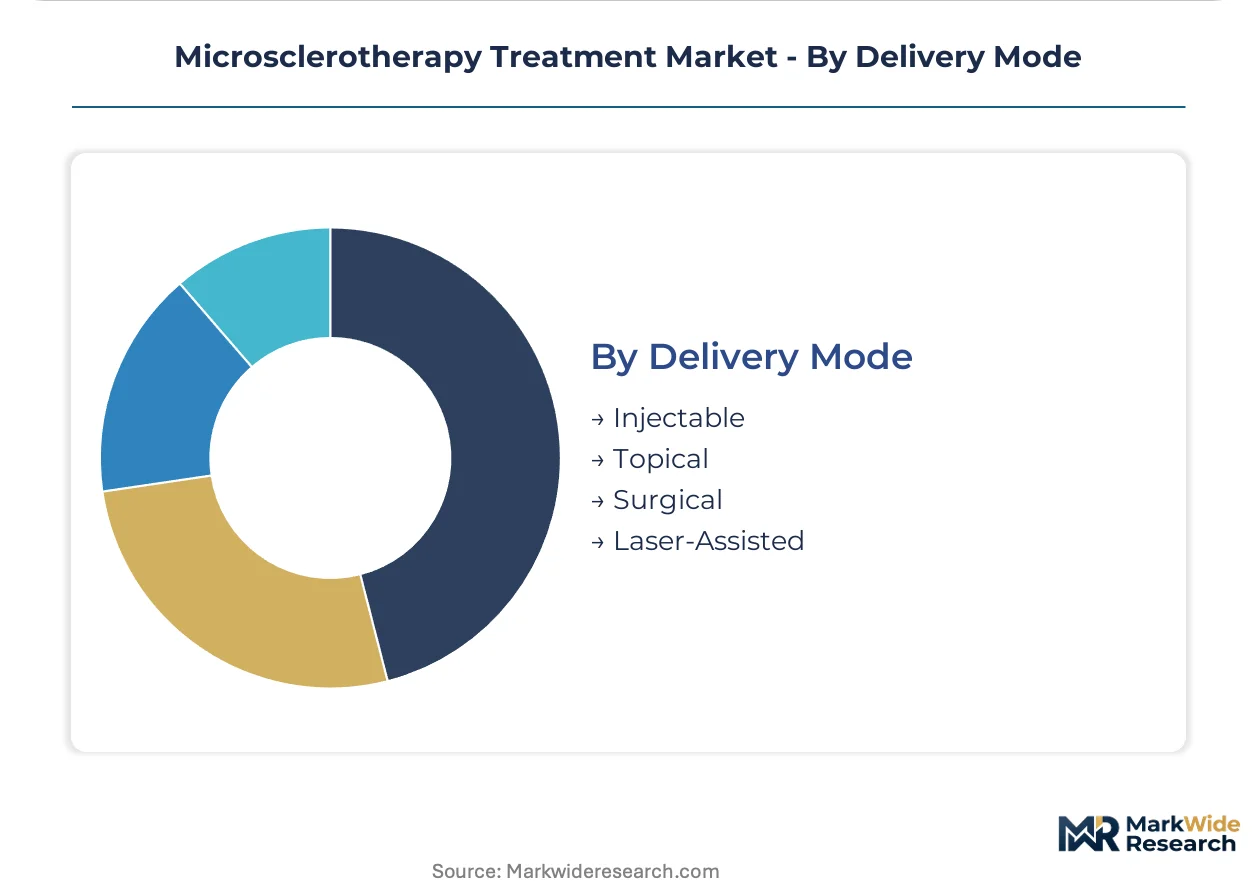
- Injectable:Direct intravascular sclerosant administration via syringe or pump remains the standard delivery mechanism. German phlebology technicians complete certified training programs for foam preparation and injection technique.
- Laser-Assisted:Transcutaneous laser systems complement sclerotherapy for resistant telangiectasia and post-sclerotherapy matting. French aesthetic clinics in Paris combine 532nm and 1064nm wavelengths with microsclerotherapy for comprehensive leg vein treatment.
- Topical:Transdermal sclerosant delivery remains investigational for superficial vessel applications. No approved topical formulations exist in European pharmaceutical formularies.
- Surgical:Phlebectomy and ligation procedures precede or accompany sclerotherapy in comprehensive vein treatment protocols. UK vascular surgery units perform hybrid procedures combining thermal ablation with adjunctive sclerotherapy.
Injectable retains the foundational position, with Laser-Assisted gaining share fastest through aesthetic channel technology adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German dermatology practices command 15-20% pricing premiums over Italian clinics for equivalent foam sclerotherapy protocols, reflecting divergent reimbursement density and regulatory compliance cost allocation across European markets.
Germany
Munich and Hamburg dermatology networks deploy compact ultrasound systems for real-time needle guidance, compressing treatment timelines. The Federal Institute for Drugs and Medical Devices enforces extended batch-release testing cycles for novel sclerosant concentrations. Bavarian hospital procurement cooperatives in Nuremberg standardize on liquid concentrates for high-volume varicose vein protocols.
France
Paris aesthetic clinics bundle spider vein packages with 532nm laser services, creating metropolitan procedure concentration. ANSM maintains stringent pharmacovigilance requirements for detergent-based sclerosant formulations. Lyon hospital networks retain solution purchasing contracts for pediatric vascular malformation cases that exclude foam alternatives.
United Kingdom
London and Manchester clinic rollups centralize procurement decision-making for consumable supply contracts. NICE guidelines reserve sclerotherapy for recurrent vein disease after thermal ablation first-line, compressing reimbursable indication scope. Birmingham independent clinic groups negotiate formulary standardization across multi-site footprints.
Austria
Salzburg and Innsbruck ambulatory surgical centers optimize scheduling density for same-day sclerotherapy sessions. The national pharmaceutical regulator aligns with EU MDR post-market surveillance mandates for sclerosant agents. Vienna aesthetic clinics favor gel viscosity preparations for periorbital telangiectasia requiring millimeter precision.
Italy
Milan private practices absorb capital costs for portable ultrasound devices to eliminate radiology referral dependencies. The Italian Medicines Agency enforces CE marking compliance for foam-generating systems under EU MDR jurisdiction. Rome clinic networks concentrate cosmetic enhancement procedures for facial vein and décolletage treatments.
Microsclerotherapy Treatment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with formulation specialists commanding premium positioning while distribution-scale operators compete on procurement efficiency. The vendor base concentrates around three strategic tiers: European pharmaceutical manufacturers with captive chemical synthesis capabilities, regional compounding specialists serving hospital procurement networks, and North American device-drug hybrid suppliers navigating FDA classification ambiguity. Dominant competitive moves include backward integration into polidocanol raw material sourcing and direct field service organization builds to bypass traditional distributor relationships.
Within the European manufacturing tier, Merz Pharma GmbH & Co. KGaA and Kreussler occupy positions anchored by specialized production infrastructure and regional procurement network penetration. QOL Medical LLC represents the North American specialist archetype, concentrating on narrow therapeutic formulations. McKesson Corporation exemplifies distribution-scale operations with consolidated logistics capabilities across multiple therapeutic categories.
| Leading Market Players |
|---|
| Merz Pharma GmbH & Co. KGaA |
| QOL Medical LLC |
| McKesson Corporation |
| Kreussler |
| Provensis |
| STD Pharmaceuticals Product Ltd. |
| Medtronic plc |
| Teleflex Incorporated |
| Boston Scientific Corporation |
| Others |
Supply & Pricing Matrix
High-volume foam formulation capacity in Germany anchors price floors across European sclerosant markets, with Bavarian manufacturing clusters leveraging batch-scale efficiencies to compress unit economics while smaller compounding operations in Austria defend premium positioning through customization depth.
Pricing Analysis
The customization-premium spread between standard liquid concentrates and patient-specific foam preparations spans three distinct pricing tiers. Foam formulations command premium positioning due to compounding complexity and paired ultrasound device requirements, while bulk liquid contracts for hospital procurement networks compete on volume scale and batch-release documentation efficiency. Pricing pressure intensifies in the standard liquid segment as Austrian purchasing cooperatives consolidate tender volumes and demand unit cost transparency. Dermatology practices exhibit the highest price sensitivity for capital equipment, whereas academic medical centers prioritize formulation certification tier over per-unit expenditure.
Supply Chain Analysis
Strait of Hormuz transit exposure for lauromacrogol feedstock intermediates concentrates supply risk in a single maritime chokepoint. Active pharmaceutical ingredient synthesis clusters in Germany, Switzerland, and the Netherlands, with detergent-based sclerosant chemistry drawing from European specialty chemical manufacturers subject to REACH compliance verification. Single-source vulnerability persists for polidocanol raw material where one Bavarian supplier controls crystallization-grade output. Distribution runs through regional compounding specialists serving hospital procurement networks, with direct manufacturer-to-clinic relationships displacing traditional pharmaceutical distributors in UK aesthetic channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The microsclerotherapy treatment market is recovering from regulatory compliance cost cyclicality, with EU MDR implementation timelines compressing margin structures before quality dossier investments yield procurement preference dividends.
For Market Incumbents: Compound defensive positioning through backward integration into polidocanol raw material sourcing and dedicated field service organizations that bypass distributor relationships in consolidating UK clinic networks. Foam-generation device classification ambiguity at the US FDA threatens transatlantic product harmonization timelines, making CE marking depth and German BfArM relationship quality critical procurement leverage.
For New Entrants and Emerging Players: Lead with narrow therapeutic formulations for pediatric vascular malformation protocols where liquid-only administration requirements exclude foam incumbents. Austrian hospital procurement networks present the most penetrable geography given limited regional competition for standardized high-volume contracts. A go-to-market angle anchored in CSRD sustainability disclosure alignment differentiates bids in German GPO evaluations.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compounding specialists with hospital network exclusivity agreements and long-term sclerosant supply contracts. Five-to-ten year viability favors manufacturers with captive chemical synthesis capabilities and notified body audit resilience. Watch EU MDR post-market surveillance data publication patterns as an inflection indicator for incumbent quality dossier valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Synthesis | Captive polidocanol production insulates Merz Pharma from European specialty chemical input volatility. |
| CE Marking Pathway Acceleration | Expedited notified body engagement compresses foam-generation device certification timelines for German manufacturers. |
| Hospital System Partnership | Direct formulary placement with Lyon university hospitals secures pediatric vascular malformation protocol lock-in. |
| Software Companion Development | Portable ultrasound vascular presets enable real-time needle guidance without radiology department infrastructure investment. |
| Reimbursement Strategy | NICE guideline navigation reserves microsclerotherapy positioning for recurrent varicose vein cases post-thermal ablation. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, hospital procurement databases, and GPO contract disclosures. Interviews with phlebology clinic directors, biomedical engineers, formulary managers, and BfArM quality assessors were cross-checked against EMA MDR implementation guidance, ANSM pharmacovigilance reports, and CMS Medicare procedure data. Bottom-up procedure volume estimates from German dermatology networks and UK aesthetic clinic rollups were triangulated against top-down sclerosant formulation shipment data from European customs records.
Segmentation dimensions modeled include product type formulation, application indication, end-user channel, and delivery mode technology pairing across the projection horizon. CAGRs were derived from regression analysis of historical procedure volume trends and reimbursement policy elasticity estimates. Industry-specific forecast inputs incorporated point-of-care ultrasound adoption curves and EU MDR batch-release testing timeline assumptions.
The analysis sits within stated boundaries; outcomes outside sustained foam protocol conversion rates or accelerated pediatric indication approvals would require recalibration. Forecasts reflect documented assumptions regarding regulatory compliance cost trajectories and clinic network consolidation velocity. Practitioners should keep alternative scenarios live as EU MDR enforcement intensity and FDA device-drug classification resolution evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Drug Eluting Stent (DES) Market
Cardiovascular Devices
Mobile Cardiac Telemetry Device Market
Cardiovascular Devices
Global Cardiovascular Disease Monitoring and Diagnostic Devices Market
Cardiovascular Devices
Cardiac Valve Market
Cardiovascular Devices
Cardiovascular Stents Market
Cardiovascular Devices
Global Catheters Market
Cardiovascular Devices
Vena Cava Clips and Filters Market
Cardiovascular Devices
Vascular Access Catheters Market
Cardiovascular Devices
Perfusion Systems Market
Cardiovascular Devices
Lung Stent Market
Cardiovascular Devices
South Africa Cardiovascular Devices Market
Cardiovascular Devices
Cardiac Catheters Market
Cardiovascular Devices
Renovascular Hypertension Treatment Market
Cardiovascular Devices
Stent Grafts Market
Cardiovascular Devices
Peripheral Vascular Interventions Market
Cardiovascular Devices
Pressure Infusion Cuffs Market